
 Global Enzymes Market | 2026-2036
Global Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enzymes Market Analysis
Buyer concentration in the food processing sector is expanding as multinational manufacturers consolidate supplier relationships and demand tailored enzyme cocktails. Novozymes leverages its integrated fermentation platform to secure long-term supply agreements with these consolidated buyers. DSM-Firmenich anchors its position through deep specialization in nutritional enzymes, while BASF SE competes on manufacturing scale across industrial biocatalysis applications. Kerry Group plc differentiates through regional formulation labs that adapt enzyme blends to local substrate conditions.
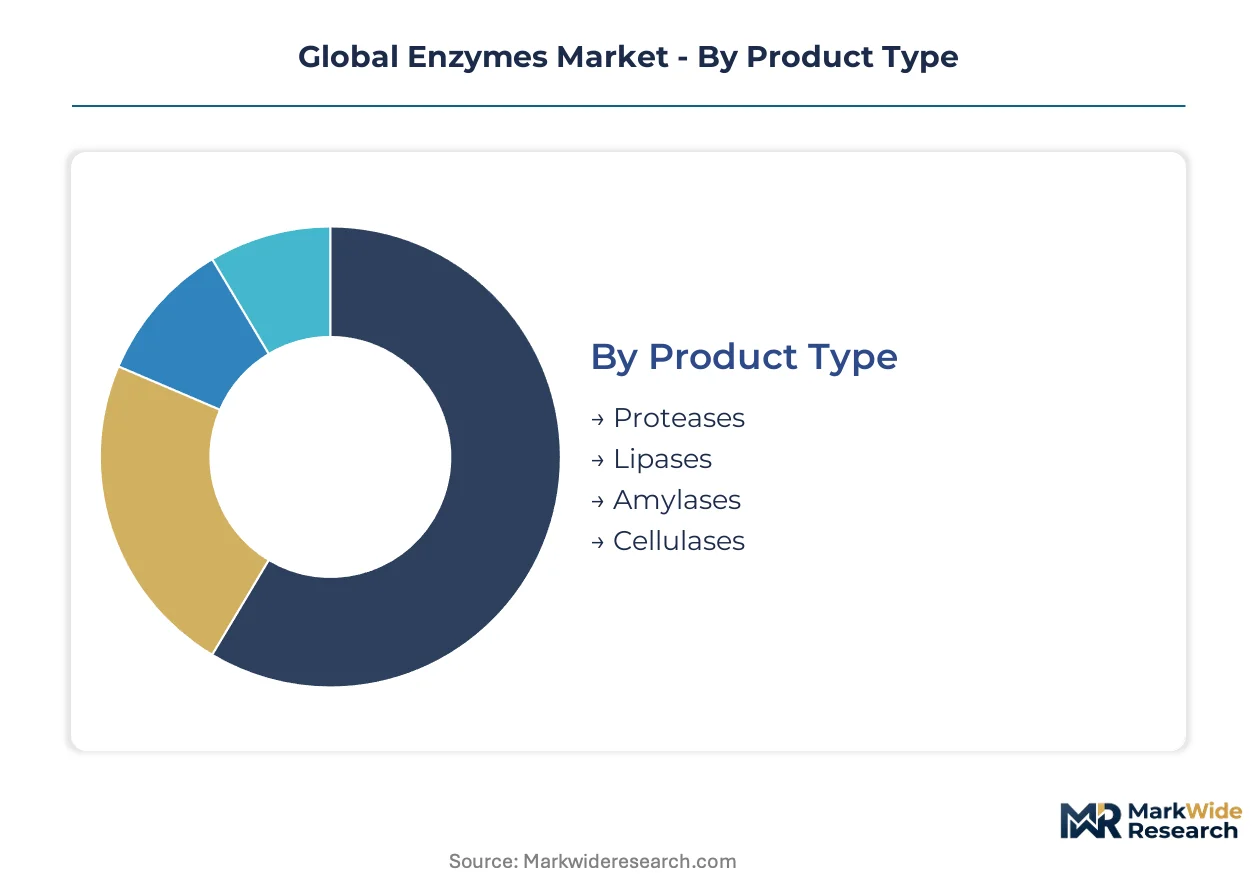
Enzymes are protein-based biocatalysts that accelerate chemical reactions without being consumed, typically operating at mild temperatures and pH ranges with high substrate specificity. They are manufactured through submerged fermentation of microbial strains, followed by downstream recovery, formulation stabilization, and standardization to declared activity units for industrial deployment. Proteases command the largest product type position due to their ubiquity across detergents, food processing, and leather treatment, while cellulases represent the fastest-expanding category driven by textile biopolishing and second-generation biofuel pre-treatment. The application dimension shows biofuels pulling ahead in growth velocity as cellulosic ethanol mandates tighten, though Food & Beverage retains the deepest margin pool owing to premium pricing for GRAS-certified and kosher/halal-qualified enzyme grades.
REACH registration requirements in Europe and EPA biofuel mandates in the United States jointly shape product development roadmaps, forcing manufacturers to document toxicological profiles and demonstrate lifecycle carbon reductions for market access. China's NMPA and GB standards add another compliance layer for enzymes entering pharmaceutical and food-contact applications, with SAMR enforcement intensifying post-market surveillance. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent biocide classifications and gene-editing disclosure rules threaten to fragment formulation strategies and complicate global product registrations.
Market Dynamics
Consolidated buyer power in food processing is compressing supplier margins while accelerating demand for customized enzyme formulations. Multinational manufacturers now specify activity profiles and substrate compatibility requirements in long-term supply agreements, forcing producers to retool fermentation platforms for batch flexibility.
Growth Catalysts
- EU Green Deal compliance deadlines:REACH registration requirements for bio-based catalysts are redirecting European formulation strategies away from petrochemical alternatives. Industrial biotech investment flows into enzyme manufacturing capacity.
- Cellulosic ethanol mandates:EPA renewable fuel standards in the United States are tightening pre-treatment enzyme specifications for second-generation biofuel facilities. Cellulase demand accelerates at corn stover and woody biomass conversion plants.
- China dual carbon policy:Beijing's emissions reduction targets are channeling state investment into industrial biotechnology clusters. Provincial governments compete to host fermentation infrastructure.
Market Restraints
- Agricultural substrate volatility:Corn steep liquor and wheat bran prices fluctuate with commodity grain markets. Fermentation feedstock costs represent 35-45% of enzyme production economics.
- Downstream recovery bottlenecks:Ultrafiltration membrane supply concentrates among German and Japanese equipment specialists. Capacity constraints delay commercial-scale deployment.
- Protein stability limitations:Thermotolerant enzyme variants remain scarce for high-temperature industrial processes. Engineering costs for directed evolution cycles constrain product pipelines.
Strategic Opportunities
- India pharmaceutical enzyme penetration:CDSCO regulatory harmonization with ICH guidelines is opening contract manufacturing pathways for active pharmaceutical ingredient biocatalysis. Domestic fermentation capacity remains underdeveloped relative to synthetic chemistry.
- Precision fermentation convergence:Synthetic biology toolkits combine with CRISPR-edited microbial chassis to produce novel enzyme classes. Startups target pharmaceutical and fine chemical applications.
- Direct-to-brewery distribution channels:Craft brewing consolidation creates demand for localized enzyme technical service. Regional formulators bypass traditional distributor markups.
Industry Challenges
- Fermentation process engineering talent scarcity:Industrial microbiology and downstream processing expertise concentrates among senior specialists at established producers. University pipeline output lags biotech sector expansion.
- GRAS certification timeline compression:FDA notification review periods for food-contact enzymes extend 12-18 months. Novel protein submissions face allergenicity assessment backlogs.
- Legacy detergent formulation integration:Protease and amylase replacement in existing manufacturing lines requires pH and temperature profile recalibration. Brand owners delay reformulation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enzymes Market |
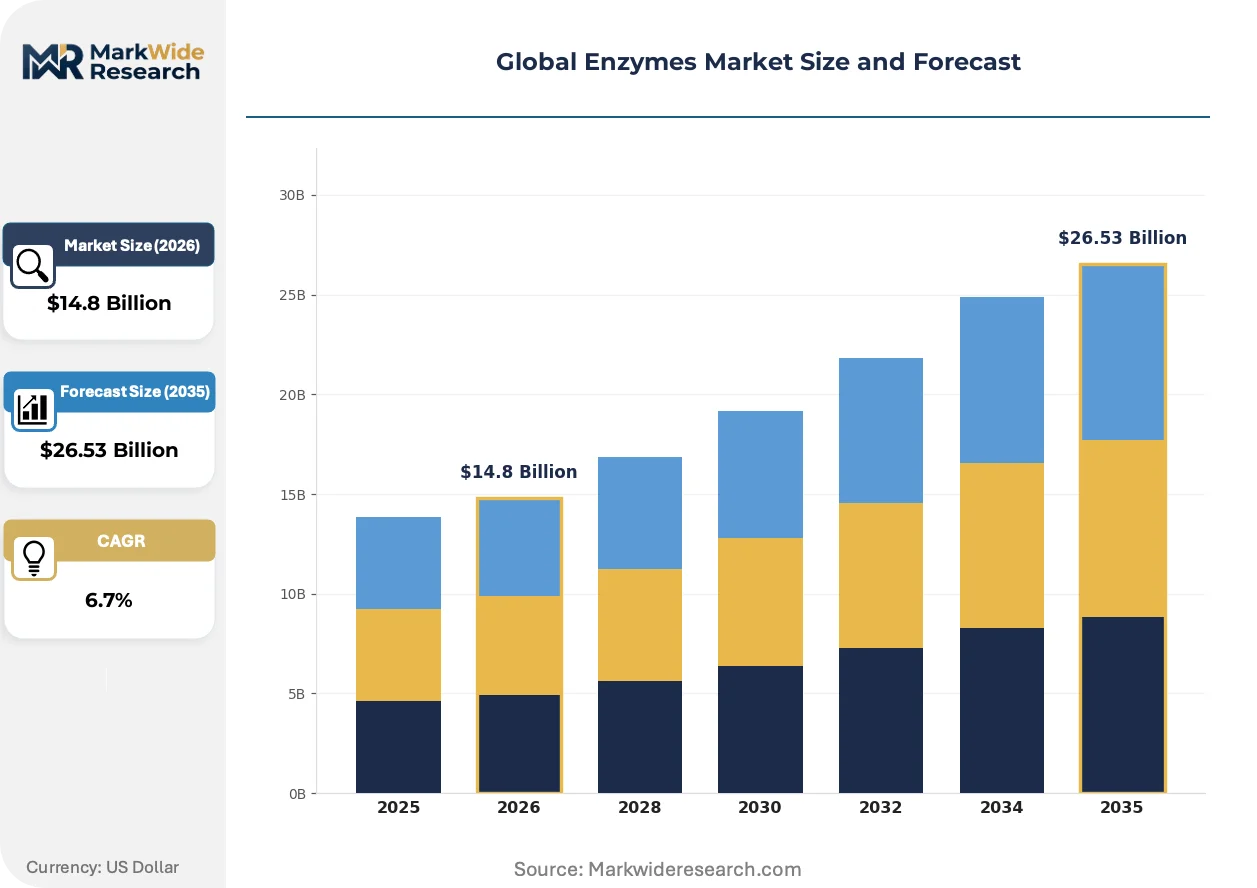
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Lipases, Amylases, Cellulases Application: Food & Beverage, Diagnostics, Agriculture, Biofuels End User: Healthcare, Food Industry, Biotechnology, Animal Feed Form: Liquid, Powder, Granular, Tablets |
| Companies Covered | Novonesis, DSM-Firmenich, BASF SE, International Flavors & Fragrances Inc., DuPont de Nemours, Inc., Kerry Group plc, Ajinomoto Co. Inc., Chr. Hansen Holding A/S, Codexis, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enzymes Market Emerging Trajectories
Enzyme engineering platforms are compressing development cycles from strain construction to commercial deployment. Computational protein design, automated high-throughput screening, and continuous fermentation technologies are converging to reshape competitive economics.
Immobilized enzyme systems are absorbing capital investment from pharmaceutical and fine chemical manufacturers seeking solvent reduction and catalyst reuse. Merck KGaA and Lonza Group deploy packed-bed and membrane-encapsulated configurations for API synthesis. This technology is absorbing share from homogeneous catalysis in chiral intermediate production.
REACH authorization timelines for persistent organic pollutants are forcing detergent manufacturers to substitute phosphonate stabilizers with biodegradable alternatives. ECHA substance evaluation dossiers now require biodegradation test data for enzyme formulation adjuncts. European laundry and dishwashing segments reformulate around citrate and polyaspartate builders.
Technical service unbundling from enzyme supply contracts is emerging as procurement departments separate catalyst purchasing from application engineering. Food processors in Germany and the Netherlands now engage independent bioprocess consultants for substrate optimization. This pattern concentrates in high-volume starch processing and dairy applications where enzyme dosing precision directly governs yield economics.
Global Enzymes Market Segmentation
Enzyme manufacturers configure fermentation capacity and downstream recovery lines around segment-specific activity specifications and stability requirements. Formulation choices cascade through pricing, distribution logistics, and regulatory compliance pathways.
Product Type:
Supply concentration in protease manufacturing dominates global fermentation capacity allocation, with specialized recovery infrastructure locking in production economics.
- Proteases:These protein-cleaving enzymes operate across broad pH ranges with varying substrate specificity profiles. Detergent manufacturers in Germany and the United States specify subtilisin variants for laundry applications, while leather processors in India demand alkaline proteases for dehairing operations. Feedstock costs and recovery yields constrain margin structures.
- Cellulases:Multi-enzyme complexes hydrolyze cellulose into fermentable sugars for biofuel production. Chinese and Brazilian cellulosic ethanol facilities drive demand for thermotolerant endoglucanase and exoglucanase cocktails. Equipment bottlenecks in membrane filtration delay capacity expansion.
- Amylases:Starch-degrading enzymes convert polysaccharides to maltose and glucose syrups.
- Lipases:Ester-bond hydrolysis enzymes enable interesterification for structured fats and biodiesel production.
Proteases absorb the bulk of installed capacity; cellulases are expanding most quickly.
Application:
Cost tier stratification separates premium-certified food-grade enzymes from commodity industrial catalysts.
- Food & Beverage:GRAS-certified and kosher/halal-qualified enzyme grades command premium positioning. Bakery, brewing, and dairy processors specify activity units per kilogram of substrate. FDA notification timelines and allergenicity assessments extend commercialization cycles.
- Biofuels:Cellulosic ethanol mandates in the United States and EU Green Deal compliance deadlines redirect formulation investments. Pre-treatment enzyme loading rates directly govern conversion economics at corn stover and woody biomass facilities.
- Diagnostics:High-purity enzyme preparations for molecular biology and clinical assays.
- Agriculture:Soil and crop processing applications for residue management and silage.
Food & Beverage retains the deepest margin pool; biofuels demonstrates the steepest expansion trajectory.
End User:
Customer type determines technical service intensity and contract structure, with pharmaceutical and food manufacturers demanding distinct support models.
- Healthcare:Pharmaceutical manufacturers deploy biocatalysts for active pharmaceutical intermediate synthesis. CDSCO harmonization with ICH guidelines in India opens contract manufacturing pathways. Immobilized enzyme systems reduce solvent use in chiral chemistry.
- Food Industry:Multinational processors consolidate supplier relationships and specify tailored enzyme cocktails. Regional formulation labs adapt blends to local substrate conditions and processing equipment.
- Biotechnology:Research and industrial biotech applications for synthetic biology workflows.
- Animal Feed:Phytase and carbohydrase supplementation for poultry and swine nutrition.
Food Industry channels the largest procurement volumes; Healthcare is climbing the fastest on precision fermentation convergence.
Form:
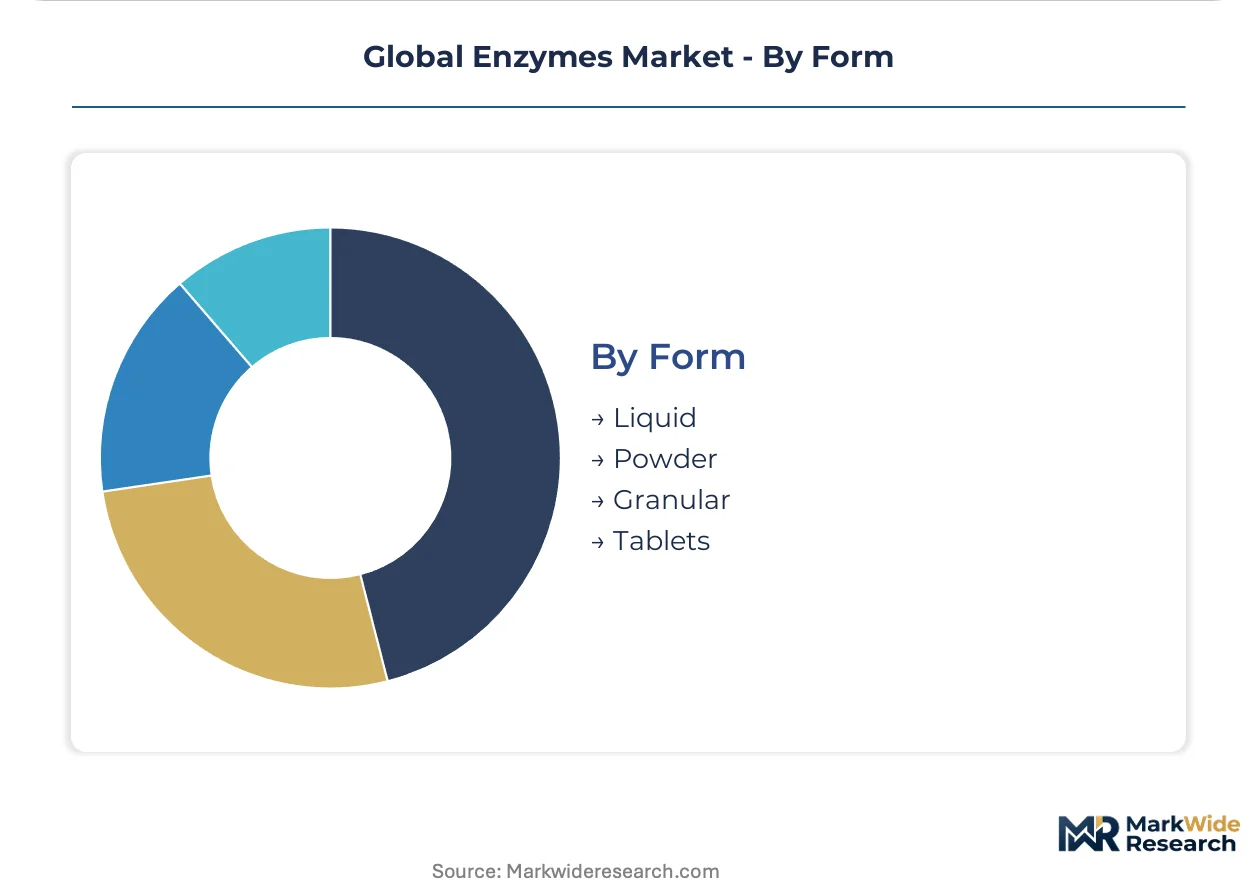
Distribution economics and shelf stability requirements segment formulation choices across liquid, solid, and granular presentations.
- Liquid:Standardized enzyme solutions suit automated dosing systems in large-scale starch processing and dairy operations. Cold chain logistics add cost layers for temperature-sensitive formulations.
- Powder:Spray-dried preparations with stabilizer matrices extend ambient storage life. REACH authorization timelines for phosphonate alternatives force builder substitutions with citrate and polyaspartate complexes.
- Granular:Dust-free formulations for detergent and feed applications.
- Tablets:Unit-dose presentations for small-scale brewing and pharmaceutical compounding.
Liquid forms dominate high-volume industrial procurement; powder formats are gaining share fastest on logistics optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China where provincial governments compete to host fermentation infrastructure under dual carbon policy mandates. European buyers redirect procurement toward REACH-compliant bio-based catalysts. North American biofuel facilities tighten pre-treatment enzyme specifications.
China
Provincial governments in Jiangsu and Shandong compete to host industrial biotechnology clusters under Beijing's emissions reduction targets. NMPA and GB standards enforcement intensifies post-market surveillance for food-contact enzymes. Tianjin and Shanghai fermentation facilities expand capacity to serve domestic starch processing and brewing demand.
United States
Cellulosic ethanol mandates tighten pre-treatment enzyme specifications at corn stover conversion facilities. EPA renewable fuel standards redirect formulation investments toward thermotolerant cellulase cocktails. Midwest biorefinery clusters in Iowa and Nebraska drive procurement volumes for biomass processing applications.
Germany
REACH registration requirements redirect formulation strategies away from petrochemical alternatives toward bio-based catalysts. ECHA substance evaluation dossiers now mandate biodegradation test data for enzyme formulation adjuncts. Cologne and Frankfurt formulation labs adapt enzyme blends to local substrate conditions for consolidated food processors.
India
CDSCO regulatory harmonization with ICH guidelines opens contract manufacturing pathways for active pharmaceutical ingredient biocatalysis. Domestic fermentation capacity remains underdeveloped relative to synthetic chemistry demand. Maharashtra and Gujarat pharmaceutical clusters absorb precision fermentation investment for enzyme-driven chiral synthesis.
Brazil
Cellulosic ethanol mandates accelerate cellulase demand at sugarcane bagasse conversion facilities. ANVISA enforcement intensifies for enzymes entering pharmaceutical and food-contact applications. São Paulo state biotechnology parks channel investment toward fermentation infrastructure for biofuel pre-treatment.
Global Enzymes Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation convergence for pharmaceutical applications. The supplier base consolidates around multinational fermentation platforms and regional formulation specialists. Three archetypes dominate: integrated fermentation platform operators, deep specialization holders in nutritional enzymes, and regional formulation laboratories. Competitive moves center on long-term supply agreement consolidation and synthetic biology toolkit licensing.
Among Denmark-based integrated platforms, Novonesis and Chr. Hansen Holding A/S exemplify the fermentation infrastructure archetype. DSM-Firmenich, a Swiss-Dutch entity, occupies a position within the nutritional specialization tier. These three entities represent contrasting strategic postures: integrated platform control, deep application expertise, and hybrid structure combining fermentation scale with formulation proximity.
| Leading Market Players |
|---|
| Novonesis |
| DSM-Firmenich |
| BASF SE |
| International Flavors & Fragrances Inc. |
| DuPont de Nemours, Inc. |
| Kerry Group plc |
| Ajinomoto Co. Inc. |
| Chr. Hansen Holding A/S |
| Codexis, Inc. |
| Others |
Supply Flow & Price Mechanics
Multinational food processors consolidating supplier relationships command contract-based pricing leverage over enzyme manufacturers, forcing tiered pricing structures that separate GRAS-certified premium grades from commodity industrial catalysts. Long-term supply agreements now embed activity specification clauses that transfer substrate compatibility risk to producers, compressing margins while locking in volume commitments.
Pricing Analysis
Volume procurement in biofuels and commodity detergents operates on thin margins, while food-grade and pharmaceutical enzyme tiers retain pricing power through certification barriers. Three-tier pricing structure across premium, standard, and economy levels stratifies by regulatory qualification depth, with kosher/halal certification and REACH compliance driving tier placement. Cost compression in standard-grade cellulases is intensifying because agricultural substrate volatility feeds directly into fermentation economics. Biofuel processors exhibit highest price sensitivity due to mandate-driven procurement volumes, whereas pharmaceutical manufacturers prioritize batch consistency over unit cost.
Supply Chain Analysis
Cold chain logistics for liquid enzyme formulations add 15-20% distribution cost layers, particularly for temperature-sensitive preparations shipped to brewing and dairy operations. Fermentation capacity concentrates in Denmark, the Netherlands, and China, with downstream recovery equipment sourcing from German and Japanese membrane specialists. Corn steep liquor and wheat bran feedstock costs hinge on commodity grain futures, creating margin volatility that enzyme producers cannot fully hedge. Single-source vulnerability in ultrafiltration membrane supply threatens commercial-scale deployment timelines. Distribution runs through regional formulation laboratories that adapt standardized concentrates to local substrate conditions and processing equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme manufacturing is becoming a vertical-integration race as players pursue captive control over fermentation feedstock supply to insulate margins from agricultural commodity swings.
For Market Incumbents: Acquire corn wet milling and agricultural processing assets to secure steep liquor feedstock supply at cost-plus terms. Consolidate regional formulation laboratory networks to defend against independent bioprocess consultants unbundling technical service from supply contracts. Precision fermentation startups leveraging CRISPR-edited chassis threaten long-term specialty enzyme margins; incumbents must preemptively license synthetic biology toolkits or acquire platform capabilities. For New Entrants and Emerging Players: Begin with direct-to-brewery distribution channels in craft brewing consolidation zones where localized technical service commands premium positioning. Target Indian pharmaceutical enzyme manufacturing, where CDSCO harmonization with ICH guidelines opens contract biocatalysis pathways yet domestic fermentation capacity lags synthetic chemistry demand. Partner with provincial biotechnology parks in China to access state-funded fermentation infrastructure under dual carbon policy mandates. For Investors and Strategic Acquirers: The window for entry favors precision fermentation platform specialists with demonstrated CRISPR strain engineering capabilities and pharmaceutical-grade downstream processing. Long-term viability rests on synthetic biology convergence displacing traditional submerged fermentation for high-value enzyme classes. Watch for FDA GRAS notification timeline compression signals indicating regulatory capacity constraints that will favor established players with dedicated submission resources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn wet milling acquisitions insulate Novozymes and DSM-Firmenich from steep liquor price volatility. |
| Precision Fermentation Platform Buildout | CRISPR-edited microbial chassis enable novel enzyme classes for pharmaceutical API synthesis. |
| Regional Formulation Laboratory Expansion | Kerry Group's localized blending operations adapt enzyme cocktails to substrate conditions in Germany and Brazil. |
| Long-term Supply Agreement Consolidation | Multinational food processors lock in multi-year contracts with activity specification clauses. |
| REACH Compliance Certification Program | ECHA biodegradation data requirements force detergent manufacturers toward bio-based catalyst alternatives. |
Methodological Framework
Trade databases, ECHA substance evaluation dossiers, and FDA GRAS notification records formed the secondary backbone for supply-side capacity mapping and regulatory pathway analysis. Primary interviews with fermentation plant managers, procurement leads at multinational food processors, downstream recovery equipment specialists, and regulatory affairs directors at enzyme manufacturers validated production economics and compliance timelines. Bottom-up and top-down triangulation reconciled strain-level activity data with sectoral demand aggregation.
Bottom-up modeling built country-specific demand from application-level enzyme loading rates and substrate throughput volumes, while top-down cross-checks applied macroeconomic drivers and policy mandate trajectories across the projection horizon. Segmentation dimensions spanned product type, application, end user, and form, with regulatory certification tier and geographic production hub as industry-specific forecast modifiers. CAGRs derived from historical capacity expansion patterns and announced fermentation infrastructure investments, weighted by cellulosic ethanol mandate tightening schedules and EU Green Deal compliance deadlines.
Underlying measurement precision varies by segment; pharmaceutical and diagnostics enzyme volumes carry tighter precision than commodity detergent and biofuel applications due to disclosed contract manufacturing relationships. Forecasts reflect documented assumptions regarding regulatory timeline stability and agricultural feedstock cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Lipase Enzymes Market
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Glucoamylase Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Bio-Refinery Market