
 North America Biocatalysts Market | 2026-2036
North America Biocatalysts Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biocatalysts Market Intelligence
ISO 14001 environmental management certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Lonza Group Ltd. leverages its integrated biomanufacturing footprint across North American contract development sites. Codexis, Inc. specializes in proprietary protein engineering platforms for pharmaceutical-grade enzyme supply. Novozymes A/S anchors the region's industrial enzyme demand through established distribution networks in food and biofuel processing.
Biocatalysts comprise enzymes or whole-cell systems that accelerate biochemical reactions under mild temperature and pH conditions, typically operating between 20°C and 60°C with high substrate specificity for pharmaceutical, food, and energy applications. Recombinant enzyme technology commands premium positioning due to tunable catalytic efficiency and batch-to-batch consistency in GMP-regulated environments. Hydrolases dominate volume consumption across food processing and beverage applications where lipase and protease activity standardize product quality. Immobilized enzyme systems capture expanding share in pharmaceutical manufacturing as resin-bound catalysts enable continuous-flow synthesis and reduce downstream purification burden.
The U.S. FDA's process validation guidance for biocatalytic drug manufacturing steps shapes facility investment and quality system requirements for enzyme suppliers serving pharmaceutical end users. Canada's PMRA and the U.S. EPA jointly influence agricultural enzyme registrations and environmental release protocols for biofuel processing applications. Stakeholders must monitor evolving Green Chemistry commitments from the U.S. federal procurement framework and state-level renewable chemical mandates that redirect capital toward biocatalytic process substitution.
Market Dynamics
Pharmaceutical-grade enzyme demand is concentrating procurement power among CDMOs operating under FDA process validation protocols, compressing supplier margins while rewarding integrated biomanufacturing capabilities.
Growth Catalysts
- EPA bio-based chemicals prioritization:The Toxic Substances Control Act pathway accelerates regulatory clearance for enzymatic process substitutions in fine chemical manufacturing.
- Continuous-flow pharmaceutical synthesis:Immobilized enzyme resin systems enable multi-step API production with reduced solvent waste and downstream purification loads.
- Great Lakes fermentation infrastructure:Existing tank capacity and enzyme engineering talent clusters lower capital barriers for biocatalytic process scale-up.
Market Restraints
- Specialized protein engineering talent scarcity:GMP-grade enzyme development requires rare combinations of molecular biology and regulatory quality systems expertise.
- Single-source fermentation input concentration:High-purity carbohydrate feedstock supply concentrates among Midwest corn processing facilities.
- Thermal stability limitations:Wild-type hydrolases degrade above 60°C, restricting application in high-temperature industrial processes.
Strategic Opportunities
- Canadian agricultural enzyme registration:PMRA streamlined pathways for biofuel processing applications remain underpenetrated relative to U.S. market development.
- Cell-free enzyme systems:Lyophilized biocatalyst kits eliminate cold-chain logistics and expand field-deployable diagnostic manufacturing.
- State renewable chemical mandates:California and New York procurement frameworks create preferential purchasing for biocatalytic-derived intermediates.
Industry Challenges
- ISO 14001 certification timeline:Environmental management system audits extend 12-18 months, delaying qualification for federal and pharmaceutical procurement.
- Legacy batch reactor retrofit complexity:Stainless steel pharmaceutical infrastructure requires significant piping and control system modification for continuous enzymatic operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biocatalysts Market |
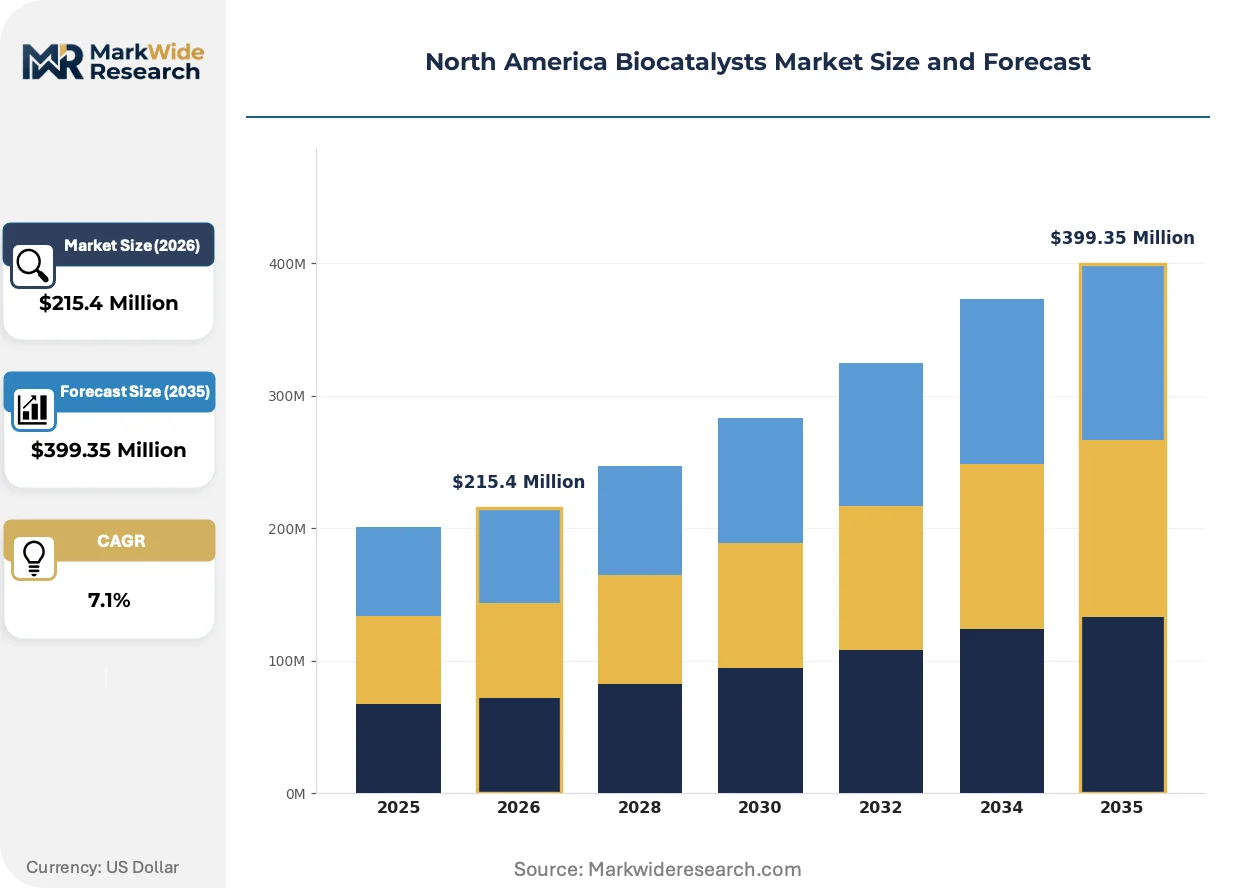
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $399.35 Million |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Applications: Beverages, Food Processing, Pharmaceuticals, Biofuels Product Type: Hydrolases, Oxidoreductases, Transferases, Lyases Technology: Immobilized Enzymes, Whole Cell Biocatalysis, Natural Enzymes, Recombinant Enzymes End User: Food Industry, Pharmaceutical Companies, Agriculture, Waste Treatment |
| Companies Covered | Lonza Group Ltd., AB Enzymes, DuPont de Nemours, Inc., Genencor, Dyadic International, Inc., BASF SE, Codexis, Inc., Cascade Biocatalysts, Novozymes A/S, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biocatalysts Market Strategic Shifts & Innovations
Enzyme engineering platforms are compressing development cycles from discovery to commercial supply, while regulatory frameworks increasingly mandate greener catalytic pathways for government procurement eligibility.
Directed evolution and machine learning-guided protein design is fragmenting the traditional enzyme supply hierarchy. Pharmaceutical manufacturers now license engineered variants directly from platform technology providers, bypassing catalog distributors. This disintermediation compresses pricing power for undifferentiated hydrolase suppliers while concentrating value capture among firms with proprietary screening capabilities.
The U.S. FDA's enhanced process validation guidance for biocatalytic drug substance steps is tightening facility qualification requirements. Suppliers must demonstrate batch-to-batch enzymatic consistency through extended stability protocols. Contract manufacturers serving generic API producers face the steepest compliance cost escalation, driving consolidation among mid-scale enzyme suppliers.
CDMO procurement patterns are hardening around single-source enzyme supply agreements with integrated quality auditing. Pharmaceutical sponsors now require locked manufacturing processes with minimal vendor change flexibility. This concentration is most visible in the U.S. Northeast corridor, where biologics developers prioritize supply security over price competition for GMP-grade catalysts.
North America Biocatalysts Market Segmentation
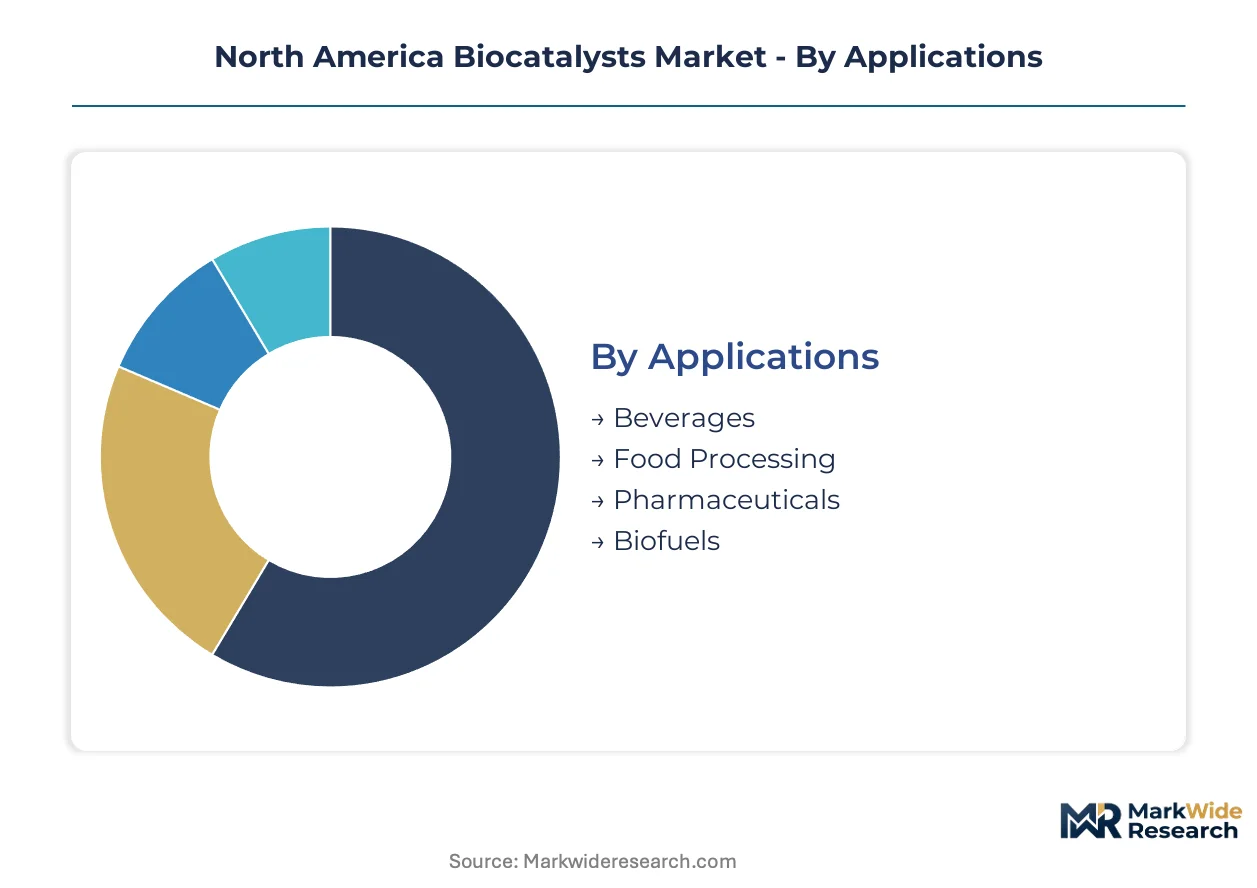
Biocatalyst segmentation in North America reflects divergent regulatory pathways across FDA-governed pharmaceutical applications and EPA-monitored biofuel processing. Enzyme suppliers must align product portfolios with distinct compliance architectures to capture procurement contracts.
Applications:
FDA process validation protocols create the steepest entry barriers for pharmaceutical-grade enzyme supply, while EPA bio-based chemical prioritization under TSCA accelerates clearance for industrial substitutions.
- Pharmaceuticals:GMP-grade enzymes for active pharmaceutical ingredient synthesis command premium positioning through batch-to-batch consistency requirements. CDMO procurement concentrates in the U.S. Northeast corridor where biologics developers prioritize locked manufacturing processes with single-source supply agreements.
- Biofuels:Cellulosic ethanol and renewable diesel processing drives volume demand for thermostable enzyme cocktails. EPA TSCA pathway clearance advantages position enzymatic process substitutions against legacy chemical catalysts in Midwest corn processing facilities.
- Food Processing:Lipase and protease standardization applications dominate enzyme consumption across dairy, baking, and protein modification operations.
- Beverages:Brewing and juice clarification applications leverage pectinase and amylase activity for product quality stabilization.
Pharmaceuticals handles the majority of throughput; Biofuels is the fastest mover on share.
Product Type:
Cost tier differentiation separates catalog hydrolase distributors from engineered oxidoreductase suppliers serving pharmaceutical contract manufacturers.
- Hydrolases:Lipase, protease, and amylase enzymes dominate volume consumption through established food and beverage applications. Wild-type thermal stability limitations above 60°C restrict penetration into high-temperature industrial processes despite lower unit costs.
- Oxidoreductases:Engineered dehydrogenases and oxygenases enable selective redox transformations in pharmaceutical intermediate synthesis. Recombinant variants with tunable cofactor specificity capture expanding share in GMP-regulated environments where batch consistency mandates premium pricing.
- Transferases:Glycosyltransferases and transaminases support carbohydrate modification and chiral amine production for specialty chemical applications.
- Lyases:C-C and C-O bond cleavage enzymes serve niche synthetic biology applications in fine chemical manufacturing.
Hydrolases handles the majority of throughput; Oxidoreductases is climbing the fastest on share.
Technology:
Application maturity separates immobilized enzyme systems with decade-long pharmaceutical validation histories from emerging cell-free formats.
- Recombinant Enzymes:Protein engineering platforms deliver tunable catalytic efficiency and extended stability profiles for GMP manufacturing. Machine learning-guided directed evolution compresses development cycles from discovery to commercial supply, concentrating value capture among platform technology providers.
- Immobilized Enzymes:Resin-bound catalysts enable continuous-flow pharmaceutical synthesis with reduced solvent waste and downstream purification burden. FDA process validation guidance for biocatalytic drug substance steps tightens facility qualification requirements for immobilized system suppliers.
- Whole Cell Biocatalysis:Intact microbial catalysts retain cofactor regeneration machinery for complex multi-step transformations in fermentation infrastructure.
- Natural Enzymes:Wild-type extracts from plant and animal sources serve cost-sensitive food processing applications with minimal regulatory filing requirements.
Recombinant Enzymes handles the majority of throughput; Immobilized Enzymes is expanding most quickly on share.
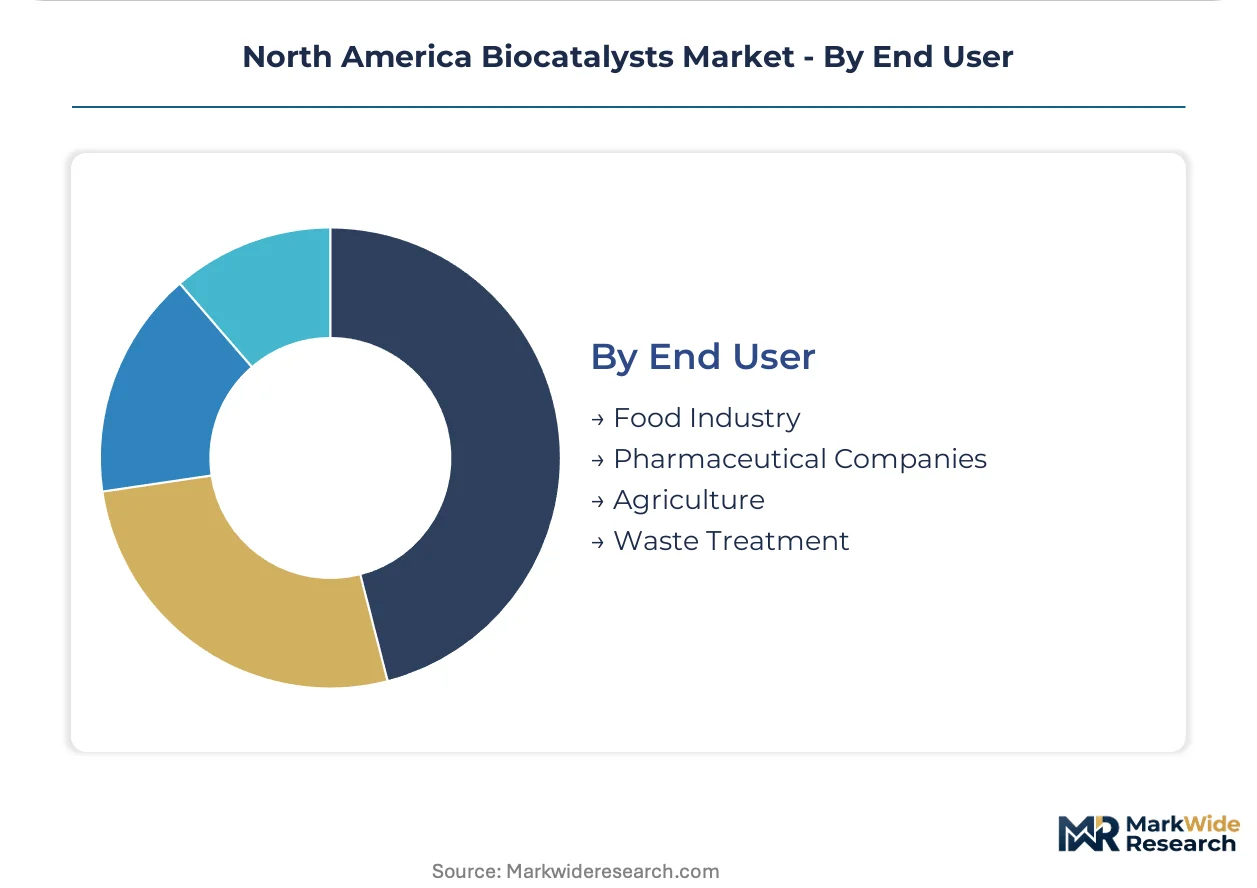
End User:
Customer procurement authority concentrates among pharmaceutical sponsors requiring locked manufacturing processes with minimal vendor change flexibility.
- Pharmaceutical Companies:Active pharmaceutical ingredient manufacturers source GMP-grade enzymes through CDMOs operating under FDA process validation protocols. Single-source supply agreements with integrated quality auditing harden procurement patterns in the U.S. Northeast corridor.
- Food Industry:Dairy, baking, and protein processors standardize product quality through lipase and protease applications with ISO 14001 certification requirements bifurcating supplier qualification.
- Agriculture:Crop residue processing and animal feed applications drive demand for cellulase and xylanase cocktails under PMRA and EPA joint registration protocols.
- Waste Treatment:Municipal and industrial bioremediation operations leverage ligninolytic enzyme systems for pollutant degradation in environmental release-permitted facilities.
Pharmaceutical Companies handles the majority of throughput; Food Industry is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical sponsors and biofuel processors concentrate procurement authority in distinct geographic corridors across North America. CDMOs in the U.S. Northeast enforce locked manufacturing processes with single-source enzyme agreements. Midwest corn processing facilities anchor industrial enzyme demand. Canadian agricultural registrations and Mexican manufacturing expansion create secondary growth vectors.
United States
Great Lakes fermentation infrastructure and enzyme engineering talent clusters lower capital barriers for biocatalytic scale-up. The EPA's TSCA bio-based chemicals prioritization accelerates regulatory clearance for enzymatic process substitutions. Chicago and Minneapolis chemical manufacturing corridors host concentrated CDMO activity serving pharmaceutical API producers.
Canada
PMRA streamlined registration pathways for biofuel processing applications remain underpenetrated relative to U.S. market development. Joint EPA-PMRA protocols govern agricultural enzyme environmental release standards. Ontario's biomanufacturing corridor near Toronto attracts fermentation capacity serving North American pharmaceutical sponsors.
Mexico
Contract manufacturing expansion for U.S. pharmaceutical sponsors drives enzyme demand in Baja California and Mexico City metro areas. COFEPRIS alignment with FDA quality standards facilitates GMP-grade biocatalyst import substitution. Guanajuato's automotive and chemical manufacturing clusters incubate industrial enzyme applications.
North America Biocatalysts Market Key Industry Players
Player mix skews toward integrated biomanufacturing specialists and protein engineering platform providers. Market structure concentrates procurement power among CDMOs operating under FDA process validation protocols, compressing margins for catalog distributors while rewarding integrated capabilities. Three archetypes dominate: GMP-grade enzyme suppliers with locked pharmaceutical agreements, industrial enzyme distributors serving food and biofuel processors, and platform technology licensors enabling directed evolution capabilities. Competitive moves center on ISO 14001 certification acquisition and continuous-flow immobilized enzyme system deployment.
Among Swiss-anchored biomanufacturing specialists, Lonza Group Ltd. exemplifies integrated contract development capabilities across North American sites. Danish industrial enzyme incumbent Novozymes A/S occupies a position anchoring regional food and biofuel processing demand through established distribution networks. California-based Codexis, Inc. represents the protein engineering platform archetype, licensing engineered variants directly to pharmaceutical manufacturers and bypassing traditional supply hierarchies.
| Leading Market Players |
|---|
| Lonza Group Ltd. |
| AB Enzymes |
| DuPont de Nemours, Inc. |
| Genencor |
| Dyadic International, Inc. |
| BASF SE |
| Codexis, Inc. |
| Cascade Biocatalysts |
| Novozymes A/S |
| Others |
Cost & Logistics Intelligence
Ninety-day enzyme stability validation protocols compress procurement cycles and amplify pricing power for GMP-certified suppliers serving pharmaceutical CDMOs. This lead-time discipline concentrates volume premiums among ISO 14001-qualified manufacturers while marginalizing catalog distributors in the Great Lakes corridor.
Pricing Analysis
Cost-plus contracts indexed to Midwest corn-derived carbohydrate feedstock prices dominate industrial enzyme procurement. Three-tier pricing structure across GMP-grade, technical-grade, and food-grade certification levels separates pharmaceutical sponsors from biofuel processors. Price compression runs through technical-grade hydrolase suppliers as machine learning-guided protein engineering platforms disintermediate traditional distributors. Pharmaceutical CDMOs exhibit lowest price sensitivity due to locked manufacturing process requirements, while food processors face acute cost pressure from commodity protein substitutes.
Supply Chain Analysis
The United States anchors GMP-grade enzyme production through Lonza's integrated biomanufacturing sites and Codexis's protein engineering platforms. Canada supplies fermentation capacity near Toronto for North American pharmaceutical sponsors. Mexico's contract manufacturing expansion in Baja California feeds COFEPRIS-aligned import substitution. High-purity dextrose and yeast extract feedstocks draw from Midwest corn processing facilities. Single-source vulnerability concentrates in specialized protein engineering talent pools. Distribution runs through CDMO quality-audited channels for pharmaceutical applications and established industrial distributor networks for food and biofuel segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has concentrated among pharmaceutical CDMOs enforcing single-source supply agreements, fragmenting pricing leverage for undifferentiated enzyme suppliers.
For Market Incumbents: Consolidate around ISO 14001 certification acquisition and continuous-flow immobilized enzyme system deployment to defend against platform technology providers licensing engineered variants directly to manufacturers. Deepen backward integration into Midwest fermentation infrastructure to secure carbohydrate feedstock supply against single-source concentration. Prioritize locked manufacturing process agreements with Northeast corridor biologics developers. For New Entrants and Emerging Players: Lead with cell-free lyophilized biocatalyst kits targeting field-deployable diagnostic manufacturing where cold-chain logistics create service gaps. Target Canadian agricultural enzyme registrations under streamlined PMRA pathways for biofuel processing applications. Position through direct licensing of machine learning-guided protein variants to bypass established distributor hierarchies. For Investors and Strategic Acquirers: Long-term, this sits as a platform-technology consolidation play because directed evolution capabilities are concentrating value capture among firms with proprietary screening infrastructure. Target protein engineering specialists with GMP-quality system integration. Watch FDA process validation guidance expansion as the inflection signal for compliance cost escalation driving mid-scale supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14001 Certification Acquisition | Environmental management qualification bifurcates supplier access to federal and pharmaceutical procurement contracts. |
| Continuous-Flow Immobilized System Deployment | Resin-bound catalysts enable multi-step API synthesis with reduced solvent waste under FDA validation protocols. |
| Backward Integration into Fermentation Infrastructure | Upstream control over Midwest tank capacity secures high-purity carbohydrate feedstock against single-source concentration. |
| Cell-Free Lyophilized Kit Development | Lyophilized biocatalyst formats eliminate cold-chain logistics for field-deployable diagnostic manufacturing expansion. |
| Machine Learning-Guided Platform Licensing | Directed evolution capabilities compress development cycles and disintermediate traditional enzyme supply hierarchies. |
Research Approach
Cross-validation between primary interviews with fermentation plant managers, pharmaceutical procurement leads, regulatory affairs directors, and enzyme engineering specialists and secondary sources including EPA TSCA filings, FDA process validation guidance documents, SEC 10-K disclosures, and ACC chemical production reports anchors the qualitative findings. Bottom-up enzyme consumption estimates triangulate against top-down market sizing across application segments.
Sensitivity analysis around regulatory clearance timelines and feedstock price volatility informs the analytical framework across the projection horizon. Segmentation dimensions model product type, technology format, end-use industry, and regional regulatory cluster. CAGRs derive from enzyme volume intensity coefficients applied to downstream pharmaceutical, biofuel, and food processing output forecasts. Machine learning platform adoption curves and GMP certification penetration rates serve as industry-specific inputs.
Forecasts assume regulatory continuity in EPA TSCA bio-based chemicals prioritization and FDA process validation protocols; material policy shifts would require re-modeling. Specific risks include PMRA registration pathway modifications, thermal stability breakthroughs displacing wild-type hydrolases, and state renewable chemical mandate expansions. Recalibration cycles align with material shifts in federal procurement framework updates and platform technology licensing momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Styrene Monooxygenase Market
Industrial Biotechnology
Glucoamylase Market