
 Biocatalyst Market | 2026-2036
Biocatalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Biocatalyst Market Intelligence
Specialty chemical distribution is tilting toward direct technical partnerships between enzyme suppliers and pharmaceutical manufacturers. Novozymes A/S leverages its fermentation scale to dominate bulk industrial enzyme supply. Evonik Industries anchors its position through backward integration into amino acid and specialty enzyme chemistry. BASF SE competes by extending its catalyst portfolio into biocatalytic process development services.
Biocatalysts are protein-based or whole-cell biological agents that accelerate chemical reactions with high substrate specificity and operate under mild temperature and pH conditions, serving primarily to replace energy-intensive metal-catalyzed processes in chemical synthesis. Hydrolases occupy the largest product category due to their established use in food processing and detergent applications, while oxidoreductases command premium pricing in pharmaceutical asymmetric synthesis where stereoselectivity determines drug efficacy. Immobilized enzyme technology leads the technology landscape in revenue terms, though whole cell biocatalysts are gaining ground in bioremediation applications where cofactor regeneration remains critical.
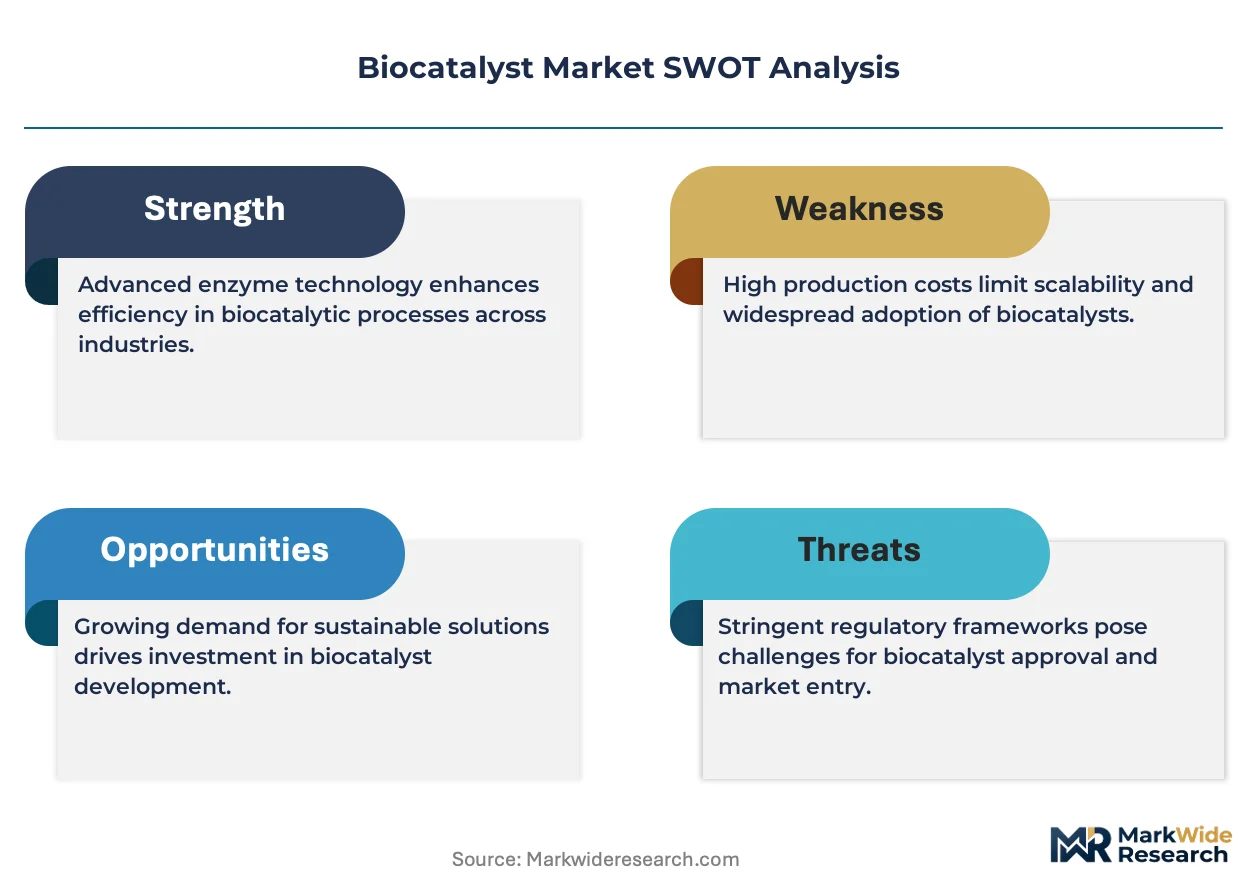
EPA industrial effluent guidelines and the EU REACH authorization process shape biocatalyst demand by restricting hazardous metal catalyst discharge and mandating greener process alternatives. FDA process validation requirements for enzymatic pharmaceutical manufacturing create compliance barriers that favor suppliers with documented quality systems. Stakeholders must monitor how evolving EMA and EPA guidance on biocatalytic process equivalency affects technology substitution timelines and capital allocation across chemical manufacturing assets.
Market Dynamics
EU REACH authorization timelines and the EU Green Deal's chemical process mandates are forcing pharmaceutical and fine chemical manufacturers to abandon metal-catalyzed synthesis routes, creating structural demand displacement toward enzymatic alternatives.
Growth Catalysts
- REACH Authorization Pressure:The EU ECHA's substance of very high concern list restricts hazardous metal catalysts, compelling manufacturers to adopt enzymatic process alternatives for compliance certainty.
- API Manufacturing:Pharmaceutical asymmetric synthesis for chiral intermediates relies on oxidoreductases where stereoselectivity directly determines therapeutic efficacy and regulatory approval pathways.
- German R&D Concentration:BASF and Evonik operate integrated biocatalyst development facilities near Ludwigshafen, creating localized technical service ecosystems that accelerate customer adoption cycles.
Market Restraints
- Enzyme Stability Limitations:Narrow pH and temperature operating windows restrict biocatalyst deployment in continuous flow chemistry systems requiring harsh solvent conditions.
- Cofactor Regeneration Costs:NAD(P)H-dependent oxidoreductases demand expensive cofactor recycling systems that erode process economics at commercial scale.
- Specialized Fermentation Capacity:Contract manufacturing of engineered enzymes concentrates among a limited supplier base, creating single-source vulnerabilities for pharmaceutical process developers.
Strategic Opportunities
- Bioremediation Applications:Whole-cell biocatalysts addressing persistent organic pollutants in soil and wastewater treatment represent underpenetrated demand outside traditional chemical synthesis.
- Immobilized Enzyme Convergence:Combination of carrier material advances with protein engineering is extending catalyst half-life from hours to weeks in continuous manufacturing configurations.
- EMA Process Validation Guidance:Evolving equivalency frameworks for biocatalytic route changes create first-mover advantages for suppliers with documented quality management systems.
Industry Challenges
- Protein Engineering Talent Scarcity:Computational enzyme design and directed evolution expertise concentrates among academic laboratories, constraining industrial scale-up capabilities.
- Legacy Asset Retrofit Complexity:Stainless steel reactor infrastructure designed for homogeneous catalysis requires substantial modification to accommodate aqueous enzymatic process conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biocatalyst Market |
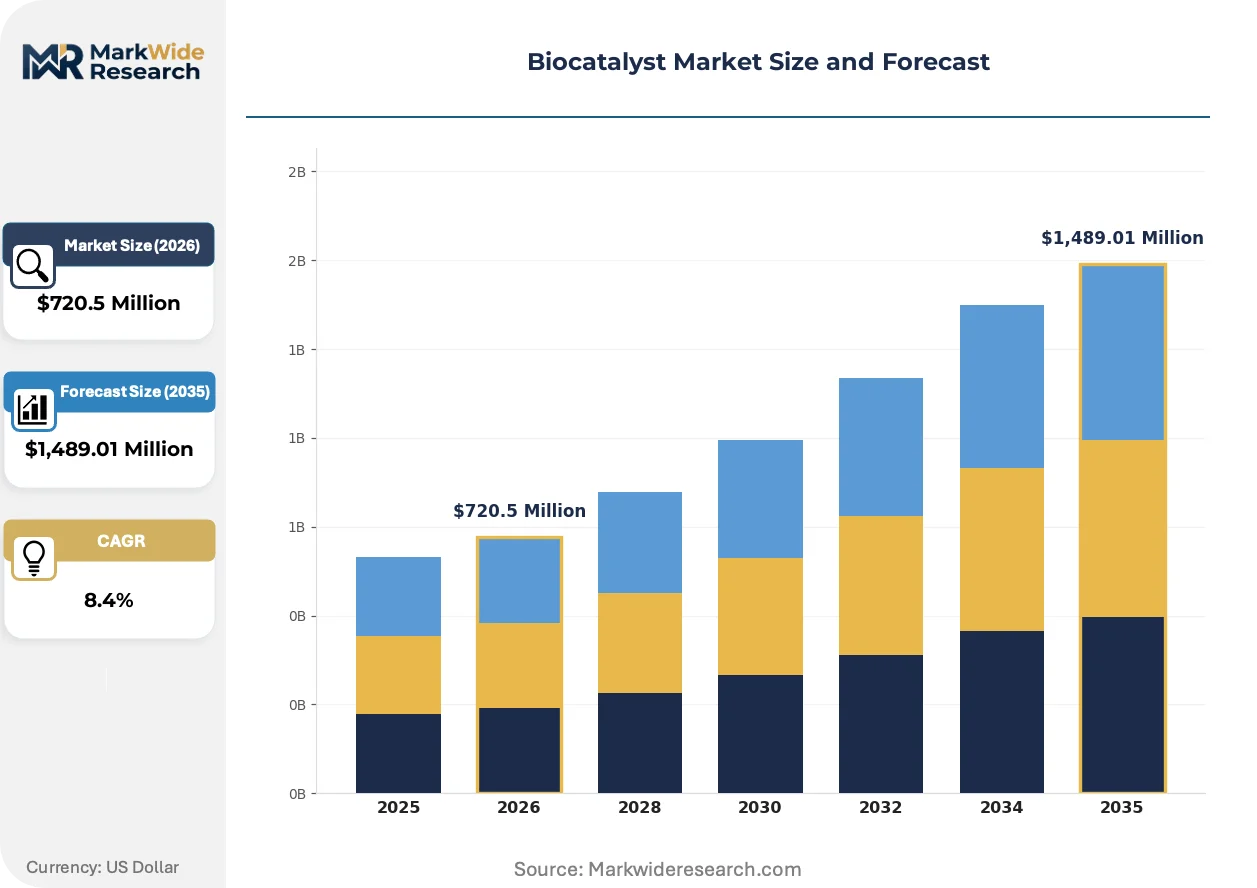
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,489.01 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolases, Oxidoreductases, Transferases, Lyases Application: Food & Beverage, Pharmaceuticals, Biofuels, Bioremediation Technology: Immobilized Enzymes, Whole Cell Biocatalysts, Co-immobilization, Biotransformation End User: Agriculture, Biopharma, Chemical Manufacturing, Environmental Services |
| Companies Covered | Codexis, Inc., Evonik Industries, Novozymes A/S, Amano Enzyme Inc, AB Enzymes GmbH, BASF SE, DSM-Firmenich, Chr. Hansen Holding, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biocatalyst Market Strategic Shifts & Innovations
Computational enzyme design tools and continuous manufacturing integration are compressing development timelines while regulatory frameworks harden around process sustainability metrics.
Directed evolution platforms combined with machine learning screening are rendering obsolete traditional rational design approaches for industrial enzyme optimization. Pharmaceutical process development groups at Merck and Eli Lilly have integrated these workflows, cutting variant screening from months to weeks. The structural consequence is collapsing the competitive moat of incumbent enzyme suppliers who rely on empirical discovery methods.
The EU F-Gas Regulation and accompanying industrial emissions directives are tightening discharge standards for fluorinated solvents used in traditional organic synthesis. Chemical manufacturers face escalating compliance costs for vent capture and thermal destruction systems. Fine chemical producers in the Netherlands and Belgium are accelerating enzymatic process validation to preempt regulatory enforcement actions.
Contract research organizations are unbundling biocatalytic route scouting from full process development, allowing pharmaceutical customers to compare enzymatic versus chemical pathways before capital commitment. This service model fragmentation is displacing integrated technology licensing arrangements previously dominated by large enzyme suppliers. The shift is most pronounced among mid-cap pharmaceutical companies in the United States and Switzerland seeking flexibility in manufacturing strategy.
Biocatalyst Market Segmentation
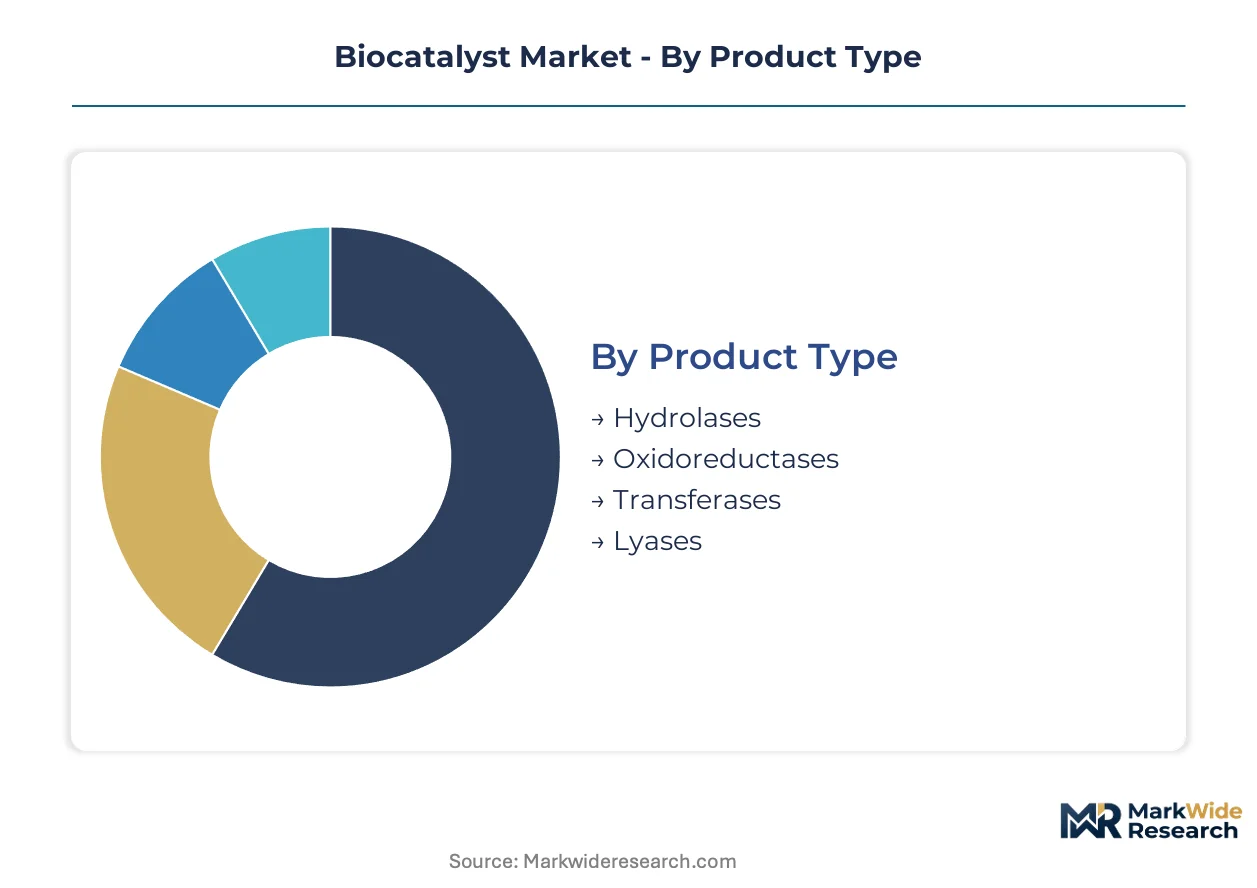
Biocatalyst segmentation reveals how protein engineering capabilities align with distinct process economics across chemical synthesis, environmental remediation, and food processing. Understanding these boundaries clarifies where immobilization technologies command premium positioning versus where whole-cell systems reduce operational complexity.
Product Type:
Use-case spectrum spans commodity hydrolysis reactions to precision pharmaceutical stereoselectivity, with cofactor requirements and substrate range determining deployment feasibility.
- Hydrolases:These enzymes catalyze bond cleavage via water addition, requiring no expensive cofactors for activity. Demand concentrates in detergent manufacturing and food processing across Germany and the Netherlands, where mild operating conditions reduce energy inputs. Established volume favors Hydrolases; emerging adoption favors Oxidoreductases.
- Oxidoreductases:Catalyzing electron transfer reactions with exceptional stereoselectivity, these enzymes enable asymmetric synthesis of chiral pharmaceutical intermediates. Pharmaceutical manufacturers in Switzerland and the United States leverage these biocatalysts where FDA validation pathways for enzymatic routes have matured.
- Transferases:Enzymes that move functional groups between molecules, finding specialized use in glycosylation and phosphorylation reactions for biopharma applications.
- Lyases:Catalyze non-hydrolytic bond cleavage through elimination mechanisms, serving niche roles in specialty chemical synthesis and carbon-carbon bond formation.
Cost tier separation is pronounced: cofactor-independent hydrolases dominate volume shipments while oxidoreductases capture value concentration in high-purity pharmaceutical applications.
Application:
Application segmentation tracks how regulatory pressure intensity varies across sectors, with pharmaceutical and environmental compliance driving fastest technology substitution.
- Food & Beverage:Hydrolases for starch processing, dairy modification, and juice clarification operate under established FDA and EFSA safety frameworks. European malt beverage producers and Japanese food ingredient manufacturers represent concentrated demand centers where process efficiency improvements yield immediate margin recovery.
- Pharmaceuticals:Asymmetric synthesis of active pharmaceutical ingredients relies on oxidoreductases and engineered hydrolases where stereoselectivity eliminates costly separation steps. German and Swiss fine chemical producers are expanding enzymatic capacity to satisfy EMA process validation requirements and EU REACH authorization timelines.
- Biofuels:Cellulase and amylase cocktails convert lignocellulosic feedstock to fermentable sugars, with Brazilian and US ethanol producers representing primary demand.
- Bioremediation:Whole-cell biocatalysts degrade persistent organic pollutants in soil and wastewater treatment, gaining traction in Belgium and the Netherlands where EU industrial emissions directives tighten discharge standards.
Margin structure inverts across the matrix: food applications run on specification-grade commodity enzymes while pharmaceutical and environmental applications sustain premium pricing through regulatory compliance value.
Technology:
Technology choice hinges on catalyst reuse economics and cofactor regeneration complexity, with immobilization maturity contrasting against whole-cell biological integration.
- Immobilized Enzymes:Carrier-bound biocatalysts extend operational half-life from hours to weeks in continuous flow configurations. German chemical manufacturers and Dutch fine chemical producers deploy these systems where reactor uptime directly determines process economics.
- Whole Cell Biocatalysts:Intact microbial cells provide integrated cofactor regeneration and multi-enzyme pathway coordination. Environmental services firms in Belgium and bioremediation contractors in the United States favor these systems for pollutant degradation where enzymatic isolation would compromise viability.
- Co-immobilization:Multiple enzyme species fixed to shared carriers enable cascade reactions without intermediate purification steps.
- Biotransformation:Direct fermentation-based conversion processes merge upstream cultivation with downstream catalytic activity.
Customer type stratification is evident: large chemical manufacturers prefer immobilized enzyme reliability while environmental contractors accept whole-cell operational variability for degradation breadth.
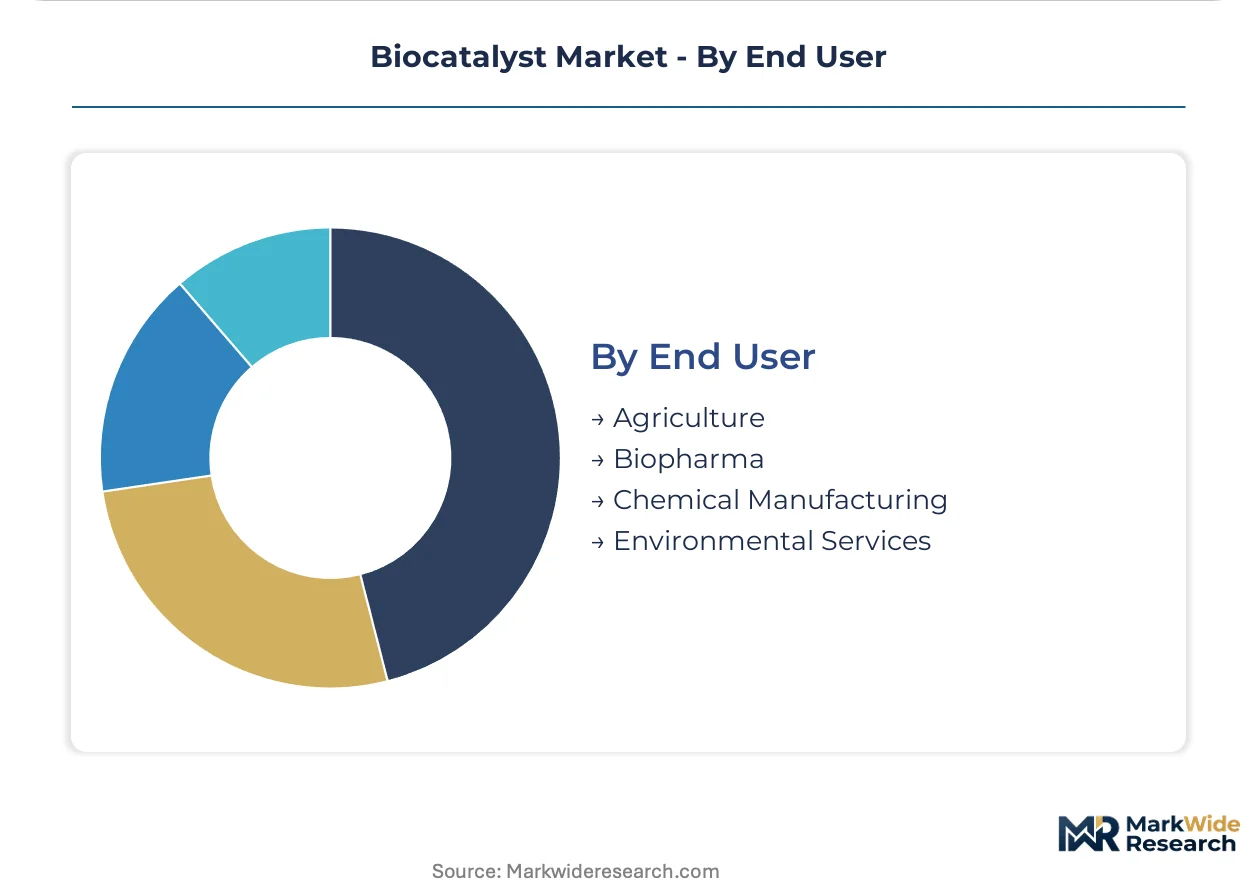
End User:
End user segmentation reflects divergent procurement sophistication, from specification-driven agricultural commodity purchasing to process-integrated biopharma partnerships.
- Agriculture:Feed enzyme supplementation and crop processing applications demand cost-optimized hydrolase formulations. Brazilian and US agricultural operations represent volume concentration where enzyme cost per ton of processed material dominates supplier selection.
- Biopharma:Contract development and manufacturing organizations integrate biocatalytic route scouting into early-phase process design. Swiss and US biopharma clusters require suppliers with documented quality management systems for FDA and EMA regulatory submissions.
- Chemical Manufacturing:Specialty and fine chemical producers substitute enzymatic for metal-catalyzed routes under EU REACH pressure.
- Environmental Services:Soil remediation and wastewater treatment contractors deploy whole-cell systems for persistent pollutant degradation.
Supply concentration shapes access: agricultural and chemical manufacturing segments source through distributors while biopharma and environmental services pursue direct technical partnerships with enzyme developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH authorization timelines and the EU Green Deal's chemical process mandates are redirecting capital toward enzymatic manufacturing infrastructure. Pharmaceutical and fine chemical producers face structural pressure to abandon metal-catalyzed synthesis routes across multiple jurisdictions.
Germany
BASF and Evonik operate integrated biocatalyst development facilities near Ludwigshafen, anchoring Europe's densest technical service ecosystem. ECHA's substance of very high concern list restricts hazardous metal catalysts, compelling manufacturers toward enzymatic alternatives. The Rhine-Neckar metropolitan region concentrates contract fermentation capacity for engineered enzyme production.
United States
FDA process validation requirements for enzymatic pharmaceutical manufacturing favor suppliers with documented quality systems. Merck and Eli Lilly have integrated directed evolution workflows into process development groups. The Boston-Cambridge biopharma cluster and New Jersey pharmaceutical corridor represent concentrated demand for oxidoreductase-based asymmetric synthesis.
Switzerland
Fine chemical producers around Basel are expanding enzymatic capacity to satisfy EMA process validation requirements and Swissmedic equivalency frameworks. Swissmedic guidance on biocatalytic route changes creates first-mover advantages for suppliers with established quality management systems. The Basel Area biotech cluster anchors contract manufacturing relationships with global pharmaceutical developers.
Netherlands
Fine chemical producers in the Rotterdam-Antwerp port corridor are accelerating enzymatic process validation to preempt EU F-Gas Regulation enforcement. The EU industrial emissions directives tighten discharge standards for fluorinated solvents used in traditional organic synthesis. DSM-Firmenich operates integrated enzyme manufacturing and formulation facilities in the southern Netherlands.
Belgium
Environmental services firms deploy whole-cell biocatalysts for persistent organic pollutant degradation in soil and wastewater treatment. The EU industrial emissions directives drive demand for bioremediation applications where cofactor regeneration remains critical. The Port of Antwerp chemical cluster houses specialized fermentation infrastructure for environmental biocatalyst production.
Biocatalyst Market Key Industry Players
On the supply side, the industry is consolidating around fermentation-scale capabilities and backward integration into amino acid chemistry. Three strategic archetypes dominate: bulk industrial enzyme suppliers leveraging scale, specialty chemical producers with captive enzyme development, and pharmaceutical-focused technology licensors. Competitive moves center on strategic partnerships for continuous manufacturing integration and geographic expansion into Asian pharmaceutical contract manufacturing.
Within the integrated chemical producer tier, BASF SE and Evonik Industries exemplify archetypes combining catalyst portfolio breadth with process development services. Novozymes A/S occupies a position as the dominant bulk enzyme supplier, representing the scale-driven archetype through fermentation infrastructure. Codexis, Inc. exemplifies the technology licensing model, anchoring the pharmaceutical-specialist segment through directed evolution platforms. These three company types collectively illustrate how competitive positioning stratifies across commodity volume, specialty integration, and precision pharmaceutical applications.
| Leading Market Players |
|---|
| Codexis, Inc. |
| Evonik Industries |
| Novozymes A/S |
| Amano Enzyme Inc |
| AB Enzymes GmbH |
| BASF SE |
| DSM-Firmenich |
| Chr. Hansen Holding |
| DuPont de Nemours |
| Others |
Cost & Logistics Intelligence
The Rhine-Neckar metropolitan region concentrates contract fermentation capacity for engineered enzyme production, anchoring European supply and transmitting pricing power downstream to pharmaceutical and fine chemical buyers dependent on localized technical service ecosystems.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial-grade biocatalyst supply. FDA-validated oxidoreductases for asymmetric API synthesis command substantial premiums over specification-grade hydrolases for food processing. Cost compression in commodity hydrolase tiers is intensifying because Brazilian and US agricultural buyers prioritize enzyme cost per ton of processed material. Pharmaceutical manufacturers exhibit least price sensitivity where stereoselectivity eliminates costly separation steps.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard as fermentation-scale suppliers manage working capital across multi-month enzyme production cycles. Germany, Denmark, and the Netherlands anchor supply through BASF, Novozymes, and DSM-Firmenich facilities. Production draws from specialized fermentation feedstocks, engineered microbial strains, and carrier materials for immobilization. Single-source vulnerability concentrates in contract manufacturing of engineered enzymes. Distribution runs through direct technical partnerships for biopharma and environmental services, with agricultural and chemical manufacturing segments sourcing through distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biocatalyst demand is fragmenting across pharmaceutical asymmetric synthesis, environmental bioremediation, and food processing applications, creating specialized niches where technical service capabilities matter more than scale alone.
For Market Incumbents: Entrench position through backward integration into amino acid chemistry and captive fermentation capacity expansion near Ludwigshafen. Deepen quality management system documentation to preempt EMA equivalency framework shifts. Lock in continuous manufacturing partnerships before immobilized enzyme technology commoditizes. For New Entrants and Emerging Players: Establish a beachhead in bioremediation applications where whole-cell systems address persistent organic pollutants and cofactor regeneration complexity deters incumbent specialization. Belgian environmental services firms and Dutch wastewater treatment contractors represent underpenetrated demand outside traditional chemical synthesis. Lead with directed evolution platform licensing to pharmaceutical CROs seeking route scouting flexibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors protein engineering specialists with documented FDA and EMA quality systems over commodity fermentation scale. Long-term viability rests on computational enzyme design capabilities compressing variant screening timelines. Watch EMA process validation guidance evolution as the inflection indicator for technology substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Chemistry | Evonik's captive supply of specialty enzyme precursors reduces cofactor regeneration cost exposure. |
| Continuous Manufacturing Partnership | Immobilized enzyme convergence with German chemical producers extends catalyst half-life from hours to weeks. |
| Directed Evolution Platform Licensing | Merck and Eli Lilly integration cuts variant screening timelines, collapsing empirical discovery moats. |
| Bioremediation Application Development | Belgian environmental services firms deploy whole-cell systems for EU industrial emissions directive compliance. |
| Quality Management System Certification | FDA and EMA documentation creates first-mover advantage in pharmaceutical process validation pathways. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fermentation process engineers, pharmaceutical regulatory affairs leads, fine chemical procurement directors, and environmental services contractors; and secondary validation against ECHA REACH authorization databases, FDA enzymatic process validation guidance, SEC 10-K filings from listed enzyme suppliers, and EU F-Gas Regulation enforcement records. Bottom-up triangulation across product type, application, and technology segments converged with top-down macroeconomic and regulatory scenario analysis.
Forecast inputs considered hydrolase versus oxidoreductase demand trajectories, immobilized enzyme versus whole-cell technology adoption curves, and pharmaceutical versus food versus environmental end-use penetration rates across the analysis window. Segmentation dimensions modeled include enzyme class, application sector, technology format, and geographic regulatory cluster. CAGRs were derived from segment-level volume and value buildups calibrated to disclosed capacity expansions and EMA equivalency framework evolution.
Sensitivities concentrate around EMA process validation guidance finalization, EU REACH authorization timeline acceleration, and protein engineering talent scarcity constraining industrial scale-up. Forecasts reflect assumptions regarding regulatory enforcement consistency and fermentation capacity expansion schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Lipase Enzymes Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Xylanase Market