
 United States Biocatalyst Market | 2026-2036
United States Biocatalyst Market Size, Share, and Industry Trends Forecast 2026-2036
United States Biocatalyst Market Intelligence
Modular enzyme kits is pivoting how pharmaceutical and food manufacturers procure biocatalysts, shifting from bulk custom orders to standardized, application-specific configurations. BASF SE leverages its integrated chemical manufacturing network to bundle immobilized enzyme systems with process optimization services. Codexis, Inc. differentiates through proprietary protein engineering platforms that sustain premium positioning in pharmaceutical synthesis. Novozymes A/S dominates the food-grade enzyme segment, extending its channel control through direct technical service teams embedded with industrial manufacturers.
Biocatalysts comprise enzymes, whole cells, or immobilized biological entities that accelerate chemical reactions under mild temperature and pH conditions, typically operating at 25–60°C and near-neutral pH to preserve substrate integrity. Their primary industrial purpose is replacing energy-intensive chemical catalysts in pharmaceutical intermediate synthesis, biofuel production, and food processing. Enzymes command the largest product type share due to decades of regulatory familiarity and established supply chains, while immobilized enzymes capture expanding margin pools as manufacturers seek catalyst recyclability. Synthetic biology represents the fastest-growing technology segment, driven by CRISPR-enabled strain engineering that compresses development timelines for custom biocatalysts.
The FDA governs biocatalyst use in pharmaceutical manufacturing through Current Good Manufacturing Practice regulations that validate enzyme consistency across production batches. The EPA administers the Toxic Substances Control Act, which classifies novel biocatalysts and determines notification requirements for industrial biotechnology applications. California's Department of Toxic Substances Control adds state-level oversight through Safer Consumer Products regulations that favor enzymatic processes over petrochemical routes. Stakeholders must monitor how the EPA's forthcoming biotechnology rulemakings under the New Chemicals Program reshape market access timelines for engineered microbial biocatalysts.
Market Dynamics
Pharmaceutical manufacturers are reconfiguring active pharmaceutical ingredient synthesis around enzyme-based pathways as FDA process validation requirements harden, compressing approval timelines for biocatalyst-dependent production methods while elevating supplier qualification barriers.
Growth Catalysts
- CRISPR-enabled strain engineering:Synthetic biology platforms compress custom biocatalyst development from years to months, accelerating pharmaceutical pipeline integration.
- FDA Current Good Manufacturing Practice enforcement:Tighter batch consistency mandates push drug manufacturers toward validated enzymatic processes with established regulatory familiarity.
- California's Safer Consumer Products regulations:State-level chemical substitution incentives favor enzymatic routes over petrochemical synthesis in consumer goods manufacturing.
Market Restraints
- Specialized fermentation infrastructure concentration:Production capacity clusters in California and Massachusetts, creating geographic supply vulnerability for national distribution.
- Protein engineering talent scarcity:The shallow pool of synthetic biology-trained biochemists constrains custom catalyst development throughput.
- Immobilized enzyme cost structure:Carrier materials and fixed-bed reactor systems impose capital intensity that blocks mid-tier manufacturer adoption.
Strategic Opportunities
- Texas and North Carolina biotech corridor expansion:Secondary clusters with lower operating costs offer white-space manufacturing capacity outside California concentration.
- USDA biofuel blending mandates:Renewable fuel standards create pull for cellulase and lipase biocatalysts in lignocellulosic ethanol production.
- Continuous flow biocatalysis convergence:Integration of immobilized enzyme systems with flow chemistry equipment enables real-time reaction monitoring and yield optimization.
Industry Challenges
- EPA New Chemicals Program uncertainty:Pending biotechnology rulemakings create timeline opacity for engineered microbial biocatalyst market access.
- Cross-functional integration complexity:Biocatalytic process implementation demands coordination between synthetic biologists, chemical engineers, and quality assurance teams that legacy organizational structures struggle to accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Biocatalyst Market |
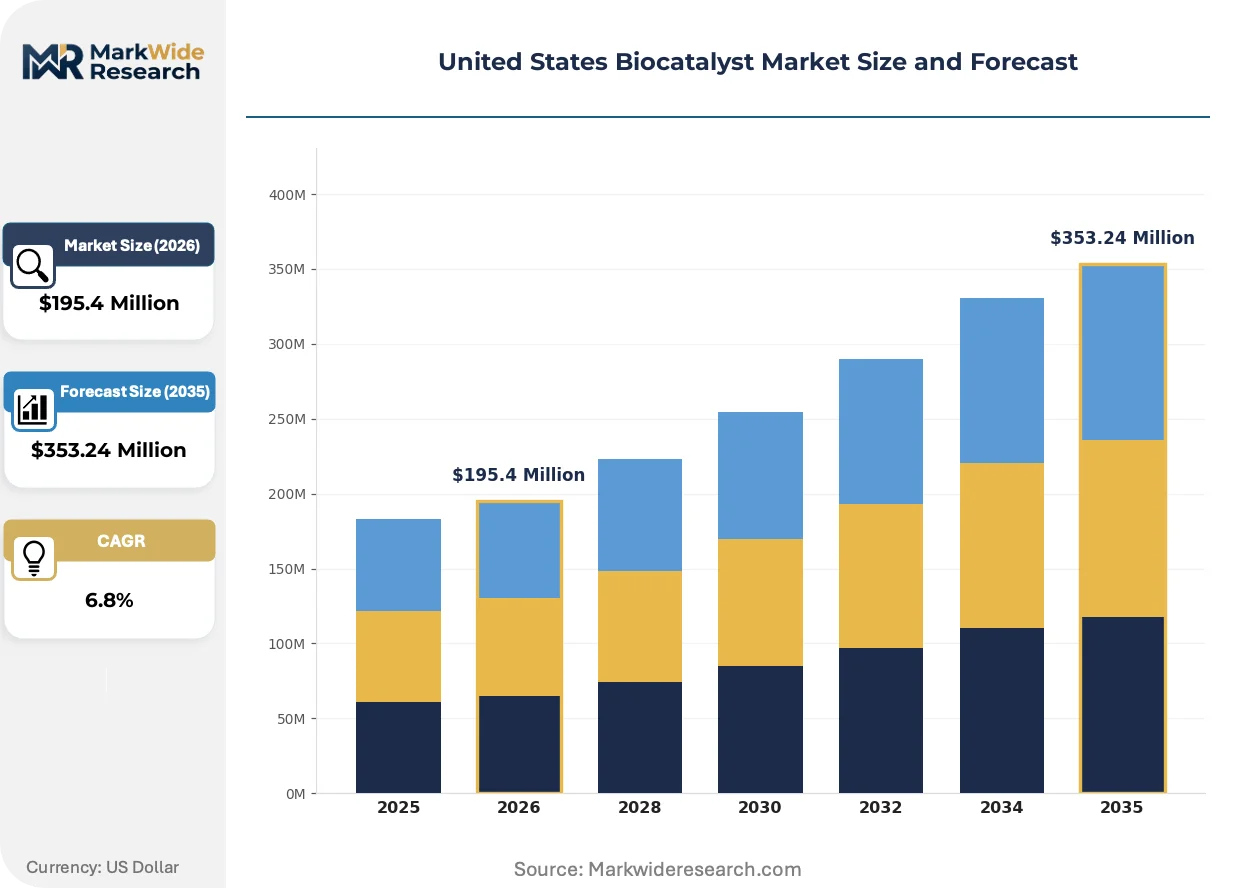
| Market Size in 2026 | $195.4 Million |
| Market Size in 2035 | $353.24 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Whole Cell Biocatalysts, Immobilized Enzymes, Microbial Biocatalysts Application: Food & Beverage, Biofuels, Pharmaceuticals, Textile Technology: Green Chemistry, Synthetic Biology, Metabolic Engineering, Fermentation Technology End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Industrial Manufacturers |
| Companies Covered | BASF SE, AB Enzymes GmbH, DuPont de Nemours, Inc., Chr. Hansen Holding A/S, Amano Enzyme Inc, Codexis, Inc., DSM-Firmenich AG, Advanced Enzyme Technologies Ltd., Novozymes A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Biocatalyst Market Strategic Shifts & Innovations
Synthetic biology toolchains are compressing biocatalyst development cycles while regulatory frameworks harden around process validation, reshaping how pharmaceutical and industrial manufacturers source and deploy enzymatic systems.
CRISPR-Cas9 genome editing is absorbing the strain optimization bottleneck that previously constrained custom enzyme commercialization. Contract research organizations now offer 12-week development timelines for novel biocatalysts. Pharmaceutical manufacturers are absorbing these accelerated pathways into early-phase drug synthesis programs.
California's Department of Toxic Substances Control is tightening Safer Consumer Products enforcement, creating state-level preference for enzymatic processing routes. Industrial biotechnology applicants face expanded notification requirements for novel microbial strains. Food-grade enzyme manufacturers are absorbing additional toxicology documentation burdens into product development budgets.
Modular enzyme kit configurations are displacing bulk custom orders as the dominant procurement format. Pharmaceutical manufacturers now specify application-specific enzyme panels rather than commissioning bespoke catalyst development. This pattern concentrates in California's synthetic biology cluster where standardized product-market fit testing accelerates purchasing decisions.
United States Biocatalyst Market Segmentation
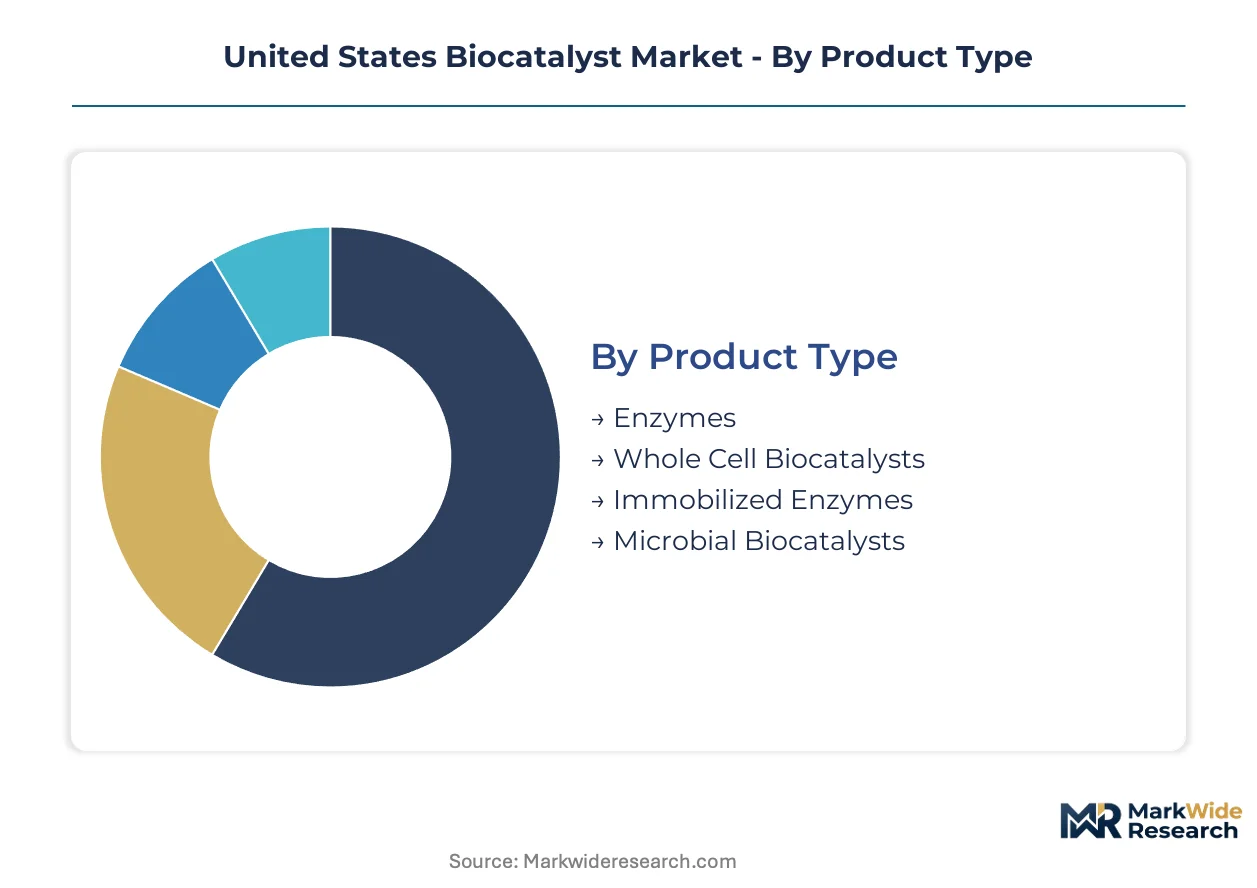
Biocatalyst procurement patterns diverge sharply across product architectures and application contexts. Pharmaceutical manufacturers prioritize regulatory-validated enzyme systems while biofuel producers optimize for volumetric throughput at minimal unit cost.
Product Type:
Volume dominance sits with commodity enzyme formulations, while premium margins concentrate in engineered immobilized systems with catalyst recyclability.
- Enzymes:Soluble protein catalysts dominate pharmaceutical intermediate synthesis and food processing applications. FDA batch consistency mandates reinforce demand from California's generic drug manufacturers seeking validated supply chains with established regulatory familiarity.
- Immobilized Enzymes:Carrier-bound catalysts enable fixed-bed reactor configurations with 10-50 reuse cycles. Capital intensity limits adoption to large-scale pharmaceutical API producers in Massachusetts and North Carolina corridor facilities.
- Whole Cell Biocatalysts:Intact microbial cells perform multi-step biotransformations without enzyme isolation. Demand concentrates in specialty chemical manufacturers seeking cofactor regeneration.
- Microbial Biocatalysts:Engineered strains execute complex synthetic pathways. EPA New Chemicals Program notification requirements create timeline uncertainty for novel strain deployment.
Today's leader: Enzymes. Tomorrow's challenger: Immobilized Enzymes.
Application:
Pharmaceutical synthesis commands premium pricing power, while biofuel applications drive volume scale through USDA mandate pull.
- Pharmaceuticals:Enzymatic routes replace energy-intensive chemical steps in active pharmaceutical ingredient manufacturing. FDA Current Good Manufacturing Practice enforcement compresses approval timelines for validated biocatalytic processes while elevating supplier qualification barriers.
- Biofuels:Cellulase and lipase systems convert lignocellulosic feedstocks to ethanol and biodiesel. Renewable fuel standard obligations pull procurement from Midwest ethanol producers with integrated enzyme dosing infrastructure.
- Food & Beverage:Proteases, amylases, and lipases modify texture, flavor, and shelf stability. California's Safer Consumer Products regulations favor enzymatic processing over petrochemical alternatives.
- Textile:Cellulases and pectinases enable bio-polishing and desizing operations. Water-intensive processing constraints limit adoption outside Southeast Asian contract manufacturing.
Pharmaceuticals capture margin concentration. Biofuels represent the steepest expansion trajectory.
Technology:
Platform maturity separates deployable solutions from development-stage capabilities with uncertain commercialization timelines.
- Synthetic Biology:CRISPR-enabled strain engineering compresses custom biocatalyst development from years to months. Contract research organizations now deliver novel enzymes in 12-week timelines, accelerating pharmaceutical pipeline integration.
- Fermentation Technology:Scalable microbial cultivation underpins commercial enzyme production. Capacity concentration in California and Massachusetts creates geographic supply vulnerability for national distribution.
- Metabolic Engineering:Pathway optimization redirects cellular metabolism toward target molecules. Talent scarcity in synthetic biology-trained biochemists constrains development throughput.
- Green Chemistry:Solvent reduction and waste minimization principles guide process design. Regulatory pressure from California's Department of Toxic Substances Control reinforces adoption preference.
Fermentation Technology anchors current supply. Synthetic Biology is gaining share fastest.
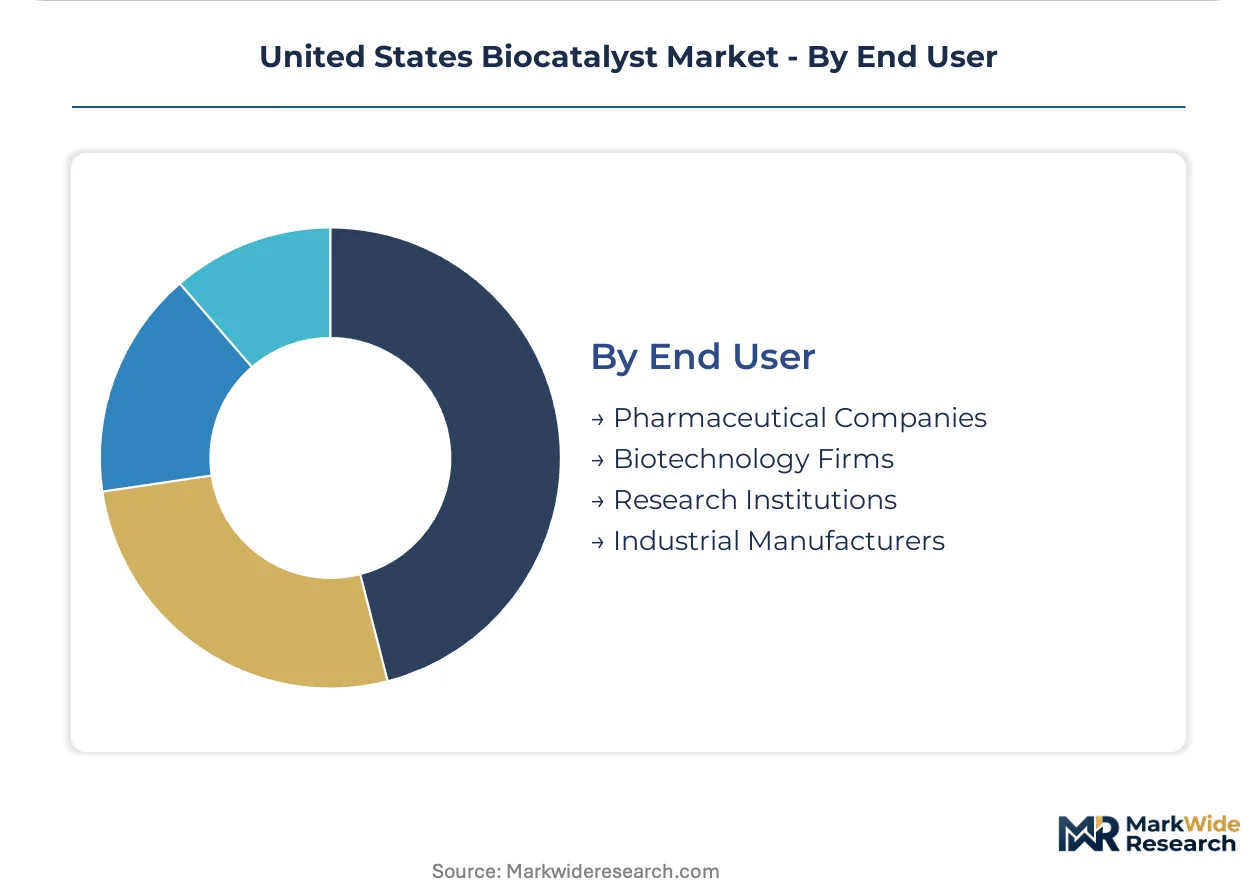
End User:
Procurement sophistication varies from standardized catalog purchasing to multi-year co-development partnerships with exclusive supply terms.
- Pharmaceutical Companies:Validated enzyme systems for GMP manufacturing with batch documentation requirements. Process validation mandates harden supplier qualification barriers, favoring established vendors with regulatory familiarity.
- Biotechnology Firms:Early-stage drug developers integrating accelerated biocatalytic pathways. CRISPR-enabled platforms absorb into synthesis programs for complex molecular architectures.
- Industrial Manufacturers:Food, textile, and chemical producers seeking cost-competitive process alternatives. Modular enzyme kit configurations displace bulk custom orders.
- Research Institutions:Academic and government laboratories advancing foundational biocatalysis science. Federal funding concentration limits commercial translation velocity.
Pharmaceutical Companies dominate premium procurement. Biotechnology Firms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biocatalyst manufacturing in the United States traces its commercial scale to post-war fermentation infrastructure built for antibiotics production, which California's biotechnology corridor repurposed for recombinant enzyme manufacturing during the 1980s biotech boom.
California
Synthetic biology startups cluster around legacy fermentation facilities in the San Francisco Bay Area and San Diego. The state's Department of Toxic Substances Control enforces Safer Consumer Products regulations that favor enzymatic processes over petrochemical routes. Novozymes A/S and Codexis, Inc. maintain technical service teams embedded with pharmaceutical manufacturers in South San Francisco.
Massachusetts
Greater Boston hosts contract development organizations specializing in CRISPR-enabled strain engineering for pharmaceutical applications. FDA Current Good Manufacturing Practice enforcement compresses approval timelines for validated biocatalytic processes developed in Cambridge and Worcester facilities. Protein engineering talent concentrates around MIT and Harvard-affiliated research hospitals.
North Carolina
The Research Triangle Park corridor offers white-space manufacturing capacity with lower operating costs than coastal clusters. USDA biofuel blending mandates pull cellulase procurement from lignocellulosic ethanol producers in the Piedmont region. Immobilized enzyme systems for fixed-bed reactor configurations are scaling at RTP-adjacent contract manufacturing organizations.
Texas
Houston's petrochemical infrastructure is repurposing fermentation capacity for industrial biotechnology applications. The state's business-friendly regulatory environment attracts secondary biotech corridor expansion from California-based firms seeking manufacturing redundancy. Gulf Coast logistics networks enable national distribution of temperature-sensitive enzyme formulations.
Illinois
Chicago's food processing heritage sustains demand for proteases, amylases, and lipases in texture modification and shelf stability applications. Midwest agricultural supply chains feed lignocellulosic feedstock processing for ethanol producers seeking cellulase biocatalysts. The Illinois Biotechnology Innovation Organization advocates for state-level incentives matching California's Safer Consumer Products framework.
United States Biocatalyst Market Key Industry Players
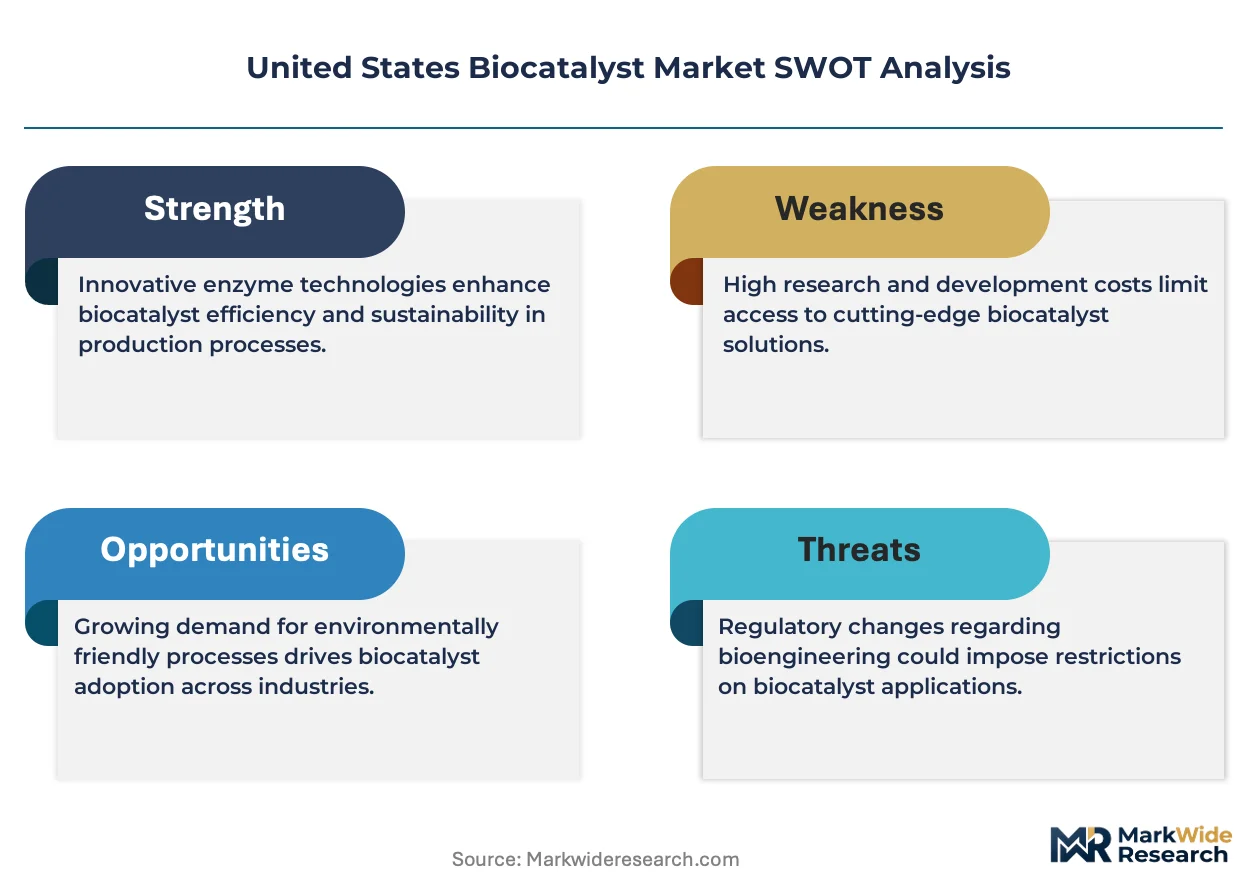
Premium-margin players sit above commodity-margin players across regulatory validation depth and protein engineering sophistication. The vendor base stratifies into three tiers: integrated chemical conglomerates bundling process optimization services, synthetic biology specialists commanding development timeline premiums, and fermentation-scale commodity producers competing on unit cost. Strategic moves concentrate on modular enzyme kit standardization and geographic manufacturing diversification beyond California concentration.
Within the integrated chemical tier, BASF SE leverages its manufacturing network to bundle immobilized systems with technical services. Among synthetic biology specialists, Codexis, Inc. occupies a position exemplifying premium positioning through proprietary protein engineering platforms. At the fermentation-scale commodity end, Novozymes A/S anchors the food-grade enzyme segment through direct technical service teams embedded with industrial manufacturers.
| Leading Market Players |
|---|
| BASF SE |
| AB Enzymes GmbH |
| DuPont de Nemours, Inc. |
| Chr. Hansen Holding A/S |
| Amano Enzyme Inc |
| Codexis, Inc. |
| DSM-Firmenich AG |
| Advanced Enzyme Technologies Ltd. |
| Novozymes A/S |
| Others |
Cost & Logistics Intelligence
Pharmaceutical manufacturers with GMP-validated procurement requirements anchor pricing power in the United States biocatalyst market, commanding volume discounts that compress margins for mid-tier fermentation-scale suppliers while rewarding synthetic biology specialists with development-timeline premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Codexis-engineered immobilized systems from BASF-integrated process bundles and commodity food-grade enzymes. Price differentiation rests on FDA validation depth and protein engineering sophistication, with California's generic drug manufacturers showing highest sensitivity to unit cost and Massachusetts-based innovators absorbing premium tiers for accelerated timelines. Cost compression in commodity enzymes is intensifying because Novozymes' embedded technical service teams reset baseline expectations for after-sales support.
Supply Chain Analysis
Domestic-content mandates under California's Safer Consumer Products regulations are reshaping sourcing toward in-state fermentation capacity and away from Asian enzyme imports. Production gravity centers on California, Massachusetts, and North Carolina, with raw material dependencies spanning corn-derived glucose for microbial cultivation, specialty resin carriers for immobilization, and CRISPR reagents for strain engineering. Single-source vulnerability concentrates in California's Bay Area synthetic biology cluster, where temperature-sensitive enzyme formulations demand cold-chain distribution through Gulf Coast logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States biocatalyst market functions as a regulatory compounder, with FDA Current Good Manufacturing Practice enforcement tightening process validation requirements that permanently elevate demand for validated enzymatic supply chains.
For Market Incumbents: Cement regulatory familiarity advantage by embedding technical service teams with pharmaceutical manufacturers in South San Francisco and Cambridge, mirroring Novozymes' channel control model. Deepen backward integration into CRISPR reagent supply to offset protein engineering talent scarcity constraining custom catalyst throughput. Prioritize capacity addition in North Carolina's Research Triangle Park to diversify beyond California concentration risk. For New Entrants and Emerging Players: Contract research organizations represent the most accessible channel partner type for synthetic biology specialists seeking pharmaceutical pipeline integration. White-space targets include USDA biofuel blending mandate pull in Midwest ethanol corridors and modular enzyme kit standardization for industrial manufacturers outside California's cluster. Target Texas biotech corridor expansion with business-friendly regulatory positioning against coastal compliance burdens. For Investors and Strategic Acquirers: Pharmaceutical conglomerates with enzyme-dependent API pipelines are the most active acquirer in this space, seeking synthetic biology capabilities to compress development timelines. Long-term viability favors platforms with CRISPR-enabled strain engineering and established FDA validation dossiers. Watch EPA New Chemicals Program biotechnology rulemakings as the critical inflection indicator for engineered microbial biocatalyst market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Platform Acquisition | Pharmaceutical conglomerates absorb synthetic biology capabilities to compress custom enzyme development from years to months. |
| North Carolina Manufacturing Scale-Up | Contract manufacturing organizations expand fixed-bed reactor capacity for immobilized enzyme systems serving RTP-adjacent biofuel producers. |
| FDA Validation Dossier Investment | Enzyme suppliers harden supplier qualification barriers against emerging competitors lacking batch consistency documentation. |
| USDA Biofuel Partnership | Cellulase producers secure long-term offtake agreements with Midwest ethanol facilities facing renewable fuel standard obligations. |
| Texas Corridor Geographic Expansion | California-based firms establish manufacturing redundancy through Houston's repurposed petrochemical fermentation infrastructure. |
Research Approach
Coverage spans California, Massachusetts, North Carolina, Texas, and Illinois, with primary inputs from each state-level biotechnology cluster. The research combines structured interviews with protein engineering directors, pharmaceutical procurement leads, fermentation facility managers, and regulatory affairs specialists with secondary validation through FDA 483 inspection observations, EPA biotechnology rulemaking dockets, USDA biofuel mandate documentation, and state-level Safer Consumer Products enforcement records. Bottom-up enzyme volume modeling triangulates against top-down pharmaceutical intermediate demand estimates.
Granularity-level framing applies distinct analytical treatments across product architectures, with immobilized enzyme systems modeled at facility-level fixed-bed reactor configurations and soluble enzymes at batch-scale pharmaceutical synthesis volumes. Segmentation dimensions span product type, application vertical, technology platform, and end-user procurement sophistication, with CAGRs derived from trend extrapolation of CRISPR-enabled development timeline compression and regulatory validation burden trajectories. Forecast inputs incorporate synthetic biology platform adoption curves and California chemical substitution enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA New Chemicals Program biotechnology rulemaking timelines and protein engineering talent pipeline constraints. The analysis reflects documented assumptions regarding FDA Current Good Manufacturing Practice enforcement continuity and USDA renewable fuel standard stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Americas Enzymes Market
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
Lipase Enzymes Market
Industrial Biotechnology
Styrene Monooxygenase Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Beta-Glucanase Market