
 Global Carbohydrase Market | 2026-2036
Global Carbohydrase Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbohydrase Market Foresight
Cellulase is pivoting from textile desizing into second-generation biofuel pre-treatment, compressing unit economics for biomass conversion. Novozymes leverages its Nordic R&D footprint to sustain technology leadership in thermostable amylase variants. BASF SE anchors European supply security through backward integration into fermentation feedstock networks. DuPont competes on pharmaceutical-grade enzyme purity standards, occupying a defensible position in high-specification contract manufacturing.
Carbohydrases constitute a class of hydrolytic enzymes that cleave glycosidic bonds in carbohydrate substrates, typically operating at pH ranges of 4.5–7.0 and temperatures between 45°C and 90°C depending on the specific enzyme and industrial application; their primary commercial purpose is to catalyze starch liquefaction, saccharification, and modification across food processing, fuel ethanol production, and animal nutrition systems. Alpha-amylase dominates volume demand as the workhorse enzyme in high-fructose corn syrup production, where thermal stability requirements create premium pricing tiers for engineered variants. Glucoamylase captures concentrated margin pools in brewing applications, where complete dextrose conversion determines yield economics. Invertase retains niche but protected positioning in confectionery manufacturing, where sucrose hydrolysis speed controls production throughput.
FDA food additive regulations and EPA renewable fuel standards jointly shape enzyme qualification pathways and biofuel offtake certainty in the United States, while REACH compliance in Europe governs enzyme formulation disclosure and occupational exposure thresholds. India's FSSAI and BIS standards create parallel certification requirements for imported enzyme preparations used in processed food and feed applications. Stakeholders must monitor how evolving carbon accounting rules under the EU Green Deal reshape biofuel enzyme demand specifications and supplier qualification criteria.
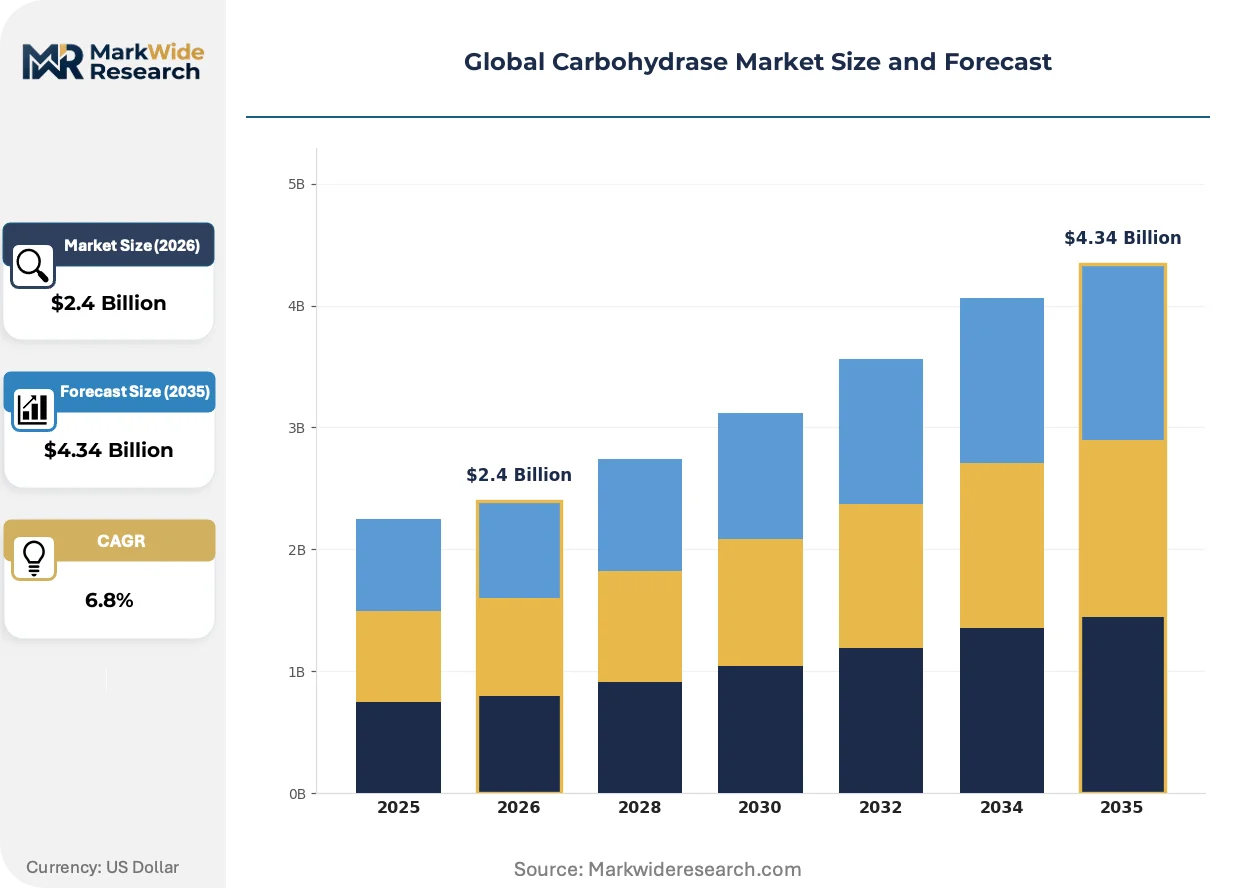
Market Dynamics
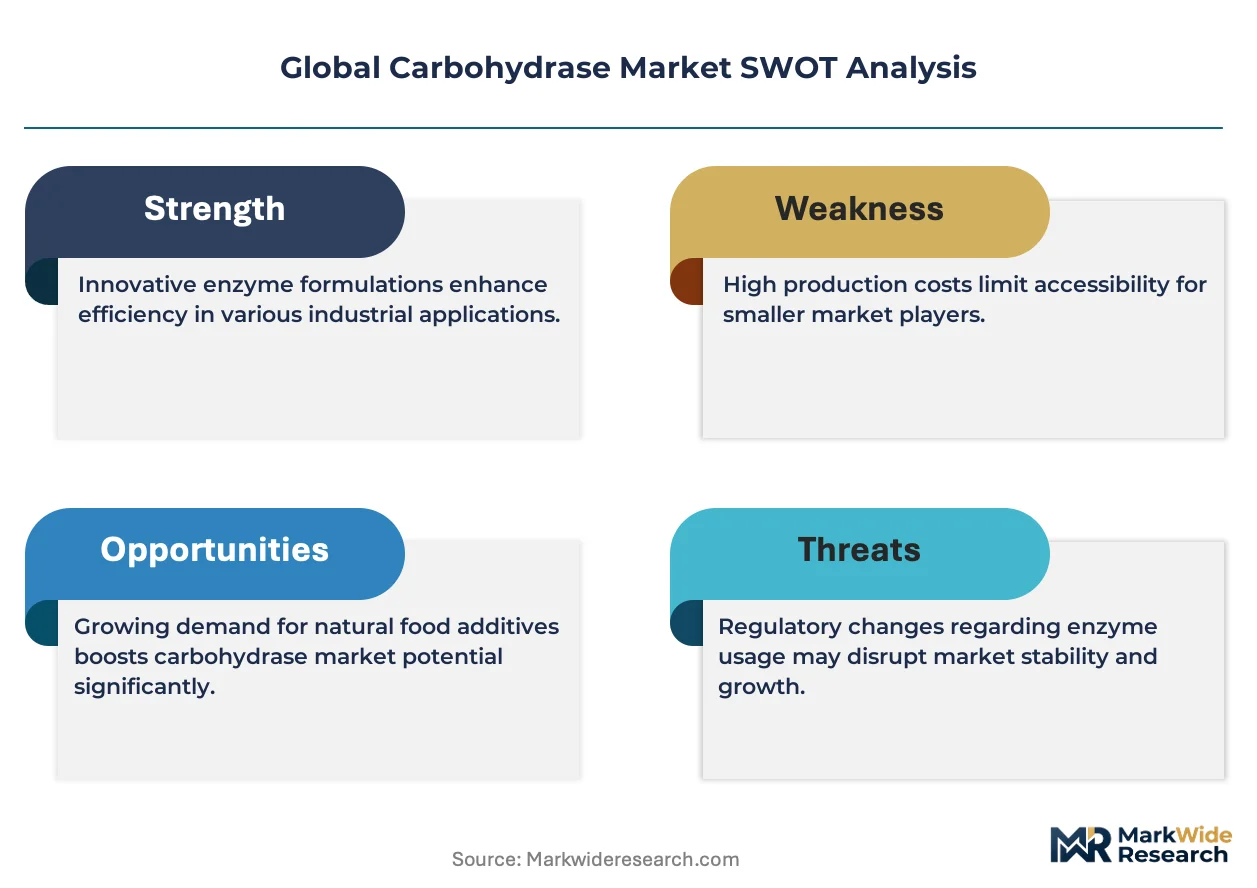
EU Green Deal carbon accounting rules and F-Gas Regulation efficiency mandates are compressing process economics for industrial enzyme manufacturers, forcing rapid fermentation technology upgrades and feedstock sourcing reconfigurations across European production clusters.
Growth Catalysts
- Clean-label baking demand:Food and beverage manufacturers in Germany and France are accelerating enzyme adoption to replace chemical conditioners in bread and pastry applications.
- REACH disclosure frameworks:ECHA compliance requirements for enzyme formulation transparency are standardizing quality tiers and locking out unqualified suppliers.
- Second-generation biofuel pre-treatment:Cellulase deployment in lignocellulosic ethanol plants is unlocking stranded biomass feedstocks in Nordic and Baltic markets.
Market Restraints
- Fermentation feedstock volatility:Corn and wheat starch price swings in Black Sea supply corridors compress margin predictability for glucoamylase producers.
- Thermostability patent thickets:Engineered alpha-amylase variants remain locked behind overlapping IP estates, constraining independent R&D pathways.
- Pharmaceutical-grade purity thresholds:FDA and EMA endotoxin limits for parenteral enzyme applications create insurmountable qualification barriers for mid-tier manufacturers.
Strategic Opportunities
- India feed enzyme penetration:FSSAI and BIS standard harmonization is opening import pathways for carbohydrase preparations in poultry and aqua nutrition.
- Continuous stirred-tank fermentation:Integration of real-time metabolite sensing with automated pH control is slashing batch cycle times in amylase production.
- Carbon border adjustment mechanisms:EU CBAM phase-in is creating preferential offtake terms for enzyme suppliers with verified low-emission fermentation footprints.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates in Danish and German biotech clusters, constraining facility expansion timelines elsewhere.
- Multi-jurisdiction certification lag:Parallel FDA, EMA, and PMDA enzyme master file submissions extend time-to-revenue for novel thermostable variants by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbohydrase Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-Amylase, Glucoamylase, Amyloglucosidase, Invertase Application: Baking, Brewing, Biofuel Production, Animal Feed End User: Food & Beverage, Pharmaceuticals, Bioenergy, Animal Nutrition Form: Liquid, Powder, Granular, Others |
| Companies Covered | AB Enzymes, Advanced Enzymes, Novozymes, Chr. Hansen Holding A/S, BASF SE, DuPont, Amano Enzyme Inc., Dyadic International Inc., Royal DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbohydrase Market Shifts & Advancements
Digital twin modeling of fermentation kinetics is compressing strain optimization cycles, while regulatory carbon intensity tracking is rewiring supplier qualification protocols across biofuel and food processing value chains.
Single-use bioreactor systems for carbohydrase production are unifying upstream seed train and downstream capture operations into continuous processing architectures. Contract manufacturers in the Netherlands and Switzerland are adopting these platforms to serve pharmaceutical-grade enzyme demand. The technology is unifying capital efficiency with regulatory flexibility, enabling rapid product changeovers between amylase and cellulase campaigns.
F-Gas Regulation phase-down schedules are forcing refrigeration-dependent fermentation facilities toward ammonia-based cooling or geothermal heat exchange. German enzyme plants around Hamburg are retrofitting absorption chillers to maintain sub-30°C seed tank temperatures. The policy shift is accelerating capital deployment into process heat integration, with Nordic producers leveraging district heating networks for competitive advantage.
Ingredient buyers in high-fructose corn syrup production are consolidating supplier rosters from six-vendor portfolios to dual-source arrangements with integrated fermentation-to-formulation capabilities. This concentration is compressing pricing leverage for standalone enzyme traders and elevating contract tenure requirements. The pattern is most pronounced among US Midwest ethanol producers seeking supply security under EPA renewable fuel standard compliance deadlines.
Global Carbohydrase Market Segmentation
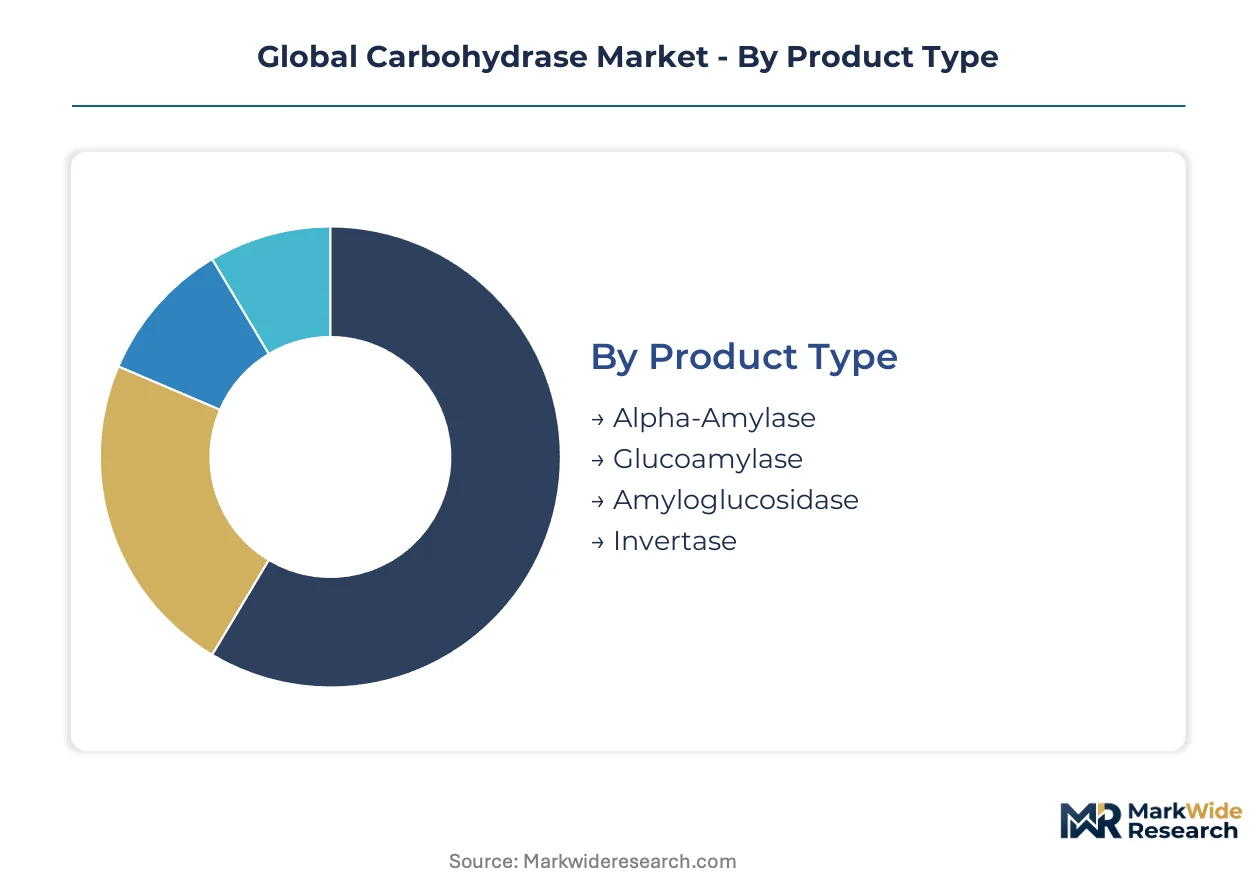
Carbohydrase procurement decisions pivot on thermal stability specifications, regulatory compliance tiers, and integration depth with downstream fermentation processes. Buyers evaluate enzyme formulations against pH tolerance windows, substrate specificity, and supplier qualification status across FDA, EFSA, and FSSAI jurisdictions.
Product Type:
Thermostability requirements in starch liquefaction and saccharification stages drive formulation selection and premium tiering.
- Alpha-Amylase:Endoenzyme that randomly hydrolyzes alpha-1,4 glycosidic bonds in starch polymers, typically sourced from Bacillus licheniformis for industrial thermal tolerance. Demand concentrates in US Midwest ethanol plants where liquefaction temperature above 105°C eliminates mesophilic alternatives. FDA food additive status and EPA renewable fuel pathway qualification create dual compliance thresholds that lock out uncertified suppliers.
- Glucoamylase:Exoenzyme releasing glucose units from non-reducing ends of starch chains, with Aspergillus niger-derived variants dominating commercial supply. Brewing applications in Germany and Belgium prioritize complete dextrose conversion yield, while Indian bioethanol distilleries under BIS standards seek cost-optimized formulations for molasses fermentation.
- Amyloglucosidase:Catalytic variant with identical substrate specificity to glucoamylase but optimized for lower pH operation in fruit processing. European fruit juice concentrators leverage this specificity for starch haze removal under EFSA processing aid approvals.
- Invertase:Beta-fructofuranosidase hydrolyzing sucrose to glucose-fructose mixtures, essential for soft-center confectionery manufacturing. Swiss and Belgian chocolate producers maintain captive demand for high-purity pharmaceutical-grade preparations.
Alpha-Amylase leads on scale; Glucoamylase leads on momentum.
Application:
Process integration depth and substrate handling complexity determine enzyme dosing economics and supplier contract structures.
- Baking:Enzyme blends replace chemical oxidizers and emulsifiers in clean-label bread formulations. German and French manufacturers under EU Green Deal sustainability reporting requirements prioritize fungal amylase for dough conditioning with verifiable carbon intensity credentials.
- Brewing:Mashing efficiency and attenuation control depend on glucoamylase adjunct dosing alongside native malt enzymes. Czech and Belgian craft breweries specify fungal alpha-amylase for high-adjunct mashes, while industrial lager producers in Brazil optimize for cost per hectoliter.
- Biofuel Production:Cellulase and amylase cocktails unlock lignocellulosic and starch-based ethanol pathways respectively. Nordic producers leveraging district heating integration achieve fermentation cost advantages under EU CBAM carbon accounting rules.
- Animal Feed:NSP-degrading carbohydrases improve digestibility in wheat and barley-based poultry rations. Indian integrators under FSSAI feed additive regulations are expanding imports of thermostable xylanase-amylase blends for tropical climate stability.
Biofuel Production commands the steepest expansion trajectory; Baking maintains the deepest supplier relationships.
End User:
Regulatory stringency and purity certification requirements fragment procurement specifications across value chains.
- Food & Beverage:Largest volume sink with tiered qualification pathways from GRAS self-affirmation to FDA food additive petition approval. US high-fructose corn syrup manufacturers consolidate around dual-source supply with integrated fermentation capabilities.
- Pharmaceuticals:Parenteral and oral dosage applications demand endotoxin-controlled, animal-origin-free enzyme preparations. EMA and FDA master file submissions extend supplier qualification timelines to 24 months, concentrating demand on established contract manufacturers in Switzerland and the Netherlands.
- Bioenergy:EPA renewable fuel standard compliance creates offtake certainty for qualified enzyme suppliers serving US ethanol producers. Carbon intensity scoring under California LCFS and impending EU CBAM is reshaping supplier selection toward low-emission fermentation footprints.
- Animal Nutrition:Feed enzyme regulations under FSSAI, BIS, and EU Feed Additives Regulation create parallel certification requirements. Brazilian and Indian poultry integrators drive volume growth for heat-stable phytase-carbohydrase combinations.
Food & Beverage dominates absolute volume; Pharmaceuticals captures the highest margin per kilogram.
Form:
Handling logistics, storage stability, and dosing precision requirements determine formulation selection across climate zones.
- Liquid:Standard concentrated preparations for automated dosing in continuous process lines. Tropical humidity exposure in Southeast Asian ethanol plants drives demand for stabilized glycerol-based formulations with extended shelf life.
- Powder:Spray-dried preparations for dry blending in flour and feed premixes. German milling operations prioritize dust-free granulation for occupational exposure compliance under REACH.
- Granular:Extruded formulations with controlled release characteristics for rumen-protected feed applications. US dairy nutrition specialists specify lipid-coated granules for bypass protein synchronization.
- Others:Immobilized enzyme preparations and customized tablet forms for specialized pharmaceutical and analytical applications. Japanese diagnostic reagent manufacturers source precision-immobilized amylase for automated clinical analyzers.
Liquid formulations lead on volume throughput; Granular preparations are climbing fastest in premium feed applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biotech clusters around Munich and Hamburg anchor enzyme manufacturing scale for European supply security, while regulatory pressure from Brussels reshapes production economics across the continent.
Germany
Clean-label baking applications and second-generation biofuel pre-treatment drive enzyme demand from Bavarian food processors and Lower Saxony biorefineries. The EU Green Deal and F-Gas Regulation mandate ammonia-based cooling retrofits for Hamburg fermentation facilities. Munich-based R&D centers develop thermostable amylase variants for starch liquefaction above 105°C.
United States
High-fructose corn syrup manufacturers and Midwest ethanol plants concentrate demand for FDA-qualified alpha-amylase preparations. EPA renewable fuel standards create dual compliance thresholds with FDA food additive regulations for biofuel enzyme suppliers. Iowa and Illinois processing corridors consolidate supplier rosters toward integrated fermentation-to-formulation capabilities.
India
Poultry integrators and aqua nutrition specialists expand imports of heat-stable carbohydrase blends for tropical climate operations. FSSAI and BIS standards harmonize import pathways for feed enzyme preparations while creating parallel certification requirements. Maharashtra and Gujarat pharmaceutical hubs demand endotoxin-controlled enzyme preparations for contract manufacturing expansion.
Netherlands
Single-use bioreactor adoption unifies upstream and downstream operations for pharmaceutical-grade enzyme contract manufacturers. REACH disclosure frameworks standardize quality tiers and lock out unqualified suppliers from Rotterdam distribution corridors. Dutch facilities serve Swiss and German pharmaceutical demand with rapid product changeover capabilities between amylase and cellulase campaigns.
Japan
Diagnostic reagent manufacturers source precision-immobilized amylase for automated clinical analyzers in Kanto and Kansai industrial zones. PMDA enzyme master file submissions extend qualification timelines, concentrating demand on established suppliers with regulatory track records. METI industrial biotechnology programs support fermentation scale-up expertise development for domestic enzyme production.
Global Carbohydrase Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated fermentation-to-formulation capabilities separate tier-one suppliers from standalone enzyme traders. The vendor base stratifies across three archetypes: Nordic R&D-driven specialists with thermostability patent estates, German chemical conglomerates with backward integration into feedstock networks, and Asian fermentation-scale specialists serving cost-optimized regional demand. M&A activity and continuous stirred-tank fermentation technology licensing represent the dominant competitive moves for securing contract tenure with consolidating buyer rosters.
Among Danish biotechnology specialists, Novozymes occupies a position exemplifying R&D-intensive thermostable variant development. BASF SE anchors European supply security archetypes through integrated chemical-enzyme manufacturing footprints. DuPont represents pharmaceutical-grade purity standards positioning for high-specification contract manufacturing qualification. These three entities collectively illustrate the geographic and capability segmentation defining competitive positioning across food, fuel, and pharmaceutical enzyme value chains.
| Leading Market Players |
|---|
| AB Enzymes |
| Advanced Enzymes |
| Novozymes |
| Chr. Hansen Holding A/S |
| BASF SE |
| DuPont |
| Amano Enzyme Inc. |
| Dyadic International Inc. |
| Royal DSM |
| Others |
Supply & Pricing Matrix
Corn starch futures volatility on the Chicago Board of Trade cascades through fermentation economics into three-tier pricing stratification across premium thermostable variants, standard industrial grades, and economy feed-enzyme formulations. Black Sea wheat price swings compress margin buffers for glucoamylase producers serving European bioethanol corridors, while EU Green Deal carbon accounting rules reweight supplier selection toward verified low-emission fermentation footprints.
Pricing Analysis
Input-cost pass-through from agricultural feedstock markets governs contract structures, with corn and wheat starch price movements transmitting directly into alpha-amylase and glucoamylase quotations within 60-90 day lags. Price differentiation separates FDA-food-additive-qualified preparations from uncertified commodity grades, while volume-scale discounts concentrate among Midwest ethanol producers consolidating toward dual-source arrangements. Pricing pressure stems from fermentation feedstock volatility in Black Sea supply corridors, with standalone enzyme traders facing margin compression against integrated fermentation-to-formulation suppliers. Pharmaceutical-grade endotoxin-controlled preparations exhibit lowest price sensitivity; Indian poultry feed integrators under FSSAI standards show highest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Danish and German biotech clusters for thermostable strain development and fermentation scale-up expertise. Manufacturing concentrates in Germany, Denmark, and the Netherlands, with Munich and Hamburg anchoring European supply security through backward integration into feedstock networks. Raw material dependencies rest on corn starch, wheat derivatives, and ammonia-based cooling infrastructure retrofitted under F-Gas Regulation mandates. Supply chain risk centers on bioprocess engineering talent scarcity constraining facility expansion timelines outside established clusters. Distribution runs through Rotterdam pharmaceutical corridors for EMA-qualified contract manufacturers and Midwest rail-liquid terminals for US ethanol plant supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in thermostable variant premiumization and continuous stirred-tank fermentation cost-down curves, with carbon intensity verification emerging as a pricing power amplifier under EU CBAM phase-in.
For Market Incumbents: Acquire continuous stirred-tank fermentation technology platforms to compress batch cycle times and defend against standalone enzyme traders losing pricing leverage. Consolidate supplier rosters from six-vendor portfolios to dual-source arrangements with captive strain development capabilities, locking in contract tenure through integrated fermentation-to-formulation offerings. Invest in ammonia-based cooling retrofits ahead of F-Gas Regulation phase-down deadlines to secure qualification status for EU biofuel enzyme supply. For New Entrants and Emerging Players: Indian poultry integrators under FSSAI feed additive regulations represent the most penetrable buyer archetype, with heat-stable xylanase-amylase blends for tropical climate operations commanding import substitution potential. Nordic lignocellulosic ethanol plants seeking cellulase supply under EU Green Deal carbon accounting rules offer second-mover entry points. Pursue toll manufacturing arrangements with established fermentation facilities to bypass bioprocess engineering talent scarcity and accelerate time-to-revenue. For Investors and Strategic Acquirers: Asymmetric upside sits with contract manufacturers in the Netherlands and Switzerland possessing single-use bioreactor platforms and rapid product changeover capabilities between amylase and cellulase campaigns. Long-term viability over the projection horizon favors entities with verified low-emission fermentation footprints and EMA/FDA master file track records. Watch for EU CBAM carbon border adjustment enforcement intensity as the inflection signal reshaping supplier qualification protocols and contract pricing structures.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Stirred-Tank Fermentation Scale-Up | Real-time metabolite sensing integration slashes batch cycle times in Danish production clusters. |
| Backward Integration into Feedstock Networks | German chemical conglomerates anchor supply security through captive corn starch sourcing. |
| Pharmaceutical-Grade Purity Certification | EMA and FDA master file submissions extend barriers to entry for parenteral enzyme applications. |
| Carbon Intensity Verification Programs | EU CBAM phase-in creates preferential offtake terms for low-emission fermentation suppliers. |
| Single-Use Bioreactor Platform Adoption | Dutch contract manufacturers unify upstream and downstream for rapid product changeover. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at European and US enzyme production facilities, procurement leads at Midwest ethanol processors, regulatory affairs specialists navigating FDA and EMA enzyme master file pathways, and feed formulation directors at Indian poultry integrators were cross-validated against secondary sources including ECHA REACH disclosure databases, EPA renewable fuel standard compliance filings, FSSAI feed additive registration records, and customs trade data for enzyme preparation imports.
Historical trendline analysis across thermostability specification tiers, regulatory compliance categories, and integration depth with downstream fermentation processes established baseline growth patterns. The forecast framework models volume and value trajectories across product type segments, application verticals, end-user industries, and formulation formats, with CAGRs derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific inputs include EU Green Deal carbon accounting rule implementation schedules and F-Gas Regulation phase-down timelines affecting refrigeration-dependent facilities.
Underlying measurement precision varies by segment; pharmaceutical-grade and food-additive-qualified preparations carry tighter precision than economy feed-enzyme categories due to registration disclosure requirements. Forecasts reflect assumptions regarding regulatory enforcement intensity, feedstock price stabilization, and bioprocess engineering talent mobility across jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Americas Enzymes Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Styrene Monooxygenase Market
Industrial Biotechnology
Biocatalyst Market