
 Tannase Market | 2026-2036
Tannase Market Size, Share, and Industry Trends Forecast 2026-2036
Tannase Market Analytics
The EU Green Deal is consolidating demand for bio-based processing enzymes across European food and beverage supply chains. Novozymes leverages its fermentation scale to dominate microbial tannase supply for continental dairy and wine applications. Amano Enzyme anchors Japanese pharmaceutical-grade production with specialized fungal tannase strains. DSM N.V. competes through backward integration into substrate cultivation, securing consistent raw material flows for European tanneries.
Tannase is an esterase enzyme that hydrolyzes ester bonds in tannins, typically operating at temperatures between 30°C and 50°C with optimal activity in mildly acidic conditions around pH 5.0 to 6.5; manufacturers deploy it to eliminate turbidity in beverages, soften leather hides, and modify polyphenol bioavailability in pharmaceutical formulations. Microbial tannase leads volume owing to scalable submerged fermentation and consistent batch-to-batch activity, while fungal tannase commands premium positioning in pharmaceutical production where specific substrate selectivity determines therapeutic efficacy. Powder form dominates industrial procurement for stability in extended storage and ease of dosing into tannery baths and beverage processing lines.
REACH in Europe and FDA enzyme safety guidelines in the United States shape substrate traceability and purity certification requirements for cross-border enzyme shipments. BIS standards in India and GB standards in China add national compliance layers for domestic manufacturing and import substitution programs. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration timelines with regional capacity expansion decisions.
Market Dynamics
Fermentation capacity concentration in China and tightening substrate traceability mandates under REACH and FDA guidelines are restructuring competitive positioning in tannase supply chains.
Growth Catalysts
- EU Green Deal bio-based mandates:Food and beverage processors across Germany, France, and Italy must substitute synthetic clarifying agents with enzymatic alternatives, pulling microbial tannase into wine stabilization and juice processing workflows.
- Leather sector expansion in Asia-Pacific:Tanneries in India and Vietnam are scaling hide-softening operations, creating sustained volume demand for fungal tannase variants in beamhouse processing stages.
- Submerged fermentation automation:Chinese manufacturers are deploying computer-controlled bioreactor systems that compress batch-to-batch variability, lowering quality assurance costs for export-grade enzyme shipments.
Market Restraints
- Tannin feedstock volatility:Gallic acid and tannic acid prices fluctuate with Chinese chestnut and Turkish sumac harvest cycles, squeezing margin stability for fermentation-based producers.
- Single-source substrate dependence:European tannase manufacturers rely predominantly on Chinese gallnut extracts, exposing supply continuity to customs processing delays and phytosanitary certificate backlogs.
- Enzyme stability limitations:Liquid tannase formulations degrade above 25°C during extended storage, forcing cold-chain logistics that inflate distribution costs to tropical markets.
Strategic Opportunities
- Pharmaceutical polyphenol modification:Drug formulators in Switzerland and Japan are testing tannase-catalyzed conversions for enhanced bioavailability of tannin-derived therapeutics, opening premium pricing tiers.
- Indian PLI scheme alignment:Domestic enzyme manufacturers can access production-linked incentives by qualifying microbial tannase under the country's biotechnology sector subsidies.
- E-commerce industrial procurement:Specialty chemical platforms are enabling mid-sized tanneries in Brazil and Mexico to bypass distributor markups through direct enzyme sourcing.
Industry Challenges
- Fermentation specialist scarcity:Industrial microbiology talent pools in Eastern Europe and Southeast Asia remain thin, constraining rapid scale-up of new production facilities.
- Multi-jurisdiction registration timelines:Synchronizing dossier submissions across EMA, FDA, and NMPA pathways extends product launch windows by 18-24 months for novel tannase strains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tannase Market |
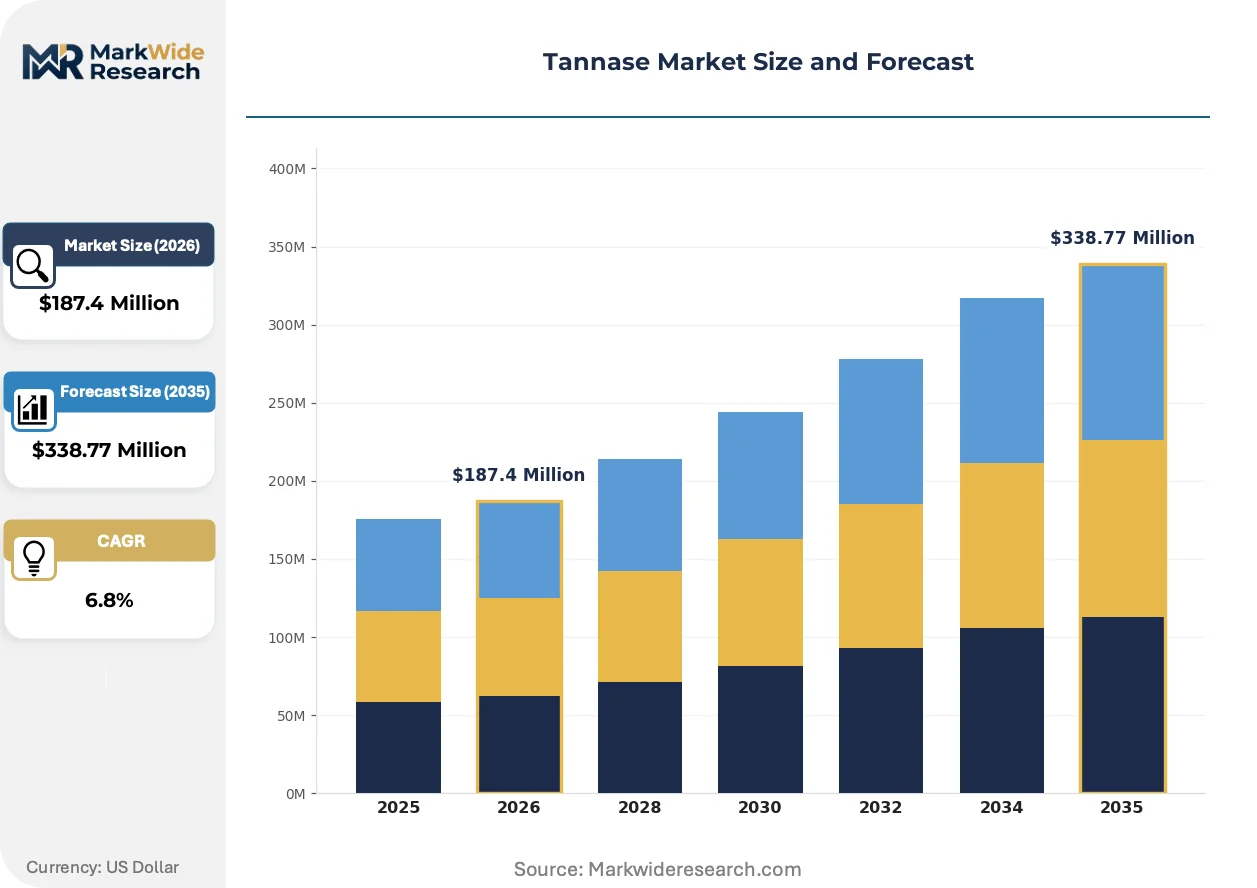
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Tannase, Plant Tannase, Fungal Tannase, Bacterial Tannase Application: Food Processing, Beverage Production, Leather Industry, Pharmaceutical Production Form: Liquid, Powder, Granular, Tablet End User: Food Manufacturers, Beverage Companies, Leather Tanners, Pharmaceutical Firms |
| Companies Covered | Novozymes, DSM N.V, Amano Enzyme, Creative Enzymes, Merck KGaA, AB Enzymes, Danisco, Biocon, Kikkoman Biochemifa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tannase Market Evolving Landscape
Process intensification and regulatory disclosure requirements are compressing traditional enzyme production cycles while fragmenting procurement channels across direct and platform-based sourcing models.
Cell-free enzyme systems are expanding into commercial viability for high-purity pharmaceutical applications. Swiss and German contract manufacturers are piloting cell-free tannase production to eliminate endotoxin contamination risks inherent in whole-cell fermentation. This approach is expanding into therapeutic-grade supply chains where batch consistency requirements exceed conventional bioprocessing capabilities.
REACH Article 33 disclosure obligations are forcing substrate provenance documentation down to the harvest site level. European tanneries and beverage processors must now map tannin extracts to specific forest cooperatives in China and Turkey, with ECHA compliance audits verifying chain-of-custody integrity. Small-batch artisanal producers in France and Italy face particular strain from this traceability burden.
Specification-driven purchasing is consolidating buyer power among large-scale tannery groups and multinational beverage conglomerates. Mid-sized enzyme distributors in India and Brazil are losing share to manufacturer-direct technical service teams that embed formulation chemists at customer sites. This shift is most visible in São Paulo and Mumbai, where leather export houses now negotiate multi-year tannase supply agreements with fermentation companies rather than regional trading houses.
Tannase Market Segmentation
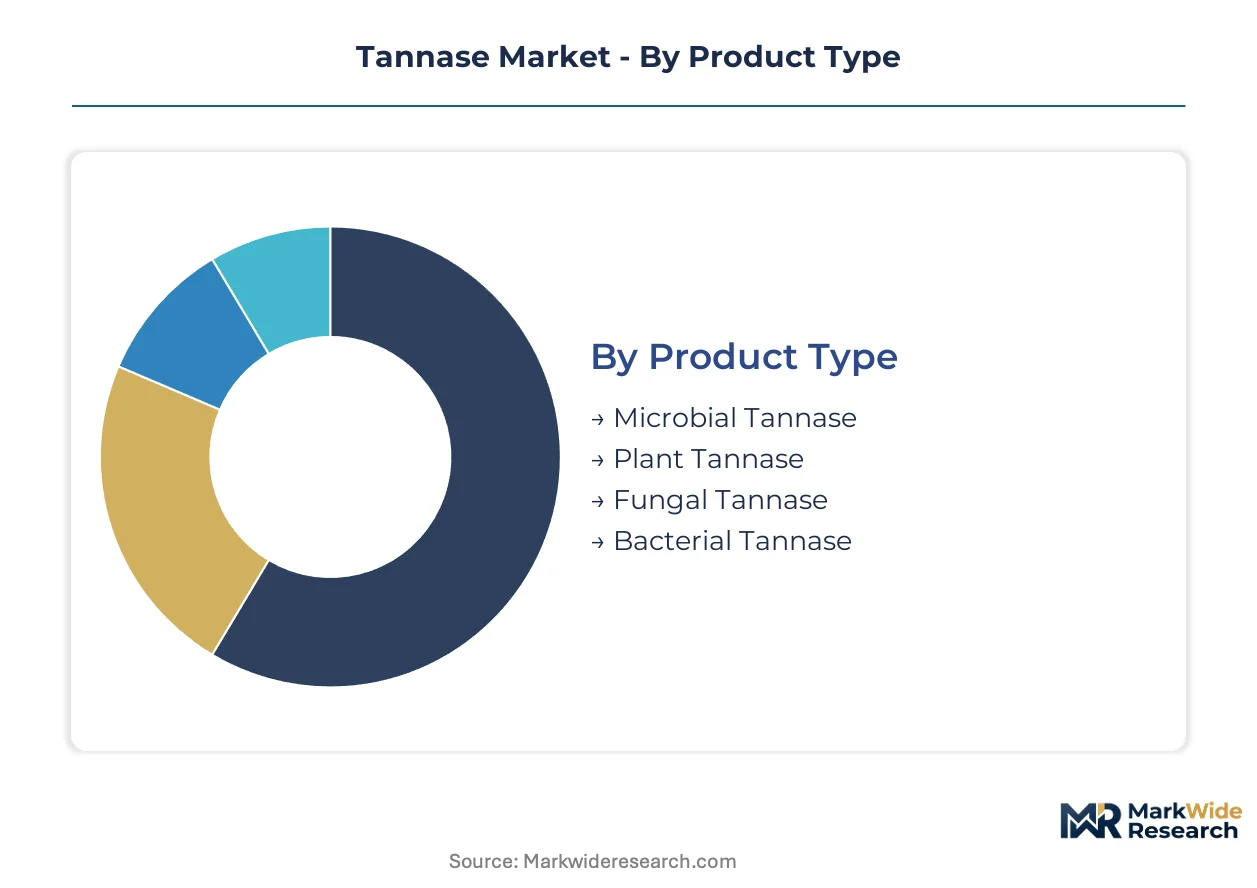
Tannase procurement decisions hinge on thermal stability requirements, substrate specificity, and downstream processing constraints. Manufacturers align product specifications with end-use performance thresholds rather than pursuing one-size-fits-all formulations.
Product Type:
Biocatalytic performance separates commercial viability across production platforms, with fermentation scalability and enzyme kinetics determining competitive positioning.
- Microbial Tannase:Submerged fermentation of Aspergillus and Penicillium strains delivers consistent batch-to-batch activity at 30-50°C operating ranges. Chinese manufacturers dominate volume supply for leather beamhouse operations in Hebei and Zhejiang provinces, where automated bioreactor systems compress quality assurance costs.
- Fungal Tannase:Higher substrate selectivity and mild pH optima around 5.0-6.5 command premium positioning in therapeutic applications. Swiss and Japanese pharmaceutical formulators specify fungal variants for polyphenol modification protocols requiring endotoxin control.
- Plant Tannase:Extracted from plant tissues including tea leaves and oak galls; limited commercial scale due to seasonal harvest dependency and extraction yield variability.
- Bacterial Tannase:Bacillus-derived variants exhibit broader pH tolerance but lower specific activity; niche deployment in industrial wastewater treatment for tannin degradation.
Mature deployment sits with Microbial Tannase. Newer deployment is concentrated in Fungal Tannase.
Application:
Process integration requirements and regulatory disclosure burdens fragment demand across industrial sectors with divergent purity thresholds.
- Food Processing:Enzymatic clarification of fruit juices and wine stabilization drives formulation standardization. Italian and French processors under EU Green Deal mandates substitute synthetic fining agents with tannase-catalyzed alternatives.
- Beverage Production:Haze elimination in apple cider and iced tea concentrates requires cold-active variants; Brazilian and Mexican mid-sized producers bypass distributor markups through e-commerce procurement platforms.
- Leather Industry:Beamhouse deliming and bating operations consume powder formulations for hide softening. Indian tanneries in Tamil Nadu and Uttar Pradesh scale beamhouse automation, pulling consistent-volume supply agreements.
- Pharmaceutical Production:Bioavailability enhancement of tannin-derived therapeutics demands GMP-grade certification. Cell-free production systems are gaining traction in Swiss contract manufacturing to eliminate endotoxin contamination risks.
Volume concentration centers on Leather Industry applications. Steepest expansion trajectory appears in Pharmaceutical Production.
Form:
Storage stability and dosing precision dictate procurement preferences across climatic zones and facility automation levels.
- Powder:Spray-dried formulations with maltodextrin carriers maintain activity above 12 months at ambient conditions. Dominates industrial procurement for tannery bath integration and bulk beverage processing.
- Liquid:Standardized activity units in glycerol-stabilized solutions enable precise metering in automated dosing systems. Cold-chain requirements above 25°C limit distribution reach to tropical markets without refrigerated logistics.
- Granular:Dust-free handling properties suit pharmaceutical cleanroom environments; higher unit costs constrain adoption outside premium therapeutic applications.
- Tablet:Pre-measured unit doses for laboratory-scale screening and artisanal wine production; minimal industrial volume.
Procurement scale favors Powder. Technical service embedding is accelerating for Liquid.
End User:
Specification authority and formulation expertise determine whether procurement flows through distributor networks or direct manufacturer relationships.
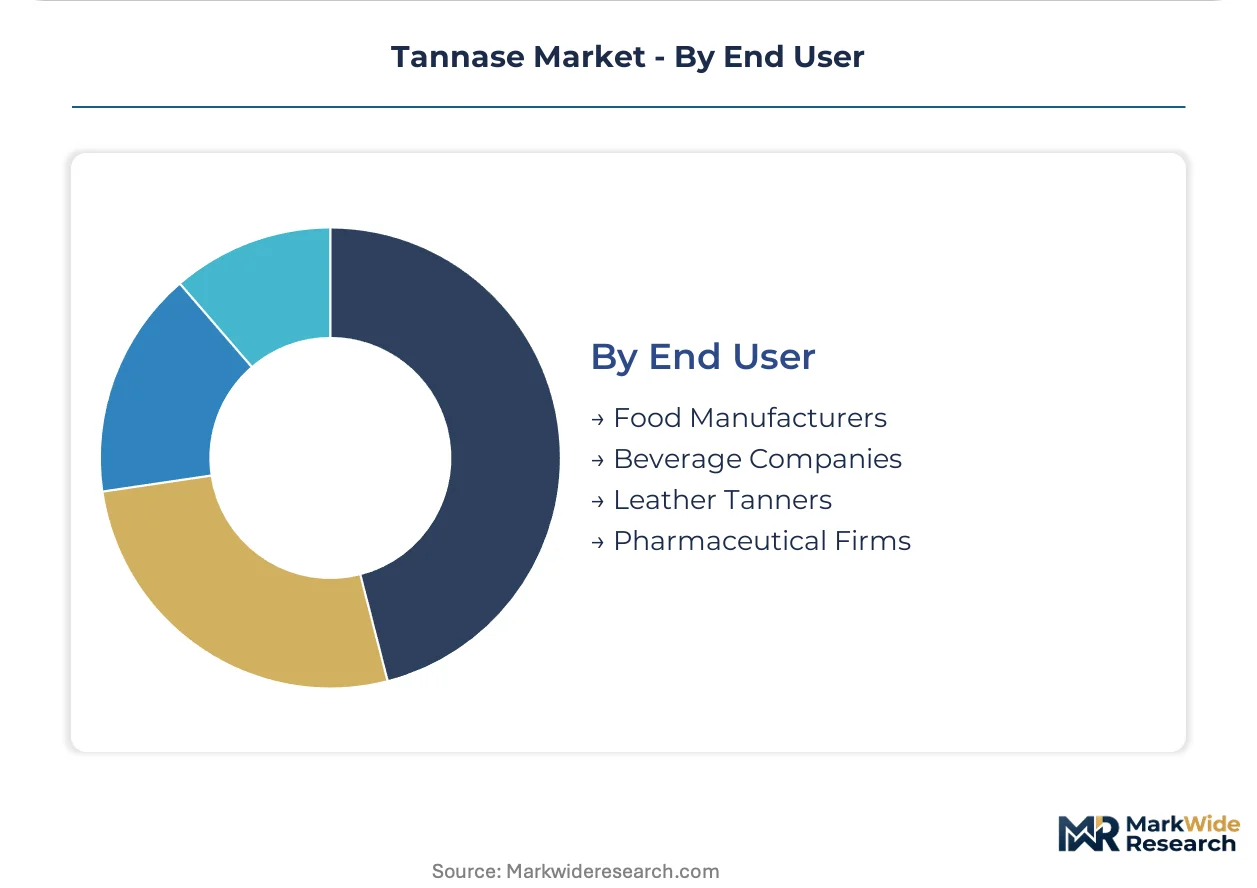
- Food Manufacturers:Multinational conglomerates consolidate buyer power through specification-driven purchasing with embedded technical service teams.
- Beverage Companies:Mid-sized regional processors in São Paulo and Mumbai shift from trading houses to direct fermentation company agreements.
- Leather Tanners:Export-oriented clusters in Vietnam and Bangladesh prioritize multi-year supply security over spot-market pricing.
- Pharmaceutical Firms:Swiss and Japanese drug developers drive demand for cell-free and GMP-certified production tiers.
Contracting leverage concentrates with Food Manufacturers. Relationship intensity is deepening fastest with Pharmaceutical Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang Province anchors the world's largest tannase fermentation capacity, with Hangzhou and Shaoxing biotech corridors supplying industrial-grade microbial enzymes to leather processors across Asia and Europe.
China
Submerged fermentation clusters in Hebei and Zhejiang provinces supply volume-grade microbial tannase for domestic tanneries and export markets. NMPA enzyme safety guidelines and GB standards mandate purity certification for cross-border shipments. Shandong Peninsula manufacturers deploy automated bioreactor systems to compress batch variability for wine stabilization enzyme exports.
India
Tamil Nadu and Uttar Pradesh leather export houses drive fungal tannase procurement for beamhouse automation. BIS standards and the PLI scheme for biotechnology incentivize domestic microbial enzyme manufacturing capacity. Kanpur and Chennai tannery clusters negotiate multi-year supply agreements directly with fermentation companies, bypassing traditional chemical distributors.
United States
FDA enzyme safety guidelines shape substrate traceability requirements for beverage clarification applications. California wine processors and Midwest juice concentrate manufacturers specify cold-active tannase variants for haze elimination. Greater Boston pharmaceutical formulators test cell-free enzyme systems for therapeutic-grade polyphenol modification protocols.
Germany
REACH Article 33 disclosure obligations force tanneries and beverage processors to map tannin extracts to specific harvest sites in China and Turkey. Bavarian and Baden-Württemberg wine cooperatives substitute synthetic fining agents under EU Green Deal bio-based mandates. Frankfurt chemical distributors lose share to manufacturer-direct technical service teams embedding formulation chemists at customer sites.
Switzerland
Swissmedic GMP certification requirements drive demand for endotoxin-controlled fungal tannase in pharmaceutical production. Basel-area contract manufacturers pilot cell-free enzyme systems to eliminate contamination risks from whole-cell fermentation. Zurich drug developers test tannase-catalyzed conversions for enhanced bioavailability of tannin-derived therapeutics, opening premium pricing tiers.
Tannase Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with GMP-grade and cell-free production commanding price multiples over standard industrial formulations. The market structures around three strategic archetypes: multinational fermentation specialists with backward integration into substrate cultivation, regional enzyme houses serving domestic tannery and beverage clusters, and emerging cell-free technology developers targeting pharmaceutical applications. Competitive moves concentrate on multi-year supply agreements with embedded technical service and capacity expansion in automated bioreactor facilities.
Among multinational specialists, Novozymes and DSM N.V. occupy positions as scale-driven fermentation leaders with continental European supply networks. Amano Enzyme exemplifies the premium-tier specialist archetype, anchoring pharmaceutical-grade production with specialized fungal strains. These three represent the dominant competitive anchors against which regional manufacturers and cell-free technology developers position alternative value propositions.
| Leading Market Players |
|---|
| Novozymes |
| DSM N.V |
| Amano Enzyme |
| Creative Enzymes |
| Merck KGaA |
| AB Enzymes |
| Danisco |
| Biocon |
| Kikkoman Biochemifa |
| Others |
Value Network & Pricing Analysis
Gallic acid and tannic acid price indices from Chinese chestnut and Turkish sumac harvest cycles cascade through fermentation economics into three-tier pricing structure across premium, standard, and economy levels, with GMP-certified fungal variants commanding multiples over industrial microbial grades while cold-chain liquid formulations inflate distribution costs to tropical markets.
Pricing Analysis
Yield-based pricing anchors pharmaceutical-grade contracts, with Swiss and Japanese drug developers paying premiums for endotoxin-controlled batch consistency. Price differentiation separates GMP-certified cell-free production from standard submerged fermentation, with volume scale and certification tier as primary drivers. Cost compression in industrial microbial grades is intensifying because Chinese automated bioreactor deployment compresses quality assurance overhead. Leather tanners in Vietnam and Bangladesh exhibit highest price sensitivity, while pharmaceutical formulators show least elasticity due to therapeutic efficacy requirements.
Supply Chain Analysis
Direct-to-tannery technical service teams handle large-scale buyer demand, displacing regional chemical distributors in São Paulo and Mumbai. Manufacturing gravity centers on China, India, and Germany, with substrate sourcing tethered to gallnut extracts from Chinese forest cooperatives, automated bioreactor components from German engineering suppliers, and maltodextrin carriers from Indian agricultural processors. Single-source dependence on Chinese gallnut extracts exposes continuity to phytosanitary certificate backlogs. Distribution runs through manufacturer-direct channels for multinational beverage conglomerates, with e-commerce platforms emerging for mid-sized Brazilian and Mexican processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-free enzyme production systems are displacing legacy whole-cell fermentation in pharmaceutical applications, creating asymmetric opportunity windows across certification tiers and geographic clusters.
For Market Incumbents: Lock in multi-year supply agreements with embedded formulation chemists at Vietnamese and Bangladeshi tannery export houses to defend against Chinese manufacturers' automated bioreactor cost advantages. Deepen backward integration into substrate cultivation to secure gallnut extract flows against REACH Article 33 traceability mandates and Turkish sumac harvest volatility. For New Entrants and Emerging Players: Launch via e-commerce industrial procurement platforms targeting mid-sized Brazilian and Mexican beverage processors seeking to bypass distributor markups for cold-active tannase variants. White-space concentration sits with cell-free production for Swiss and Japanese pharmaceutical applications, where endotoxin control requirements exceed incumbent whole-cell capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated fermentation specialists in Zhejiang and Hebei provinces with idle bioreactor capacity and established GB standard compliance. Long-term viability hinges on positioning for pharmaceutical-grade certification tier migration. Monitor NMPA enzyme safety guideline revisions as inflection signal for Chinese export-grade capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Free Production Scale-Up | Eliminates endotoxin contamination risks for Swissmedic GMP certification requirements. |
| Backward Integration into Substrate Cultivation | Secures gallnut extract supply continuity against REACH traceability audit burdens. |
| Automated Bioreactor Deployment | Compresses batch-to-batch variability for Chinese export-grade enzyme shipments. |
| Direct-to-Processor Technical Service Embedding | Displaces Indian and Brazilian chemical distributors through on-site formulation support. |
| E-Commerce Platform Partnership | Enables São Paulo and Mumbai mid-sized tanners to bypass traditional procurement markups. |
Research Methodology
Multi-period observation of fermentation capacity utilization rates, substrate price indices, and regulatory disclosure timelines anchored the trend analysis, supplemented by interviews with submerged fermentation plant managers, leather beamhouse procurement leads, pharmaceutical formulation chemists, and beverage processing technical directors. Secondary validation drew from NMPA enzyme safety filings, ECHA REACH Article 33 compliance databases, Chinese customs export records, and BIS standard certification registries. Bottom-up volume modeling triangulated against top-down expenditure estimates across end-use sectors.
Input-output matrices mapped tannase production economics across microbial strain selection, substrate conversion yields, and downstream purification intensity, with segmentation dimensions spanning product type, application purity threshold, form stability requirements, and end-user specification authority. CAGRs were derived from curve-fitting observed shipment volumes against projected capacity expansion schedules. Industry-specific forecast inputs included gallic acid harvest cycle patterns and EU Green Deal bio-based substitution mandates.
Substrate price volatility, regulatory registration timeline extensions, and fermentation specialist labor scarcity are the dominant revision risks to modeled outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Lipase Enzymes Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
Styrene Monooxygenase Market