
 Unnatural Amino Acids Market | 2026-2036
Unnatural Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Unnatural Amino Acids Market Outlook
The EU Green Deal's chemical sustainability targets is realigning procurement criteria across European pharmaceutical supply chains. Evonik Industries AG leverages its integrated amino acid platform to sustain cost advantages in D-amino acid production. Thermo Fisher Scientific anchors its position through captive distribution to contract research organizations worldwide. Merck KGaA differentiates via pharmaceutical-grade certification depth that exceeds baseline regulatory thresholds.
Unnatural amino acids are synthetic or non-proteogenic amino acid analogs engineered with altered side chains, stereochemistry, or backbone modifications, typically produced through solid-phase peptide synthesis or microbial fermentation with auxotrophic strains. Their primary purpose is to expand the structural and functional repertoire of peptides and proteins for therapeutic, diagnostic, and materials science applications. Non-canonical amino acids occupy the highest-margin tier as they command premium pricing for site-specific protein conjugation in antibody-drug conjugate pipelines. Pharmaceutical-grade material dominates volume consumption, though research-grade SKUs retain faster growth velocity among academic CRISPR engineering programs. Customized amino acids concentrate margin pools where batch sizes fall below one kilogram and synthesis complexity justifies project-based contracting.
FDA peptide quality guidelines, EMA's MDR substance documentation requirements, and China's NMPA pharmacopoeia amendments for synthetic peptides collectively elevate purity and traceability standards for market access. These frameworks force suppliers to maintain dual-certified manufacturing lines or forfeit participation in regulated therapeutic segments. Stakeholders must monitor how biosimilar peptide pipelines absorb pharmaceutical-grade capacity and whether research-grade demand from gene-editing tool developers creates supply tension for specialized precursors.
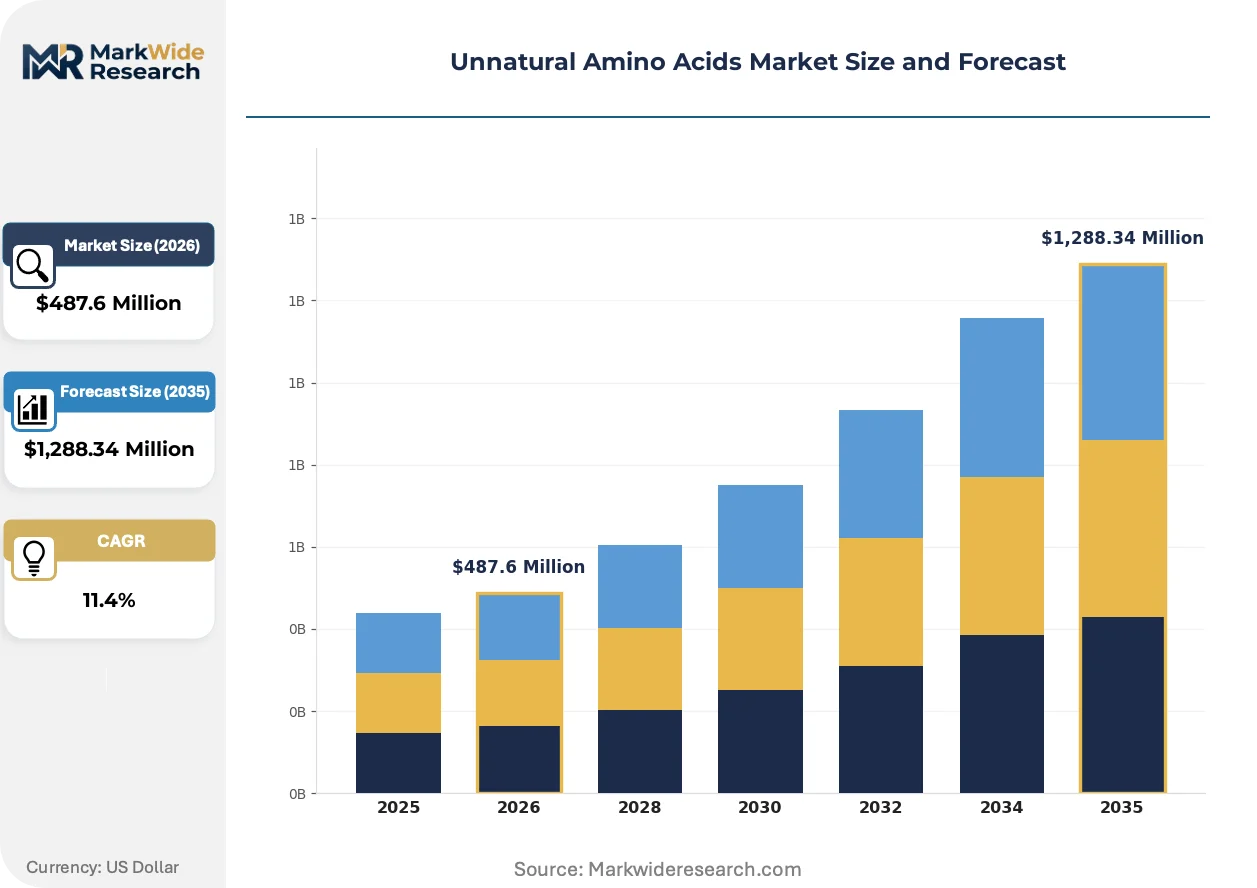
Market Dynamics
Peptide therapeutics developers are absorbing pharmaceutical-grade unnatural amino acid capacity faster than fermentation and synthetic chemistry suppliers can certify new manufacturing lines, creating allocation tension at the high-purity tier.
Growth Catalysts
- FDA peptide quality guidelines:Tightening purity benchmarks for complex generic peptides force developers toward certified suppliers, consolidating procurement toward dual-certified manufacturing lines.
- Antibody-drug conjugate pipelines:Site-specific protein conjugation requirements pull non-canonical amino acid demand upward as biotech clusters in Boston and San Diego scale biologic production.
- CRISPR engineering programs:Academic gene-editing tool developers accelerate research-grade consumption for auxotrophic strain engineering and expanded genetic code applications.
Market Restraints
- Petrochemical feedstock volatility:Aromatic side-chain precursors and protected amino acid building blocks expose synthesis costs to benzene and acrylonitrile price swings.
- Pharmaceutical-grade certification backlog:EMA MDR substance documentation requirements and FDA validation timelines stretch 18-24 months, gating supplier market entry.
- Recombinant expression alternatives:Cell-free protein synthesis and engineered yeast platforms threaten demand for certain synthetic amino acid intermediates in research applications.
Strategic Opportunities
- India's PLI scheme for active pharmaceutical ingredients:Government production-linked incentives attract fermentation-based amino acid manufacturing to offset import dependence.
- EU Green Deal chemical sustainability targets:Procurement criteria realignment favors suppliers with bio-based synthesis routes and solvent recovery systems in European pharmaceutical supply chains.
- Microfluidic peptide synthesis convergence:Continuous-flow chemistry integration with solid-phase methods enables on-demand production of sub-kilogram customized batches for precision medicine.
Industry Challenges
- Dual-use export control navigation:Controlled precursor classifications for certain D-amino acids and fluorinated analogs complicate cross-border shipments to contract research organizations.
- PhD-level chemist scarcity:Specialized expertise in stereoselective synthesis and chiral resolution remains concentrated among aging practitioner networks in Basel and New Jersey.
- Legacy quality management system upgrades:Small-batch custom houses face ERP and electronic batch record investments to meet FDA data integrity expectations for therapeutic-grade supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unnatural Amino Acids Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Canonical Amino Acids, Synthetic Amino Acids, Customized Amino Acids, D-Amino Acids Application: Biotechnology, Pharmaceutical Development, Nutritional Supplements, Research End User: Academic Institutions, Pharmaceutical Companies, Contract Research Organizations, Biotechnology Firms Grade: Research Grade, Pharmaceutical Grade, Industrial Grade, Food Grade |
| Companies Covered | GenScript Biotech Corporation, Evonik Industries AG, Thermo Fisher Scientific, AnaSpec Inc., Creative Peptides, Merck KGaA, Bachem Holding AG, Kyowa Hakko Bio Co., Ltd., Ajinomoto Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unnatural Amino Acids Market Strategic Shifts
Automation and sustainability mandates are compressing batch timelines while fragmenting the supplier base between high-volume fermentation platforms and agile synthetic chemistry houses.
Cell-free protein synthesis systems are modularizing access to non-canonical amino acid incorporation, enabling therapeutic developers to bypass auxotrophic strain engineering for rapid proof-of-concept studies. Contract research organizations in Cambridge and South San Francisco adopt these platforms to compress antibody-drug conjugate candidate timelines from months to weeks. The technology is modularizing project-based contracting structures, allowing buyers to disaggregate fermentation capacity from early-stage discovery.
EMA's MDR substance documentation requirements now mandate batch-level traceability for synthetic peptide starting materials, forcing suppliers to deploy serialization and electronic batch records. European pharmaceutical manufacturers audit upstream amino acid vendors against these standards, rejecting single-certified facilities. Custom synthesis houses in Switzerland and Germany respond by segregating pharmaceutical-grade lines from research-grade operations, doubling facility overhead but securing therapeutic pipeline access.
Consolidated procurement desks at large biopharma developers now mandate pharmaceutical-grade certification even for early-phase programs, compressing research-grade demand toward academic and gene-editing tool developers. Distributor relationships with Thermo Fisher and Merck KGaA displace direct supplier engagement for standardized SKUs. This preference shift concentrates margin pools at customized amino acid specialists serving sub-kilogram antibody-drug conjugate projects in Boston and San Diego.
Unnatural Amino Acids Market Segmentation
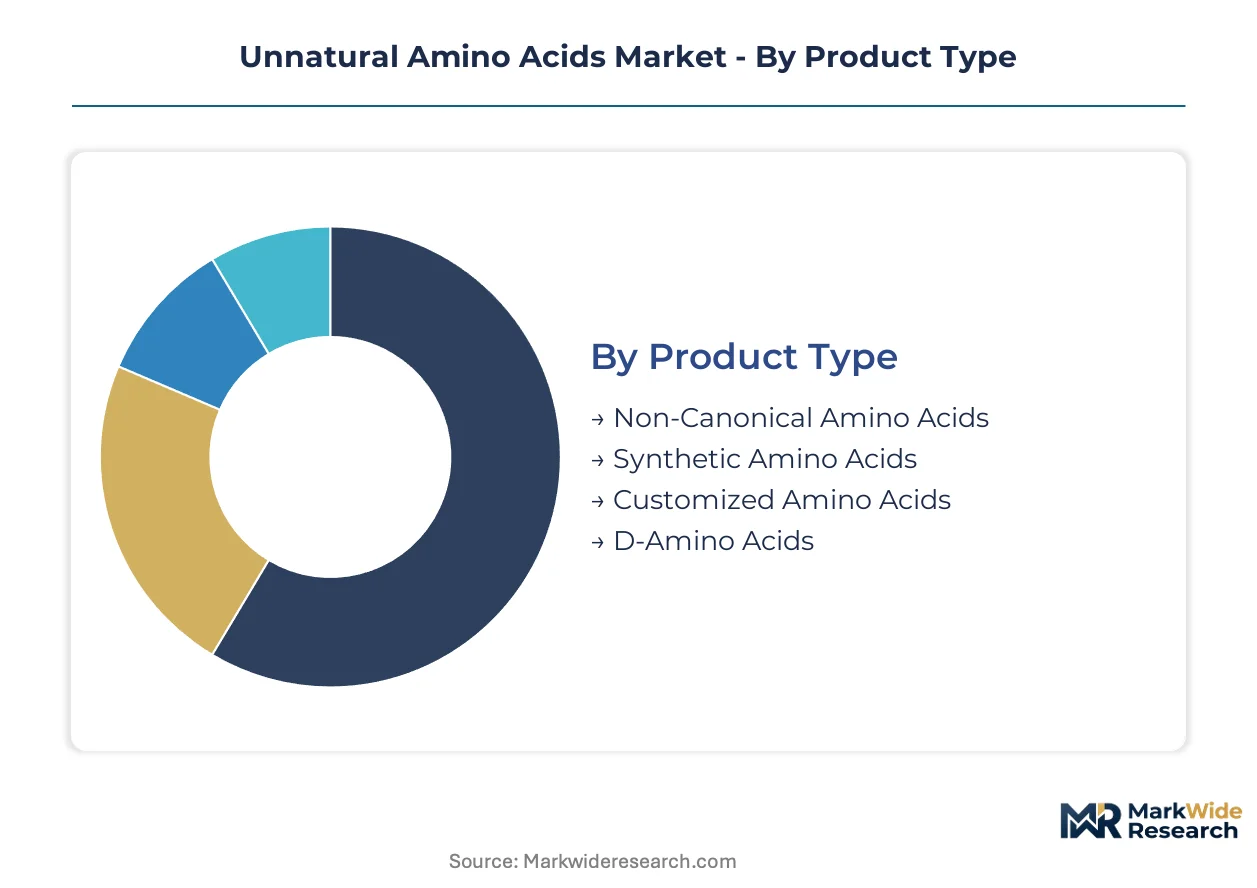
Unnatural amino acids fragment across four intersecting dimensions that determine pricing power, certification burden, and customer loyalty. Product chemistry dictates synthesis complexity while application context sets purity thresholds and regulatory exposure.
Product Type:
Buyers in this category separate by conjugation precision requirements and stereochemistry control needs rather than volume scale alone.
- Non-Canonical Amino Acids:Engineered residues with side chains absent from the universal genetic code enable site-specific protein modification for antibody-drug conjugate payloads. Demand concentrates in Boston and San Diego biotech clusters where developers engineer expanded genetic code systems for therapeutic proteins.
- Synthetic Amino Acids:Chemically constructed analogs produced through solid-phase or solution-phase methods offer batch-to-batch consistency critical for GMP peptide manufacturing. Pharmaceutical developers in New Jersey and Basel favor these for commercial peptide API production where fermentation variability risks regulatory rejection.
- Customized Amino Acids:Project-specific molecules synthesized to client-defined specifications occupy the highest-margin tier where sub-kilogram batches justify premium pricing. Contract research organizations commission these for exploratory antibody-drug conjugate programs requiring unique linker chemistries.
- D-Amino Acids:Mirror-image stereoisomers resist proteolytic degradation, extending peptide half-life in vivo. Protease-resistant therapeutic developers source these for oral peptide formulations targeting metabolic and gastrointestinal indications.
Non-canonical amino acids lead volumes today; customized variants are gaining share fastest.
Application:
End-use context determines whether buyers accept research-grade material or demand pharmaceutical-grade certification with full batch documentation.
- Biotechnology:Enzyme engineering and industrial biocatalysis applications consume stable-isotope-labeled and unnatural residues for metabolic flux analysis and directed evolution campaigns. Synthetic biology startups in South San Francisco drive consumption of auxotrophic strain-compatible analogs.
- Pharmaceutical Development:Peptide therapeutic and antibody-drug conjugate pipelines absorb the highest-purity tier, with FDA peptide quality guidelines forcing developers toward dual-certified suppliers. GLP toxicology studies require GMP-grade material even at preclinical stages, compressing research-grade participation.
- Nutritional Supplements:Modified amino acids for sports nutrition and clinical nutrition support muscle protein synthesis modulation and metabolic disorder management. This segment tolerates food-grade certification, opening procurement to broader supplier bases.
- Research:Academic laboratories and gene-editing tool developers accelerate consumption of research-grade material for CRISPR engineering and expanded genetic code proof-of-concept studies. CRISPR programs at MIT and Stanford represent the fastest-expanding demand pool in this tier.
Pharmaceutical development commands the largest revenue pool; research applications are climbing the fastest.
End User:
Procurement sophistication varies dramatically, with consolidated biopharma desks imposing pharmaceutical-grade standards even on early-phase programs.
- Academic Institutions:University laboratories and federally funded research centers purchase research-grade material through distributor relationships with Thermo Fisher Scientific and Merck KGaA. Grant-funded CRISPR engineering programs at UC Berkeley and Harvard Medical School drive specialized precursor demand.
- Pharmaceutical Companies:Large-cap developers maintain captive procurement desks mandating pharmaceutical-grade certification across all program phases, displacing direct supplier engagement for standardized SKUs. Consolidated buyers in Basel and New Jersey negotiate multi-year supply agreements with fermentation specialists.
- Contract Research Organizations:CDMOs and discovery service providers bridge research-grade and pharmaceutical-grade procurement, with Cambridge and South San Francisco operators adopting cell-free protein synthesis platforms to compress antibody-drug conjugate candidate timelines.
- Biotechnology Firms:Venture-backed peptide therapeutics developers represent the fastest-expanding buyer segment, absorbing pharmaceutical-grade capacity faster than suppliers can certify new manufacturing lines. Boston and San Diego clusters disproportionately consume non-canonical amino acids for next-generation biologics.
Pharmaceutical companies dominate procurement volumes today; biotechnology firms are expanding most quickly.
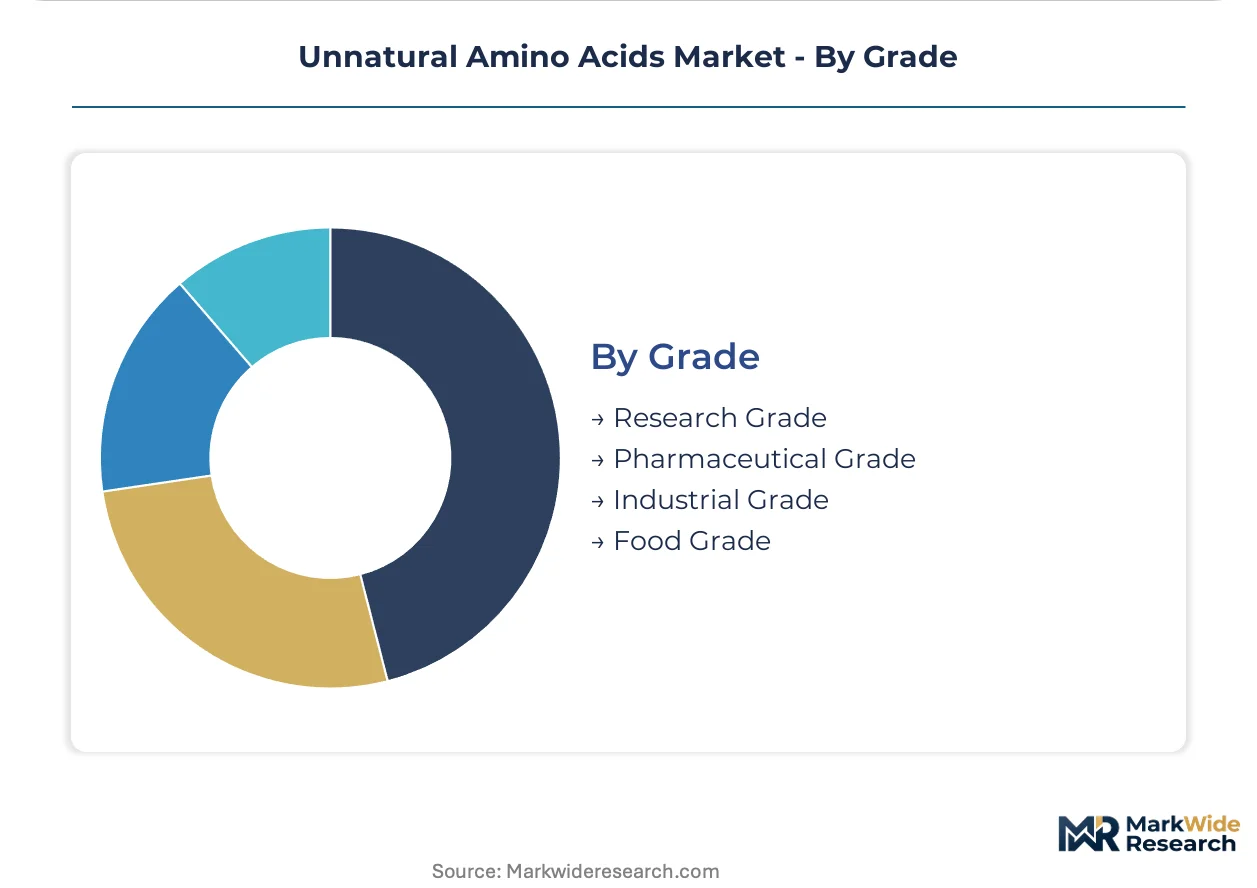
Grade:
Certification depth directly determines addressable market scope, with regulatory frameworks forcing facility segregation or dual-certified manufacturing lines.
- Research Grade:Purity levels sufficient for exploratory biology and tool development, typically 95-98% with basic characterization documentation. Academic CRISPR programs and early discovery campaigns tolerate this tier, though distributor relationships increasingly displace direct supplier engagement.
- Pharmaceutical Grade:GMP-compliant material with full batch records, stability data, and regulatory starting material qualification packages required for IND-enabling and commercial peptide API manufacturing. EMA MDR substance documentation requirements and FDA validation timelines stretch supplier certification to 18-24 months, gating market entry.
- Industrial Grade:Bulk material for biocatalysis and enzyme engineering applications where purity thresholds fall below pharmaceutical requirements. This tier faces displacement pressure from recombinant expression alternatives and cell-free protein synthesis systems.
- Food Grade:Nutritional supplement applications requiring FSSAI, FDA food facility registration, or equivalent national food safety certifications rather than pharmaceutical agency oversight. India's PLI scheme for active pharmaceutical ingredients attracts fermentation-based manufacturing to serve this tier.
Pharmaceutical grade leads revenue concentration today; research grade retains the steepest expansion trajectory among gene-editing tool developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide chemistry originated in European pharmaceutical laboratories during the mid-twentieth century before migrating to US biotechnology clusters and Asian fermentation centers. Today's supply geography reflects this diffusion, with manufacturing capability distributed across three continents and demand concentrating in established therapeutic development hubs.
United States
FDA peptide quality guidelines tighten purity benchmarks for complex generic peptides, forcing developers toward dual-certified suppliers. Boston and San Diego biotech clusters absorb disproportionate volumes of pharmaceutical-grade non-canonical amino acids for antibody-drug conjugate pipelines. Consolidated procurement desks at large-cap developers now mandate GMP certification even for early-phase programs.
Germany
EMA MDR substance documentation requirements mandate batch-level traceability for synthetic peptide starting materials, gating market access for uncertified suppliers. Evonik Industries AG leverages its integrated amino acid platform to sustain cost advantages in D-amino acid production. Custom synthesis houses in Switzerland and Germany segregate pharmaceutical-grade lines from research-grade operations to secure therapeutic pipeline access.
China
NMPA pharmacopoeia amendments for synthetic peptides elevate purity and traceability standards for domestic and imported material. Government dual carbon goals pressure fermentation facilities to adopt bio-based synthesis routes and solvent recovery systems. Contract manufacturers in the Yangtze River Delta expand capacity to serve both domestic biotech firms and Western pharmaceutical developers seeking cost-competitive GMP material.
India
CDSCO aligns with international pharmacopoeia standards while the PLI scheme for active pharmaceutical ingredients attracts fermentation-based amino acid manufacturing. Government production-linked incentives aim to offset import dependence for peptide therapeutic precursors. Maharashtra and Gujarat host emerging custom synthesis operations targeting research-grade demand from academic CRISPR engineering programs.
Switzerland
Swissmedic maintains pharmaceutical-grade certification depth that exceeds baseline regulatory thresholds across European markets. Basel's aging practitioner networks retain concentrated expertise in stereoselective synthesis and chiral resolution. Bachem Holding AG anchors the region's position in GMP peptide API manufacturing, with facility investments addressing the 18-24 month certification backlog facing new market entrants.
Unnatural Amino Acids Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and synthesis complexity tiers. The supplier base fragments between high-volume fermentation platforms serving standardized SKUs and agile synthetic chemistry houses capturing customized sub-kilogram projects. Three archetypes dominate: integrated chemical conglomerates with captive amino acid platforms, specialized peptide houses with GMP certification depth, and distributor-anchored catalog suppliers with global logistics networks. Competitive moves concentrate on dual-certified manufacturing line expansion and strategic partnerships with CRISPR tool developers.
Within the integrated chemical conglomerate tier, Evonik Industries AG and Merck KGaA exemplify players leveraging diversified material science portfolios to sustain amino acid cost positions. Among specialized peptide houses, Bachem Holding AG and GenScript Biotech Corporation occupy positions defined by GMP certification breadth and custom synthesis capability respectively. Thermo Fisher Scientific anchors the distributor-anchored catalog tier, with captive distribution networks displacing direct supplier engagement for standardized research-grade SKUs.
| Leading Market Players |
|---|
| GenScript Biotech Corporation |
| Evonik Industries AG |
| Thermo Fisher Scientific |
| AnaSpec Inc. |
| Creative Peptides |
| Merck KGaA |
| Bachem Holding AG |
| Kyowa Hakko Bio Co., Ltd. |
| Ajinomoto Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Biotechnology firms in Boston and San Diego clusters anchor pricing power for pharmaceutical-grade non-canonical amino acids, compressing procurement toward project-based contracting for sub-kilogram customized batches while standardized SKUs face distributor-anchored catalog pressure.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, research-grade, and industrial-grade certification levels stratifies margin pools by purity threshold and documentation depth. Price differentiation hinges on GMP compliance burden and batch traceability requirements, with EMA MDR substance documentation mandates stretching supplier certification timelines. Cost compression in research-grade tiers is intensifying as cell-free protein synthesis platforms displace synthetic precursor demand. Academic CRISPR programs exhibit highest price sensitivity, while antibody-drug conjugate developers tolerate premium positioning for site-specific conjugation precision.
Supply Chain Analysis
Cross-border freight complexity for controlled D-amino acid and fluorinated analog precursors elevates landed costs for contract research organizations in Cambridge and South San Francisco. Manufacturing concentrates in Germany, Switzerland, and China, with fermentation-based capacity expanding in India's Maharashtra and Gujarat under PLI scheme incentives. Raw material dependencies draw from aromatic petrochemical feedstocks, protected amino acid building blocks, and chiral resolution reagents. Single-source vulnerability concentrates in Basel's aging practitioner networks for stereoselective synthesis expertise. Distribution runs through Thermo Fisher Scientific and Merck KGaA captive networks for standardized SKUs, while direct supplier engagement persists for customized sub-kilogram batches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The unnatural amino acids market compounds steadily as peptide therapeutic pipelines absorb pharmaceutical-grade capacity faster than certification timelines permit, creating durable margin protection for dual-certified suppliers.
For Market Incumbents: Lock in therapeutic pipeline access by segregating pharmaceutical-grade manufacturing lines from research-grade operations to satisfy EMA MDR batch-level traceability mandates. Expand dual-certified capacity in Switzerland and Germany to capture antibody-drug conjugate demand from Boston and San Diego biotech clusters before fermentation alternatives mature. For New Entrants and Emerging Players: Cell-free protein synthesis platform providers represent the most penetrable entry vector, enabling rapid proof-of-concept services that bypass auxotrophic strain engineering bottlenecks. Target academic CRISPR engineering programs at MIT and Stanford with research-grade catalog offerings, then migrate toward pharmaceutical-grade certification as programs advance to IND-enabling stages. For Investors and Strategic Acquirers: Specialized peptide houses with GMP certification depth are the most active acquirer targets in this space, as integrated chemical conglomerates seek custom synthesis capability to complement fermentation platforms. Watch biosimilar peptide pipeline announcements as inflection indicators for pharmaceutical-grade capacity absorption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certified Manufacturing Line Expansion | EMA MDR and FDA peptide quality guidelines force facility segregation to secure therapeutic pipeline access. |
| Cell-Free Protein Synthesis Platform Integration | Cambridge and South San Francisco CROs compress antibody-drug conjugate candidate timelines from months to weeks. |
| Backward Integration into Aromatic Feedstocks | Evonik Industries AG sustains D-amino acid cost advantages through captive petrochemical precursor supply. |
| Strategic Partnership with CRISPR Tool Developers | MIT and Stanford gene-editing programs accelerate research-grade consumption for expanded genetic code applications. |
| Long-Term Supply Agreement with Biotech Clusters | Boston and San Diego developers absorb pharmaceutical-grade capacity faster than suppliers can certify new lines. |
Study Parameters
Multiple input streams — primary interviews with peptide therapeutics developers, regulatory affairs leads at dual-certified suppliers, and academic CRISPR engineering program directors, alongside secondary validation against FDA peptide quality guideline filings, EMA MDR substance documentation requirements, and NMPA pharmacopoeia amendments — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Historical volume trajectories were cross-referenced against panel input from fermentation specialists and synthetic chemistry houses to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product chemistry class, application context, end-user procurement sophistication, and grade certification tier. CAGRs were derived from supply-demand balance analysis incorporating biosimilar peptide pipeline absorption rates and cell-free protein synthesis platform displacement curves.
The model holds under stable regulatory certification timelines; deviation in EMA MDR documentation requirement stringency or FDA peptide quality guideline enforcement would shift capacity allocation between pharmaceutical-grade and research-grade tiers. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Americas Enzymes Market
Industrial Biotechnology
White Biotechnology Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Global Specialty Enzymes Market