
 Beta-Glucanase Market | 2026-2036
Beta-Glucanase Market Size, Share, and Industry Trends Forecast 2026-2036
Beta-Glucanase Market Outlook
Animal feed formulations is broadening as livestock producers seek alternatives to antibiotic growth promoters. Cargill Inc leverages its integrated grain-handling network to distribute beta-glucanase directly into regional feed mill operations. DSM Firmenich anchors its position through deep R&D investment in enzyme stability under varying pH conditions. Lesaffre Group competes by specializing in yeast-derived enzyme systems for brewing applications.
Beta-glucanase comprises a class of glycoside hydrolase enzymes that cleave beta-1,3 and beta-1,4 glycosidic bonds in polysaccharide substrates, typically operating optimally between pH 4.5 and 6.5 with temperature stability up to 60°C in commercial preparations. Manufacturers produce these enzymes through submerged fermentation of Aspergillus niger or Trichoderma reesei strains for industrial-scale deployment in viscosity reduction and cell wall degradation. Food Grade beta-glucanase dominates value capture due to stringent purity requirements in baking and brewing, while Feed Grade volumes are expanding fastest as livestock operations standardize enzyme supplementation in monogastric diets. Bacterial Source enzymes lead in thermal tolerance for industrial processes, though Fungal Source variants retain cost advantages in food applications.
EPA industrial effluent guidelines and FDA food additive regulations in the United States shape enzyme manufacturing standards and labeling requirements for commercial beta-glucanase products. REACH registration obligations in Europe constrain import pathways for non-compliant fermentation-derived inputs. Stakeholders must monitor evolving enzyme classification under EPA and FDA frameworks while evaluating captive fermentation investments against third-party sourcing economics.
Market Dynamics
Enzyme stabilization technology is compressing formulation costs while EU F-Gas Regulation compliance is forcing fermentation facility upgrades across European production bases. These dual pressures are restructuring competitive positioning between thermal-tolerant bacterial strains and cost-optimized fungal fermentation systems.
Growth Catalysts
- Feed enzyme mandates:Livestock producers in China are standardizing beta-glucanase supplementation in monogastric diets to replace antibiotic growth promoters, tightening substrate specificity requirements for barley and oat-based rations.
- REACH registration pathways:ECHA obligations for fermentation-derived enzymes are consolidating compliant supplier networks, advantaging producers with captive strain libraries and documented toxicology dossiers.
- Brewing viscosity reduction:Craft and industrial brewers are deploying fungal-source beta-glucanase to accelerate lautering throughput and improve wort filtration efficiency in high-beta-glucan malt varieties.
Market Restraints
- Input cost volatility:Corn steep liquor and soybean meal prices for submerged fermentation media fluctuate with agricultural commodity cycles, compressing margin stability for bulk enzyme manufacturers.
- Supply concentration risk:Strain IP and master cell bank custody concentrates among three legacy fungal genetics repositories in Denmark, the Netherlands, and Japan, creating bottleneck vulnerability.
- Substitution threat:Xylanase and cellulase cocktails from Trichoderma reesei are displacing standalone beta-glucanase in certain feed applications where broader fiber degradation is acceptable.
Strategic Opportunities
- Indian feed sector penetration:FSSAI enzyme approval frameworks are formalizing, opening pathway for imported beta-glucanase in poultry and aquaculture expansion zones around Hyderabad and Chennai.
- Precision fermentation convergence:Synthetic biology platforms combining CRISPR strain engineering with continuous bioprocessing are enabling novel thermostable variants with expanded pH operating windows.
- Direct-to-mill distribution:Bypassing traditional distributor networks, enzyme producers are establishing technical service partnerships with regional feed compounders in Shandong and Henan provinces.
Industry Challenges
- Fermentation scale-up expertise:Qualified bioprocess engineers capable of optimizing oxygen transfer and shear stress management in 100,000+ liter tanks remain scarce across Midwest US and Central European hiring markets.
- Dual-use certification timelines:Food-grade and feed-grade enzyme registrations require parallel toxicology studies under FDA and EPA frameworks, extending commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beta-Glucanase Market |
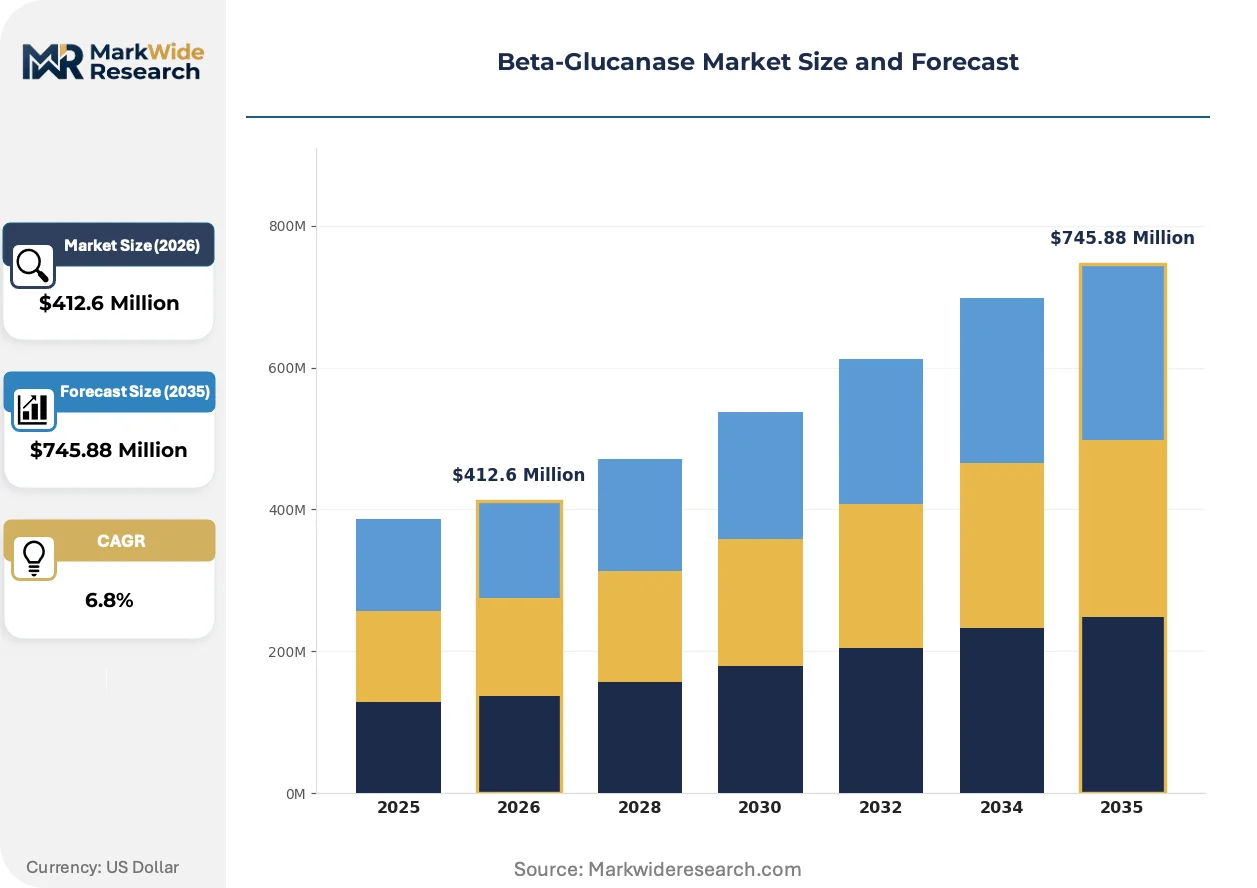
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Feed Grade, Pharmaceutical Grade, Industrial Grade Application: Baking, Animal Feed, Brewing, Pharmaceuticals Source: Bacterial, Fungal, Yeast, Plant End User: Bakers, Farmers, Food Manufacturers, Pharmaceutical Companies |
| Companies Covered | Cargill Inc, Kemin Industries, Tate & Lyle PLC, Merck KGaA, Lesaffre Group, Kerry Group PLC, Angel Yeast Co. Ltd, Biorigin, DSM Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beta-Glucanase Market Strategic Shifts
Continuous processing architectures and AI-guided strain optimization are compressing development timelines while reshaping how enzyme producers defend technical differentiation. These shifts are redrawing capability requirements across fermentation science and downstream formulation.
Immobilized enzyme systems using cross-linked aggregate technology are absorbing market share in brewing applications where reusability across multiple batch cycles justifies higher upfront biocatalyst costs. Regional breweries in Bavaria and Bohemia are piloting these systems to reduce enzyme dosing frequency. The technology is absorbing volume from traditional liquid enzyme additions by demonstrating comparable attenuation performance with 40% lower per-hectoliter enzyme expenditure.
EU F-Gas Regulation phase-down schedules are forcing refrigeration-dependent fermentation facilities to retrofit cooling infrastructure or relocate production to climates with ambient temperature advantages. Industrial enzyme manufacturers with legacy plants in Northern Europe face capital allocation decisions between chiller upgrades and greenfield investment in Iberian or Anatolian zones. Food-grade beta-glucanase production with stringent temperature control requirements is most exposed to these compliance-driven relocation pressures.
Buyer consolidation among integrated protein companies is compressing supplier negotiation cycles and demanding bundled enzyme-service contracts with guaranteed performance metrics. Large feed mill operators in Iowa and São Paulo states are unbundling technical support from commodity enzyme supply, selecting partners based on in vivo digestibility trial data rather than standard activity units. This behavior is most visible in North American swine operations where margin pressure has intensified procurement sophistication.
Beta-Glucanase Market Segmentation
Enzyme grade specifications and source organism selection determine capital deployment patterns across fermentation infrastructure. Manufacturers align product portfolios with end-use purity requirements and thermal stability demands.
Product Type:
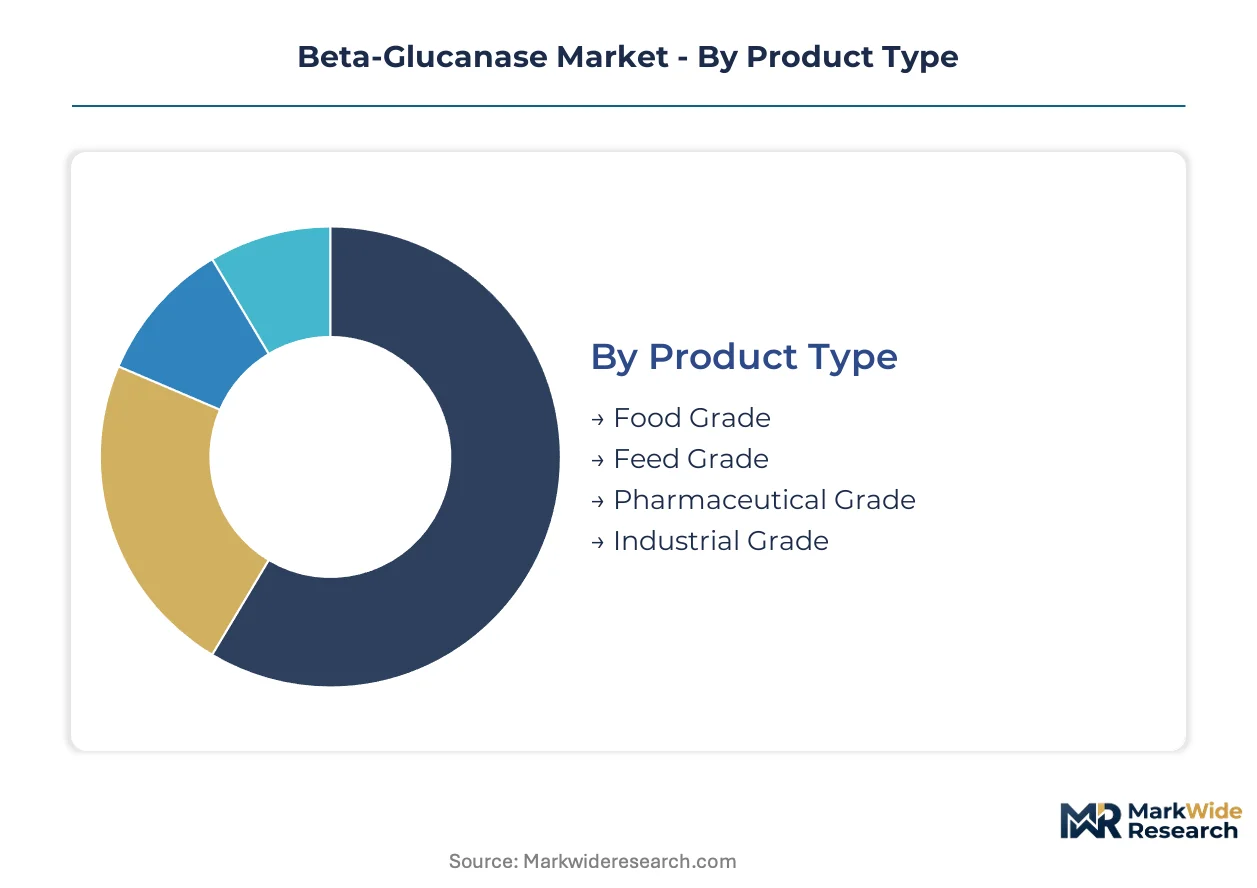
Food Grade beta-glucanase demands the heaviest upfront investment due to FDA and EFSA compliance requirements for fermentation media traceability and downstream purification systems.
- Food Grade:Stringent purity thresholds require multi-stage chromatography and viral clearance validation. Demand concentrates in Bavarian and Bohemian brewing clusters where lautering efficiency drives specification premiums. REACH registration dossiers for food-contact enzymes extend commercialization timelines.
- Feed Grade:Lower purity tolerances permit streamlined downstream processing. Shandong and Henan feed compounders are standardizing supplementation in monogastric diets as antibiotic growth promoter alternatives tighten substrate specificity requirements for barley-based rations.
- Pharmaceutical Grade:cGMP compliance and injectable-grade endotoxin limits impose specialized cleanroom fermentation and extensive documentation burdens.
- Industrial Grade:Bulk viscosity reduction applications in textile and paper processing tolerate higher impurity loads, enabling cost-optimized production economics.
Food Grade absorbs the bulk of installed capacity; Feed Grade is expanding most quickly.
Application:
Volume concentration follows end-use processing scale, with brewing and feed milling commanding the largest single-site enzyme consumption.
- Baking:Dough conditioning applications require fungal-source enzymes with specific activity against water-soluble beta-glucans in rye and oat flours. North American artisanal bakeries are adopting micro-encapsulated formulations for extended shelf stability.
- Animal Feed:Monogastric digestibility improvement drives the steepest volume expansion. Iowa and São Paulo swine operations are unbundling technical support from commodity supply, selecting partners based on in vivo trial data rather than standard activity units.
- Brewing:High-beta-glucan malt varieties in craft and industrial settings deploy fungal-source enzymes to accelerate lautering throughput. Immobilized enzyme systems using cross-linked aggregate technology are absorbing share in Bavaria through reusability across multiple batch cycles.
- Pharmaceuticals:Beta-glucanase serves as a processing aid in cell wall disruption for beta-glucan extraction, with CDSCO and FDA oversight shaping validation requirements.
Animal Feed claims the steepest expansion trajectory; Brewing maintains the highest value per kilogram realization.
Source:
Thermal tolerance requirements and pH operating windows dictate strain selection and corresponding fermentation infrastructure design.
- Bacterial:Thermostable variants from Bacillus subtilis dominate industrial processes requiring sustained activity above 70°C. Capital intensity concentrates in cooling infrastructure for high-density fermentation.
- Fungal:Aspergillus niger and Trichoderma reesei strains retain cost advantages in food applications with moderate temperature requirements. EU F-Gas Regulation compliance is forcing refrigeration-dependent facilities to retrofit or relocate.
- Yeast:Saccharomyces-derived systems compete in brewing applications where strain familiarity simplifies regulatory navigation. Lesaffre Group specializes in this source for European malt processing.
- Plant:Emerging extraction from germinating barley and oat tissues serves niche organic certification markets with limited commercial scale.
Fungal Source maintains dominant installed base; Bacterial Source is gaining share fastest in thermally demanding industrial segments.
End User:
Procurement sophistication varies sharply across buyer categories, with integrated protein companies compressing supplier negotiation cycles.
- Bakers:Small-batch artisanal operations prioritize enzyme stability under variable hydration conditions. Distribution runs through regional ingredient distributors with technical service attachments.
- Farmers:Direct supplementation remains limited; most enzyme exposure occurs through pre-mixed feed from compounders. Hyderabad and Chennai poultry zones are formalizing FSSAI enzyme approval pathways.
- Food Manufacturers:Cargill Inc leverages integrated grain-handling networks to distribute beta-glucanase directly into regional feed mill operations, bypassing traditional distributor layers.
- Pharmaceutical Companies:Dual-use certification timelines for food-grade and feed-grade registrations require parallel toxicology studies, extending commercialization cycles.
Food Manufacturers absorb the bulk of volume throughput; Farmers represent the fastest-climbing adoption curve as pre-mixed enzyme feed standardizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's feed-industry special economic zones concentrate domestic enzyme manufacturing capacity, drawing foreign direct investment into fermentation infrastructure. Henan province's compounder clusters anchor distribution networks for monogastric feed supplementation.
China
Livestock producers in Shandong and Henan provinces standardize beta-glucanase supplementation as antibiotic growth promoter alternatives tighten. SAMR's enzyme approval frameworks formalize import substitution pathways for domestic yeast-derived systems. Qingdao and Zhengzhou fermentation parks scale submerged production capacity to serve regional brewing and feed milling demand.
United States
Iowa and São Paulo swine operations unbundle technical support from commodity enzyme supply, selecting partners based on in vivo digestibility trial data. EPA industrial effluent guidelines and FDA food additive regulations shape manufacturing standards and labeling requirements for commercial products. Midwest feed mill operators demand bundled enzyme-service contracts with guaranteed performance metrics.
Germany
Bavarian and Bohemian brewing clusters deploy fungal-source beta-glucanase to accelerate lautering throughput in high-beta-glucan malt varieties. EU F-Gas Regulation phase-down schedules force refrigeration-dependent fermentation facilities to retrofit cooling infrastructure or relocate production. Munich-area technical service partnerships bypass traditional distributor networks for regional compounders.
India
FSSAI enzyme approval frameworks are formalizing, opening pathways for imported beta-glucanase in poultry and aquaculture expansion zones around Hyderabad and Chennai. CDSCO oversight shapes validation requirements for pharmaceutical-grade applications. Telangana and Tamil Nadu feed sectors represent the fastest-climbing adoption curve as pre-mixed enzyme feed standardizes.
Netherlands
REACH registration obligations for fermentation-derived enzymes consolidate compliant supplier networks, advantaging producers with captive strain libraries and documented toxicology dossiers. Eindhoven-region bioprocess engineering expertise supports scale-up optimization for 100,000+ liter tanks. Dutch legacy fungal genetics repositories concentrate strain IP and master cell bank custody.
Beta-Glucanase Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated grain-handlers controlling feed-grade distribution and yeast-derived specialists anchoring brewing applications. The vendor base concentrates among fermentation-science conglomerates with captive strain libraries and regional compounders with technical service attachments. Three archetypes dominate: integrated agribusinesses with direct-to-mill networks, R&D-intensive enzyme houses with pH-stability platforms, and yeast-specialist fermentation houses. Competitive moves center on backward integration into strain engineering and geographic relocation to evade EU F-Gas Regulation compliance costs.
Within the integrated agribusiness tier, Cargill Inc leverages its grain-handling network to distribute directly into regional feed mill operations. DSM Firmenich anchors the R&D-intensive enzyme house position through investment in stability under varying pH conditions. Lesaffre Group occupies the yeast-specialist niche, competing through fermentation systems derived from familiar Saccharomyces platforms for malt processing applications.
| Leading Market Players |
|---|
| Cargill Inc |
| Kemin Industries |
| Tate & Lyle PLC |
| Merck KGaA |
| Lesaffre Group |
| Kerry Group PLC |
| Angel Yeast Co. Ltd |
| Biorigin |
| DSM Firmenich |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation phase-down schedules are compressing qualified supply pools while erecting cost barriers that gate premium-tier pricing access for compliant fermentation capacity. Buyers now face bifurcated sourcing economics where refrigeration-dependent facilities command scarcity premiums against relocated or retrofitted competitors.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Iowa and São Paulo feed mills demand guaranteed enzyme availability during seasonal ration formulation peaks. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and technical service bundling, with Food Grade enzymes capturing the widest spreads. Cost compression in Feed Grade tiers is intensifying because Shandong compounders are unbundling performance guarantees from base enzyme supply. Small-batch artisanal bakers show least price sensitivity due to formulation flexibility requirements, while bulk commodity feed operations drive hardest volume negotiations.
Supply Chain Analysis
Domestic-content mandates under China's SAMR enzyme approval frameworks are reshaping sourcing patterns for multinational suppliers seeking market access. Production gravity centers on Denmark, the Netherlands, and Japan for master cell bank custody, with China and India scaling submerged fermentation capacity for regional feed and brewing demand. Strain IP concentration in legacy fungal genetics repositories creates single-source vulnerability for thermostable variants. Corn steep liquor and soybean meal feedstock costs fluctuate with agricultural commodity cycles, compressing margin stability. Distribution runs through integrated grain-handlers like Cargill Inc bypassing traditional distributor layers for direct-to-mill technical service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation compliance costs are forcing sub-scale fermentation operators toward exit or acquisition, consolidating viable supply among capital-resilient incumbents with captive strain libraries and documented REACH dossiers.
For Market Incumbents: Deepen backward integration into CRISPR strain engineering platforms to defend against xylanase-cellulase cocktail substitution in feed applications. Acquire bioprocess engineering talent in Eindhoven-region or Midwest US hiring markets to resolve scale-up expertise scarcity. Lock long-term offtake agreements with Shandong and Henan compounders before new entrants establish technical service footholds.
For New Entrants and Emerging Players: Begin with precision fermentation convergence targeting thermostable bacterial variants for industrial viscosity reduction applications where incumbent R&D intensity lags. Target India's FSSAI-formalizing enzyme approval pathways in Hyderabad and Chennai poultry zones as the most penetrable geography. Lead with immobilized enzyme system pilots for Bavarian craft breweries seeking reusability economics.
For Investors and Strategic Acquirers: DSM Firmenich's pH-stability platform deepening is the leading indicator that R&D-intensive enzyme houses are pulling ahead of commodity competitors. Position for five-to-ten year consolidation plays favoring mid-cap specialists with SAMR-compliant China access and REACH-registered European dossiers. Watch for ECHA registration pathway bottlenecks as the signal for distressed acquisition opportunities among non-compliant fermentation operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Engineering | Captive CRISPR platforms reduce licensing costs for thermostable variant development. |
| Geographic Relocation to Anatolian Zones | Ambient temperature advantages lower EU F-Gas Regulation compliance capital burdens. |
| Immobilized Enzyme System Deployment | Cross-linked aggregate technology captures Bavarian brewing demand through reusability economics. |
| Direct-to-Mill Technical Partnerships | Bypassing distributor layers locks Iowa and São Paulo swine operations to performance-guaranteed supply. |
| REACH Registration Dossier Completion | ECHA-compliant toxicology documentation consolidates supplier networks advantaging incumbent positions. |
Study Parameters
Independent corroboration across fermentation plant managers, feed compounder procurement leads, brewing technical directors, and enzyme distribution channel partners underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings of listed enzyme houses, ECHA REACH registration databases, and SAMR enzyme approval disclosures. Bottom-up volume modeling from individual facility capacity announcements triangulates against top-down demand estimates from livestock census data and malt processing statistics.
Rate-of-change decomposition across the analysis window segments volume and value by enzyme grade tier, source organism, end-use application, and regional regulatory cluster. CAGRs derive from modeled adoption curves for antibiotic growth promoter replacement in monogastric diets and lautering efficiency improvements in high-beta-glucan malt processing. Strain thermal tolerance benchmarks and fermentation scale-up timelines inform supply-side capacity expansion assumptions.
Input cost volatility in agricultural commodity feedstocks, regulatory timeline slippage in dual-use certification pathways, and substitution acceleration by xylanase-cellulase cocktails are the dominant revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Glucoamylase Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market
Industrial Biotechnology
White Biotechnology Market