
 China Biofuels Market | 2026-2036
China Biofuels Market Size, Share, and Industry Trends Forecast 2026-2036
China Biofuels Market Outlook
Modular refinery retrofits is realigning buyer choice across China's biofuels procurement landscape. Sinopec leverages its existing petrochemical infrastructure to anchor ethanol distribution networks in coastal provinces. COFCO Bioenergy dominates corn-based ethanol production through captive access to agricultural feedstock streams. Zhuoyue New Energy specializes in waste-oil biodiesel systems that extend regional collection radius beyond conventional supply boundaries.
China biofuels encompass liquid and gaseous energy carriers derived from biomass conversion, with ethanol typically produced via yeast fermentation of starch crops at concentrations reaching 99.5% purity for fuel blending, and biodiesel manufactured through transesterification of waste oils to meet GB 25199 diesel fuel specifications. Ethanol retains the largest production base among product types, reflecting mature grain-processing infrastructure and established blending mandates. Biodiesel sourced from waste oils captures expanding margin pools as municipal grease collection networks formalize under environmental compliance protocols. Renewable diesel, though nascent, occupies strategic positioning for aviation end-use as hydrotreated vegetable oil pathways achieve certification alignment with international jet fuel standards.
China's National Development and Reform Commission shapes biofuel demand through mandatory ethanol blending quotas in designated provinces, while SAMR enforces GB standard compliance for fuel quality and labeling. The Ministry of Ecology and Environment (MEE) regulates biogas project emissions thresholds, directing investment toward closed-loop anaerobic digestion systems. Stakeholders must monitor how provincial implementation timelines for national blending mandates affect feedstock procurement strategies and regional capacity allocation decisions.
Market Dynamics
Aviation fuel blending mandates from China's national aviation regulator are restructuring procurement priorities, pulling capital toward hydrotreated vegetable oil pathways and compressing timelines for renewable diesel certification alignment with international jet fuel standards.
Growth Catalysts
- CAAC Blending Mandates:China's Civil Aviation Administration mandates are forcing refiners to secure certified sustainable aviation fuel supply chains, redirecting biogas upgrading investments toward aviation-grade output specifications.
- Shandong Waste-to-Energy Cluster:Municipal biogas projects in this province concentrate equipment procurement, creating localized demand surges for anaerobic digestion system vendors.
- Ethanol Distribution Infrastructure:Coastal province blending terminals leverage existing petrochemical pipeline networks, reducing last-mile logistics costs for fuel-grade ethanol delivery.
Market Restraints
- Feedstock Cost Volatility:Corn price fluctuations strain ethanol margin structures, particularly for producers without captive agricultural supply agreements.
- GB Standard Compliance Friction:SAMR enforcement of fuel quality and labeling standards creates certification bottlenecks, delaying product market entry for non-compliant blenders.
- Waste Oil Collection Network Gaps:Municipal grease formalization remains uneven across provinces, constraining biodiesel feedstock availability outside compliance-mandated urban centers.
Strategic Opportunities
- Aviation End-Use Expansion:Hydrotreated vegetable oil pathways achieving international jet fuel certification alignment open premium pricing tiers for renewable diesel producers.
- Closed-Loop Anaerobic Digestion:MEE emissions thresholds are directing investment toward integrated biogas systems that capture methane for grid injection or vehicle fuel.
- Coastal Province Blending Terminals:Underutilized petrochemical infrastructure in eastern provinces offers retrofit potential for ethanol distribution network expansion.
Industry Challenges
- Certification Timeline Compression:International aviation fuel standards require extensive testing protocols, stretching technical validation resources for renewable diesel developers.
- Feedstock Quality Standardization:Waste oil sourcing from informal collection networks introduces variability that complicates transesterification process control and GB 25199 compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Biofuels Market |
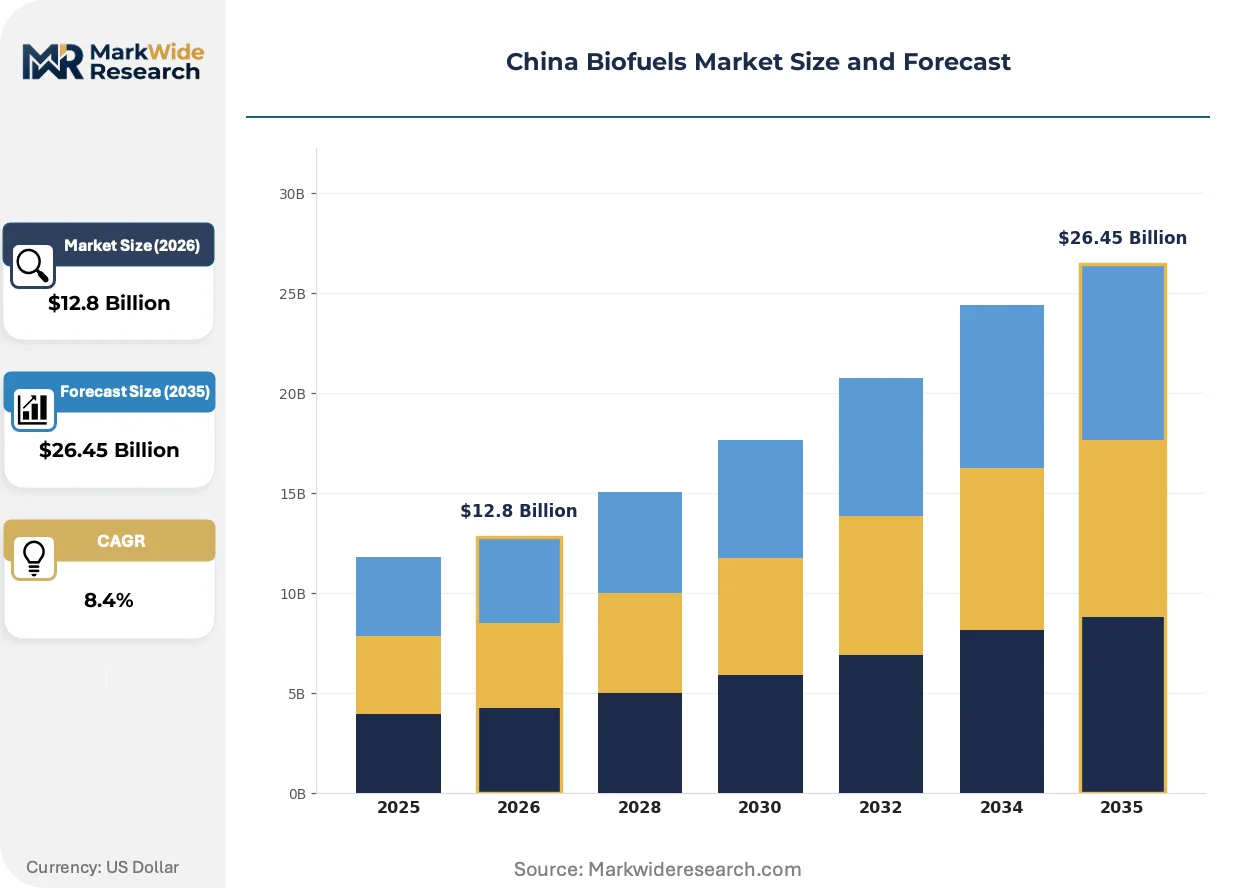
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethanol, Biodiesel, Biogas, Renewable Diesel Feedstock: Corn, Sugarcane, Waste Oils, Algae Application: Transportation, Power Generation, Heating, Industrial Use End User: Automotive, Aviation, Marine, Power Utilities |
| Companies Covered | Sinopec, COFCO Bioenergy, Zhuoyue New Energy, Zhejiang Jia'ao Environment Protection, China National Petroleum Corporation, Jilin Fuel Ethanol Ltd., Shangao Huanneng, SDIC, Shandong Longlive, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Biofuels Market Strategic Shifts
Process intensification and digital control systems are compressing conversion economics while regulatory pressure on aviation emissions accelerates certification investments across the value chain.
Continuous stirred-tank reactor automation is automating yeast fermentation monitoring in starch-based ethanol plants. Sinopec and COFCO Bioenergy deploy these systems to maintain 99.5% purity thresholds with reduced manual intervention. The technology is automating quality control staffing requirements while tightening batch consistency for fuel blending applications.
MEE emissions thresholds for biogas projects are forcing closed-loop anaerobic digestion adoption. This regulatory pressure redirects capital toward methane capture infrastructure and away from simple flaring systems. Shandong province project developers respond fastest, integrating upgrading equipment for pipeline injection or compressed biomethane vehicle fuel.
Buyers are consolidating procurement around vertically integrated suppliers with captive feedstock streams. Fuel distributors favor ethanol blenders with direct corn supply agreements over merchant market purchasers. This concentration pattern is most visible in coastal provinces where Sinopec's distribution networks anchor procurement decisions.
China Biofuels Market Segmentation
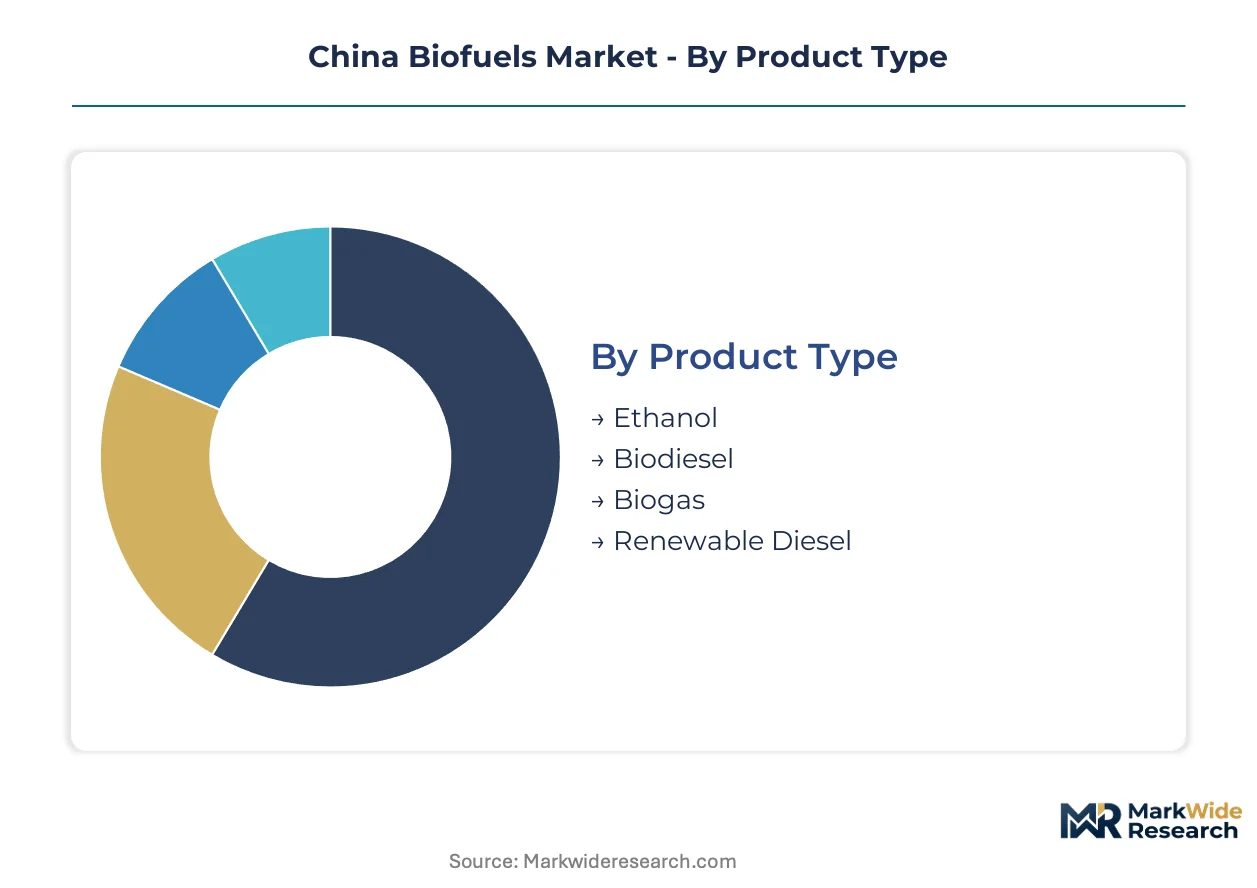
China's biofuels market fragments across production pathways and end-use specifications that dictate capital allocation, feedstock procurement, and regulatory compliance requirements. Each segmentation axis reveals distinct margin structures and competitive dynamics that shape supplier positioning across provincial markets.
Product Type:
Technology maturity and certification complexity separate established liquid fuel pathways from emerging gaseous and synthetic alternatives.
- Ethanol:Produced via yeast fermentation of starch crops at 99.5% purity for fuel blending under GB standards. Sinopec and COFCO Bioenergy anchor production in coastal provinces where blending terminals leverage existing petrochemical pipeline networks for last-mile distribution.
- Biodiesel:Manufactured through transesterification of waste oils to meet GB 25199 diesel fuel specifications. Municipal grease collection networks under MEE environmental compliance protocols are formalizing feedstock supply in urban centers, though rural collection gaps persist.
- Biogas:Captured through anaerobic digestion of municipal organic waste, with upgrading equipment enabling pipeline injection or compressed vehicle fuel. Shandong province concentrates procurement activity for upgrading systems as waste-to-energy clusters expand.
- Renewable Diesel:Hydrotreated vegetable oil pathways achieving certification alignment with international jet fuel standards. CAAC aviation fuel blending mandates are compressing timelines for technical validation and capital deployment toward aviation-grade output specifications.
Mature deployment sits with ethanol. Newer deployment is concentrated in renewable diesel.
Feedstock:
Supply security and price volatility differentiate captive agricultural streams from distributed waste collection networks.
- Corn:Dominates starch-based ethanol production through established grain-processing infrastructure. COFCO Bioenergy maintains cost advantages via captive access to agricultural supply agreements that insulate margin structures from commodity price swings.
- Waste Oils:Sourced from municipal grease traps and industrial food processing for biodiesel transesterification. Zhuoyue New Energy extends regional collection radius beyond conventional supply boundaries through specialized logistics systems.
- Sugarcane:Limited domestic cultivation restricts scale; primarily relevant for southern provinces with marginal sugar industry presence.
- Algae:Experimental cultivation systems remain pre-commercial, with cultivation economics unproven at industrial scale.
Feedstock procurement gravitates toward corn where agricultural infrastructure exists. Waste oil collection networks are expanding fastest in compliance-mandated urban centers.
Application:
Regulatory mandates and infrastructure compatibility determine adoption velocity across energy end-uses.
- Transportation:Mandatory ethanol blending quotas in designated provinces anchor demand, with fuel distributors consolidating procurement around vertically integrated suppliers with direct feedstock supply agreements.
- Power Generation:Biogas-to-electricity projects respond to MEE emissions thresholds, with closed-loop anaerobic digestion systems capturing methane for grid injection.
- Heating:Seasonal demand concentration in northern provinces, with biogas competing against established natural gas distribution networks.
- Industrial Use:Process heat applications remain niche, limited by combustion equipment retrofit requirements and fuel quality standardization.
Transportation commands infrastructure investment. Power generation is gaining regulatory momentum through emissions compliance pathways.
End User:
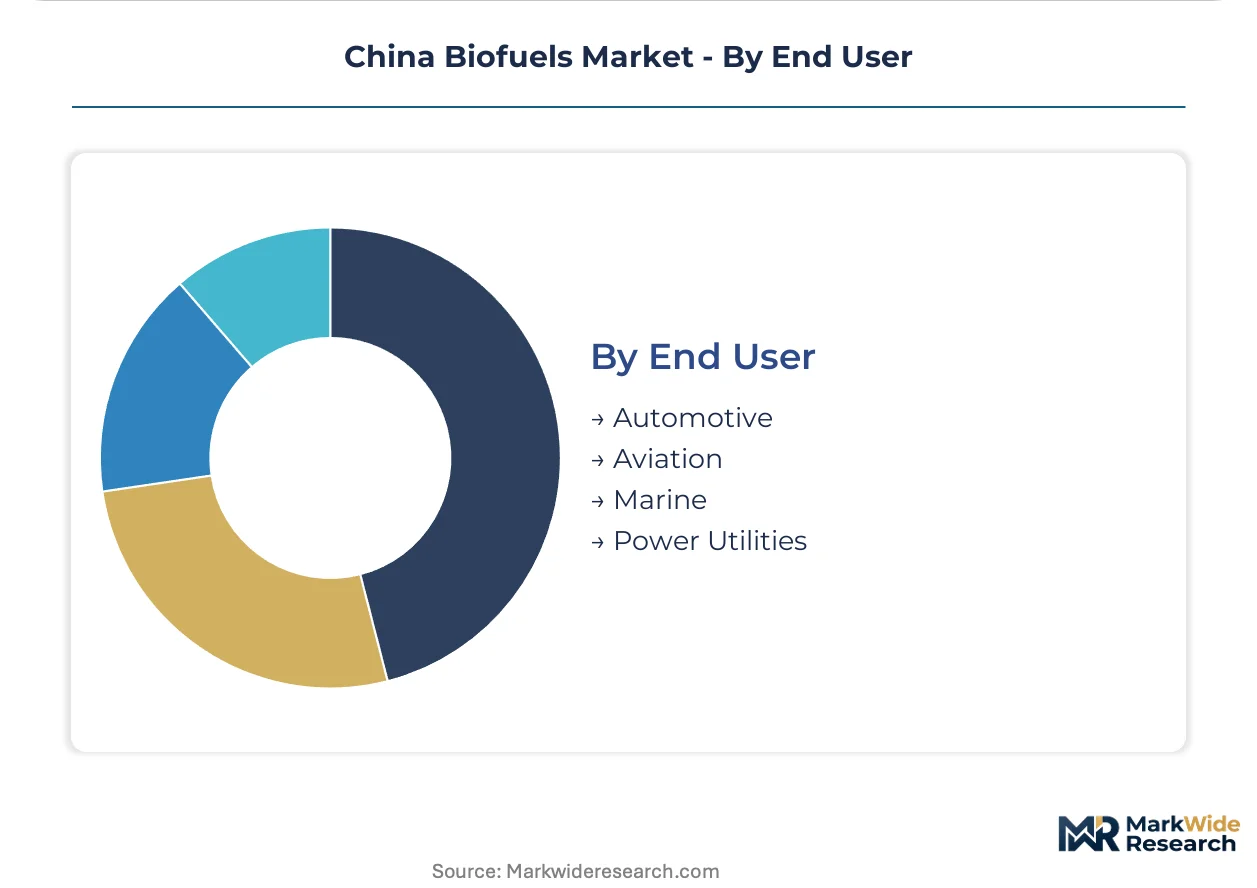
Certification requirements and volume concentration separate mass-market fuel blenders from specialized aviation and marine buyers.
- Automotive:Fuel-grade ethanol blending at provincial terminals serves the largest volume base, with Sinopec's distribution networks anchoring procurement decisions in eastern coastal provinces.
- Aviation:CAAC mandates for sustainable aviation fuel are restructuring procurement priorities, pulling capital toward hydrotreated vegetable oil pathways and premium pricing tiers for certified renewable diesel producers.
- Marine:International shipping emissions regulations are beginning to penetrate bunker fuel procurement specifications, though domestic fleet adoption lags.
- Power Utilities:Grid injection of upgraded biogas requires pipeline interconnection investments that concentrate activity around established natural gas infrastructure corridors.
Automotive retains volume concentration. Aviation is climbing the fastest on regulatory mandate pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's biofuels production concentrates in grain-processing belts and coastal refining corridors, while consumption spreads across provincial blending mandates that outpace domestic supply capacity. This geographic mismatch shapes logistics infrastructure investments and regional procurement strategies.
Shandong Province
Municipal waste-to-energy clusters concentrate biogas upgrading equipment demand as anaerobic digestion projects scale under MEE emissions compliance timelines. The province anchors northern China's biogas value chain, with project developers integrating methane capture systems for pipeline injection or compressed vehicle fuel production.
Jiangsu Province
Coastal blending terminals leverage Yangtze River Delta petrochemical infrastructure for fuel-grade ethanol distribution to provincial mandate zones. SAMR enforcement of GB fuel quality standards shapes terminal operator procurement decisions, favoring suppliers with verified purity certification and direct feedstock supply agreements.
Heilongjiang Province
Corn-processing infrastructure dominates starch-based ethanol production, with agricultural supply chains anchoring cost-competitive output for national blending programs. The National Development and Reform Commission's provincial quota allocations direct investment toward capacity expansion in this grain belt region.
Guangdong Province
Pearl River Delta refining complexes pilot hydrotreated vegetable oil pathways for aviation fuel certification under CAAC sustainable aviation fuel mandates. The province's integration with international shipping corridors accelerates renewable diesel technical validation timelines for export-grade output specifications.
Sichuan Province
Sugar industry residues and municipal organic waste feed regional biogas projects responding to western China's grid injection incentives. Chengdu-based project developers deploy closed-loop digestion systems to capture methane for vehicle fuel markets, with MEE thresholds driving capital toward emissions-compliant infrastructure.
China Biofuels Market Competitive Environment
The competitive structure tilts toward state-affiliated energy majors with captive distribution infrastructure. Sinopec and China National Petroleum Corporation anchor procurement decisions through coastal blending terminal networks, while agricultural conglomerates secure feedstock supply advantages. Three archetypes dominate: petrochemical incumbents leveraging existing pipeline assets, grain processors with backward integration into corn supply, and waste-oil specialists extending collection radius through logistics innovation. Capacity expansion and strategic partnerships with provincial distributors constitute the primary competitive moves, with certification alignment for aviation fuel emerging as a differentiation vector.
Among state-affiliated energy majors, Sinopec exemplifies the infrastructure-anchored archetype through coastal terminal dominance. COFCO Bioenergy occupies a position within the agricultural integration tier, representing feedstock-captive production models. Zhuoyue New Energy sits among specialized waste-oil processors, exemplifying regional collection network expansion strategies that extend beyond conventional municipal supply boundaries.
| Leading Market Players |
|---|
| Sinopec |
| COFCO Bioenergy |
| Zhuoyue New Energy |
| Zhejiang Jia'ao Environment Protection |
| China National Petroleum Corporation |
| Jilin Fuel Ethanol Ltd. |
| Shangao Huanneng |
| SDIC |
| Shandong Longlive |
| Others |
Value Chain & Pricing Dynamics
CAAC aviation fuel blending mandates are forcing refiners to secure certified sustainable aviation fuel supply chains, compelling supply base consolidation around hydrotreated vegetable oil pathway developers and compressing margin structures for non-certified producers.
Pricing Analysis
Margin tightening in renewable diesel reflects CAAC certification timeline compression and the capital intensity of hydrotreated vegetable oil pathway validation. Three-tier pricing structure across aviation-certified, industrial-grade, and uncertified biodiesel separates premium tiers from commodity ethanol blending pools. Cost-down pressure on waste-oil biodiesel accelerates because municipal grease collection network formalization remains uneven across provinces. Fuel distributors with direct corn supply agreements exhibit lowest price sensitivity; merchant market ethanol purchasers face highest feedstock cost volatility exposure.
Supply Chain Analysis
GB standard compliance and SAMR fuel quality enforcement act as certification gates that filter supplier participation in national blending programs. Feedstock supply concentrates in Heilongjiang corn-processing belts, Shandong waste-to-energy clusters, and Guangdong hydrotreatment pilot facilities. Raw material flows draw from captive agricultural streams, municipal organic waste networks, and imported vegetable oil feedstocks for aviation pathways. Single-source vulnerability sits with concentrated biogas upgrading equipment vendors serving Shandong project developers. Distribution runs through Sinopec's coastal blending terminals and COFCO's grain-belt ethanol pipeline networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
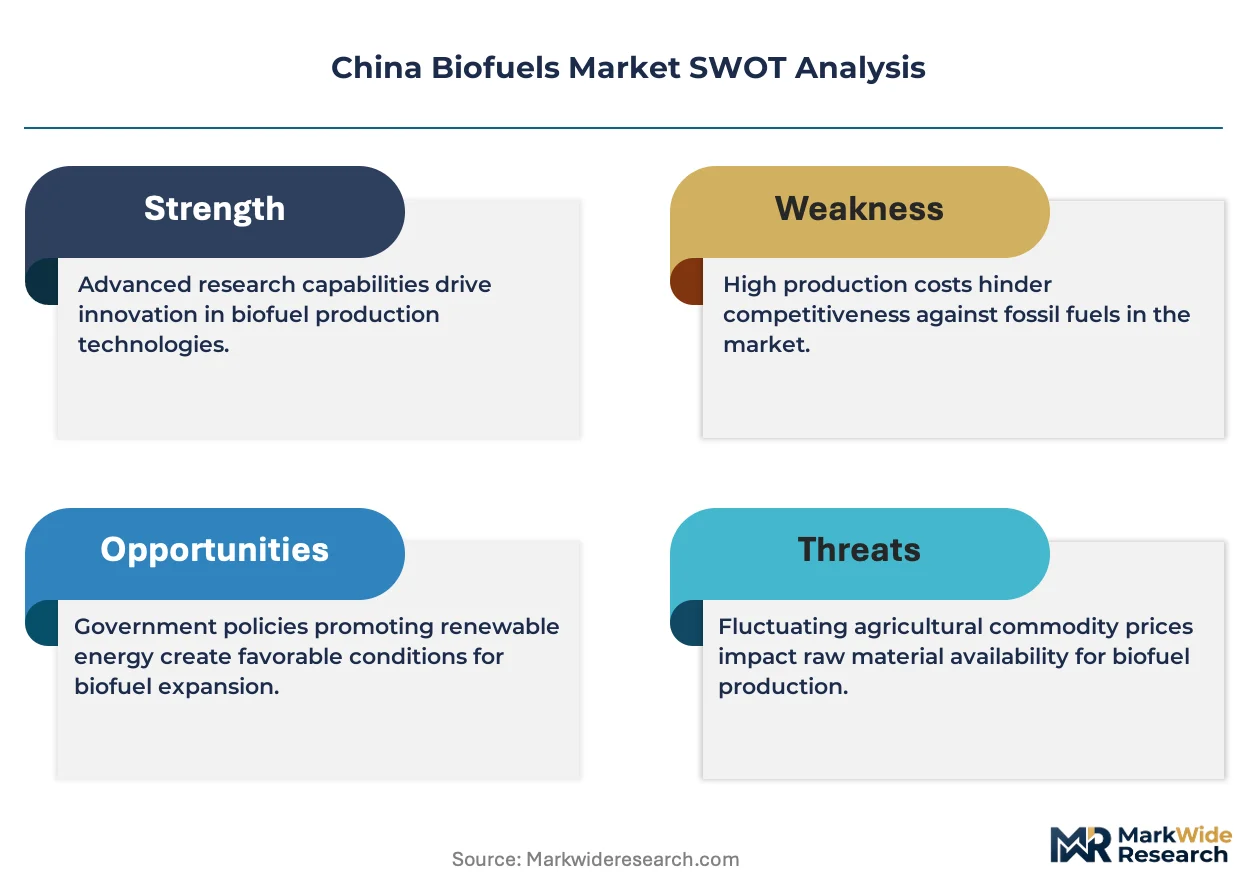
This market operates as a cost-of-compliance story where MEE emissions thresholds and CAAC aviation mandates erect barrier-to-entry moats favoring capitalized incumbents with certification infrastructure already deployed.
For Market Incumbents: Extend backward integration into captive corn supply agreements to insulate margin structures from commodity price swings. Lock in long-term offtake contracts with provincial fuel distributors before CAAC aviation mandates accelerate renewable diesel procurement consolidation. Counter the threat of hydrotreated vegetable oil pathway specialists by accelerating GB standard compliance investments.
For New Entrants and Emerging Players: CAAC sustainable aviation fuel mandates in Guangdong and coastal provinces open a window for hydrotreated vegetable oil pathway developers with international certification alignment. Target Shandong biogas upgrading equipment procurement where MEE emissions compliance timelines concentrate demand. Penetrate through closed-loop anaerobic digestion system integration for pipeline injection or compressed vehicle fuel output.
For Investors and Strategic Acquirers: The window for entry favors waste-oil collection network specialists with logistics systems extending beyond conventional municipal supply boundaries. Long-term viability centers on feedstock-captive production models with direct agricultural supply agreements or formalized grease collection infrastructure. Watch for CAAC certification milestone announcements as inflection indicators for renewable diesel valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Aviation Fuel Certification Investment | CAAC mandate compliance unlocks premium pricing tiers for hydrotreated vegetable oil producers. |
| Closed-Loop Anaerobic Digestion Buildout | MEE emissions thresholds redirect capital toward methane capture infrastructure in Shandong clusters. |
| Coastal Blending Terminal Retrofit | Sinopec leverages underutilized petrochemical pipeline assets for ethanol distribution expansion. |
| Waste Oil Collection Network Formalization | Zhuoyue New Energy extends regional collection radius beyond compliance-mandated urban centers. |
| Corn Supply Agreement Consolidation | COFCO Bioenergy anchors cost-competitive ethanol production through captive agricultural streams. |
Study Parameters
Document review covered NDRC policy circulars, CAAC aviation fuel standards, MEE emissions regulations, and SAMR GB compliance frameworks, complemented by interviews with biofuel plant managers, provincial fuel distributors, EPC contractors specializing in biogas upgrading systems, and agricultural procurement leads at ethanol producers. Secondary validation drew from customs trade data, National Bureau of Statistics energy output reports, and provincial environmental compliance disclosures. Bottom-up capacity installation tracking and top-down demand modeling from blending mandate quotas were triangulated to derive market estimates.
Cross-referencing historical capacity deployment patterns against expert panel input on CAAC certification timeline expectations shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include fuel type, feedstock source, application end-use, and provincial regulatory cluster. CAGRs were derived from supply-demand gap analysis and mandate-driven demand pull assumptions. Forecast inputs incorporated aviation fuel blending percentage trajectories and municipal waste-to-energy project pipeline data from Shandong and Sichuan provinces.
The model assumes a particular technology adoption path centered on hydrotreated vegetable oil for aviation; alternative pathways for renewable diesel via Fischer-Tropsch synthesis would alter the outlook for capital allocation and certification timelines. Forecasts reflect assumptions about CAAC mandate enforcement consistency and MEE emissions threshold maintenance. A model refresh is warranted upon material change in national blending quota allocations or international sustainable aviation fuel standard harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Biorational Pesticides Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Biopesticides Market