
 Italy Oral Anti-Diabetic Drug Market | 2026-2036
Italy Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Oral Anti-Diabetic Drug Market Outlook
The capital-intensity divergence between large-scale biopharma manufacturers and mid-size generic specialists is collapsing as both segments converge on high-complexity formulation platforms. Sanofi leverages its integrated insulin and oral drug portfolio to sustain pricing power across Italy's hospital procurement channels. Novo Nordisk anchors its position through deep R&D investment in combination therapies that bridge injectable and oral delivery. Eli Lilly competes aggressively on manufacturing scale for its SGLT2 inhibitor franchise, securing volume contracts with regional health authorities.
Italy oral anti-diabetic drugs comprise chemically synthesized or biologically derived active pharmaceutical ingredients formulated into tablets, capsules, or fixed-dose combinations that modulate glucose metabolism through distinct pharmacological pathways, including hepatic gluconeogenesis suppression, insulin secretion enhancement, or renal glucose reabsorption inhibition. These agents serve as first-line or adjunct therapies in Type 2 diabetes mellitus management within outpatient, institutional, and home-based care settings. The SGLT2 inhibitor class captures disproportionate margin pools as cardiorenal outcome data expand reimbursable indications beyond glycemic control alone. DPP-4 inhibitors occupy a mature but stable position where generic erosion has compressed prices while preserving volume across Italy's chronic disease management programs. Metformin remains the foundational volume anchor, though its commodity status limits value expansion despite sustained prescription dominance.
AIFA, Italy's national pharmaceutical regulator, governs pricing negotiations and reimbursement inclusion for oral anti-diabetic therapies through its HTA-driven assessment framework, directly conditioning market access timelines and commercial viability. The EMA's centralized marketing authorization procedures, supplemented by Italy's regional health system procurement consortia, create a dual-layer compliance environment that shapes product launch sequencing and promotional investment allocation. Stakeholders must monitor evolving AIFA cost-effectiveness thresholds for combination therapies and anticipate how regional formularies will integrate emerging dual-acting agents into standard care pathways.
Market Dynamics
AIFA's HTA-driven reimbursement revisions for SGLT2 inhibitors and GLP-1 combinations are redirecting prescribing patterns, compressing timelines for formulary inclusion while expanding reimbursable indications beyond glycemic control into cardiorenal protection.
Growth Catalysts
- Cardiorenal Outcome Data Expansion:Robust clinical evidence for SGLT2 inhibitors in heart failure and chronic kidney disease indications is broadening reimbursable patient populations across Italy's regional health systems.
- Integrated Diabetes Care Networks:Northern industrial corridor clusters spanning Milan, Turin, and Bologna are consolidating outpatient protocols around oral hypoglycemic-first treatment pathways.
- Fixed-Dose Combination Formulations:DPP-4 inhibitor and SGLT2 inhibitor dual-acting tablets are streamlining adherence protocols for polypharmacy patients in chronic disease management programs.
Market Restraints
- Generic Erosion in DPP-4 Class:Patent expirations for sitagliptin and saxagliptin are compressing pricing power for originator molecules despite sustained prescription volumes.
- Commodity Status of Metformin:Active pharmaceutical ingredient oversupply from Indian and Chinese manufacturers has eliminated margin expansion potential for this foundational volume anchor.
- Regional Procurement Fragmentation:Italy's 20 autonomous regional health authorities operate divergent formulary timelines, delaying uniform market access for novel combination therapies.
Strategic Opportunities
- Central-Southern Network Expansion:Underpenetrated diabetes care infrastructure in Campania, Sicily, and Calabria presents whitespace for integrated oral therapy protocols.
- Dual-Acting Agent Development:Convergence of GLP-1 receptor agonist oral formulations with SGLT2 inhibitor platforms is opening new pharmacological categories for hospital outpatient departments.
- Home-Based Monitoring Integration:Telemedicine-enabled glucose management platforms are creating novel channels for oral anti-diabetic therapy adherence programs.
Industry Challenges
- Formulation Complexity Talent Gap:High-complexity fixed-dose combination manufacturing requires specialized pharmaceutical scientists that mid-size generic specialists struggle to recruit.
- AIFA Negotiation Timeline Compression:Accelerated HTA assessment windows are compressing evidence-generation timelines for health economic dossiers.
- Legacy Distribution Infrastructure:Hospital-centric logistics networks require costly reconfiguration to support direct-to-patient delivery models for chronic disease management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Oral Anti-Diabetic Drug Market |
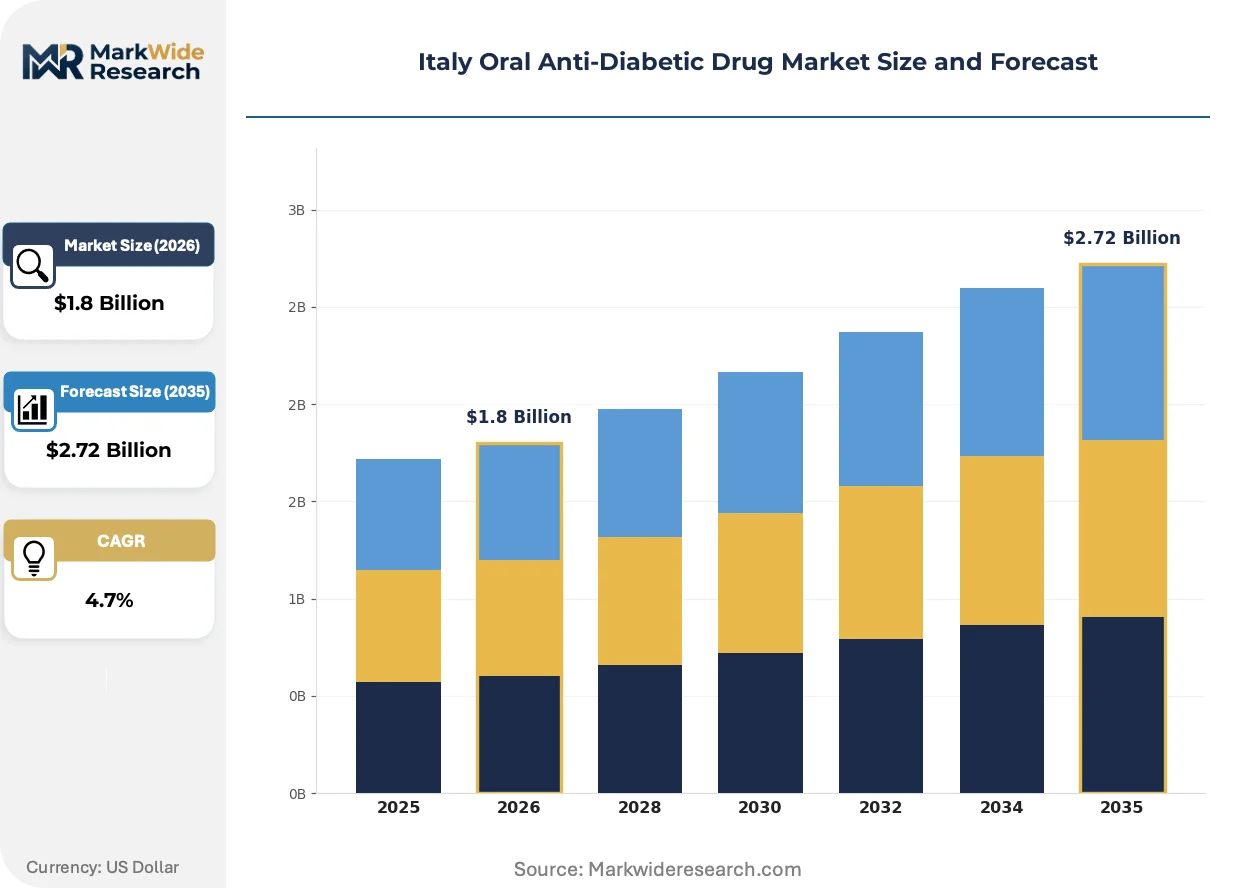
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Administration Route: Oral, Intravenous, Subcutaneous, Inhalation End User: Clinics, Outpatient Facilities, Hospitals, Home Care Distribution Channel: Pharmacies, Hospital Pharmacies, Online Retail, Wholesalers |
| Companies Covered | Sanofi, Novo Nordisk, Eli Lilly, AstraZeneca, Astellas, Merck & Co, Boehringer Ingelheim, Takeda, Janssen Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Oral Anti-Diabetic Drug Market Strategic Shifts
Oral anti-diabetic drug development is pivoting toward cardiometabolic multimorbidity management, with formulation innovation and reimbursement architecture evolving in parallel to capture expanded indication sets.
Fixed-dose combination platforms integrating SGLT2 inhibition with DPP-4 blockade are bifurcating the chronic disease management landscape. Hospital outpatient departments in Lombardy and Emilia-Romagna are adopting these dual-acting protocols at accelerated pace for patients with concurrent heart failure risk. This technology convergence is compressing standalone DPP-4 inhibitor volumes while expanding reimbursable SGLT2-containing regimens.
AIFA's cost-effectiveness threshold recalibrations for cardiorenal outcome trials are reshaping clinical trial investment priorities. Manufacturers must now generate Italy-specific health economic evidence to secure formulary inclusion within compressed negotiation windows. The SGLT2 inhibitor class bears the heaviest compliance burden as regional authorities demand localized real-world effectiveness data.
Patient adherence programs are migrating from pharmacy-based counseling to digital therapeutic companions. Smartphone-integrated medication reminders and glucose logging applications are displacing traditional nurse educator touchpoints in chronic disease management. This behavioral shift is most visible in northern industrial corridor cities where smartphone penetration and integrated care network density converge.
Italy Oral Anti-Diabetic Drug Market Segmentation
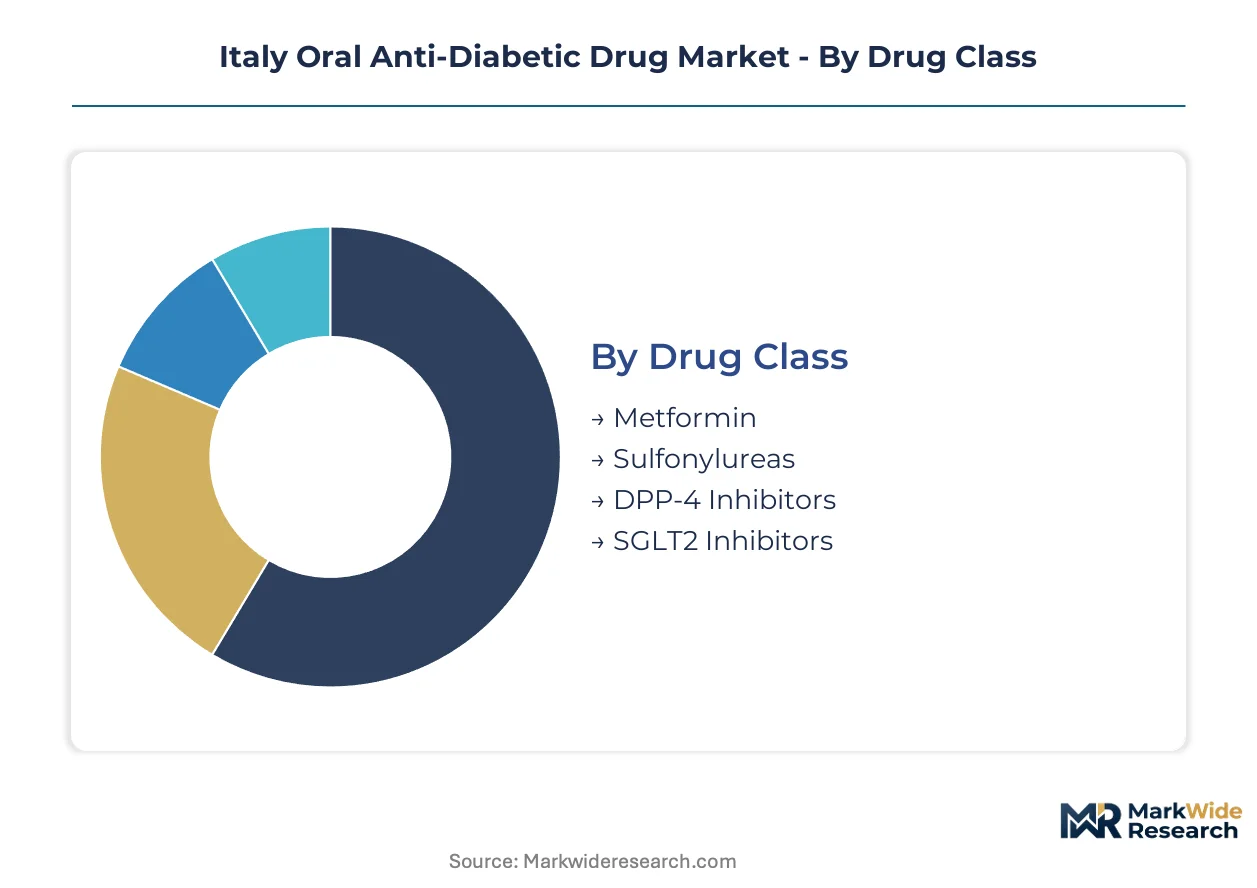
Oral anti-diabetic drug segmentation in Italy reveals how margin pools concentrate in high-complexity formulations while volume anchors remain commoditized. Understanding these splits enables targeted resource allocation across AIFA reimbursement tiers and regional procurement channels.
Drug Class:
Margin pools concentrate disproportionately in newer mechanistic classes where cardiorenal outcome data commands premium pricing.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers reduce renal glucose reabsorption and demonstrate proven cardiovascular protection. Hospital outpatient departments in Lombardy and Emilia-Romagna are prioritizing these agents for heart failure comorbidities as AIFA expands reimbursable indications beyond glycemic control.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors enhance incretin hormone activity to stimulate glucose-dependent insulin secretion. Northern integrated care networks maintain prescription volumes despite generic erosion of sitagliptin and saxagliptin originators.
- Metformin:Biguanide compounds suppress hepatic gluconeogenesis and remain the foundational first-line therapy across Italy's chronic disease management programs.
- Sulfonylureas:Pancreatic beta-cell stimulating agents persist in cost-sensitive regional formularies where older protocols dominate procurement decisions.
The dominant share belongs to Metformin, while SGLT2 Inhibitors are closing the gap fastest.
Administration Route:
Route selection determines patient adherence economics and care setting infrastructure requirements across Italy's fragmented regional health system.
- Oral:Tablet and capsule formulations enable home-based chronic disease management without clinical supervision. Demand concentrates in outpatient protocols across Milan, Turin, and Bologna where integrated diabetes care networks operate at highest density.
- Subcutaneous:Injectable delivery supports GLP-1 receptor agonist therapies that bridge toward oral formulation development pipelines.
- Intravenous:Hospital-administered routes apply in acute metabolic decompensation scenarios requiring inpatient glycemic stabilization.
- Inhalation:Pulmonary insulin delivery remains a niche experimental category with limited Italian regulatory traction.
Oral administration commands absolute volume dominance, though Subcutaneous delivery is expanding most quickly in combination therapy protocols.
End User:
Care setting segmentation reflects Italy's dual public-private infrastructure and the geographic concentration of specialized diabetes services.
- Hospitals:Acute care institutions manage complex Type 2 diabetes with comorbid cardiovascular or renal impairment. Procurement runs through regional health authority tenders with AIFA-mandated cost-effectiveness thresholds.
- Outpatient Facilities:Dedicated diabetes centers in northern industrial corridors coordinate oral hypoglycemic-first treatment pathways and patient monitoring programs.
- Clinics:Primary care settings initiate metformin therapy and refer complex cases to specialized hospital departments.
- Home Care:Telemedicine-enabled glucose management platforms are creating novel adherence channels for stable patients in Campania and Sicily.
Hospital outpatient departments capture the highest-value prescribing, while Home Care is gaining share fastest through digital therapeutic integration.
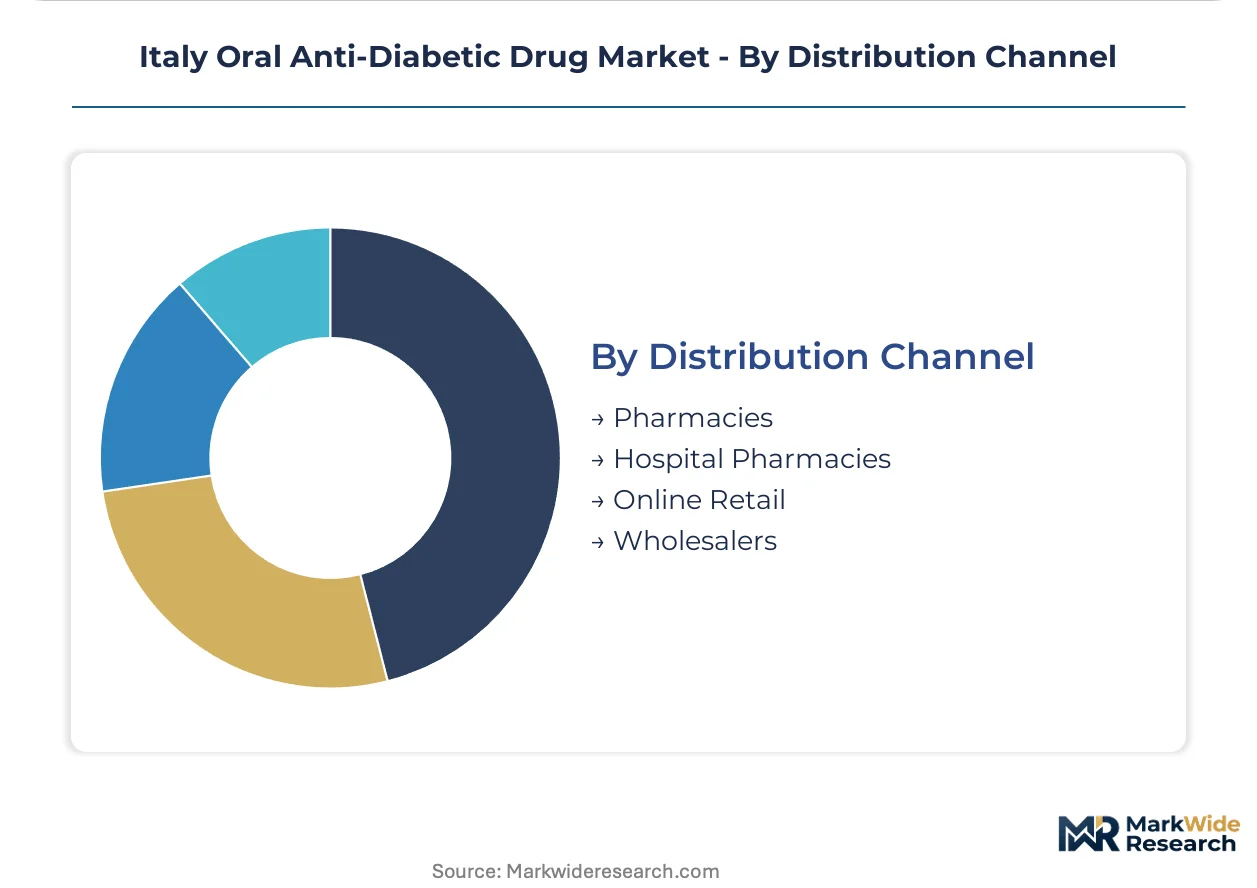
Distribution Channel:
Channel economics vary sharply between reimbursed hospital procurement and retail pharmacy margins.
- Hospital Pharmacies:Centralized regional procurement consortia negotiate volume contracts for SGLT2 inhibitor and combination therapies under AIFA pricing frameworks.
- Pharmacies:Community dispensaries handle chronic prescription refills for metformin and generic DPP-4 inhibitors with minimal margin capture.
- Wholesalers:Distribution intermediaries manage inventory logistics across Italy's 20 autonomous regional health authorities with divergent formulary timelines.
- Online Retail:Digital pharmacy platforms face regulatory constraints under Italy's strict pharmaceutical sales legislation.
Hospital Pharmacies dominate value throughput, though Wholesalers are restructuring fastest to support direct-to-patient delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prescription value in Lombardy commands premium reimbursement rates that southern regions cannot match, creating a pricing-power asymmetry that shapes manufacturer investment allocation across Italy's fragmented health system.
Lombardy
Hospital outpatient departments in Milan and Brescia prioritize SGLT2 inhibitor protocols for heart failure comorbidities. AIFA's regional formulary negotiations accelerate access for cardiorenal indication expansions. The metropolitan diabetes care network concentrates prescribing authority among integrated specialists.
Piedmont
Turin's industrial corridor sustains high-volume metformin and DPP-4 inhibitor demand through employer-sponsored chronic disease programs. Regional health authority tenders emphasize cost-effectiveness thresholds for generic substitution. The city anchors northern procurement consortium negotiations.
Emilia-Romagna
Bologna's university hospital system generates clinical trial recruitment for fixed-dose combination therapies. AIFA's HTA assessments reference real-world evidence from this region's integrated electronic health records. The Po Valley corridor links pharmaceutical distribution to Adriatic port logistics.
Campania
Naples and surrounding provinces present underpenetrated whitespace for oral hypoglycemic-first protocols. Regional budget constraints delay formulary updates for newer drug classes. Home-based telemedicine platforms are gaining traction for stable patient monitoring.
Sicily
Palermo and Catania operate legacy procurement systems with slower AIFA reimbursement implementation. Chronic disease management programs rely heavily on sulfonylureas and metformin due to cost pressures. Digital therapeutic adherence tools are expanding through EU-funded health infrastructure grants.
Italy Oral Anti-Diabetic Drug Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes within Italy's oral anti-diabetic drug market. Large-scale biopharma manufacturers command premium pricing through cardiorenal outcome data and integrated portfolios, while mid-size specialists compete on manufacturing scale and generic volume. The structure consolidates around three strategic archetypes: outcome-data-driven originators, high-volume generic manufacturers, and formulation-focused combination therapy developers. Dominant competitive moves include strategic partnerships for dual-acting agent pipelines and geographic expansion into central-southern regional networks.
Among originator-tier pharmaceutical companies, Sanofi, Novo Nordisk, and Eli Lilly occupy positions that exemplify distinct competitive strategies within AIFA's reimbursement framework. Sanofi represents the integrated portfolio archetype spanning insulin and oral delivery systems. Novo Nordisk anchors the R&D-intensive combination therapy segment bridging injectable and oral platforms. Eli Lilly exemplifies scale-driven manufacturing competition for SGLT2 inhibitor volume contracts with regional health authorities.
| Leading Market Players |
|---|
| Sanofi |
| Novo Nordisk |
| Eli Lilly |
| AstraZeneca |
| Astellas |
| Merck & Co |
| Boehringer Ingelheim |
| Takeda |
| Janssen Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Generic sitagliptin substitution for originator DPP-4 inhibitors is simultaneously redrawing Italy's API sourcing geography toward Indian manufacturers and collapsing pricing premiums in regional formularies. This input swap concentrates procurement leverage with AIFA's centralized negotiators while eroding margin pools for legacy compound holders.
Pricing Analysis
Standard-generic pricing spreads against configured-to-order SGLT2-cardiorenal bundles dominate Italy's oral anti-diabetic landscape. Contract-based long-term offtake agreements with regional health authorities secure volume for originator-tier manufacturers, while commodity spot dynamics govern metformin procurement. Price differentiation rests on AIFA reimbursement tier and real-world evidence dossier quality, with cost compression intensifying in the DPP-4 class as patent cliffs deepen. Hospital outpatient departments demonstrate lowest price sensitivity due to outcome-based procurement mandates, whereas primary care clinics in southern regions exhibit acute cost responsiveness.
Supply Chain Analysis
Inbound logistics costs through Adriatic ports and container availability on Asia-Europe trade lanes constrain API delivery timelines for Italian formulation sites. Active pharmaceutical ingredients draw from India, China, and Switzerland, with key intermediate dependencies on specialized fermentation substrates and high-purity solvents. Single-source vulnerability concentrates in SGLT2 inhibitor starting materials from select Chinese manufacturers. Distribution runs through regional health authority consortia to hospital pharmacies, with wholesale reconfiguration toward direct-to-patient channels accelerating for chronic disease management programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation complexity expertise for fixed-dose combination manufacturing represents the critical bottleneck constraining competitive entry, as mid-size specialists struggle to recruit pharmaceutical scientists capable of high-complexity platform development.
For Market Incumbents: Secure cardiorenal outcome data generation partnerships with Lombardy and Emilia-Romagna hospital systems to fortify AIFA reimbursement dossiers against emerging SGLT2 biosimilar threats. Deepen backward integration into high-complexity combination formulation capacity to preserve margin capture as generic erosion accelerates in the DPP-4 class. For New Entrants and Emerging Players: Anchor in Campania and Sicily telemedicine-enabled adherence platforms as the most penetrable whitespace for oral hypoglycemic-first protocol expansion. Target hospital outpatient department partnerships in underpenetrated central-southern networks, leveraging EU-funded digital health infrastructure grants as the primary go-to-market mechanism. For Investors and Strategic Acquirers: AIFA's HTA-driven reimbursement recalibrations for dual-acting agents reshape the acquisition landscape toward formulation-focused developers with cardiorenal trial capabilities. Five-to-ten-year viability favors targets possessing integrated oral-injectable combination pipelines and established regional health authority relationships. Monitor AIFA cost-effectiveness threshold publications as the critical inflection signal for portfolio rebalancing toward SGLT2-GLP-1 convergence plays.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiorenal Outcome Trial Advancement | Generates AIFA-reimbursable indication expansions beyond glycemic control for SGLT2 inhibitor portfolios. |
| Fixed-Dose Combination Manufacturing Scale-Up | Captures hospital outpatient volume contracts in Lombardy's integrated diabetes care networks. |
| Regional Health Authority Partnership | Accelerates formulary inclusion timelines for novel dual-acting agents across Italy's 20 autonomous authorities. |
| Telemedicine Platform Integration | Creates adherence program channels for stable patients in Campania and Sicily home-care settings. |
| API Sourcing Diversification | Mitigates single-source vulnerability in SGLT2 inhibitor starting materials from concentrated Asian suppliers. |
Study Parameters
Operator-level perspectives from AIFA reimbursement specialists, hospital formulary directors, regional procurement managers, and chronic disease program coordinators anchored the qualitative base for this analysis. Primary interview intelligence combined with secondary validation from EMA centralized marketing authorization records, AIFA pricing negotiation disclosures, ClinicalTrials.gov cardiorenal outcome registrations, and regional health authority tender databases. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources to establish segment boundaries.
Sensitivity analysis tested forecast robustness across alternative AIFA HTA timeline scenarios and generic erosion velocity assumptions throughout the projection horizon. Segmentation dimensions modeled encompass drug class, administration route, end-user care setting, and distribution channel, with patient population risk stratification as the industry-specific overlay. CAGRs derived from regression-based trend extrapolation against historical reimbursement volume data, incorporating AIFA cost-effectiveness threshold evolution and regional formulary adoption lag patterns as key forecast inputs.
Underlying assumptions cover sustained AIFA cardiorenal indication expansion for SGLT2 inhibitors and stable regional health authority procurement fragmentation, with deviation risk concentrated in accelerated generic entry for DPP-4 inhibitors and API supply disruption from Asian manufacturing clusters. Practitioners should keep alternative scenarios live as AIFA negotiation timelines and EMA regulatory guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market