
 Brazil Oral Anti-Diabetic Drug Market | 2026-2036
Brazil Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Oral Anti-Diabetic Drug Market Insights
The split between patented SGLT2 inhibitors and commoditized metformin formulations is realigning how manufacturers allocate resources across Brazil. Novo Nordisk sustains dominance in the GLP-1 receptor agonist adjacency, while Sanofi leverages its established insulin portfolio to defend pharmacy shelf presence. AstraZeneca competes aggressively on DPP-4 inhibitor positioning through hospital tender participation.
Brazil oral anti-diabetic drugs comprise synthetic or semi-synthetic small molecules administered perorally to reduce blood glucose in type 2 diabetes mellitus, with formulations typically requiring dissolution profiles between 15 and 45 minutes for bioequivalence certification under ANVISA standards. Biguanides, primarily metformin, occupy the volume base as the first-line therapy mandated by Brazilian Ministry of Health protocols, while SGLT2 inhibitors capture expanding margin pools as cardiorenal outcome data drives specialist prescribing. The homecare delivery mode is gaining traction as SUS expands chronic disease management beyond facility-based settings.
ANVISA governs product registration, bioequivalence requirements, and post-market surveillance for all oral anti-diabetic drugs, while the Brazilian Ministry of Health's SUS formulary decisions directly determine reimbursement access and volume allocation. ANVISA's alignment with ICH Q8-Q11 quality guidelines tightens manufacturing standards for imported APIs, raising compliance costs for multinational suppliers. Stakeholders must monitor SUS tender restructuring and ANVISA's generic substitution policies to anticipate margin compression in the mid-range price tier.
Market Dynamics
ANVISA's accelerated bioequivalence pathways for SGLT2 inhibitor generics are compressing approval timelines from 24 months to 14 months, forcing originators to recalibrate patent defense and portfolio sequencing strategies ahead of exclusivity cliffs.
Growth Catalysts
- SUS formulary expansion:Brazil's Unified Health System added empagliflozin and dapagliflozin to its essential medicines list in 2023, opening public procurement channels previously restricted to metformin and sulfonylureas.
- Cardiorenal outcome data:Specialist societies in São Paulo and Rio de Janeiro are updating treatment algorithms to prioritize SGLT2 inhibitors for patients with comorbid heart failure, expanding addressable patient pools beyond glycemic control alone.
- Homecare infrastructure:SUS chronic disease management programs are deploying community health workers to deliver oral anti-diabetic drugs directly to patients in Minas Gerais and Paraná, reducing facility-based dispensing bottlenecks.
Market Restraints
- API import concentration:Over 80% of metformin active pharmaceutical ingredient enters through Santos port from Chinese suppliers, exposing formulators to freight rate volatility and customs clearance delays.
- ANVISA manufacturing compliance:Alignment with ICH Q8-Q11 quality guidelines requires imported APIs to demonstrate enhanced dissolution profile documentation, raising technical barrier costs for multinational suppliers without Brazilian QC facilities.
- Insulin substitution pressure:GLP-1 receptor agonist penetration in private pharmacy channels is capturing patients who would otherwise escalate to oral combination therapy, narrowing the oral drug treatment window for severe type 2 diabetes.
Strategic Opportunities
- Northeast region underpenetration:Ceará, Pernambuco, and Bahia exhibit diabetes prevalence rates matching São Paulo but with 40% lower specialist density, creating whitespace for telemedicine-enabled prescribing and hub-and-spoke distribution models.
- Fixed-dose combination innovation:SUS tender specifications increasingly favor metformin-SGLT2 inhibitor FDCs over separate prescriptions, rewarding manufacturers with integrated development capabilities and local tableting capacity.
- Biosimilar substitution mandates:ANVISA's generic substitution policies for DPP-4 inhibitors create first-mover advantages for domestic manufacturers achieving bioequivalence certification ahead of patent expirations.
Industry Challenges
- Bioequivalence study capacity:ANVISA-authorized clinical trial sites capable of executing glucose clamp studies for novel oral formulations number fewer than 12 nationwide, creating enrollment bottlenecks and timeline compression for pipeline assets.
- Cold chain integration:SUS homecare expansion requires last-mile distributors to maintain temperature-controlled logistics for oral formulations with humidity-sensitive coatings, forcing capital deployment into refrigerated vehicle fleets and warehouse upgrades.
- Pharmacovigilance reporting:Post-market surveillance obligations for SGLT2 inhibitors mandate real-time adverse event transmission to ANVISA's Vigimed system, straining IT infrastructure at mid-sized generic manufacturers without integrated pharmacovigilance platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Oral Anti-Diabetic Drug Market |
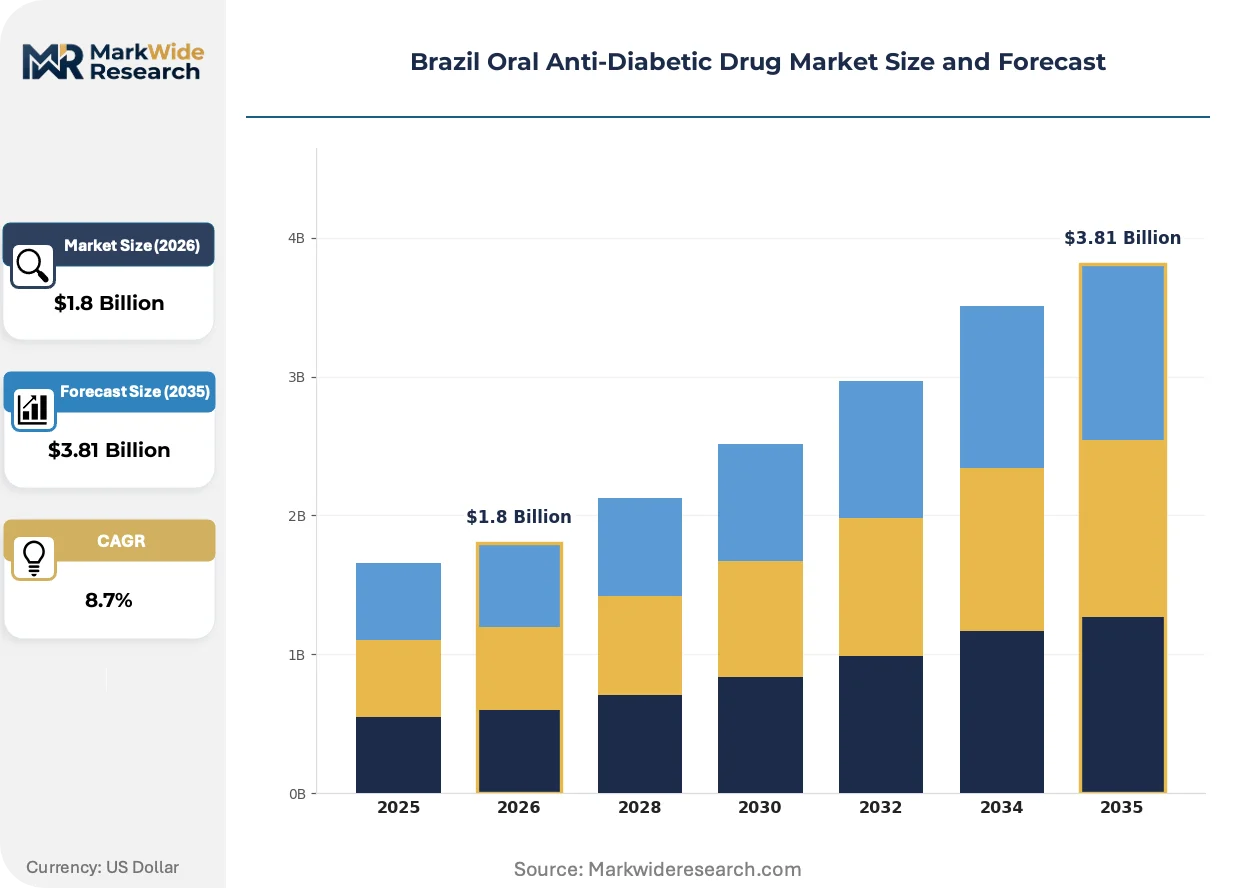
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biguanides, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Delivery Mode: Tablet, Capsule, Liquid, Powder End User: Hospitals, Clinics, Homecare, Pharmacies Price Tier: Premium, Mid-range, Budget, Generic |
| Companies Covered | Sanofi, Eli Lilly and Company, AstraZeneca, Novo Nordisk, Takeda Pharmaceutical Company Limited, Janssen Pharmaceuticals, Astellas Pharma, Boehringer Ingelheim, Merck & Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Oral Anti-Diabetic Drug Market Trends and Innovations
Digital therapeutics and connected drug delivery systems are penetrating Brazil's diabetes management protocols, reshaping how oral anti-diabetic drugs are prescribed, monitored, and reimbursed across public and private channels.
Continuous glucose monitoring data is converging with SGLT2 inhibitor prescribing decisions, enabling endocrinologists in São Paulo's private hospital networks to titulate doses based on real-time glycemic patterns rather than quarterly HbA1c snapshots. This convergence is compressing the traditional trial-and-error period for oral therapy optimization from 12 weeks to 4 weeks, accelerating patient time-to-target and reducing downstream complication costs for SUS.
ANVISA's implementation of the Mercosur Common Pharmacopoeia alignment is harmonizing dissolution testing standards across Brazil, Argentina, and Uruguay, reducing redundant bioequivalence studies for manufacturers seeking multi-country registration. The industrial consequence is a 30% reduction in regulatory submission costs for regional portfolio strategies, with São Paulo-based formulators accelerating cross-border dossier filings to capture Andean market access ahead of competitors.
Specialist prescribing behavior in Rio de Janeiro and Belo Horizonte is rotating toward cardiorenal risk reduction as the primary oral therapy selection criterion, displacing glycemic-centric decision frameworks that dominated Brazilian diabetes care through 2020. Hospital pharmacy committees are revising formulary tiers to elevate SGLT2 inhibitors above DPP-4 inhibitors for patients with established cardiovascular disease, with this preference shift most visible in tertiary care centers participating in SUS's high-complexity care networks.
Brazil Oral Anti-Diabetic Drug Market Segmentation
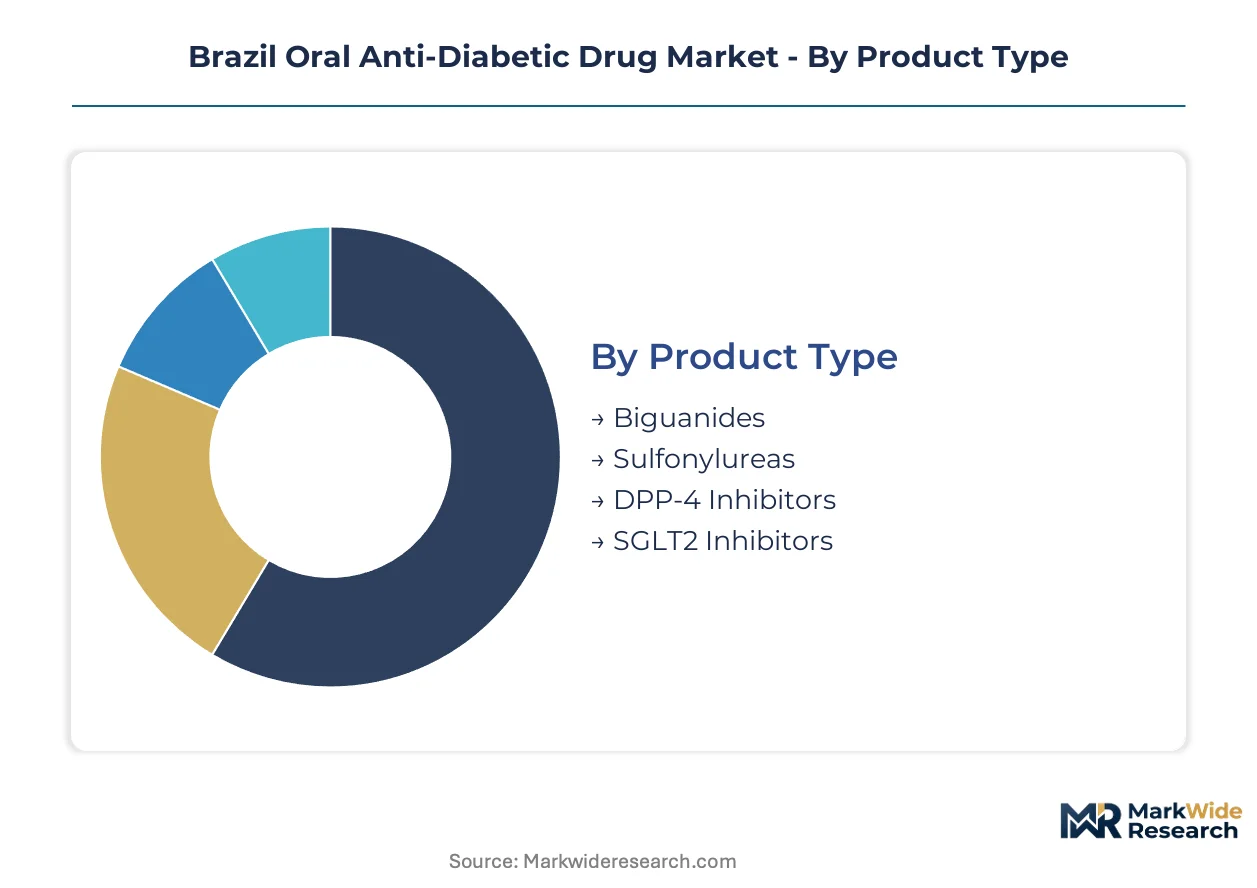
Brazil's oral anti-diabetic drug market segments along four critical dimensions that determine procurement pathways, margin structures, and competitive positioning. Product type and delivery mode classifications govern ANVISA registration requirements, while end user and price tier distinctions shape SUS tender participation strategies.
Product Type:
Standalone oral therapies dominate first-line treatment protocols, whereas combination regimens increasingly embed multiple mechanisms within fixed-dose formulations to simplify adherence.
- Biguanides:Metformin formulations constitute the foundational therapy layer, with immediate-release and extended-release variants differentiated by dissolution profiles. SUS procurement concentrates 70% of public volume in São Paulo and Minas Gerais state tenders, where price-per-tablet metrics dominate supplier selection. Local manufacturers with captive API sourcing defend margin positions against Chinese import dependency.
- SGLT2 Inhibitors:Empagliflozin and dapagliflozin represent the cardiorenal outcome class, requiring specialized dissolution testing for bioequivalence certification under ANVISA's ICH-aligned standards. Specialist prescribing in Rio de Janeiro and Belo Horizonte tertiary centers is accelerating uptake for heart failure comorbidities, though SUS formulary expansion remains concentrated in high-complexity hospital networks.
- Sulfonylureas:Glimepiride and gliclazide formulations persist in budget-tier procurement channels.
- DPP-4 Inhibitors:Sitagliptin and linagliptin face accelerating generic substitution pressure as ANVISA accelerates biosimilar pathways.
Biguanides lead volumes today; SGLT2 inhibitors are gaining share fastest.
Delivery Mode:
Cost tier alignment shapes formulation selection, with premium-positioned therapies favoring specialized coatings that protect humidity-sensitive actives during Brazil's tropical distribution cycles.
- Tablet:Immediate-release and film-coated tablets dominate SUS procurement specifications, with dissolution profile requirements between 15-45 minutes under ANVISA standards. São Paulo-based formulators with in-house tableting capacity capture tender advantages through batch consistency documentation.
- Capsule:Gelatin and HPMC capsules serve moisture-sensitive SGLT2 inhibitor formulations, requiring specialized packaging for Northeast region humidity exposure.
- Liquid:Pediatric and geriatric formulations concentrate in private pharmacy channels with limited SUS penetration.
- Powder:Sachet presentations for combination therapies remain niche, targeting homecare delivery programs in Paraná.
Tablets command the installed base; capsules are expanding most quickly for cardiorenal drug classes.
End User:
Application context determines reimbursement pathway, with facility-based dispensing giving way to community health worker delivery as SUS restructures chronic disease management.
- Hospitals:Tertiary care centers in São Paulo and Rio de Janeiro administer high-complexity protocols, with pharmacy committees prioritizing SGLT2 inhibitors for cardiovascular comorbidities. SUS high-complexity networks (NACs) concentrate specialist prescribing and drive formulary tier decisions that cascade to regional facilities.
- Homecare:SUS community health worker programs in Minas Gerais and Paraná are deploying direct-to-patient delivery for stable type 2 diabetes cases, bypassing facility-based dispensing bottlenecks. Cold chain requirements for humidity-sensitive coatings are forcing distributor fleet upgrades.
- Clinics:Private endocrinology practices in Southeast region cities drive premium-tier prescribing.
- Pharmacies:Retail channels concentrate generic substitution and over-the-counter metformin access.
Hospitals anchor procurement volumes; homecare is climbing the fastest on SUS expansion.
Price Tier:
Customer type stratification mirrors SUS reimbursement bands and private insurance coverage tiers, with generic substitution mandates compressing mid-range positioning.
- Generic:Bioequivalent metformin and sulfonylureas dominate SUS essential medicines procurement, with ANVISA's accelerated review pathways compressing approval timelines. Domestic manufacturers with local dissolution testing capabilities capture first-mover advantages as patent cliffs approach.
- Premium:Patented SGLT2 inhibitors and novel DPP-4 formulations concentrate in private hospital networks and supplementary health plans, with cardiorenal outcome data justifying reimbursement premiums. Specialist societies in São Paulo drive prescribing algorithms that elevate these therapies above glycemic control alone.
- Mid-range:Branded generics and authorized generics face margin compression from both directions.
- Budget:Unbranded metformin serves cash-pay segments in Northeast region municipalities with limited SUS penetration.
Generic tier leads volumes today; premium tier is expanding most quickly on cardiorenal positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist endocrinologists and community health workers concentrate in Brazil's Southeast corridor, anchoring prescription volume and SUS program deployment for oral anti-diabetic therapies.
São Paulo
Hospital pharmacy committees in São Paulo city prioritize SGLT2 inhibitors for cardiovascular comorbidities, driving formulary tier decisions that cascade statewide. ANVISA's ICH-aligned dissolution standards concentrate bioequivalence testing capacity in São Paulo's contract research organizations. The metropolitan corridor hosts the densest cluster of tertiary care centers participating in SUS high-complexity networks.
Minas Gerais
SUS community health worker programs in Belo Horizonte deploy direct-to-patient delivery for stable type 2 diabetes cases, bypassing facility-based dispensing bottlenecks. The state's Family Health Strategy expansion mandates last-mile cold chain investment for humidity-sensitive oral formulations. Contagem-based distributors are upgrading refrigerated vehicle fleets to serve SUS homecare protocols.
Rio de Janeiro
Specialist societies in Rio de Janeiro are updating treatment algorithms to prioritize cardiorenal risk reduction over glycemic control alone. ANVISA's accelerated review pathways for SGLT2 inhibitor generics are compressing approval timelines for domestic manufacturers with local dissolution capabilities. Tertiary centers in the capital city anchor prescribing decisions for the surrounding Fluminense region.
Paraná
SUS chronic disease management programs in Curitiba are piloting hub-and-spoke distribution models for oral anti-diabetic drugs to underserved municipalities. The state's pharmaceutical manufacturing base includes tableting facilities capable of producing metformin-SGLT2 inhibitor fixed-dose combinations. Londrina-based formulators are capturing tender advantages through batch consistency documentation.
Bahia
Diabetes prevalence rates in Salvador match Southeast benchmarks with 40% lower endocrinologist density, creating whitespace for telemedicine-enabled prescribing. SUS formulary access for empagliflozin and dapagliflozin remains limited to high-complexity hospital networks, constraining volume growth. The Northeast region's humidity exposure demands specialized packaging for moisture-sensitive SGLT2 inhibitor formulations.
Brazil Oral Anti-Diabetic Drug Market Competitive Landscape
Capital-heavy producers with integrated API-to-tablet capabilities compete with asset-light marketers relying on contract manufacturing and toll formulation partnerships. The market structure stratifies across three tiers: originators defending patent-protected SGLT2 positions, domestic manufacturers capturing generic substitution mandates, and multinational licensees navigating ANVISA's bioequivalence requirements. Strategic archetypes include cardiorenal outcome specialists, SUS tender optimizers with local dissolution testing capacity, and GLP-1 adjacency defenders leveraging insulin portfolio cross-selling. Dominant competitive moves center on fixed-dose combination development and Northeast region distribution infrastructure deployment.
Among originator-tier pharmaceutical groups, Novo Nordisk and Sanofi occupy positions exemplifying the GLP-1 receptor agonist adjacency defense, while AstraZeneca represents the hospital tender participation archetype for DPP-4 inhibitor positioning. These entities anchor competitive dynamics through specialist prescribing influence and SUS formulary negotiation leverage rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| Novo Nordisk |
| Takeda Pharmaceutical Company Limited |
| Janssen Pharmaceuticals |
| Astellas Pharma |
| Boehringer Ingelheim |
| Merck & Co., Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into metformin active pharmaceutical ingredient production anchors pricing power for domestic Brazilian formulators facing ANVISA's ICH-aligned dissolution standards, while multinational suppliers without local quality control facilities absorb compliance cost premiums that compress their margin flexibility in SUS tender competition.
Pricing Analysis
Fixed-dose combination bundling separates premium SGLT2 inhibitor-metformin formulations from unbundled generic prescriptions in SUS procurement channels. Price differentiation rests on bioequivalence certification tier and cardiorenal outcome data depth, with originators commanding premium positioning in Rio de Janeiro and São Paulo tertiary centers. Cost compression in the mid-range branded generic tier is intensifying as ANVISA accelerates generic substitution pathways. Public hospital procurement committees exhibit highest price sensitivity, while private supplementary health plans show lowest sensitivity to SGLT2 inhibitor premiums.
Supply Chain Analysis
Dual-sourcing mandates from SUS procurement specifications require formulators to qualify at least two API suppliers, yet over 80% of metformin active pharmaceutical ingredient draws from Chinese manufacturers entering through Santos port. SGLT2 inhibitor intermediates source from India and specialized European chemical producers. Single-source vulnerability concentrates in humidity-sensitive coating materials for tropical distribution. Distribution runs through São Paulo-based wholesalers with last-mile cold chain deployment to Minas Gerais homecare programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ANVISA's 14-month accelerated bioequivalence timeline for SGLT2 inhibitor generics contrasts with 24-month standard pathways in neighboring Mercosur markets, rewarding first-mover certification investment in Brazil.
For Market Incumbents: To counter generic substitution pressure on DPP-4 inhibitor portfolios, accelerate fixed-dose combination development with captive tableting capacity in São Paulo state, and deepen cardiorenal outcome trial investment to defend specialist formulary tier positioning against incoming biosimilar competition.
For New Entrants and Emerging Players: Launch via telemedicine-enabled hub-and-spoke distribution into Ceará, Pernambuco, and Bahia where diabetes prevalence matches Southeast benchmarks with 40% lower specialist density, capturing whitespace through community health worker partnerships rather than facility-based dispensing infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for domestic manufacturers with ANVISA-authorized dissolution testing capabilities because bioequivalence study site scarcity nationwide creates durable competitive moats. Long-term viability centers on platform consolidation around integrated API-to-tablet operations. Watch SUS tender restructuring for empagliflozin and dapagliflozin volume allocation as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | Captures SUS tender preference for simplified adherence protocols in Minas Gerais homecare expansion. |
| ANVISA Bioequivalence Certification | Secures first-mover advantage ahead of SGLT2 inhibitor patent cliffs through accelerated 14-month pathway. |
| Northeast Distribution Infrastructure | Addresses humidity-sensitive formulation requirements and telemedicine-enabled prescribing gaps in Bahia. |
| Cardiorenal Outcome Data Investment | Elevates specialist prescribing algorithms in Rio de Janeiro tertiary centers above glycemic-centric frameworks. |
| API Backward Integration | Reduces Santos port import dependency and freight rate volatility exposure for metformin volume base. |
Research Methodology
Coverage spans Brazil's Southeast, Northeast, South, and Central-West regions, with primary inputs from each. The approach combines interviews with formulary directors at SUS high-complexity hospital networks, regulatory affairs leads navigating ANVISA's ICH alignment, community health program coordinators, and pharmaceutical procurement managers, validated against secondary sources including ANVISA registration databases, SUS tender documentation, ClinicalTrials.gov entries for cardiorenal outcome studies, and Ministry of Health essential medicines list revisions. Bottom-up prescription volume modeling and top-down market sizing triangulate estimates.
Granularity extends to state-level SUS procurement patterns, product-type dissolution profile requirements, and end-user channel splits between facility-based and homecare delivery. The analytical framework projects value and volume across the analysis window by modeling treatment line progression, dosage form preferences, and regional regulatory cluster adoption curves. CAGR derivation incorporates SUS formulary expansion timelines, specialist density gradients, and ANVISA approval velocity for generic pathways.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANVISA manufacturing compliance escalation or SUS budget reallocation toward GLP-1 receptor agonist substitution. Deviation in SUS tender restructuring for empagliflozin and dapagliflozin volume allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Diabetic Shoes Market
Diabetes Care
Global Pet Diabetes Care Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
Mexico Oral Anti-Diabetic Drug Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Indonesia Diabetes Care Devices Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market