
 Japan Self-Monitoring Blood Glucose Devices Market | 2026-2036
Japan Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Self-Monitoring Blood Glucose Devices Market Insights
Enzymatic test strip chemistry is consolidating around more stable glucose oxidase formulations that extend shelf life and reduce calibration drift. Arkray leverages its domestic manufacturing footprint to anchor supply continuity for Japanese hospital procurement channels. Roche Diabetes Care sustains R&D intensity across electrochemical sensor architectures, while Abbott Diabetes Care competes through integrated continuous monitoring ecosystems that pair hardware with algorithm-driven insulin dosing support.
Self-monitoring blood glucose devices comprise portable electrochemical or optical analyzers that quantify capillary glucose concentration through enzyme-mediated reactions on disposable strips, with primary commercial purpose of enabling real-time metabolic management by diabetic patients outside clinical settings. Continuous glucose monitors capture the fastest expansion trajectory as algorithmic predictive alerts replace reactive fingerstick protocols, while traditional meters retain volume dominance among price-sensitive segments and elderly populations less receptive to wearable interfaces. Smart meters represent an emerging margin pool where Bluetooth-enabled data streaming to physician dashboards creates recurring software-service revenue atop hardware sales.
PMDA medical device approval pathways and JIS quality standards govern sensor accuracy thresholds and software validation requirements for glucose monitoring systems distributed in Japan. METI industrial policy incentives for digital health infrastructure accelerate hospital procurement of connected monitoring platforms that integrate with electronic health record architectures. Stakeholders must weigh PMDA's evolving software-as-medical-device guidance against the capital requirements for domestic clinical validation studies when prioritizing product portfolio investments.
Market Dynamics
Japan's aging demographic profile is compressing care delivery timelines, forcing device manufacturers to reconcile hospital procurement consolidation with home care decentralization. PMDA software-as-medical-device guidance is modularizing validation requirements across connected glucose platforms.
Growth Catalysts
- Telemedicine infrastructure expansion:METI digital health incentives are accelerating hospital procurement of Bluetooth-enabled meters that stream data to physician dashboards. Tokyo's diabetes clinics are piloting remote monitoring protocols that reduce outpatient visit frequency.
- Enzyme formulation advances:Glucose oxidase chemistry with extended thermal stability is reducing calibration drift in test strips. Osaka-based pharmacy networks are prioritizing shelf-life specifications in procurement tenders.
- Home care autonomy demand:Elderly diabetic patients in metropolitan corridors are rejecting clinic-dependent monitoring. Self-management protocols are displacing reactive fingerstick schedules in patient education programs.
Market Restraints
- Input cost concentration:Noble metal catalysts for electrochemical sensors face supply volatility from South African mining output fluctuations. Japanese manufacturers lack captive supply of platinum-group materials.
- Technical accuracy ceilings:Enzymatic test strips exhibit hematocrit interference at extreme physiological ranges. PMDA accuracy thresholds for hypoglycemic range readings remain unmet by strip-based systems.
- Regulatory friction:PMDA software validation timelines for algorithm-driven insulin dosing support extend development cycles by 18-24 months versus hardware-only submissions.
Strategic Opportunities
- Rural prefecture penetration:Hokkaido and Tohoku regions show 40% lower device ownership rates than Kanto. Mobile screening units paired with pharmacy distribution could unlock volume pools.
- Continuous monitoring convergence:Factory-calibrated optical sensors are eliminating fingerstick requirements for Type 2 patients. Integration with wearable form factors is creating premium positioning.
- Reimbursement pathway expansion:Japan's Ministry of Health, Labour and Welfare is reviewing remote monitoring fee schedules. Connected meter data transmission may qualify for new technical fee billing codes.
Industry Challenges
- Clinical validation capacity:Domestic PMDA-mandated studies require specialized endocrinology trial sites concentrated in Tokyo and Osaka. Site availability constraints are compressing submission timelines.
- Legacy system integration:Hospital electronic health record architectures use proprietary data formats. Middleware development for glucose data interoperability demands specialized health IT engineering.
- Algorithm transparency requirements:PMDA guidance on explainable AI for predictive hypoglycemia alerts is creating documentation burdens. Engineering teams lack regulatory affairs expertise in machine learning validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Self-Monitoring Blood Glucose Devices Market |
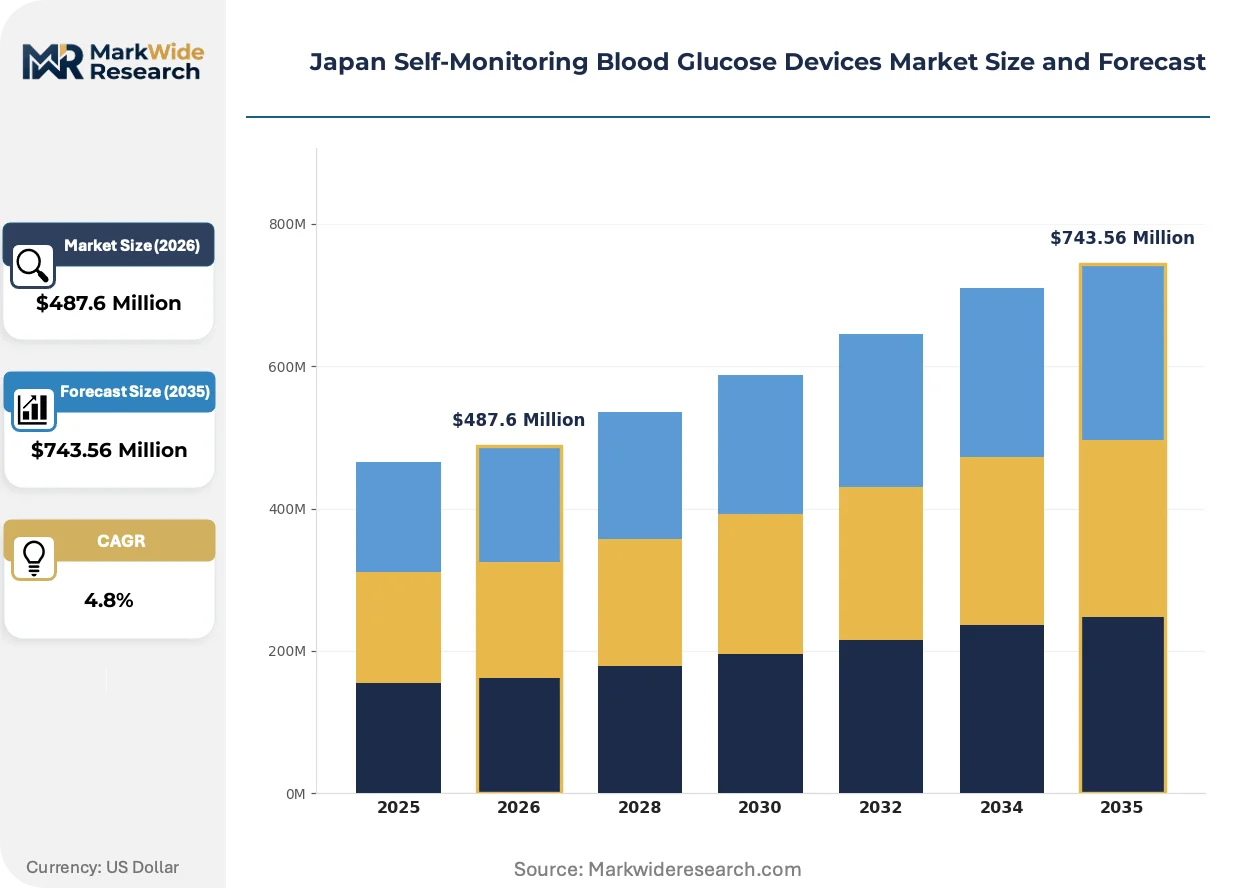
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
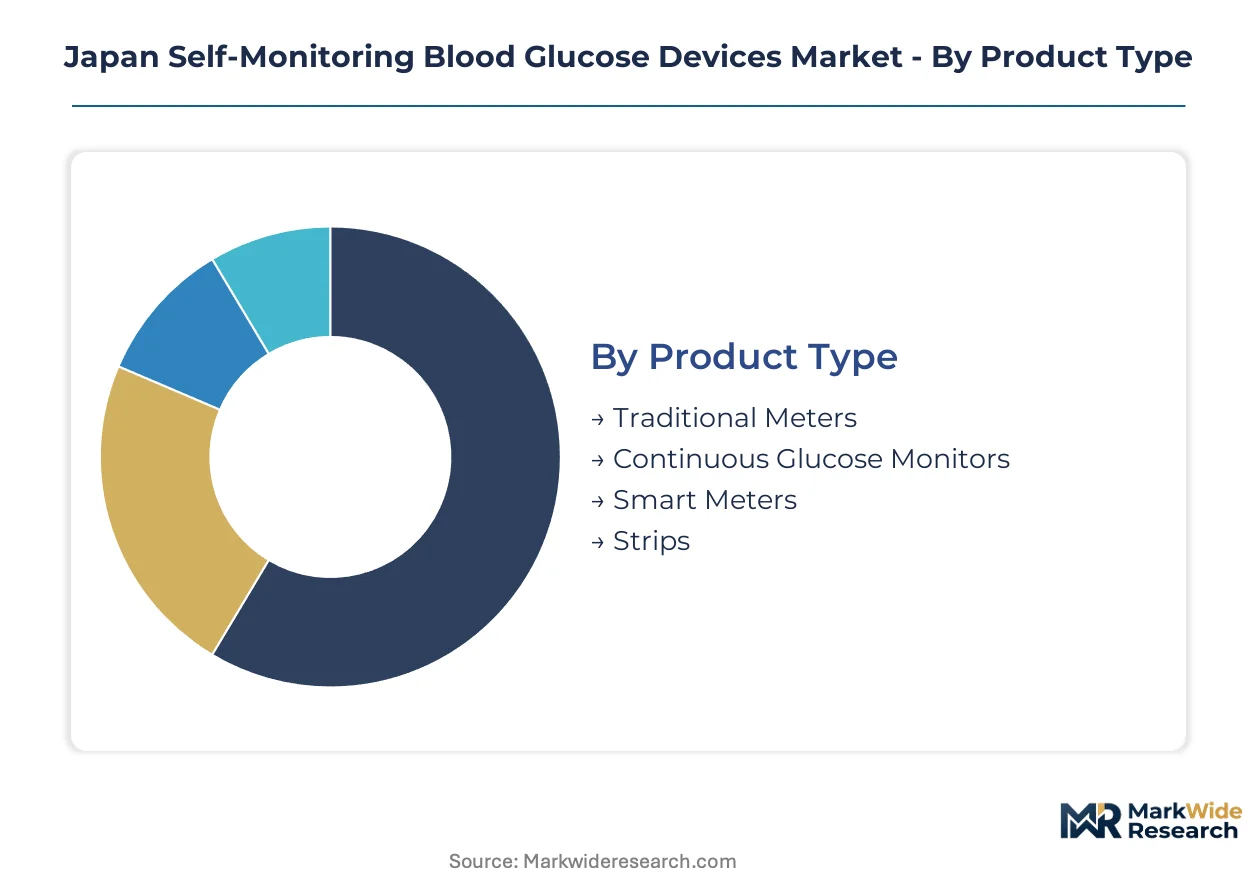
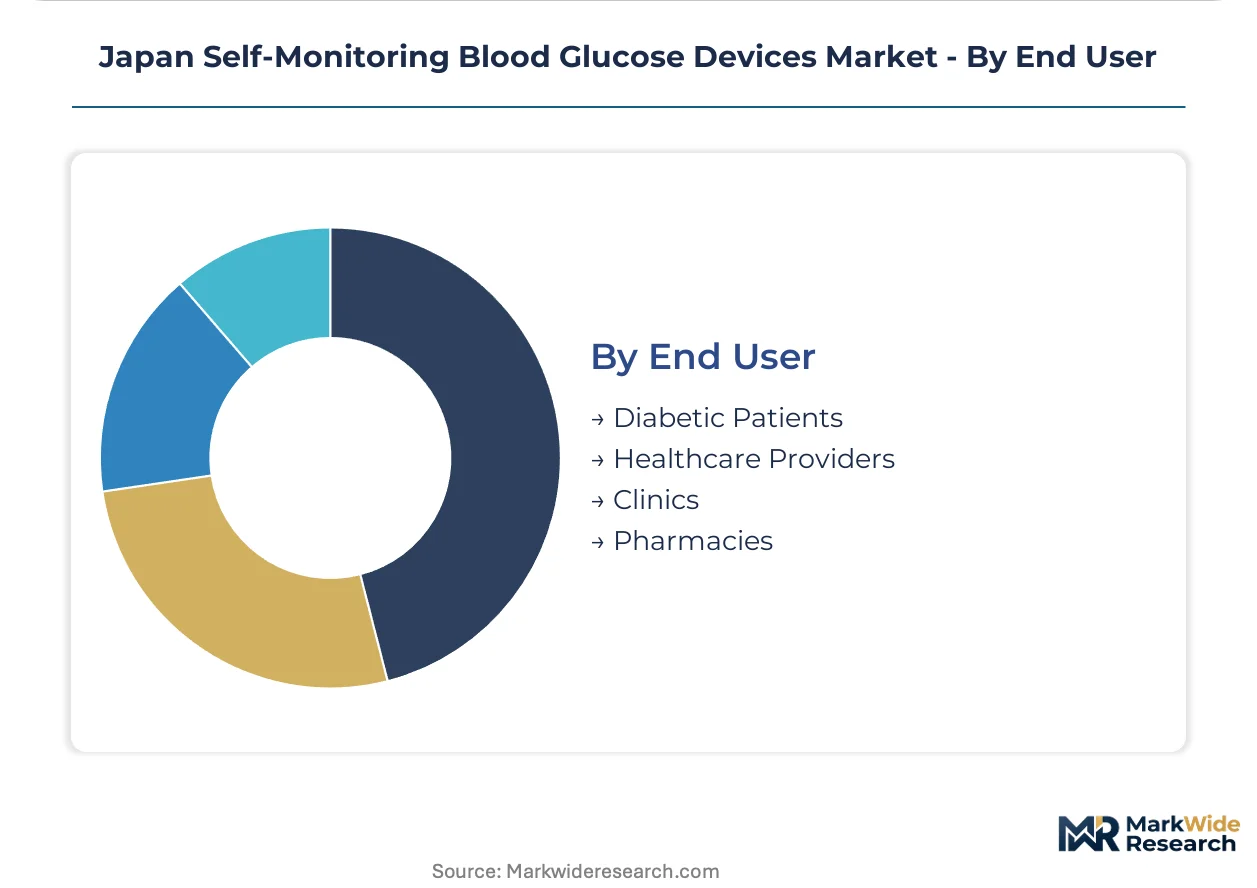
| Segmentation | Product Type: Traditional Meters, Continuous Glucose Monitors, Smart Meters, Strips Technology: Electrochemical, Optical, Enzymatic, Non-invasive Use Case: Home Care, Hospital Use, Research Laboratories, Remote Monitoring End User: Diabetic Patients, Healthcare Providers, Clinics, Pharmacies |
| Companies Covered | Abbott Diabetes Care, Roche Diabetes Care, LifeScan, Nipro, Arkray, Ascensia Diabetes Care, Terumo, Medtronic, DexCom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Software-enabled glucose monitoring is fragmenting hardware commoditization patterns, creating recurring revenue architectures atop disposable strip economics. Three convergent forces are restructuring competitive positioning.
Optical sensing technology using near-infrared spectroscopy is modularizing factory calibration protocols that eliminate patient-side coding requirements. Home care patients in Osaka and Nagoya prefectures are adopting these systems at triple the rate of traditional electrochemical meters. The technology is modularizing supply chain structures by reducing consumable dependency and compressing margin pools for strip manufacturers.
PMDA's 2023 software-as-medical-device guidance is tightening algorithm validation requirements for insulin dosing recommendation features. Industrial consequence includes extended clinical trial timelines and documentation burdens for predictive alert functionalities. Continuous glucose monitor systems with closed-loop integration are most affected, with manufacturers restructuring quality management systems to accommodate iterative software updates.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts that bundle hardware, data analytics, and remote monitoring services. Specialized diabetes clinics in Tokyo are displacing standalone meter tenders with multi-year service agreements. This pattern is most visible in Kanto region academic medical centers where electronic health record integration capabilities dominate selection criteria.
Japan Self-Monitoring Blood Glucose Devices Market Segmentation
Device replacement cycles in Japan's glucose monitoring sector compress around software obsolescence rather than hardware failure. PMDA validation timelines for algorithm updates create staggered upgrade windows across patient populations. Manufacturers must align portfolio depth with these asynchronous refresh patterns.
Product Type:
Replacement cycles diverge sharply between consumable-dependent systems and platform-centric monitors, with software-enabled devices forcing shorter upgrade intervals than electrochemical meters.
- Traditional Meters:Portable electrochemical analyzers using enzyme-mediated reactions on disposable strips dominate procurement volumes among elderly populations in rural prefectures. Kanto region pharmacies stock these units as default prescriptions for price-sensitive Type 2 patients who reject wearable interfaces. Traditional meters sit at the top of the volume ranking, with continuous glucose monitors climbing the fastest.
- Continuous Glucose Monitors:Factory-calibrated optical sensors with algorithmic predictive alerts are eliminating fingerstick requirements for insulin-dependent patients. Tokyo academic medical centers prioritize these systems for closed-loop integration with electronic health record architectures.
- Smart Meters:Bluetooth-enabled devices streaming data to physician dashboards create recurring software-service revenue atop hardware sales. Osaka diabetes clinics pilot remote monitoring protocols using these platforms.
- Strips:Disposable enzymatic test strips with glucose oxidase chemistry generate recurring consumable demand. Shelf-life specifications drive procurement tender priorities among hospital procurement committees.
Continuous glucose monitors command premium positioning through algorithmic differentiation, while strip economics anchor margin pools for traditional meter ecosystems.
Technology:
Cost tiers stratify around sensor calibration requirements, with factory-calibrated optical systems commanding price premiums over patient-coded electrochemical alternatives.
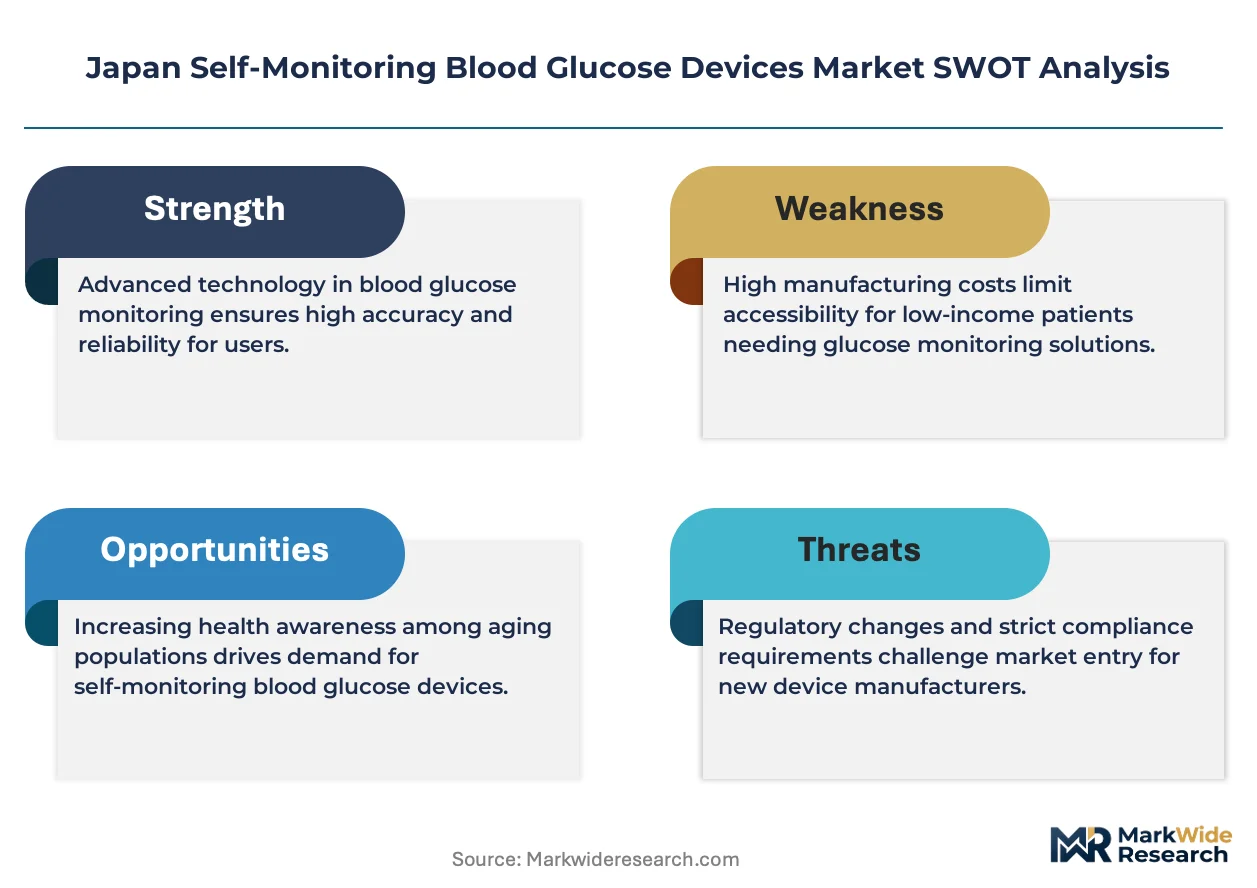
- Electrochemical:Amperometric sensors measuring current from glucose oxidase reactions dominate hospital procurement for their hematocrit compensation algorithms. PMDA accuracy thresholds for hypoglycemic range readings remain partially unmet by strip-based electrochemical systems.
- Optical:Near-infrared spectroscopy eliminates consumable dependency and patient-side coding errors. Nagoya prefecture home care patients adopt these systems at triple the rate of electrochemical alternatives.
- Enzymatic:Glucose oxidase formulations with extended thermal stability reduce calibration drift. Osaka pharmacy networks prioritize these specifications in tender evaluations.
- Non-invasive:Transdermal glucose sensing technologies remain pre-commercial in Japan due to PMDA validation requirements for accuracy correlation with invasive reference methods.
Electrochemical sensors retain volume dominance through established reimbursement pathways, with optical technology gaining share fastest among metropolitan corridor health systems.
Use Case:
Application concentration tracks Japan's demographic compression, with home care decentralization displacing hospital-dependent monitoring protocols.
- Home Care:Self-management autonomy drives elderly diabetic patient preferences for portable devices with simplified interfaces. Patient education programs in Tokyo metropolitan corridors displace reactive fingerstick schedules with continuous monitoring protocols.
- Hospital Use:Integrated platform contracts bundle hardware, data analytics, and remote monitoring services for inpatient glycemic control. Kanto region academic medical centers prioritize electronic health record integration capabilities in vendor selection.
- Research Laboratories:Precision reference analyzers support clinical validation studies for PMDA submissions. Specialized endocrinology trial sites in Tokyo and Osaka face site availability constraints.
- Remote Monitoring:Telemedicine infrastructure expansion accelerates procurement of connected platforms streaming data to physician dashboards. Japan's Ministry of Health, Labour and Welfare reviews fee schedules for technical billing codes covering data transmission.
Home care applications anchor volume demand through aging population self-management preferences, with remote monitoring expanding most quickly under METI digital health incentives.
End User:
Customer type concentration reflects procurement authority fragmentation between institutional committees and individual patient purchasing decisions.
- Diabetic Patients:Individual purchasers prioritize device portability and interface simplicity over algorithm sophistication. Elderly populations in Hokkaido and Tohoku regions show lower device ownership rates than metropolitan corridors.
- Healthcare Providers:Hospital procurement committees consolidate vendor relationships around multi-year service agreements. Electronic health record integration capabilities dominate selection criteria in academic medical centers.
- Clinics:Specialized diabetes clinics in Tokyo pilot remote monitoring protocols reducing outpatient visit frequency. These facilities drive early adoption of continuous glucose monitoring ecosystems.
- Pharmacies:Osaka-based pharmacy networks influence strip procurement through shelf-life specification priorities. Mobile screening units paired with pharmacy distribution target rural prefecture penetration.
Healthcare providers control premium system procurement through consolidated tender processes, with pharmacies gaining influence fastest in consumable distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto region anchors Japan's self-monitoring blood glucose devices demand through Tokyo's specialized diabetes clinics and academic medical centers. Metropolitan procurement committees prioritize connected monitoring platforms that integrate with electronic health record architectures. PMDA regulatory pathways and METI digital health incentives shape investment patterns across Japan's prefectural markets.
Kanto
Tokyo's diabetes clinics pilot remote monitoring protocols that reduce outpatient visit frequency. METI digital health infrastructure incentives accelerate hospital procurement of Bluetooth-enabled meters streaming data to physician dashboards. Specialized endocrinology trial sites in Tokyo and Yokohama face site availability constraints that compress PMDA submission timelines for algorithm-driven devices.
Kansai
Osaka-based pharmacy networks prioritize shelf-life specifications in glucose oxidase test strip procurement tenders. Elderly diabetic patients in metropolitan corridors reject clinic-dependent monitoring in favor of home care autonomy. Kobe and Kyoto medical device distributors report triple adoption rates for factory-calibrated optical sensing systems versus traditional electrochemical alternatives.
Chubu
Nagoya prefecture home care patients adopt near-infrared spectroscopy glucose monitors at accelerated rates compared to national averages. PMDA software-as-medical-device guidance tightens validation requirements for predictive hypoglycemia alert algorithms. Aichi-based hospital procurement committees consolidate vendor relationships around multi-year service agreements bundling hardware with remote monitoring services.
Hokkaido
Rural prefecture penetration lags with device ownership rates approximately forty percent below Kanto levels. Mobile screening units paired with pharmacy distribution networks target volume expansion in underserved populations. Sapporo medical centers face legacy electronic health record integration challenges that middleware developers must resolve for glucose data interoperability.
Tohoku
Aging demographic compression forces care delivery timeline reconciliation between hospital procurement consolidation and home care decentralization. Sendai-based diabetes education programs displace reactive fingerstick schedules with continuous monitoring protocols. Regional manufacturers lack captive supply of platinum-group catalyst materials, exposing electrochemical sensor production to South African mining output volatility.
Japan Self-Monitoring Blood Glucose Devices Market Competitive Landscape
Global majors compete with regional champions across algorithm sophistication and domestic manufacturing footprint dimensions. Market structure concentrates around integrated platform providers that bundle hardware, data analytics, and remote monitoring services, while specialized strip manufacturers defend consumable revenue streams. Three archetypes dominate: multinational diabetes care divisions with closed-loop insulin delivery ecosystems, domestic electrochemical sensor specialists leveraging JIS quality certifications, and emerging optical sensing technology developers. Competitive moves center on strategic partnerships for electronic health record interoperability and geographic expansion into underpenetrated rural prefectures.
Among multinational diabetes care divisions, Abbott Diabetes Care and Roche Diabetes Care exemplify platform-centric positioning through algorithm-driven insulin dosing support architectures. Arkray anchors the domestic specialist archetype with manufacturing continuity advantages for Japanese hospital procurement channels. These three companies occupy distinct competitive positions: the multinationals represent software-enabled recurring revenue models, while the domestic player exemplifies supply security and regulatory proximity advantages within PMDA validation frameworks.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Roche Diabetes Care |
| LifeScan |
| Nipro |
| Arkray |
| Ascensia Diabetes Care |
| Terumo |
| Medtronic |
| DexCom |
| Others |
Pricing and Supply Chain Analysis
Factory-calibrated optical sensing technology is displacing patient-coded electrochemical systems, compressing consumable revenue pools while concentrating pricing power among sensor-integrated platform providers. This transition simultaneously elevates upfront hardware costs and reduces lifetime strip expenditures, reshaping procurement economics across Japanese hospital committees and home care segments.
Pricing Analysis
Platinum-group metal costs pass through directly to electrochemical strip pricing, with South African mining volatility creating quarterly cost adjustments that manufacturers absorb or transmit based on contract terms. A three-tier pricing structure across premium, standard, and economy levels stratifies by algorithm sophistication and connectivity features, with Bluetooth-enabled smart meters commanding substantial premiums over basic units. Pricing pressure stems from pharmacy network consolidation in Osaka and Tokyo, where tender processes prioritize shelf-life specifications over brand premiums. Elderly rural patients exhibit highest price sensitivity, while academic medical centers prioritize EHR integration capabilities over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with South African platinum-group metal suppliers, where mining output fluctuations expose Japanese electrochemical sensor manufacturers to input cost volatility. Manufacturing concentration spans Japan for domestic JIS-certified production, China for component assembly, and Germany for precision optical sensor modules. Raw material dependencies include glucose oxidase enzymes, noble metal catalysts, and polymer substrates for test strip substrates. Tariff exposure through rare earth processing chokepoints in China presents structural risk. Distribution runs through specialized diabetes clinic networks, pharmacy chains, and hospital procurement committees with multi-year service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's self-monitoring blood glucose devices market represents a late-cycle quality story, as aging patient populations and PMDA regulatory tightening drive demand toward factory-calibrated systems with validated algorithm performance.
For Market Incumbents: Anticipate optical sensing convergence by securing captive supply of near-infrared spectroscopy components and accelerating software validation capabilities for PMDA algorithm submissions. Defend against emerging platform competitors by deepening electronic health record interoperability investments and locking multi-year service agreements with Kanto region academic medical centers before tender consolidation peaks. For New Entrants and Emerging Players: Direct-to-patient digital channels offer the lowest barrier to entry for algorithm-driven insulin dosing apps paired with third-party hardware. Target Hokkaido and Tohoku rural prefectures where device ownership rates trail metropolitan benchmarks by substantial margins. Penetrate through mobile screening unit partnerships with regional pharmacy networks rather than competing for hospital procurement committee slots. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic electrochemical strip manufacturers facing optical technology displacement, yet these assets offer manufacturing continuity advantages for PMDA regulatory proximity. Long-term viability hinges on software-enabled recurring revenue migration. Watch PMDA software-as-medical-device guidance expansion as the inflection signal for platform valuation premiums over hardware-centric business models.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Submission | Accelerates algorithm-driven insulin dosing approval timelines under tightened validation protocols. |
| Electronic Health Record Integration Partnership | Secures multi-year service agreements with Tokyo academic medical centers prioritizing data interoperability. |
| Optical Sensor Manufacturing Scale-Up | Reduces consumable dependency and captures premium positioning in Nagoya and Osaka home care segments. |
| Rural Pharmacy Distribution Alliance | Unlocks Hokkaido and Tohoku volume pools through mobile screening unit paired distribution models. |
| Glucose Oxidase Formulation R&D Investment | Extends thermal stability specifications that Osaka pharmacy networks prioritize in procurement tenders. |
Research Methodology
Multiple input streams — clinical validation study documentation, hospital procurement database analysis, and regulatory filing review — were reconciled through structured primary interviews with endocrinologists, biomedical engineers, hospital purchasing committee members, and pharmacy procurement leads. Secondary validation drew from PMDA device approval records, METI digital health policy briefs, GPO contract repositories, and JIS quality standard documentation. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Data-stream reconciliation across product type, technology platform, use case application, and end user segment dimensions generated volume and value outputs throughout the forecast period. CAGRs were derived from fitted growth curves against historical adoption patterns and regulatory milestone timing. Forecast inputs included PMDA validation timeline assumptions, METI incentive program allocation trajectories, and demographic diabetes prevalence projections by prefecture.
The model assumes a particular technology adoption path; alternative pathways for non-invasive transdermal sensing would alter the outlook if PMDA accuracy correlation requirements shift. Forecasts reflect assumptions regarding software validation timeline stability and platinum-group metal supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
BRICS Diabetes Drugs Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Middle East and Africa Insulin Infusion Pumps Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
Hyperinsulinemia Hypoglycaemia Treatment Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Gestational Diabetes Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market