
 Italy Self-Monitoring Blood Glucose Devices Market | 2026-2036
Italy Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Self-Monitoring Blood Glucose Devices Market Insights
Italy's domestic medical device manufacturing corridor is rewriting procurement dynamics for glucose monitoring systems. Abbott Laboratories leverages its FreeStyle platform to anchor hospital-to-home transitions across Lombardy and Veneto. Roche Diabetes Care sustains brand loyalty through dense pharmacy distribution, while Menarini Diagnostics competes via localized production and Italian regulatory familiarity.
Self-monitoring blood glucose devices comprise portable electrochemical and optical systems that measure capillary glucose concentration through enzyme-mediated reactions on disposable test strips, enabling real-time metabolic management outside clinical settings. Continuous glucose monitors are displacing traditional meter-strip combinations among Type 1 diabetics, where electrochemical enzymatic technology dominates due to precision at low sample volumes. Pharmacy channels still occupy the largest transaction share, though online retail is accelerating fastest among younger home users seeking subscription-based strip replenishment.
Italy's Ministry of Health and the Italian Medicines Agency (AIFA) govern reimbursement eligibility and pricing ceilings for glucose monitoring devices through the National Diabetes Plan and Essential Levels of Care framework. AIFA's periodic reassessment of which devices qualify for public reimbursement directly shapes manufacturer market access and patient out-of-pocket exposure. Stakeholders must monitor whether Rome tightens local production requirements or expands remote patient monitoring reimbursement to reshape competitive positioning.
Market Dynamics
Continuous glucose monitoring systems are compressing the addressable base for traditional meter-strip combinations across Italian diabetes centers and home care settings, forcing electrochemical test strip manufacturers to defend pharmacy shelf space through bundled pricing and digital connectivity upgrades.
Growth Catalysts
- National Diabetes Plan Reimbursement Expansion:Italy's Essential Levels of Care framework now covers broader patient categories for self-monitoring supplies, reducing out-of-pocket costs and expanding the eligible population across Lombardy and Veneto regions.
- Home-Based Patient Monitoring:The shift toward decentralized diabetes management is accelerating device penetration among Type 2 patients in northern industrial clusters where pharmacy networks achieve highest coverage density.
- Enzymatic Electrochemical Precision:Advanced glucose oxidase and dehydrogenase sensor chemistries are improving accuracy at low sample volumes, sustaining clinical confidence in capillary testing among specialist diabetes centers.
Market Restraints
- Test Strip Input Cost Volatility:Fluctuations in noble metal catalyst prices and polymer substrate materials are compressing margins for disposable component manufacturers serving the Italian market.
- Continuous Monitor Substitution:Real-time CGM systems with factory-calibrated sensors are eliminating fingerstick requirements for insulin-intensive patients, structurally limiting traditional meter growth in Type 1 segments.
- AIFA Reimbursement Reassessment Cycles:Periodic device delisting under Italy's pricing ceiling protocols creates sudden revenue discontinuities for manufacturers dependent on public procurement channels.
Strategic Opportunities
- Southern Italy Underpenetration:Calabria, Sicily, and Puglia exhibit significantly lower device density per diabetic capita, presenting expansion targets for pharmacy distribution networks and telemedicine-integrated monitoring programs.
- Subscription-Based Strip Replenishment:Direct-to-patient digital platforms are capturing younger home users seeking automated supply continuity, bypassing traditional pharmacy transaction friction.
- Remote Patient Monitoring Integration:Italy's Ministry of Health is piloting reimbursement for cloud-connected glucose data transmission, enabling new service revenue models linking device sales to chronic care management fees.
Industry Challenges
- MDR Certification Timeline Compression:Italy's notified body capacity constraints are extending CE marking approval cycles for next-generation connected meters, delaying product launches against faster-certified competitors.
- Legacy Health IT Integration Complexity:Hospital information systems in Turin and Milan diabetes centers require proprietary data formats, forcing manufacturers to maintain multiple software interfaces and fragmenting R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Self-Monitoring Blood Glucose Devices Market |
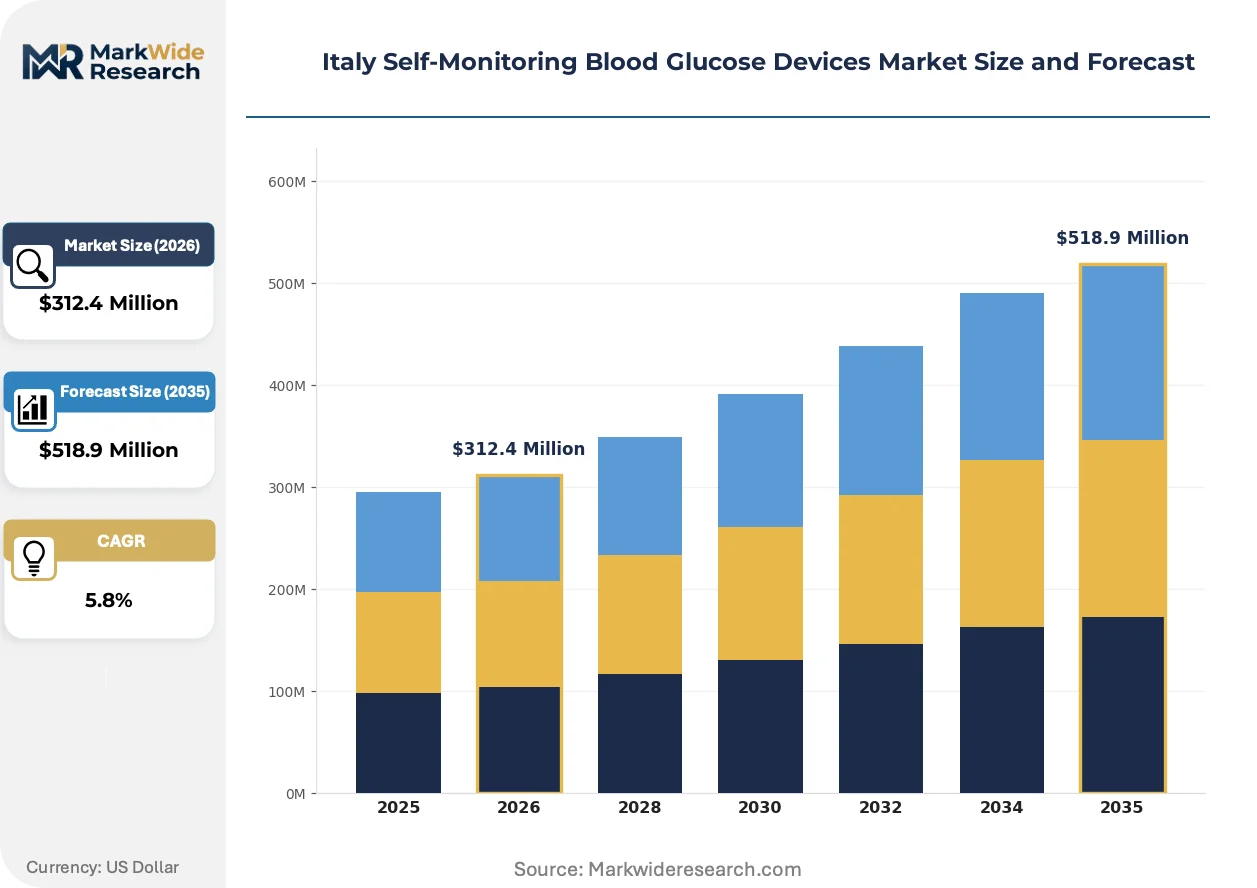
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Continuous Glucose Monitors, Test Strips, Lancing Devices Technology: Electrochemical, Optical, Thermal, Enzymatic End User: Diabetics, Healthcare Professionals, Laboratories, Home Users Distribution Channel: Pharmacies, Online Retail, Hospitals, Clinics |
| Companies Covered | Roche Diabetes Care, Abbott Laboratories, LifeScan, Ascensia Diabetes Care, Medtronic, Dexcom, ARKRAY, B. Braun Melsungen AG, Menarini Diagnostics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Sensor miniaturization and cloud connectivity are redefining how Italian patients interact with metabolic data, compressing the gap between clinical-grade accuracy and consumer convenience while regulatory frameworks scramble to accommodate software-as-medical-device classifications.
Optical non-invasive glucose sensing is collapsing the invasive sampling paradigm that has dominated self-monitoring for decades. Research consortia in Milan are piloting near-infrared spectroscopy and interstitial fluid extraction methods for Type 2 patients seeking pain-free alternatives. This technology is collapsing the compliance barrier that has limited testing frequency among needle-averse demographics, though enzymatic electrochemical systems retain clinical authority for insulin dosing decisions.
Italy's implementation of the EU Medical Device Regulation is tightening post-market surveillance requirements for glucose monitoring systems. AIFA now mandates enhanced clinical evidence for software updates and algorithm modifications, extending validation timelines for AI-enabled pattern recognition features. Manufacturers serving the Italian market are responding by segregating hardware and software approval pathways, delaying integrated launches to manage regulatory risk.
Younger diabetic patients in northern urban centers are abandoning pharmacy-centric replenishment for direct manufacturer subscriptions. Digital-native users prioritize mobile app integration and automated supply forecasting over pharmacist consultation, fragmenting the traditional channel monopoly. This behavioral pivot is most pronounced in Milan and Turin, where same-day delivery logistics and telehealth prescribing laws enable seamless bypass of retail intermediaries.
Italy Self-Monitoring Blood Glucose Devices Market Segmentation
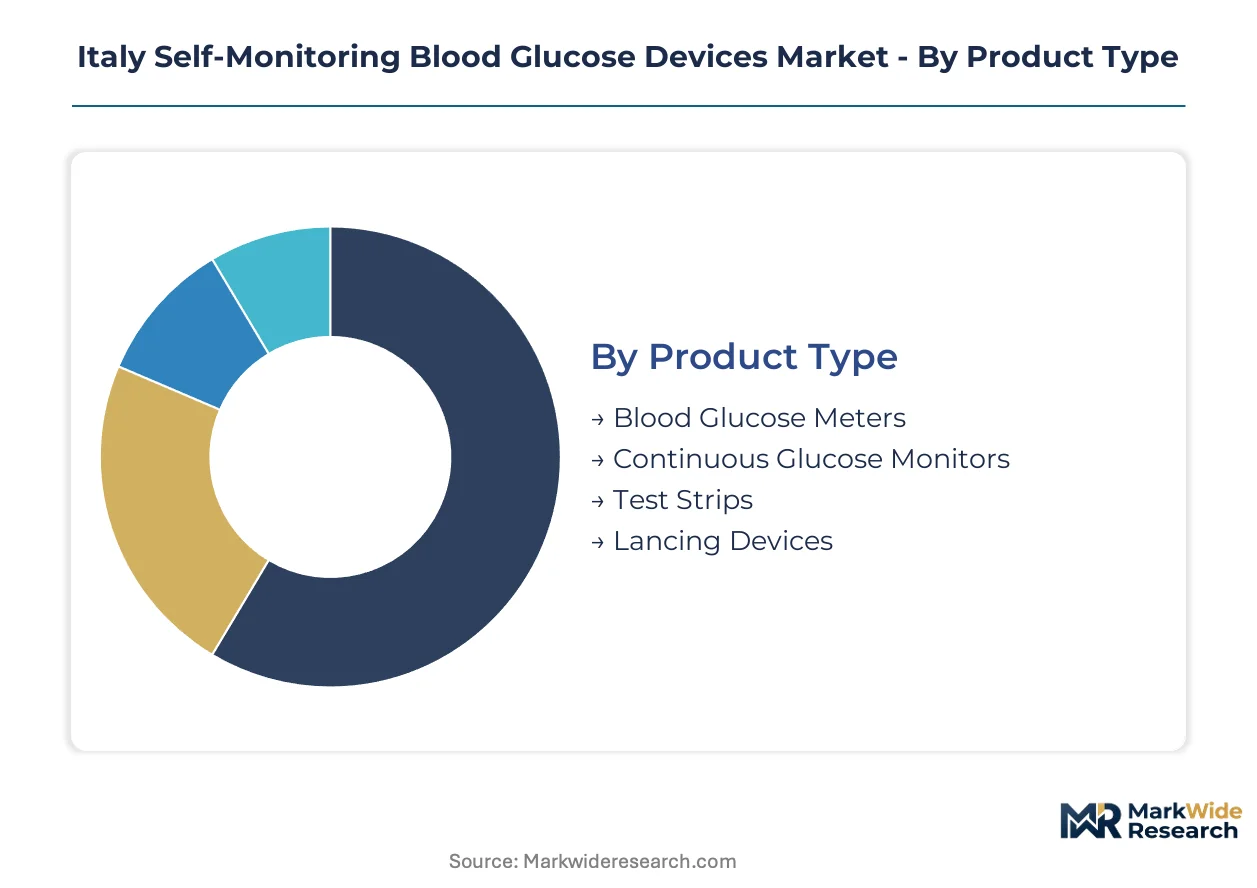
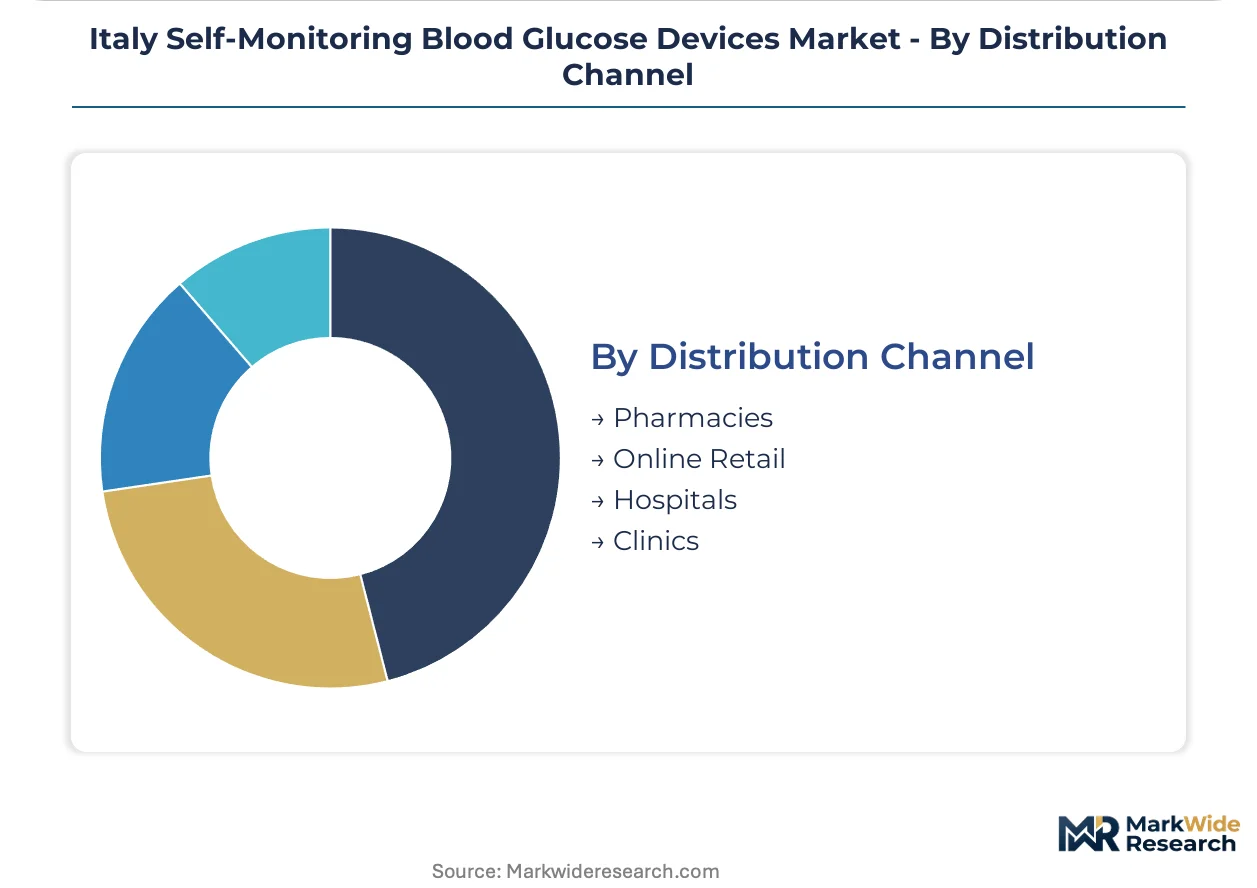
Italian glucose monitoring procurement splits across four distinct category axes, each reflecting divergent reimbursement pathways, technical maturity levels, and patient self-management capabilities. Understanding these segment boundaries clarifies where AIFA pricing ceilings bite hardest and where subscription-based models bypass traditional pharmacy capture.
Product Type:
Device selection spans the full use-case spectrum from discrete capillary testing to real-time metabolic surveillance.
- Blood Glucose Meters:Portable electrochemical analyzers paired with disposable enzyme strips dominate pharmacy transactions across Lombardy and Veneto. AIFA reimbursement ceilings compress margin flexibility for manufacturers defending shelf space against CGM substitution.
- Continuous Glucose Monitors:Factory-calibrated interstitial sensors with wireless transmitters eliminate fingerstick requirements for insulin-intensive Type 1 patients. Northern diabetes centers in Milan and Turin drive adoption where specialist prescribing density supports prior authorization workflows.
- Test Strips:Single-use glucose oxidase reagents on polymer substrates constitute the highest-volume consumable segment. Noble metal catalyst cost volatility squeezes disposable component suppliers serving public procurement channels.
- Lancing Devices:Spring-loaded penetration tools for capillary blood extraction. Spring mechanism precision and pain reduction features differentiate premium units from economy alternatives in retail pharmacy.
Established volume favors test strips; emerging adoption favors continuous glucose monitors.
Technology:
Detection chemistry selection maps directly to accuracy requirements, cost constraints, and regulatory validation burden.
- Electrochemical:Amperometric glucose oxidase and dehydrogenase sensors deliver clinical-grade precision at microliter sample volumes. This enzymatic approach anchors hospital-to-home transitions across Italian specialist centers where dosing decisions demand documented accuracy.
- Optical:Near-infrared spectroscopy and colorimetric reflectance methods enable non-invasive or minimally invasive measurement paradigms. Milan research consortia pilot interstitial fluid extraction for needle-averse Type 2 demographics seeking pain-free alternatives.
- Thermal:Heat-based glucose detection through skin permeability modulation. Thermal methods remain experimental within Italian clinical validation frameworks, lacking AIFA reimbursement eligibility for commercial deployment.
- Enzymatic:Bio-catalytic reaction systems leveraging glucose oxidase or hexokinase pathways. Enzymatic specificity sustains physician confidence in capillary testing for insulin titration decisions despite CGM expansion.
Regulatory clearance concentrates on electrochemical platforms; optical innovation attracts R&D investment.
End User:
Patient type and care setting determine device complexity, connectivity requirements, and reimbursement tier.
- Diabetics:Individual patients managing metabolic status through self-directed testing or automated monitoring. Home-based Type 2 patients in northern industrial clusters exhibit highest device penetration where pharmacy network density supports supply continuity.
- Healthcare Professionals:General practitioners and diabetes specialists prescribing and interpreting glucose data. Professional calibration verification and software integration requirements shape procurement specifications for clinical practice settings.
- Laboratories:Centralized diagnostic facilities processing venous samples for HbA1c correlation. Laboratory-grade accuracy demands and high-throughput workflows favor benchtop analyzers over portable meters.
- Home Users:Family caregivers and non-diabetic individuals conducting preventive screening. Younger digital-native users in Turin and Milan bypass pharmacies for direct manufacturer subscription platforms with automated replenishment.
Reimbursement eligibility favors diagnosed diabetics; out-of-pocket spending concentrates among preventive home users.
Distribution Channel:
Supply pathway selection reflects patient age, digital literacy, and urgency of need.
- Pharmacies:Brick-and-mortar retail networks with pharmacist consultation and same-day availability. Dense pharmacy coverage across Lombardy and Veneto sustains transaction share despite digital disruption.
- Online Retail:E-commerce platforms and manufacturer-direct subscription services. Online channels gain fastest among younger patients in urban centers where telehealth prescribing laws enable seamless bypass of retail intermediaries.
- Hospitals:Inpatient and outpatient diabetes centers with integrated electronic health records. Hospital procurement requires proprietary data format compatibility, fragmenting manufacturer R&D resources across Turin and Milan health IT systems.
- Clinics:Specialist diabetes centers and primary care facilities with structured monitoring protocols. Clinic-based distribution concentrates in northern regions where specialist density supports reimbursement authorization workflows.
Transaction volume concentrates in pharmacies; growth velocity favors online retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AIFA governs reimbursement eligibility across Italy's fragmented regional healthcare systems, creating divergent device penetration patterns between northern industrial clusters and southern underpenetrated zones. The National Diabetes Plan allocates monitoring supplies through regional health authorities, producing stark adoption gradients that manufacturers must navigate.
Lombardy
Milan anchors the highest device density per diabetic capita, driven by dense pharmacy networks and specialist diabetes center concentration. The region's Essential Levels of Care implementation covers broader self-monitoring categories than national baselines, reducing patient out-of-pocket exposure. Abbott Laboratories leverages its FreeStyle platform across hospital-to-home transitions in this cluster.
Veneto
Verona and Padua diabetes centers drive CGM adoption among Type 1 insulin-intensive patients through streamlined prior authorization workflows. Regional health authority procurement favors connected meters with proprietary EHR integration, fragmenting manufacturer R&D resources across multiple software interfaces. Pharmacy network density sustains test strip transaction volume despite digital disruption.
Piedmont
Turin's integrated health IT systems require specific data format compatibility for glucose monitoring device procurement, creating technical barriers for new market entrants. The region's industrial base supports localized production advantages for domestic manufacturers. Menarini Diagnostics competes through regulatory familiarity and shortened supply chains to Turin diabetes centers.
Calabria
Southern underpenetration manifests in significantly lower meter ownership rates among diagnosed Type 2 patients, presenting expansion targets for pharmacy distribution networks. Sparse specialist density limits CGM authorization workflows, preserving traditional capillary testing dominance. Telemedicine-integrated monitoring programs pilot here to bypass infrastructure gaps.
Sicily
Palermo and Catania exhibit the widest gap between diagnosed diabetic population and active self-monitoring device users among Italian regions. AIFA reimbursement ceilings bite hardest where pharmacy network coverage is thinnest, forcing cash purchases for preventive home users. Subscription-based direct-to-patient platforms target younger demographics seeking automated supply continuity.
Italy Self-Monitoring Blood Glucose Devices Market Competitive Landscape
Capability concentration sits with multinational diagnostics conglomerates; scale advantage sits with diversified medical technology holding companies. The vendor base organizes around three strategic archetypes: electrochemical sensor specialists defending pharmacy shelf space, CGM platform builders capturing insulin-intensive segments, and regional producers leveraging domestic regulatory familiarity. Competitive moves center on bundled pricing for meter-strip combinations and digital connectivity upgrades that bridge hospital-to-home care transitions.
Among the multinational tier, Roche Diabetes Care, Abbott Laboratories, and Medtronic occupy positions defined by their core technology platforms rather than geographic origin. Roche exemplifies the pharmacy-centric archetype through dense distribution network relationships. Abbott represents the hospital-to-home transition specialist, while Medtronic anchors the interventional diabetes technology vector. Menarini Diagnostics sits within the domestic producer tier, competing on AIFA regulatory process familiarity and shortened logistics chains to Italian health authorities.
| Leading Market Players |
|---|
| Roche Diabetes Care |
| Abbott Laboratories |
| LifeScan |
| Ascensia Diabetes Care |
| Medtronic |
| Dexcom |
| ARKRAY |
| B. Braun Melsungen AG |
| Menarini Diagnostics |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Asian test strip manufacturing is compressing margin structures for Italian market suppliers, forcing manufacturers to absorb noble metal catalyst volatility while AIFA reimbursement ceilings cap pass-through pricing power.
Pricing Analysis
Geographic price spreads between northern Lombardy pharmacies and southern Calabria retail channels exceed thirty percent for identical meter-strip bundles. Pricing stratifies across premium connected meters, standard electrochemical systems, and economy disposable units based on AIFA reimbursement tier eligibility and software integration depth. Cost compression in economy tiers is intensifying because polymer substrate suppliers face noble metal price volatility. Cash-paying preventive home users in Sicily exhibit highest price sensitivity; insulin-intensive Type 1 patients in Veneto specialist centers show lowest sensitivity due to full reimbursement coverage.
Supply Chain Analysis
Contract manufacturing concentration sits with German and Swiss precision electronics specialists holding electrochemical sensor fabrication capacity, while Chinese polymer substrate producers dominate disposable component supply. Raw material dependencies draw from Malaysian rubber for lancet springs, South Korean display modules for connected meters, and Belgian enzyme reagents for test strip chemistry. Single-source vulnerability in glucose oxidase supply creates structural risk for Italian strip manufacturers. Distribution runs through regional pharmacy wholesalers in Lombardy and Veneto, with direct-to-patient subscription platforms bypassing traditional intermediaries in Milan and Turin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous glucose monitoring reimbursement expansion under Italy's National Diabetes Plan is accelerating technology substitution, compressing the addressable window for traditional meter-strip manufacturers to execute defensive pivots.
For Market Incumbents: Pre-empt CGM substitution by bundling legacy meters with cloud connectivity upgrades and automated strip replenishment subscriptions. Defend pharmacy shelf space in Lombardy through exclusive distribution agreements with regional wholesaler networks. Invest in MDR certification acceleration to outpace notified body bottlenecks delaying competitor launches.
For New Entrants and Emerging Players: Southern Italian regions Calabria and Sicily represent the most penetrable entry point, where specialist diabetes center scarcity preserves traditional capillary testing dominance and pharmacy network undercoverage creates direct-to-patient subscription opportunities. Target younger digital-native home users in Palermo and Catania through telehealth-integrated platforms with same-day delivery logistics. Deploy reimbursement navigation services to bridge AIFA eligibility complexity for cash-paying patients.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across disposable test strip manufacturing as automated production lines reduce labor content per unit. Long-term viability favors platform builders with software-as-medical-device revenue streams over pure hardware manufacturers. Target acquisition candidates with established AIFA regulatory relationships and southern Italy distribution infrastructure. Watch for AIFA reimbursement reassessment cycles as inflection indicators for revenue discontinuity risk.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR certification delays compress competitive windows; early clearance secures hospital procurement access in Milan and Turin. |
| Hospital System Partnership | Integrated EHR compatibility requirements in Piedmont favor vendors with proprietary data format development resources. |
| Software Companion Development | Cloud-connected glucose data transmission pilots by Italy's Ministry of Health enable chronic care management fee attachment. |
| Reimbursement Strategy | AIFA pricing ceiling navigation determines patient out-of-pocket exposure and manufacturer margin preservation. |
| Geographic Expansion | Southern underpenetration in Calabria and Sicily offers volume growth offsetting northern CGM substitution pressure. |
Research Methodology
The analysis maps electrochemical meter systems, continuous glucose monitors, test strip consumables, and lancing devices, each validated through procurement managers at Italian hospital systems, pharmacy network directors, diabetes specialist clinicians, and biomedical engineers at notified bodies. Primary interviews with industry stakeholders combined with secondary validation against AIFA reimbursement databases, Essential Levels of Care framework documentation, EU MDR regulatory filings, and regional health authority procurement records. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume estimates.
Assumption-sets held AIFA reimbursement tier stability and noble metal catalyst price bands fixed while varying CGM adoption velocity and southern Italy pharmacy network expansion rates across sensitivity scenarios. Segmentation dimensions modeled include product type, detection technology, end user category, and distribution channel. CAGRs derived from fitted growth curves applied to diagnosed diabetic population projections and device penetration rate assumptions. Forecast inputs incorporated National Diabetes Plan implementation timelines and regional health authority budget allocation patterns.
Macroeconomic conditions sit as an overlay; deviation in euro exchange rates, Italian public health expenditure growth, or EU medical device regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions without guarantee of realization. Cross-checking against hospital procurement database benchmarks and pharmacy transaction audit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
North America Insulin Infusion Pumps Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Pet Diabetes Care Devices Market