
 Sensor Based Glucose Measuring Systems Market | 2026-2036
Sensor Based Glucose Measuring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Based Glucose Measuring Systems Market Analytics
Product bundling is shifting how hospitals and health systems purchase glucose monitoring infrastructure, with buyers increasingly favoring subscription-style packages that combine hardware, sensors, and analytics software. Abbott Laboratories leverages its vertically integrated manufacturing footprint to anchor pricing power across integrated delivery networks. Dexcom differentiates through algorithm-intensive platforms that extend patient time-in-range metrics. Medtronic dominates pump-sensor hybrid systems, competing on closed-loop automation credibility.
Sensor based glucose measuring systems comprise electrochemical, optical, enzymatic, and microfluidic technologies that transduce glucose concentration into quantifiable electrical or optical signals, typically operating through minimally invasive interstitial fluid sampling or non-invasive spectral methods for real-time metabolic monitoring. Continuous glucose monitors lead the product type landscape, with wearable devices representing the fastest-expanding configuration as miniaturization and battery efficiency improve. Electrochemical technology sustains the largest installed base, though optical platforms are gaining traction in non-invasive research applications where patient compliance priorities reshape hardware specifications.
FDA premarket clearance pathways and CMS national coverage determinations shape United States market access timelines and reimbursement eligibility for new sensor entrants. The EU MDR and GDPR compliance requirements impose clinical evidence and data governance burdens on manufacturers distributing across European member states. Stakeholders must monitor evolving interoperability mandates from the Office of the National Coordinator for Health IT, as federal push for device data portability threatens proprietary ecosystem lock-in and rewards open-architecture investments.
Market Dynamics
Hospital procurement departments now bundle continuous glucose monitors with analytics platforms, forcing manufacturers to abandon standalone hardware sales in favor of integrated subscription contracts that lock in multi-year sensor commitments.
Growth Catalysts
- CMS Reimbursement Expansion:The Centers for Medicare & Medicaid Services broadened coverage criteria for continuous glucose monitors in the United States, triggering hospital system-wide adoption mandates for insulin-treated patient populations.
- Optical Sensing Convergence:Non-invasive spectral glucose monitoring is integrating with wearable form factors, opening regulatory pathways for patient populations resistant to interstitial needle insertion.
- Germany Statutory Approval:German health insurance funds now routinely authorize sensor-based systems for Type 1 and insulin-dependent Type 2 diabetes, establishing the largest reimbursed installed base in Europe.
Market Restraints
- Platinum Electrode Supply Concentration:Electrochemical sensor manufacturing depends on platinum group metal refining concentrated in South Africa and Russia, exposing production costs to geopolitical supply disruptions.
- EU MDR Clinical Evidence Burden:The European Medical Device Regulation imposes extended clinical trial requirements for glucose sensor renewals, delaying market access for iterative hardware improvements by 18-24 months.
- Non-Invasive Accuracy Ceiling:Optical and transdermal glucose sensing technologies remain clinically inferior to interstitial fluid sampling for hypoglycemia detection, limiting substitution in critical care settings.
Strategic Opportunities
- India Out-of-Pocket Market:Private diabetes clinics in Mumbai and Delhi represent an underpenetrated channel where direct-to-consumer sensor sales bypass public reimbursement constraints entirely.
- Pump-Sensor Hybrid Automation:Convergence of continuous glucose monitoring with insulin delivery algorithms creates closed-loop system demand among pediatric endocrinology practices seeking reduced caregiver intervention.
- ONC Interoperability Mandates:The Office of the National Coordinator for Health IT data portability requirements reward manufacturers investing in open-architecture platforms that export real-time glucose streams to electronic health records.
Industry Challenges
- Biocompatibility Engineering Talent Scarcity:Sensor membrane development requires specialized polymer chemists conversant in both enzymatic stability and skin irritation protocols, a skill intersection rare in medical device labor markets.
- FDA 510(k) Predicate Device Trap:Incremental algorithm improvements face regulatory classification as substantial equivalence disputes, forcing manufacturers into de novo pathways with unpredictable timeline outcomes.
- Legacy Hospital IT Integration:Bedside glucose data feeds must interface with proprietary Cerner and Epic architectures, requiring costly custom middleware development for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Based Glucose Measuring Systems Market |
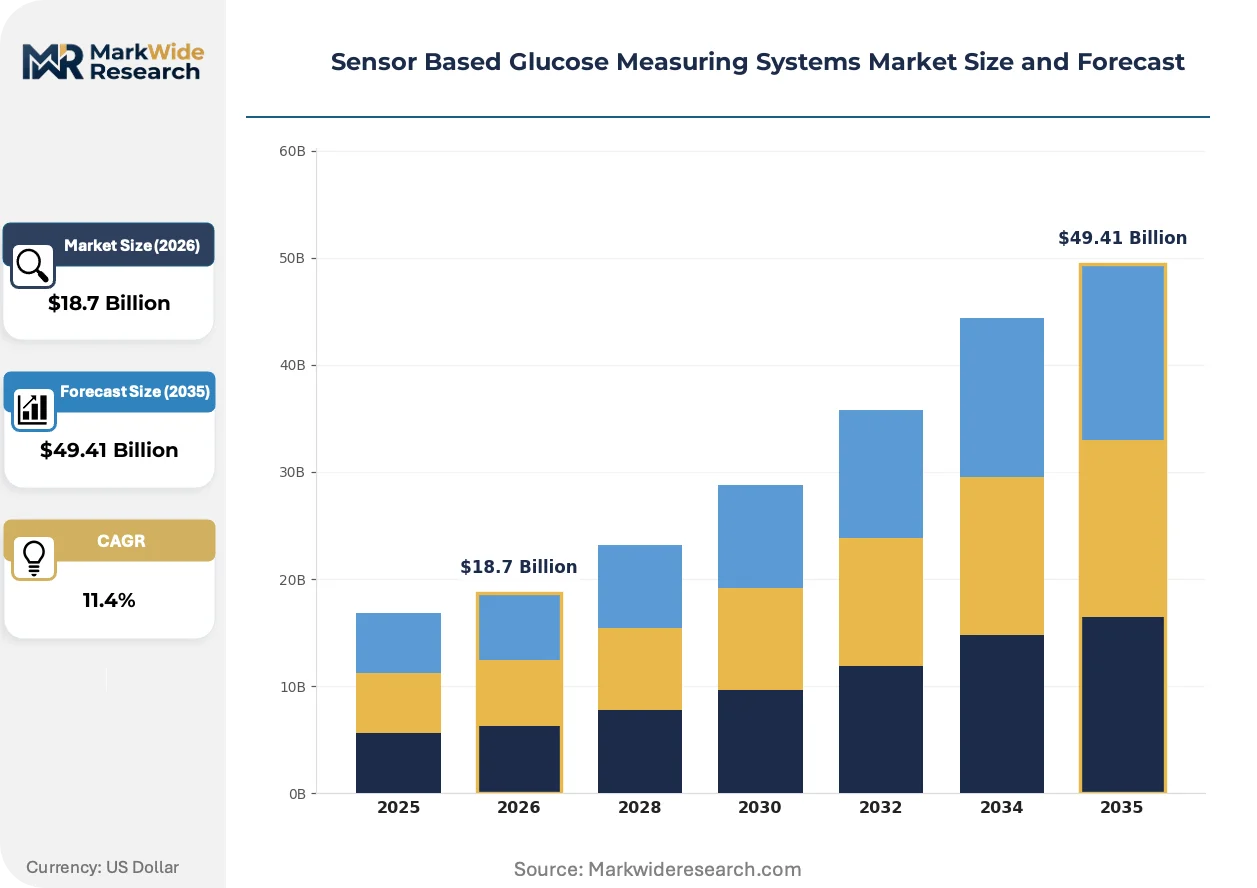
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Blood Glucose Meters, Smart Insulin Pens, Wearable Devices Technology: Electrochemical, Optical, Enzymatic, Microfluidics End User: Hospitals, Home Healthcare, Clinics, Research Institutions Application: Diabetes Management, Clinical Trials, Health Monitoring, Research Studies |
| Companies Covered | Abbott Laboratories, Dexcom, Medtronic, Roche Diabetes Care, Senseonics, Ascensia Diabetes Care, LifeScan, Novo Nordisk, B. Braun Melsungen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Based Glucose Measuring Systems Market Evolving Landscape
Algorithmic personalization is displacing one-size-fits-all glucose threshold alerts, with machine learning models now adapting to individual patient metabolic patterns in real-time. This shift redefines competitive advantage around software sophistication rather than sensor hardware specifications alone.
Multianalyte electrochemical sensors are integrating lactate and ketone detection alongside glucose measurement, enabling metabolic crisis prediction for diabetic ketoacidosis risk. Intensive care units in academic medical centers are piloting these platforms for sepsis patient glycemic control. The structural consequence is compressing the addressable market for standalone point-of-care ketone meters.
MDR Article 120 transition deadlines are forcing glucose sensor manufacturers to resubmit technical documentation under stricter clinical evidence requirements. Small and mid-sized European distributors lack the regulatory affairs capacity to manage notified body audits, triggering consolidation toward manufacturers with in-house CE marking expertise. Germany and France are experiencing the most pronounced distributor attrition as resubmission costs escalate.
Health system purchasing committees now mandate total cost-of-ownership analysis spanning sensor failure rates, calibration labor, and IT integration expenses. This behavioral shift displaces unit-price negotiations as the dominant procurement criterion. The United States exhibits the most advanced committee structures, with integrated delivery networks in Texas and California standardizing three-year total cost models for vendor selection.
Sensor Based Glucose Measuring Systems Market Segmentation
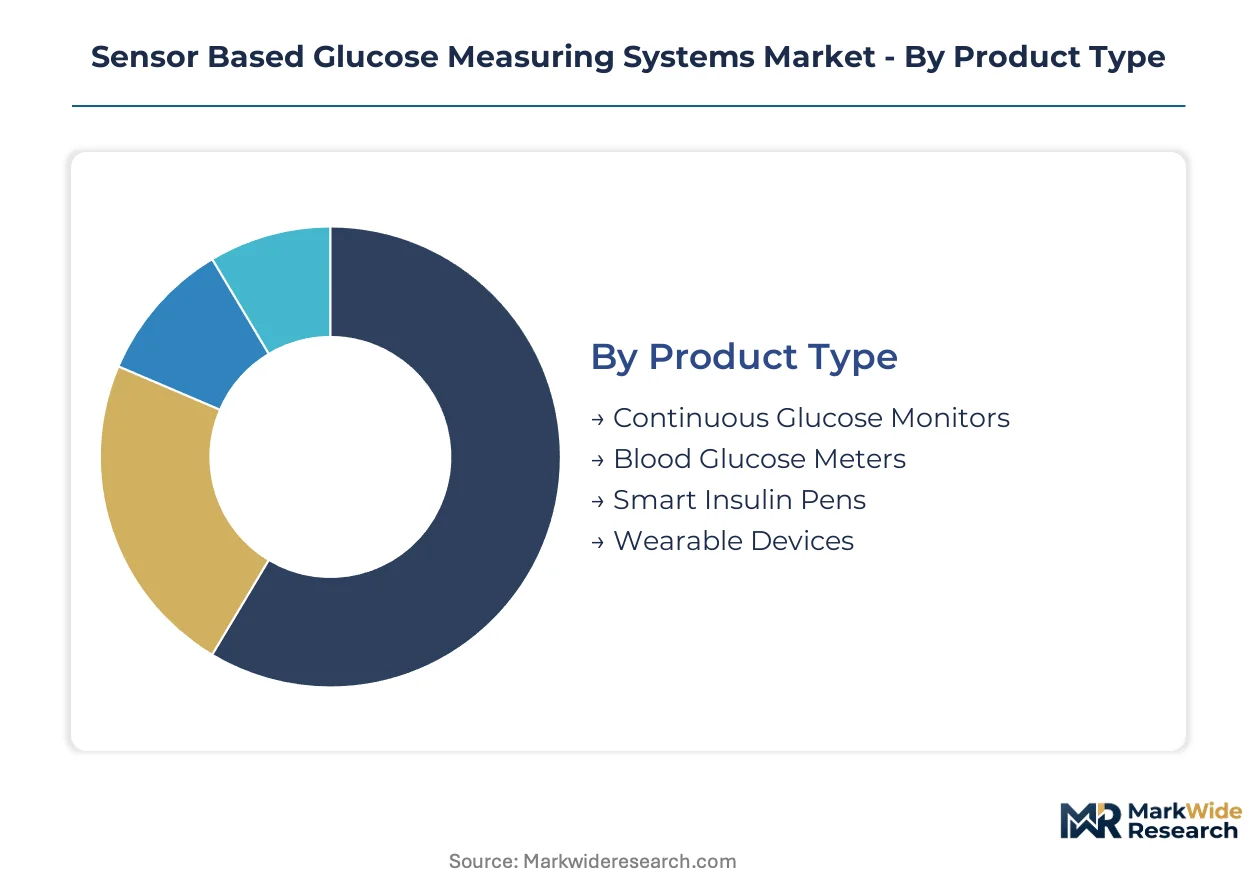
Sensor based glucose measuring systems fragment across four intersecting dimensions that reshape procurement patterns and R&D allocation. Technology choices determine reimbursement eligibility, while end-user concentration shifts between institutional buyers and direct-to-consumer channels. Understanding these segment boundaries clarifies where manufacturers must build distinct commercial capabilities.
Product Type:
Electrochemical foundations and optical research frontiers define how hardware specifications cluster into commercial categories.
- Continuous Glucose Monitors:Interstitial fluid sampling systems with factory-calibrated electrochemical sensors dominate hospital formularies and insulin-dependent patient populations. CMS reimbursement expansion in the United States has triggered system-wide adoption mandates across integrated delivery networks managing insulin-treated diabetes.
- Wearable Devices:Miniaturized form factors integrating optical or electrochemical sensing with smartphone connectivity represent the configuration expanding most quickly. Battery efficiency improvements and patient compliance priorities in Germany's statutory health insurance system accelerate demand for discreet, adhesive-patch designs.
- Blood Glucose Meters:Fingerstick capillary sampling devices retain cost-sensitive market presence through pharmacy retail channels and emerging economy out-of-pocket purchases.
- Smart Insulin Pens:Bluetooth-enabled dose tracking and timing reminders bridge injection therapy with digital adherence monitoring, appealing to Type 2 patients not yet requiring pump therapy.
Mature deployment sits with continuous glucose monitors. Newer deployment is concentrated in wearable devices.
Technology:
Signal transduction mechanisms separate clinically validated platforms from pre-commercial research trajectories.
- Electrochemical:Enzyme-mediated glucose oxidation at platinum-group electrodes sustains the largest installed base across continuous monitoring systems. South African and Russian platinum refining concentration exposes production economics to geopolitical supply disruptions.
- Optical:Near-infrared spectroscopy and Raman scattering methods enable non-invasive transdermal measurement research. Patient populations resistant to interstitial needle insertion in academic medical centers pilot these platforms despite hypoglycemia detection accuracy limitations.
- Enzymatic:Glucose oxidase or dehydrogenase biocatalytic reactions remain foundational to disposable test strip manufacturing for point-of-care meters.
- Microfluidics:Lab-on-chip architectures integrating sample handling with electrochemical detection enable multianalyte metabolic panels for intensive care glycemic control.
Volume leadership belongs to electrochemical platforms. Optical approaches claim the steepest expansion trajectory in non-invasive research applications.
End User:
Purchasing authority and reimbursement pathways concentrate demand across institutional and consumer channels.
- Hospitals:Procurement committees now mandate total cost-of-ownership analysis spanning sensor failure rates, calibration labor, and Epic or Cerner IT integration expenses. Bundled subscription contracts with multi-year sensor commitments displace standalone hardware negotiations.
- Home Healthcare:Remote patient monitoring programs and aging-in-place initiatives expand reimbursement for connected glucose devices. Durable medical equipment suppliers in the United States manage distribution logistics for Medicare-covered continuous monitor prescriptions.
- Clinics:Endocrinology practices and diabetes specialty centers prescribe and train patients on sensor-based systems, influencing brand selection through clinical preference.
- Research Institutions:Clinical trial sponsors and academic medical centers source investigational devices with open data architectures for algorithm development and regulatory submission support.
Institutional purchasing power concentrates in hospitals. Direct-to-consumer momentum builds fastest in home healthcare channels.
Application:
Use case specificity determines regulatory pathway, clinical evidence requirements, and pricing architecture.
- Diabetes Management:Real-time glucose monitoring for insulin dosing decisions represents the primary reimbursed indication. FDA 510(k) clearance and CMS national coverage determinations shape market access timelines for new entrants.
- Clinical Trials:Pharmaceutical sponsors deploy continuous glucose monitors as biomarker collection tools for diabetes drug development programs. Data portability requirements from the Office of the National Coordinator for Health IT reward open-architecture platform investments.
- Health Monitoring:Wellness-oriented consumers without diagnosed diabetes adopt continuous monitoring for metabolic optimization and preventive health tracking.
- Research Studies:Academic investigations into glycemic variability, exercise metabolism, and nutrition science generate demand for raw data export capabilities and customizable alert thresholds.
Revenue concentration remains with diabetes management. Research studies show the fastest adoption velocity among non-reimbursed applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States, while consumption spreads across reimbursed patient populations in statutory health insurance systems. South Korean battery suppliers feed miniaturization trends for wearable form factors. Indian private clinics absorb direct-to-consumer sensor volumes outside public reimbursement frameworks.
United States
Hospital procurement committees at integrated delivery networks in Texas and California now mandate three-year total cost-of-ownership contracts for continuous glucose monitors. CMS national coverage determinations expanded reimbursement criteria for insulin-treated populations, triggering system-wide adoption mandates across Medicare Advantage plans. The FDA 510(k) clearance pathway shapes market access timelines for electrochemical sensor entrants seeking predicate device classification.
Germany
Statutory health insurance funds in Bavaria and North Rhine-Westphalia routinely authorize sensor-based systems for Type 1 and insulin-dependent Type 2 diabetes patients. The EU MDR Article 120 transition deadlines force manufacturers to resubmit technical documentation under stricter clinical evidence requirements, delaying iterative hardware improvements by 18-24 months. Berlin-based distributors lack regulatory affairs capacity for notified body audits, triggering consolidation toward manufacturers with in-house CE marking expertise.
India
Private diabetes clinics in Mumbai and Delhi represent underpenetrated channels where direct-to-consumer sensor sales bypass public reimbursement constraints entirely. The Central Drugs Standard Control Organization regulates glucose monitoring devices as medical devices requiring import licenses for foreign manufacturers. Karnataka's medical device manufacturing corridor near Bangalore hosts contract manufacturers assembling electrochemical test strips for export markets.
Japan
The Ministry of Health, Labour and Welfare reimbursement pricing for continuous glucose monitors lags European benchmarks, constraining hospital adoption despite aging diabetic demographics. Pharmaceutical and Medical Devices Agency consultations for algorithm-intensive platforms require local clinical trial data, extending pre-market timelines for foreign entrants. Osaka-based trading houses manage distribution logistics for imported sensor systems into prefectural hospital networks.
South Korea
Ministry of Food and Drug Safety fast-track approvals for wearable glucose monitors align with national digital health initiatives targeting diabetic management. Samsung SDI and LG Chem supply lithium polymer batteries enabling multi-day sensor wear time in adhesive-patch designs. Seoul Capital Area endocrinology practices pilot optical sensing research platforms for patient populations resistant to interstitial needle insertion.
Sensor Based Glucose Measuring Systems Market Competitive Landscape
The competitive structure tilts toward vertically integrated conglomerates with captive sensor manufacturing and algorithm development capabilities. Three tiers separate subscription-platform operators, pump-sensor hybrid specialists, and point-of-care test strip commoditizers. Dominant competitive moves include strategic partnerships with health system purchasing committees and geographic expansion through distributor acquisition in EU MDR transition markets.
Among vertically integrated conglomerates, Abbott Laboratories anchors pricing power across integrated delivery networks through manufacturing scale. Dexcom occupies a position exemplifying algorithm-intensive platform differentiation focused on time-in-range metrics. Medtronic sits within the pump-sensor hybrid automation tier, competing on closed-loop credibility in pediatric endocrinology practices. These three represent distinct strategic archetypes rather than direct substitutes.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom |
| Medtronic |
| Roche Diabetes Care |
| Senseonics |
| Ascensia Diabetes Care |
| LifeScan |
| Novo Nordisk |
| B. Braun Melsungen |
| Others |
Value Network & Pricing Analysis
Algorithm-performance divergence between factory-calibrated electrochemical sensors and optical research platforms manifests in subscription premiums for closed-loop automation versus per-unit spot pricing for investigational non-invasive devices. This bifurcation concentrates margin capture with vertically integrated manufacturers controlling platinum electrode supply and software companion development, while contract assemblers compete on test strip commoditization.
Pricing Analysis
Margin tightening in point-of-care test strips reflects South African platinum price volatility and Korean battery cost pass-through. Three-tier pricing structure across premium closed-loop systems, standard continuous monitors, and economy fingerstick meters differentiates by calibration automation and algorithm personalization depth. Cost-down pressure on disposable sensors accelerates because German statutory funds now mandate total cost-of-ownership procurement. Hospital committees exhibit lowest price sensitivity; direct-to-consumer channels in India absorb highest elasticity.
Supply Chain Analysis
Regional distribution centers in Illinois and Bavaria coordinate hub-and-spoke replenishment for hospital integrated delivery networks. Manufacturing concentrates in Germany, the United States, and South Korea. Platinum group metals draw from South African and Russian refining; glucose oxidase enzymes source from Danish biocatalysis specialists; lithium polymer batteries feed from Samsung SDI and LG Chem facilities. Single-source vulnerability sits with platinum electrode supply. Distribution runs through durable medical equipment suppliers managing Medicare logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive position in sensor-based glucose monitoring hinges on backward integration into platinum-group metal procurement and captive algorithm development. Manufacturers without upstream enzyme supply agreements face margin compression as statutory reimbursement tightens.
For Market Incumbents: Anticipate FDA 510(k) predicate disputes forcing de novo pathways for iterative sensor improvements by building regulatory affairs capacity ahead of submission. Secure multi-year platinum supply contracts with South African refiners to buffer geopolitical disruption. Defend hospital formulary position through Epic and Cerner middleware pre-certification.
For New Entrants and Emerging Players: Optical sensing convergence with wearable form factors offers a technology-first wedge for patient populations resistant to interstitial needle insertion. Target private diabetes clinics in Mumbai and Delhi where out-of-pocket purchases bypass reimbursement constraints. Pursue fast-track MFDS approval in South Korea to establish clinical credibility before FDA submission.
For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-intensive platform specialists given CMS interoperability mandates rewarding open-architecture investments. Long-term viability favors manufacturers with in-house CE marking expertise navigating EU MDR Article 120 resubmission deadlines. Watch distributor consolidation in Germany and France as a signal of regulatory capacity scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Locks in multi-year sensor subscriptions through integrated delivery network procurement committees. |
| CE Marking Pathway Investment | Preserves European market access as MDR clinical evidence requirements delay competitor renewals. |
| Software Companion Development | Extends time-in-range metrics through machine learning personalization beyond hardware specifications. |
| Backward Integration into Enzyme Supply | Reduces exposure to Danish biocatalysis specialist pricing and secures glucose oxidase stability. |
| Reimbursement Strategy | Aligns CMS national coverage determination timing with hospital adoption mandate windows. |
Research Methodology
FDA 510(k) filings, CMS Medicare claims data, and EU MDR notified body documentation formed the secondary backbone of this analysis. Primary interviews with hospital procurement managers, biomedical engineers, endocrinology practice administrators, and GPO contracts specialists validated demand assumptions. Bottom-up sensor shipment estimates triangulated against top-down statutory health insurance reimbursement volumes across Germany, the United States, and Japan.
Bottom-up modeling tracked electrochemical, optical, enzymatic, and microfluidic technology segments alongside continuous monitor, wearable, and point-of-care product configurations. Top-down validation referenced diabetes prevalence databases and insulin-treated population penetration rates. CAGRs derived from pricing trajectory analysis and sensor replacement cycle compression. Forecast inputs incorporated platinum group metal supply elasticity and battery energy density improvement curves.
Several conditions sit outside the modeled scope, including breakthrough non-invasive optical accuracy achieving hypoglycemia detection parity and single-payer reimbursement adoption in India. Forecasts reflect documented assumptions around CMS coverage stability and EU MDR transition timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
France Diabetes Devices Market