
 Mexico Diabetes Medication Market | 2026-2036
Mexico Diabetes Medication Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Diabetes Medication Market Insights
Pharmaceutical distribution through institutional tenders is reconfiguring as public hospital networks consolidate purchasing power across Mexican states. Novo Nordisk leverages its manufacturing scale to anchor supply agreements with the largest federal health institutions. Eli Lilly and Company competes through differentiated pen-device technology that reduces dosing errors in rural clinics. Sanofi sustains brand loyalty among endocrinologists through specialized medical education programs targeting secondary cities.
Mexico diabetes medication encompasses chemically synthesized and biologically produced therapeutic agents that modulate glucose metabolism through insulin supplementation, secretion enhancement, or sensitivity improvement, with formulations requiring cold-chain stability between two and eight degrees Celsius for biological products. These medications serve to prevent microvascular complications including nephropathy and retinopathy while reducing macrovascular event risk in diabetic populations. Injectable delivery modes lead prescription value due to insulin analogue and GLP-1 agonist concentration, while oral formulations retain volume dominance in Type 2 diabetes first-line therapy where metformin occupies the standard-of-care position. Homecare channels represent the fastest-growing end-user segment as pen devices and continuous glucose monitoring enable patient self-management outside clinical settings.
COFEPRIS maintains stringent bioequivalence requirements for biosimilar insulins entering the Mexican market, while the national health secretariat's procurement guidelines shape formulary composition across IMSS and ISSSTE networks. SEGOB coordinates with trade authorities to prevent counterfeit antidiabetic circulation through pharmaceutical track-and-trace mandates. Stakeholders must monitor how AMLO administration's pharmaceutical sovereignty initiatives reshape import dependency for active pharmaceutical ingredients and finished biological products.
Market Dynamics
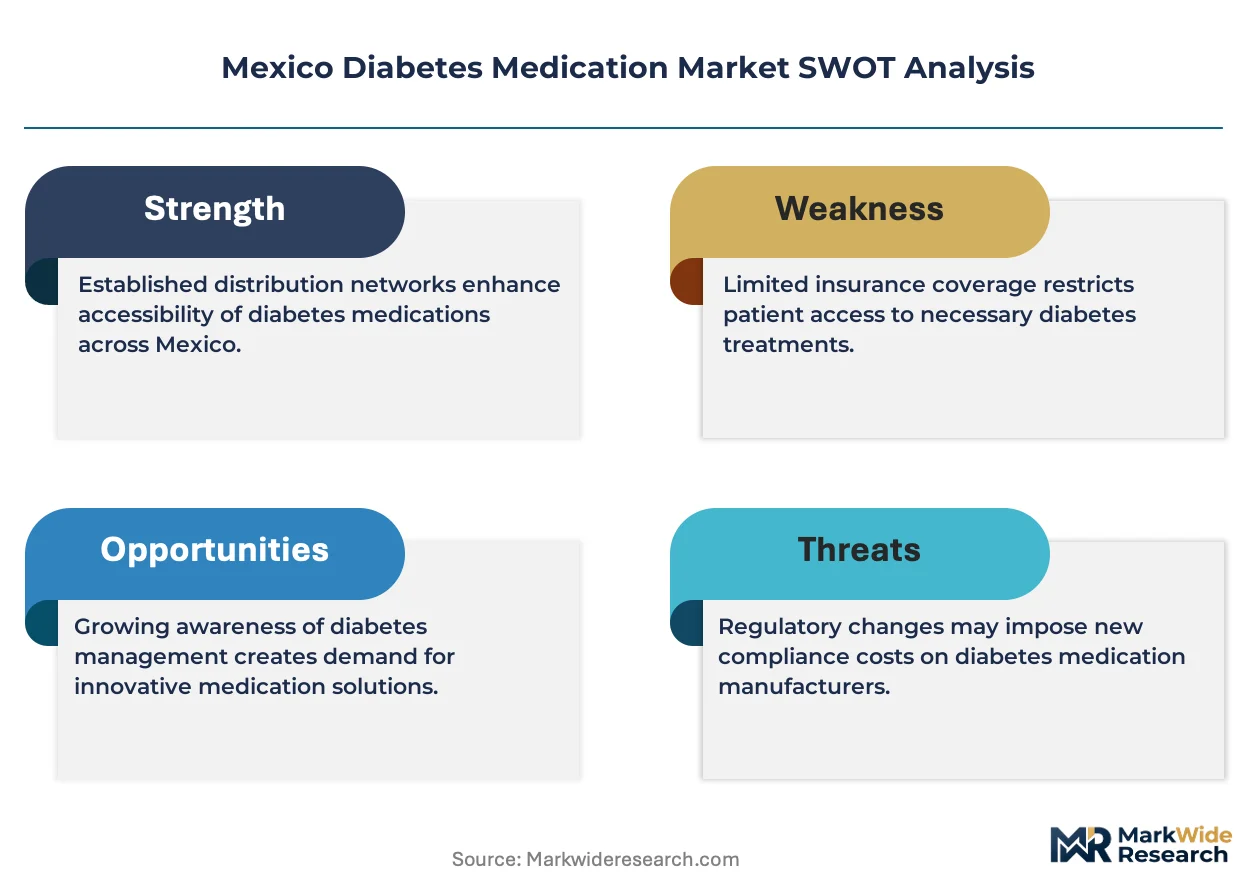
Hospital procurement consolidation across IMSS and ISSSTE networks is concentrating purchasing power into fewer tender processes, forcing manufacturers to restructure distribution partnerships and cold-chain logistics around institutional rather than retail pharmacy channels.
Growth Catalysts
- COFEPRIS biosimilar pathway acceleration:Streamlined bioequivalence protocols for insulin analogues are compressing time-to-market for domestic manufacturers and expanding formulary access within public health institutions.
- Endocrinology center clustering:Concentration of specialized diabetes care in Mexico City and Jalisco is generating prescription volume density that justifies dedicated supply infrastructure and medical education investments.
- Pen-device technology maturation:Dosing accuracy improvements in reusable injector systems are reducing hypoglycemia incidents and extending therapy adherence in rural clinic settings.
Market Restraints
- Active pharmaceutical ingredient import dependency:Mexico lacks domestic fermentation capacity for recombinant insulin production, exposing finished dose pricing to currency volatility and trade friction.
- Cold-chain infrastructure gaps:Temperature excursions during last-mile distribution to southern states degrade biological product efficacy and trigger insurance claims.
- Metformin generic saturation:First-line oral therapy commoditization is compressing manufacturer margins and diverting R&D resources toward injectable biologics.
Strategic Opportunities
- Homecare channel expansion:Continuous glucose monitoring integration with smartphone applications is enabling patient self-management outside clinical supervision.
- Guerrero and Oaxaca penetration:Underserved southern states present volume growth potential as Seguro Popular coverage expansion reaches previously uninsured diabetic populations.
- AMLO pharmaceutical sovereignty incentives:Domestic API manufacturing subsidies and technology transfer requirements are creating partnership opportunities for local joint ventures.
Industry Challenges
- Refrigeration technician scarcity:Specialized cold-chain maintenance skills are concentrated in major metropolitan areas, complicating biological product storage in remote clinics.
- COFEPRIS inspection backlog:Extended facility certification timelines delay product launches and tie up capital in inventory holding costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Diabetes Medication Market |
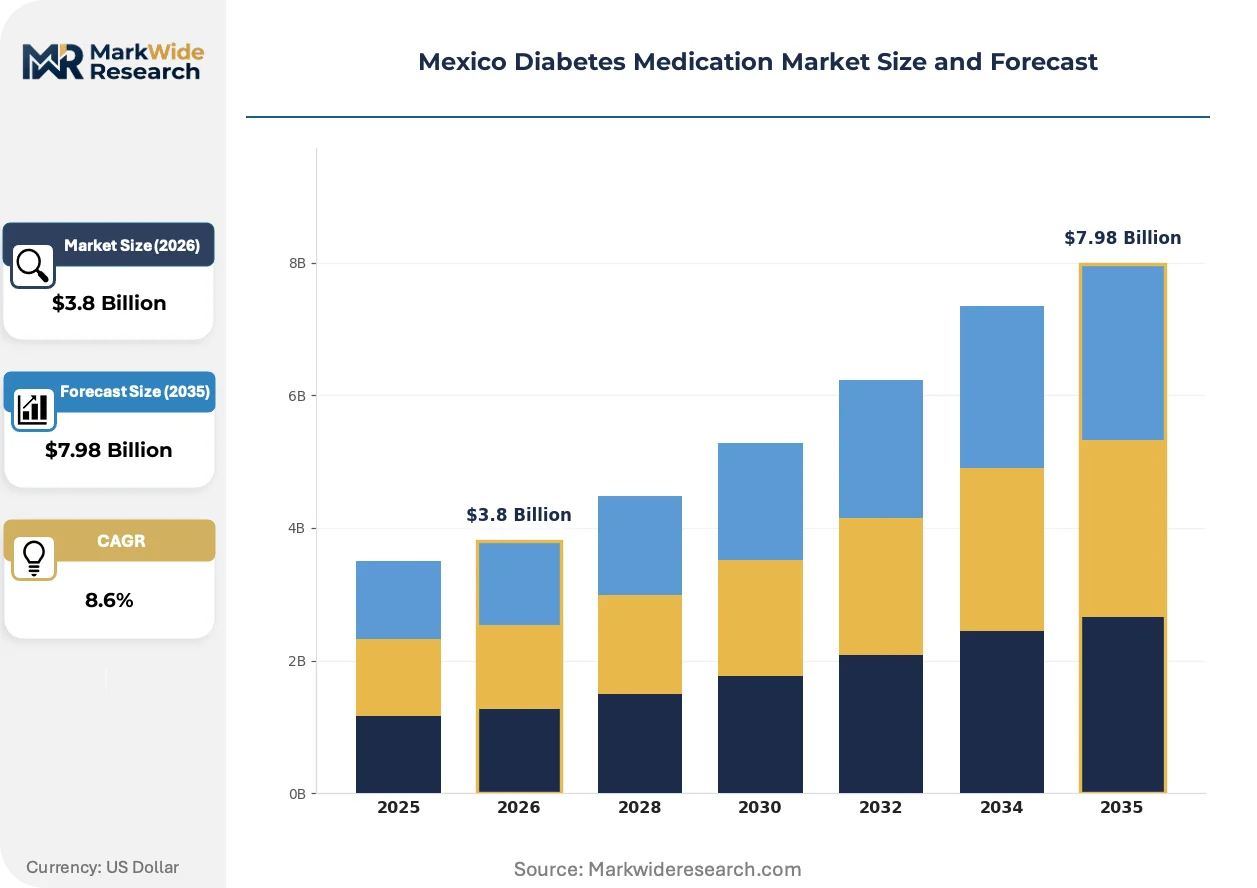
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
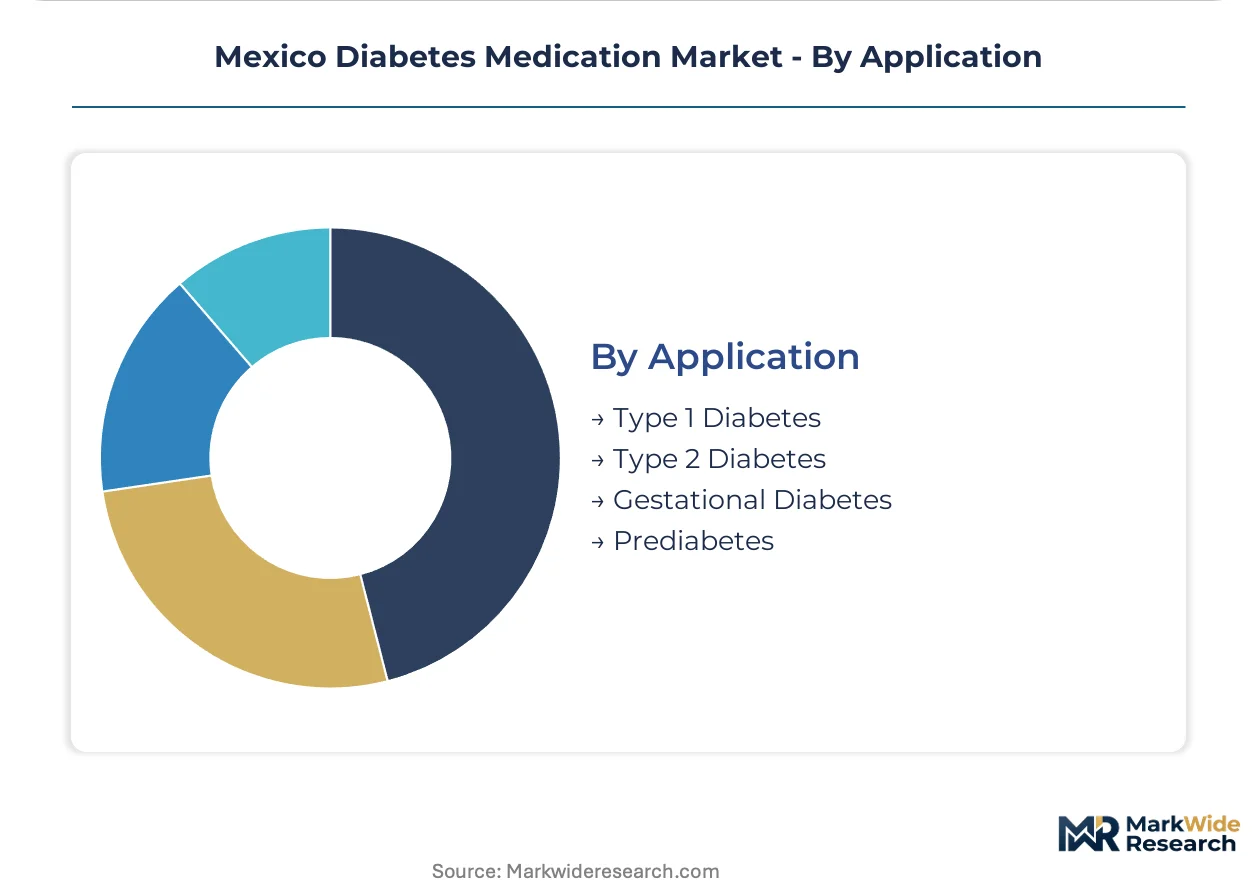
| Segmentation | Product Type: Insulin, Metformin, Sulfonylureas, DPP-4 Inhibitors End User: Hospitals, Clinics, Pharmacies, Homecare Delivery Mode: Injectable, Oral, Inhaled, Continuous Monitoring Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, AstraZeneca, Boehringer Ingelheim, Sanofi, Takeda, Pfizer, Merck and Co., Bristol Myers Squibb, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Diabetes Medication Market Trends and Innovations
Digital therapeutics and connected delivery devices are restructuring how Mexican patients interact with diabetes management, shifting accountability from clinic-based providers to technology-mediated self-care platforms that generate real-world evidence for formulary negotiations.
Smart pen devices with dose logging and Bluetooth connectivity are rendering obsolete manual injection record-keeping that previously relied on patient memory or paper diaries. IMSS hospital networks are piloting these systems in Mexico City endocrinology units to reduce medication error reporting. The technology is compressing the feedback loop between patient behavior and prescriber intervention, enabling tighter glycemic control without proportional nursing staff expansion.
COFEPRIS is tightening track-and-trace mandates for antidiabetic products through serialization requirements aligned with SEGOB counterfeit prevention protocols. Manufacturers must now integrate unique identifier systems across packaging lines serving the Mexican market. Secondary cities with fragmented wholesale networks face the steepest compliance costs as distributors consolidate to meet technical infrastructure thresholds.
Patient acquisition through digital pharmacies is displacing traditional retail foot traffic as convenience-oriented diabetics prioritize home delivery of temperature-sensitive medications. Mexico City and Monterrey exhibit the fastest channel migration, where same-day cold-chain courier services have achieved coverage density. This behavioral shift is forcing manufacturers to renegotiate margin structures with institutional buyers who previously captured exclusive volume commitments.
Mexico Diabetes Medication Market Segmentation
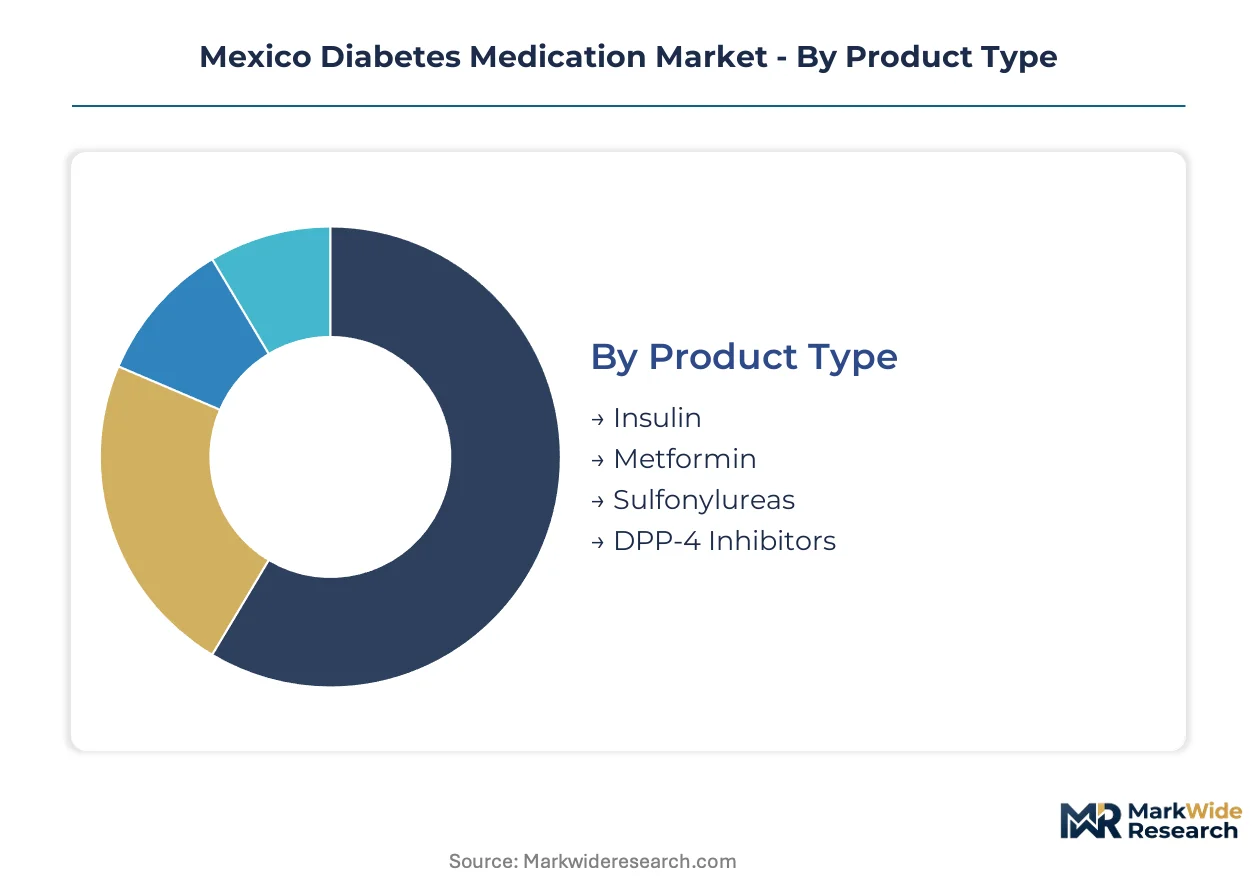
Segmentation in the Mexico diabetes medication market reveals how reimbursement pathways, cold-chain requirements, and prescriber specialization concentrate value across distinct product and delivery categories. Understanding these divisions exposes where procurement consolidation and patient self-management trends are redirecting commercial investment.
Product Type:
After-sales service intensity varies sharply across product categories, with biological therapies demanding specialized refrigeration maintenance and dose-adjustment counseling that synthetic oral agents do not require.
- Insulin:Recombinant protein formulations require uninterrupted cold-chain custody from manufacturing through patient administration. Mexico City and Jalisco endocrinology centers anchor demand for rapid-acting and long-acting analogues as COFEPRIS biosimilar approvals expand formulary options within IMSS networks.
- Metformin:Biguanide compounds dominate first-line Type 2 diabetes therapy through generic manufacturing scale that minimizes per-unit cost. Volume concentrates in retail pharmacy channels where Seguro Popular coverage eliminates copayment barriers for uninsured populations in southern states.
- Sulfonylureas:Pancreatic beta-cell stimulants retain position in resource-constrained settings where insulin cold-chain infrastructure proves unreliable.
- DPP-4 Inhibitors:Gliptin-class oral agents compete on glycemic control without hypoglycemia risk, appealing to employed populations prioritizing workday stability.
By volume, Metformin leads. By growth pace, Insulin analogue biosimilars are climbing the fastest.
End User:
Cost tier differentiation separates institutional procurement from retail transactions, with federal hospital networks extracting volume discounts unavailable to individual pharmacies.
- Hospitals:IMSS and ISSSTE facilities consolidate tender processes for advanced biological therapies, leveraging purchasing scale to secure preferential pricing on GLP-1 agonists and insulin analogues. Cold-chain infrastructure investments concentrate in Mexico City metropolitan hospitals where endocrinology specialist density justifies dedicated storage capacity.
- Homecare:Pen-device technology and continuous glucose monitoring enable patient-managed therapy outside clinical supervision. Same-day courier networks in Monterrey and Guadalajara are expanding temperature-controlled delivery coverage that supports this channel's steepest expansion trajectory.
- Clinics:Secondary and tertiary care facilities in state health systems handle stable patients requiring routine monitoring without specialist referral.
- Pharmacies:Retail dispensing faces margin compression as digital pharmacies and institutional tenders capture volume concentration.
By patient volume, Hospitals dominate. By channel expansion rate, Homecare is gaining share fastest.
Delivery Mode:
Application context determines delivery selection, with acute glycemic crises requiring parenteral intervention while chronic maintenance favors patient-administered options.
- Injectable:Subcutaneous administration encompasses insulin analogues, GLP-1 receptor agonists, and emergency glucagon formulations. Pen-device technology maturation is reducing dosing errors in rural Jalisco clinics where nursing staff coverage remains thin.
- Oral:Tablet and capsule formulations of metformin, sulfonylureas, and DPP-4 inhibitors retain prescription volume leadership through convenience and ambient storage requirements that eliminate cold-chain dependency.
- Inhaled:Pulmonary insulin delivery remains niche due to COFEPRIS respiratory safety review requirements and limited prescriber familiarity.
- Continuous Monitoring:Interstitial glucose sensors paired with algorithm-driven insulin pumps represent the technology frontier, with IMSS pilot programs in Mexico City testing reimbursement viability.
By prescription count, Oral formulations lead. By technology investment flow, Continuous Monitoring shows the steepest expansion trajectory.
Application:
Patient maturity and disease progression stage shape therapy intensity, with autoimmune onset requiring immediate insulin dependence while metabolic dysfunction permits gradual pharmacological escalation.
- Type 2 Diabetes:Insulin resistance and progressive beta-cell failure characterize the predominant patient population. Jalisco and Mexico City specialist centers concentrate demand for advanced combination therapies as disease duration extends.
- Type 1 Diabetes:Autoimmune destruction of pancreatic beta cells mandates lifelong insulin replacement from diagnosis. Pediatric endocrinology units in federal hospitals anchor concentrated demand for rapid-acting and basal analogue formulations.
- Gestational Diabetes:Pregnancy-related glucose intolerance requires temporary glycemic management with fetal safety constraints on pharmacological selection.
- Prediabetes:Impaired glucose tolerance presents intervention opportunity through lifestyle modification and metformin prophylaxis in employed populations with health screening access.
By patient population, Type 2 Diabetes dominates. By unmet need intensity, Type 1 Diabetes commands the most specialized clinical resources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Lázaro Cárdenas anchors pharmaceutical import flows for central Mexico, while the Mexico City-Querétaro highway corridor enables cold-chain distribution to inland manufacturing clusters. Federal health infrastructure investments concentrate procurement power in metropolitan zones with specialized endocrinology capacity.
Mexico City Metro
Hospital networks IMSS and ISSSTE anchor insulin analogue demand through consolidated tender processes. COFEPRIS headquarters proximity accelerates biosimilar approval timelines for manufacturers submitting bioequivalence data. The Tlalnepantla industrial corridor hosts cold-chain logistics hubs serving metropolitan endocrinology centers.
Jalisco
Guadalajara's medical device manufacturing ecosystem supports pen-device assembly and glucose sensor distribution. State health system expansion under Seguro Popular extends formulary access to uninsured populations. The El Salto pharmaceutical zone concentrates insulin packaging operations for western Mexico.
Nuevo León
Monterrey's private hospital chains drive premium GLP-1 agonist adoption among insured employed populations. Same-day courier networks enable homecare channel penetration for temperature-sensitive biologics. The Apodaca industrial park anchors distribution centers serving northern border states.
Bajío Region
Querétaro and Guanajuato automotive worker health plans generate employer-sponsored diabetes screening and medication coverage. Manufacturing plant clinics handle stable Type 2 cases without specialist referral. León's wholesale pharmaceutical district links to Mexico City distribution arteries.
Northern Border States
Chihuahua and Baja California maquiladora health programs mirror US employer insurance structures for cross-border workforce retention. COFEPRIS track-and-trace mandates intersect with US FDA serialization requirements at export-oriented packaging facilities. Tijuana's medical tourism corridor channels US patients seeking cost-differentiated insulin formulations.
Mexico Diabetes Medication Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying API intermediates and delivery device subassemblies. The Mexico diabetes medication market consolidates around multinational biologics manufacturers with fermentation scale and domestic formulation partnerships. Three archetypes dominate: vertically integrated insulin producers with captive API supply, pen-device technology licensors, and biosimilar challengers exploiting COFEPRIS pathway acceleration. Competitive moves concentrate on hospital tender consolidation through volume commitments and cold-chain infrastructure co-investment with federal health networks.
Among Danish and US-based biologics manufacturers, Novo Nordisk and Eli Lilly and Company exemplify the platform-integrator archetype through manufacturing scale anchoring IMSS supply agreements. Sanofi occupies a position bridging biological insulin production and delivery device specialization. These three entities represent distinct strategic postures: fermentation capacity dominance, differentiated injector technology, and endocrinologist education investment respectively.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| AstraZeneca |
| Boehringer Ingelheim |
| Sanofi |
| Takeda |
| Pfizer |
| Merck and Co. |
| Bristol Myers Squibb |
| Others |
Pricing and Supply Chain Analysis
Tlalnepantla's cold-chain logistics corridor anchors insulin analogue distribution for central Mexico, concentrating storage capacity within a 40-kilometer radius of COFEPRIS headquarters. This geographic clustering grants incumbent manufacturers leverage over tender pricing at IMSS and ISSSTE facilities, while southern states absorb freight premiums that compress margins for biosimilar challengers lacking scale.
Pricing Analysis
Volume-discount tiering separates federal hospital networks from retail pharmacy channels, with IMSS consolidated tenders extracting 15-30% price concessions unavailable to individual dispensaries. Price differentiation rests on cold-chain reliability certification and pen-device technology bundling, where reusable injector systems command premium positioning over standard vial-and-syringe formats. Cost compression in the metformin generic segment is intensifying because domestic manufacturers exploit fermentation capacity in India and China to undercut originator brands. Uninsured patients in Guerrero and Oaxaca exhibit highest price sensitivity, while Monterrey's private hospital chains prioritize glycemic control outcomes over per-unit cost.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk planning for finished dose packaging operations in Tijuana and Ciudad Juárez. Active pharmaceutical ingredient production concentrates in China, India, and Denmark, with recombinant insulin fermentation drawing from Danish and US biologics capacity. Supply chain vulnerability centers on single-source dependency for GLP-1 receptor agonist peptide intermediates, where COFEPRIS bioequivalence requirements limit qualified supplier pools. Distribution runs through institutional tender channels for biological therapies, while ambient-storage oral agents flow via wholesale pharmaceutical districts in León and Guadalajara.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement at IMSS and ISSSTE networks, compressing manufacturer margins as tender volumes concentrate in fewer annual negotiations. Hospital network consolidation across Mexican states fragments retail pharmacy influence over formulary composition.
For Market Incumbents: Insulate market position through captive API supply agreements with Indian fermentation partners and cold-chain infrastructure co-investment with federal health networks. Biosimilar challengers exploiting COFEPRIS pathway acceleration threaten insulin analogue margins; vertical integration into pen-device manufacturing in Jalisco's El Salto zone preserves differentiation through delivery technology bundling. For New Entrants and Emerging Players: Southern state underpenetration in Guerrero and Oaxaca offers volume expansion as Seguro Popular coverage reaches previously uninsured diabetic populations. Homecare channel penetration through same-day courier partnerships in Monterrey and Guadalajara represents the most penetrable segment; target employed populations with continuous glucose monitoring integration and smartphone application adherence tools. For Investors and Strategic Acquirers: Long-term, this sits as a biosimilar manufacturing scale play because COFEPRIS streamlining compresses time-to-market for domestic producers with Indian API partnerships. Acquisition targets include mid-cap formulation facilities with existing cold-chain certification and COFEPRIS inspection history. Watch COFEPRIS facility certification backlog resolution as the signal indicating regulatory capacity to absorb accelerated biosimilar submissions.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Co-Investment | IMSS hospital networks prioritize suppliers with verified refrigeration redundancy in southern states. |
| COFEPRIS Biosimilar Approval Pathway | Streamlined bioequivalence protocols compress regulatory timelines for insulin analogue entrants. |
| Pen-Device Technology Licensing | Reusable injector systems reduce dosing errors in Jalisco rural clinics with thin nursing coverage. |
| Digital Pharmacy Partnership | Same-day courier networks in Mexico City enable patient acquisition outside institutional tender channels. |
| API Manufacturing Subsidy Utilization | AMLO pharmaceutical sovereignty incentives reward domestic fermentation joint ventures with technology transfer. |
Research Methodology
Desk research of COFEPRIS regulatory filings, IMSS procurement databases, and pharmaceutical trade customs data preceded structured interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and endocrinology specialists. Primary fieldwork validated secondary findings on biosimilar approval timelines and tender consolidation patterns. Bottom-up patient population estimates triangulated against top-down health expenditure data from federal health secretariat disclosures.
Assumptions held COFEPRIS inspection capacity and AMLO pharmaceutical sovereignty policy direction fixed across the analysis window, while currency volatility and API import tariff trajectories were stress-tested. Segmentation modeling spanned product type, end-user channel, delivery mode, and application across the projection horizon. CAGRs derived from patient population growth, therapy penetration rates, and price trajectory assumptions for biological versus synthetic agents. Forecast inputs incorporated Seguro Popular coverage expansion timelines and endocrinology center density projections for Mexico City and Jalisco.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by biosimilar challengers or sudden COFEPRIS regulatory tightening would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Global Blood Glucose Test Strip Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Continuous Glucose Monitoring Market