
 United States Cardiometabolic Fixed-Dose Combinations Market | 2026-2036
United States Cardiometabolic Fixed-Dose Combinations Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cardiometabolic Fixed-Dose Combinations Market Insights
Specialty clinics is rotating toward cardiometabolic fixed-dose combinations as primary care physicians face time constraints managing polypharmacy patients. Pfizer Inc. leverages its cardiovascular heritage to sustain formulary positioning across integrated delivery networks. AstraZeneca anchors its portfolio through SGLT2 inhibitor combinations that dominate hospital discharge protocols. Novo Nordisk A/S differentiates via injectable fixed-dose platforms that occupy the obesity-diabetes intersection.
Cardiometabolic fixed-dose combinations are pharmaceutical formulations containing two or more active therapeutic agents in a single dosage unit, typically combining antihypertensive, antidiabetic, or lipid-modifying compounds with complementary mechanisms of action, manufactured through advanced granulation and tableting processes to ensure uniform drug distribution and dissolution profiles. Their primary purpose is to improve medication adherence, reduce pill burden, and achieve synergistic therapeutic effects in patients with multiple cardiometabolic risk factors. Antihypertensives represent the most mature segment, with established generic competition compressing margins on legacy ACE inhibitor-diuretic combinations, while diabetes management combinations containing GLP-1 receptor agonist partnerships command premium positioning due to unmet need and patent protection. Extended-release formulations are gaining fastest adoption as delivery mode, driven by payer preference for reduced dosing frequency and improved adherence metrics in value-based contracts.
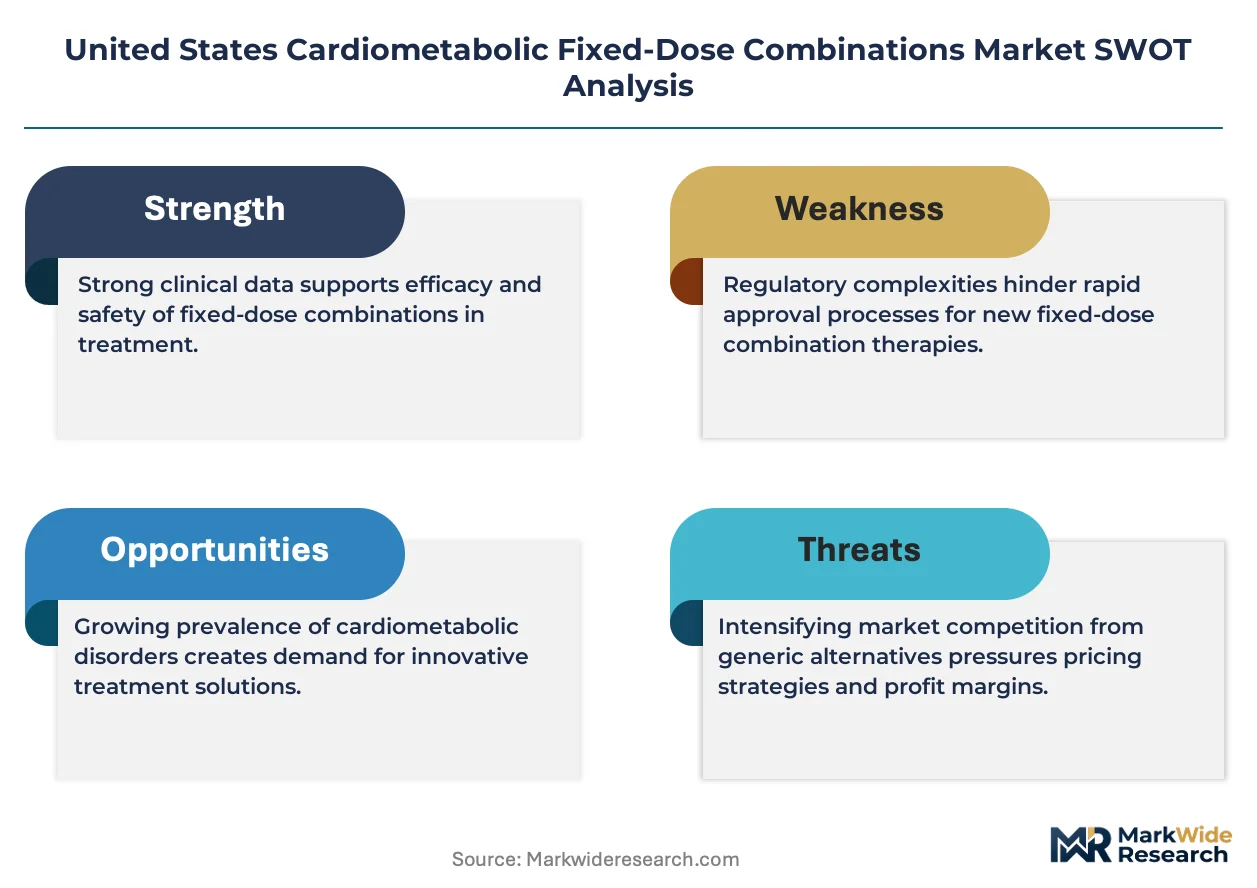
FDA review standards for fixed-dose combinations require demonstration of contribution from each component to the claimed effects, shaping clinical trial design and development timelines for sponsors. The IRA's Medicare price negotiation provisions and CMS quality measures for cardiovascular outcomes influence which combinations achieve preferred tier status versus step-therapy placement. Stakeholders must monitor how FDA guidance on complex generic equivalence for fixed-dose products evolves, as this will determine the competitive intensity and investment rationale for novel combination development programs.
Market Dynamics
The IRA's Medicare price negotiation provisions are restructuring formulary economics, forcing sponsors to recalibrate development priorities toward combinations with durable patent protection or differentiated clinical profiles that resist commoditization pressure.
Growth Catalysts
- Integrated Delivery Networks:IDN consolidation across Texas and Florida is standardizing discharge protocols that embed fixed-dose combinations into post-acute care bundles, locking in volume commitments through multi-year therapeutic contracts.
- CMS Quality Measures:Hospital reimbursement tied to cardiovascular outcome metrics is accelerating adoption of guideline-concordant combination therapies that demonstrate readmission reduction in congestive heart failure populations.
- Extended-Release Platforms:Once-daily formulations are capturing preferential tier placement in value-based contracts where adherence metrics determine pharmacy benefit manager rebate structures.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing for SGLT2 inhibitor combinations concentrates among Chinese contract manufacturers, exposing sponsors to tariff volatility and geopolitical disruption risk.
- FDA Equivalence Standards:Complex generic guidance requiring identical pharmacokinetic profiles for fixed-dose products extends development timelines and elevates bioequivalence study costs for follow-on entrants.
- Step-Therapy Mandates:Commercial payers increasingly require failure on generic antihypertensive monotherapy before authorizing branded combination products, compressing first-line prescribing volume.
Strategic Opportunities
- Obesity-Diabetes Convergence:Fixed-dose combinations pairing GLP-1 receptor agonists with SGLT2 inhibitors are penetrating the Medicare Part D coverage gap where dual-indication products command premium positioning.
- Specialty Clinic Expansion:Cardiometabolic-focused ambulatory centers in Florida are deploying pharmacist-led medication therapy management programs that drive combination product selection through protocol-driven care pathways.
- IRA Exemption Window:Small-molecule combinations with FDA approval dates post-2031 fall outside initial Medicare price negotiation rounds, preserving pricing autonomy for late-stage pipeline assets.
Industry Challenges
- Formulation Complexity:Achieving compatible dissolution profiles for antihypertensive-antidiabetic combinations requires specialized granulation expertise that concentrates among a limited cohort of contract development and manufacturing organizations.
- Clinical Trial Design:FDA's contribution-of-components requirement necessitates factorial study designs that expand enrollment targets and extend development timelines for novel combination submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cardiometabolic Fixed-Dose Combinations Market |
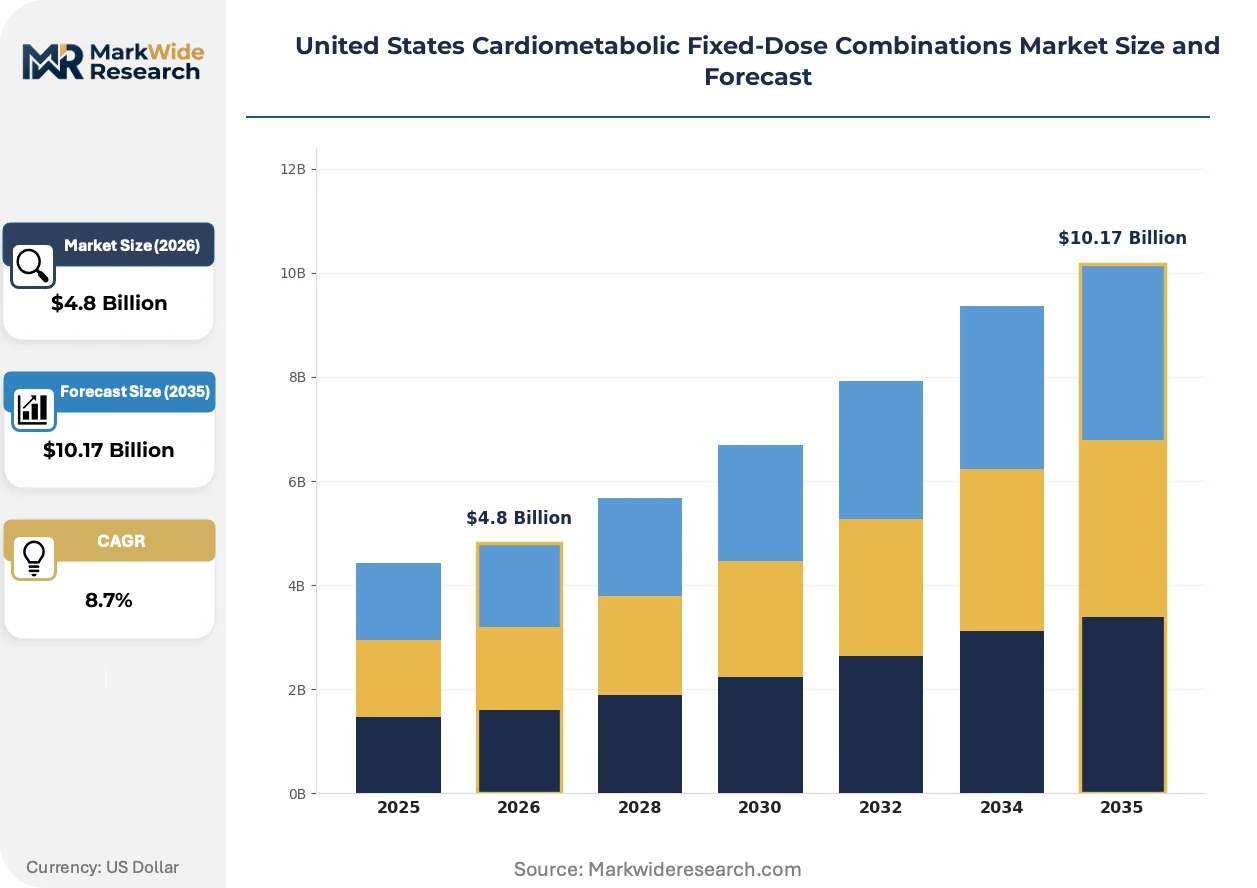
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihypertensives, Diabetes Management, Cholesterol Regulators, Weight Management Delivery Mode: Oral Tablets, Injectable Solutions, Extended-Release Formulations, Sublingual Tablets End User: Primary Care Clinics, Specialty Clinics, Home Care Settings, Hospitals Therapy Area: Diabetes, Hypertension, Dyslipidemia, Obesity |
| Companies Covered | Merck & Co., Inc., AstraZeneca, Pfizer Inc., Novo Nordisk A/S, Sanofi, Boehringer Ingelheim International GmbH, Sandoz AG, Azurity Pharmaceuticals Inc., Novartis AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cardiometabolic Fixed-Dose Combinations Market Trends and Innovations
Formulation science and reimbursement mechanics are converging to favor products that compress dosing frequency while satisfying increasingly granular outcome-based contracting requirements from integrated payers.
Dual-chamber injection devices combining GLP-1 receptor agonists with basal insulin are supplanting separate-injection regimens in obesity-diabetes management. Endocrinology practices within Texas Medical Center-affiliated networks are transitioning patients to these platforms at accelerating velocity. The technology is enabling sponsors to capture lifetime value through reduced switching flexibility and improved persistence metrics that satisfy value-based contract performance guarantees.
FDA's evolving guidance on complex generic bioequivalence for fixed-dose products is tightening substitutability standards for legacy ACE inhibitor-diuretic combinations. Sponsors of novel combinations are responding by investing in differentiated delivery technologies that create higher equivalence barriers for generic challengers. The antihypertensive segment faces the most acute pressure as historical therapeutic categories confront abbreviated new drug application pathways with elevated clinical evidence requirements.
Hospital-at-home programs are restructuring post-acute prescribing authority toward remote pharmacy platforms that favor simplified regimens with reduced pill burden. Cardiology practices participating in CMS innovation center demonstrations are directing patients toward mail-order specialty pharmacies that stock extended-release fixed-dose combinations exclusively. This shift is most visible in Florida's Medicare Advantage-heavy counties where capitated arrangements concentrate pharmacy benefit decisions within integrated delivery network formularies.
United States Cardiometabolic Fixed-Dose Combinations Market Segmentation
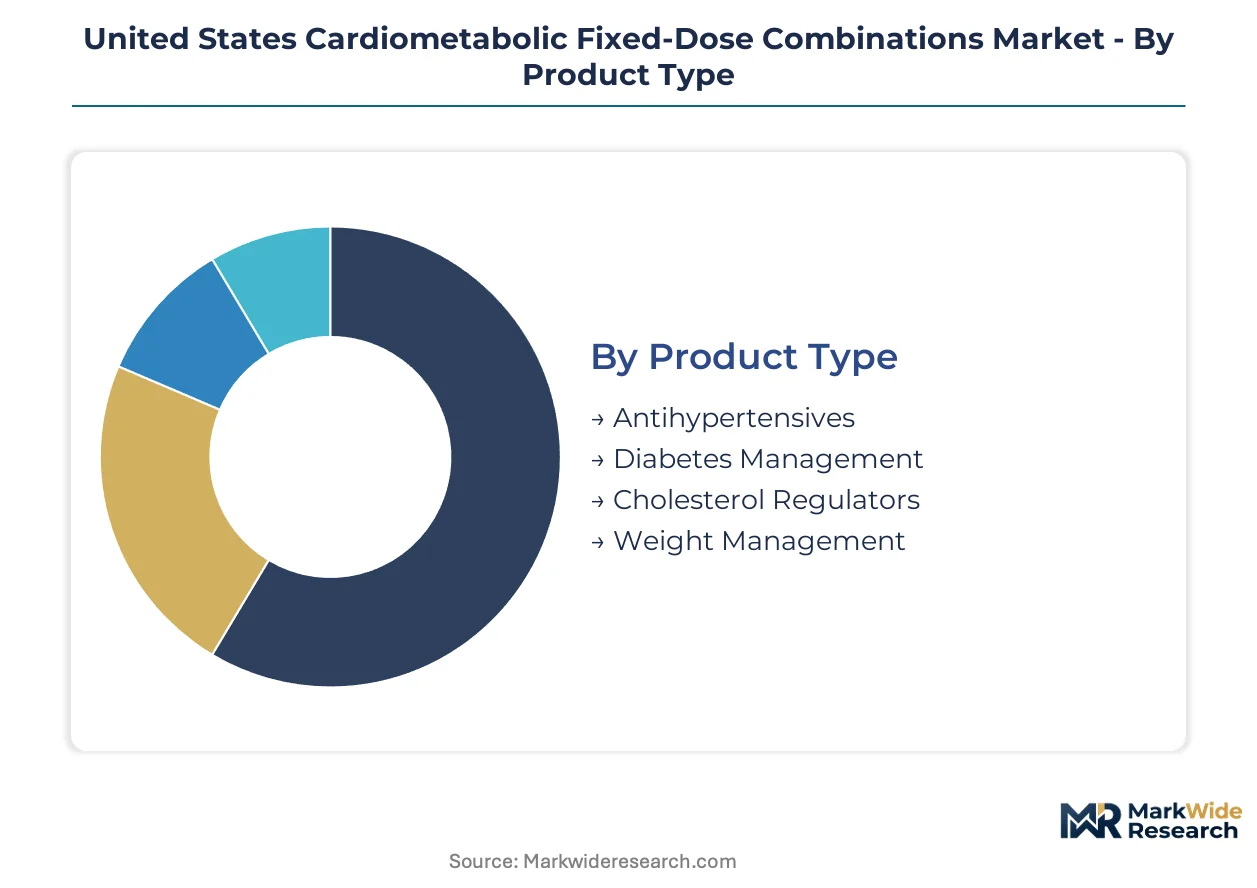
Cardiometabolic fixed-dose combinations fragment across four distinct segmentation axes that determine formulary positioning, reimbursement tiering, and patient access pathways. Product type and delivery mode classifications drive manufacturing investment decisions, while end user and therapy area distinctions shape commercial deployment strategies across Texas and Florida prescribing clusters.
Product Type:
Margin pools concentrate in diabetes management combinations where GLP-1 receptor agonist pairings command premium reimbursement, while antihypertensive segments face acute generic compression.
- Antihypertensives:ACE inhibitor-diuretic and ARB-calcium channel blocker combinations dominate legacy prescribing volumes. Florida Medicare Advantage formularies increasingly mandate step-therapy through generic monotherapy before authorizing branded fixed-dose products, eroding first-line positioning.
- Diabetes Management:SGLT2 inhibitor-metformin and GLP-1 receptor agonist combinations anchor hospital discharge protocols across Texas Medical Center networks. Extended-release formulations satisfy CMS quality measures for cardiovascular outcomes, securing preferential tier placement in value-based contracts.
- Cholesterol Regulators:Statin-ezetimibe combinations target residual cardiovascular risk populations.
- Weight Management:Emerging fixed-dose platforms pair incretin mimetics with metabolic activators for obesity-diabetes convergence indications.
Antihypertensives hold installed capacity. Diabetes Management is rotating up the share rankings.
Delivery Mode:
Volume distribution tilts toward oral platforms, though injectable solutions capture disproportionate value through reduced switching flexibility and improved persistence metrics.
- Oral Tablets:Immediate-release antihypertensive-diuretic combinations remain the default prescribing format in primary care settings. Texas and Florida Medicaid programs favor these formulations for cost-containment, though adherence gaps persist in polypharmacy populations.
- Injectable Solutions:Dual-chamber devices combining GLP-1 receptor agonists with basal insulin are supplanting separate-injection regimens in endocrinology practices. The technology enables sponsors to capture lifetime value through locked-in delivery platforms that satisfy performance guarantees in integrated delivery network contracts.
- Extended-Release Formulations:Once-daily dosing improves adherence metrics that determine pharmacy benefit manager rebate structures.
- Sublingual Tablets:Rapid-onset combinations target acute hypertensive crisis management in emergency department settings.
Oral Tablets maintain volume dominance. Injectable Solutions are climbing the fastest in value contribution.
End User:
Customer type segmentation reveals a structural shift from primary care toward specialty clinic control over combination therapy selection.
- Specialty Clinics:Cardiometabolic-focused ambulatory centers in Florida deploy pharmacist-led medication therapy management programs that drive protocol-driven care pathways. These facilities concentrate prescribing authority for complex patients with multiple comorbidities.
- Primary Care Clinics:Time-constrained physicians in Texas face polypharmacy management burdens that favor simplified regimens, though step-therapy mandates increasingly restrict branded combination first-line access.
- Home Care Settings:Hospital-at-home programs favor reduced pill burden regimens delivered through mail-order specialty pharmacies.
- Hospitals:Discharge protocol standardization embeds fixed-dose combinations into post-acute care bundles.
Hospitals hold installed capacity. Specialty Clinics are gaining share fastest through protocol capture.
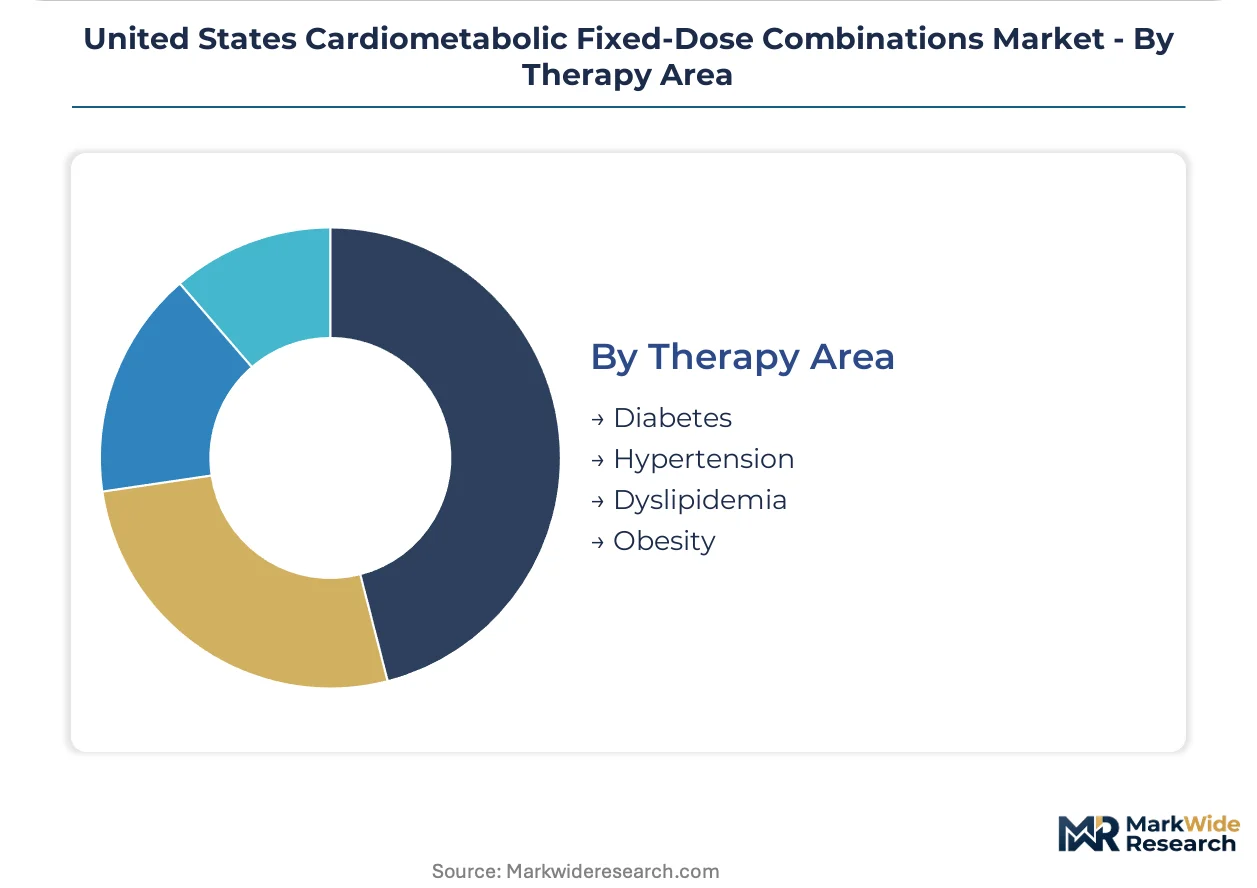
Therapy Area:
Application segmentation tracks the convergence of metabolic disease management under unified cardiovascular risk reduction frameworks.
- Diabetes:Fixed-dose combinations containing SGLT2 inhibitors dominate hospital discharge protocols due to demonstrated readmission reduction in congestive heart failure populations. CMS quality measures tied to cardiovascular outcomes accelerate adoption beyond glycemic control indications.
- Hypertension:Legacy ACE inhibitor-diuretic combinations face substitutability pressure from complex generic entrants under evolving FDA equivalence standards.
- Dyslipidemia:Statin combination therapies target residual risk populations post-acute coronary syndrome.
- Obesity:GLP-1 receptor agonist combinations penetrate Medicare Part D coverage gap where dual-indication products command premium positioning.
Hypertension holds installed capacity. Obesity is rotating up the share rankings through diabetes convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty clinic networks and Medicare Advantage penetration concentrate prescribing authority in four distinct U.S. sub-regions. Each geography exhibits unique reimbursement mechanics and patient population characteristics that shape fixed-dose combination demand.
Texas
Texas Medical Center-affiliated networks standardize discharge protocols embedding SGLT2 inhibitor combinations into post-acute care bundles. The state's Medicaid program favors immediate-release oral formulations for cost-containment. Houston and Dallas-Fort Worth clusters concentrate endocrinology practices transitioning patients to dual-chamber injectable platforms.
Florida
Medicare Advantage-heavy counties deploy capitated arrangements concentrating pharmacy benefit decisions within integrated delivery network formularies. CMS innovation center demonstrations direct patients toward mail-order specialty pharmacies stocking extended-release fixed-dose combinations. Tampa and Miami cardiometabolic ambulatory centers deploy pharmacist-led medication therapy management programs.
California
Value-based contracts linking adherence metrics to pharmacy benefit manager rebate structures favor once-daily formulations. The state's hospital-at-home programs restructure post-acute prescribing authority toward remote pharmacy platforms. Los Angeles and San Francisco Bay Area networks participate in CMS quality measure demonstrations accelerating guideline-concordant combination adoption.
New York Metro
Integrated delivery network consolidation locks in volume commitments through multi-year therapeutic contracts. The region's academic medical centers influence national prescribing patterns through protocol dissemination. Manhattan and Long Island specialty clinics concentrate complex polypharmacy patients requiring simplified regimens.
Midwest (Illinois/Ohio/Michigan)
Step-therapy mandates from commercial payers restrict first-line branded combination access, favoring generic antihypertensive monotherapy. Industrial pharmacy benefit management headquarters in Chicago and Minneapolis shape national formulary design. Cleveland Clinic and Mayo Clinic-affiliated networks drive protocol standardization across multi-state systems.
United States Cardiometabolic Fixed-Dose Combinations Market Competitive Landscape
Player mix skews toward multinational pharmaceutical conglomerates with cardiovascular and metabolic heritage. Market structure exhibits tiered concentration with premium-tier innovators, mid-tier generic challengers, and emerging specialty formulation players. Dominant competitive moves include portfolio diversification into obesity-diabetes convergence indications and strategic partnerships for dual-chamber delivery technology.
Among established pharmaceutical conglomerates, Pfizer Inc., AstraZeneca, and Novo Nordisk A/S occupy positions representing distinct strategic archetypes. Pfizer leverages cardiovascular heritage to sustain formulary positioning across integrated delivery networks. AstraZeneca anchors portfolio presence through SGLT2 inhibitor combinations dominating hospital discharge protocols. Novo Nordisk exemplifies differentiation via injectable fixed-dose platforms occupying the obesity-diabetes intersection.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| AstraZeneca |
| Pfizer Inc. |
| Novo Nordisk A/S |
| Sanofi |
| Boehringer Ingelheim International GmbH |
| Sandoz AG |
| Azurity Pharmaceuticals Inc. |
| Novartis AG |
| Others |
Pricing and Supply Chain Analysis
Extended-release formulation substitution for immediate-release antihypertensive combinations redraws manufacturing geography toward specialized contract development organizations while compressing margins on legacy oral tablets through payer preference for adherence-linked rebate structures. This displacement concentrates pricing power with dual-chamber injectable platforms that lock in lifetime value through reduced switching flexibility.
Pricing Analysis
Next-generation dual-chamber injectable devices command substantial premiums over current-generation oral fixed-dose combinations and prior-generation separate-injection regimens. Three-tier pricing structure across premium GLP-1 agonist pairings, standard SGLT2 inhibitor combinations, and economy ACE inhibitor-diuretic generics reflects patent protection intensity and clinical differentiation depth. Cost compression in antihypertensive tiers is intensifying because step-therapy mandates favor generic monotherapy before branded combination authorization. Primary care physicians exhibit highest price sensitivity due to formulary restrictions, while specialty clinics demonstrate lowest sensitivity through protocol-driven care pathway control.
Supply Chain Analysis
Strategic stockpiling of SGLT2 inhibitor active pharmaceutical ingredients dominates sponsor inventory posture given Chinese contract manufacturer concentration and tariff exposure vulnerability. API sourcing draws from China, India, and limited domestic fermentation capacity for peptide-based GLP-1 agonist components. Raw material dependencies center on specialized granulation excipients, dual-chamber injection device components, and cold-chain distribution infrastructure. Single-source vulnerability pervades extended-release formulation technology licensing. Distribution runs through integrated delivery network specialty pharmacies and mail-order platforms that consolidate volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as specialty clinic expansion and hospital-at-home program proliferation create prescriber archetype niches demanding differentiated formulation and service bundling.
For Market Incumbents: Fortify formulary positioning through backward integration into dual-chamber device manufacturing and captive supply of extended-release granulation technology. Patent cliff exposure on legacy antihypertensive combinations demands accelerated pipeline investment toward obesity-diabetes convergence indications. Channel control through exclusive integrated delivery network therapeutic contracts anchors volume defense against complex generic entrants. For New Entrants and Emerging Players: Anchor in Florida Medicare Advantage-heavy counties where capitated arrangements concentrate pharmacy benefit decisions and pharmacist-led medication therapy management programs create protocol entry points. Specialty clinic white space offers lowest competitive density versus saturated primary care channels. Go-to-market execution should prioritize hospital discharge protocol participation through demonstrated readmission reduction evidence packages. For Investors and Strategic Acquirers: IRA Medicare price negotiation implementation reshapes the acquisition landscape by exempting small-molecule combinations with post-2031 approval dates from initial negotiation rounds. Five-to-ten year viability favors late-stage pipeline assets with durable pricing autonomy. Target acquisition archetype: specialty formulation players with dual-chamber device capabilities and integrated delivery network contract infrastructure. Signal to monitor: FDA complex generic bioequivalence guidance evolution determining substitutability barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Chamber Device Manufacturing Scale-Up | Captures lifetime patient value through locked-in delivery platforms satisfying integrated delivery network performance guarantees. |
| Extended-Release Formulation Patent Expansion | Elevates bioequivalence barriers for generic challengers under evolving FDA substitutability standards. |
| Specialty Clinic Partnership Network | Secures protocol-driven prescribing authority through pharmacist-led medication therapy management program integration. |
| Hospital Discharge Protocol Embedding | Locks in post-acute volume commitments through standardized care bundles across Texas Medical Center networks. |
| Obesity-Diabetes Indication Diversification | Penetrates Medicare Part D coverage gap where dual-indication GLP-1 combinations command premium positioning. |
Research Methodology
Cross-validation between formulary database analysis and hospital procurement records anchors the qualitative findings on prescribing pattern shifts. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists combined with secondary validation against FDA filings, CMS Medicare data, ClinicalTrials.gov records, and integrated delivery network contract disclosures. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation ensure segmentation consistency.
Sensitivity analysis across patent expiration scenarios, IRA negotiation implementation timelines, and specialty clinic penetration rates frames the projection envelope. Segmentation dimensions modeled include product type, delivery mode, end user archetype, therapy area, and regional regulatory cluster. CAGRs derive from patient population growth, pricing trajectory assumptions, and share shift dynamics between formulation generations. Forecast inputs incorporate hospital discharge protocol adoption curves and value-based contract performance guarantee structures.
Material uncertainties — regulatory guidance evolution on complex generic bioequivalence, tariff policy shifts affecting API sourcing economics, and integrated delivery network consolidation velocity — sit outside the modeled envelope. Forecasts reflect assumptions on prescriber behavior persistence and payer policy continuity. Revision becomes warranted when FDA substitutability standard stringency or IRA exemption window interpretations cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Hypercholesterolemia Drugs Market
Cardiovascular
Cardiopulmonary Disease Diagnostics and Treatment Market
Cardiovascular
Paroxysmal Supraventricular Tachycardia (PSVT) Market
Cardiovascular
Heart Blocks Treatment Market
Cardiovascular
US Statin Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Global Hyperlipidemia Drugs Market
Cardiovascular
Cardiac Safety Services Market
Cardiovascular
Treatment-Resistant Hypertension Management Market
Cardiovascular
Carotid Stenosis Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Stable Angina Management Market