
 United States Blood Glucose Monitoring Market | 2026-2036
United States Blood Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
United States Blood Glucose Monitoring Market Analytics
Subscription-based leasing for continuous glucose monitor hardware is rewriting capital deployment across the competitive landscape. Dexcom Inc. leverages direct-to-consumer channel control to sustain recurring revenue density in the homecare segment. Abbott Diabetes Care anchors its position through vertically integrated sensor manufacturing that compresses unit economics at scale. Roche Holding AG competes via specialized hospital contracting structures that bundle meter placement with multi-year test strip supply agreements.
Blood glucose monitoring encompasses electrochemical biosensor systems that quantify interstitial or capillary glucose concentration through enzymatic oxidation reactions, typically reporting values in milligrams per deciliter with calibration against laboratory plasma references. These systems serve the clinical management of diabetes mellitus by enabling insulin dosing decisions, hypoglycemia detection, and long-term glycemic control assessment. Continuous glucose monitors now lead product type expansion as real-time data streams integrate with automated insulin delivery platforms, while self-monitoring technology retains dominant volume through pharmacy and retail distribution channels serving cost-sensitive patient populations. Flash glucose monitoring represents the fastest-growing technology segment, capturing patients transitioning from fingerstick routines toward sensor-based workflows without full closed-loop automation.
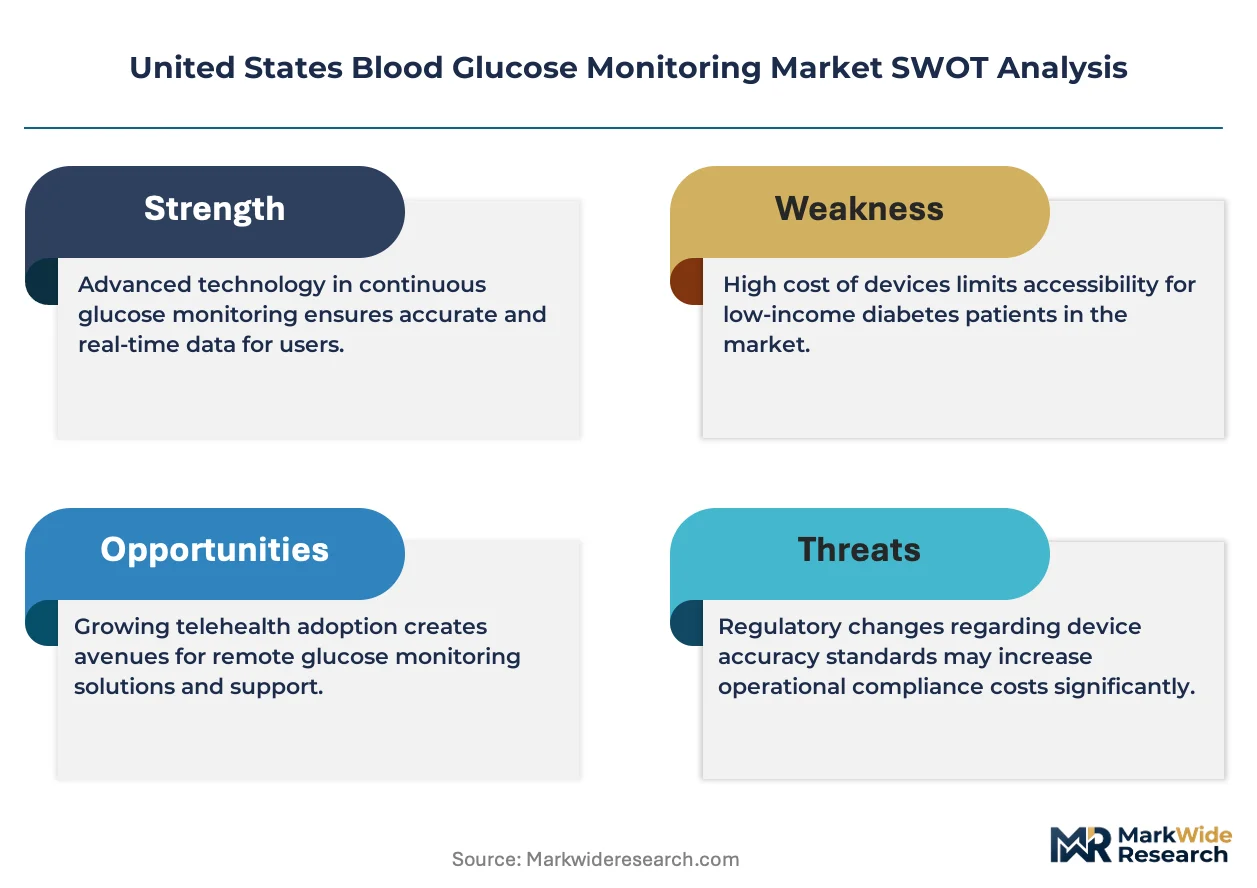
FDA software-as-medical-device oversight and CMS national coverage determinations for therapeutic continuous glucose monitoring jointly shape reimbursement access and predicate device requirements for market entry. The Centers for Medicare & Medicaid Services maintains stringent beneficiary eligibility criteria that tie device qualification to intensive insulin therapy regimens, directly filtering addressable demand. Stakeholders must monitor evolving HIPAA interoperability mandates and state-level telehealth parity laws that determine whether remote glucose data transmission qualifies for synchronous clinical reimbursement.
Market Dynamics
Algorithm-based glucose prediction is virtualizing diagnostic workflows across the United States, compressing the boundary between consumer wellness devices and regulated medical equipment as FDA's software-as-medical-device framework matures.
Growth Catalysts
- CMS Therapeutic CGM Coverage:Medicare national coverage determinations for continuous glucose monitoring expand beneficiary access among Type 2 diabetes patients on intensive insulin therapy, directly enlarging the addressable patient base.
- Texas Demographic Concentration:The state's aging population and managed care penetration create concentrated demand pull for home-based monitoring devices through Medicare Advantage channel density.
- Interoperability Mandates:HIPAA-aligned data portability requirements enable seamless glucose data transmission between patient devices and electronic health records, reducing clinical workflow friction.
Market Restraints
- Sensor Manufacturing Concentration:Domestic production of electrochemical biosensor membranes relies on specialized polymer supply chains concentrated in single-source contract manufacturers, creating input vulnerability.
- Beneficiary Eligibility Filters:CMS intensive insulin therapy requirements exclude non-insulin-dependent Type 2 patients from therapeutic CGM reimbursement, structurally capping penetration rates.
- Calibration Drift Limitations:Enzymatic glucose oxidase sensors exhibit measurable signal degradation over 10-14 day wear periods, requiring replacement cycles that constrain unit economics.
Strategic Opportunities
- Florida Retirement Corridor:The state's Medicare-enrolled senior concentration remains underpenetrated by pharmacy-based CGM counseling services, creating white space for retail clinic integration.
- Telehealth Parity Tailwinds:State-level laws mandating synchronous reimbursement for remote glucose monitoring sessions enable new clinical service revenue streams beyond device sales.
- Algorithm-Hardware Convergence:Predictive glucose forecasting models paired with insulin dosing recommendation engines create regulatory pathways for integrated therapeutic platforms.
Industry Challenges
- Biocompatibility Engineering Talent:Scarce expertise in subcutaneous sensor materials science prolongs product development timelines for extended-wear formulations.
- 510(k) Software Documentation:FDA's evolving expectations for algorithm validation datasets demand expanded clinical trial footprints, compressing capital efficiency for new entrants.
- Legacy Meter Data Migration:Health system integration of decades of fingerstick glucose records into continuous monitoring platforms creates technical debt and workflow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Blood Glucose Monitoring Market |
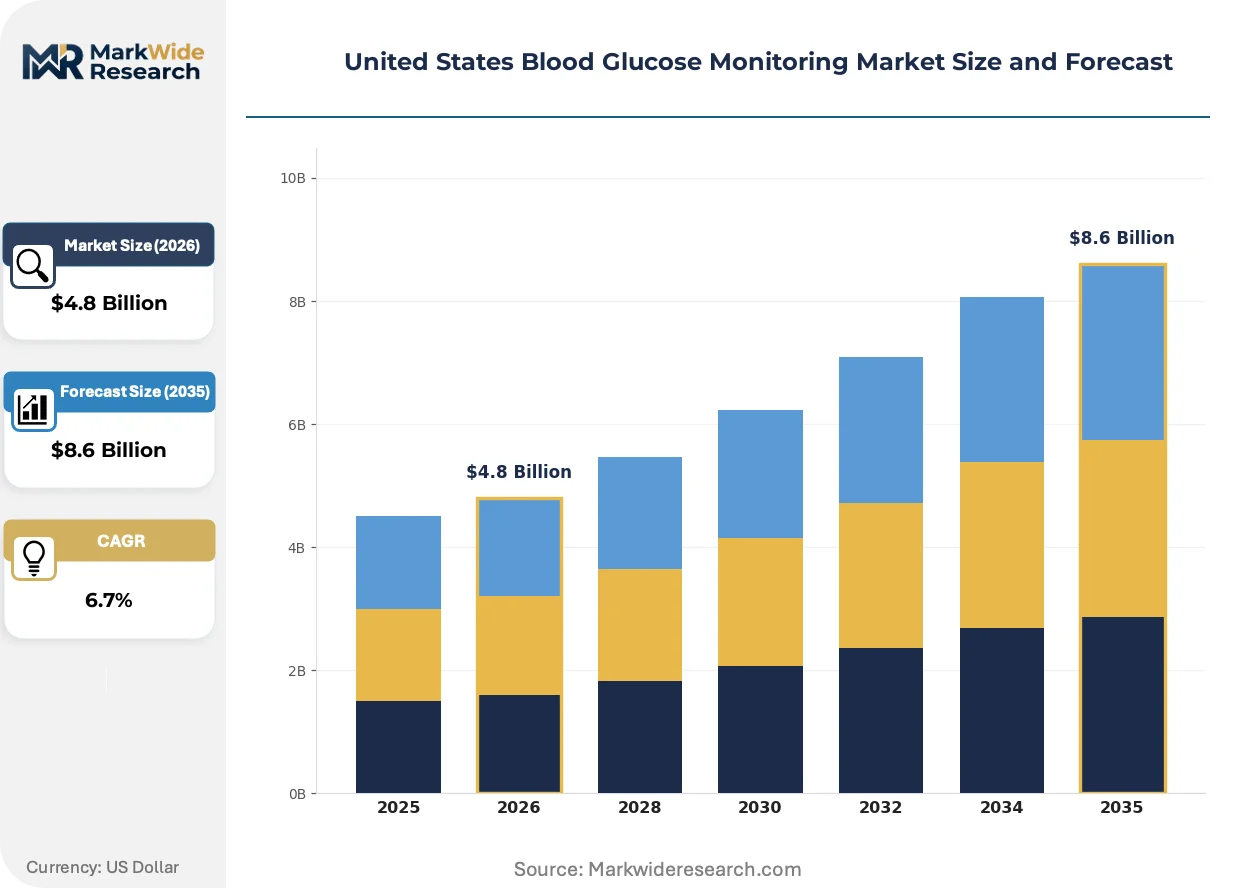
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Test Strips, Continuous Glucose Monitors, Lancets End User: Hospitals, Homecare, Diabetes Clinics, Pharmacies Technology: Self-Monitoring, Continuous Monitoring, Flash Glucose Monitoring, Smart Meters Distribution Channel: Online, Retail, Supermarkets, Medical Supply Stores |
| Companies Covered | Roche Holding AG, Medtronic, Abbott Diabetes Care, Senseonics, ARKRAY Inc., Dexcom Inc., Ascensia Diabetes Care, i-SENS Inc., LifeScan Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Blood Glucose Monitoring Market Evolving Landscape
Real-time glucose data streams are restructuring how patients, payers, and providers coordinate diabetes management, shifting value capture from discrete test strip transactions toward integrated monitoring ecosystems.
Non-invasive optical glucose sensing is virtualizing the measurement interface, replacing interstitial fluid extraction with spectroscopic approaches. Research consortia at California academic medical centers are advancing multispectral imaging prototypes toward clinical validation. This technology is virtualizing the physical sensor entirely, potentially eliminating consumable economics that currently dominate revenue models.
FDA's software-as-medical-device guidance for machine learning-enabled glucose prediction is tightening predicate device requirements for algorithm-based clearance. Manufacturers must now submit locked algorithm versions with predetermined change control plans, increasing documentation burden. The homecare segment is responding by consolidating vendor relationships with established 510(k) holders possessing validated quality management systems.
Subscription leasing arrangements for continuous glucose monitor hardware are displacing capital purchase models in the Medicare Advantage channel. Pharmacy benefit managers are bundling sensor supply with clinical coaching services, unbundling the traditional device-reagent economic linkage. California's integrated delivery networks are most advanced in this transition, negotiating multi-year population health contracts that align sensor deployment with HEDIS quality metrics.
United States Blood Glucose Monitoring Market Segmentation
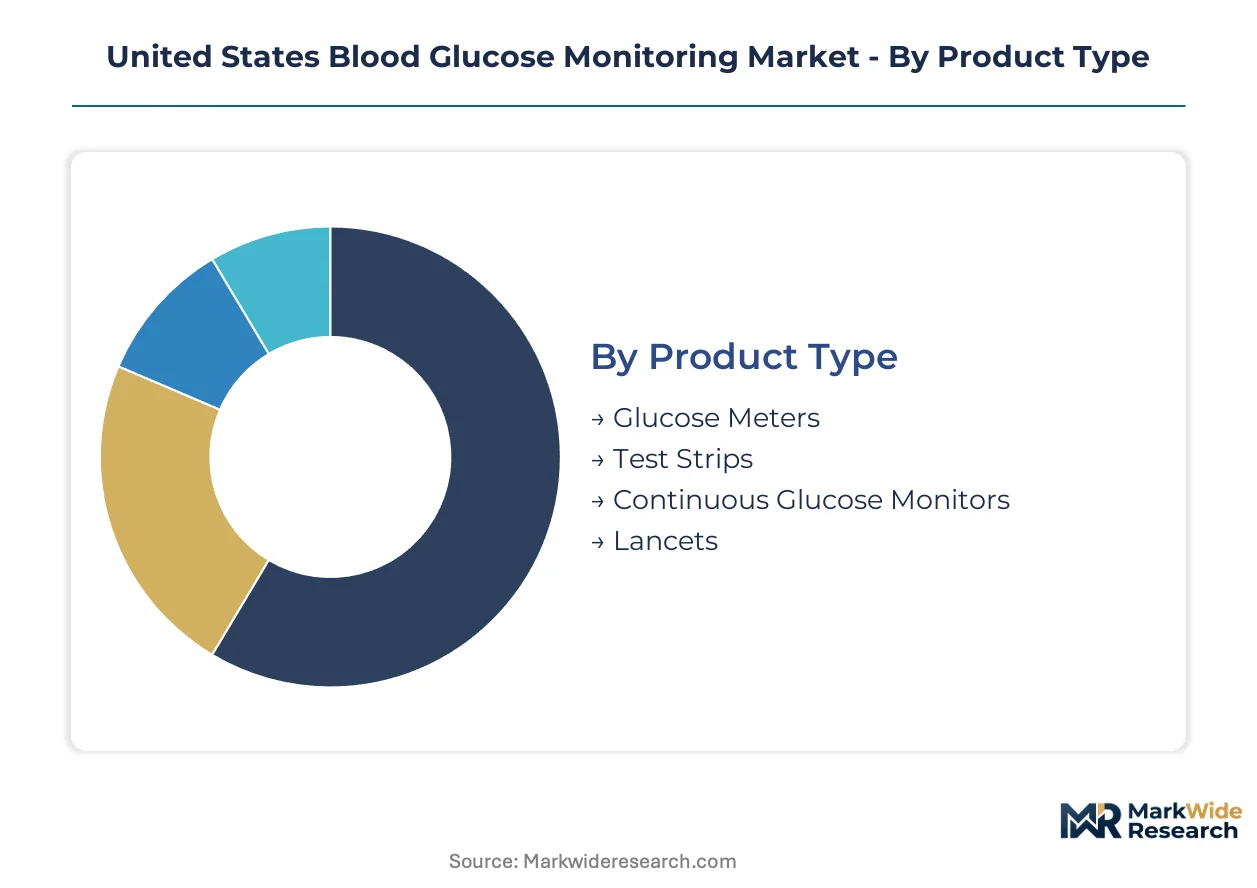
Segmentation in the United States blood glucose monitoring market reveals how reimbursement pathways, patient acuity, and distribution economics partition addressable demand across distinct technology and channel configurations. Understanding these divisions illuminates where capital deployment, regulatory strategy, and patient acquisition investments concentrate.
Product Type:
Cost tier differentiation separates capital-intensive continuous systems from consumable-dependent episodic testing modalities.
- Glucose Meters:Handheld electrochemical devices measuring capillary glucose via enzymatic test strips. Demand concentrates in Medicare Advantage plans across Texas and Florida, where pharmacy benefit managers bundle meter placement with multi-year strip supply agreements to lock in recurring revenue density.
- Test Strips:Disposable biosensor membranes utilizing glucose oxidase chemistry for single-use capillary sampling. Volume leadership persists through retail pharmacy channels serving cost-sensitive Type 2 populations in California's integrated delivery networks, though reimbursement compression constrains margin expansion.
- Continuous Glucose Monitors:Interstitial fluid sensors transmitting real-time glucose data to receiver devices or smartphones.
- Lancets:Spring-loaded or manual devices for capillary blood extraction preceding meter-based testing.
Test strips command the established base. The steepest expansion runs through continuous glucose monitors.
End User:
Application context determines device specification, regulatory classification, and reimbursement coding requirements.
- Hospitals:Acute care settings requiring FDA-cleared devices with enhanced accuracy specifications for insulin dosing in critical care units. Demand concentrates in California's academic medical centers where interoperability mandates drive integration with electronic health record systems.
- Homecare:Patient-managed environments where Medicare therapeutic CGM coverage has expanded beneficiary access among intensive insulin therapy patients. Texas and Florida retirement corridors show concentrated penetration through Medicare Advantage channel density.
- Diabetes Clinics:Specialized outpatient facilities integrating continuous monitoring data into care coordination workflows.
- Pharmacies:Community-based retail locations providing episodic testing supplies and emerging CGM counseling services.
Homecare settings capture volume leadership. Diabetes clinics are gaining share fastest through value-based contracting alignment.
Technology:
Measurement modality defines the boundary between regulated medical devices and consumer wellness products under FDA's evolving software-as-medical-device framework.
- Self-Monitoring:Fingerstick-based capillary glucose testing with discrete point-in-time readings. Demand persists among non-insulin-dependent Type 2 patients excluded from CMS therapeutic CGM reimbursement, particularly in cost-sensitive populations across retail pharmacy channels.
- Continuous Monitoring:Interstitial sensors providing real-time glucose trends and predictive alerts. CMS national coverage determinations for therapeutic use are reshaping qualification pathways, with beneficiary eligibility tied to intensive insulin therapy documentation.
- Flash Glucose Monitoring:Sensor-based systems requiring manual scan for glucose retrieval without continuous transmission.
- Smart Meters:Connected devices integrating cellular or Bluetooth data transmission with dosing decision support applications.
Self-monitoring retains the installed base. Flash glucose monitoring represents the steepest expansion trajectory as patients transition from fingerstick routines toward sensor-based workflows.
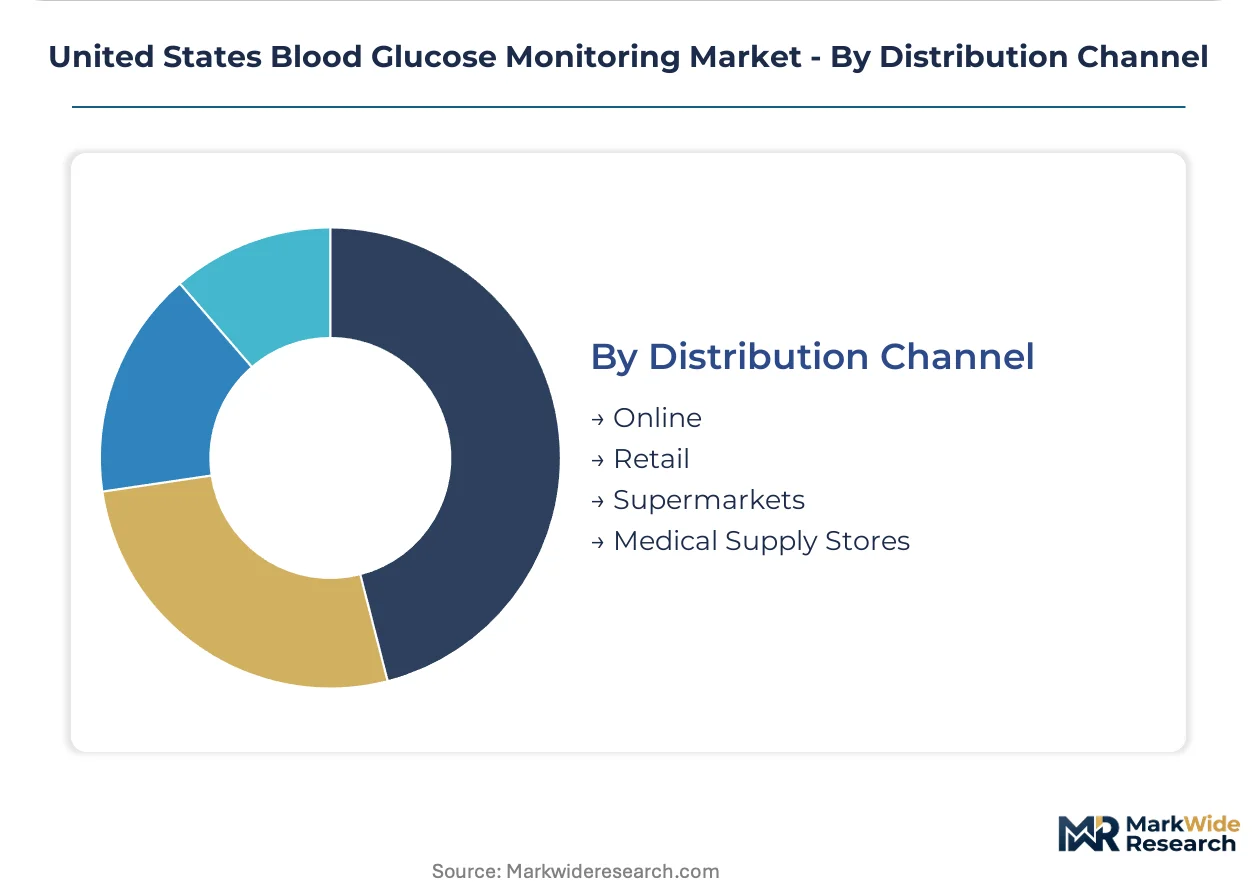
Distribution Channel:
Channel economics shape patient acquisition costs, reimbursement capture efficiency, and subscription model viability.
- Online:Direct-to-consumer platforms enabling subscription-based sensor replenishment with automated prior authorization processing. California's integrated delivery networks are most advanced in negotiating multi-year population health contracts through this channel.
- Retail:Brick-and-mortar pharmacies and big-box stores providing immediate product access and clinical counseling. Texas and Florida show concentrated Medicare Advantage penetration through retail clinic integration.
- Supermarkets:Mass merchant locations with limited clinical service attachment for episodic supply purchasing.
- Medical Supply Stores:Durable medical equipment distributors serving Medicare fee-for-service beneficiaries with documentation-intensive reimbursement workflows.
Retail channels anchor volume. Online distribution is expanding most quickly as pharmacy benefit managers consolidate vendor relationships with established 510(k) holders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States blood glucose monitoring market operates with minimal import dependency for finished devices, though specialized electrochemical biosensor membranes and polymer substrates concentrate in domestic contract manufacturing clusters. Texas, Florida, and California collectively absorb the majority of Medicare-reimbursed device volume.
Texas
Medicare Advantage enrollment density and managed care penetration drive concentrated demand for home-based continuous glucose monitors in the Dallas-Fort Worth and Houston metropolitan corridors. CMS therapeutic CGM coverage determinations filter beneficiary eligibility through intensive insulin therapy documentation requirements. San Antonio anchors a growing cluster of pharmacy-based CGM counseling services targeting retirement community populations.
Florida
The state's Medicare-enrolled senior concentration creates sustained pull for subscription-based sensor replenishment models across the Tampa-St. Petersburg and Miami-Fort Lauderdale corridors. State-level telehealth parity laws mandate synchronous reimbursement for remote glucose monitoring sessions, enabling new clinical service revenue streams. Orlando medical supply distributors are consolidating vendor relationships with established 510(k) holders to streamline prior authorization workflows.
California
Integrated delivery networks in Los Angeles and San Francisco negotiate multi-year population health contracts aligning sensor deployment with HEDIS quality metrics. FDA's software-as-medical-device guidance for algorithm-based glucose prediction tightens predicate device requirements for machine learning-enabled clearance pathways. Stanford and UCSF academic medical centers advance multispectral imaging prototypes toward clinical validation for non-invasive optical glucose sensing.
Illinois
Chicago's hospital systems require FDA-cleared devices with enhanced accuracy specifications for critical care insulin dosing, driving interoperability integration with electronic health record platforms. HIPAA-aligned data portability mandates enable seamless glucose data transmission between patient devices and provider systems. The Midwest's durable medical equipment distributors serve Medicare fee-for-service beneficiaries with documentation-intensive reimbursement workflows.
New York
Greater New York's diabetes clinics integrate continuous monitoring data into value-based care coordination workflows, capturing fastest-growing share through contracting alignment. State-level regulations governing remote patient monitoring reimbursement determine whether asynchronous glucose data review qualifies for clinical payment. Rochester and Buffalo pharmacy benefit managers are bundling sensor supply with clinical coaching services, unbundling traditional device-reagent economics.
United States Blood Glucose Monitoring Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated sensor manufacturers and direct-to-consumer channel controllers. Three strategic archetypes dominate: full-stack CGM platforms owning hardware, software, and data layers; diversified diagnostics conglomerates leveraging hospital contracting scale; and specialized sensor technology licensors supplying white-label components. Competitive moves concentrate on multi-year population health contract negotiation and algorithm-hardware convergence for integrated therapeutic platforms.
Within the full-stack CGM tier, Dexcom Inc. and Abbott Diabetes Care occupy positions exemplifying direct-to-consumer channel control and vertically integrated sensor manufacturing respectively. Roche Holding AG anchors the hospital-contracting archetype through bundled meter placement and test strip supply agreements. Among specialized continuous monitoring innovators, Senseonics represents extended-wear implantable sensor technology, while Medtronic exemplifies convergence between glucose monitoring and automated insulin delivery platforms.
| Leading Market Players |
|---|
| Roche Holding AG |
| Medtronic |
| Abbott Diabetes Care |
| Senseonics |
| ARKRAY Inc. |
| Dexcom Inc. |
| Ascensia Diabetes Care |
| i-SENS Inc. |
| LifeScan Inc. |
| Others |
Value Network & Pricing Analysis
The I-35 freight corridor linking Texas manufacturing clusters to California distribution hubs concentrates glucose sensor logistics costs, amplifying price spreads between Medicare Advantage bulk purchasers and retail pharmacy cash buyers while compressing margins for mid-tier distributors caught between these buyer archetypes.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels in the United States blood glucose monitoring market. Price differentiation rests on FDA clearance tier and interoperability certification with electronic health record systems. Cost compression in the standard tier is intensifying because pharmacy benefit managers are consolidating vendor relationships with established 510(k) holders. Medicare fee-for-service beneficiaries exhibit highest price sensitivity due to documentation-intensive reimbursement workflows, while integrated delivery networks in California demonstrate lowest sensitivity through multi-year population health contract structures.
Supply Chain Analysis
Domestic contract manufacturers in Massachusetts and Minnesota hold concentrated capacity for electrochemical biosensor membrane production. Raw material dependencies center on specialized polymer substrates from Germany, glucose oxidase enzymes from Denmark, and adhesive chemistries from Japan. Single-source vulnerability runs through the polymer supply chain, where specialized fluoropolymer formulations lack qualified secondary suppliers. Distribution runs through durable medical equipment distributors serving Medicare beneficiaries, pharmacy benefit manager direct contracting, and retail pharmacy channels for episodic supply purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Medicare Advantage plan consolidation, with three national carriers now controlling reimbursement access for over sixty percent of therapeutic CGM beneficiaries in Texas and Florida retirement corridors.
For Market Incumbents: Entrench market position through backward integration into sensor polymer manufacturing and captive supply of glucose oxidase enzymes. Dexcom Inc.'s direct-to-consumer channel control faces threat from Abbott Diabetes Care's vertically integrated sensor economics; priority investment rests on algorithm-hardware convergence for integrated therapeutic platforms with automated insulin delivery compatibility. For New Entrants and Emerging Players: Pursue white-space opportunity in Florida's pharmacy-based CGM counseling services, where retail clinic integration remains underpenetrated despite concentrated Medicare-enrolled senior populations. Target non-insulin-dependent Type 2 patients excluded from CMS therapeutic CGM reimbursement through flash glucose monitoring transitions. Go-to-market angle centers on state-level telehealth parity law compliance for synchronous remote monitoring reimbursement. For Investors and Strategic Acquirers: FDA's software-as-medical-device guidance for machine learning-enabled glucose prediction reshapes the acquisition landscape, elevating quality management system maturity and locked algorithm validation datasets as due diligence priorities. Long-term viability favors platforms with demonstrated 510(k) clearance velocity and hospital system interoperability integration. Acquisition target archetype: specialized sensor technology licensors with extended-wear biocompatibility engineering capabilities. Signal to watch: CMS national coverage determination expansion beyond intensive insulin therapy eligibility criteria.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Locked algorithm versions with predetermined change control plans satisfy evolving predicate device requirements for clearance pathways. |
| Hospital System Partnership | Interoperability integration with Epic and Cerner electronic health record platforms enables acute care insulin dosing workflow capture. |
| Reimbursement Strategy | Prior authorization automation with Medicare Advantage plans reduces beneficiary access friction for therapeutic CGM qualification. |
| Software Companion Development | Predictive glucose forecasting applications paired with dosing recommendation engines create integrated therapeutic platform differentiation. |
| CE Marking Pathway | European conformity assessment for non-invasive optical glucose sensing prototypes expands addressable market beyond United States regulatory jurisdiction. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, CMS national coverage determination records, and hospital procurement contract disclosures preceded structured interviews with biomedical engineers, GPO contracts managers, Medicare Advantage plan formulary directors, and pharmacy benefit manager vendor relations leads. Secondary validation drew from American Diabetes Association clinical practice guidelines, SEC 10-K filings of publicly traded device manufacturers, and state-level telehealth parity law compilations. Bottom-up patient population estimates triangulated against top-down Medicare expenditure data.
Assumptions held fixed include CMS beneficiary eligibility criteria for therapeutic CGM coverage, HIPAA interoperability mandate implementation timelines, and FDA software-as-medical-device guidance stability across the projection horizon. Segmentation dimensions modeled encompass product type, end user setting, technology modality, and distribution channel. CAGRs were derived from logarithmic trend fitting of historical Medicare device volume data and payer-reported sensor utilization rates. Industry-specific forecast inputs incorporated biosensor wear period degradation curves and pharmacy benefit manager vendor consolidation patterns.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rate indexing or durable medical equipment competitive bidding program expansion would shift the trajectory. Forecasts reflect assumptions about regulatory pathway stability and sensor manufacturing cost curves. Quarterly review of CMS national coverage determination updates and FDA algorithm validation dataset expectations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Spain Self-Monitoring Blood Glucose Devices Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market