
 APAC Insulin Infusion Pumps Market | 2026-2036
APAC Insulin Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Insulin Infusion Pumps Market Outlook
Aftermarket service revenue is rewriting how manufacturers capture lifetime value from device deployments. Medtronic leverages its extensive Asia-Pacific service infrastructure to lock in recurring calibration and consumable contracts. Insulet Corporation anchors its growth strategy on direct-to-patient subscription models that minimize hospital channel dependence. Tandem Diabetes Care competes through software-enabled feature upgrades that extend product lifecycles without hardware replacement.
An insulin infusion pump is a programmable electromechanical device that delivers rapid-acting insulin through a subcutaneous cannula at calibrated basal rates and patient-triggered bolus doses, typically maintaining glycemic control within 70-180 mg/dL target ranges for type 1 and insulin-dependent type 2 diabetes patients. Portable pumps retain the largest installed base across APAC due to physician familiarity and reimbursement alignment, though patch pumps are gaining fastest adoption among pediatric and adolescent populations seeking discretion. Closed loop systems with continuous glucose monitoring integration command premium positioning as endocrinologists in Japan, South Korea, and Australia prioritize automated insulin delivery that reduces hypoglycemic events.
Japan's PMDA and Australia's TGA enforce stringent electromagnetic compatibility and biocompatibility standards that filter out lower-cost competitors, while India's CDSCO has streamlined medical device rules to accelerate market entry for CE-marked and FDA-cleared products. China's NMPA now requires localized clinical data for closed-loop systems, creating a dual-track approval burden that favors multinationals with regional trial capabilities. Stakeholders must weigh regulatory capital requirements against the margin compression risk from domestic challengers in China and India that are developing simplified open-loop alternatives.
Market Dynamics
Closed-loop automation with continuous glucose monitoring integration is compressing hardware replacement cycles while locking patients into recurring consumable ecosystems across Japan, South Korea, and Australia.
Growth Catalysts
- PMDA's accelerated approval pathway:Japan's pharmaceutical regulator has streamlined review timelines for hybrid closed-loop systems, cutting time-to-market for algorithm-enabled pumps by nearly half compared to conventional device classifications.
- Home care migration:Endocrinology clinics across India's tier-1 cities are deploying remote monitoring infrastructure that shifts patient management from hospital wards to residential settings, expanding addressable patient populations.
- Sensor-augmented pump therapy:Integration of real-time glucose data streams with predictive insulin dosing algorithms is reducing hypoglycemic events and driving physician preference for automated delivery platforms.
Market Restraints
- Biocompatibility testing costs:Australia's TGA and Japan's PMDA require extensive cytotoxicity and sensitization studies for subcutaneous cannula materials, adding twelve to eighteen months to product development timelines.
- Single-source sensor dependency:APAC markets rely heavily on glucose sensor imports from North American and European suppliers, exposing distributors to freight volatility and customs clearance bottlenecks.
- Smartphone-controlled dosing limitations:Regulatory bodies in China and India restrict fully automated dosing decisions without physician confirmation, constraining algorithm autonomy for closed-loop systems.
Strategic Opportunities
- Vietnam and Indonesia expansion:Underpenetrated diabetes care infrastructure in Southeast Asian markets offers first-mover positioning for patch pump formats suited to humid climates and limited refrigeration access.
- Subscription-based consumable bundling:Direct-to-patient replenishment models bypass fragmented hospital procurement channels and capture lifetime value through locked-in insulin cartridge and infusion set contracts.
- CE-marked fast-track entry:India's CDSCO mutual recognition agreements with European notified bodies allow accelerated market access for devices already cleared under EU MDR, compressing regulatory capital requirements.
Industry Challenges
- Algorithm validation talent scarcity:Clinical engineering teams capable of training and validating machine learning models for glucose prediction remain concentrated in Tokyo, Seoul, and Sydney, constraining localization efforts.
- NMPA clinical data mandates:China's national medical products regulator now requires indigenous trial cohorts for closed-loop systems, forcing duplicative study designs that strain regional R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Insulin Infusion Pumps Market |
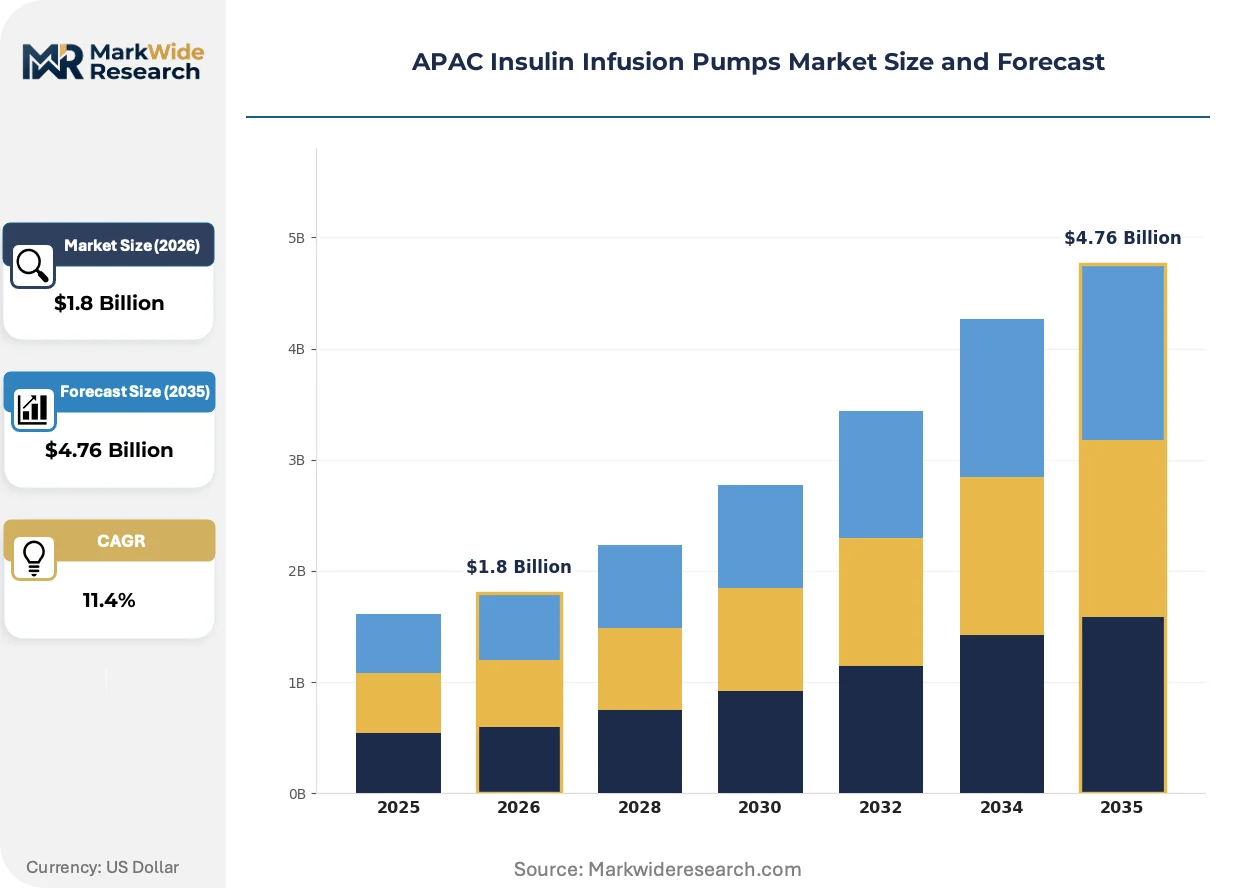
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Pumps, Patch Pumps, Wearable Pumps, Implantable Pumps End User: Hospitals, Home Care Settings, Diabetes Clinics, Long-Term Care Facilities Technology: Closed Loop Systems, Open Loop Systems, Continuous Glucose Monitoring Integration, Remote Monitoring Distribution Channel: Pharmacies, Online Retailers, Medical Device Distributors, Direct Sales |
| Companies Covered | Medtronic, Insulet Corporation, Tandem Diabetes Care, Ypsomed, Roche, SOOIL Development, Terumo, Animas Corporation, Cellnovo, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Insulin Infusion Pumps Market Strategic Shifts
Software-defined functionality is decoupling clinical value from hardware refresh cycles, enabling manufacturers to monetize feature upgrades through firmware releases rather than device replacements.
Cloud-connected pump platforms are virtualizing the traditional patient-clinic relationship. Adolescent users in Japan and South Korea are migrating to smartphone-integrated systems that enable parental remote monitoring and automated data sharing with endocrinology teams. This architecture is compressing the addressable market for standalone personal computer-based download systems while expanding recurring revenue from data analytics subscriptions.
China's NMPA has introduced localized cybersecurity standards for wireless-enabled medical devices, mandating encryption protocols and domestic data residency for cloud-connected pumps. Manufacturers must re-architect data flows and establish mainland server infrastructure, favoring multinationals with existing Chinese IT partnerships over smaller entrants. The policy is accelerating compliance investments while filtering out software-only competitors lacking hardware manufacturing footprints.
Hospital procurement departments across India are unbundling device acquisition from consumable supply contracts, shifting toward competitive tendering for insulin cartridges and infusion sets. This fragmentation is eroding bundled pricing power for incumbent manufacturers and creating entry points for domestic challengers with simplified open-loop alternatives. The pattern is most pronounced in Mumbai and Delhi's public hospital networks, where cost-containment mandates override brand loyalty.
APAC Insulin Infusion Pumps Market Segmentation
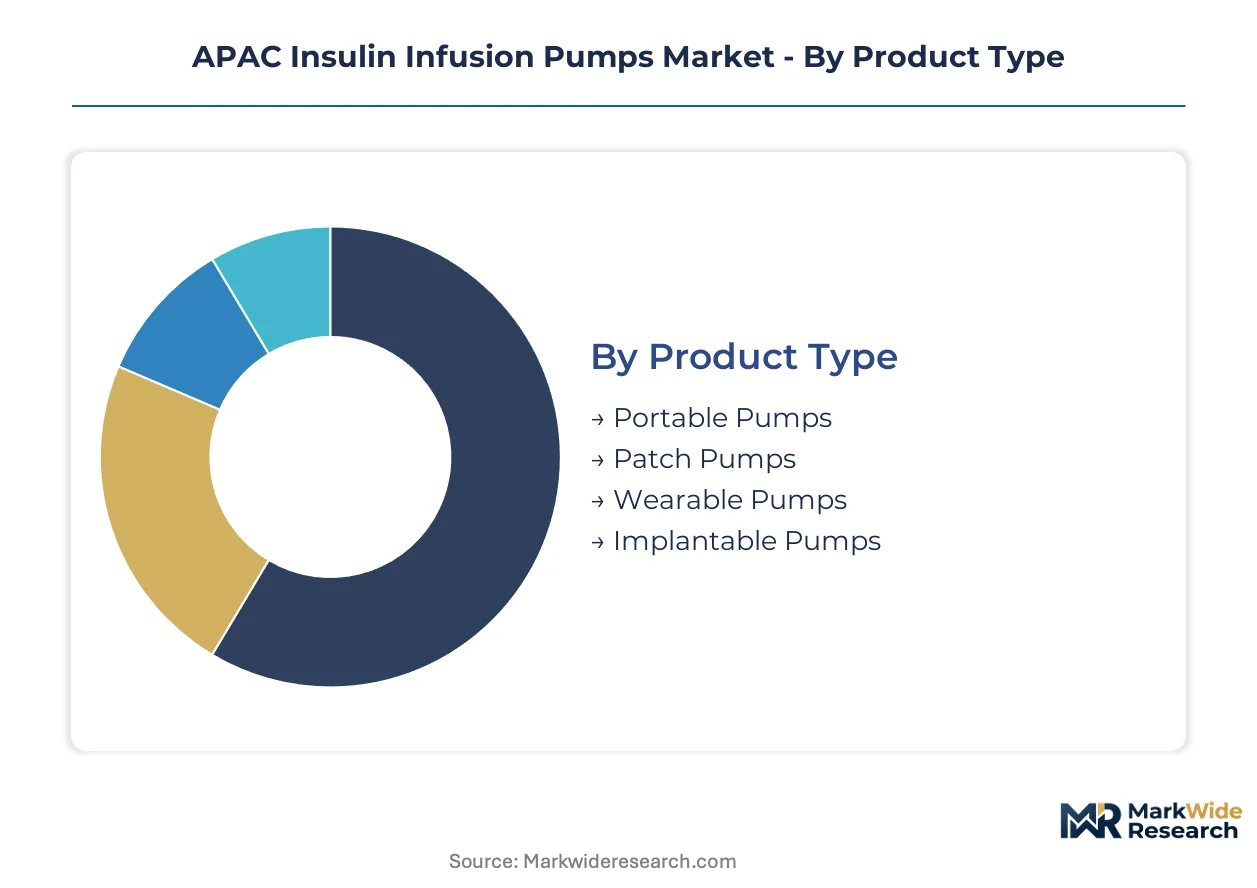
Insulin infusion pump segmentation reveals divergent service economics across device architectures. Patch and wearable formats demand specialized calibration support, while portable pumps leverage established technician networks. Each category shapes recurring revenue potential and channel strategy differently.
Product Type:
After-sales-service intensity varies sharply across pump architectures, with tethered systems requiring ongoing cannula replacement training and patch formats demanding adhesive troubleshooting support.
- Portable Pumps:Traditional electromechanical devices with external tubing and detachable infusion sets dominate reimbursement schedules across Japan, South Korea, and Australia. Physician familiarity in tertiary hospitals sustains installed base retention despite bulkier form factors.
- Patch Pumps:Tubeless adhesive-mounted devices integrate insulin reservoir and cannula in disposable units, attracting adolescent populations in Tokyo and Seoul seeking discretion. Humid climate performance in Southeast Asia drives demand for sweat-resistant adhesive formulations.
- Wearable Pumps:Compact belt-worn or clothing-integrated systems balance reservoir capacity with mobility, finding traction among working-age diabetics in Mumbai and Bangalore's corporate health programs.
- Implantable Pumps:Surgically placed intraperitoneal devices deliver insulin directly to the liver, restricted to specialized metabolic surgery centers in Osaka and Sydney due to invasive placement requirements.
Portable pumps hold the largest share; momentum sits with patch pumps.
End User:
Cost tier stratification separates acute-care capital equipment procurement from direct-to-patient subscription models in residential settings.
- Hospitals:Inpatient glycemic management programs in tertiary centers across Delhi and Chennai utilize tethered pumps for perioperative insulin delivery, with procurement governed by centralized medical device committees.
- Home Care Settings:Remote monitoring infrastructure expansion across India's tier-1 cities shifts patient management from clinical wards to residential environments, expanding addressable populations beyond hospital catchment areas.
- Diabetes Clinics:Specialized endocrinology practices in Tokyo, Seoul, and Melbourne concentrate algorithm-enabled pump prescribing, with physician training programs determining technology diffusion rates.
- Long-Term Care Facilities:Nursing homes and assisted living centers in Japan's aging prefectures adopt simplified open-loop systems with staff-administered dosing protocols.
Home care settings are expanding most quickly; hospitals retain the highest equipment value per bed.
Technology:
Volume concentration favors sensor-augmented platforms, while margin accrues to fully automated delivery systems with predictive algorithm licensing.
- Closed Loop Systems:Hybrid artificial pancreas platforms integrate continuous glucose monitors with predictive insulin dosing algorithms, commanding premium positioning as PMDA-accelerated approvals reduce time-to-market for algorithm-enabled devices in Japan.
- Open Loop Systems:Patient-directed basal rate programming with manual bolus calculation retains dominant volume across price-sensitive markets, particularly in India's public hospital networks where cost-containment mandates override automation preferences.
- Continuous Glucose Monitoring Integration:Real-time glucose data streaming to pump controllers enables predictive low-glucose suspend functionality, with sensor calibration requirements locking patients into recurring consumable ecosystems.
- Remote Monitoring:Cloud-connected platforms enabling parental oversight and clinician data access are gaining fastest adoption among pediatric populations in South Korea and urban Japan.
Open loop systems maintain installed base dominance; closed loop systems show the steepest expansion trajectory.
Distribution Channel:
Customer type fragmentation separates institutional procurement through medical device distributors from direct-to-patient subscription models bypassing hospital channels entirely.
- Pharmacies:Community and hospital-affiliated retail outlets across Australia and Japan handle insulin cartridge refills and infusion set replacements, with pharmacist counseling requirements varying by prefecture and state regulations.
- Online Retailers:E-commerce platforms serve price-comparison shoppers for consumable replenishment, though pump hardware sales remain restricted to prescription-verified channels in most jurisdictions.
- Medical Device Distributors:Specialized logistics networks manage capital equipment sales to hospital procurement departments, with bundled service contracts determining vendor selection in India's competitive tendering environment.
- Direct Sales:Manufacturer-owned field forces and telemedicine-integrated subscription programs target affluent urban diabetics in Seoul, Singapore, and Sydney with concierge onboarding and remote calibration support.
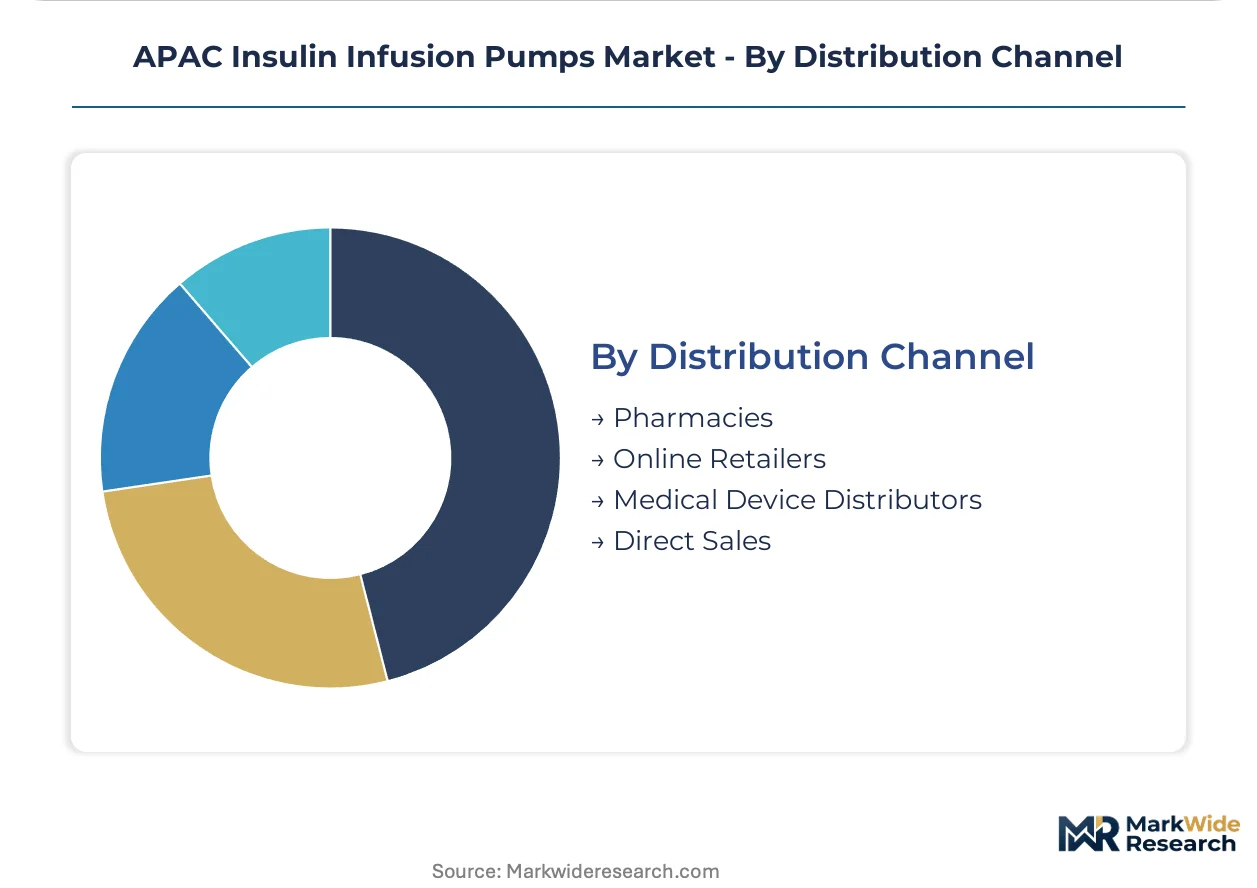
Medical device distributors capture the highest hardware transaction values; direct sales channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across APAC. India's tier-1 cities demand low-cost open-loop alternatives, while Japan and Australia absorb premium closed-loop systems with minimal reimbursement friction.
Japan
Tokyo's endocrinology clinics drive closed-loop adoption among aging diabetics seeking automated glycemic control. PMDA's accelerated approval pathway for hybrid artificial pancreas systems compresses regulatory timelines by nearly half versus conventional device classifications. Osaka's specialized metabolic surgery centers concentrate implantable pump placements for refractory cases.
China
Shanghai and Beijing's corporate health programs subsidize wearable pumps for working-age diabetics in technology and finance sectors. NMPA mandates localized clinical trial cohorts for closed-loop systems, forcing duplicative study investments that favor multinationals with established regional R&D infrastructure. Yangtze River Delta medical device clusters host cybersecurity compliance centers for cloud-connected pump data residency requirements.
India
Mumbai and Delhi's public hospital networks unbundle device procurement from consumable contracts, eroding bundled pricing power for incumbents. CDSCO mutual recognition agreements with European notified bodies accelerate market entry for CE-marked products. Bangalore's diabetes clinic networks expand remote monitoring infrastructure that shifts patient management from wards to residential settings.
South Korea
Seoul's adolescent populations drive patch pump demand for discretion in school and social environments. MFDS aligns electromagnetic compatibility standards with international benchmarks while maintaining stringent biocompatibility requirements for subcutaneous materials. Busan-Ulsan's medical device distributors specialize in direct-to-patient subscription models that bypass fragmented hospital procurement channels.
Australia
Melbourne and Sydney's endocrinologists prioritize sensor-augmented pump therapy with predictive low-glucose suspend functionality. TGA enforces extensive cytotoxicity and sensitization studies for cannula materials, filtering out lower-cost competitors. New South Wales and Victoria concentrate cloud-connected platform adoption enabling parental remote monitoring for pediatric users.
APAC Insulin Infusion Pumps Market Competitive Environment
Multinational device manufacturers and regional specialists split the market along technology-tier lines. The vendor base concentrates around closed-loop automation capabilities in premium segments while fragmenting across simplified open-loop alternatives in price-sensitive markets. Three archetypes dominate: integrated diabetes care conglomerates with full-stack sensor-pump platforms, patch pump specialists with direct-to-patient subscription models, and emerging domestic challengers with cost-optimized open-loop designs. Competitive moves center on consumable ecosystem lock-in and regulatory fast-track exploitation through CE-marked and FDA-cleared product portfolios.
Among integrated diabetes care conglomerates, Medtronic anchors the premium tier through extensive Asia-Pacific service infrastructure that captures recurring calibration and consumable contracts. Insulet Corporation exemplifies the patch pump specialist archetype with direct-to-patient subscription models minimizing hospital channel dependence. Tandem Diabetes Care occupies a software-enabled positioning where firmware upgrades extend product lifecycles without hardware replacement.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Tandem Diabetes Care |
| Ypsomed |
| Roche |
| SOOIL Development |
| Terumo |
| Animas Corporation |
| Cellnovo |
| Others |
Value Chain & Pricing Dynamics
Single-source glucose sensor dependency from North American and European suppliers determines both tiered pricing spreads across premium closed-loop and economy open-loop systems and the elongated supply chain structure that buffers APAC distributors against customs clearance volatility.
Pricing Analysis
Consumable replenishment contracts drive lifetime value capture more than hardware margins. Three-tier pricing structure across premium closed-loop, standard sensor-augmented, and economy open-loop levels separates reimbursement-aligned portable pumps from direct-pay patch formats. Price differentiation rests on PMDA-accelerated approval status and bundled calibration service intensity. Cost compression in India's public hospital networks is intensifying because procurement committees unbundle device acquisition from consumable supply. Home care subscribers in Seoul and Sydney show lowest price sensitivity; tier-1 city public hospitals in Mumbai and Delhi exhibit highest.
Supply Chain Analysis
Tariff exposure between glucose sensor manufacturing clusters in the United States and Germany and APAC distribution hubs dominates supply chain risk architecture. Component sourcing draws from semiconductor foundries in Taiwan, medical-grade polymer processors in Japan, and precision motor suppliers in South Korea. Raw material dependencies include subcutaneous cannula polymers, lithium-ion cell arrays, and glucose oxidase sensor membranes. Single-source vulnerability concentrates in continuous glucose monitor imports. Distribution runs through specialized medical device distributors for hospital procurement and direct-to-patient subscription platforms for residential settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue layers expand faster than hardware sales as calibration contracts and consumable subscriptions lock in patient lifetime value across Japan, South Korea, and Australia.
For Market Incumbents: Harden consumable ecosystem lock-in through exclusive sensor-pump compatibility protocols that raise switching costs for patients already on automated delivery platforms. Deepen backward integration into glucose sensor manufacturing to reduce freight volatility exposure from trans-Pacific supply lanes. Prioritize certification investment for PMDA-accelerated pathway exploitation before domestic challengers achieve algorithm validation capabilities. For New Entrants and Emerging Players: Vietnam and Indonesia's underpenetrated diabetes clinic infrastructure offers first-mover positioning for patch pump formats engineered for humid climate performance and limited cold-chain logistics. Target adolescent populations in Ho Chi Minh City and Jakarta seeking discretion over traditional portable pumps. Pursue CE-marked fast-track entry through India's CDSCO mutual recognition agreements to compress regulatory capital requirements versus de novo approval pathways. For Investors and Strategic Acquirers: NMPA's localized clinical data mandate for closed-loop systems reshapes the acquisition landscape toward multinationals with established China trial infrastructure. Long-term viability favors integrated diabetes care platforms with full-stack sensor-pump capabilities over hardware-only manufacturers facing margin compression. Watch algorithm validation talent concentration in Tokyo, Seoul, and Sydney as inflection indicator for localization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Regulatory Fast-Track | PMDA-accelerated approvals compress time-to-market for algorithm-enabled pumps in Japan. |
| Direct-to-Patient Subscription Model | Bypasses fragmented hospital procurement channels in India's competitive tendering environment. |
| Sensor Manufacturing Backward Integration | Captive glucose sensor production insulates against trans-Pacific freight volatility. |
| Cloud Platform Cybersecurity Compliance | NMPA data residency mandates favor multinationals with mainland server infrastructure. |
| Adolescent-Focused Patch Pump Development | Discretion requirements in Seoul and Tokyo school environments drive premium positioning. |
Study Parameters
The analysis maps portable pump, patch pump, wearable pump, and implantable pump architectures, each validated through endocrinologists, hospital procurement managers, biomedical engineers, and diabetes clinic network operators. Primary interviews with these stakeholders combined with secondary validation from PMDA filings, CDSCO device approvals, hospital procurement databases, and GPO contracts. Bottom-up patient population sizing and top-down manufacturer revenue triangulation anchored volume estimates.
Assumptions held reimbursement alignment for portable pumps and regulatory pathway timelines fixed while varying closed-loop algorithm adoption rates and domestic challenger entry intensity across the analysis window. Segmentation dimensions modeled include product architecture, end-user setting, technology tier, and distribution channel. CAGRs derived from installed base growth, replacement cycle compression, and consumable attach rate expansion. Forecast inputs incorporated PMDA approval velocity and NMPA clinical data mandate compliance costs.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by simplified open-loop domestic manufacturers in China and India would shift outcomes. Macroeconomic deviation, regulatory pathway acceleration or delay, and breakthrough closed-loop algorithm performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Hyperinsulinemia Hypoglycaemia Treatment Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Type-1 Diabetes Treatment Market