
 Philippines Diabetes Care Devices Market | 2026-2036
Philippines Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Diabetes Care Devices Market Analytics
The Philippine FDA's updated medical device registration framework is broadening compliance requirements for glucose monitoring imports. Abbott Laboratories leverages its FreeStyle portfolio to anchor the continuous glucose monitor segment through established pharmacy networks. Medtronic sustains its insulin pump presence via specialized diabetes clinics in Metro Manila and Cebu. Dexcom competes on real-time data integration with local telemedicine platforms.
Diabetes care devices encompass instruments for glucose measurement, insulin delivery, and metabolic monitoring, typically operating through electrochemical sensor technology with measurement precision within 15% of laboratory reference values for home-use systems. Their primary purpose is enabling glycemic control outside clinical settings to reduce diabetic complication incidence. Blood glucose monitors occupy the largest installed base among product types, though continuous glucose monitors capture expanding share as wearable technology adoption deepens among tech-enabled individuals. Smart devices and mobile applications within the technology dimension represent the fastest structural expansion, driven by payer interest in remote patient monitoring cost reductions.
The Philippine FDA, the Department of Health's Bureau of Health Devices and Technology, and the ASEAN Medical Device Directive harmonization framework collectively shape product standards, import licensing timelines, and post-market surveillance obligations for device manufacturers. CDSCO-aligned reference standards for sensor accuracy influence which overseas suppliers secure market authorization. Stakeholders must monitor evolving reimbursement negotiations between the Philippine Health Insurance Corporation and continuous glucose monitor suppliers, as coverage decisions will reshape patient access economics and competitive positioning across the archipelago.
Market Dynamics
The Philippine Food and Drug Administration's tightened medical device registration pathways are compressing import timelines and forcing glucose monitoring suppliers to front-load compliance investments before market entry.
Growth Catalysts
- Home care expansion:Self-monitoring tools are penetrating provincial diabetes centers in Cebu and Davao as telemedicine infrastructure spreads beyond Metro Manila.
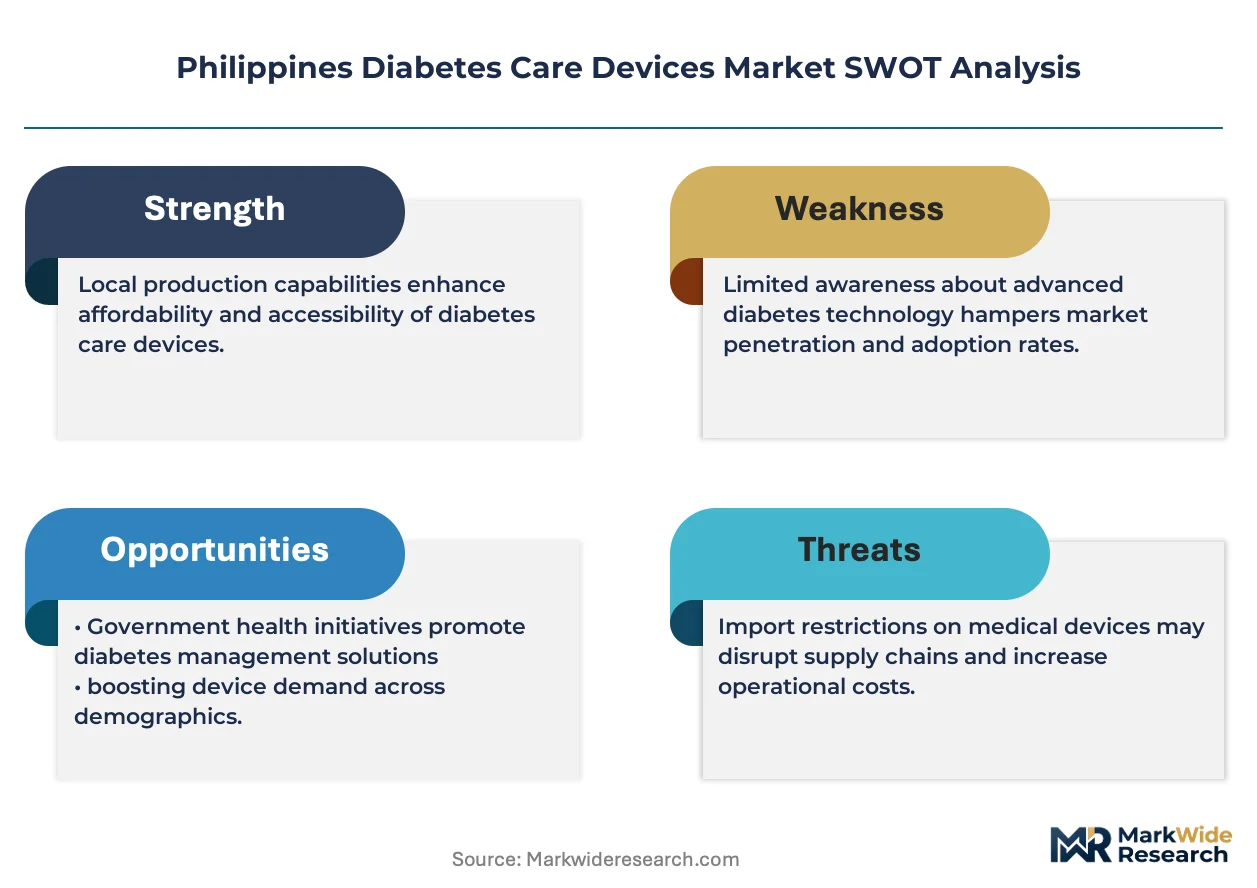
- ASEAN Medical Device Directive harmonization:The framework is accelerating quality benchmarks for imported glucose monitoring systems and reducing duplicate testing burdens for regional suppliers.
- Electrochemical sensor maturation:Measurement precision improvements within 15% of laboratory reference values are validating home-use systems for clinical decision support.
Market Restraints
- Import licensing friction:CDSCO-aligned reference standards for sensor accuracy are filtering out overseas suppliers unable to meet Philippine FDA validation protocols.
- Reimbursement uncertainty:Negotiations between the Philippine Health Insurance Corporation and continuous glucose monitor suppliers remain unresolved, constraining patient access economics.
- Metro Manila demand concentration:Private hospital networks in the capital capture disproportionate device volumes, leaving provincial markets underserved.
Strategic Opportunities
- Provincial diabetes center buildout:Emerging facilities in Cebu and Davao represent underpenetrated channels for wearable glucose monitoring deployment.
- Remote patient monitoring integration:Smart devices and mobile applications are converging with local telemedicine platforms to enable real-time glycemic data transmission.
- Post-market surveillance data monetization:Manufacturers can leverage Philippine FDA surveillance obligations to generate real-world evidence for payer negotiations.
Industry Challenges
- Regulatory talent scarcity:Specialized expertise in ASEAN Medical Device Directive technical documentation and Philippine FDA registration pathways commands premium compensation.
- Legacy system integration complexity:Hospital information systems in provincial networks require customized middleware to accept continuous glucose monitor data streams.
- Calibration infrastructure gaps:Maintaining electrochemical sensor accuracy across tropical humidity conditions demands localized quality control investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Diabetes Care Devices Market |
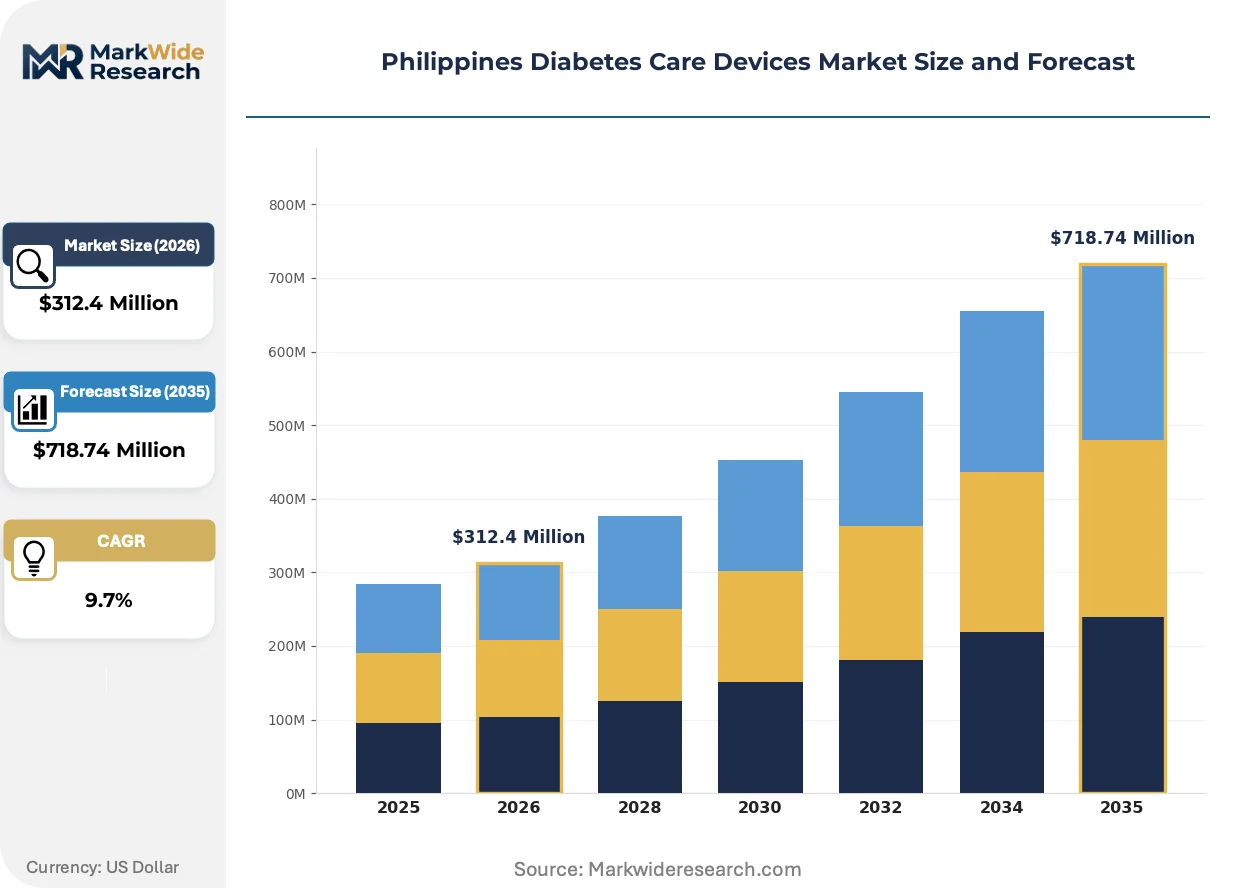
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Blood Glucose Monitors, Continuous Glucose Monitors, Lancets Application: Home Care, Hospitals, Clinics, Diagnostic Labs Technology: Smart Devices, Wearable Technology, Mobile Applications, Digital Health Solutions End User: Individuals, Healthcare Providers, Payers, Caregivers |
| Companies Covered | Sanofi, Insulet Corporation, Medtronic, Becton Dickinson, Dexcom, Abbott Laboratories, Novo Nordisk A/S, Eli Lilly and Company, F. Hoffmann-La Roche Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Diabetes Care Devices Market Evolving Landscape
Wearable technology adoption is deepening among tech-enabled individuals across the archipelago, compressing the traditional blood glucose monitor installed base while elevating data integration expectations.
Continuous glucose monitoring systems are rewriting competitive positioning in the Philippine market. These wearable devices transmit real-time glycemic data to smartphones and clinical dashboards. Tech-enabled patients in Metro Manila's private hospital networks are adopting these systems at accelerating rates. The technology is rewriting how endocrinologists manage Type 1 diabetes, shifting from episodic fingerstick measurements to continuous trend analysis and predictive alerting.
The Philippine FDA's updated medical device registration framework is broadening compliance requirements for glucose monitoring imports. The policy mandates additional clinical validation studies for novel sensor technologies and tightens post-market adverse event reporting timelines. Continuous glucose monitor suppliers face the steepest compliance burden, with several international manufacturers extending their Philippine launch timelines to complete supplementary Philippine-based accuracy trials.
Patient self-management behavior is pivoting toward data-driven glycemic control as wearable device penetration deepens. Traditional pharmacy-based glucose test strip purchases are fragmenting into app-mediated subscription models for sensor supplies. This shift is most visible among employed professionals in Metro Manila who prioritize seamless data sharing with their endocrinologists over lowest-cost monitoring options.
Philippines Diabetes Care Devices Market Segmentation
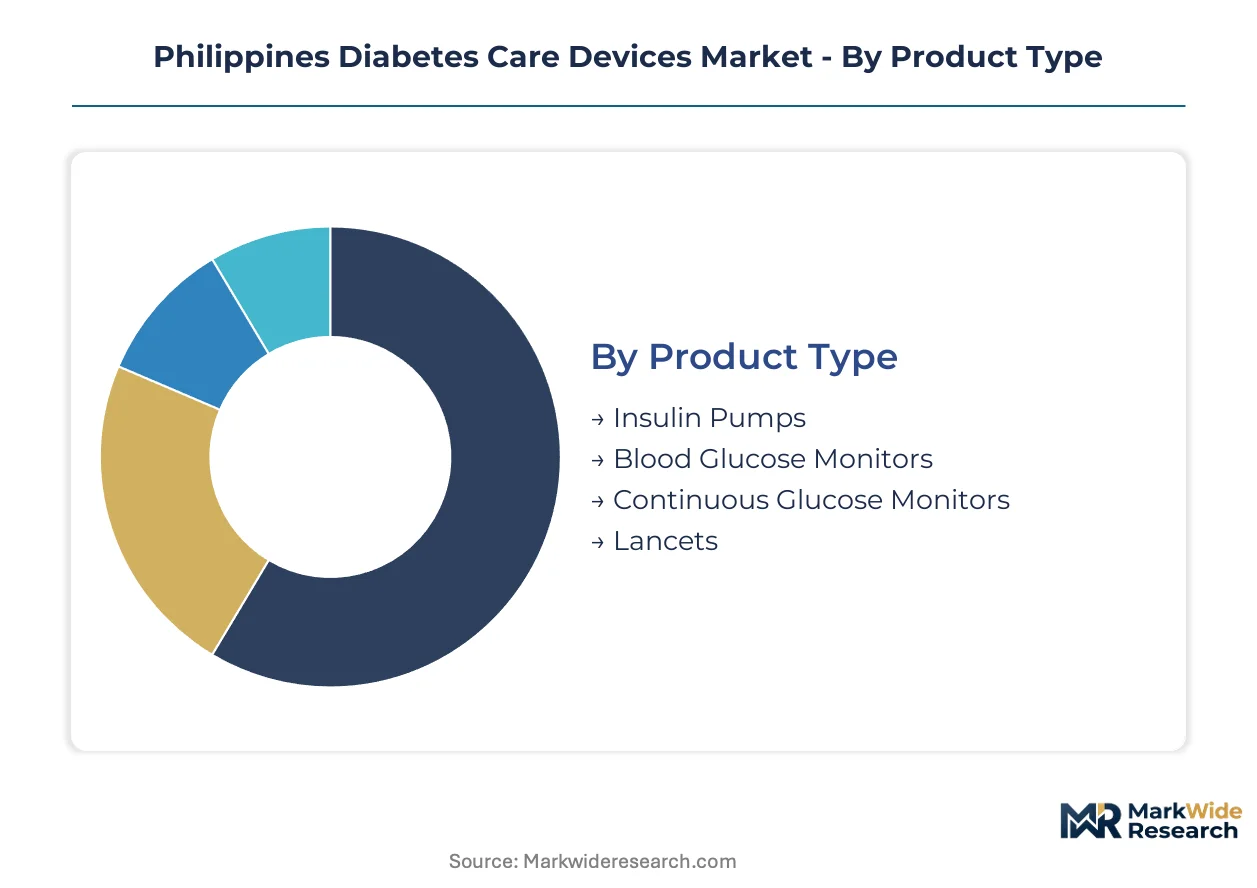
Segmentation in the Philippine diabetes care devices market reveals how purchasing power, care setting infrastructure, and digital readiness stratify demand across the archipelago. Buyers weigh upfront device costs against long-term complication avoidance, creating distinct preference clusters between Metro Manila's private hospitals and provincial home-care adopters.
Product Type:
Cost tier structures purchasing decisions, with patients and facilities trading measurement frequency against capital outlay and consumable burdens.
- Blood Glucose Monitors:Electrochemical sensor systems measuring capillary glucose through test strip chemistry dominate installed base across Philippine households. Demand concentrates in Metro Manila pharmacy networks and emerging provincial diabetes centers in Cebu and Davao, driven by Philippine Health Insurance Corporation partial reimbursement for strip-based monitoring.
- Continuous Glucose Monitors:Wearable subcutaneous sensors transmitting real-time glycemic data to smartphones are gaining share among tech-enabled professionals in private hospital networks. Metro Manila endocrinology clinics report accelerating patient requests for predictive alerting capabilities and seamless telemedicine platform integration.
- Insulin Pumps:Programmable infusion devices delivering basal-bolus insulin regimens serve Type 1 diabetes populations through specialized diabetes clinics.
- Lancets:Single-use penetrating devices for capillary blood sampling represent the lowest-cost consumable category with commodity pricing dynamics.
Blood glucose monitors lead on scale; continuous glucose monitors lead on momentum.
Application:
Volume distribution tracks healthcare infrastructure maturity, with facility-based care retaining dominance while home settings expand fastest.
- Home Care:Self-monitoring tools penetrating provincial markets leverage spreading telemedicine infrastructure beyond Metro Manila. Cebu and Davao diabetes centers are channeling home-use device volumes as remote patient monitoring reduces clinic visit burdens for stable patients.
- Hospitals:Private hospital networks in Metro Manila capture disproportionate device volumes for acute glycemic management and perioperative monitoring, though provincial networks remain underserved relative to diabetes prevalence.
- Clinics:Outpatient endocrinology practices in urban centers concentrate insulin pump initiation and continuous glucose monitor training services.
- Diagnostic Labs:Centralized laboratory settings deploy calibrated reference systems for device accuracy validation and HbA1c correlation studies.
Hospitals lead on scale; home care leads on momentum.
Technology:
Customer type differentiation separates digitally fluent patients seeking autonomous management from institutionally anchored procurement.
- Smart Devices:Connected glucose meters with cloud data synchronization are expanding fastest among employed professionals prioritizing endocrinologist data sharing.
- Wearable Technology:Skin-adhered sensors with smartphone pairing dominate continuous glucose monitoring adoption in Metro Manila's tech-enabled demographic.
- Mobile Applications:Software platforms aggregating glycemic data, meal logging, and medication tracking support self-management behavior change.
- Digital Health Solutions:Integrated ecosystems combining hardware, software, and clinical dashboard access serve payer remote monitoring initiatives.
Wearable technology leads on scale; smart devices lead on momentum.
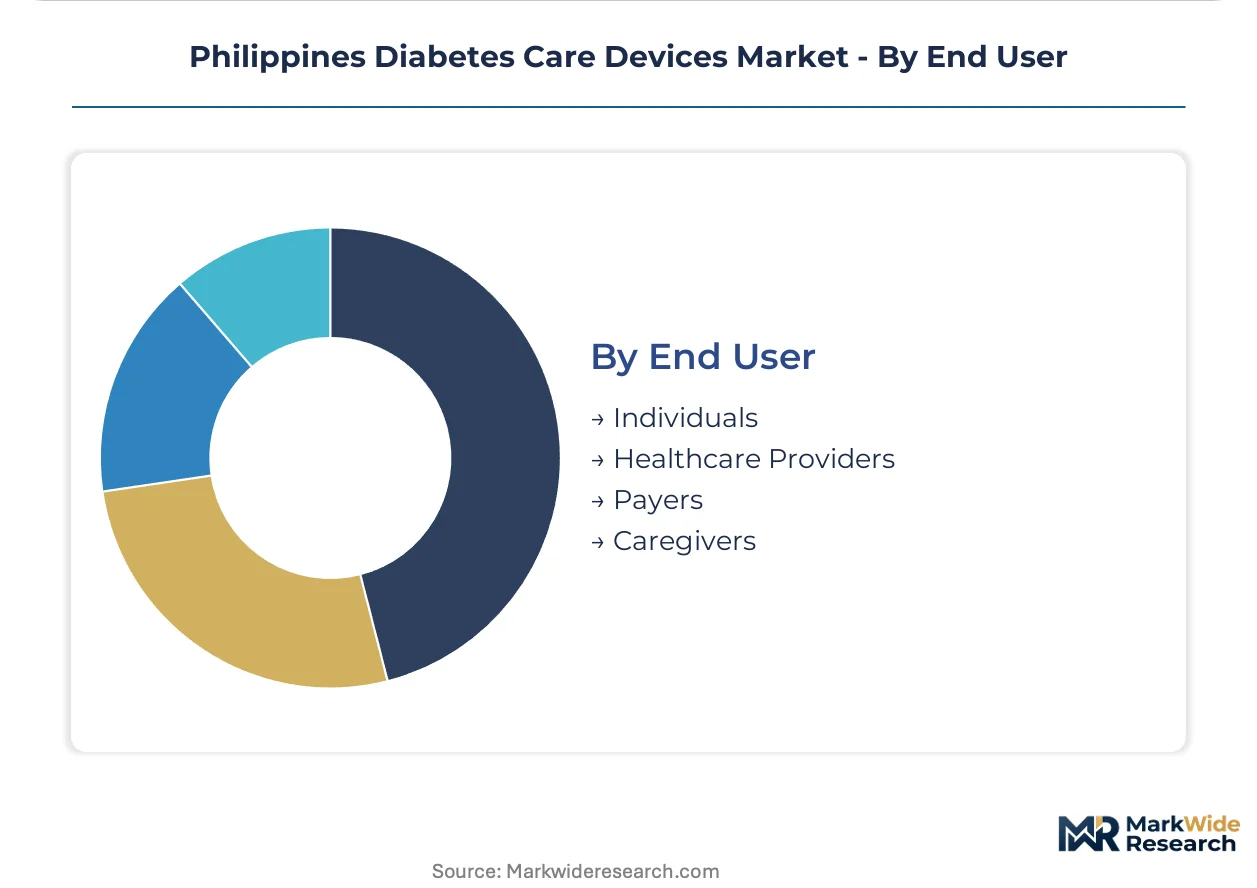
End User:
Margin concentration varies sharply, with individual out-of-pocket purchases commanding premium pricing versus institutional procurement.
- Individuals:Out-of-pocket purchasers in Metro Manila's private sector drive premium device adoption and subscription-based sensor replenishment models.
- Healthcare Providers:Hospital and clinic procurement departments negotiate volume pricing for blood glucose monitors and lancet supplies.
- Payers:Philippine Health Insurance Corporation reimbursement negotiations with continuous glucose monitor suppliers remain unresolved, constraining patient access economics.
- Caregivers:Family members managing diabetes for elderly or pediatric patients prioritize simplicity and alarm reliability over advanced analytics.
Individuals lead on scale; payers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized endocrinology talent concentrates in Metro Manila's private hospital corridors, anchoring sophisticated diabetes management protocols that cascade outward to provincial networks.
Metro Manila
Private hospital networks in Makati and Quezon City drive continuous glucose monitor adoption among employed professionals seeking seamless telemedicine integration. The Philippine FDA's tightened medical device registration pathways compress import timelines for established glucose monitoring suppliers. Endocrinology clinics in Ortigas Center report accelerating patient requests for real-time data sharing capabilities.
Central Visayas
Emerging diabetes centers in Cebu City channel home-use device volumes as remote patient monitoring reduces clinic visit burdens for stable patients. The Department of Health's provincial health office coordinates with PhilHealth on partial reimbursement protocols for strip-based monitoring. Mandaue City's medical device distributors are expanding warehouse capacity to serve the Visayas archipelago.
Davao Region
Provincial diabetes facilities in Davao City leverage spreading telemedicine infrastructure to penetrate previously underserved populations. The Philippine FDA's ASEAN Medical Device Directive harmonization reduces duplicate testing burdens for regional suppliers seeking market authorization. Davao del Sur's emerging clinic networks represent underpenetrated channels for wearable glucose monitoring deployment.
Calabarzon
Industrial corridor workers in Laguna and Cavite generate demand for employer-sponsored diabetes screening programs and connected monitoring devices. The Bureau of Health Devices and Technology enforces CDSCO-aligned reference standards for sensor accuracy validation. Biñan's pharmaceutical distribution hubs are consolidating logistics for glucose test strip supply chains.
Western Visayas
Iloilo City's expanding healthcare infrastructure attracts diabetes device suppliers seeking alternatives to Metro Manila saturation. PhilHealth regional offices negotiate coverage terms for insulin pump therapy with specialized diabetes clinics. Bacolod's private hospital networks are upgrading hospital information systems to accept continuous glucose monitor data streams.
Philippines Diabetes Care Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Philippine diabetes care devices landscape. The vendor base stratifies between multinational manufacturers with established regulatory compliance infrastructure and regional distributors serving price-sensitive provincial markets. Three archetypes dominate: integrated glucose monitoring system suppliers, specialized insulin delivery device manufacturers, and digital health platform integrators. Capacity expansion and strategic partnerships with local telemedicine providers represent the dominant competitive vectors reshaping market access.
Among the integrated system suppliers, Abbott Laboratories and Medtronic occupy positions anchoring distinct technology segments, while Dexcom exemplifies the data integration specialist archetype competing on real-time platform connectivity. Sanofi and Novo Nordisk A/S represent pharmaceutical-origin manufacturers extending into delivery device portfolios. These named entities illustrate how competitive positioning in the Philippine market increasingly depends on regulatory navigation capabilities and provincial distribution reach rather than product specifications alone.
| Leading Market Players |
|---|
| Sanofi |
| Insulet Corporation |
| Medtronic |
| Becton Dickinson |
| Dexcom |
| Abbott Laboratories |
| Novo Nordisk A/S |
| Eli Lilly and Company |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Network & Pricing Analysis
PhilHealth reimbursement negotiations anchor pricing power for continuous glucose monitor suppliers while out-of-pocket purchasers in Metro Manila's private sector absorb premium device costs without institutional bargaining leverage.
Pricing Analysis
Subscription-based sensor replenishment models dominate continuous glucose monitoring, separating premium wearable tiers from standard blood glucose monitor pricing. Price differentiation rests on Philippine FDA registration tier and telemedicine platform integration depth. Cost compression in the standard tier intensifies because regional distributors compete for provincial pharmacy networks. Individual out-of-pocket purchasers in Metro Manila show lowest price sensitivity, while provincial home-care adopters prioritize lowest-cost strip-based monitoring.
Supply Chain Analysis
Specialized electrochemical sensor manufacturing expertise concentrates in Malaysia, Singapore, and South Korea, with Philippine distributors serving as downstream fulfillment nodes. Raw material dependencies span medical-grade adhesives, noble metal electrode coatings, and biocompatible polymers. Single-source vulnerability runs through Malaysian sensor foundries serving multiple ASEAN markets. Distribution runs through Makati-based medical device distributors with provincial satellite warehouses in Cebu and Davao.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines diabetes care devices market compounds steadily as home-care expansion and wearable technology adoption create durable demand tailwinds across the archipelago.
For Market Incumbents: Hedge against reimbursement uncertainty by diversifying revenue between institutional procurement and direct-to-consumer subscription channels. Deepen backward integration into sensor calibration infrastructure to address tropical humidity accuracy challenges. Prioritize Philippine FDA post-market surveillance data generation to strengthen PhilHealth negotiation positions. For New Entrants and Emerging Players: Begin with provincial diabetes centers in Davao and Iloilo, where hospital information system upgrades create integration opportunities for connected monitoring devices. Target employed professionals in Calabarzon's industrial corridors through employer-sponsored screening programs. Deploy telemedicine platform partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Regional medical device distributors with established Philippine FDA compliance infrastructure are the most active acquirer in this space. Long-term viability centers on provincial network expansion and reimbursement resolution rather than technology differentiation. Watch PhilHealth coverage decisions for continuous glucose monitors as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| PhilHealth Reimbursement Strategy | Coverage resolution for continuous glucose monitors would reshape patient access economics across Metro Manila and provincial networks. |
| Provincial Distribution Expansion | Warehouse capacity additions in Cebu and Davao reduce delivery friction for emerging diabetes centers in Central and Southern Philippines. |
| Telemedicine Platform Integration | Seamless data transmission to clinician dashboards differentiates wearable glucose monitoring from legacy blood glucose meters. |
| Philippine FDA Registration Pathway | Accelerated ASEAN Medical Device Directive harmonization compresses market entry timelines for regional suppliers. |
| Sensor Calibration Infrastructure | Localized quality control investments address tropical humidity effects on electrochemical measurement accuracy. |
Research Methodology
Coverage spans Metro Manila, Central Visayas, Davao Region, Calabarzon, and Western Visayas, with primary inputs from each. The approach combines structured interviews with endocrinologists, hospital procurement managers, medical device distributors, and Philippine FDA regulatory affairs specialists with secondary validation from hospital procurement databases, GPO contracts, PhilHealth reimbursement filings, and ASEAN Medical Device Directive implementation records. Bottom-up patient population estimates and top-down device shipment data undergo triangulation to anchor market sizing.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include product type, application setting, technology tier, and end-user archetype, with additional granularity on provincial versus Metro Manila adoption patterns. CAGRs derive from patient prevalence projections, device replacement cycles, and technology substitution curves. Forecast inputs incorporate PhilHealth reimbursement scenario analysis and Philippine FDA registration timeline assumptions.
Several conditions sit outside the modeled scope, including abrupt PhilHealth policy reversals, Philippine FDA registration moratoriums, and macroeconomic shocks affecting private hospital capital expenditure. Forecasts reflect documented assumptions about reimbursement trajectory and regulatory harmonization pace. Material deviation in PhilHealth coverage decisions or ASEAN Medical Device Directive implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Brazil Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
France Insulin Infusion Pump Market