
 Volumetric Arc Therapy Market | 2026-2036
Volumetric Arc Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Volumetric Arc Therapy Market Analytics
Germany is reshaping European VMAT capacity through accelerated linac installations and proton therapy center expansions. Varian Medical Systems leverages its Halcyon platform to dominate automated arc delivery workflows across German university hospitals. Elekta sustains competitive pressure through its Unity MR-linac integration, while Siemens Healthineers anchors regional service infrastructure with native engineering support.
Volumetric Arc Therapy delivers modulated radiation through continuous gantry rotation while the multi-leaf collimator shapes the beam dynamically, typically completing treatment in single or multiple arcs under two minutes. Linear accelerators remain the dominant technology platform, though cone beam CT integration represents the fastest-expanding capability segment as clinics demand real-time anatomical verification. Treatment planning software captures concentrated margin pools due to recurring licensing models and AI-driven plan optimization modules.
FDA 21 CFR Part 1020 governs US radiological health performance standards for linac systems, while EMA coordinates European radiation device safety assessments through notified body frameworks. The EU Medical Device Regulation intensifies clinical evidence requirements for software-driven planning systems, reshaping market access timelines for new entrants. Stakeholders must monitor reimbursement parity between VMAT and conventional IMRT across national health technology assessment bodies to anticipate volume shifts.
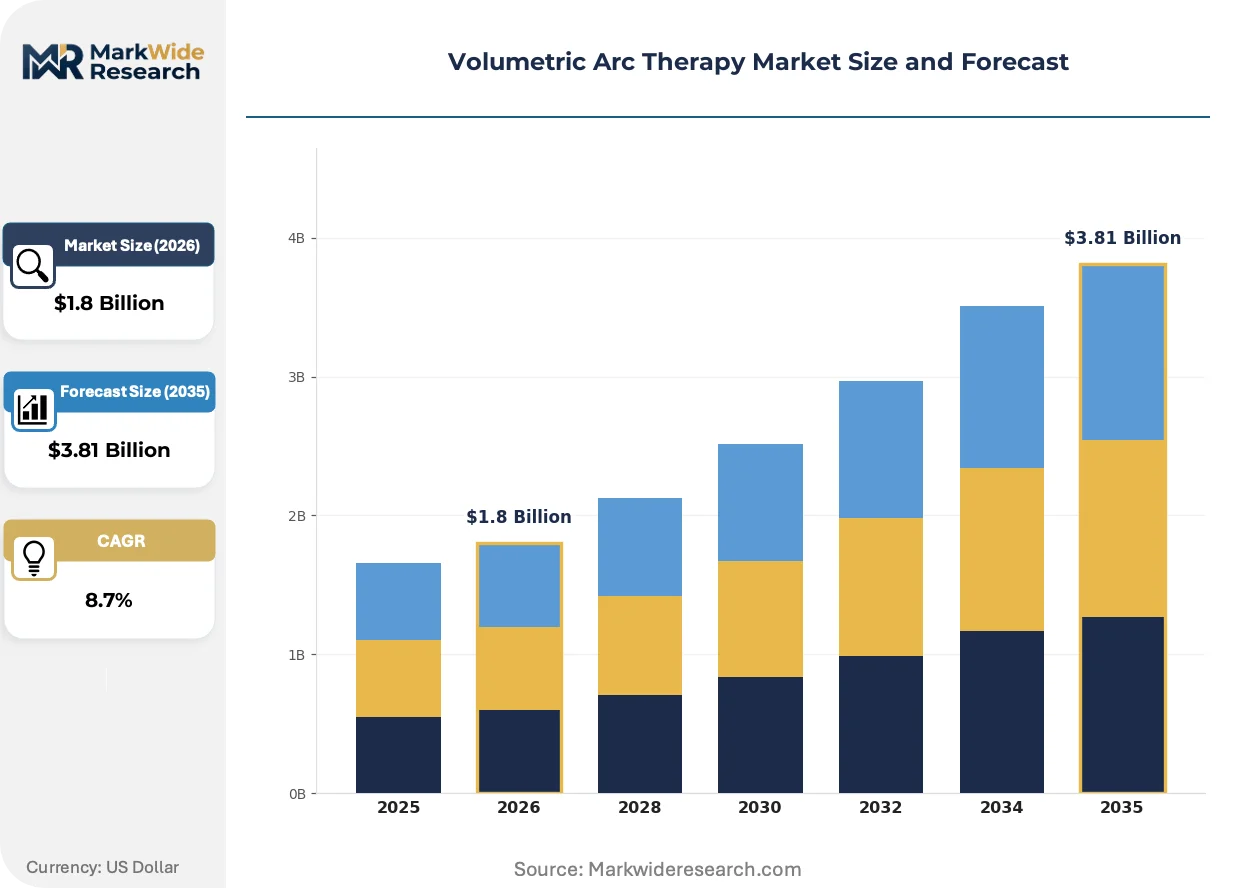
Market Dynamics
Continuous gantry rotation with dynamic multi-leaf collimation is compressing treatment times below two minutes, forcing oncology centers to reconfigure workflow capacity and capital deployment around throughput metrics rather than legacy appointment scheduling.
Growth Catalysts
- FDA 21 CFR Part 1020:US radiological health performance standards mandate linac safety benchmarks that VMAT systems exceed, accelerating hospital replacement cycles of aging cobalt units.
- Head and neck oncology:Arc delivery precision demonstrably reduces xerostomia and dysphagia toxicity profiles, pulling demand from conventional IMRT toward VMAT protocols.
- German university hospital clusters:EMA radiation safety directives are driving synchronized linac procurement waves across Heidelberg, Munich, and Berlin metropolitan treatment networks.
Market Restraints
- Linear accelerator supply concentration:Three manufacturers control gantry mechanics and RF source production, creating 14-18 month delivery backlogs for new installations.
- EU Medical Device Regulation:Intensified clinical evidence requirements for AI-driven planning modules extend market access timelines by 24-36 months for software entrants.
- Proton therapy substitution:Carbon-ion and proton centers in Japan and Germany are capturing pediatric and ocular cases where VMAT dose conformity remains inferior.
Strategic Opportunities
- Cone beam CT integration:Real-time anatomical verification during arc delivery represents the fastest-expanding capability segment as clinics demand adaptive replanning workflows.
- Indian tertiary cancer centers:Underpenetrated VMAT capacity in Mumbai, Delhi, and Chennai oncology institutes offers first-mover positioning before domestic linac assembly matures.
- AI plan optimization modules:Treatment planning software vendors are embedding machine learning engines that automate beam angle selection and dose-volume histogram prediction.
Industry Challenges
- Medical physics workforce scarcity:VMAT commissioning and quality assurance require specialized dosimetry expertise that residency programs are failing to replenish at replacement rates.
- Legacy PACS integration:Arc therapy planning systems must interface with decade-old hospital imaging archives, creating DICOM-RT compatibility failures and manual data migration burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volumetric Arc Therapy Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cancer Treatment, Radiation Device, Treatment Planning Software, Patient Monitoring System End User: Oncology Clinics, Hospitals, Research Institutes, Academic Centers Technology: Linear Accelerators, Cone Beam CT, Multi-Leaf Collimators, Imaging Systems Treatment Area: Head and Neck, Abdomen, Thorax, Pelvis |
| Companies Covered | Accuray Incorporated, Elekta, Varian Medical Systems, ViewRay Technologies, IBA Worldwide, Siemens Healthineers, Hitachi, Mevion Medical Systems, RaySearch Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volumetric Arc Therapy Market Evolving Landscape
Automation is penetrating every VMAT workflow layer from contouring through delivery verification, compressing the skill gradient between academic and community practice settings while elevating throughput expectations.
Magnetic resonance-guided linear accelerators are migrating from experimental installations to standard-of-care configurations for abdominal and pelvic malignancies. Academic medical centers in the US and Netherlands are prioritizing MR-linac procurement over conventional linac upgrades. This migration is compressing the addressable market for standalone cone beam CT enhancements as real-time soft-tissue tracking becomes the new baseline expectation.
The EU Medical Device Regulation's software classification rules are forcing planning system vendors to submit AI modules as Class IIb or III medical devices. Manufacturers are responding by segregating optimization algorithms into locked-down, validated releases rather than continuous-deployment cloud architectures. German notified bodies are experiencing 40% application volume increases, extending review timelines and freezing feature roadmaps.
Hospital procurement departments are unbundling after-sales service contracts from hardware acquisition, pitting independent service organizations against OEM field engineering teams. Large US health systems are negotiating multi-year performance-based agreements that tie service fees to machine uptime percentages rather than preventive visit counts. This behavior is most visible in the Kaiser Permanente and HCA network consolidations, where centralized capital planning favors vendor-agnostic technical staffing.
Volumetric Arc Therapy Market Segmentation
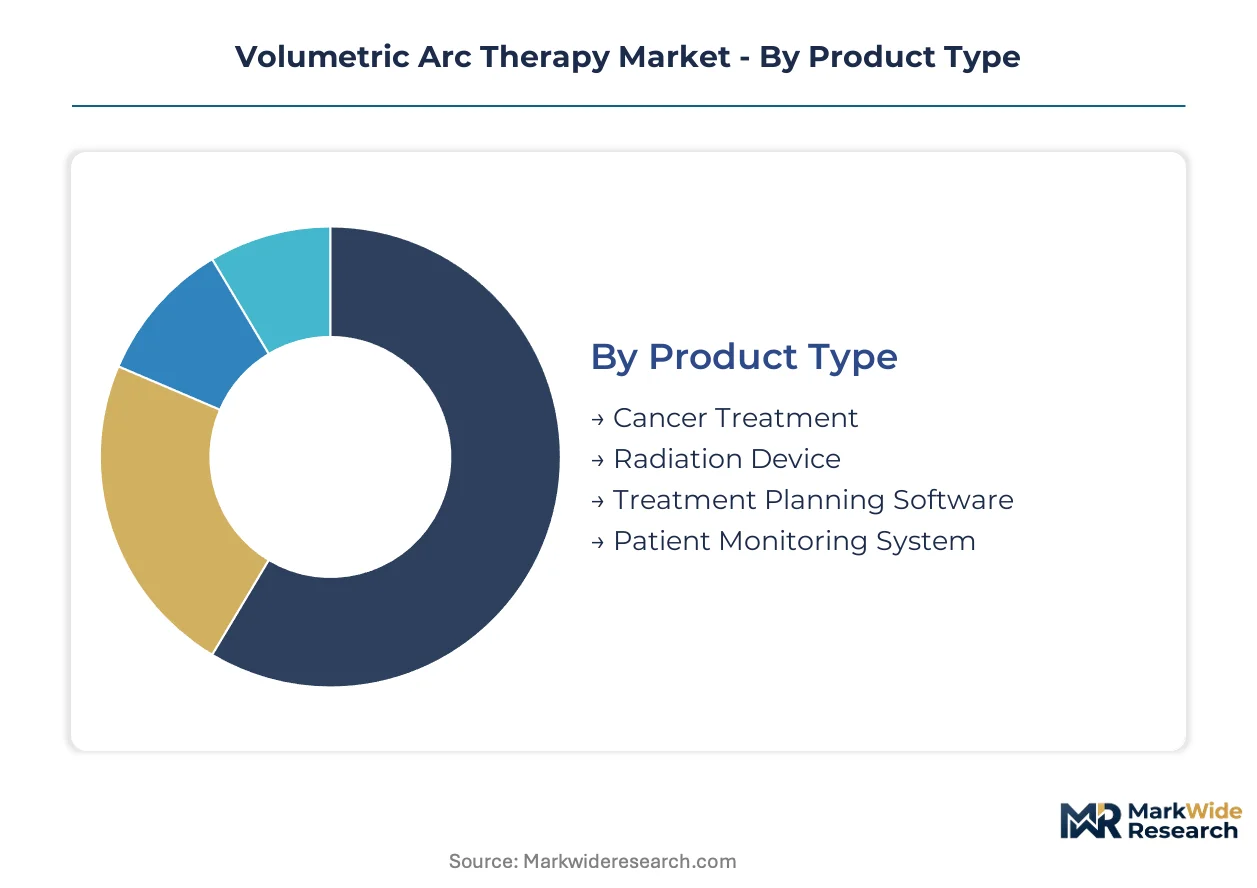
VMAT market structure reflects competing technology platforms, diverse clinical settings, and anatomical specialization requirements. Understanding segment boundaries clarifies where capital investment concentrates versus where software and service margins accumulate.
Product Type:
The use-case spectrum spans curative intent through workflow orchestration, with hardware platforms commanding upfront capital and software layers capturing recurring revenue streams.
- Cancer Treatment:Clinical service delivery encompassing fractionated protocols and hypofractionated regimens. German university hospitals are expanding service lines here as EMA radiation safety directives accelerate linac procurement cycles.
- Radiation Device:Gantry-based delivery systems integrating beam generation, collimation, and patient positioning mechanics. Supply concentration among three manufacturers creates 14-18 month installation backlogs that constrain capacity expansion timelines.
- Treatment Planning Software:Dose calculation engines and optimization modules operating under recurring licensing models. AI-driven plan automation is embedding machine learning for beam angle selection and DVH prediction.
- Patient Monitoring System:Real-time tracking and respiratory gating interfaces. Cone beam CT integration represents the fastest capability expansion as clinics demand adaptive replanning workflows.
Established volume favors radiation devices; emerging adoption favors treatment planning software.
End User:
Customer type determines procurement sophistication, with consolidated networks extracting performance-based terms that community settings cannot replicate.
- Oncology Clinics:Dedicated cancer treatment facilities optimizing throughput through high-volume arc protocols. Indian tertiary centers in Mumbai, Delhi, and Chennai present first-mover positioning before domestic linac assembly matures.
- Hospitals:General acute care institutions integrating radiation oncology within broader service portfolios. Workflow reconfiguration around sub-two-minute treatment times is compressing appointment scheduling architectures.
- Research Institutes:Experimental protocol development and clinical trial execution sites. MR-linac procurement is migrating from experimental installations to standard-of-care configurations for abdominal and pelvic malignancies.
- Academic Centers:Training and residency programs with commissioning and quality assurance responsibilities. Medical physics workforce scarcity here creates specialized dosimetry expertise gaps that residency programs fail to replenish.
Procurement scale favors hospitals; margin capture favors academic centers.
Technology:
Platform maturity varies sharply, with legacy gantry mechanics facing displacement from integrated imaging modalities.
- Linear Accelerators:RF source and waveguide assemblies generating megavoltage photon beams. Three manufacturers control gantry mechanics production, creating supply bottlenecks that extend delivery timelines.
- Cone Beam CT:Volumetric imaging during treatment delivery for anatomical verification. Real-time soft-tissue tracking is becoming baseline expectation, compressing addressable market for standalone enhancements.
- Multi-Leaf Collimators:Tungsten leaf arrays shaping beam aperture during continuous gantry rotation. Dynamic leaf motion enables dose modulation that reduces xerostomia and dysphagia toxicity in head and neck applications.
- Imaging Systems:Portal imaging and fluoroscopic verification subsystems. Legacy PACS integration creates DICOM-RT compatibility failures and manual data migration burdens across decade-old hospital archives.
Hardware concentration favors linear accelerators; capability expansion favors cone beam CT.
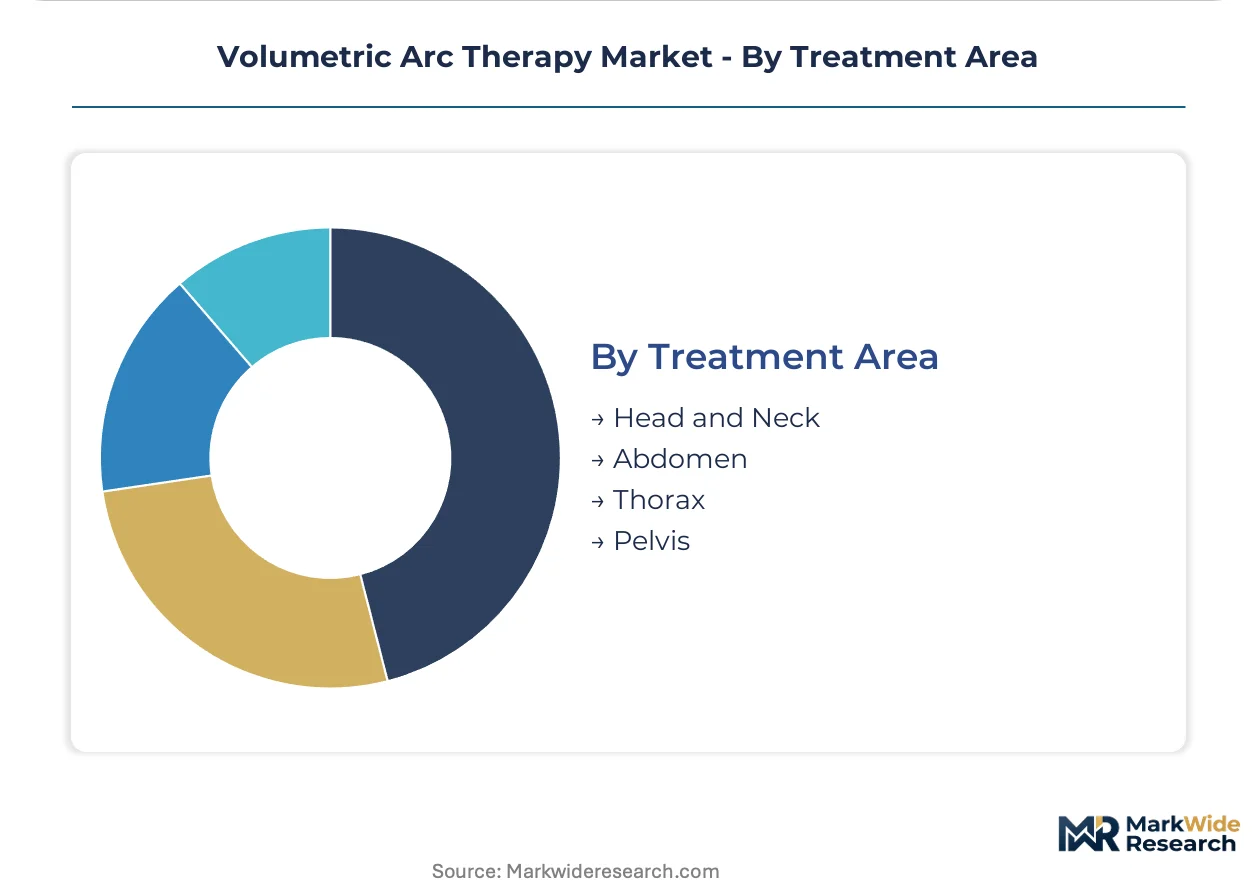
Treatment Area:
Anatomical targeting precision requirements vary, with motion management complexity driving technology selection.
- Head and Neck:Complex concave target volumes adjacent to critical structures including parotid glands and spinal cord. Arc delivery precision demonstrably reduces toxicity profiles, pulling demand from conventional IMRT protocols.
- Abdomen:Respiratory motion-compensated delivery for liver and pancreatic malignancies. MR-linac platforms are prioritizing this anatomy for real-time soft-tissue tracking capabilities.
- Thorax:Lung and mediastinal targets requiring robust motion management. Beam angle selection optimization is automating around cardiac sparing and lung dose minimization objectives.
- Pelvis:Prostate, gynecologic, and rectal cancer protocols with bladder and rectal filling variability. Adaptive replanning workflows are concentrating investment here as anatomical changes fraction-to-fraction compromise plan quality.
Clinical evidence depth favors head and neck; adaptive workflow investment favors pelvis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 1020 governs radiological health standards across the United States, anchoring North American VMAT deployment while EMA radiation safety directives coordinate European procurement cycles.
United States
Kaiser Permanente and HCA network consolidations are renegotiating multi-year performance-based service agreements tied to machine uptime percentages. FDA 21 CFR Part 1020 mandates linac safety benchmarks that accelerate hospital replacement cycles of aging cobalt units. The Greater Boston and Pacific Northwest metropolitan treatment networks are prioritizing MR-linac procurement over conventional linac upgrades.
Germany
University hospital clusters in Heidelberg, Munich, and Berlin are executing synchronized linac procurement waves under EMA radiation safety directives. The EU Medical Device Regulation intensifies clinical evidence requirements for AI-driven planning systems, extending market access timelines for software entrants. Siemens Healthineers anchors regional service infrastructure with native engineering support across Baden-Württemberg and Bavaria.
India
Tertiary cancer centers in Mumbai, Delhi, and Chennai present first-mover positioning before domestic linac assembly matures. The country's national pharmaceutical regulator coordinates radiation device safety assessments through notified body frameworks. Maharashtra and Delhi-NCR oncology institutes are expanding VMAT capacity through accelerated linac installations.
Japan
Carbon-ion and proton centers are capturing pediatric and ocular cases where VMAT dose conformity remains inferior. The Pharmaceuticals and Medical Devices Agency governs software classification rules for AI modules in treatment planning systems. The Kanto and Kansai metropolitan regions are migrating MR-linac platforms from experimental installations to standard-of-care configurations.
United Kingdom
NHS England technology assessment bodies are monitoring reimbursement parity between VMAT and conventional IMRT to anticipate volume shifts. The Medicines and Healthcare products Regulatory Agency enforces CE marking requirements for radiation device safety. London and Southeast England academic medical centers are prioritizing adaptive replanning workflows for pelvic malignancies.
Volumetric Arc Therapy Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where specialized engineering houses compete against integrated health technology conglomerates. The vendor base organizes around three strategic archetypes: gantry mechanics specialists, software optimization vendors, and full-stack radiation therapy platform builders. Competitive moves concentrate on unbundling after-sales service contracts from hardware acquisition and negotiating performance-based agreements tied to machine uptime percentages.
Within the full-stack platform tier, Varian Medical Systems and Elekta occupy positions defined by automated arc delivery workflows and MR-linac integration respectively. Siemens Healthineers anchors European service infrastructure through native engineering support capabilities. Accuray Incorporated sits within the precision-focused specialist tier, exemplifying compact system architectures for targeted treatment applications.
| Leading Market Players |
|---|
| Accuray Incorporated |
| Elekta |
| Varian Medical Systems |
| ViewRay Technologies |
| IBA Worldwide |
| Siemens Healthineers |
| Hitachi |
| Mevion Medical Systems |
| RaySearch Laboratories |
| Others |
Value Network & Pricing Analysis
Frankfurt-Hamburg freight corridors carry gantry subassemblies from central European manufacturing hubs to German university hospital clusters, with logistics cost pass-through amplifying the spread between premium-tier MR-linac platforms and standard linear accelerator configurations. Three manufacturers control RF source and gantry mechanics production, concentrating upstream pricing power while downstream buyers unbundle service contracts to extract performance-based terms.
Pricing Analysis
German procurement contracts trade at 15-25 percent premiums over Indian tertiary center installations for equivalent gantry specifications, reflecting CE marking compliance costs and native engineering support bundling. Three-tier pricing structure across premium, standard, and economy levels separates MR-integrated platforms from cone beam CT-enhanced systems and base linear accelerator configurations. Cost compression in the standard tier is intensifying because hospital procurement departments are negotiating uptime-guaranteed service agreements that shift risk to vendors. Community oncology clinics exhibit highest price sensitivity, while consolidated US health systems extract least-cost positioning through multi-year fleet agreements.
Supply Chain Analysis
Supplier-financing facilities from German engineering houses extend 180-day payment terms to linac manufacturers, easing working capital pressure during 14-18 month gantry assembly cycles. Supply concentrates in Germany, Sweden, and the United States for precision gantry mechanics, with Japan and South Korea anchoring RF source and magnetron production. Raw material dependencies include high-purity copper waveguides, tungsten alloy collimator leaves, and rare-earth magnets for beam steering assemblies. Single-source vulnerability sits with superconducting magnet suppliers for MR-linac platforms. Distribution runs through OEM direct sales teams for academic medical centers, with independent service organizations penetrating community hospital accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proton and carbon-ion therapy centers in Japan and Germany are capturing pediatric and ocular cases where VMAT dose conformity remains inferior, forcing arc therapy incumbents to defend positioning through adaptive workflow superiority rather than hardware specification alone.
For Market Incumbents: Insulate service revenue streams by embedding AI-driven plan optimization modules into locked-down, validated releases that comply with EU Medical Device Regulation Class IIb software classification requirements. Capture backward integration into cone beam CT detector manufacturing to reduce dependency on imaging subsystem vendors. Counter proton therapy substitution threats by prioritizing pelvic and abdominal adaptive replanning workflows where MR-linac real-time tracking maintains clinical differentiation. For New Entrants and Emerging Players: Build out independent service organization capabilities in Maharashtra and Delhi-NCR oncology institutes before domestic linac assembly matures in India, securing first-mover positioning in underpenetrated VMAT capacity. Target treatment planning software licensing as the most penetrable segment, where AI-driven beam angle selection modules face lower regulatory barriers than hardware platforms. Pursue GPO contract penetration through performance-based uptime guarantees that incumbent OEM field engineering teams cannot match on cost structure. For Investors and Strategic Acquirers: Software optimization vendors with validated AI modules and recurring licensing models present acquisition profiles with defensive margin characteristics against hardware commoditization. Long-term viability across the analysis window hinges on reimbursement parity maintenance between VMAT and conventional IMRT across national health technology assessment bodies. Watch NHS England technology assessment deliberations as the signal to watch for volume shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation compliance unlocks German university hospital procurement cycles under EMA radiation safety directives. |
| Hospital System Partnership | Kaiser Permanente and HCA network consolidations favor multi-year performance-based agreements tied to machine uptime percentages. |
| Software Companion Development | AI-driven plan optimization modules automate beam angle selection and DVH prediction, embedding recurring licensing revenue. |
| Reimbursement Strategy | Parity maintenance between VMAT and IMRT across national health technology assessment bodies determines volume elasticity. |
| Backward Integration | In-house production of cone beam CT detectors reduces imaging subsystem vendor dependency and service margin leakage. |
Research Methodology
Initial hypotheses were tested against primary input from radiation oncology department heads, medical physics residency directors, hospital procurement committee members, and GPO contracts managers, then refined through secondary validation against FDA 21 CFR Part 1020 filings, EMA radiation device safety assessments, CMS Medicare reimbursement databases, and hospital capital expenditure disclosures. Bottom-up triangulation across installed base estimates and top-down cross-check against manufacturer shipment data anchored volume figures.
Demand-supply-balance framing modeled treatment delivery capacity expansion against patient volume growth across the projection horizon, with segmentation dimensions spanning product type, end user archetype, technology platform, and anatomical treatment area. CAGRs were derived from slope analysis of historical procurement cycles and elasticity assumptions around reimbursement parity shifts. Forecast inputs incorporated linac replacement cycle acceleration under FDA safety mandates and proton therapy substitution rates in pediatric oncology.
The forecast holds incumbent behavior within observed patterns; aggressive moves by carbon-ion center developers or AI-native planning software entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
US Trauma Fixation Devices Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
Cyclotron Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
US Contact Lenses Market
Medical Devices
Oxygen Generator Market