
 Capsulotomy Market | 2026-2036
Capsulotomy Market Size, Share, and Industry Trends Forecast 2026-2036
Capsulotomy Market Analytics
Buyer concentration among ambulatory surgical centers is consolidating as outpatient ophthalmic networks expand their purchasing power across regional markets. Carl Zeiss Meditec leverages its integrated diagnostic-to-surgical platform to anchor premium system placements in high-volume cataract settings. Lumenis competes through specialized laser technology leadership, while Ellex Medical Lasers sustains geographic dominance across Asia-Pacific through established distributor relationships.
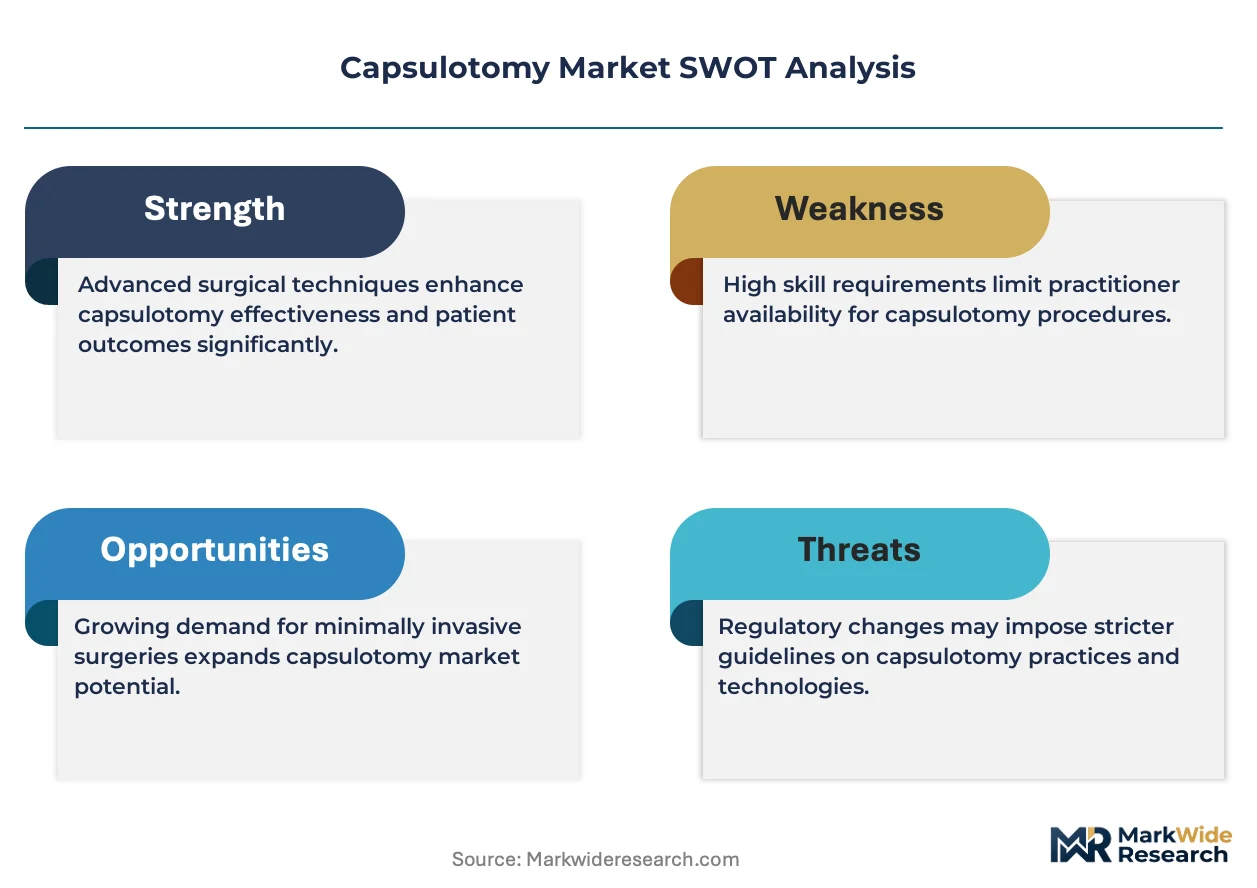
A capsulotomy is a surgical incision of the lens capsule, typically performed using Nd:YAG laser energy at 1064 nm wavelength to create a precise opening in the posterior capsule following cataract extraction. The procedure restores visual clarity by eliminating posterior capsule opacification, the most common complication of modern phacoemulsification surgery. Laser systems command the highest margin pools due to recurring consumable revenue and service contracts, while manual instruments occupy cost-sensitive segments in emerging markets. Electrosurgery technology differentiates through integrated anterior segment platforms, and cataract surgery applications dominate procedure volumes across all end-user settings.
FDA 510(k) premarket notification requirements and EU MDR conformity assessment procedures govern device commercialization, with clinical evidence thresholds rising under strengthened post-market surveillance mandates. ISO 13485 quality management certification has become a baseline expectation for supplier qualification by hospital procurement committees. Stakeholders must monitor evolving reimbursement coding for laser-assisted procedures versus manual techniques, as payer decisions will reshape capital equipment investment cycles and technology mix across surgical settings.
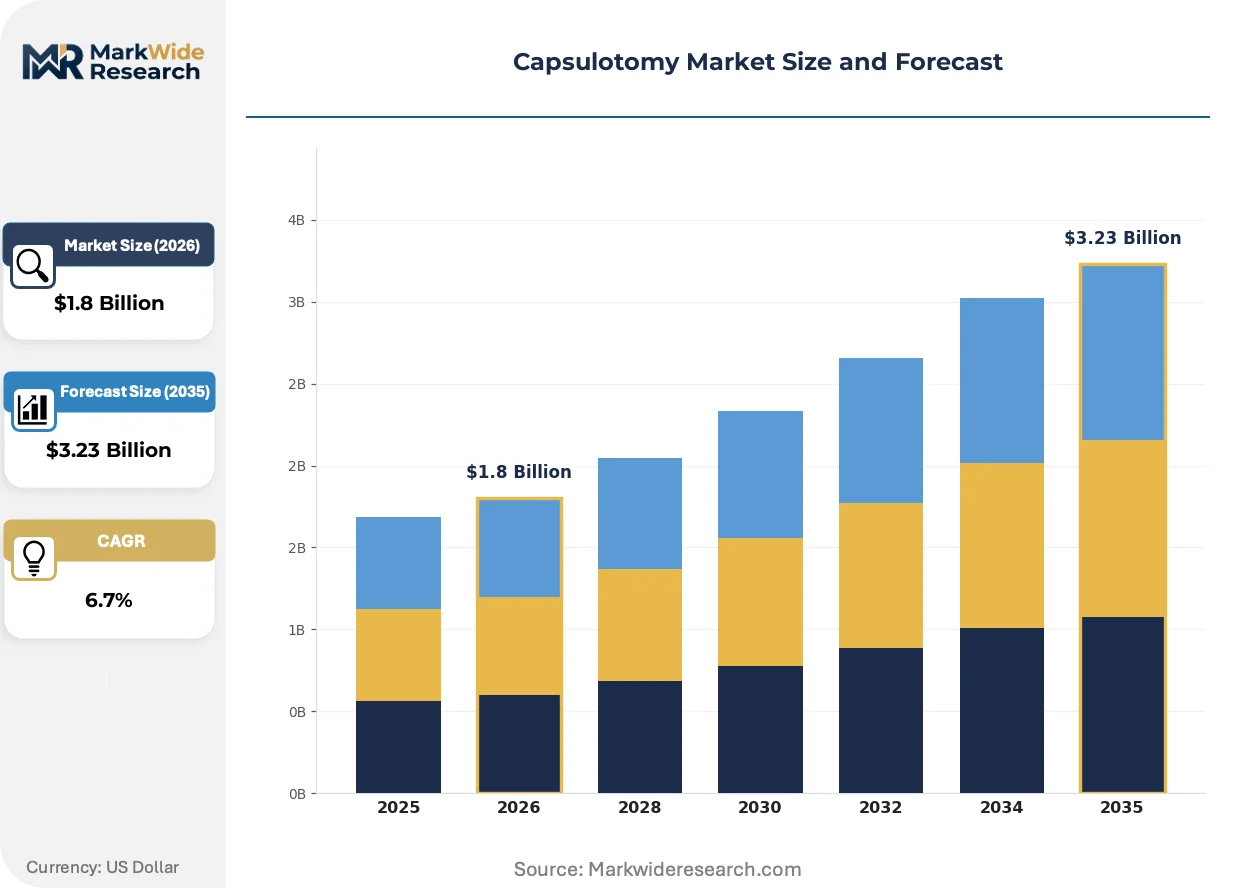
Market Dynamics
The capsulotomy market is consolidating around laser system platforms that generate recurring revenue through disposable delivery systems and service contracts, compressing margins for standalone manual instrument suppliers.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage determinations for outpatient laser procedures sustain procedural volumes across United States ambulatory surgical centers.
- Nd:YAG wavelength standardization:The 1064 nm specification anchors device interoperability and reduces training burdens for ophthalmic surgical staff.
- India's cataract burden:Government screening programs and subsidized surgical camps drive manual capsulotomy instrument demand in tier-2 and tier-3 cities.
Market Restraints
- Laser system capex concentration:High upfront capital requirements limit penetration in cost-sensitive clinics and public hospital systems.
- EU MDR transition costs:Strengthened clinical evidence requirements and notified body capacity constraints extend conformity assessment timelines for device manufacturers.
- Phacoemulsification platform bundling:Integrated surgical system vendors bundle capsulotomy modules, eroding standalone laser system addressable market.
Strategic Opportunities
- Brazil's SUS expansion:Unified health system procurement scale creates volume contracts for mid-tier laser platforms serving public ophthalmology networks.
- Femtosecond-laser convergence:Cataract platform integration with anterior segment imaging enables single-procedure capsulotomy-cataract extraction workflows.
- Telemedicine-enabled pre-screening:Remote posterior capsule opacification detection channels patients toward laser capsulotomy referral networks.
Industry Challenges
- Laser safety officer certification:Jurisdictional training mandates for Class 4 laser operation create staffing bottlenecks in high-volume surgical settings.
- Legacy device service continuity:Discontinued Nd:YAG platform parts availability forces premature capital replacement cycles at independent surgery centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capsulotomy Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissors, Forceps, Blades, Systems Technology: Laser, Electrosurgery, Manual, Ultrasound End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Labs Application: Cataract Surgery, Lens Extraction, Glaucoma Treatment, Others |
| Companies Covered | Mynosys Cellular Devices, International BioMedical Devices, EXCEL-LENS, Optotek Medical, Carl Zeiss Meditec, Ellex Medical Lasers, Lumenis, ASTANZA, SpaMedica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capsulotomy Market Evolving Landscape
Digital anterior segment imaging and automated treatment planning are compressing the skill gradient between novice and expert laser capsulotomy operators, reshaping training economics and staffing models across outpatient surgical networks.
Optical coherence tomography-guided laser targeting is unifying preoperative measurement with intraoperative energy delivery. High-volume cataract networks in Germany and Japan are adopting these integrated platforms to standardize capsulotomy diameter and centration. The technology is unifying diagnostic and therapeutic workflows into single-vendor ecosystems that lock in consumable revenue streams.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection for laser ophthalmic devices. Manufacturers must now maintain active implant registries and periodic safety update reports, increasing compliance overhead. Premium system vendors with established quality management infrastructure are absorbing these costs more readily than mid-tier competitors, accelerating vendor consolidation.
After-sales service unbundling is emerging as procurement committees separate equipment purchase from maintenance contracts. United States ambulatory surgical center networks are negotiating multi-year service agreements independent of capital acquisition, pressuring OEM service margins. This shift is most visible in regional ophthalmology platforms across Texas and Florida, where purchasing cooperatives standardize service terms across device categories.
Capsulotomy Market Segmentation
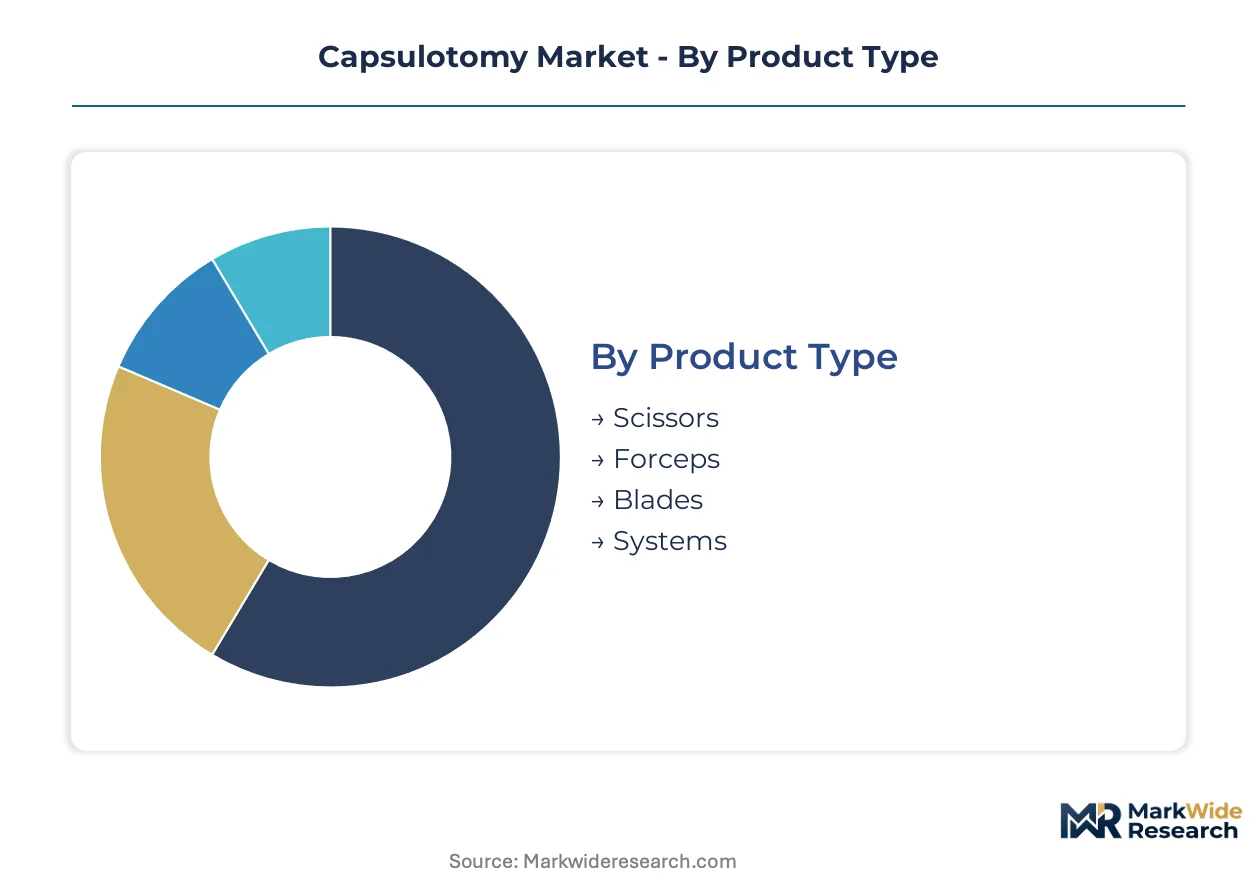
Capsulotomy market segmentation reveals divergent regulatory pathways across product categories. Laser systems trigger FDA 510(k) and EU MDR Class IIb scrutiny, while manual instruments face lighter conformity burdens.
Product Type:
Laser systems require FDA 510(k) premarket notification and EU MDR technical documentation with clinical evaluation reports. Manual instruments qualify under self-certification routes in most jurisdictions.
- Systems:Integrated Nd:YAG laser platforms deliver 1064 nm wavelength energy through slit-lamp delivery systems. Demand concentrates in United States ambulatory surgical centers where Medicare reimbursement sustains capital replacement cycles. FDA 510(k) clearance timelines and service contract bundling shape procurement decisions.
- Blades:Disposable cystotome instruments create anterior capsulotomy openings during manual cataract extraction. Volume demand clusters in India's tier-2 cities where government screening programs subsidize surgical camps. CDSCO registration requirements govern importation into Indian public health systems.
- Scissors:Microsurgical capsulotomy scissors for intraoperative capsule manipulation.
- Forceps:Capsulorhexis forceps for continuous curvilinear capsulorhexis in manual techniques.
Leading the category by volume: Blades. Growing fastest: Systems.
Technology:
Technology segments stratify by capital intensity and consumable attachment rates. Laser platforms command premium pricing through disposable delivery systems, while manual techniques dominate cost-constrained settings.
- Laser:Nd:YAG photodisruption at 1064 nm wavelength creates precise posterior capsule openings without intraocular entry. United States Medicare reimbursement codes differentiate laser capsulotomy from manual alternatives, directing hospital purchasing toward capital equipment. ISO 13485 certification and FDA 510(k) submissions impose compliance overhead that favors established manufacturers.
- Manual:Mechanical instrumentation for capsulorhexis and capsulotomy without energy delivery. India's cataract surgical camps and Brazil's SUS public procurement networks drive volume demand. Lower regulatory thresholds accelerate market entry for regional instrument suppliers.
- Electrosurgery:Radiofrequency energy integrated into anterior segment platforms for combined procedures.
- Ultrasound:Phacoemulsification-coupled ultrasound applications for capsular manipulation.
Revenue concentrates in Laser. Steepest expansion trajectory: Manual in emerging markets.
End User:
End-user segments diverge by procurement scale and technology sophistication. Ambulatory surgical centers consolidate purchasing power through regional networks, while research labs drive early adoption of imaging-integrated platforms.
- Ambulatory Surgical Centers:Outpatient ophthalmic networks perform high-volume cataract and YAG capsulotomy procedures on same-day discharge protocols. United States Medicare reimbursement rates for facility fees sustain capital investment in laser platforms. Group purchasing organizations across Texas and Florida negotiate multi-year service agreements independent of equipment acquisition.
- Hospitals:Academic medical centers and public hospital systems with integrated ophthalmology departments. EU MDR transition costs and notified body capacity constraints delay laser system procurement in European hospital networks. Budget fragmentation between capital and operating expenditure limits technology refresh cycles.
- Clinics:Private ophthalmology practices and standalone surgical facilities.
- Research Labs:Academic and clinical research institutions evaluating next-generation capsulotomy techniques.
Procedure volume leader: Ambulatory Surgical Centers. Fastest-growing procurement sophistication: Research Labs with imaging integration.
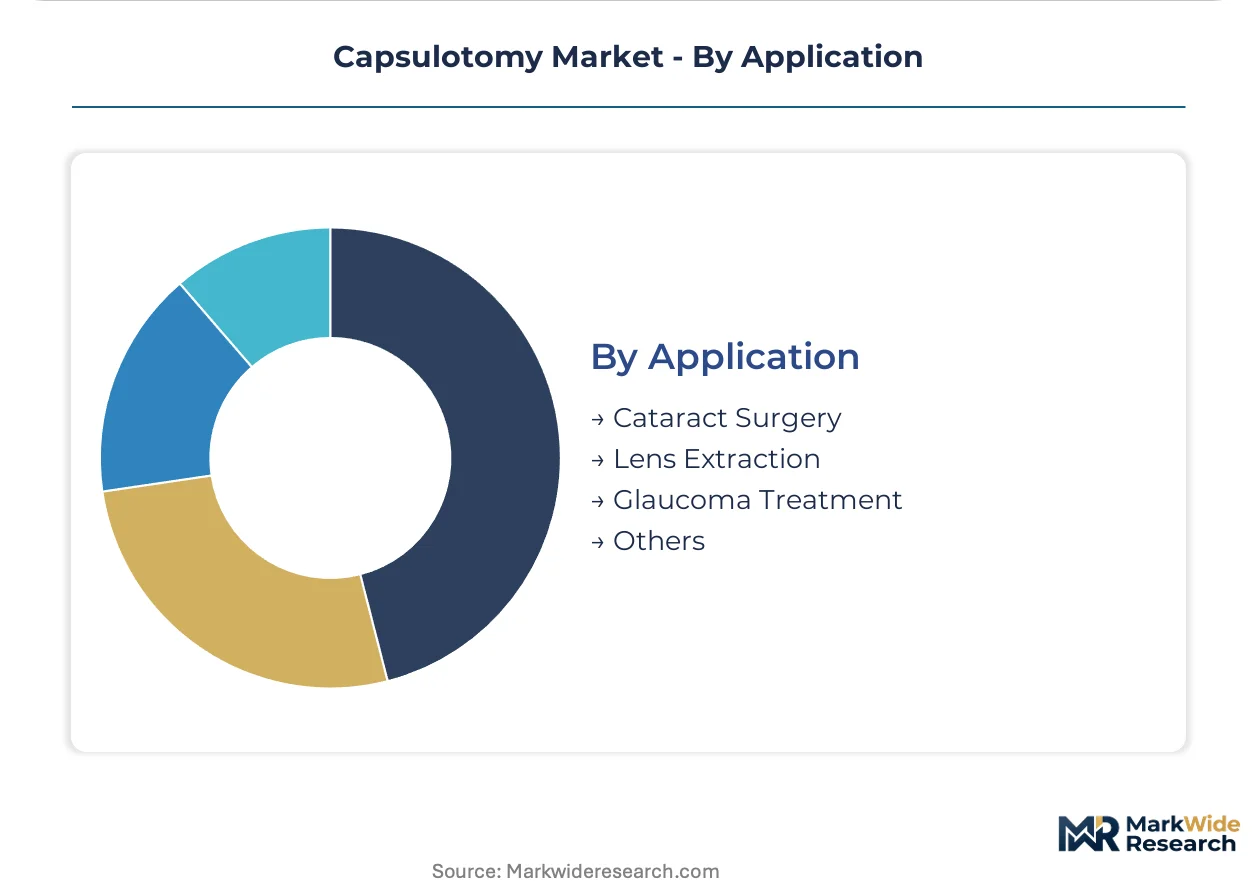
Application:
Application segments align with procedural reimbursement coding and complication rates. Cataract surgery generates recurring capsulotomy demand through posterior capsule opacification, the most common postoperative complication.
- Cataract Surgery:Posterior capsule opacification treatment following phacoemulsification accounts for dominant procedure volumes. Germany and Japan's high-volume cataract networks adopt OCT-guided laser targeting to standardize capsulotomy centration. EU MDR post-market surveillance mandates systematic clinical follow-up data collection for laser devices used in this indication.
- Lens Extraction:Capsulotomy preceding intraocular lens removal or exchange procedures. United States ambulatory surgical centers report growing volumes tied to premium IOL explantation cases. Reimbursement coding complexity creates administrative burden for standalone lens extraction without concurrent cataract diagnosis.
- Glaucoma Treatment:Capsulotomy adjunct procedures for angle-closure glaucoma management.
- Others:Secondary indications including traumatic capsule injury repair and pediatric applications.
Volume concentration: Cataract Surgery. Fastest-growing complexity: Lens Extraction with premium IOL involvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ambulatory surgical centers concentrate the highest procedure volumes for laser capsulotomy, while Germany and Japan drive adoption of imaging-integrated platforms. India's government-subsidized surgical camps and Brazil's public health procurement sustain manual instrument demand at scale.
United States
Medicare reimbursement for outpatient YAG laser procedures sustains capital replacement cycles across regional ophthalmology networks. FDA 510(k) clearance pathways govern commercialization timelines for Nd:YAG system manufacturers. Texas and Florida purchasing cooperatives negotiate multi-year service agreements independent of equipment acquisition.
Germany
High-volume cataract networks in Bavaria and North Rhine-Westphalia adopt OCT-guided laser targeting to standardize capsulotomy centration. EU MDR post-market surveillance mandates systematic clinical follow-up data collection for laser ophthalmic devices. The Stuttgart-Mannheim corridor anchors premium system placements through integrated diagnostic-to-surgical platforms.
Japan
Aging demographics drive procedural demand in Tokyo and Osaka metropolitan surgical centers. PMDA regulatory reviews align with ISO 13485 quality management certification requirements for supplier qualification. The Nagoya-Chubu region concentrates manufacturing partnerships for anterior segment platform integration.
India
Government screening programs and subsidized surgical camps drive manual capsulotomy instrument demand in tier-2 and tier-3 cities. CDSCO registration requirements govern importation into Indian public health systems. Maharashtra and Gujarat host distributor networks for regional instrument suppliers serving camp-based cataract programs.
Brazil
Unified health system procurement scale creates volume contracts for mid-tier laser platforms serving public ophthalmology networks. ANVISA conformity assessment procedures shape device commercialization timelines. São Paulo's private hospital clusters and Minas Gerais public networks represent divergent technology adoption patterns.
Capsulotomy Market Competitive Landscape
German and Swiss producers anchor the premium integrated-platform tier; Australian and Israeli specialists hold positions in laser technology components. The vendor structure concentrates around three strategic archetypes: diversified optical conglomerates with diagnostic-to-surgical ecosystems, pure-play laser technology specialists, and regional manual instrument fabricators. Competitive positioning depends on M&A activity for imaging integration capabilities and geographic expansion through distributor network acquisitions.
Within the diversified optical tier, Carl Zeiss Meditec anchors integrated platform positioning. Lumenis and Ellex Medical Lasers occupy specialist positions in laser energy delivery systems. These three entities exemplify contrasting geographic origins and structural approaches to the capsulotomy device segment.
| Leading Market Players |
|---|
| Mynosys Cellular Devices |
| International BioMedical Devices |
| EXCEL-LENS |
| Optotek Medical |
| Carl Zeiss Meditec |
| Ellex Medical Lasers |
| Lumenis |
| ASTANZA |
| SpaMedica |
| Others |
Value Network & Pricing Analysis
EU MDR post-market surveillance mandates gate qualified supply access and premium-tier pricing power, as manufacturers absorbing clinical follow-up data collection costs capture reimbursement-linked procurement while mid-tier competitors face margin compression from compliance overhead.
Pricing Analysis
Volume concentrates in manual blades for India's subsidized surgical camps, while margins pool in Nd:YAG laser systems through disposable delivery systems and multi-year service contracts. Three-tier pricing structure across premium, standard, and economy levels separates integrated diagnostic-to-surgical platforms from standalone lasers and basic instrumentation. Pricing pressure stems from after-sales service unbundling as United States ambulatory surgical center cooperatives negotiate maintenance terms independent of capital acquisition. Public hospital systems in Brazil and tier-2 Indian cities exhibit highest price sensitivity; premium integrated platforms face least sensitivity in German and Japanese high-volume cataract networks.
Supply Chain Analysis
India's PLI scheme for medical devices and Brazil's ANVISA local-content preferences are reshaping sourcing patterns for regional instrument suppliers serving public procurement networks. Nd:YAG laser resonators and optical coherence tomography components concentrate in Germany, Japan, and Switzerland; manual instrument fabrication clusters in India and China. Supply chains draw from rare-earth elements for laser crystals, precision optics, and biocompatible alloys for disposable delivery systems. Single-source vulnerability runs through sole suppliers of 1064 nm laser cavity components. Distribution runs through established distributor networks in Asia-Pacific and direct hospital system contracts in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance cost escalation is accelerating vendor consolidation, forcing mid-tier laser manufacturers without established quality management infrastructure toward exit or acquisition.
For Market Incumbents: Deploy service contract bundling as the primary retention lever. Lock ambulatory surgical center networks into multi-year maintenance agreements independent of equipment refresh cycles to defend against after-sales unbundling pressure. Deepen backward integration into optical coherence tomography component supply to capture imaging-integrated platform premiums and reduce sole-source vulnerability in laser cavity sourcing. For New Entrants and Emerging Players: Capture white-space opportunity in Brazil's SUS mid-tier laser procurement and India's tier-3 city manual instrument replacement cycles. Public health system volume contracts in São Paulo and Minas Gerais represent the most penetrable entry point, with distributor network acquisition as the critical go-to-market angle to bypass established channel control by incumbent specialists. For Investors and Strategic Acquirers: ANVISA and CDSCO registration completion for mid-tier laser platforms is the leading indicator that regional players have absorbed regulatory fixed costs and present viable acquisition targets. The five-to-ten year viability window favors integrated diagnostic-to-surgical platform vendors with recurring consumable revenue over standalone laser specialists facing phacoemulsification bundling erosion. Watch for EU MDR periodic safety update report filings as the signal of quality infrastructure depth.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation with clinical evaluation reports unlocks German hospital network procurement. |
| Hospital System Partnership | Texas and Florida purchasing cooperatives standardize multi-year service terms across regional ophthalmology platforms. |
| FDA 510(k) Submission | Premarket notification clearance sustains Medicare reimbursement-linked capital replacement cycles in United States ambulatory settings. |
| Software Companion Development | Automated treatment planning applications compress skill gradients and expand addressable operator base. |
| Reimbursement Strategy | CMS coverage determination alignment directs group purchasing organization technology mix toward laser-assisted procedures. |
Research Methodology
Multi-period observation of cataract surgical volume trajectories, Medicare reimbursement code utilization, and EU MDR notified body capacity constraints anchored the trend analysis, supplemented by interviews with ophthalmic surgeons, ambulatory surgical center purchasing managers, biomedical engineers, and GPO contracts specialists. Secondary validation drew from FDA 510(k) filings, CMS Medicare claims data, hospital procurement databases, and ANVISA registration records. Bottom-up procedure volume modeling triangulated against top-down capital equipment shipment estimates.
Input-output matrix framing connected Nd:YAG laser system placements to disposable delivery system attachment rates and service contract renewal probabilities across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user setting, application indication, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for technology substitution and reimbursement elasticity estimates. Forecast inputs incorporated phacoemulsification platform bundling intensity and telemedicine-enabled pre-screening channel development.
The model holds under stable Medicare reimbursement rates and EU MDR notified body capacity; deviation in CMS coverage determinations or MDR transition timeline extensions would shift capital equipment investment cycles. Forecasts reflect documented assumptions regarding procedure volume growth and technology substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Smart Wearable Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Ostomy Drainage Systems Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Appendage Management Market
Medical Devices
Muscle Stimulator Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Skincare Devices Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Spain Ultrasound Devices Market