
 Global Artificial Tendons and Ligaments Market | 2026-2036
Global Artificial Tendons and Ligaments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Tendons and Ligaments Market Foresight
Switzerland is tilting toward advanced synthetic ligament manufacturing through Mathys AG Bettlach's specialized production footprint. Arthrex leverages integrated sports medicine portfolios to sustain premium positioning across ACL reconstruction workflows. Stryker anchors North American distribution through its established orthopedic hospital networks. Shanghai PINE&POWER Biotech competes on cost-optimized PET fiber production for emerging Asian markets.
Artificial tendons and ligaments are permanent implantable constructs manufactured from synthetic polymers or biologically derived matrices, typically engineered to achieve tensile strengths exceeding 50 MPa while maintaining controlled porosity for host tissue integration; their primary purpose is restoring mechanical stability to musculoskeletal joints following traumatic rupture or degenerative failure. Polyethylene terephthalate dominates current surgical volume due to decades of clinical validation and predictable load-bearing performance, while collagen-based scaffolds represent the fastest-expanding category as surgeons prioritize biointegration over immediate mechanical strength. Electrospinning technology commands concentrated R&D investment because nanofiber architectures enable simultaneous control of degradation kinetics and cellular infiltration depth.
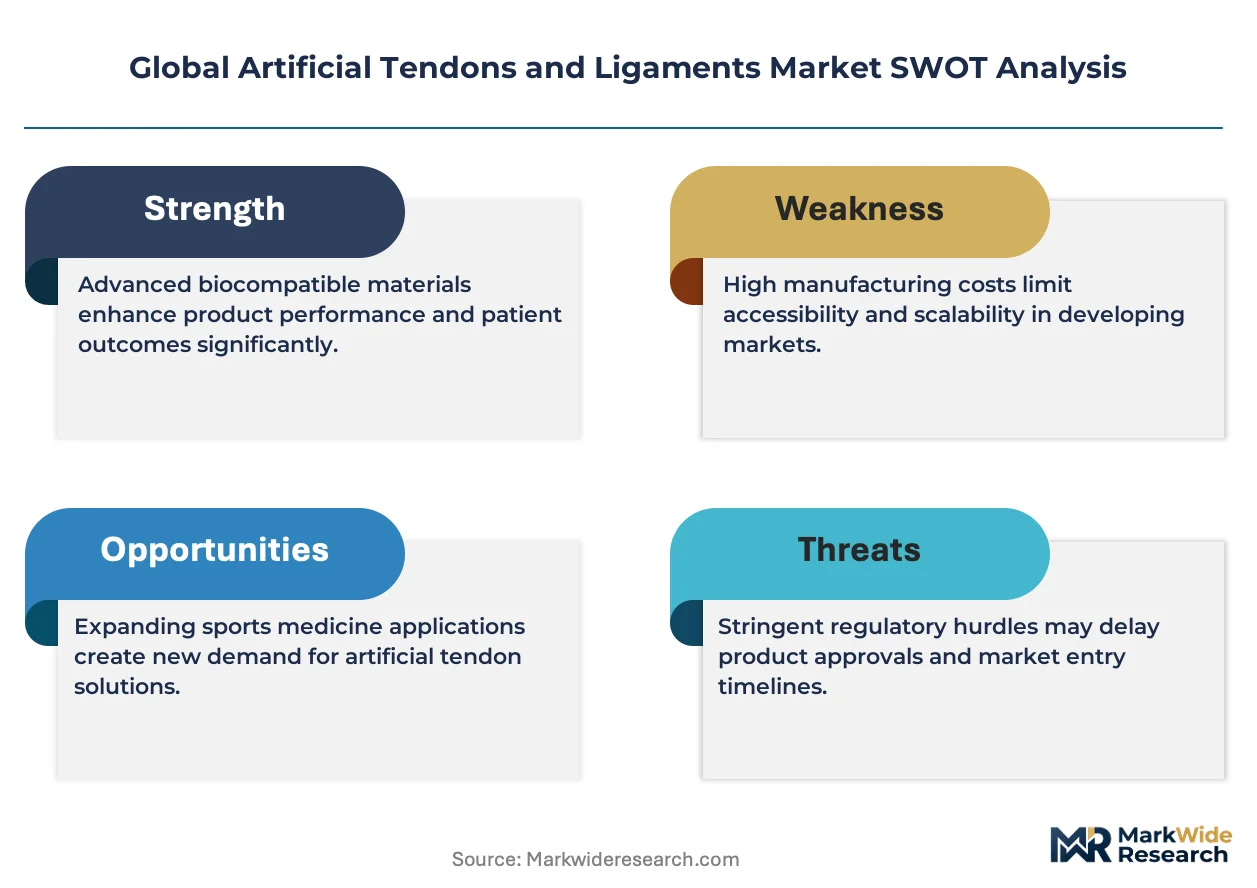
FDA 510(k) clearance pathways and EU MDR Class III implantable device requirements impose substantial biocompatibility and mechanical testing burdens that filter out undercapitalized entrants. ISO 10993 biological evaluation standards and REACH substance restrictions on polymer additives further constrain material selection freedom for manufacturers targeting dual-market registration. Stakeholders must monitor evolving FDA guidance on permanent synthetic ligaments as the agency weighs long-term degradation profiles against revision surgery risks.
Market Dynamics
EU MDR Class III implantable device requirements are compressing vendor timelines and elevating biocompatibility testing costs, filtering participation toward capitalized manufacturers with dedicated regulatory affairs infrastructure.
Growth Catalysts
- EU MDR framework tightening:Stricter biocompatibility testing for permanent implants is accelerating consolidation around validated polymer platforms, advantaging incumbents with established ISO 10993 documentation.
- Sports medicine center expansion:Specialized orthopedic clinics in Germany are scaling synthetic ligament adoption through streamlined reimbursement pathways for ACL reconstruction procedures.
- Electrospinning R&D concentration:Nanofiber architecture control is enabling simultaneous degradation kinetics and cellular infiltration depth management, opening biointegration performance gaps versus conventional weaving.
Market Restraints
- Polymer additive restrictions:REACH substance limitations on phthalates and stabilizers constrain PET fiber formulation freedom, forcing reformulation cycles that extend development timelines.
- Supply concentration in specialty fiber production:High-tenacity medical-grade PET yarn capacity clusters among three European chemical conglomerates, creating input vulnerability for mid-tier device assemblers.
- Allograft substitution persistence:Cadaver-derived tendon grafts retain preference among cost-sensitive hospital systems in Southern Europe and Latin America, capping synthetic penetration in price-elastic segments.
Strategic Opportunities
- India orthopedic infrastructure buildout:Government hospital modernization programs and private sports medicine clinic chains in Mumbai and Delhi are creating first-mover windows for cost-optimized PET ligament suppliers.
- Collagen-scaffold biointegration premium:Surgeons in Swiss and German university hospitals are prioritizing cellular infiltration performance over immediate tensile strength, shifting volume toward resorbable matrix platforms.
- Integrated sports medicine distribution:Direct procurement relationships between synthetic ligament manufacturers and Bundesliga team medical departments are bypassing traditional distributor markups.
Industry Challenges
- Electrospinning scale-up complexity:Translating nanofiber laboratory architectures to GMP-compliant production lines demands specialized cleanroom infrastructure and process engineering talent scarce outside Basel and Boston corridors.
- Dual-market registration synchronization:Misaligned FDA 510(k) review timelines with EU MDR notified body backlogs are forcing parallel submission strategies that strain regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Tendons and Ligaments Market |
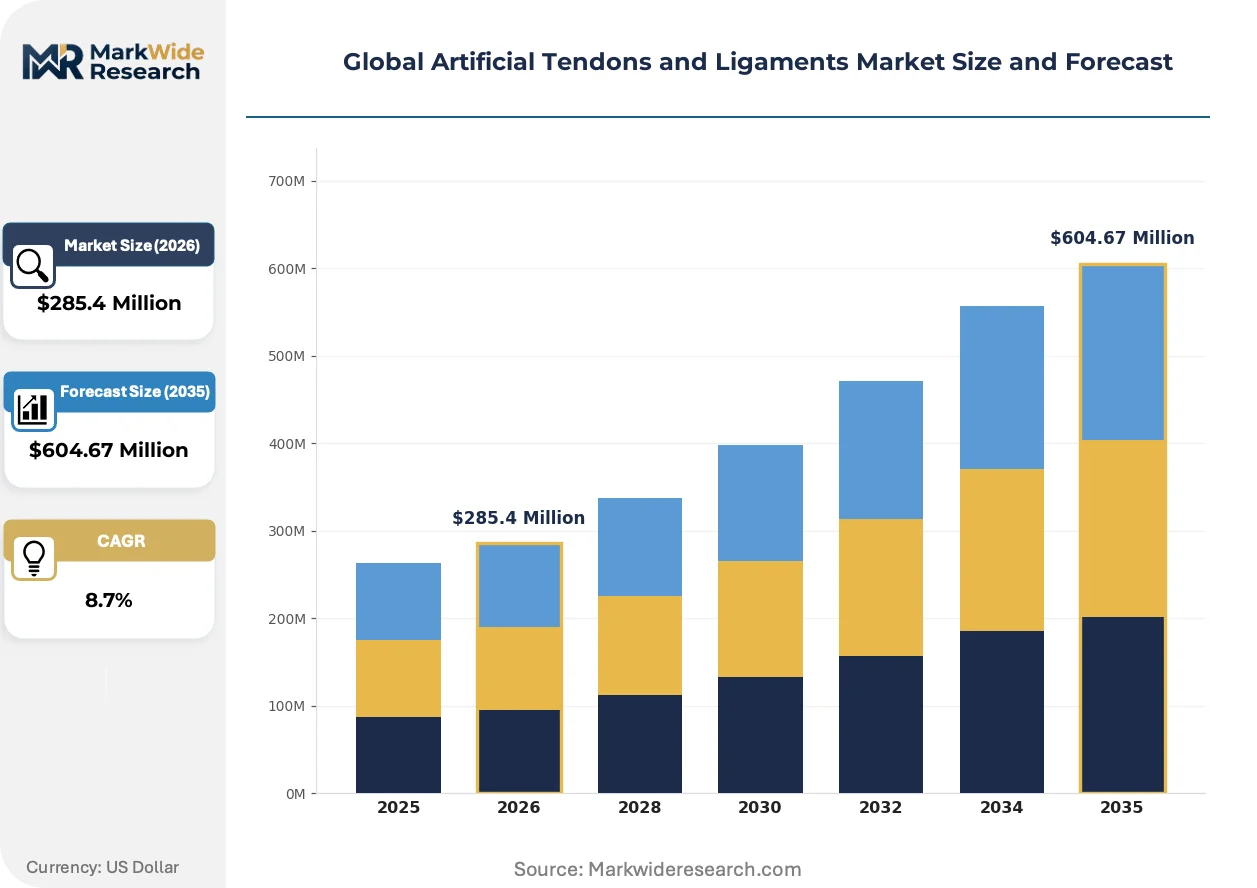
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, Polyurethane, Collagen-Based, Silk-Based, Others Application: Anterior Cruciate Ligament Reconstruction, Rotator Cuff Repair, Achilles Tendon Repair, Medial Collateral Ligament Repair, Patellar Tendon Reconstruction End User: Orthopedic Clinics, Sports Medicine Centers, Rehabilitation Facilities, Surgical Hospitals Technology: Biodegradable Scaffolds, Tissue Engineering, Synthetic Fiber Technology, Electrospinning, Nanofiber Fabrication |
| Companies Covered | LARS, Neoligaments, Cousin Biotech, Orthomed, FX Solutions, Shanghai PINE&POWER Biotech, Mathys AG Bettlach, Arthrex, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Tendons and Ligaments Market Shifts & Advancements
Material science convergence with digital surgical planning is redefining ligament reconstruction workflows, compressing the gap between mechanical performance and biological acceptance.
Collagen-based scaffolds are hybridizing synthetic load-bearing cores with bioresorbable outer matrices, enabling staged mechanical-to-biological transition that sports medicine surgeons in German clinics are adopting faster than general orthopedic practices. This architecture is hybridizing the traditional trade-off between immediate fixation strength and long-term tissue remodeling, collapsing the historical segmentation between permanent synthetics and temporary biological aids.
EU MDR clinical evaluation requirements for Class III permanent implants are mandating extended follow-up data that smaller manufacturers cannot fund, shifting competitive advantage toward firms with decade-long PET ligament registries. Swissmedic and BfArM are harmonizing post-market surveillance expectations, forcing standardized adverse event reporting that raises compliance costs but also creates defensible quality differentiation. High-volume ACL reconstruction centers in Bavaria and North Rhine-Westphalia are now requiring MDR-compliant technical documentation as a procurement prerequisite.
Surgeon training concentration is rotating toward robotic-assisted ligament placement systems that demand pre-operative digital templating, unbundling traditional device-and-technique bundled education models. Sports medicine fellowship programs in Zurich and Munich are incorporating synthetic ligament-specific modules that privilege manufacturers with dedicated surgical training infrastructure. This behavioral shift is most pronounced in German-speaking Europe, where hospital purchasing committees increasingly weight training ecosystem depth alongside device pricing.
Global Artificial Tendons and Ligaments Market Segmentation
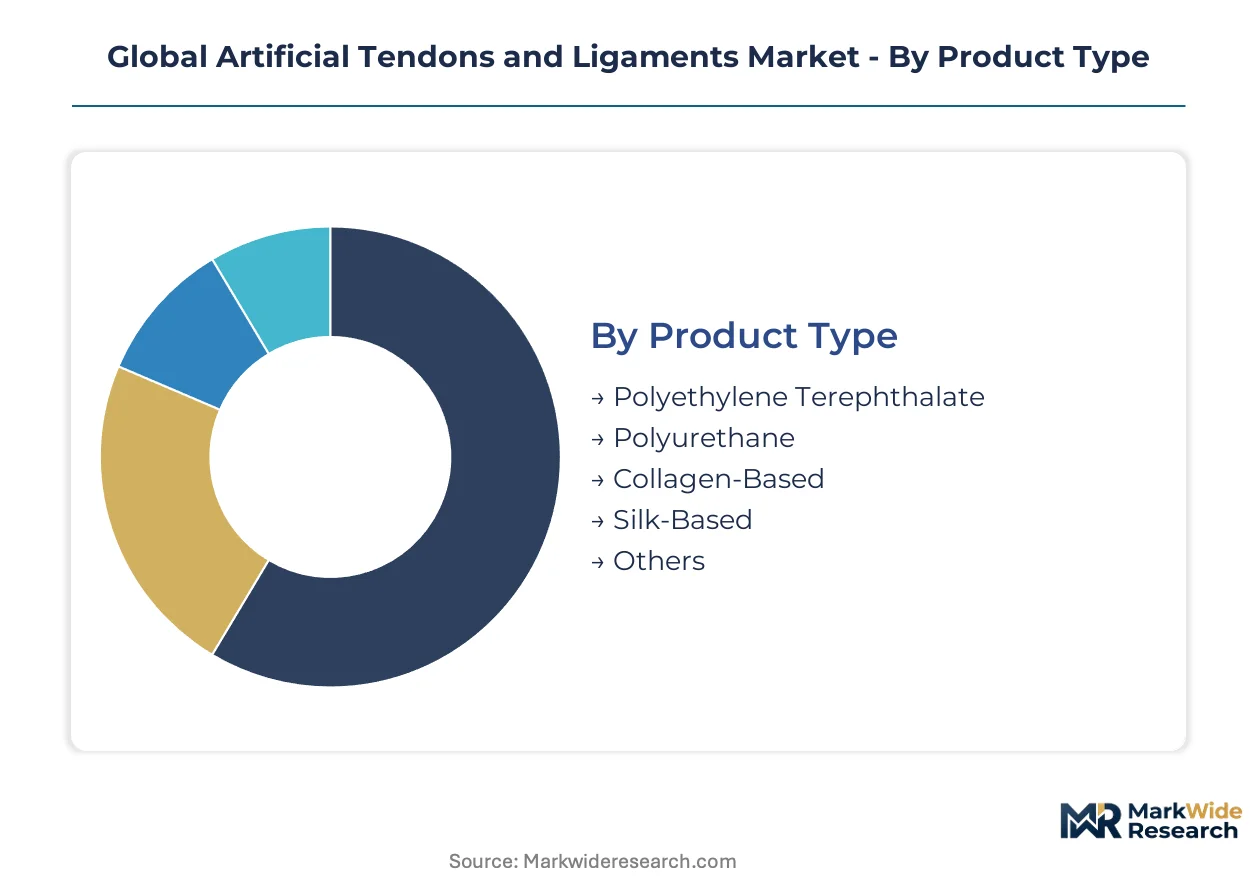
Synthetic ligament manufacturers engineer material specifications around load-bearing requirements and biointegration timelines. Segmentation reveals how polymer chemistry, surgical application, and manufacturing technology intersect to determine procurement decisions across German university hospitals and Asian cost-optimized markets.
Product Type:
Material composition determines tensile strength thresholds, degradation profiles, and regulatory classification pathways for permanent implantable devices.
- Polyethylene Terephthalate:High-tenacity PET fibers deliver tensile strengths exceeding 50 MPa with decades of clinical validation in ACL reconstruction. German orthopedic clinics prioritize PET ligaments for predictable mechanical performance under ISO 10993 biocompatibility frameworks.
- Collagen-Based:Bioresorbable matrices derived from purified collagen enable cellular infiltration and staged mechanical-to-biological transition. Swiss university hospitals are rotating procurement toward collagen platforms despite longer fixation timelines.
- Polyurethane:Elastomeric segments provide fatigue resistance for dynamic tendon applications.
- Silk-Based:Bombyx mori fibroin constructs offer tunable degradation kinetics.
- Others:PTFE and carbon fiber composites serve niche load-bearing requirements.
PET holds installed capacity across European chemical conglomerates. Collagen-based platforms are rotating up the share rankings in premium surgical centers.
Application:
Surgical indication dictates implant geometry, fixation hardware compatibility, and rehabilitation protocol integration.
- Anterior Cruciate Ligament Reconstruction:The highest-volume ligament procedure demands implants with immediate tensile strength and controlled porosity for bone tunnel integration. Sports medicine centers in Germany and Switzerland account for concentrated procurement volume through streamlined reimbursement.
- Rotator Cuff Repair:Shoulder tendon reconstruction requires suture-compatible implant designs with abrasion resistance against acromial arch contact. Bavarian shoulder specialists are driving adoption of synthetic augmentation for massive tears.
- Achilles Tendon Repair:High-load lower extremity applications prioritize fatigue-resistant fiber architectures.
- Medial Collateral Ligament Repair:Knee stabilization procedures favor anatomic footprint-matching geometries.
- Patellar Tendon Reconstruction:Extensor mechanism restoration demands quadriceps load-bearing specifications.
ACL reconstruction holds installed capacity across sports medicine infrastructure. Rotator cuff repair is rotating up the share rankings with shoulder specialist concentration.
End User:
Customer type determines procurement authority, pricing tolerance, and training ecosystem requirements.
- Orthopedic Clinics:Specialized outpatient facilities concentrate decision-making with individual surgeons who prioritize device familiarity and instrumentation compatibility. German private orthopedic chains negotiate direct procurement contracts bypassing distributor markups.
- Sports Medicine Centers:Dedicated athletic injury facilities demand rapid-return-to-play protocols and integrated rehabilitation tracking. Bundesliga team medical departments in Munich and Dortmund source synthetic ligaments through manufacturer-direct relationships.
- Rehabilitation Facilities:Post-operative care centers influence implant selection through outcome data feedback.
- Surgical Hospitals:General acute care institutions balance cost containment with inventory standardization.
Orthopedic clinics hold installed capacity with surgeon-driven purchasing. Sports medicine centers are rotating up the share rankings through professional sports integration.
Technology:
Manufacturing methodology controls fiber architecture, surface topology, and degradation kinetics that determine biological acceptance.
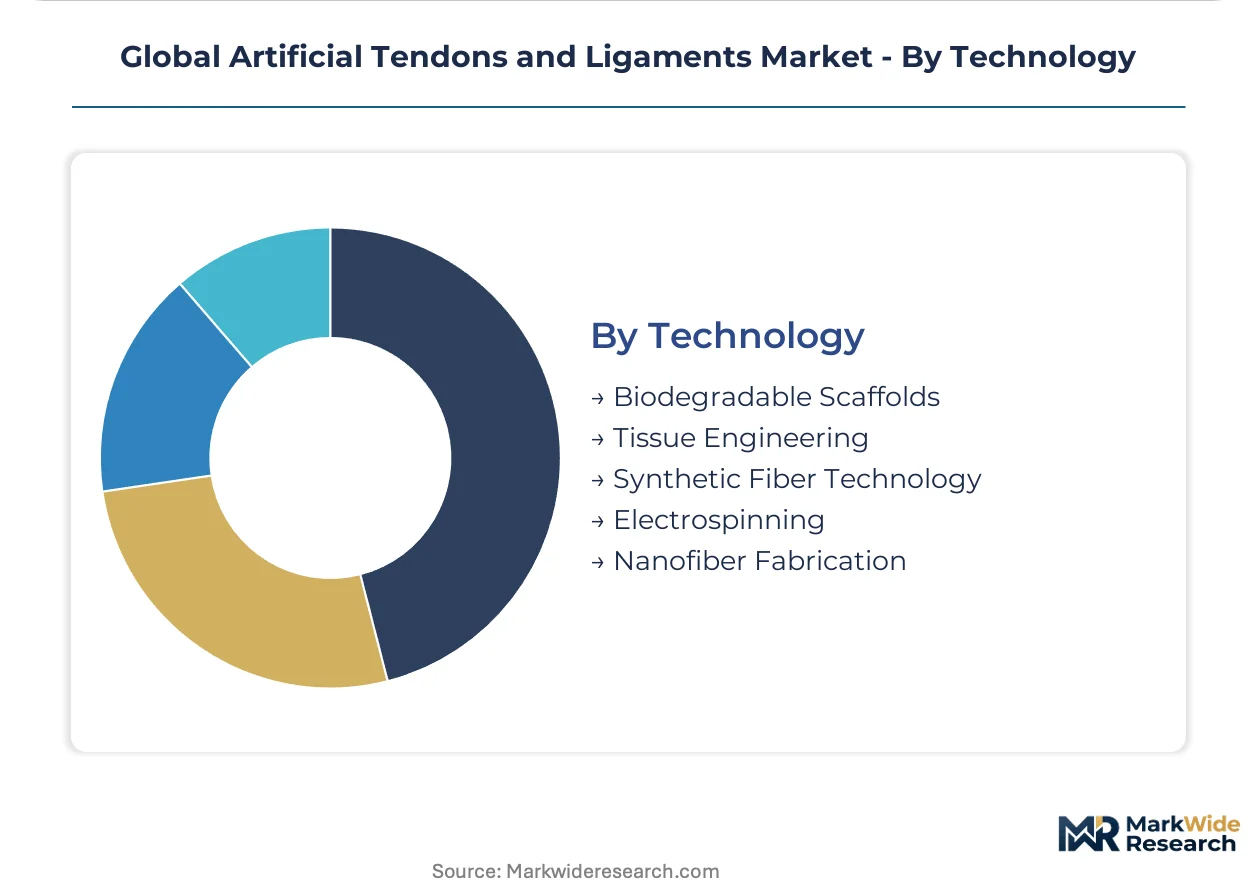
- Electrospinning:Nanofiber production enables simultaneous control of pore size distribution and mechanical anisotropy. Basel and Boston corridor cleanroom infrastructure concentrates GMP-compliant scale-up capacity for this process.
- Synthetic Fiber Technology:Conventional weaving and braiding of medical-grade polymers delivers predictable load-bearing with established sterilization protocols. European chemical conglomerates control high-tenacity yarn supply.
- Biodegradable Scaffolds:Resorbable polymer platforms enable temporary mechanical support with staged replacement by host tissue.
- Tissue Engineering:Cell-seeded constructs require bioreactor infrastructure and extended regulatory pathways.
- Nanofiber Fabrication:Alternative electrospinning approaches include solution blow spinning and centrifugal spinning.
Synthetic fiber technology holds installed capacity with decades of clinical documentation. Electrospinning is rotating up the share rankings with nanofiber biointegration performance gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes synthetic ligaments through specialized orthopedic clinics prioritizing mechanical reliability, while Swiss university hospitals favor biointegration performance over immediate tensile strength. India represents an emerging volume opportunity where cost-optimized PET solutions address government hospital modernization programs.
Germany
Bavarian and North Rhine-Westphalian sports medicine centers drive concentrated procurement through streamlined reimbursement pathways for ACL reconstruction. BfArM harmonizes post-market surveillance expectations with Swissmedic, mandating standardized adverse event reporting for Class III permanent implants. The Basel-Boston corridor extends into Baden-Württemberg through specialized cleanroom infrastructure for electrospinning scale-up.
Switzerland
Swiss university hospitals in Zurich prioritize collagen-scaffold platforms enabling staged mechanical-to-biological transition over PET's immediate fixation strength. Swissmedic tightens clinical evaluation requirements for permanent implants, advantaging manufacturers with decade-long ligament registries. Mathys AG Bettlach anchors specialized synthetic ligament manufacturing in the Basel region through dedicated production footprints.
United States
FDA 510(k) clearance pathways filter participation toward capitalized manufacturers with dedicated regulatory affairs infrastructure and established ISO 10993 documentation. The agency weighs long-term degradation profiles against revision surgery risks in evolving guidance on permanent synthetic ligaments. Boston corridor cleanroom infrastructure concentrates GMP-compliant electrospinning capacity alongside Basel.
India
Government hospital modernization programs and private sports medicine clinic chains in Mumbai and Delhi create first-mover windows for cost-optimized PET ligament suppliers. The country's national pharmaceutical regulator imposes biocompatibility testing burdens that favor suppliers with existing ISO 10993 frameworks. Shanghai PINE&POWER Biotech competes on cost-optimized PET fiber production targeting emerging Asian markets including Indian procurement channels.
China
Domestic manufacturers leverage integrated textile-polymer supply chains for medical-grade PET yarn production serving regional orthopedic device assemblers. NMPA Class III implantable device requirements align with international biocompatibility standards while prioritizing local clinical trial data. Yangtze River Delta chemical conglomerates control high-tenacity fiber capacity that feeds both domestic device makers and export-oriented suppliers.
Global Artificial Tendons and Ligaments Market Competitive Landscape
Capability concentration sits with specialized polymer platform developers; scale advantage sits with diversified orthopedic conglomerates. The vendor base stratifies across three tiers: integrated sports medicine portfolios commanding premium positioning, dedicated synthetic ligament specialists with focused manufacturing footprints, and cost-optimized Asian suppliers competing on PET fiber production economics. Dominant competitive moves include regulatory registration synchronization across FDA and EU MDR pathways, plus direct procurement relationships with professional sports medical departments that bypass traditional distributor markups.
Among European specialists, Mathys AG Bettlach and Cousin Biotech occupy positions within the dedicated manufacturing tier, while Arthrex exemplifies integrated sports medicine portfolio strategy. Shanghai PINE&POWER Biotech represents the cost-optimized production archetype targeting emerging market volume. Stryker anchors diversified orthopedic conglomerate positioning through established hospital network distribution. These players collectively illustrate how regulatory documentation depth, manufacturing specialization, and procurement channel control define competitive differentiation.
| Leading Market Players |
|---|
| LARS |
| Neoligaments |
| Cousin Biotech |
| Orthomed |
| FX Solutions |
| Shanghai PINE&POWER Biotech |
| Mathys AG Bettlach |
| Arthrex |
| Stryker |
| Others |
Supply & Pricing Matrix
Undercapacity in high-tenacity medical-grade PET yarn production across European chemical conglomerates is compressing supplier margins while elevating pricing power for fiber producers serving synthetic ligament assemblers. This utilization squeeze forces mid-tier device manufacturers into longer-term offtake commitments or spot market exposure, reshaping procurement cost structures across German orthopedic clinics and Asian cost-optimized markets.
Pricing Analysis
Long-term offtake contracts dominate procurement between high-tenacity PET yarn producers and synthetic ligament manufacturers, with spot purchasing limited to formulation adjustments and small-batch collagen-scaffold inputs. Three-tier pricing structure across premium, standard, and economy levels separates MDR-compliant technical documentation tiers from basic ISO 10993 certification grades, with volume scale and after-sales surgical training bundling as secondary differentiation drivers. Pricing pressure stems from REACH substance reformulation cycles extending development timelines for PET fiber platforms. Government hospital systems in Southern Europe and Latin America exhibit highest price sensitivity, while Swiss and German university hospitals prioritize biointegration performance over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard between European chemical conglomerates and mid-tier device assemblers, with supply-chain finance facilities emerging as working capital bridges. High-tenacity medical-grade PET yarn capacity concentrates in Germany, Switzerland, and China's Yangtze River Delta, drawing from purified terephthalic acid and ethylene glycol feedstocks alongside collagen purification bioreactor infrastructure. Single-source vulnerability in specialty nanofiber cleanroom equipment creates chokepoint risk for electrospinning scale-up. Distribution runs through direct procurement relationships with Bundesliga team medical departments and specialized orthopedic clinic chains, bypassing traditional distributor markups in concentrated German and Swiss markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical training ecosystem attach rates are expanding faster than hardware unit sales, as sports medicine fellowship programs in Zurich and Munich mandate manufacturer-specific ligament placement modules that lock in recurring education revenue alongside implant procurement.
For Market Incumbents: Build regulatory documentation moats by synchronizing FDA 510(k) submissions with EU MDR notified body pathways, compressing review timeline advantages over capital-constrained entrants. Invest in captive supply of high-tenacity PET yarn through backward integration into European chemical conglomerate offtake agreements, insulating against input cost volatility. Defend against collagen-scaffold substitution by embedding electrospinning nanofiber architectures into premium tier offerings. For New Entrants and Emerging Players: Build out India orthopedic infrastructure relationships through cost-optimized PET ligament production targeting government hospital modernization programs in Mumbai and Delhi. Private sports medicine clinic chains in these cities represent the most penetrable segment, with procurement decisions concentrated among individual surgeons rather than committee-based purchasing. Establish direct manufacturer relationships with emerging market distributors to bypass legacy orthopedic conglomerate channel control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrospinning technology developers with GMP-compliant cleanroom infrastructure in the Basel-Boston corridor, where nanofiber platform licensing creates annuity streams beyond device sales. Long-term viability over the five-to-ten year window favors manufacturers with decade-long PET ligament registries satisfying EU MDR clinical evaluation requirements. Watch FDA guidance evolution on permanent synthetic ligament degradation profiles as the critical inflection signal for portfolio rebalancing toward bioresorbable matrix platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | BfArM harmonization with Swissmedic creates defensible quality differentiation for Class III permanent implants. |
| Electrospinning GMP Scale-Up | Basel and Boston corridor cleanroom infrastructure concentrates nanofiber biointegration capability. |
| Direct Procurement Relationships | Bundesliga team medical departments in Munich and Dortmund bypass traditional distributor markups. |
| Collagen-Scaffold Hybrid Development | Swiss university hospitals prioritize cellular infiltration over immediate tensile strength in procurement decisions. |
| India Market Entry Partnership | Government hospital modernization programs in Mumbai and Delhi create first-mover windows for cost-optimized suppliers. |
Research Methodology
Cross-validation between primary interviews with orthopedic surgeons, sports medicine fellowship directors, and hospital purchasing committee members anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, and ISO 10993 biocompatibility test reports. Bottom-up triangulation across synthetic ligament unit demand from German and Swiss sports medicine centers converges with top-down market sizing from polymer feedstock capacity disclosures.
Calibration against historical PET ligament adoption curves and collagen-scaffold clinical trial progression informs the analytical framework across the projection horizon. Segmentation dimensions modeled include material composition, surgical application, end-user facility type, and manufacturing technology complexity. CAGRs derive from regression analysis of procedure volume growth, reimbursement pathway evolution, and regulatory approval timeline compression.
Stress conditions across REACH substance restriction severity, EU MDR notified body backlog duration, and electrospinning scale-up success rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on procedure adoption curves and regulatory harmonization progress. Macroeconomic contraction, unexpected FDA guidance shifts, or breakthrough bioresorbable platform efficacy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
South Korea Massage Equipment Market
Medical Devices
Sphincterotomes Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Prescription Lens Market
Medical Devices
Bandage Contact Lenses Market
Medical Devices
Acoustic Puncture Assist Devices Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Latin America Implantable Medical Devices Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Power Smart Bed Market
Medical Devices
Neurotechnology Market