
 Global Micro Guide Catheters Market | 2026-2036
Global Micro Guide Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micro Guide Catheters Market Foresight
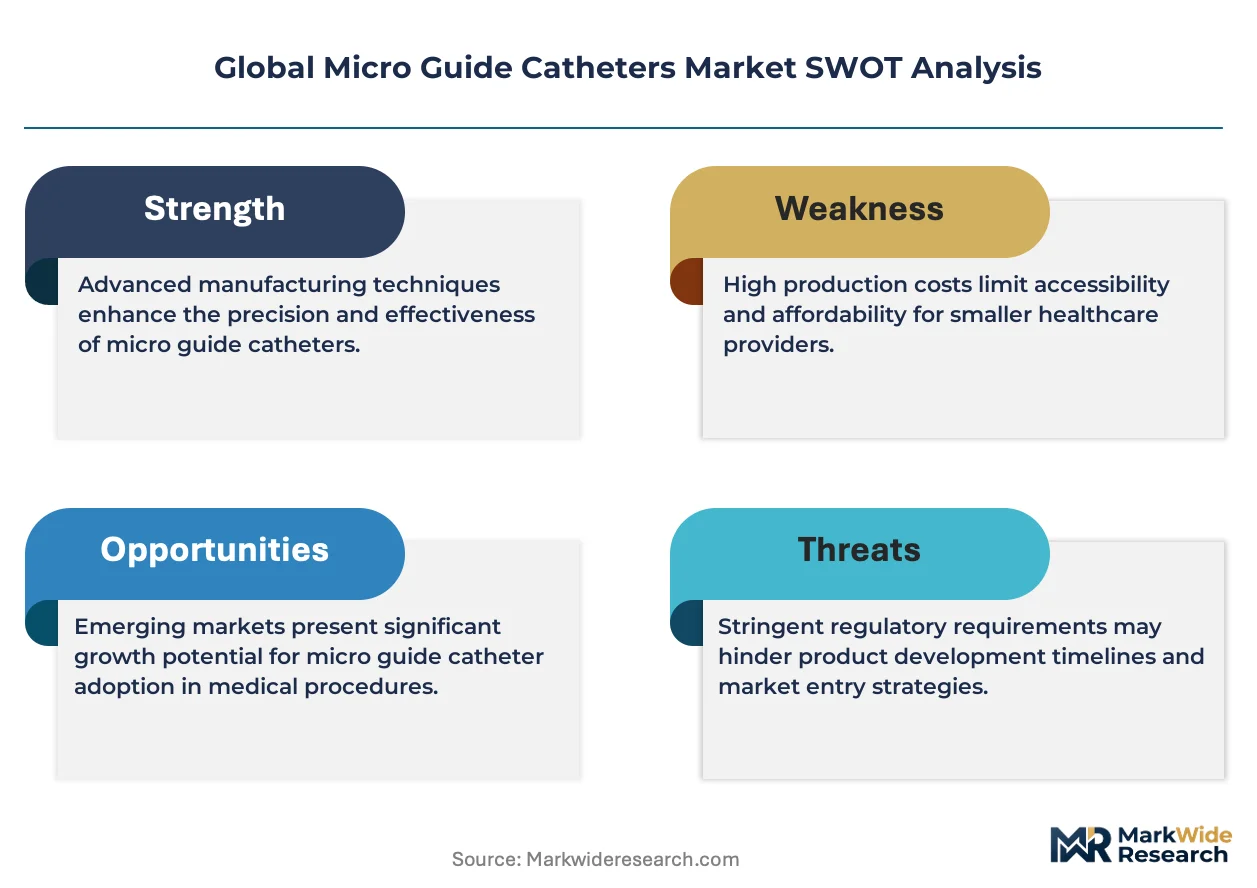
Modular catheter kits that pair micro guide catheters with compatible accessories are repositioning procurement decisions in interventional suites. Boston Scientific Corporation leverages integrated delivery ecosystems to sustain preference among high-volume cardiology centers. Terumo Corporation anchors its position through proprietary hydrophilic coating technologies that dominate Japanese and European hospital supply chains. Merit Medical Systems differentiates via specialized neurovascular configurations that occupy a narrow but defensible niche in stroke intervention workflows.
Micro guide catheters are thin-walled, torque-responsive delivery devices typically constructed from polyamide, polyimide, or Pebax multilayer shafts with distal radiopaque markers, designed to navigate tortuous vasculature and support guidewire exchange or device delivery during minimally invasive procedures. Hydrophilic-coated variants lead procedural volume in coronary and peripheral applications where lubricity reduces vessel trauma, while dual-lumen configurations represent the fastest-expanding segment as operators demand simultaneous guidewire and device channels for complex bifurcation lesions. Neurosurgery clinics and specialized stroke centers now constitute the highest-margin end-user pool, with outpatient facilities trailing due to reimbursement constraints on advanced interventional equipment.
FDA 510(k) premarket notification requirements and the EU MDR's stricter clinical evidence standards are extending development timelines and consolidating market access among manufacturers with established quality management systems. Japan's PMDA and China's NMPA maintain distinct biocompatibility and sterilization validation protocols that fragment regulatory strategy for multinational suppliers. Stakeholders must monitor evolving notified body capacity in Europe and FDA digital health pre-certification pilots that could eventually encompass imaging-integrated catheter platforms.
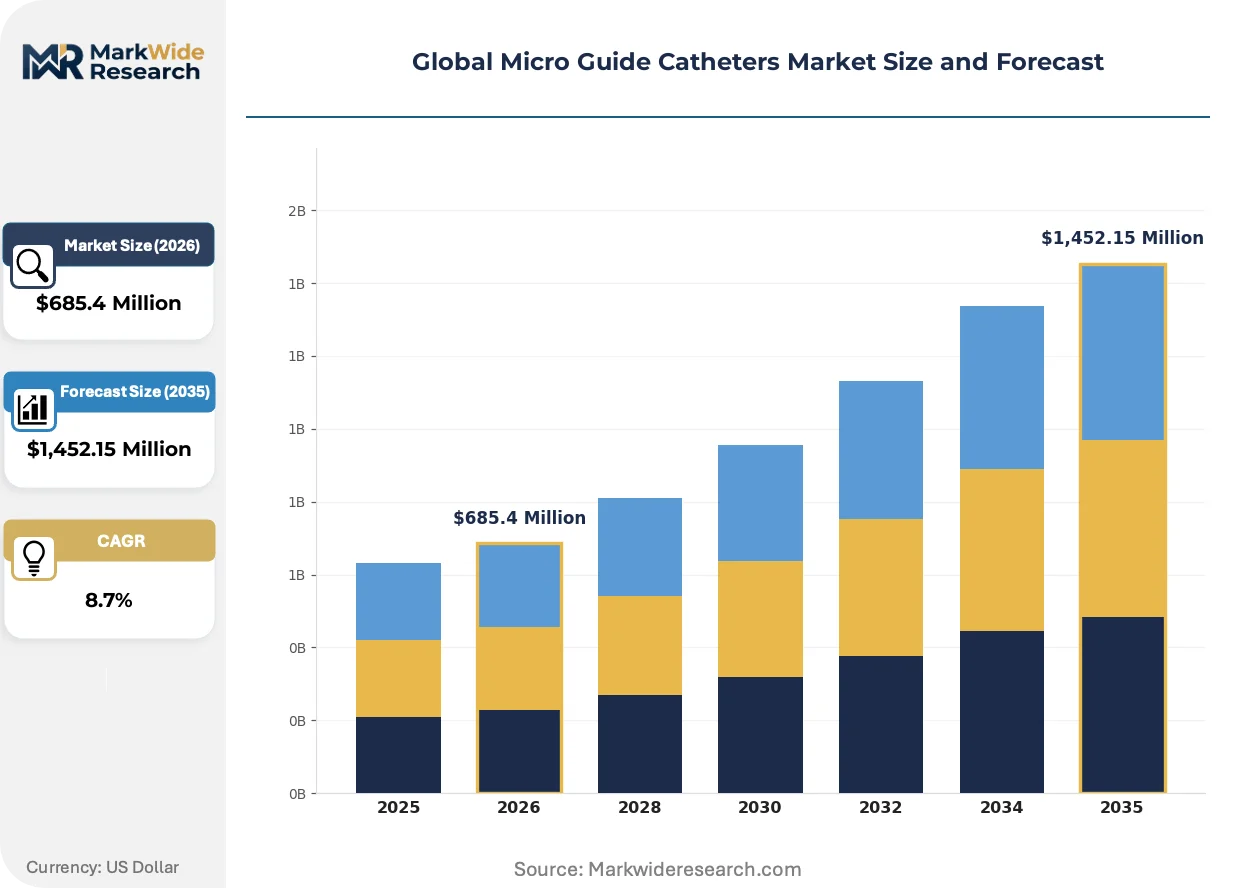
Market Dynamics
Dual-lumen catheter configurations are compressing procedural complexity into single-device workflows, forcing manufacturers to reengineer shaft geometries while hydrophilic coating chemistry becomes the primary battleground for differentiation among interventional suites.
Growth Catalysts
- EU MDR clinical evidence requirements:Stricter post-market surveillance mandates are filtering out marginal suppliers and concentrating procurement authority among hospital systems with established quality frameworks.
- Japanese stroke center certification:METI-backed specialized neurovascular facility designations are accelerating catheter utilization in complex aneurysm and intracranial stenosis procedures.
- Pebax multilayer shaft construction:Advanced polymer lamination techniques are extending trackability limits in tortuous coronary anatomy, expanding addressable lesion complexity.
Market Restraints
- Nitinol hypotube supply concentration:Precision tubing fabrication for torque transmission layers clusters among Japanese and German specialty metallurgy suppliers, creating input vulnerability.
- FDA 510(k) predicate device limitations:Novel dual-lumen geometries face extended review timelines when existing clearance pathways lack comparable device references.
- Reimbursement compression in outpatient settings:CMS facility fee differentials favor hospital-based catheterization labs over ambulatory surgical centers for complex interventions.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are opening cost-optimized production bases for export-oriented catheter suppliers.
- Robotic navigation integration:Magnetic and electromechanical guidance platforms are creating demand for catheter designs with embedded sensor compatibility.
- China's NMPA innovation fast-track:Priority review pathways for breakthrough devices are shortening market entry timelines for novel coating technologies.
Industry Challenges
- Polymer extrusion technician scarcity:Multilayer shaft fabrication requires specialized process engineering expertise concentrated among legacy medical device manufacturing regions.
- ISO 10993 biocompatibility testing backlog:Extended cytotoxicity and hemocompatibility validation timelines are compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micro Guide Catheters Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophilic, Non-Hydrophilic, Dual Lumen, Coil, Braided Application: Neurovascular, Peripheral Vascular, Coronary, Urological, Gastrointestinal Technology: Balloon-Assisted, Rapid Exchange, Over-The-Wire, Steerable, Imaging Integrated End User: Cardiology Centers, Neurosurgery Clinics, Outpatient Facilities, Specialized Laboratories |
| Companies Covered | Medtronic, Boston Scientific Corporation, Terumo Corporation, Stryker, Merit Medical Systems, Penumbra, Inc., Cook, Teleflex Incorporated, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micro Guide Catheters Market Shifts & Advancements
Catheter platform architectures are converging around integrated delivery ecosystems where device, guidewire, and accessory compatibility locks purchasing decisions into single-vendor relationships.
Shape-memory polymer distal tips are unifying lesion crossing and device support functions in single catheter designs. High-volume interventional cardiology centers in Germany and the United States are phasing out dedicated exchange catheters in favor of these hybrid configurations. The technology is unifying previously separate device categories and compressing SKU proliferation in hospital supply chains.
Japan's PMDA has tightened sterilization validation requirements for hydrophilic-coated devices, mandating residual solvent testing beyond ISO 10993 baseline standards. Manufacturers must now submit accelerated aging data specific to coating polymer degradation profiles. Neurovascular product lines face the steepest compliance burden, with several notified bodies requiring supplemental clinical follow-up for coated intracranial devices.
Hospital procurement committees are consolidating catheter purchasing into multi-year sole-source agreements with technical performance guarantees. Interventional suites in France and the Netherlands are replacing spot-buying with contracted utilization tiers that penalize off-contract consumption. This concentration is most visible in academic medical centers where value analysis committees now mandate head-to-head trackability benchmarking before contract renewal.
Global Micro Guide Catheters Market Segmentation
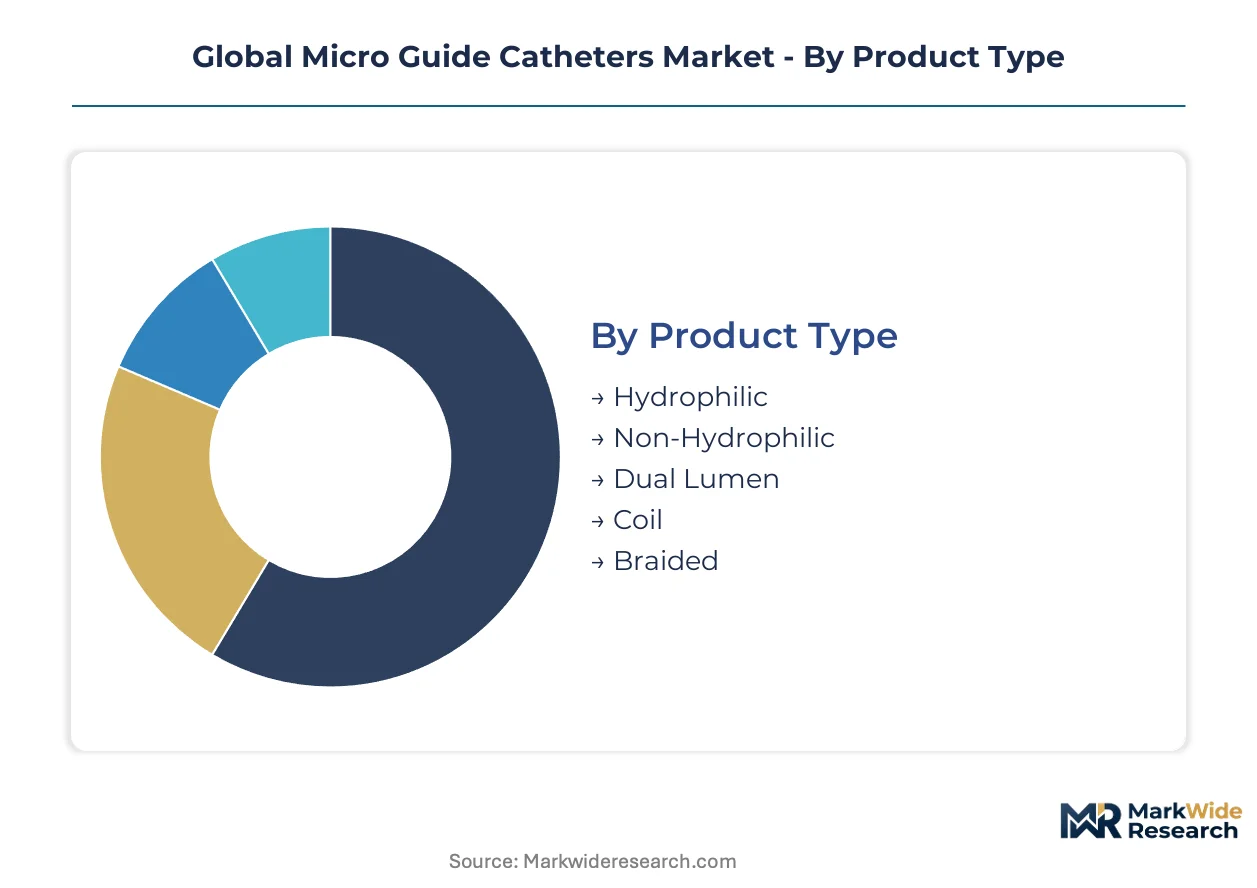
Micro guide catheter procurement decisions fragment across technical specifications, procedural complexity, and institutional capability tiers. Manufacturers engineer portfolio depth around coating chemistry, shaft construction, and lumen architecture to capture specific intervention workflows.
Product Type:
Coating technology and lumen configuration define the primary axis of competitive differentiation and clinical utility.
- Hydrophilic:Polyvinylpyrrolidone or polyethylene oxide surface treatments reduce friction coefficients during tortuous navigation. German and Japanese interventional cardiology centers specify these variants for complex coronary lesions where vessel trauma minimization is paramount.
- Dual Lumen:Parallel or coaxial channel designs enable simultaneous guidewire stability and device delivery through a single access site. Neurovascular specialists in US academic medical centers are expanding utilization for bifurcation aneurysm treatments requiring parallel wire techniques.
- Non-Hydrophilic:Uncoated polyamide or polyimide shafts serve cost-sensitive procurement tiers and specific procedures where tactile feedback outweighs lubricity requirements.
- Coil:Stainless steel or platinum coil-reinforced shafts provide kink resistance in peripheral vascular applications requiring extended reach through femoral access.
- Braided:Flat-wire mesh construction delivers torque transmission precision for coronary interventions demanding rotational control.
Hydrophilic variants lead on procedural volume; dual-lumen configurations lead on momentum.
Application:
Anatomical target and lesion complexity determine catheter specification requirements and reimbursement economics.
- Neurovascular:Intracranial navigation demands ultra-low-profile shafts with distal flexibility gradients. Japanese stroke centers certified under METI specialized facility programs are expanding procedural volume for aneurysm coiling and intracranial stenosis interventions.
- Coronary:Chronic total occlusion and calcified lesion subsets require hybrid coating and reinforcement combinations. US hospital systems with bundled payment contracts favor trackability-optimized platforms that reduce procedure time.
- Peripheral Vascular:Below-the-knee and pedal access procedures utilize extended-length configurations with enhanced pushability.
- Urological:Renal and prostatic access applications employ shorter working lengths with specialized tip geometries.
- Gastrointestinal:Biliary and pancreatic interventions utilize hydrophilic variants for stricture navigation.
Coronary applications anchor revenue scale; neurovascular applications command premium positioning.
Technology:
Delivery mechanism architecture shapes operator workflow efficiency and device compatibility requirements.
- Over-The-Wire:Full-length guidewire lumen enables wire exchange without catheter removal. Complex coronary interventions in German high-volume centers maintain preference for this traditional architecture.
- Rapid Exchange:Short guidewire exit ports reduce assistant dependence and procedure time. US outpatient catheterization labs specify these configurations for throughput optimization.
- Balloon-Assisted:Integrated inflation lumens support simultaneous angioplasty and delivery functions.
- Steerable:Deflectable distal tips enable active navigation in tortuous anatomy without wire support.
- Imaging Integrated:Embedded sensor channels accommodate intravascular ultrasound or optical coherence tomography compatibility.
Over-the-wire systems retain installed base dominance; rapid exchange platforms are gaining share fastest.
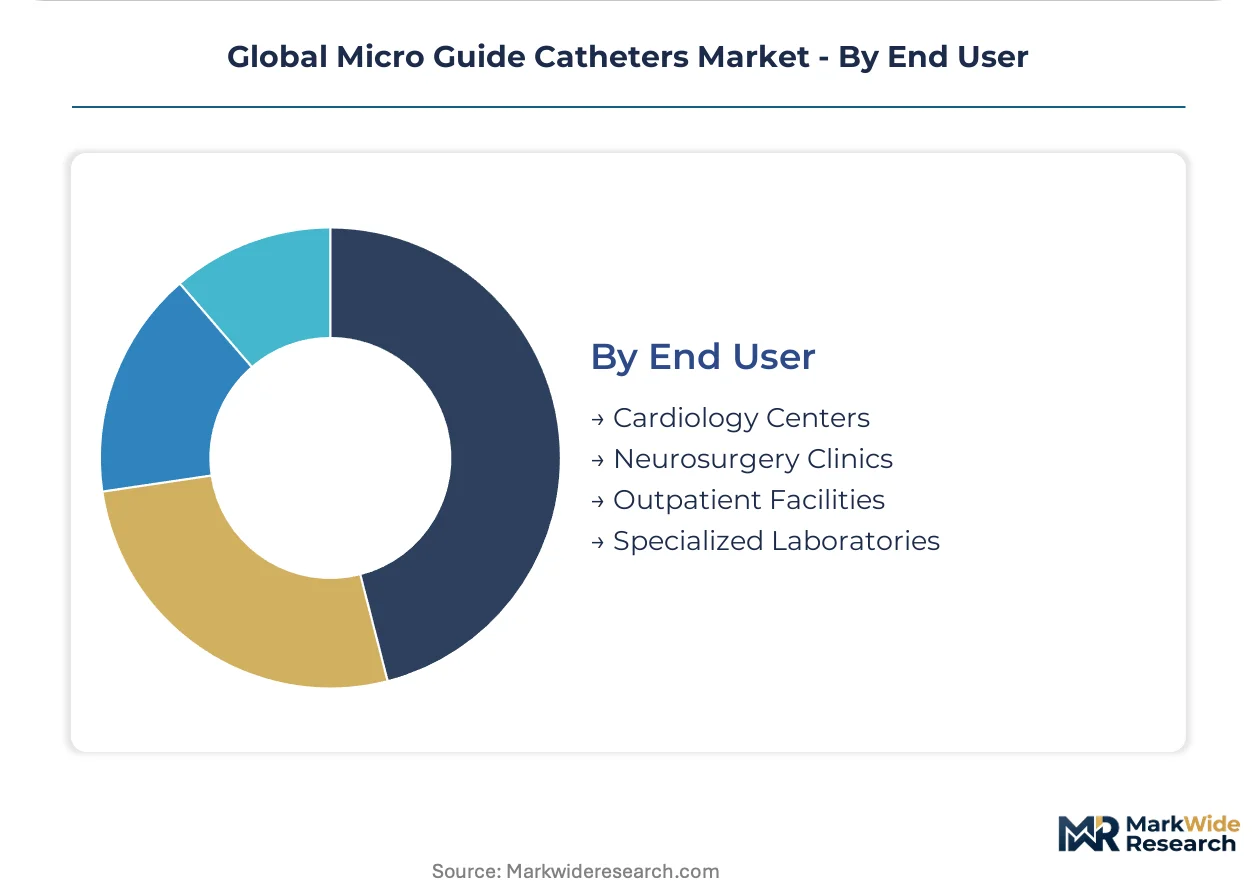
End User:
Institutional scale and specialization level determine procurement authority and technical specification intensity.
- Cardiology Centers:High-volume interventional suites in the United States and Germany consolidate purchasing through multi-year sole-source agreements with utilization guarantees and technical performance benchmarking.
- Neurosurgery Clinics:Specialized stroke and cerebrovascular facilities in Japan command premium pricing tolerance for coating technologies and distal flexibility optimization.
- Outpatient Facilities:Ambulatory surgical centers face CMS reimbursement compression that constrains advanced catheter procurement.
- Specialized Laboratories:Research and training institutions drive early adoption of steerable and imaging-integrated platforms.
Cardiology centers concentrate procurement volume; neurosurgery clinics concentrate margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional cardiology and neurovascular procedural innovation traces its commercial roots to Minnesota's medical device corridor and Germany's precision engineering clusters, with subsequent scaling across Japanese manufacturing centers and emerging production bases in India and China.
United States
Hospital systems in Minneapolis-St. Paul and Boston anchor procurement volume for complex coronary interventions. FDA 510(k) clearance pathways govern market access for dual-lumen and hydrophilic-coated variants. The Research Triangle Park corridor in North Carolina concentrates catheter manufacturing facilities serving domestic and export demand.
Germany
Rhineland cardiology centers specify trackability-optimized platforms for chronic total occlusion procedures. EU MDR clinical evidence requirements filter supplier participation toward established quality management systems. The Freiburg-Tübingen-Stuttgart triangle hosts specialized polymer extrusion facilities supplying multilayer shaft components.
Japan
METI-certified stroke centers in Tokyo and Osaka drive premium catheter utilization for intracranial aneurysm treatments. PMDA sterilization validation mandates for hydrophilic-coated devices exceed ISO 10993 baseline standards. Nagoya-based precision metallurgy suppliers dominate nitinol hypotube fabrication for torque transmission layers.
China
NMPA innovation fast-track pathways accelerate market entry for novel coating technologies in Shanghai and Beijing hospital systems. Domestic manufacturing capacity expansion in Suzhou and Shenzhen targets cost-optimized production for regional supply. Provincial centralized procurement frameworks compress pricing for standard configurations.
India
PLI scheme incentives for medical devices attract catheter assembly operations to Gujarat and Karnataka export zones. CDSCO regulatory harmonization efforts streamline import substitution for hydrophilic variants. Chennai and Hyderabad emerging as training hubs for interventional specialists driving procedural volume growth.
Global Micro Guide Catheters Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating chemistry specialization and regulatory dossier depth. The vendor base stratifies into three tiers: integrated delivery ecosystem architects, proprietary technology specialists, and regional cost-optimized fabricators. Dominant competitive moves include strategic partnerships for coating chemistry access and backward integration into polymer extrusion capabilities.
Within the integrated delivery ecosystem tier, Boston Scientific Corporation and Terumo Corporation exemplify archetype positioning through comprehensive portfolio breadth. Merit Medical Systems occupies a specialist position in neurovascular configurations. These three entities anchor competitive dynamics through differentiated technical capabilities rather than scale-driven cost positioning alone.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Terumo Corporation |
| Stryker |
| Merit Medical Systems |
| Penumbra, Inc. |
| Cook |
| Teleflex Incorporated |
| Cardinal Health |
| Others |
Supply & Pricing Matrix
Polymer extrusion technician scarcity in Minnesota's medical device corridor and Baden-Württemberg's precision engineering clusters feeds directly into pricing-tier spreads. Labor-cost differentials between these legacy manufacturing regions and emerging assembly bases in Gujarat widen the gap between premium hydrophilic-coated variants and standard non-coated configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates catheter procurement. Price differentiation rests on FDA 510(k) clearance tier and hydrophilic coating chemistry grade. Cost compression in economy-tier non-hydrophilic variants is intensifying because India's PLI scheme enables domestic manufacturing at reduced labor input. Ambulatory surgical centers exhibit highest price sensitivity; Japanese METI-certified stroke centers demonstrate lowest.
Supply Chain Analysis
Freight cost escalation for temperature-controlled polymer resin shipments from Germany to US assembly plants is reshaping regional sourcing patterns. Nitinol hypotube fabrication concentrates in Japan's Nagoya precision metallurgy belt and Germany's specialty tubing suppliers. Raw material dependencies include Pebax elastomer resins, polyimide films, and platinum-iridium radiopaque markers. Single-source vulnerability in Japanese nitinol supply creates structural risk. Distribution runs through hospital GPO contracts and specialized interventional cardiology distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Micro Guide Catheters Market functions as a stable compounder anchored by chronic disease procedural volumes that resist cyclical demand fluctuation.
For Market Incumbents: Acquire proprietary coating chemistry IP to defend against emerging entrants with novel surface treatment platforms. Backward integration into polymer extrusion capabilities in Freiburg-Tübingen-Stuttgart triangle secures shaft component supply. Hospital system sole-source contract renewal cycles represent the critical lever for volume retention. For New Entrants and Emerging Players: China's NMPA innovation fast-track opens a window for breakthrough hydrophilic coating technologies seeking accelerated market entry. Neurovascular dual-lumen configurations in US academic medical centers offer the most penetrable white-space target. Go-to-market execution should prioritize head-to-head trackability benchmarking against incumbent platforms. For Investors and Strategic Acquirers: Medical device conglomerates with interventional cardiology portfolios are the most active acquirer in this space. Five-to-ten-year viability hinges on regulatory dossier depth and coating chemistry differentiation. Target acquisition archetype: mid-scale specialists with proprietary shaft construction patents and established EU MDR quality systems. Signal to watch: notified body capacity constraints extending competitor product launch timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Pathway Expansion | Novel dual-lumen geometries gain faster clearance through established device references. |
| EU MDR Quality System Investment | Notified body capacity constraints filter marginal suppliers from German hospital procurement. |
| Hospital System Partnership | Sole-source agreements with utilization guarantees lock purchasing decisions in US cardiology centers. |
| Coating Chemistry Licensing | Proprietary hydrophilic surface treatments differentiate Terumo's position in Japanese supply chains. |
| Reimbursement Strategy | CMS facility fee differentials favor hospital-based labs over ambulatory surgical centers. |
Research Methodology
Bottom-up interventional procedure volume modeling reconciled against top-down catheter shipment tracking forms the analytical core. Primary interviews with interventional cardiologists, neurovascular surgeons, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers combine with secondary validation from FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement schedules, and Japanese METI stroke center certification records.
Input-output matrices map procedural volume drivers across coating technology, lumen configuration, application anatomy, and end-user institutional tier. CAGRs derive from segmented demand elasticity coefficients and replacement cycle dynamics. Forecast inputs incorporate PMDA sterilization validation timeline shifts and nitinol hypotube supply concentration indices.
Revisions become necessary when EU notified body capacity constraints intensify, PMDA tightens hydrophilic coating residual solvent mandates, or India's PLI scheme accelerates domestic production scale. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Implantable Defibrillators Market