
 Self-Destructing Syringe Market | 2026-2036
Self-Destructing Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Destructing Syringe Market Insights
The WHO PQS prequalification mandate for immunization devices is pivoting procurement toward mechanically irreversible auto-disable designs. BD leverages backward integration into precision molding to sustain cost leadership across high-volume tenders. Star Syringes anchors its position through dedicated R&D on metal-free breakaway mechanisms for tropical climates. Univec differentiates via concentrated manufacturing scale serving African and South Asian ministry of health contracts.
A self-destructing syringe incorporates a single-use activation feature—typically a plunger lock, snap-ring fracture, or retractable needle carrier—that physically prevents re-aspiration after injection, with barrel materials specified for polypropylene or cyclo-olefin polymer to ensure dimensional stability under gamma sterilization. Its primary purpose is eliminating needle reuse in resource-limited settings where sterilization infrastructure remains unreliable. Auto-disable syringes dominate volume procurement for Gavi-aligned national immunization programs, while safety syringes command premium positioning in European hospital systems requiring sharps-injury compliance. Prefilled formats are capturing fastest-growing share as biologics manufacturers seek integrated delivery systems with built-in tamper evidence.
The FDA enforces 510(k) clearance for retraction-activated devices under sharps injury prevention rules, while the EMA MDR framework mandates clinical evidence of passive safety feature reliability across European Economic Area markets. WHO PQS prequalification functions as the de facto gatekeeper for developing-country procurement, with failing audit protocols excluding suppliers from UNICEF and PAFO tenders. Stakeholders must monitor evolving biodegradability mandates from India's Central Drugs Standard Control Organisation and the EU Green Deal's pressure on medical plastic waste streams.
Market Dynamics
WHO PQS prequalification mandates are compressing supplier qualification timelines while mechanically irreversible auto-disable designs displace conventional safety syringes in high-volume immunization tenders across Sub-Saharan Africa and South Asia.
Growth Catalysts
- EU MDR technical barriers:Sharps-injury prevention rules under the Medical Device Regulation are elevating procurement specifications for passive safety features in European hospital systems.
- Biologics delivery integration:Prefilled auto-disable formats are capturing share as pharmaceutical manufacturers seek tamper-evident delivery systems with built-in needle re-use prevention.
- India's export manufacturing base:Domestic producers in Gujarat and Tamil Nadu are scaling cyclo-olefin polymer molding capacity to serve ministry of health contracts across Southeast Asia and Africa.
Market Restraints
- Gamma sterilization infrastructure gaps:Polypropylene dimensional stability requirements demand capital-intensive electron-beam or gamma facilities that concentrate in industrial corridors near Mumbai and Shenzhen.
- Metal-free mechanism R&D costs:Tropical climate compatibility for breakaway ring designs requires specialized polymer formulations with limited supplier bases.
- Prefilled format cold chain dependency:Integrated biologics delivery systems require temperature-controlled logistics that exclude rural health posts lacking refrigeration infrastructure.
Strategic Opportunities
- CDSCO biodegradability mandates:India's Central Drugs Standard Control Organisation is signaling polymer waste stream regulations that would advantage domestic manufacturers with compostable material pipelines.
- UNICEF tender consolidation:Gavi-aligned national immunization programs are aggregating demand into multi-year framework agreements favoring suppliers with WHO PQS prequalification and regional warehousing.
- Retractable needle carrier convergence:Integration of passive retraction mechanisms with connected health data capture is creating premium positioning in European chronic disease management protocols.
Industry Challenges
- WHO PQS audit protocol volatility:Prequalification standards for needle re-use prevention mechanisms are tightening faster than validation timelines, compressing product recertification windows.
- Precision molding talent scarcity:Micro-injection molding expertise for breakaway activation features concentrates among technicians trained in medical device hubs in Massachusetts and Bavaria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Destructing Syringe Market |
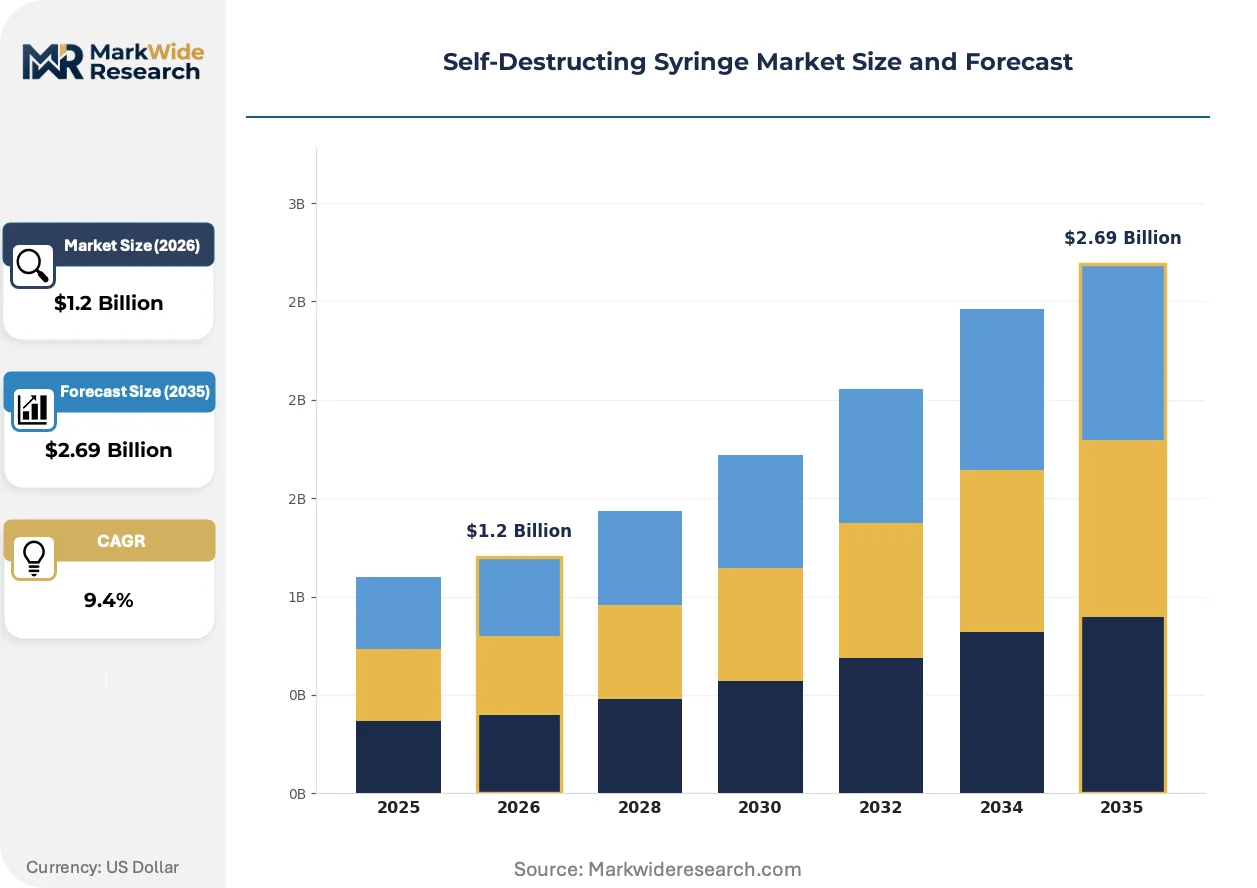
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.69 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Auto-Disable, Safety Syringe, Prefilled End User: Hospitals, Clinics, Homecare, Pharmacies Material: Plastic, Glass, Biodegradable, Latex-Free Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Transdermal |
| Companies Covered | BD, Star Syringes, Univec, Biologica, Terumo Corporation, Weigao Group, SPM Medicare, Yangzhou Goldenwell Medical Devices Factory, CANMAX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Destructing Syringe Market Trends and Innovations
Auto-disable syringe engineering is pivoting from mechanical lock designs toward material-science solutions that embed single-use activation into barrel polymers themselves, collapsing manufacturing steps while raising performance thresholds.
Metal-free breakaway mechanisms are converging with tropical climate stabilization requirements as manufacturers replace stainless steel snap-rings with glass-filled polymer formulations that resist humidity-induced fatigue. UNICEF and PAFO procurement offices are specifying these designs for West African immunization campaigns where monsoon season storage conditions degrade conventional metal components. The shift is compressing supplier qualification timelines while elevating R&D intensity for heat-stable activation features.
REACH restrictions on medical plastic additives are forcing reformulation of polypropylene compounds used in barrel production, with ECHA scrutiny of phthalate plasticizers accelerating migration toward bio-based stabilizers. European Economic Area markets are experiencing certification delays as manufacturers resubmit technical files for MDR compliance under revised biocompatibility testing protocols. German and French hospital purchasing consortia are now requiring documentation of additive-free material streams in tender submissions.
Ministry of health buyers are consolidating procurement through centralized framework agreements that displace fragmented district-level purchasing, with Kenya's national vaccine program and Indonesia's Badan Pengawas Obat dan Makanan coordinating multi-year supply contracts. This aggregation is compressing price negotiation cycles while elevating supplier performance bonding requirements. East African Community member states are piloting pooled procurement mechanisms modeled on PAFO regional tender structures.
Self-Destructing Syringe Market Segmentation
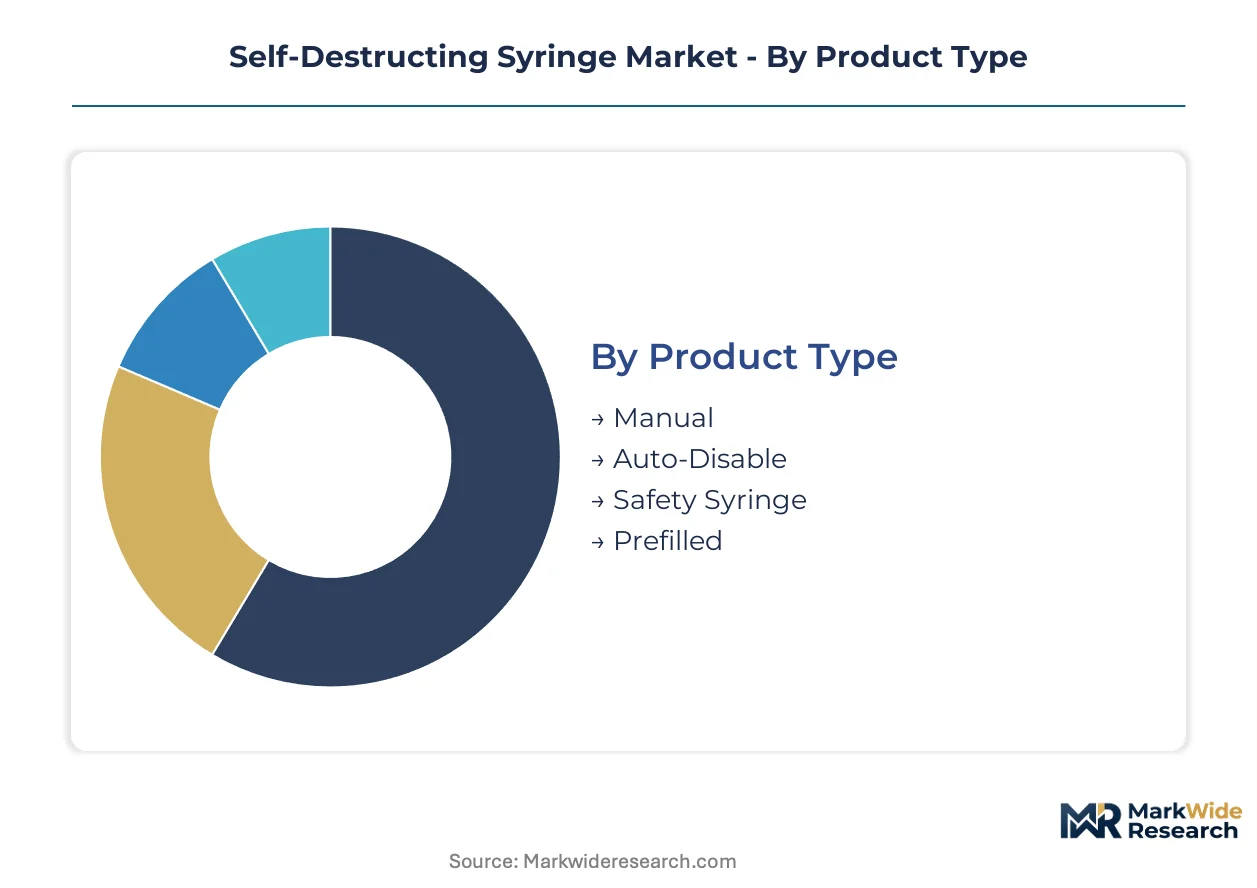
Procurement patterns for self-destructing syringes diverge sharply across product architectures and delivery contexts. WHO-backed immunization programs favor mechanically irreversible designs, while hospital systems prioritize passive safety features aligned with sharps-injury regulations.
Product Type:
Cost tier determines access: high-volume tenders favor basic auto-disable mechanisms, while premium hospital contracts reward integrated safety engineering.
- Manual:Basic plunger-lock designs rely on user discipline for single-use compliance. Demand concentrates in informal healthcare settings across rural India and Southeast Asia where procurement budgets exclude engineered safety features.
- Auto-Disable:Mechanically irreversible activation triggers upon full plunger depression, physically blocking re-aspiration. WHO PQS prequalification mandates have concentrated procurement for Gavi-aligned national immunization programs in Sub-Saharan Africa on this format.
- Safety Syringe:Passive retraction or shielding mechanisms satisfy EU MDR sharps-injury prevention rules. European hospital systems specify these for occupational health compliance, accepting price premiums over auto-disable alternatives.
- Prefilled:Integrated drug-container designs with tamper-evident activation. Biologics manufacturers seek these for chronic disease protocols requiring cold-chain integrity and dose accuracy.
Volume sits with Auto-Disable; growth tilts toward Prefilled.
End User:
Application context shapes specification: acute care demands passive safety, while community settings prioritize cost and cold-chain independence.
- Hospitals:Occupational health liability drives procurement of retractable-needle designs under FDA 510(k) and EU MDR frameworks. German and French purchasing consortia now require additive-free material documentation.
- Clinics:Mixed patient volumes create specification tension between premium safety features and budget constraints. India's urban primary health centers split procurement between auto-disable immunization stock and safety syringes for curative care.
- Homecare:Patient self-administration protocols favor prefilled formats with intuitive activation. Growth concentrates in European chronic disease management programs for diabetes and multiple sclerosis therapies.
- Pharmacies:Retail distribution channels supply emergency and travel health markets. Product mix skews toward manual and basic auto-disable formats where pharmacist counseling substitutes for engineered safety.
Hospitals command specification authority; Homecare represents the steepest expansion trajectory.
Material:
Margin structure separates commodity polymers from certified specialty compounds.
- Plastic:Polypropylene and cyclo-olefin polymer barrels dominate volume production. Gamma sterilization compatibility requirements concentrate molding capacity near Mumbai and Shenzhen industrial corridors.
- Glass:Borosilicate barrels serve prefilled formats requiring drug-container interaction testing. Pharmaceutical manufacturers specify these for parenteral biologics with stability-sensitive protein structures.
- Biodegradable:Emerging compostable polymers respond to India's CDSCO signaling on medical waste stream regulations. Domestic manufacturers in Gujarat are piloting polylactic acid formulations for government tender qualification.
- Latex-Free:Synthetic elastomer plunger seals eliminate allergen exposure liability. ECHA scrutiny of rubber additives under REACH has accelerated migration toward silicone-based alternatives.
Plastic carries volume; Biodegradable gains share fastest on regulatory pressure.
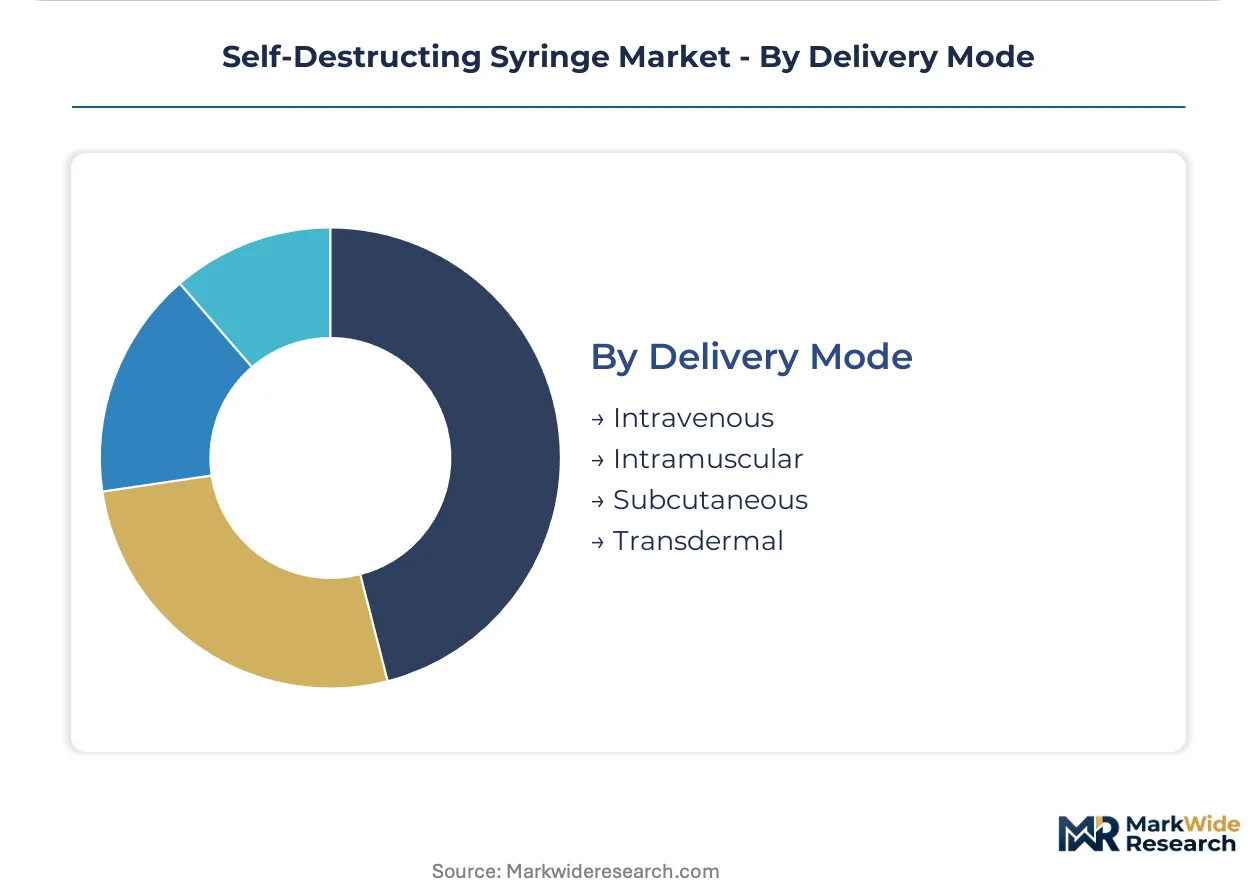
Delivery Mode:
Volume scale concentrates in intramuscular administration for mass immunization.
- Intravenous:Precision dosing requirements favor prefilled formats with integrated needle gauges. Hospital pharmacy compounding operations specify these for medication safety protocols.
- Intramuscular:Standard vaccination delivery drives highest absolute demand. UNICEF and PAFO tenders specify 0.5mL auto-disable designs with fixed-needle configurations for national immunization programs.
- Subcutaneous:Insulin and hormone therapies create demand for ultra-fine gauge needles with passive retraction. European homecare markets specify these for patient self-administration.
- Transdermal:Microneedle array formats remain developmental, with pilot procurement for pediatric and needle-phobic patient populations in Japanese and South Korean clinical trial settings.
Intramuscular anchors procurement volume; Subcutaneous climbs fastest on biologics expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's industrial corridor anchors global self-destructing syringe molding capacity, with gamma sterilization infrastructure clustering around Gujarat and Maharashtra to serve WHO PQS procurement pipelines.
India
Domestic manufacturers in Gujarat and Tamil Nadu scale cyclo-olefin polymer production for ministry of health contracts across Southeast Asia and Africa. CDSCO signaling on biodegradable mandates drives polylactic acid pilot programs in Ahmedabad. The Mumbai-Pune industrial belt concentrates electron-beam sterilization facilities for export qualification.
United States
FDA 510(k) clearance requirements for retraction-activated devices shape procurement specifications for hospital systems and chronic disease management programs. Massachusetts medical device hubs host precision molding expertise for breakaway activation features. Greater Boston clusters micro-injection molding technicians serving passive safety engineering.
Germany
EMA MDR framework mandates clinical evidence of passive safety feature reliability across hospital purchasing consortia in Bavaria and North Rhine-Westphalia. REACH restrictions on medical plastic additives force polypropylene reformulation for barrel production. Frankfurt and Stuttgart hospital networks require additive-free material documentation in tender submissions.
China
Shenzhen industrial corridors concentrate gamma sterilization infrastructure for polypropylene dimensional stability requirements. NMPA alignment with WHO PQS standards accelerates domestic manufacturer qualification for UNICEF tenders. Yangtze River Delta molding capacity serves Southeast Asian ministry of health contracts.
Brazil
ANVISA regulatory convergence with WHO prequalification standards opens procurement pathways for Gavi-aligned national immunization programs. São Paulo state health secretariats pilot centralized framework agreements displacing fragmented district-level purchasing. Southeast Asian manufacturers target Brazilian tenders through regional warehousing strategies.
Self-Destructing Syringe Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and sterilization infrastructure access. The vendor base stratifies between WHO PQS-prequalified suppliers capturing multi-year framework agreements and regional fabricators serving informal healthcare settings. Three archetypes dominate: backward-integrated precision molders, tropical-climate mechanism specialists, and scale-driven tender aggregators. Competitive moves concentrate on sterilization facility expansion and biodegradability pipeline development.
Among Asia-Pacific fabricators, Weigao Group and Yangzhou Goldenwell Medical Devices Factory exemplify scale-driven positioning for high-volume immunization tenders. BD occupies a position representing backward-integrated precision molding capacity serving cost leadership across government procurement. Star Syringes and Univec anchor the specialization tier through dedicated R&D positioning on metal-free breakaway mechanisms and concentrated manufacturing scale for African and South Asian contracts respectively.
| Leading Market Players |
|---|
| BD |
| Star Syringes |
| Univec |
| Biologica |
| Terumo Corporation |
| Weigao Group |
| SPM Medicare |
| Yangzhou Goldenwell Medical Devices Factory |
| CANMAX |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between WHO PQS-prequalified and non-qualified suppliers manifests in pricing power concentration and sterilization infrastructure placement. Premium-tier suppliers capture multi-year framework agreements through backward integration into gamma facilities, while commodity fabricators compete on cyclo-olefin polymer unit costs without qualification access.
Pricing Analysis
Value-based pricing anchors on immunization throughput guarantees in Gavi-aligned tenders. Three-tier pricing structure across WHO PQS-prequalified, CE-marked, and uncertified manufacturers reflects sterilization infrastructure ownership and audit protocol compliance. Pricing pressure stems from UNICEF tender consolidation compressing negotiation cycles. Ministry of health buyers in Sub-Saharan Africa exhibit highest price sensitivity; European hospital purchasing consortia accept premiums for additive-free material documentation.
Supply Chain Analysis
Micro-injection molding technician scarcity in Massachusetts and Bavaria constrains precision activation feature production. Supply concentrates in India, China, and Germany for cyclo-olefin polymer barrels, stainless steel needle cannulas, and gamma sterilization equipment. Raw material dependencies include polypropylene resin, glass-filled polymer formulations, and silicone-based plunger seals. Single-source vulnerability sits with electron-beam sterilization capacity near Mumbai and Shenzhen. Distribution runs through regional warehousing networks serving PAFO and UNICEF procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where sterilization facility ownership and polymer compounding capabilities determine qualification access. Players are pursuing upstream control over gamma infrastructure to lock in WHO PQS prequalification.
For Market Incumbents: Deepen backward integration into electron-beam sterilization corridors near Mumbai and Shenzhen to defend framework agreement capture against emerging Indian domestic manufacturers. Expand polylactic acid pilot programs ahead of CDSCO biodegradability mandates to preempt regulatory displacement. Certification investment in metal-free breakaway mechanisms for tropical climates represents the critical defensive lever against tropical-climate specialists. For New Entrants and Emerging Players: Launch via regional warehousing partnerships targeting East African Community pooled procurement pilots modeled on PAFO structures. The most penetrable white space sits in biodegradable barrel formats for Indian government tenders where domestic qualification pathways remain open. Prefilled format cold-chain logistics partnerships with biologics manufacturers offer a differentiated go-to-market angle outside immunization tender commoditization. For Investors and Strategic Acquirers: Exit pathways concentrate in sterilization infrastructure rollups and WHO PQS audit consultancy acquisitions. Long-term viability favors vertically integrated molders with captive gamma capacity and polymer formulation R&D. The signal to watch is CDSCO enforcement timing on medical plastic waste stream regulations, which would trigger accelerated consolidation among Gujarat-based fabricators lacking compostable material pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| WHO PQS Prequalification Investment | UNICEF tender access locks in multi-year revenue visibility for immunization device suppliers. |
| Gamma Sterilization Capacity Expansion | Electron-beam facility ownership near Mumbai secures polypropylene dimensional stability for export qualification. |
| Metal-Free Mechanism R&D | Glass-filled polymer breakaway designs capture West African monsoon-season procurement specifications. |
| Biodegradable Polymer Pipeline Development | Polylactic acid formulation readiness positions suppliers ahead of CDSCO waste stream mandates. |
| Regional Warehousing Network Buildout | East African distribution nodes enable response to Kenya's centralized vaccine program framework agreements. |
Research Methodology
Independent corroboration across hospital procurement managers, GPO contracts specialists, biomedical engineers, and ministry of health immunization officers underwrites the qualitative findings. Primary interviews with WHO PQS audit coordinators and cyclo-olefin polymer molding technicians combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, UNICEF tender databases, and Indian customs export records. Bottom-up segment sizing triangulates against top-down immunization program budget allocations across the analysis window.
Rate-of-change decomposition separates volume expansion from price trajectory shifts across product type, material grade, end-user setting, and regional regulatory cluster dimensions. CAGRs derive from fitted growth curves applied to procurement pipeline data and sterilization capacity expansion announcements. Industry-specific forecast inputs include Gavi pledge disbursement schedules and CDSCO regulatory signaling timelines.
The model assumes a particular technology adoption path; alternative pathways for biodegradable barrel polymers would alter the outlook. Forecasts reflect assumptions regarding WHO PQS audit protocol stability and gamma sterilization infrastructure financing availability. Material deviation in CDSCO enforcement timing or UNICEF tender aggregation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
TMJ Implants Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Medication Management System Market
Medical Devices
Cyclotron Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
EEG Amplifiers Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Catheter Coatings Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Global Cardiac Resuscitation Device Market
Medical Devices
Blood Collection Devices Market
Medical Devices
Defibrillator Pads Market