
 North America Ambulatory Infusion Pumps Market | 2026-2036
North America Ambulatory Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ambulatory Infusion Pumps Market Analytics
Hospital-to-home discharge channels are rewriting how ambulatory infusion pumps reach end users, with direct-to-patient logistics and remote monitoring platforms displacing traditional durable medical equipment distribution. Becton, Dickinson and Company leverages its vascular access portfolio to anchor bundled infusion contracts with integrated health networks. Fresenius Kabi competes through captive manufacturing of parenteral nutrition and generic injectables paired with pump hardware. MOOG Inc. specializes in precision motor and fluid control systems that differentiate its ambulatory pump mechanics from conventional peristaltic designs.
North America ambulatory infusion pumps are programmable, battery-operated devices designed to deliver medications, nutrients, or fluids into a patient's circulatory system at controlled rates through vascular access devices, typically operating at flow rates from 0.1 to 999 mL/hour with occlusion pressure sensing and dose error reduction software. Their primary purpose is to enable continuous or intermittent therapeutic administration outside acute care settings while maintaining clinician oversight through connectivity and alarm systems. Electronic pumps lead product type demand due to programmable flexibility and safety software integration, while smart pumps within the technology dimension capture margin pools through wireless connectivity, drug library databases, and EMR interoperability that reduce programming errors. Home healthcare dominates end user volume as payors push reimbursement toward lower-cost outpatient settings, though hospitals remain the gateway for patient training and initial pump titration protocols.
FDA 510(k) clearance requirements and the agency's infusion pump improvement initiative enforce design controls, software validation, and post-market surveillance that elevate barriers for new entrants while compelling incumbents to invest in cybersecurity and human factors engineering. The Centers for Medicare and Medicaid Services national coverage determinations for home infusion therapy directly shape reimbursement accessibility and patient eligibility criteria across the United States. Stakeholders must monitor evolving FDA guidance on interoperable medical devices and state-level scope-of-practice regulations governing nurse-administered home infusion as these frameworks determine service model economics and competitive positioning.
Market Dynamics
Hospital-to-home discharge channels are rewriting how ambulatory infusion pumps reach end users, with direct-to-patient logistics and remote monitoring platforms displacing traditional durable medical equipment distribution. This structural shift compresses channel layers while elevating requirements for connectivity infrastructure and patient self-management capabilities.
Growth Catalysts
- Home Infusion Therapy Reimbursement:Centers for Medicare and Medicaid Services national coverage determinations expand patient eligibility for outpatient parenteral administration, channeling chronic disease volumes away from institutional settings.
- Connectivity Integration:Wireless-enabled smart pumps with EMR interoperability reduce programming errors and enable remote dose verification, satisfying payor demands for oversight without bedside presence.
- Aging Demographics:United States population concentration in Medicare-eligible cohorts sustains demand for ambulatory chemotherapy, antibiotic, and pain management infusion outside acute facilities.
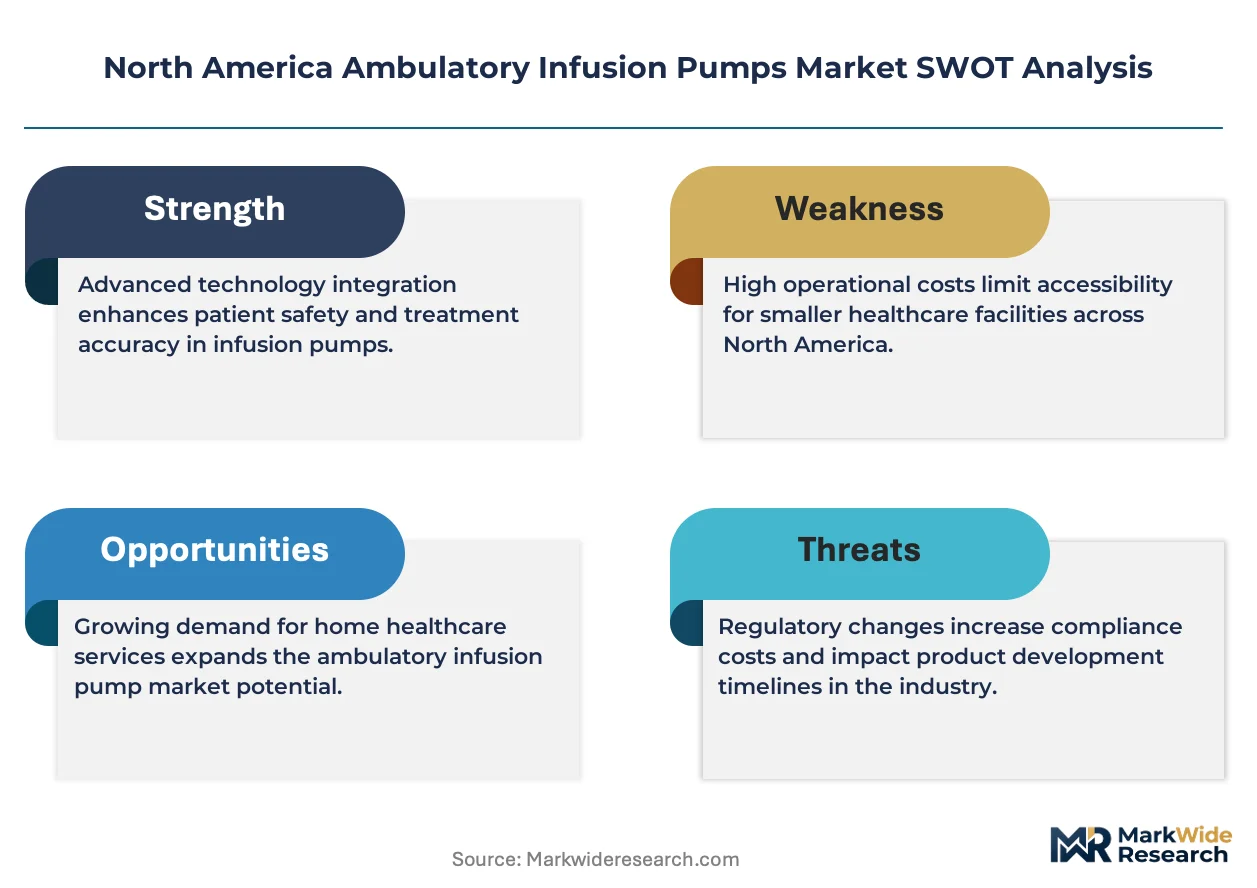
Market Restraints
- FDA 510(k) Pathway Friction:Premarket notification requirements enforce extended software validation and human factors testing, elevating capital requirements for device clearance and design iteration cycles.
- Component Supply Concentration:Precision motor and sensor sourcing concentrates among specialized electromechanical suppliers, exposing manufacturers to lead time volatility and single-source vulnerabilities.
- Substitution by Oral Formulations:Advancements in bioavailability-enhanced oral oncology and anti-infective drugs threaten addressable volumes for parenteral delivery in select therapeutic categories.
Strategic Opportunities
- Pediatric Ambulatory Expansion:Underpenetrated pediatric home infusion protocols in Canada present white space for device miniaturization and family-centered training programs.
- Interoperable Device Mandates:Evolving FDA guidance on medical device interoperability creates competitive differentiation for platforms enabling seamless health information exchange across care settings.
- Biologics Delivery Convergence:Combination of ambulatory pumps with cold-chain logistics and patient support services captures margin pools from specialty pharmacy integration.
Industry Challenges
- Cybersecurity Validation Burden:FDA post-market surveillance requirements for networked infusion devices demand continuous software patching and threat monitoring competencies that strain quality assurance organizations.
- Field Service Network Scaling:Direct-to-patient distribution models require technician deployment for device setup and troubleshooting across dispersed geographies, compressing service economics.
- Legacy EMR Integration Complexity:Hospital information system heterogeneity forces pump vendors to maintain multiple interoperability protocols, fragmenting development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ambulatory Infusion Pumps Market |
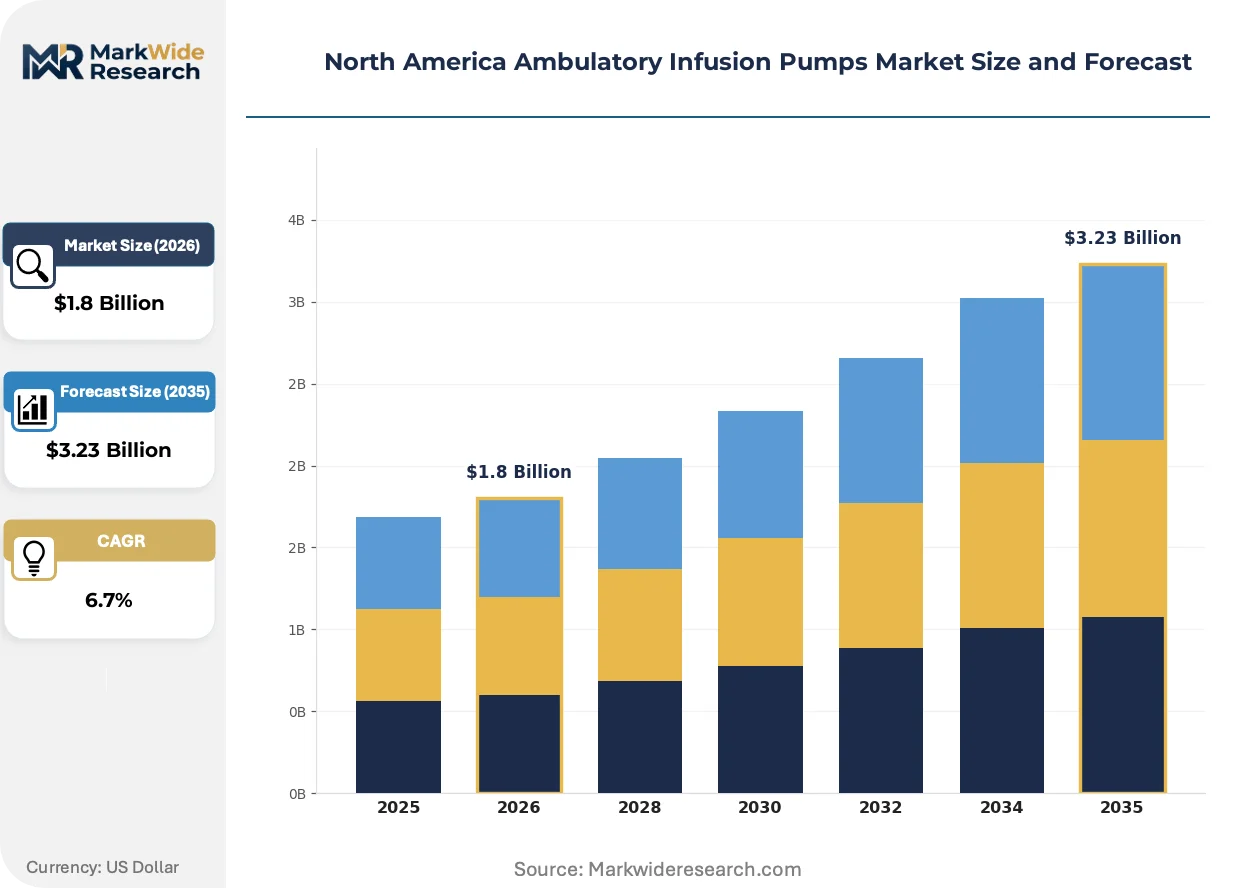
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Pumps, Syringe Pumps, Volumetric Pumps, PCA Pumps End User: Home Healthcare, Hospitals, Clinics, Long-term Care Facilities Technology: Smart Pumps, Standard Pumps, Specialty Pumps, Portable Pumps Application: Pain Management, Chemotherapy, Antibiotic Delivery, Hydration Therapy |
| Companies Covered | B. Braun Melsungen AG, MOOG Inc., WalkMed LLC, Medtronic plc, Fresenius Kabi, Becton, Dickinson and Company, KORU Medical Systems, ICU Medical Inc., Avanos Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ambulatory Infusion Pumps Market Evolving Landscape
Device miniaturization and algorithmic dosing are converging to enable patient self-management of complex infusion regimens previously requiring clinical supervision. These advances compress the boundary between acute and ambulatory care settings.
Peristaltic pump mechanisms are collapsing into compact rotary designs with fewer moving parts. Home healthcare providers are adopting these devices for immunoglobulin and parenteral nutrition patients requiring multi-day ambulatory therapy. The structural consequence is collapsing maintenance requirements and device failure rates that previously justified institutional inventory buffers.
FDA infusion pump improvement initiative enforcement is elevating software documentation and post-market surveillance obligations. Manufacturers must demonstrate cybersecurity controls and human factors validation across product lifecycles. Small device developers in the United States are responding by outsourcing quality systems rather than building internal regulatory infrastructure.
Patient acquisition patterns are fragmenting across specialty pharmacy, home health agency, and integrated delivery network channels. Durable medical equipment distributors are losing gatekeeper status as manufacturers deploy direct-to-patient platforms with embedded remote monitoring. This disintermediation is most visible in United States oncology and infectious disease infusion therapy markets where payor steerage concentrates volume among narrow networks.
North America Ambulatory Infusion Pumps Market Segmentation
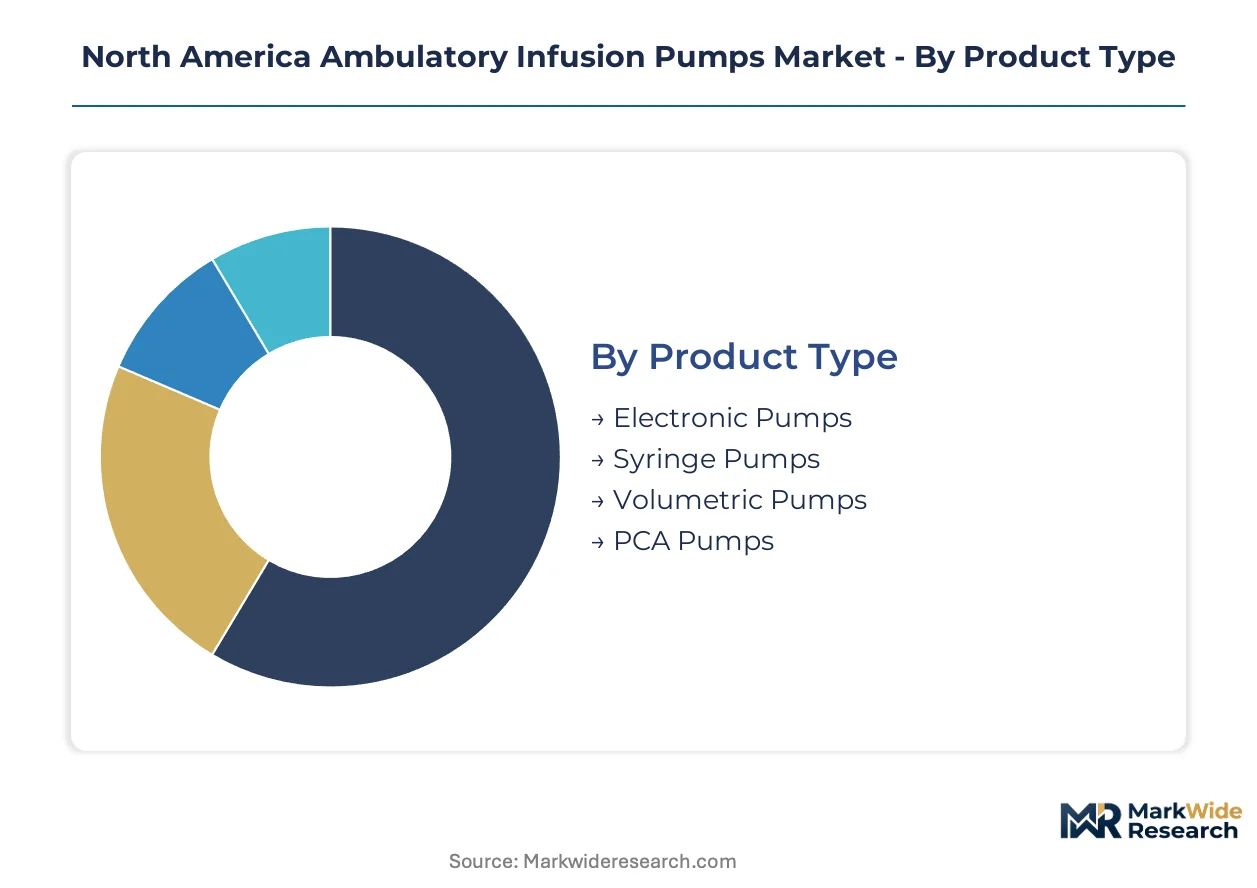
Ambulatory infusion pump purchasing cycles vary dramatically across segments, with hardware refresh timelines stretching from three years in hospital settings to seven-plus years in home healthcare. Understanding these replacement velocities helps vendors align inventory planning with revenue recognition patterns.
Product Type:
Electronic pumps turn over fastest in high-acuity settings where software obsolescence drives replacement, while mechanical volumetric designs persist longer in cost-constrained environments.
- Electronic Pumps:Programmable devices with dose error reduction software and occlusion pressure sensing dominate United States hospital discharge protocols. Demand concentrates in integrated delivery networks seeking EMR interoperability for remote titration oversight.
- Syringe Pumps:Compact precision units deliver small-volume infusions (0.1-50 mL) for pediatric and neonatal applications. Canadian pediatric home infusion programs represent the fastest expansion trajectory for this segment.
- Volumetric Pumps:Gravity-independent large-volume delivery systems serve parenteral nutrition and hydration therapy patients. Long replacement cycles characterize United States long-term care facility procurement.
- PCA Pumps:Patient-controlled analgesia devices with lockout intervals and dosing logs support post-surgical pain management. Demand clusters in United States ambulatory surgery centers with same-day discharge mandates.
Electronic pumps dominate installed base. Syringe pumps are where expansion concentrates.
End User:
Cost tier stratification separates capital-rich hospital purchasers from reimbursement-dependent home healthcare providers operating on thin device margins.
- Home Healthcare:Medicare reimbursement for home infusion therapy drives volume leadership across the United States. Remote monitoring platform integration now determines competitive selection criteria for agency pump procurement.
- Hospitals:Acute care facilities serve as patient training and titration gateways before discharge to ambulatory settings. FDA 510(k) clearance requirements elevate vendor qualification thresholds for institutional purchasing committees.
- Clinics:Outpatient infusion centers handle chemotherapy and biologic administration with mid-acuity monitoring capabilities. United States oncology clinic networks are consolidating pump standardization across multi-site operations.
- Long-term Care Facilities:Skilled nursing facilities manage stable infusion regimens with lower connectivity requirements. Reimbursement compression under Medicare Part A constrains capital equipment refresh rates.
Home healthcare captures volume leadership. Hospitals anchor technology adoption decisions.
Technology:
Maturity gradients separate established standard pump hardware from emerging smart connectivity platforms requiring continuous software validation.
- Smart Pumps:Wireless-enabled devices with drug library databases and dose error reduction systems command premium positioning. FDA cybersecurity guidance for networked medical devices elevates development burden for this segment.
- Standard Pumps:Basic programmable units without connectivity infrastructure serve cost-sensitive purchasers. Canadian provincial health authorities specify these devices for stable chronic therapy protocols.
- Specialty Pumps:Disease-specific designs address chemotherapy, immunoglobulin, and parenteral nutrition requirements. United States specialty pharmacy networks drive specification standards for this segment.
- Portable Pumps:Wearable and pocket-sized devices enable patient mobility during multi-day infusion regimens. Miniaturization investments target United States immunoglobulin patient populations requiring 24-48 hour ambulatory delivery.
Standard pumps dominate installed base. Smart pumps are where expansion concentrates.
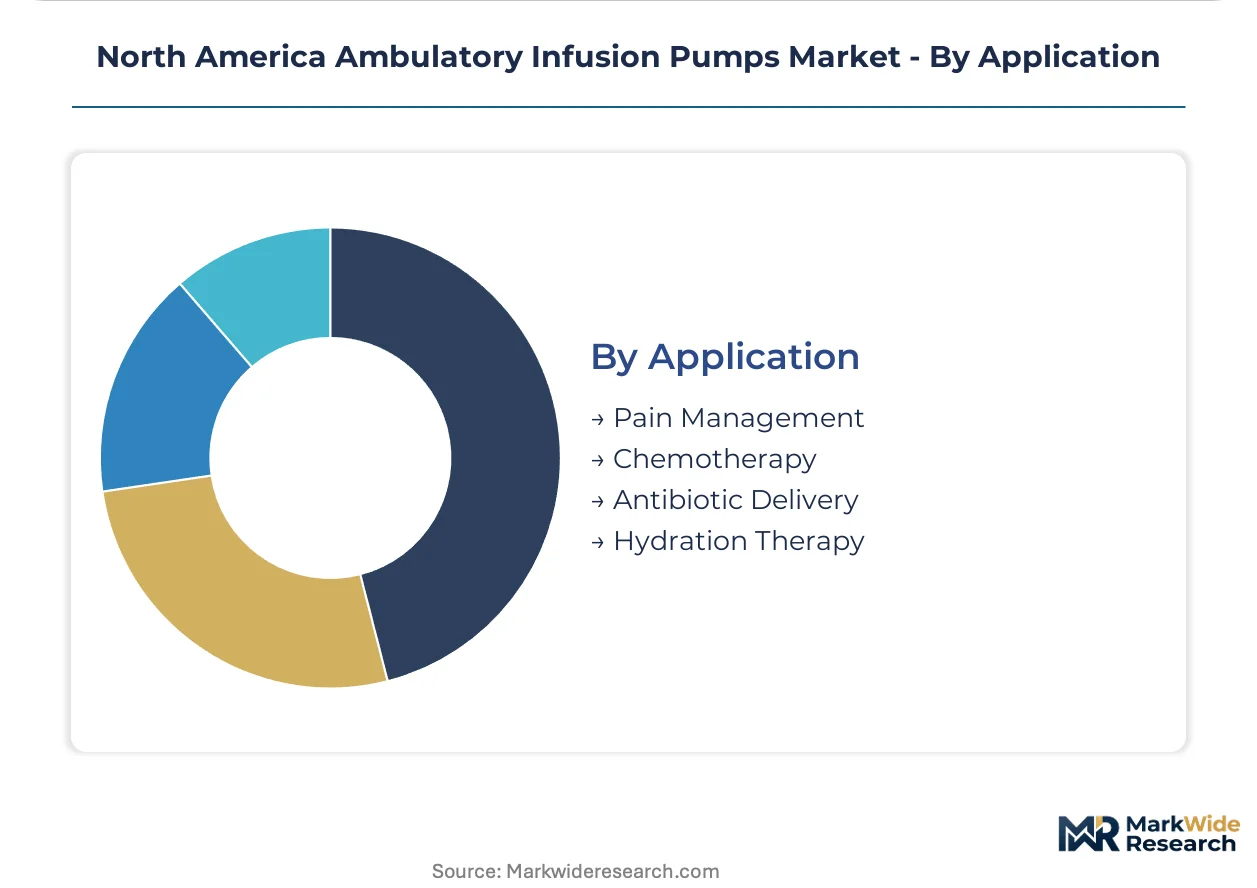
Application:
Application demand correlates with chronic disease prevalence and therapeutic substitution risk from advancing oral formulations.
- Pain Management:Opioid and local anesthetic delivery systems support post-operative and palliative care protocols. United States ambulatory surgery volume growth sustains demand for portable PCA configurations.
- Chemotherapy:Continuous infusion devices enable outpatient administration of cytotoxic and biologic oncology agents. United States oncology practice consolidation is standardizing pump selection across network sites.
- Antibiotic Delivery:Extended-infusion beta-lactam and other anti-infective administration supports outpatient infectious disease management. Oral bioavailability improvements in anti-infective drug development threaten long-term volume for this segment.
- Hydration Therapy:Fluid replacement and electrolyte correction devices serve gastrointestinal and oncology patient populations. Canadian home healthcare reimbursement frameworks support stable demand for this application.
Pain management dominates installed base. Chemotherapy is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-95 corridor and Great Lakes rail networks enable just-in-time pump distribution from Midwest manufacturing clusters to East Coast healthcare systems. Cross-border logistics through Detroit-Windsor and Buffalo-Niagara facilitate Canadian market access. Mexico's maquiladora zones near Tijuana and Ciudad Juárez assemble components for US-bound finished devices.
United States
Medicare home infusion reimbursement expansions drive patient volume migration from hospitals to ambulatory settings. FDA 510(k) clearance requirements enforce software validation and human factors testing that elevate design costs. Minneapolis-St. Paul anchors precision electromechanical manufacturing for pump motor and sensor subsystems.
Canada
Provincial health authorities in Ontario and British Columbia standardize pump procurement for chronic therapy protocols. Health Canada medical device licensing aligns with FDA predicate device pathways to accelerate cross-border approvals. Toronto's medtech corridor concentrates distribution infrastructure serving Ontario's aging population.
Mexico
Maquiladora assembly operations in Baja California and Chihuahua manufacture pump housings and disposable infusion sets for US market supply. COFEPRIS regulatory convergence with FDA quality system requirements enables integrated North American production. Tijuana medical device parks specialize in plastic injection molding for ambulatory pump enclosures.
North America Ambulatory Infusion Pumps Market Competitive Landscape
On the supply side, the industry is consolidated among diversified medical technology conglomerates with vascular access and pharmaceutical manufacturing adjacencies. Three strategic archetypes dominate: integrated health system contractors bundling pumps with consumables, precision electromechanical specialists supplying motor and fluid control subsystems, and specialty pharmacy-aligned device vendors. Competitive moves center on FDA 510(k) clearance velocity for smart pump connectivity features and direct-to-patient logistics platform deployment.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Fresenius Kabi occupy positions anchored by vascular access and parenteral nutrition portfolios respectively. MOOG Inc. represents the precision electromechanical specialist archetype with fluid control system expertise. These three exemplify the competitive vectors shaping contract structures with integrated delivery networks and home healthcare agencies.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| MOOG Inc. |
| WalkMed LLC |
| Medtronic plc |
| Fresenius Kabi |
| Becton, Dickinson and Company |
| KORU Medical Systems |
| ICU Medical Inc. |
| Avanos Medical Inc. |
| Others |
Value Network & Pricing Analysis
Precision motor manufacturing concentrates in Minneapolis-St. Paul and Shenzhen, anchoring margin pools in smart pump connectivity modules and drug library software subscriptions rather than commoditized hardware housings. This upstream concentration forces downstream vendors to absorb component cost volatility or cede margin to integrated electromechanical specialists.
Pricing Analysis
Volume-discount tiering structures separate integrated delivery network bundled contracts from individual home healthcare agency procurements. Three-tier pricing stratifies across premium smart pumps with EMR interoperability, standard programmable units for stable chronic therapy, and economy mechanical designs for long-term care facilities. Price differentiation rests on FDA 510(k) clearance tier and wireless connectivity certification rather than raw hardware specifications. Pricing pressure stems from Medicare reimbursement compression for home infusion therapy, squeezing mid-tier vendor margins. Home healthcare agencies exhibit highest price sensitivity due to thin device margins under bundled payment models, while hospital purchasing committees prioritize interoperability over unit cost.
Supply Chain Analysis
Supplier-financing facilities from electromechanical component vendors extend payment terms to 90-120 days for pump manufacturers with established FDA clearance track records. Geographic supply concentration centers on the United States for precision motor subsystems, Mexico for plastic injection-molded housings and disposable infusion sets, and China for sensor electronics and battery cells. Raw material dependencies include medical-grade polymers, lithium-ion power cells, and stainless steel for fluid contact surfaces. Single-source vulnerability in precision motor sourcing from Minneapolis-St. Paul suppliers exposes manufacturers to lead time volatility. Distribution runs through direct-to-patient logistics platforms displacing traditional durable medical equipment distributors, with specialty pharmacy networks increasingly controlling patient acquisition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) software validation expertise and cybersecurity compliance capabilities represent scarce assets that determine competitive survival, with fewer than a dozen vendors possessing in-house regulatory infrastructure sufficient for smart pump development.
For Market Incumbents: Pre-empt emerging connectivity standard fragmentation by anchoring drug library databases and EMR interoperability protocols across integrated delivery network contracts before FDA interoperability guidance hardens. Acquire or partner with specialty pharmacy logistics platforms to capture patient acquisition channels disintermediating durable medical equipment distributors. Defend against precision motor supply concentration by securing dual-source agreements with Shenzhen suppliers alongside Minneapolis-St. Paul anchors. For New Entrants and Emerging Players: Pursue Canadian pediatric home infusion protocols as the most penetrable geography, where provincial health authority standardization lags United States integrated delivery network consolidation and miniaturization requirements remain unsatisfied. Target syringe pump segments for neonatal applications where incumbent attention concentrates on high-volume electronic platforms. Establish go-to-market alignment with Toronto medtech corridor distributors serving Ontario's aging population. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision electromechanical specialists possessing FDA-cleared fluid control subsystems but lacking downstream pump assembly and commercial infrastructure. Long-term viability across the analysis window hinges on cybersecurity validation competencies and direct-to-patient logistics platform ownership. Watch FDA guidance issuance on medical device interoperability as the signal indicating whether connectivity-enabled platforms will command sustained premium positioning or face commoditization from mandated standardization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates clearance timelines for smart pump connectivity features ahead of interoperability mandates. |
| Hospital System Partnership | Secures bundled infusion contracts with integrated delivery networks seeking EMR interoperability. |
| Software Companion Development | Enables remote dose verification and patient self-management capabilities for home healthcare. |
| Reimbursement Strategy | Aligns pump specifications with CMS national coverage determinations for home infusion therapy. |
| CE Marking Pathway | Facilitates cross-border Canadian market access through Health Canada predicate device alignment. |
Research Methodology
The analysis maps electronic pump, syringe pump, volumetric pump, and PCA pump sub-sectors, each validated through hospital purchasing committee interviews, home healthcare agency procurement directors, biomedical engineers, and GPO contracts managers. Primary fieldwork combined with secondary validation from FDA 510(k) clearance databases, CMS Medicare reimbursement filings, hospital procurement databases, and integrated delivery network capital equipment budgets. Bottom-up installed base modeling triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Assumption sets held FDA regulatory pathway timelines and Medicare reimbursement frameworks fixed while varying home healthcare volume migration rates and oral formulation substitution trajectories across the projection horizon. Segmentation dimensions modeled include pump mechanism type, care setting acuity, connectivity tier, therapeutic application, and regional reimbursement cluster. CAGRs derived from replacement cycle analysis weighted against patient volume forecasts from chronic disease prevalence data. Industry-specific inputs incorporated precision motor supplier lead times and specialty pharmacy channel growth rates.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, FDA guidance timing, or precision motor supply availability would shift the trajectory. Forecasts reflect documented assumptions regarding patient discharge velocity and oral bioavailability advancement timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Netherlands Respiratory Devices Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
Aesthetic Devices Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
South America C-Arms Market
Medical Devices
Pipette Controllers Market
Medical Devices
Electronic Pill Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Feeding Tubes Market