
 Spherical IOL Market | 2026-2036
Spherical IOL Market Size, Share, and Industry Trends Forecast 2026-2036
Spherical IOL Market Insights
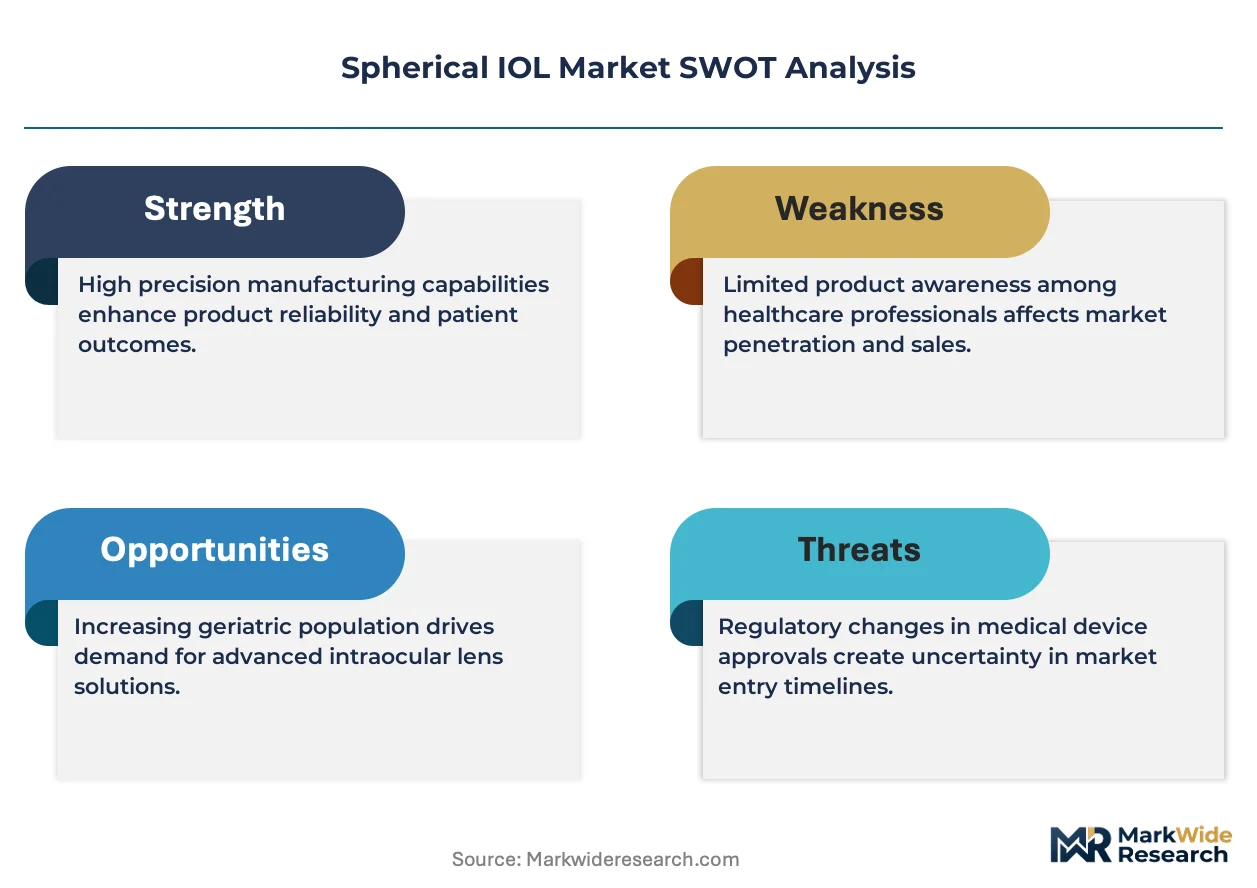
A shortage of trained cataract surgeons is unwinding access constraints in emerging markets. Alcon leverages its vertically integrated manufacturing network to sustain cost advantages across acrylic and hydrogel platforms. Johnson & Johnson Vision anchors its position through R&D intensity in laser-assisted delivery systems. HOYA Corporation specializes in precision-molded optics that dominate Japanese hospital procurement channels.
A spherical intraocular lens is a monofocal or multifocal implant with rotationally symmetric optic geometry, typically manufactured from hydrophobic acrylic or silicone hydrogel through lathe-cutting or injection-molding processes, designed to restore visual acuity after cataract extraction by focusing light onto a single focal point. Monofocal variants still occupy the largest volume share due to established reimbursement codes, while multifocal and toric platforms command premium positioning where out-of-pocket payment capacity exists. Acrylic material technology leads in developed markets for its biocompatibility and glistening resistance, whereas hydrogel formulations compete on cost in price-sensitive regions.
The FDA's Class III PMA pathway, the EU Medical Device Regulation's notified body requirements, and Japan's PMDA pharmaceutical and medical device agency collectively elevate barriers to market entry while ensuring clinical safety benchmarks. CE marking under MDR and compliance with ISO 11979 ophthalmic implant standards shape product development roadmaps and commercial launch sequencing across jurisdictions. Stakeholders must monitor evolving national reimbursement classifications for premium IOL categories as these determinations directly influence surgeon adoption rates and manufacturer portfolio prioritization.
Market Dynamics
The spherical IOL market is currently shaped by the migration of cataract procedures from inpatient hospitals to ambulatory surgery centers, a structural shift that compresses procurement cycles and elevates cost-per-unit sensitivity among facility buyers.
Growth Catalysts
- Aging demographics:Population cohorts over 65 in Japan, Germany, and the United States are expanding surgical candidacy pools and sustaining procedure volume growth in outpatient ophthalmology settings.
- FDA Class III PMA pathway maturation:Established premarket approval precedents for acrylic monofocal platforms are shortening regulatory review timelines for iterative product modifications.
- Acrylic material biocompatibility:Hydrophobic acrylic formulations with glistening-resistant properties are displacing silicone alternatives in premium reimbursement corridors.
Market Restraints
- Polymer feedstock volatility:Hydrophobic acrylic resin supply concentrates among specialized chemical manufacturers, exposing IOL molders to input cost swings.
- EU MDR notified body capacity:Consolidation of CE marking assessment capacity under the Medical Device Regulation is elongating certification timelines for new hydrogel platform launches.
- Monofocal reimbursement ceilings:Established procedural codes in Medicare and statutory health insurance systems cap revenue per lens regardless of manufacturing sophistication.
Strategic Opportunities
- Indian outpatient expansion:Underpenetrated cataract surgery access in tier-two and tier-three cities creates volume potential for cost-optimized hydrogel IOL platforms.
- Laser-assisted delivery convergence:Integration of femtosecond capsulotomy systems with pre-loaded IOL injectors is opening premium positioning in Japanese and German hospital procurement.
- PLI scheme manufacturing incentives:India's production-linked incentive framework for medical devices is attracting contract manufacturing investment for export-oriented IOL production.
Industry Challenges
- Micro-molding precision engineering:Tolerances below five microns for optic surface finish require specialized mold fabrication expertise that concentrates among Japanese and German tooling suppliers.
- ISO 11979 biocompatibility testing:Extended cytotoxicity and implantation study durations for novel material formulations compress product development runway visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spherical IOL Market |
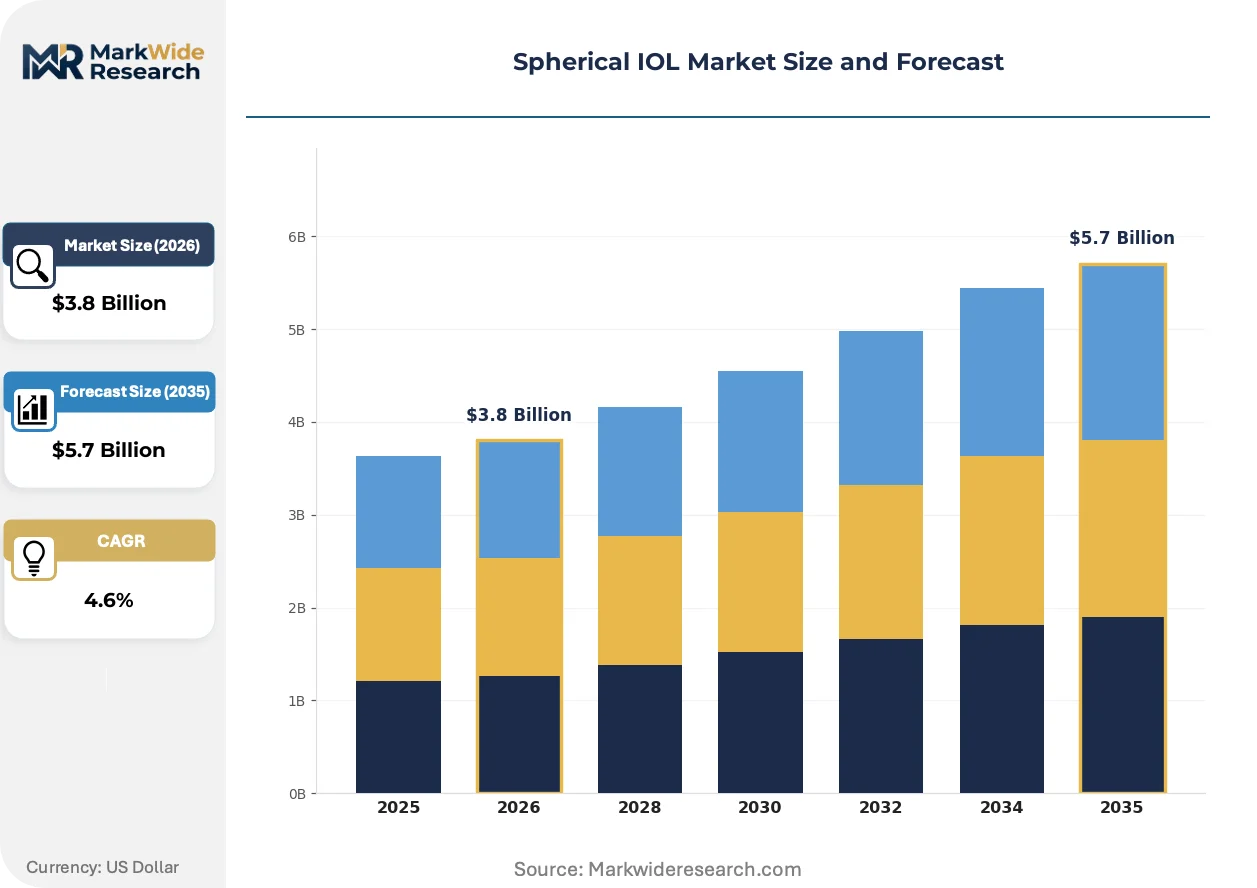
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofocal, Multifocal, Toric, Accommodation Technology: Artificial Intelligence, Laser-Assisted, Hydrogel, Acrylic End User: Hospitals, Eye Clinics, Research Institutes, Outpatient Facilities Application: Cataract Surgery, Refractive Surgery, Vision Correction, Ocular Implants |
| Companies Covered | Alcon, Johnson & Johnson Vision, Bausch & Lomb, Carl Zeiss Meditec, HOYA Corporation, Rayner Intraocular Lenses, Lenstec, STAAR Surgical Company, Ophtec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spherical IOL Market Trends and Innovations
Active innovation in spherical IOL manufacturing is concentrating on material purity, injection-molding precision, and pre-loaded delivery systems that reduce surgical variability.
Pre-loaded IOL injector systems are decomposing the traditional surgical workflow by integrating sterile packaging with automated insertion mechanisms. Ambulatory surgery centers in the United States and Germany are adopting these systems at accelerated pace to minimize operating room turnover time. The technology is decomposing demand for standalone lens-handling accessories and compressing supplier fragmentation in the surgical consumables tier.
The EU Medical Device Regulation's enhanced clinical evidence requirements are reshaping product development roadmaps for hydrogel platform extensions. Manufacturers must now generate post-market surveillance data comparable to pre-approval study rigor, elevating documentation burdens. Japanese and EU markets are most affected, with portfolio managers delaying multi-focal line extensions to consolidate MDR technical files.
Surgeon preference for single-use disposable instrumentation is fragmenting procurement authority within hospital systems. Purchasing departments now negotiate lens-injector bundles rather than standalone IOL contracts, compressing price transparency. This behavioral shift is most visible in United States ambulatory surgery center chains where administrator oversight of supply costs has intensified.
Spherical IOL Market Segmentation
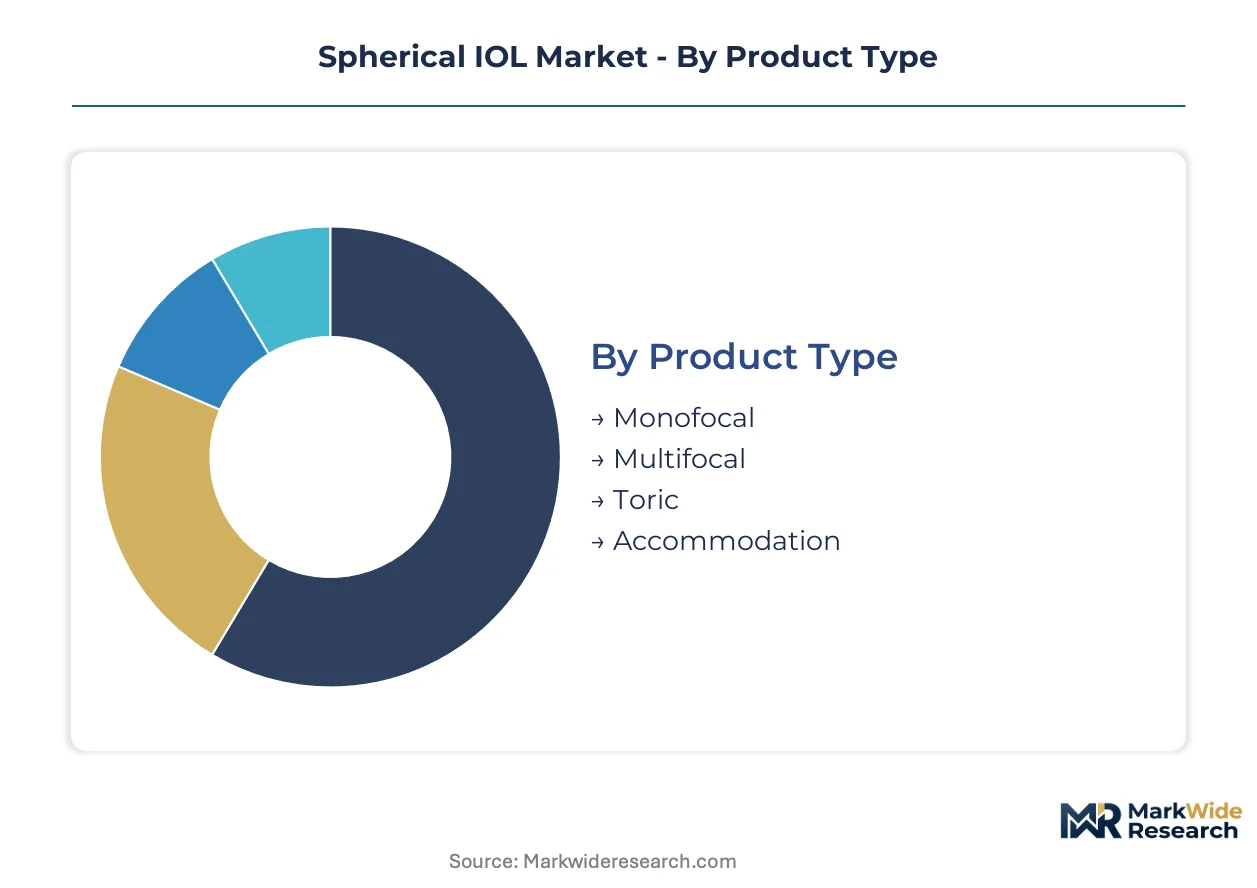
Spherical IOL procurement patterns diverge sharply across product platforms, surgical settings, and reimbursement corridors. Understanding margin concentration within each dimension enables manufacturers to prioritize R&D allocation and commercial resource deployment.
Product Type:
Premium positioning and out-of-pocket payment capacity concentrate margin pools in advanced optic geometries, while volume throughput remains anchored in established monofocal platforms.
- Monofocal:Single-focus optic design manufactured from hydrophobic acrylic or silicone hydrogel dominates procedure volumes in Medicare and statutory health insurance systems. Demand concentrates in United States ambulatory surgery centers where reimbursement codes cap unit revenue regardless of material sophistication. Established procurement pathways and surgeon familiarity sustain this segment's installed base.
- Multifocal:Diffractive or refractive optic designs provide simultaneous near and distance vision correction through concentric ring patterns or aspheric profiles. Premium uptake clusters in Japanese and German private-pay corridors where patients absorb incremental costs for spectacle independence. PMDA and CE marking precedents under MDR have shortened regulatory pathways for iterative platform extensions.
- Toric:Cylindrical power incorporation corrects pre-existing corneal astigmatism through marked haptic alignment systems.
- Accommodation:Mechanisms enabling post-implantation focal length adjustment through ciliary muscle interaction or hinged optic designs.
Monofocal platforms hold installed capacity. Multifocal is rotating up the share rankings.
Technology:
Material science differentiation and surgical workflow integration determine technology tiering, with biocompatibility certification acting as the primary value gate.
- Artificial Intelligence:Preoperative biometric calculation algorithms and intraoperative guidance systems optimize IOL power selection and placement accuracy. Adoption accelerates in German university hospitals and Japanese high-volume cataract centers where digital infrastructure investment precedes device procurement.
- Laser-Assisted:Femtosecond laser platforms perform capsulotomy, lens fragmentation, and corneal incisions with micron-level precision. United States ambulatory surgery center chains deploy these systems to differentiate premium service tiers and capture out-of-pocket revenue streams above standard Medicare reimbursement.
- Hydrogel:Hydrophilic polymer formulations compete on cost in price-sensitive Indian and Southeast Asian markets.
- Acrylic:Hydrophobic formulations with glistening-resistant properties command preference in developed-market premium segments.
Acrylic platforms hold installed capacity. Laser-Assisted is rotating up the share rankings.
End User:
Procurement authority fragmentation between clinical and administrative stakeholders reshapes contract structures across facility types.
- Hospitals:Inpatient and outpatient departments within integrated health systems negotiate enterprise-level IOL contracts bundled with surgical instrumentation. Japanese hospital procurement channels favor precision-molded optics from domestic suppliers, while German university hospitals prioritize research collaboration access in vendor selection.
- Eye Clinics:Specialized ophthalmology practices concentrate surgical volume in cataract and refractive procedures. United States private clinics exercise direct purchasing authority for premium IOL categories outside group purchasing organization constraints.
- Research Institutes:Academic medical centers and contract research organizations source investigational devices for clinical trials.
- Outpatient Facilities:Ambulatory surgery centers in the United States and Germany compress operating room turnover through pre-loaded injector adoption.
Hospitals hold installed capacity. Outpatient Facilities are rotating up the share rankings.
Application:
Reimbursement classification boundaries between medically necessary and elective procedures segment addressable demand pools.
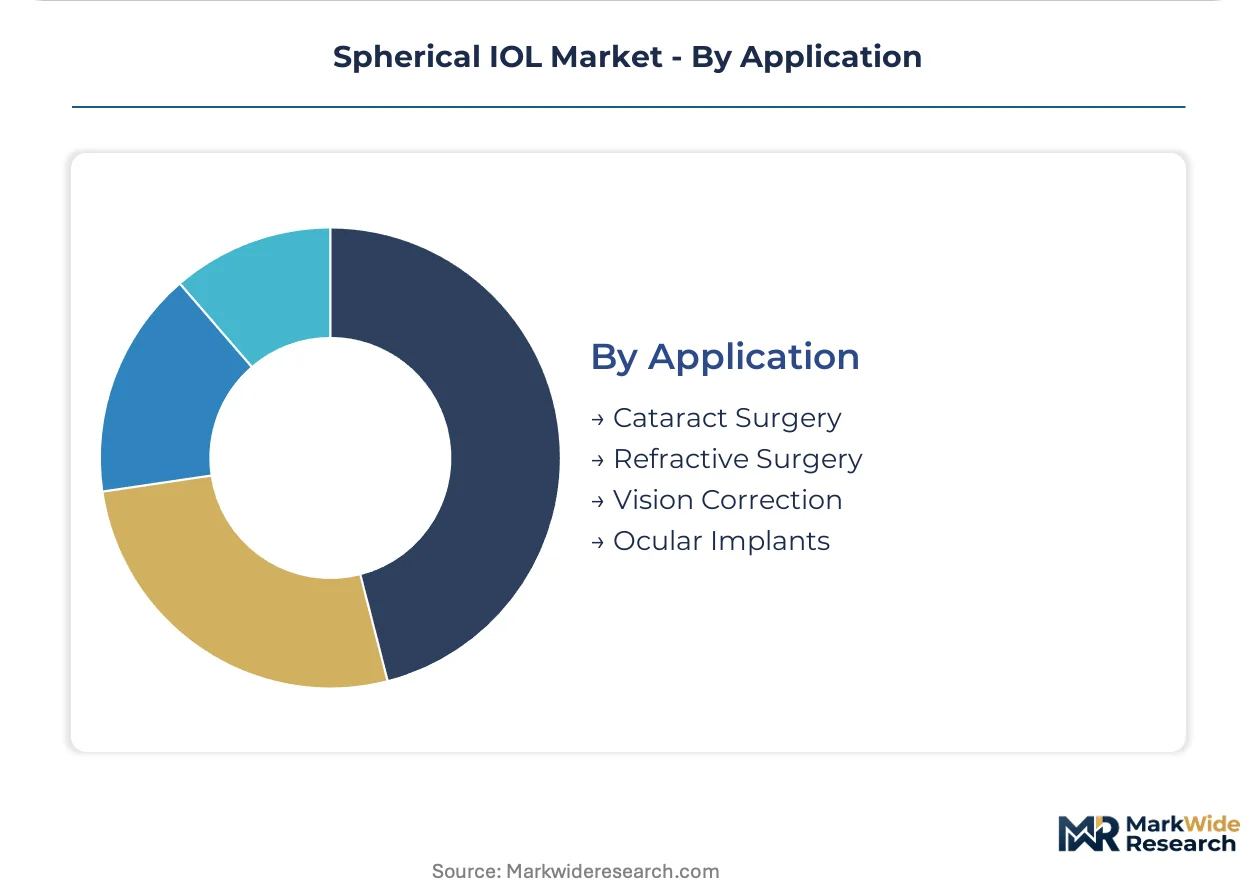
- Cataract Surgery:Extraction of opacified crystalline lens with IOL implantation represents the dominant procedure category. Aging demographics in Japan, Germany, and the United States expand surgical candidacy pools, while Indian tier-two and tier-three cities present volume potential for cost-optimized platforms.
- Refractive Surgery:Clear lens extraction or phakic IOL implantation for myopia, hyperopia, or astigmatism correction outside cataract indication. Private-pay concentration in German and Japanese markets sustains premium pricing for advanced optic designs.
- Vision Correction:Broad category encompassing presbyopia management and post-refractive surgery enhancement procedures.
- Ocular Implants:Secondary IOL placement and complex anterior segment reconstruction applications.
Cataract Surgery holds installed capacity. Refractive Surgery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature reimbursement corridors and emerging volume markets. Japanese and German patients absorb premium out-of-pocket costs for advanced optic geometries, while Indian tier-two cities prioritize cost-optimized hydrogel platforms.
United States
Medicare reimbursement codes cap monofocal IOL unit revenue, compressing procurement cycles at ambulatory surgery centers. The FDA's Class III PMA pathway governs commercialization timelines for acrylic platform iterations. Dallas and Phoenix surgery center chains are adopting pre-loaded injector systems to minimize operating room turnover.
Germany
Statutory health insurance maintains monofocal ceilings while private-pay corridors sustain premium multifocal uptake. The EU MDR's notified body requirements elongate CE marking timelines for hydrogel launches. Heidelberg and Munich university hospitals prioritize laser-assisted delivery integration in procurement decisions.
Japan
Aging demographics over 65 expand surgical candidacy pools faster than surgeon training capacity. PMDA pharmaceutical and medical device agency standards shape product registration sequencing. Tokyo and Osaka hospital procurement channels favor precision-molded optics from domestic suppliers.
India
Tier-two and tier-three cities present underpenetrated cataract surgery access for cost-optimized platforms. The PLI scheme for medical devices attracts contract manufacturing investment. Hyderabad and Bengaluru are developing export-oriented IOL production clusters.
Spherical IOL Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the spherical IOL market structure. Acrylic and hydrogel material platforms concentrate among vertically integrated manufacturers with captive polymer supply arrangements. Two strategic archetypes dominate: diversified ophthalmology conglomerates spanning surgical consumables and diagnostic equipment, and pure-play IOL specialists focused on precision-molded optic geometries. Competitive moves center on pre-loaded injector system development and laser-assisted delivery convergence.
Among diversified ophthalmology conglomerates, Alcon and Johnson & Johnson Vision represent the integrated leader archetype with broad surgical portfolio coverage. HOYA Corporation exemplifies the precision-optics specialist position, anchoring Japanese hospital procurement channels through domestic manufacturing presence. These three entities occupy distinct competitive vectors—material platform breadth, laser-system integration, and regional supply proximity—without overlapping positioning.
| Leading Market Players |
|---|
| Alcon |
| Johnson & Johnson Vision |
| Bausch & Lomb |
| Carl Zeiss Meditec |
| HOYA Corporation |
| Rayner Intraocular Lenses |
| Lenstec |
| STAAR Surgical Company |
| Ophtec |
| Others |
Pricing and Supply Chain Analysis
Ninety-day polymer resin inventory cycles among Japanese hydrophobic acrylic suppliers concentrate pricing power with feedstock specialists, compressing margin capture for IOL molders lacking captive polymer arrangements. This lead-time structure shapes how procurement contracts distribute cost volatility risk across the value chain.
Pricing Analysis
Long-term offtake agreements dominate procurement between ambulatory surgery center chains and acrylic platform manufacturers, insulating volume commitments from spot resin volatility. Pricing stratifies across premium multifocal, standard monofocal, and economy hydrogel tiers, with FDA PMA certification tier and geographic delivery cost as primary differentiation drivers. Cost compression in the monofocal segment intensifies because Medicare reimbursement ceilings fix unit revenue regardless of material sophistication. Eye clinics in the United States private-pay corridor exhibit least price sensitivity, while Indian tier-two outpatient facilities absorb maximum cost pressure.
Supply Chain Analysis
Seventy-five-day mold fabrication lead times from German and Japanese precision tooling suppliers constrain production scaling for novel optic geometries. Hydrophobic acrylic resin production concentrates in Japan, Germany, and the United States, while silicone hydrogel feedstocks draw from South Korean and Chinese chemical manufacturers. Supply chain risk centers on single-source vulnerability for sub-five-micron surface finish molds. Distribution runs through regional medical device distributors with hospital system and GPO contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from procurement authority shifting toward ambulatory surgery center administrators, creating niche positioning for workflow-integrated delivery systems outside traditional hospital contracting channels.
For Market Incumbents: Consolidate position through backward integration into hydrophobic acrylic resin production, neutralizing feedstock cost volatility that erodes monofocal margins. Capture channel control by bundling pre-loaded injector systems with IOL contracts to lock out standalone accessory suppliers. FDA PMA pathway maturation for iterative platforms shortens defensive R&D cycles against emerging hydrogel specialists.
For New Entrants and Emerging Players: Anchor in Indian tier-two and tier-three outpatient expansion, where underpenetrated cataract surgery access meets PLI scheme manufacturing incentives for cost-optimized hydrogel platforms. Target laser-assisted delivery convergence as the most penetrable technology segment, where femtosecond capsulotomy integration with pre-loaded injectors commands premium positioning. Pursue hospital system partnership as the go-to-market angle, bypassing GPO constraints through direct clinical workflow integration.
For Investors and Strategic Acquirers: Long-term, this sits as a demographic-utility play because aging populations in Japan, Germany, and the United States sustain procedure volume growth regardless of economic cycles. Acquisition target archetype: precision-molded optic specialists with PMDA or CE marking precedents under MDR, enabling rapid platform extension. Signal to watch: notified body capacity expansion under EU MDR, which would accelerate hydrogel launch timelines and compress competitive windows.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical file consolidation delays multi-focal line extensions in EU markets. |
| Hospital System Partnership | Japanese procurement channels favor domestic precision-molded optics with research collaboration access. |
| Backward Integration | Captive hydrophobic acrylic resin supply neutralizes polymer feedstock volatility exposure. |
| Software Companion Development | AI-powered preoperative biometric algorithms optimize IOL power selection in German university hospitals. |
| Reimbursement Strategy | Premium multifocal positioning in private-pay corridors sustains margin above Medicare ceilings. |
Research Methodology
Desk research of FDA PMA filings, EU MDR technical documentation, and hospital procurement databases preceded structured interviews with cataract surgeons, ambulatory surgery center administrators, biomedical engineers, and GPO contracts managers. Primary fieldwork combined with secondary validation from PMDA registration data, ISO 11979 certification records, and national reimbursement classification databases. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Variance decomposition across product type, material technology, end-user facility category, and regional reimbursement framework shaped the analytical framework over the projection horizon. CAGRs derived from logistic diffusion modeling of cataract surgery penetration rates by age cohort, calibrated to historical procedure volume trajectories. Forecast inputs incorporated surgeon training capacity constraints and evolving national reimbursement classifications for premium IOL categories.
Material uncertainties — surgeon workforce expansion rates, notified body capacity under EU MDR, and polymer feedstock cost trajectories — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from regulatory pathway changes or reimbursement reclassification events. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Prosthetic Liners Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
Magnetic Ablation Catheter Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Artificial Pancreas Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
India Hemostats Market
Medical Devices
Vibrating Mesh Nebulizer Market
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
Flexible Spinal Implants Market