
 Europe Electric Wheelchair Market | 2026-2036
Europe Electric Wheelchair Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Wheelchair Market Insights
Institutional procurement from senior living facilities is collapsing toward individual direct purchases as home-based care reimbursement expands across EU member states. Permobil AB dominates premium positioning through its sustained R&D intensity in standing-frame electromechanics. Ottobock Healthcare anchors German market share through its specialized rehabilitation channel network. Sunrise Medical competes aggressively on portable lithium-ion configurations for community-dwelling users.
An electric wheelchair is a battery-powered mobility device with motorized drive systems, programmable controllers, and customizable seating platforms designed to transport users with limited ambulatory function across indoor and outdoor environments. Product type segmentation reveals portable models capturing margin pools through airline-compatible folding frames and reduced curb weights, while all-terrain variants lead growth trajectories among younger disabled populations seeking outdoor access parity. End user dynamics show rehabilitation centers standardizing on joystick-controlled platforms for post-stroke training, whereas senior living facilities increasingly specify sip-and-puff interfaces for advanced neuromuscular conditions.
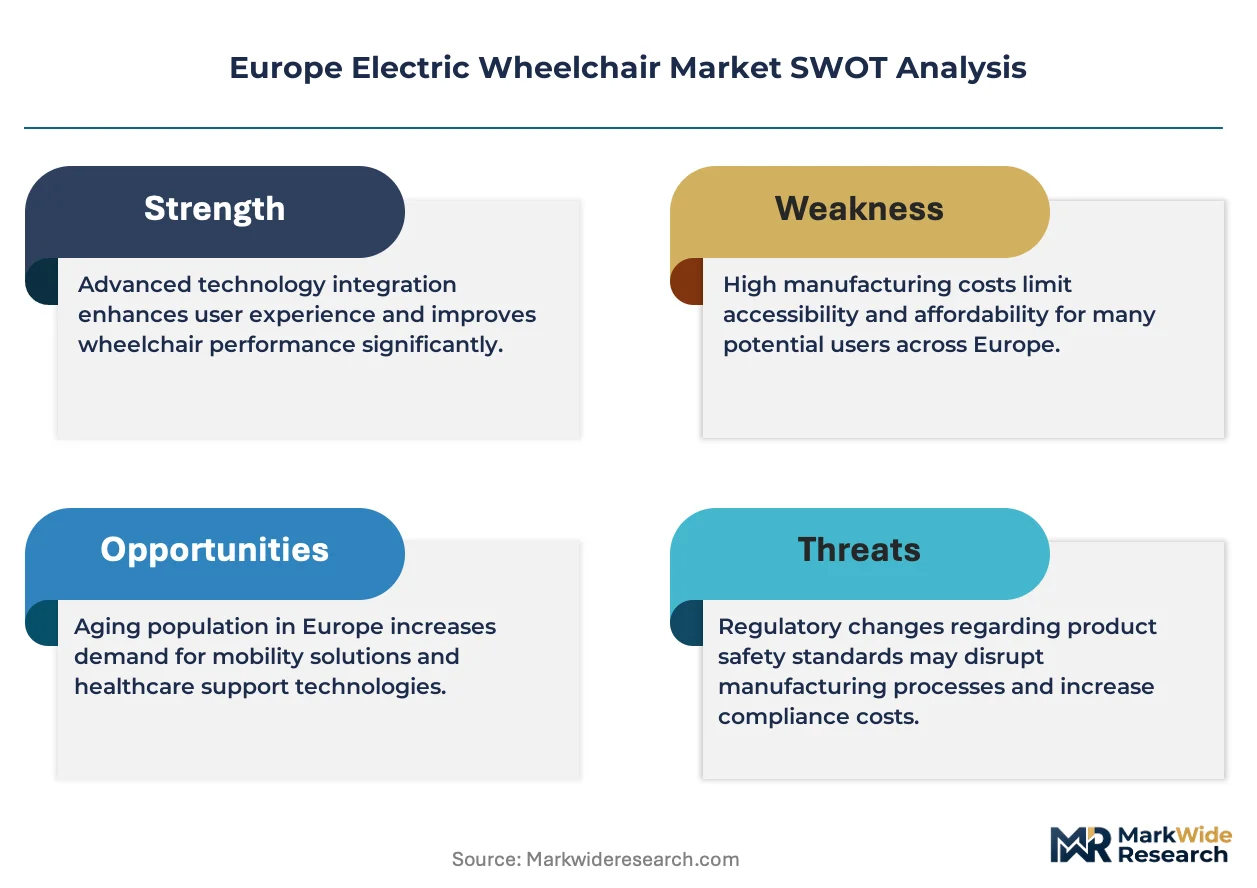
The EU Medical Device Regulation and CE marking framework mandate clinical evidence portfolios for Class IIa active devices, elevating compliance costs for smaller manufacturers while creating structural advantages for established players with notified body relationships. Germany's KBA and France's ANSM coordinate national vigilance reporting for adverse incidents, tightening post-market surveillance obligations. Stakeholders must monitor the interplay between national reimbursement catalog revisions and the EU Green Deal's battery sustainability mandates, as these dual pressures will reshape supplier qualification criteria and raw material sourcing strategies.
Market Dynamics
EU Medical Device Regulation's clinical evidence mandates are compressing supplier viability, concentrating procurement authority among notified body-aligned manufacturers while reimbursement parity accelerates replacement cycles across member states.
Growth Catalysts
- CE Marking Harmonization:MDR Class IIa active device frameworks standardize cross-border procurement for German rehabilitation centers, eliminating redundant national certifications.
- Lithium-Ion Energy Density:Portable folding configurations with airline-compatible battery packs capture margin pools from community-dwelling users seeking outdoor mobility parity.
- France:ANSM-coordinated vigilance reporting streamlines adverse incident transparency, reducing liability premiums for institutional buyers specifying powered seating platforms.
Market Restraints
- Neodymium Magnet Volatility:Rare earth supply concentration in Chinese processing facilities exposes motor assembly costs to export quota fluctuations.
- Notified Body Bottlenecks:MDR designation delays for orthopedic device specialists extend certification timelines beyond 18 months for standing-frame electromechanics.
- Manual Wheelchair Substitution:Lightweight carbon-fiber passive frames retain cost advantage in acute post-surgical recovery settings with short-term rehabilitation needs.
Strategic Opportunities
- Netherlands Home Care Expansion:Municipal Wlz budget reallocations toward individual direct purchases bypass traditional institutional procurement channels.
- EU Green Deal Battery Mandates:Circular economy sourcing requirements for lithium recovery create first-mover advantages for closed-loop supply chain architects.
- Sip-and-Puff Interface Convergence:Integration of respiratory-controlled navigation with environmental control systems opens advanced neuromuscular segments previously served by separate device categories.
Industry Challenges
- Biomechanical Engineer Scarcity:Specialized seating clinic capacity constraints limit customization throughput for complex postural support configurations.
- Legacy Controller Integration:Proprietary joystick protocols from 1990s-era installations resist interoperability with modern Bluetooth-enabled environmental control modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Wheelchair Market |
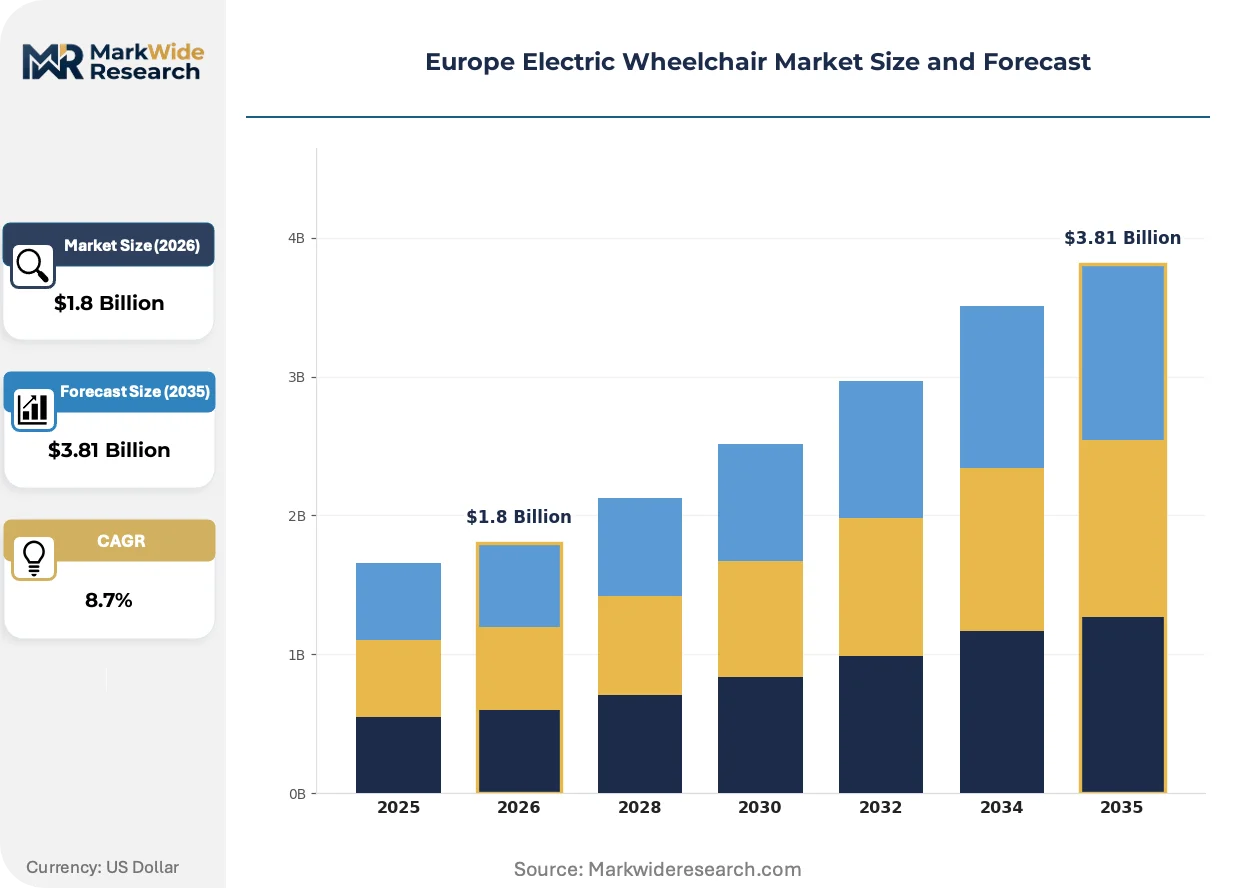
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standing, All-Terrain, Fixed End User: Individuals, Hospitals, Rehabilitation Centers, Senior Living Facilities Battery Type: Li-ion, Lead Acid, Gel, NiMH Control Type: Joystick, Sip-and-Puff, Head Control, Touchscreen |
| Companies Covered | Ottobock Healthcare, GF Health Products, Invacare Corporation, Meyra Group, Levo AG, Permobil AB, Pride Mobility, Karman Healthcare, Sunrise Medical, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Wheelchair Market Trends and Innovations
Standing-frame electromechanics are migrating from rehabilitation centers into domestic settings as programmable controller sophistication enables unsupervised home deployment without clinical oversight infrastructure.
Brushless DC hub motors with integrated electromagnetic braking are displacing traditional gearbox-driven propulsion systems in premium configurations. German outpatient clinics specify these platforms for post-stroke ambulation training where precise speed modulation matters. The technology is displacing maintenance-intensive belt-drive assemblies that previously dominated mid-market institutional procurement.
MDR's post-market surveillance obligations now require systematic clinical follow-up data for Class IIa active mobility devices. Manufacturers must establish pharmacovigilance-equivalent systems tracking device performance across patient populations. Rehabilitation centers in France and Germany face expanded documentation burdens when specifying powered seating for amyotrophic lateral sclerosis progression management.
Individual direct purchases from community-dwelling users are fragmenting traditional distributor relationships that previously dominated institutional sales channels. Netherlands-based home care equipment specialists now maintain digital configuration tools allowing remote seating assessment without clinic visits. This pattern concentrates most visibly in Flanders and North Rhine-Westphalia where municipal reimbursement pre-authorization systems accommodate telehealth-validated prescriptions.
Europe Electric Wheelchair Market Segmentation
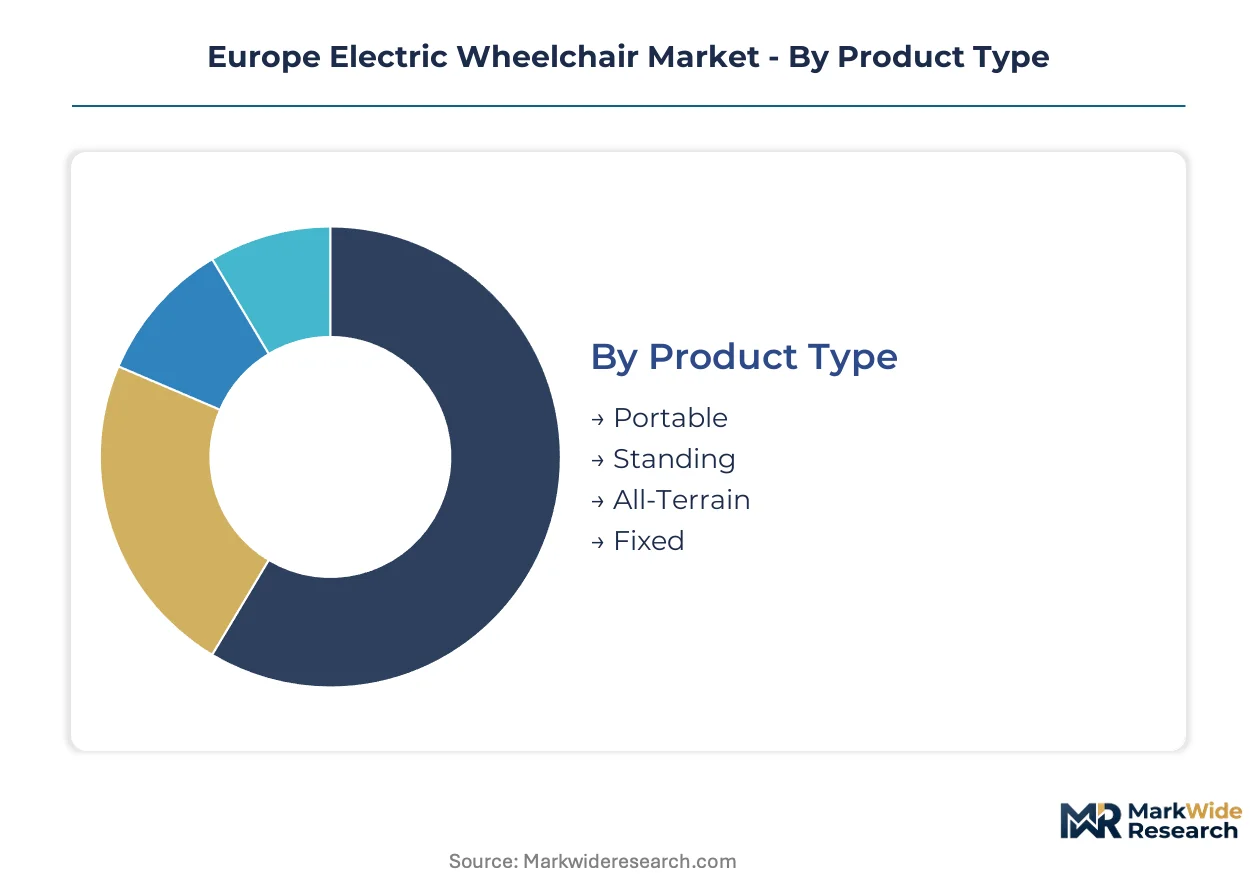
Segmentation in the Europe Electric Wheelchair Market reveals distinct procurement channels and reimbursement pathways that determine manufacturer positioning. Each dimension—product configuration, end-user setting, power source, and control interface—carries specific regulatory and margin implications under MDR compliance frameworks.
Product Type:
Channel distribution varies sharply by mobility configuration, with institutional buyers dominating heavy-duty categories and direct-to-consumer channels capturing portable variants.
- Portable:Folding aluminum frames with airline-compatible lithium-ion packs target community-dwelling users through Netherlands-based home care equipment specialists. Municipal Wlz budget reallocations in Flanders accelerate bypass of traditional distributor networks.
- Standing:Electromechanical lift mechanisms enable postural transition for neuromuscular rehabilitation. German outpatient clinics specify these for post-stroke ambulation training where precise speed modulation supports gait re-education protocols.
- All-Terrain:Four-wheel independent suspension with knobby tread configurations serves younger disabled populations seeking outdoor access parity across rural France and Alpine regions.
- Fixed:Rigid steel-frame platforms with sealed lead-acid batteries anchor budget procurement for long-term care facilities in Eastern European markets with constrained reimbursement ceilings.
By volume, Fixed leads institutional procurement. By growth pace, Portable is gaining share fastest through municipal home care expansion.
End User:
Cost tier stratification separates premium clinical specifications from economy municipal contracts, with reimbursement parity driving replacement cycle acceleration.
- Individuals:Direct purchases through digital configuration tools enable remote seating assessment without clinic visits in North Rhine-Westphalia and Flanders. Telehealth-validated prescriptions concentrate demand among community-dwelling users with complex postural needs.
- Hospitals:Acute care settings prioritize rapid-deployment portable units for post-surgical mobility support. Short length-of-stay protocols favor lightweight configurations over standing-frame electromechanics.
- Rehabilitation Centers:German facilities standardize on joystick-controlled platforms with programmable controllers for standardized post-stroke training protocols. MDR clinical evidence mandates elevate procurement authority toward notified body-aligned manufacturers.
- Senior Living Facilities:France's ANSM-coordinated vigilance reporting streamlines adverse incident transparency for institutional buyers specifying powered seating platforms with sip-and-puff interfaces for advanced neuromuscular conditions.
By volume, Rehabilitation Centers dominate premium procurement. By growth pace, Individuals are expanding most quickly through reimbursement parity reforms.
Battery Type:
Supply concentration in Chinese rare earth processing shapes cost tier differentiation across motor assembly configurations.
- Li-ion:High energy density cells enable airline-compatible folding frames with reduced curb weights. EU Green Deal circular economy mandates for lithium recovery create qualification barriers for non-compliant suppliers.
- Lead Acid:Sealed absorbent glass mat configurations retain cost advantage in fixed-frame institutional procurement with predictable daily duty cycles and indoor-only deployment.
- Gel:Maintenance-free electrolyte suspension suits senior living facilities with limited technical staff capacity for battery management protocols.
- NiMH:Nickel-metal hydride packs persist in legacy controller integrations where proprietary voltage protocols resist lithium migration without full system replacement.
By volume, Lead Acid retains installed base dominance. By growth pace, Li-ion is climbing the fastest through EU sustainability mandates and portable segment expansion.
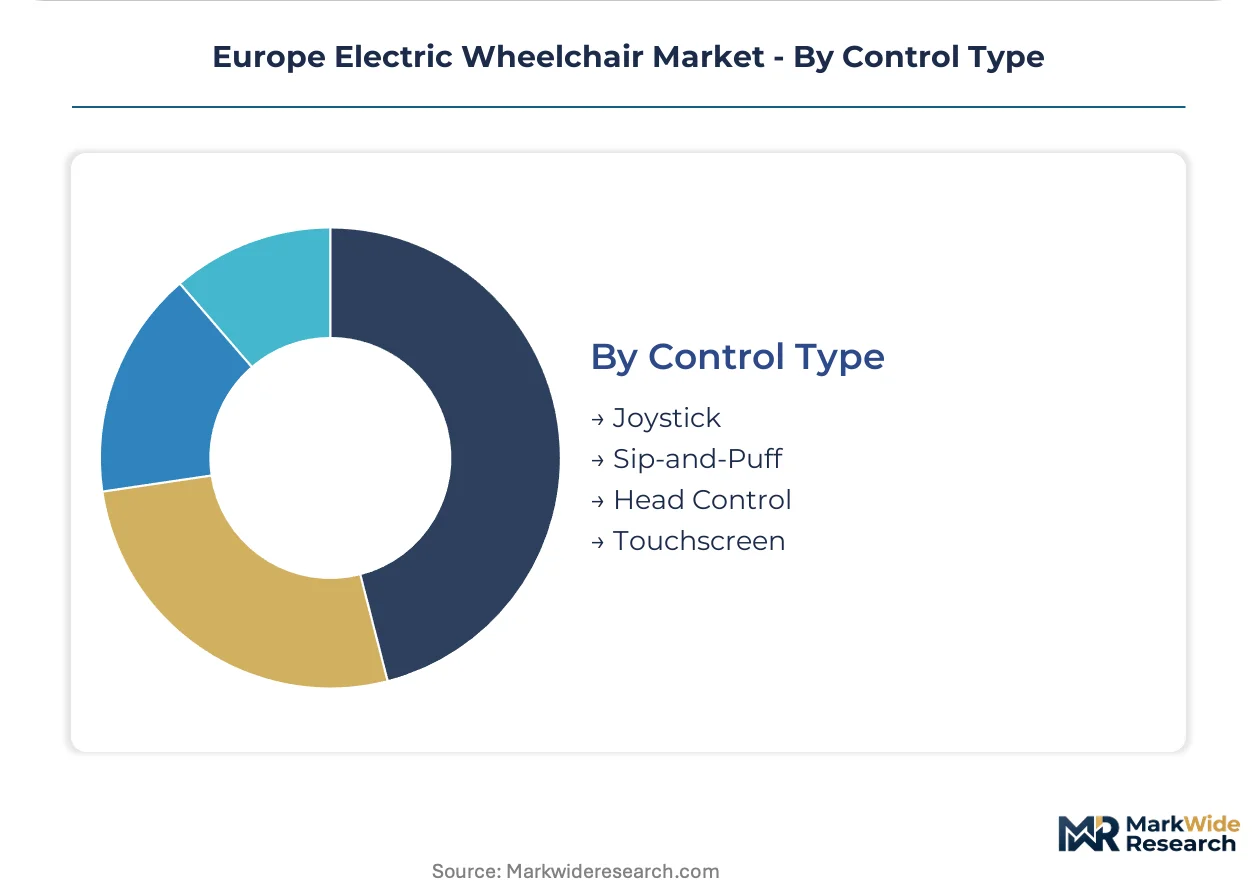
Control Type:
Application specificity determines interface specification, with neurological indication severity driving premium control system integration.
- Joystick:Proportional control with programmable acceleration curves dominates rehabilitation center procurement for post-stroke training where fine motor recovery assessment matters.
- Sip-and-Puff:Respiratory pressure sensors enable navigation for ALS progression management in French and German centers. Environmental control system convergence opens advanced neuromuscular segments previously served by separate device categories.
- Head Control:Proximity-sensing arrays mounted on headrest assemblies serve high-level spinal cord injury populations with preserved cervical mobility but absent upper extremity function.
- Touchscreen:Capacitive display interfaces with gesture recognition target younger disabled users with sufficient fine motor control for smartphone-parallel interaction patterns.
By volume, Joystick leads across institutional procurement. By growth pace, Sip-and-Puff shows steepest expansion trajectory through ALS demographic concentration and environmental control integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers dominate export flows to French rehabilitation networks, while Dutch municipal procurement reforms redirect institutional purchasing toward direct consumer channels across the Low Countries.
Germany
Post-stroke rehabilitation protocols drive joystick-controlled platform demand from outpatient clinics. KBA coordinates national vigilance reporting for adverse incidents, tightening post-market surveillance. North Rhine-Westphalia hosts the densest concentration of seating assessment centers where telehealth-validated prescriptions accelerate individual procurement.
France
ALS progression management creates specialized demand for sip-and-puff interface integration. ANSM streamlines adverse incident transparency for institutional buyers specifying powered seating platforms. Rehabilitation centers in Île-de-France standardize procurement toward notified body-aligned manufacturers with established clinical evidence portfolios.
Netherlands
Municipal Wlz budget reallocations shift procurement authority from senior living facilities toward individual direct purchases. EU Green Deal battery sustainability mandates reshape supplier qualification criteria for lithium recovery compliance. Flanders-based home care equipment specialists deploy digital configuration tools enabling remote seating assessment without clinic visits.
United Kingdom
Community-dwelling users seek outdoor mobility parity through portable folding configurations. NHS reimbursement catalog revisions accelerate replacement cycles for powered seating platforms. Greater London rehabilitation networks concentrate demand for standing-frame electromechanics in post-stroke ambulation training.
Italy
Eastern European budget procurement constraints anchor fixed-frame platform demand with sealed lead-acid configurations. CE marking harmonization eliminates redundant national certifications for cross-border institutional sales. Lombardy-based distributors serve as intermediaries for German manufacturer penetration into Mediterranean markets.
Europe Electric Wheelchair Market Competitive Landscape
Player mix skews toward diversified rehabilitation conglomerates with established notified body relationships. Market structure concentrates procurement authority among manufacturers with pharmacovigilance-equivalent post-market surveillance systems. Strategic archetypes include premium electromechanics specialists, portable lithium-ion configurators, and institutional channel anchors. Dominant competitive moves encompass M&A for clinical evidence portfolio accumulation and capacity expansion into closed-loop battery supply chains.
Within the premium-tier vector, Permobil AB and Ottobock Healthcare occupy positions shaped by sustained R&D intensity and specialized rehabilitation channel networks respectively. Sunrise Medical exemplifies the portable configuration archetype through airline-compatible folding frame development. Meyra Group anchors mid-market institutional procurement with standardized joystick-controlled platforms. These three entities represent the competitive spectrum from standing-frame electromechanics to community-dwelling portability solutions.
| Leading Market Players |
|---|
| Ottobock Healthcare |
| GF Health Products |
| Invacare Corporation |
| Meyra Group |
| Levo AG |
| Permobil AB |
| Pride Mobility |
| Karman Healthcare |
| Sunrise Medical |
| Others |
Pricing and Supply Chain Analysis
Brushless DC hub motor substitution for belt-drive assemblies simultaneously relocates motor manufacturing toward Chinese rare earth processing zones and compresses premium-tier pricing spreads as electromagnetic braking modules standardize across German and French procurement catalogs.
Pricing Analysis
Technology-generation pricing gaps separate next-generation brushless DC platforms from legacy belt-drive configurations and emerging solid-state battery prototypes. Three-tier pricing structure across premium standing-frame electromechanics, standard joystick-controlled rehabilitation platforms, and economy fixed-frame institutional units prevails. Cost compression in mid-market portable lithium-ion segments is intensifying because airline-compatible folding frames commoditize faster than MDR certification costs can differentiate suppliers. Rehabilitation centers in Germany exhibit lowest price sensitivity given clinical evidence mandates, while Eastern European long-term care facilities anchor economy-tier volume.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for lithium-ion cell shipments from South Korean and Chinese manufacturing hubs. Motor assembly draws from Chinese rare earth processing facilities, German precision controller fabrication, and Taiwanese semiconductor packaging for programmable drive modules. Single-source vulnerability concentrates in neodymium magnet supply chains tethered to Chinese export quota administration. Distribution runs through notified body-aligned manufacturer direct sales for institutional procurement and Netherlands-based home care equipment specialists for individual direct purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controller-protocol interoperability platforms are reshaping competitive economics as Bluetooth-enabled environmental control modules displace proprietary 1990s-era joystick architectures across French and German rehabilitation networks.
For Market Incumbents: Secure notified body relationship deepening through MDR clinical evidence portfolio expansion, defending against portable-specialist entrants exploiting municipal Wlz budget reallocations. Backward integration into closed-loop lithium recovery systems anchors EU Green Deal compliance advantages. Capacity addition in North Rhine-Westphalia seating assessment clusters captures telehealth-validated prescription growth.
For New Entrants and Emerging Players: Anchor in Flanders and North Rhine-Westphalia municipal home care channels where digital configuration tools bypass traditional distributor relationships. The most penetrable segment comprises community-dwelling users with complex postural needs seeking remote assessment capabilities. A direct-to-consumer go-to-market angle through telehealth-integrated prescription platforms avoids institutional procurement bottlenecks.
For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors notified body-aligned manufacturers with pharmacovigilance-equivalent post-market surveillance infrastructure. Long-term viability hinges on MDR certification asset accumulation rather than manufacturing scale alone. Acquisition target archetype: mid-cap portable configurators with airline-compatible folding frame IP and established lithium-ion supply relationships. The signal to watch is ANSM-coordinated adverse incident reporting transparency tightening liability premiums for non-compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Class IIa active device certification eliminates redundant national approvals for cross-border German-French procurement. |
| Hospital System Partnership | Rehabilitation center standardization contracts lock in joystick-controlled platform volume for post-stroke training protocols. |
| Software Companion Development | Bluetooth-enabled environmental control integration opens ALS progression management segments for sip-and-puff interfaces. |
| Reimbursement Strategy | Municipal Wlz budget alignment accelerates individual direct purchase bypass of traditional institutional channels. |
| Backward Integration | Closed-loop lithium recovery systems satisfy EU Green Deal circular economy mandates for battery sustainability compliance. |
Research Methodology
Desk research of EU Medical Device Regulation guidance documents, ANSM vigilance reporting databases, and municipal Wlz budget allocation records preceded structured interviews with rehabilitation center procurement directors, biomedical engineers specializing in seating assessment, notified body technical reviewers, and home care equipment specialist distributors. Secondary validation drew from KBA adverse incident filings, hospital procurement database extracts, and lithium-ion trade flow customs records. Bottom-up unit demand estimates triangulated against top-down reimbursement catalog expenditure analysis.
Variance decomposition across product configuration, end-user setting, battery chemistry, and control interface dimensions shaped analytical framework construction over the projection horizon. CAGRs derived from replacement cycle acceleration patterns under reimbursement parity reforms and penetration curve modeling for standing-frame electromechanics in domestic settings. Forecast inputs incorporated MDR certification timeline delays and EU Green Deal battery mandate implementation pacing.
Decision-makers should treat outputs as directional under sustained reimbursement parity and stable rare earth supply assumptions; material deviation in Chinese export quota administration or municipal budget reallocation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Self-Injection Device Market
Medical Devices
Spinal Implant Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Cholecystectomy Devices Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Global Ileostomy Market
Medical Devices
Global Medical Implants Market
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Global Microcatheter Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Gel Implants Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
China Contraceptive Devices Market
Medical Devices
Handheld Red Light Therapy Device Market