
 Superficial Radiation Therapy System Market | 2026-2036
Superficial Radiation Therapy System Market Size, Share, and Industry Trends Forecast 2026-2036
Superficial Radiation Therapy System Market Outlook
Software-defined treatment planning and remote dose monitoring is recalibrating how superficial radiation therapy systems are sold, shifting hardware vendors toward recurring revenue architectures. Sensus Healthcare leverages its installed base of mobile SRT units to anchor aftermarket service contracts. Xstrahl Limited specializes in fixed-beam superficial systems for hospital dermatology departments. Varian Medical Systems extends its radiation oncology software stack into lower-energy modalities, competing on workflow integration rather than dose physics alone.
Superficial radiation therapy systems deliver precisely controlled low-energy radiation—typically 50 to 150 kV or beta-emitting isotopes—to treat lesions at depths up to 5 mm without penetrating deeper tissue. These devices serve primarily as alternatives to surgical excision for basal and squamous cell carcinomas, keloid suppression, and select benign dermatological conditions. Mobile units dominate current procurement patterns among outpatient dermatology practices seeking capital flexibility, while electron therapy technology leads clinical preference for irregular lesion geometries. NanoBeam technology represents the fastest-growing segment, though its premium pricing limits penetration outside academic cancer treatment centers where reimbursement rates absorb innovation costs.
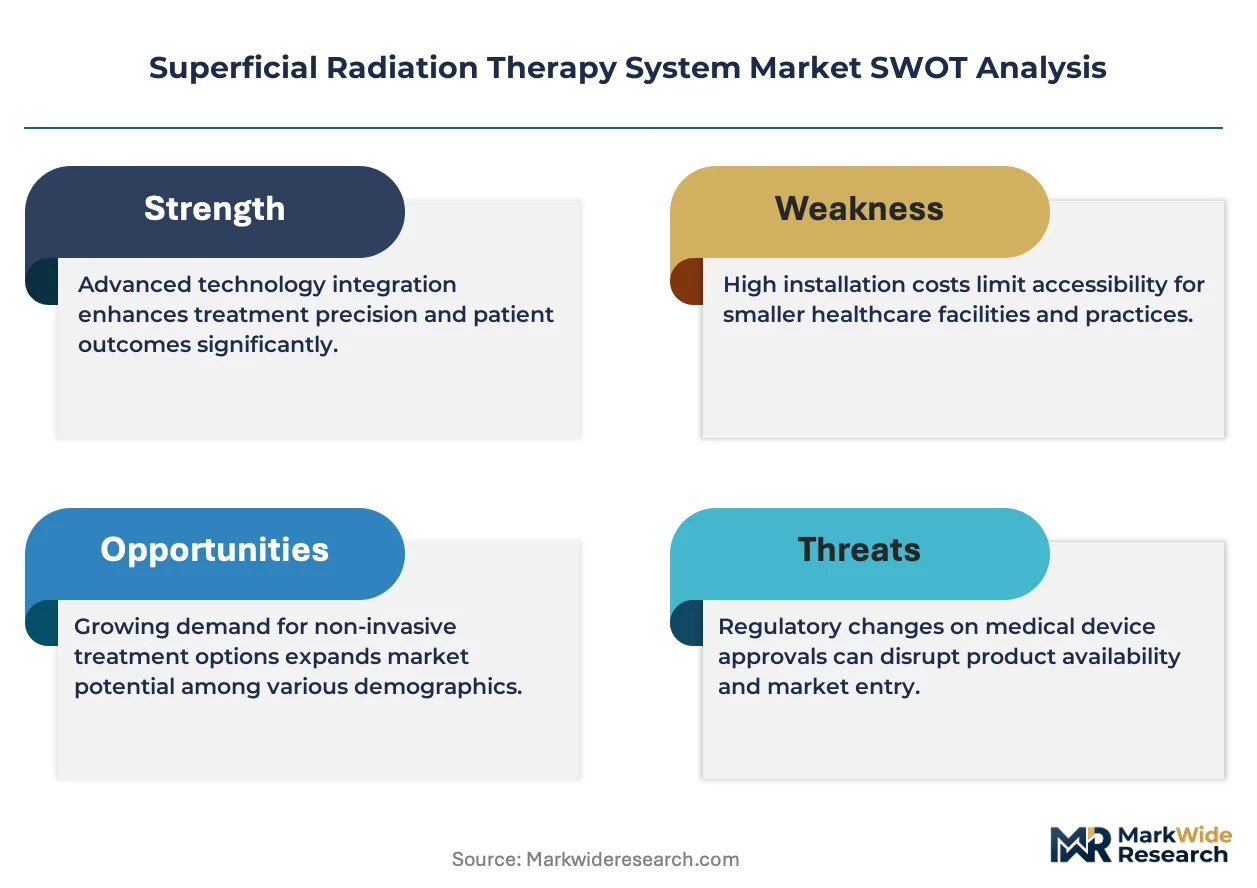
The FDA governs 510(k) premarket notification for these Class II radiation-emitting devices, while the Nuclear Regulatory Commission maintains jurisdiction over isotope-based systems such as strontium-90 applicators. State-level radiation control programs add licensing layers that fragment go-to-market speed across jurisdictions. ISO 13485 quality management certification functions as a de facto market access threshold for original equipment manufacturers serving institutional buyers. Stakeholders must monitor how CMS reimbursement coding for image-guided superficial radiation evolves relative to Mohs surgery alternatives, as payment parity decisions will reshape site-of-care economics and capital deployment priorities.
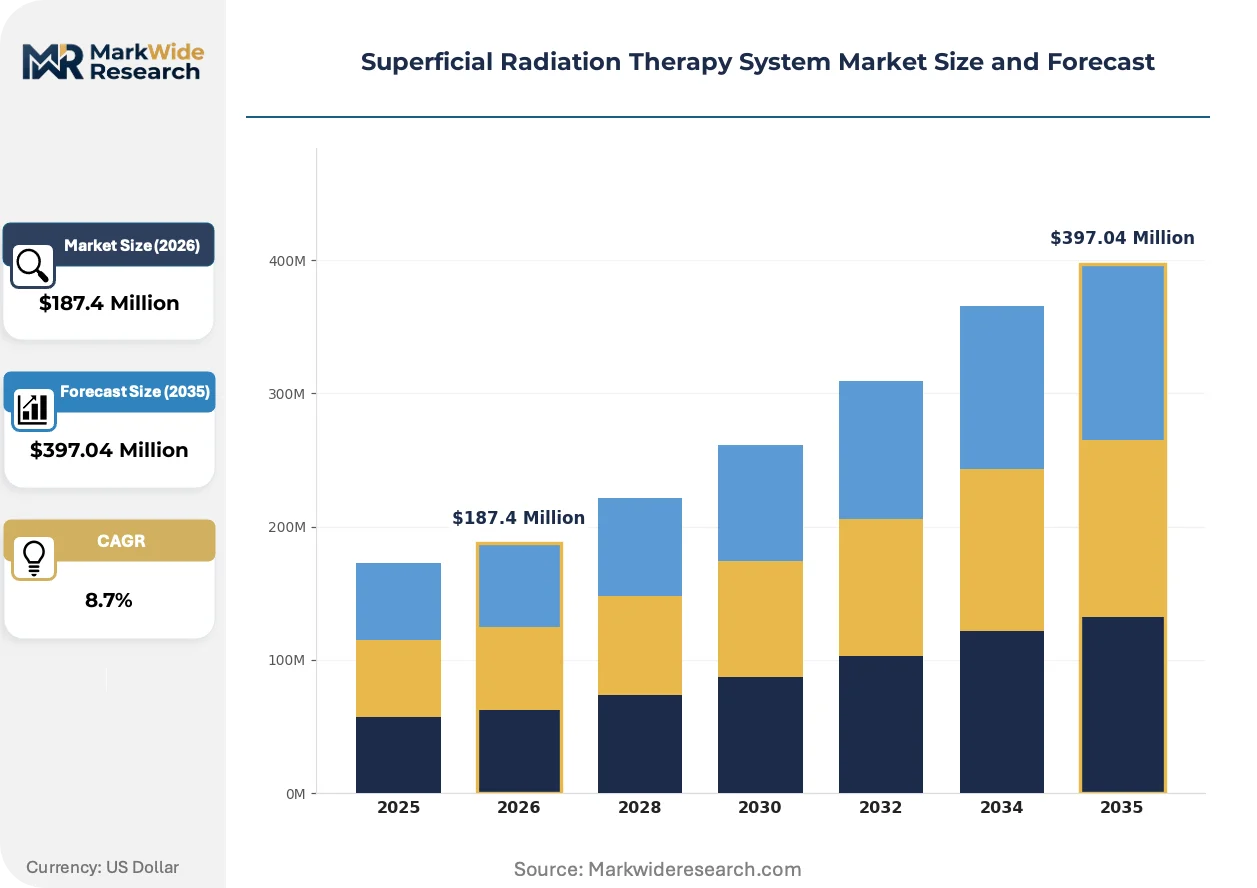
Market Dynamics
Software-defined treatment planning is compressing hardware margins and forcing superficial radiation therapy vendors toward recurring revenue models anchored by service contracts and remote monitoring subscriptions.
Growth Catalysts
- FDA 510(k) clearance pathways:The streamlined premarket notification process for Class II radiation-emitting devices accelerates product iteration cycles and reduces regulatory capital requirements for original equipment manufacturers.
- Aging population demographics:Rising incidence of basal cell carcinoma among patients over 65 drives referral volumes into dermatology clinics seeking non-surgical alternatives to Mohs excision.
- Electron therapy technology:Superior dose conformity for irregular lesion geometries positions electron-based systems as the clinical preference for complex anatomical sites.
Market Restraints
- Isotope supply concentration:Strontium-90 sourcing depends on limited nuclear reactor infrastructure, creating vulnerability for beta-emitter applicator manufacturers.
- State-level licensing fragmentation:Radiation control programs vary across jurisdictions, multiplying compliance costs and slowing go-to-market velocity for multi-state clinic networks.
- Mohs surgery reimbursement parity:Established payment rates for surgical excision create a substitute threat that limits superficial radiation therapy adoption in fee-for-service environments.
Strategic Opportunities
- Academic cancer centers:NanoBeam technology penetration concentrates in institutions with reimbursement rates that absorb premium pricing for advanced beam delivery systems.
- Image-guided coding evolution:CMS reimbursement pathway development for image-guided superficial radiation creates payment parity potential that would reshape site-of-care economics.
- Mobile unit leasing models:Capital flexibility demands from outpatient dermatology practices open channel innovation through equipment-as-a-service structures.
Industry Challenges
- Medical physicist staffing:Specialized expertise requirements for treatment planning and quality assurance create bottlenecks in clinic expansion timelines.
- ISO 13485 certification timelines:Quality management system implementation delays market access for original equipment manufacturers targeting institutional buyers.
- Legacy EMR integration:Workflow connectivity with existing electronic medical record systems demands custom interface development that extends deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superficial Radiation Therapy System Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Units, Fixed Units, Hybrid Systems, Software Solutions End User: Hospitals, Outpatient Clinics, Research Institutions, Cancer Treatment Centers Technology: Electron Therapy, Photon Therapy, Strontium-90 Therapy, NanoBeam Technology Application: Skin Cancer Treatment, Benign Lesions, Keloid Management, Palliative Care |
| Companies Covered | Sensus Healthcare, Xstrahl Limited, Varian Medical Systems, Elekta, Siemens Healthineers, Mevion Medical Systems, Ion Beam Applications, RaySearch Laboratories, IsoRay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superficial Radiation Therapy System Market Strategic Shifts
Artificial intelligence is embedding into treatment planning workflows, while reimbursement policy evolution and procurement model restructuring reshape how capital equipment flows into clinical settings.
Image-guided superficial radiation therapy systems are consolidating market positioning by integrating real-time lesion visualization with automated beam positioning. Dermatology clinics with high patient throughput are adopting these systems fastest, prioritizing workflow efficiency over capital cost. The technology is consolidating competitive differentiation around software capabilities rather than dose physics alone.
The FDA maintains 510(k) premarket notification jurisdiction over Class II radiation-emitting devices, while the Nuclear Regulatory Commission governs isotope-based systems. This dual-agency oversight creates compliance complexity that favors vendors with established regulatory affairs infrastructure. Hospital-based dermatology departments absorb these friction costs more readily than independent outpatient practices.
Service contract unbundling is separating hardware acquisition from maintenance and software access. Outpatient dermatology practices increasingly prefer subscription-based remote monitoring over bundled capital purchases. This shift concentrates most visibly in the United States, where private clinic ownership structures prioritize cash flow predictability over asset ownership.
Superficial Radiation Therapy System Market Segmentation
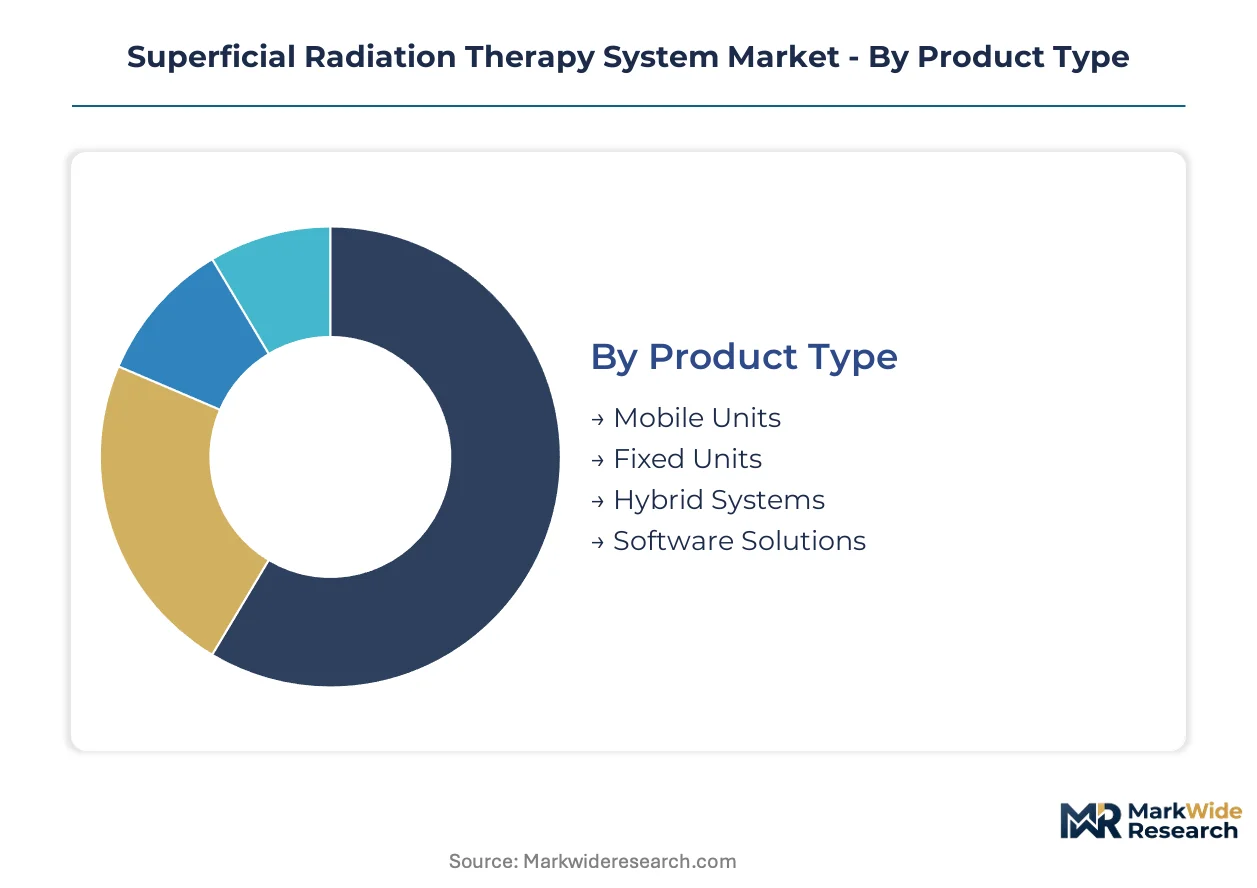
Superficial radiation therapy system procurement diverges sharply across clinical settings, with capital constraints, reimbursement structures, and lesion complexity dictating hardware versus software priorities. Vendors calibrate product roadmaps around these fault lines, optimizing for either high-throughput outpatient workflows or precision-driven academic protocols.
Product Type:
Customization-versus-standardization tension runs deepest here, as mobile configurations sacrifice beam stability for deployment flexibility while fixed installations optimize dose physics at the cost of capital mobility.
- Mobile Units:Self-contained systems mounted on wheeled platforms enable same-day deployment across multiple treatment rooms. Outpatient dermatology practices in the United States favor these configurations for their lease-friendly capital profiles and minimal facility retrofit requirements.
- Fixed Units:Permanent installations with reinforced shielding and hardwired power conditioning deliver superior dose reproducibility. Hospital dermatology departments absorb higher upfront costs to secure tighter integration with existing radiation oncology infrastructure.
- Hybrid Systems:Modular architectures allowing field conversion between mobile and fixed configurations.
- Software Solutions:Standalone treatment planning and remote monitoring platforms decoupled from hardware acquisition.
Leading the category by volume: Mobile Units. Expanding most quickly: Software Solutions.
End User:
Procurement authority concentrates differently across this category, with hospital purchasing committees emphasizing total cost of ownership while independent clinics prioritize payback period metrics.
- Outpatient Clinics:Independent dermatology practices with high basal cell carcinoma caseloads drive demand for streamlined workflows and minimal physicist dependency. These facilities in Florida and Arizona prioritize systems with automated quality assurance protocols to offset staffing constraints.
- Hospitals:Integrated health systems leverage existing radiation oncology departments for shared physicist coverage and centralized maintenance contracts. Academic medical centers in Boston and Houston favor these arrangements for their resident training synergies.
- Cancer Treatment Centers:Specialized oncology facilities with dedicated dermatologic surgery divisions.
- Research Institutions:University-affiliated centers conducting protocol development and device validation studies.
Volume leader: Outpatient Clinics. Steepest expansion trajectory: Cancer Treatment Centers.
Technology:
Clinical preference splits along lesion geometry complexity, with irregular anatomical sites demanding superior dose conformity while routine presentations tolerate simpler beam characteristics.
- Electron Therapy:Accelerated particle beams with customizable applicator sizes enable precise dose sculpting around curved surfaces like the nasal ala or helical rim. Major cancer centers in New York and California specify these systems for their Mohs surgery alternative programs.
- NanoBeam Technology:Sub-millimeter beam collimation with real-time imaging feedback supports treatment of periorbital and digital lesions. Premium pricing restricts deployment to academic institutions with reimbursement rates absorbing capital intensity.
- Photon Therapy:Lower-energy X-ray systems with simpler calibration requirements for routine superficial applications.
- Strontium-90 Therapy:Beta-emitting isotope applicators for thin lesions with minimal depth penetration requirements.
Volume leader: Electron Therapy. Gaining share fastest: NanoBeam Technology.
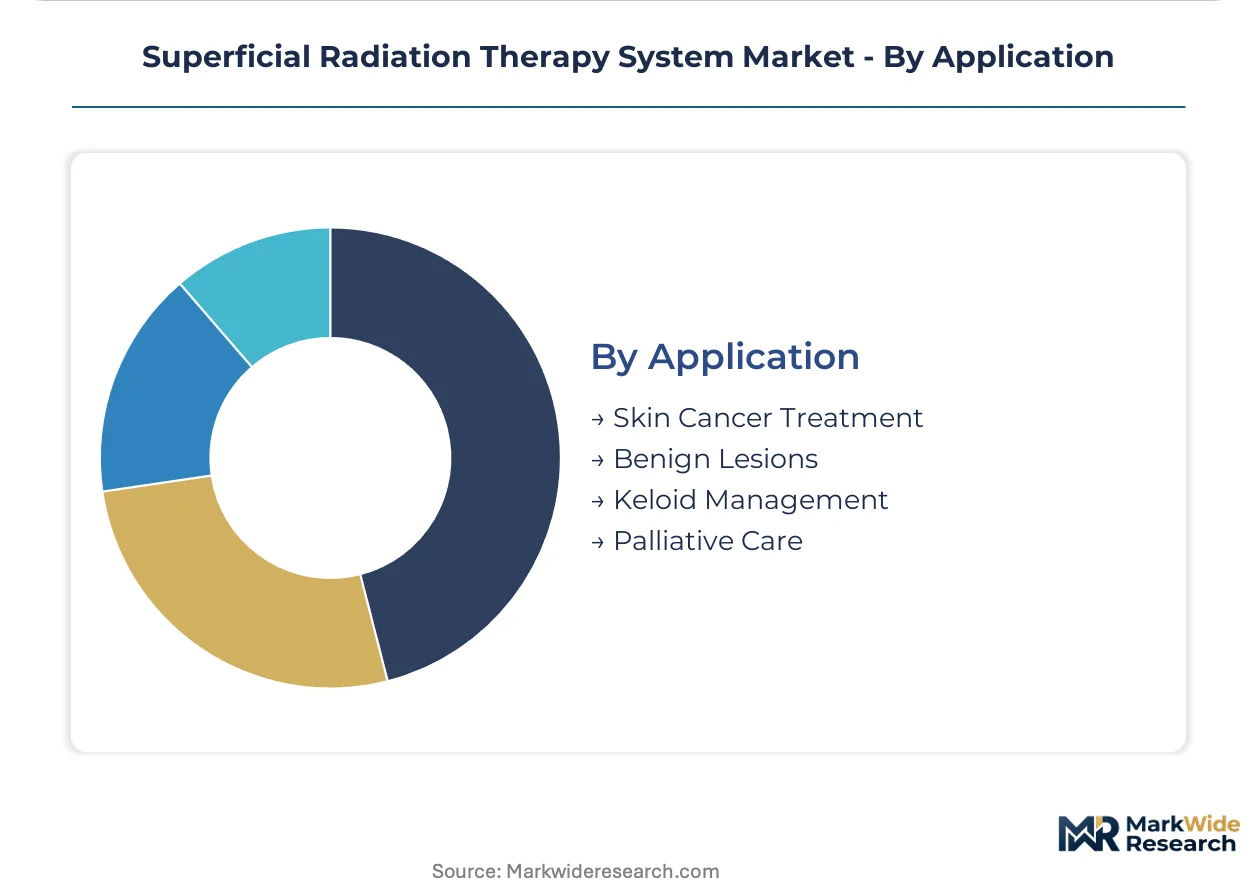
Application:
Reimbursement parity dynamics reshape priority rankings here, with established surgical alternatives constraining adoption in some indications while unmet needs accelerate penetration in others.
- Skin Cancer Treatment:Basal and squamous cell carcinoma protocols constitute the primary revenue anchor, with non-melanoma lesions amenable to radiation-based organ preservation. Medicare reimbursement coding evolution in the United States determines site-of-care economics for this segment.
- Keloid Management:Post-surgical radiation protocols for hypertrophic scar prevention command premium pricing in cosmetic surgery adjacencies. Demand concentrates in metropolitan markets with high aesthetic procedure density.
- Benign Lesions:Seborrheic keratosis and other non-malignant indications with elective treatment profiles.
- Palliative Care:Symptom-directed applications for fungating tumors and bleeding control in advanced disease.
Volume leader: Skin Cancer Treatment. Climbing the fastest: Keloid Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American superficial radiation therapy system deployment, with Massachusetts General Hospital and Dana-Farber Cancer Institute driving clinical protocol development and resident training pipelines.
United States
Florida and Arizona dermatology practices prioritize mobile SRT units for lease-friendly capital profiles. FDA 510(k) clearance pathways accelerate product iteration for Class II radiation devices. Miami-Dade County outpatient clinics deploy automated quality assurance protocols to offset medical physicist staffing constraints.
Germany
Hospital dermatology departments in Bavaria and North Rhine-Westphalia favor fixed-beam installations with reinforced shielding. CE marking under EU MDR governs device market access timelines. Heidelberg University Hospital integrates superficial radiation systems with existing radiation oncology infrastructure for shared physicist coverage.
United Kingdom
NHS England reimbursement frameworks shape site-of-care economics for non-melanoma skin cancer protocols. MHRA maintains jurisdiction over premarket device registration. London teaching hospitals concentrate electron therapy adoption for Mohs surgery alternative programs.
Japan
Tokyo metropolitan cancer centers absorb premium NanoBeam technology pricing within reimbursement-absorbing institutional budgets. PMDA reviews radiation-emitting medical devices under Pharmaceutical and Medical Device Act provisions. Osaka-Kobe medical corridor facilities emphasize workflow integration with legacy radiation oncology software stacks.
Australia
Melbourne and Sydney dermatology networks expand mobile unit leasing for capital flexibility in private practice structures. TGA regulates therapeutic radiation devices under medical device framework. Queensland regional clinics deploy remote dose monitoring subscriptions to reduce on-site physicist dependency.
Superficial Radiation Therapy System Market Competitive Environment
Capital-heavy producers compete with asset-light designers across superficial radiation therapy system supply. The vendor base stratifies between integrated radiation oncology conglomerates and specialized dermatology-focused equipment fabricators. Three archetypes dominate: mobile-first outpatient specialists, fixed-installation hospital suppliers, and software-centric workflow integrators. Competitive maneuvering concentrates on service contract unbundling and recurring revenue architectures displacing bundled capital sales.
Within the mobile-specialist tier, Sensus Healthcare and Xstrahl Limited exemplify hardware vendors pivoting toward aftermarket service anchoring. Varian Medical Systems occupies a position among scale-driven radiation oncology platform providers extending software stacks into lower-energy modalities. These three represent contrasting strategic postures—capital mobility versus institutional integration versus workflow software penetration—without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| Sensus Healthcare |
| Xstrahl Limited |
| Varian Medical Systems |
| Elekta |
| Siemens Healthineers |
| Mevion Medical Systems |
| Ion Beam Applications |
| RaySearch Laboratories |
| IsoRay |
| Others |
Value Chain & Pricing Dynamics
Medical physicist concentration in Boston and Heidelberg sustains labor-cost premiums that separate premium-tier NanoBeam installations from standard electron-therapy configurations across outpatient dermatology markets.
Pricing Analysis
Throughput-linked pricing anchors vendor revenue models, with outpatient clinics in Florida and Arizona paying subscription rates tied to patient volume rather than capital ownership. Price differentiation separates ISO 13485-certified institutional systems from non-certified alternatives, while software companion access commands recurring premiums. Cost compression in mobile-unit leasing intensifies as Sensus Healthcare and Xstrahl Limited compete for dermatology practice contracts. Independent outpatient clinics exhibit highest price sensitivity, whereas academic cancer centers in Tokyo and Boston absorb premium NanoBeam pricing within reimbursement-absorbing budgets.
Supply Chain Analysis
Domestic-content mandates in Germany and Japan reshape sourcing for radiation shielding components and beam collimation hardware. Manufacturing concentrates in the United States, Germany, and Japan for precision-machined applicators and power conditioning modules. Strontium-90 isotope supply rests on limited nuclear reactor infrastructure in Russia and South Africa. Single-source vulnerability in beta-emitter sourcing threatens applicator manufacturers during geopolitical disruptions. Distribution runs through specialized radiation oncology equipment distributors with regional physicist training capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Superficial Radiation Therapy System Market operates as a cost-of-compliance story where FDA 510(k) clearance pathways and ISO 13485 certification timelines create barrier-to-entry moats favoring established regulatory affairs infrastructure.
For Market Incumbents: Anchor defensive positioning through exclusive service contract unbundling that locks outpatient dermatology practices into remote monitoring subscriptions. Deepen backward integration into treatment planning software stacks to offset hardware margin compression from mobile-unit leasing competition. Counter emerging software-centric workflow integrators by accelerating EMR interface pre-certification with Epic and Cerner deployments.
For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass established distributor relationships that favor incumbents with physicist training networks. Target keloid management protocols in metropolitan cosmetic surgery markets where reimbursement flexibility exceeds skin cancer treatment parity constraints. Pursue white-label manufacturing partnerships with existing Class II radiation device holders to compress FDA 510(k) pathway timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with software-centric workflow integrators given CMS image-guided reimbursement coding evolution as a catalyst for recurring revenue multiple expansion. Long-term viability favors vendors with installed bases exceeding 500 mobile units capable of anchoring aftermarket service contract transitions. Monitor Nuclear Regulatory Commission isotope licensing backlog as an inflection signal for beta-emitter applicator supply constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined premarket notification compresses product iteration cycles for Class II radiation devices. |
| Hospital System Partnership | Integrated health systems in Boston and Houston enable shared physicist coverage across dermatology departments. |
| Software Companion Development | Standalone treatment planning platforms decouple revenue from hardware acquisition cycles. |
| Reimbursement Strategy | CMS coding evolution for image-guided superficial radiation reshapes site-of-care economics. |
| CE Marking Pathway | EU MDR compliance opens Bavaria and North Rhine-Westphalia hospital procurement channels. |
Study Parameters
Multi-period observation of FDA 510(k) clearance volumes, CMS reimbursement coding updates, and dermatology clinic expansion rates anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiation oncology department heads. Secondary validation drew from FDA 510(k) database filings, CMS Medicare fee schedule releases, hospital procurement databases, and ISO 13485 certification registries. Bottom-up unit deployment tracking across outpatient clinics and top-down revenue estimation for installed base service contracts were triangulated against manufacturer reported shipment data.
Input-output matrices mapped electron therapy, NanoBeam technology, photon therapy, and strontium-90 modality penetration against outpatient clinic, hospital, and cancer treatment center end-user segments across the projection horizon. CAGRs were derived from segmented growth rate aggregation with cross-validation against macroeconomic healthcare expenditure trends. Forecast inputs incorporated medical physicist staffing ratios by metropolitan statistical area and state-level radiation control program licensing velocity as demand-side constraints.
The model holds under stable FDA 510(k) review timelines and intact isotope supply chains; deviation in Nuclear Regulatory Commission enforcement posture or strontium-90 reactor outages would shift deployment trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Massage Equipment Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
Organ Care Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Global High-Flow Nasal Cannula Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
US Nebulizer Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market