
 Casting Resin Market | 2026-2036
Casting Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Casting Resin Market Analysis
German chemical producers is pivoting toward bio-based epoxy precursors to reduce petrochemical exposure. Dow Chemical leverages integrated propylene oxide supply chains to anchor its polyurethane casting resin position. BASF SE competes through specialty amine hardener portfolios that differentiate performance in high-voltage electrical encapsulation. Ashland Global specializes in vinyl ester formulations that dominate corrosion-resistant industrial applications across North American infrastructure projects.
Casting resin denotes a thermosetting polymer system that cures from liquid to solid through cross-linking reactions, typically achieving Shore D hardness above 80 and glass transition temperatures ranging from 60°C to 180°C depending on formulation chemistry. These materials serve primarily as protective encapsulants, structural binders, and dimensional replication media across manufacturing workflows. Epoxy resin commands the largest product type position due to superior adhesion and chemical resistance in electrical and industrial applications, while polyurethane segments capture faster growth in automotive lightweighting where flexibility and impact absorption outweigh rigid encapsulation needs. Silicone formulations occupy premium margin pools in high-temperature art and craft applications where thermal stability beyond 200°C justifies material cost premiums.
EPA regulates volatile organic compound emissions from polyester resin operations under 40 CFR Part 63 Subpart WWWW, while REACH restricts isocyanate concentrations in polyurethane systems sold across Europe. OSHA mandates respiratory protection standards for styrene exposure during open-mold polyester casting in US fabrication facilities. Stakeholders must monitor evolving bio-based content certification schemes as procurement criteria shift from performance-only to lifecycle-assessment-weighted specifications.
Market Dynamics
Wind turbine blade scaling beyond 100 meters is concentrating epoxy resin demand among a handful of specialized formulators capable of meeting aerospace-grade fatigue specifications. REACH volatile organic compound limits and OSHA styrene exposure mandates are simultaneously compressing polyester processing margins while redirecting capital toward polyurethane and silicone alternatives.
Growth Catalysts
- Offshore wind installation acceleration:Turbine OEMs in China are contracting multi-year epoxy resin supply agreements to secure blade material for 15MW+ offshore platforms. NMPA certification requirements for electrical encapsulation in high-voltage converters are expanding qualified supplier lists.
- REACH Substance of Very High Concern listings:ECHA restrictions on bisphenol-A derivatives are forcing formulators to validate bio-based epoxy precursors from lignin and vegetable oil feedstocks. German chemical producers are scaling pilot plants for commercial qualification.
- Corrosion-resistant infrastructure renewal:Vinyl ester formulations are displacing conventional steel in North American wastewater treatment and chemical processing facilities. Ashland Global holds formulation patents for sulfuric acid exposure environments exceeding 90°C.
Market Restraints
- Petrochemical feedstock volatility:Propylene oxide and bisphenol-A pricing swings compress casting resin margins unpredictably. Dow Chemical's integrated PO supply chain provides cost insulation unavailable to non-integrated competitors.
- Isocyanate supply concentration:Polyurethane system production depends on MDI and TDI supply controlled by BASF, Covestro, and Wanhua. Geopolitical friction affecting Chinese chemical exports disrupts just-in-time availability for European automotive encapsulation programs.
- Cure kinetics limitations:Epoxy formulations require elevated temperature post-cure to achieve glass transition temperatures above 150°C. Energy-intensive thermal processing adds facility capex barriers for small-batch custom molders.
Strategic Opportunities
- India PLI scheme for renewable energy manufacturing:Domestic content requirements for wind and solar components are attracting epoxy resin joint ventures. Suzlon and Inox Wind are qualifying local formulators for blade shell infusion processes.
- Silicone-art crossover applications:Thermal stability above 200°C positions addition-cure silicones for jewelry casting and museum-grade replication. Premium pricing tolerates 3-4x material cost versus conventional epoxy systems.
- EU Green Deal bio-content mandates:Public procurement specifications are weighting lifecycle assessment scores above unit price. Formulators with certified renewable carbon content gain preferential access to infrastructure tenders in France and the Netherlands.
Industry Challenges
- Formulation chemist scarcity:Expertise in amine hardener selection for high-voltage electrical encapsulation resides with retiring specialists. BASF and Huntsman are competing for limited talent pools across Europe and North America.
- Multi-standard certification timelines:UL 94 flammability, IEC 61086 electrical insulation, and customer-specific automotive approvals require 18-24 month validation cycles. Concurrent testing across jurisdictions strains R&D bandwidth.
- Legacy open-mold styrene exposure:OSHA 29 CFR 1910.1000 compliance requires ventilation infrastructure upgrades at US boatbuilding and sanitary ware facilities. Smaller fabricators face equipment capex decisions amid uncertain polyester demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casting Resin Market |
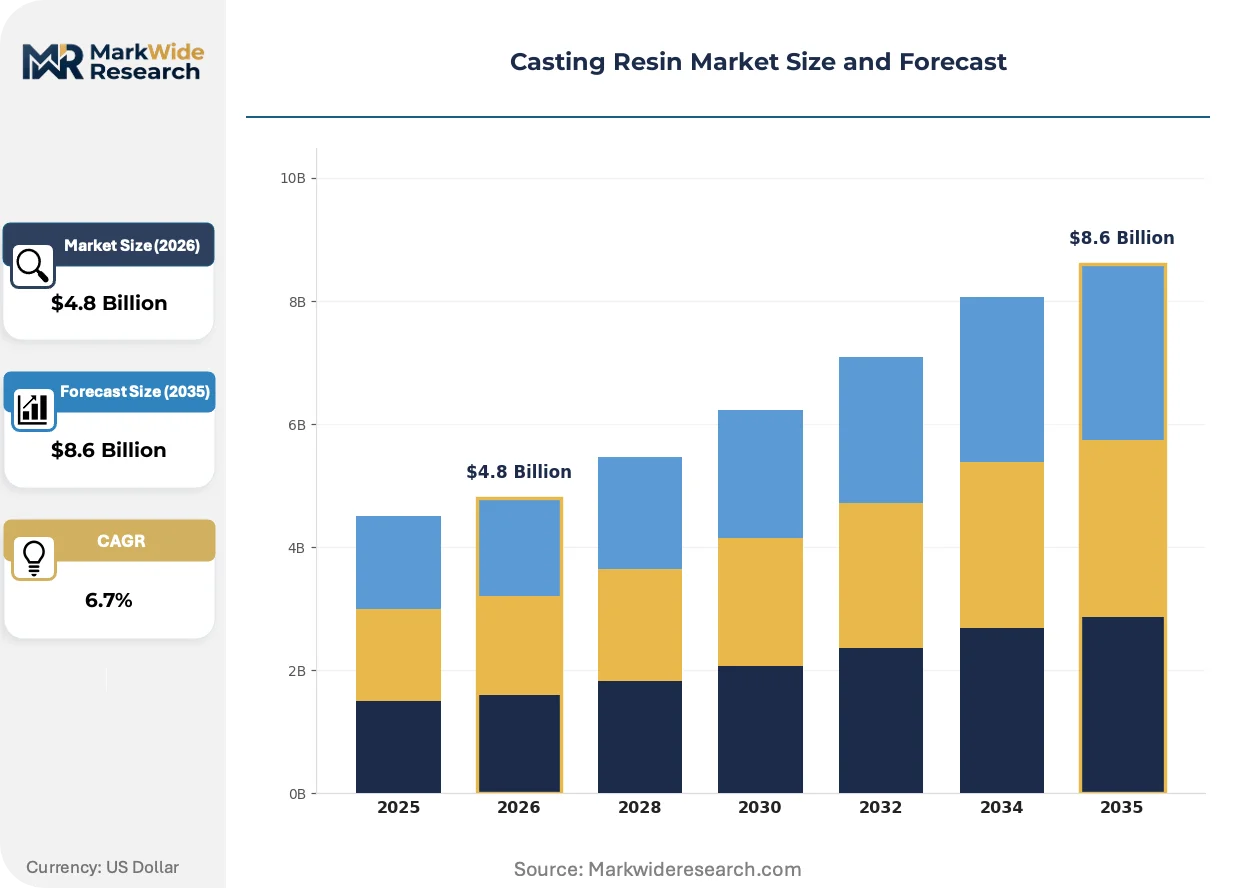
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Polyurethane, Silicone Application: Art & Craft, Industrial, Automotive, Electrical End User: Manufacturers, Artisans, Engineering Firms, Consumers Form: Liquid, Solid, Paste, Pre-made |
| Companies Covered | Ellsworth Adhesives, Dow Chemical, Master Bond, Inc., Ashland Global, BASF SE, Epoxy Technology, Inc., Aremco Products, Inc., Interplastic Corporation, Nylatech, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casting Resin Market Emerging Trajectories
Bio-based feedstock substitution, regulatory-driven chemistry reformulation, and buyer consolidation around qualified suppliers are compressing traditional formulation margins while rewarding specialized performance capabilities.
Recycled carbon fiber reinforced epoxy compounds are absorbing fragmented aerospace and automotive composite waste streams into industrial casting applications. Wind blade manufacturers are piloting these materials for non-structural fairings and root inserts. The technology is absorbing price pressure on virgin carbon fiber while establishing circular material credentials for ESG reporting.
EPA 40 CFR Part 63 Subpart WWWW enforcement is tightening volatile organic compound capture requirements at US polyester fabrication facilities. Open-mold operations face recurring inspection protocols and documented abatement technology deployment. Small-batch custom molders are consolidating or converting to closed-mold resin transfer molding to maintain operating permits.
Direct contracting between wind turbine OEMs and resin formulators is displacing distributor intermediaries in blade supply chains. Vestas and Siemens Gamesa are negotiating multi-year offtake agreements with volume commitments and technical collaboration clauses. China and Denmark host the most advanced procurement restructuring, with formulators establishing embedded technical service teams at blade manufacturing campuses.
Casting Resin Market Segmentation
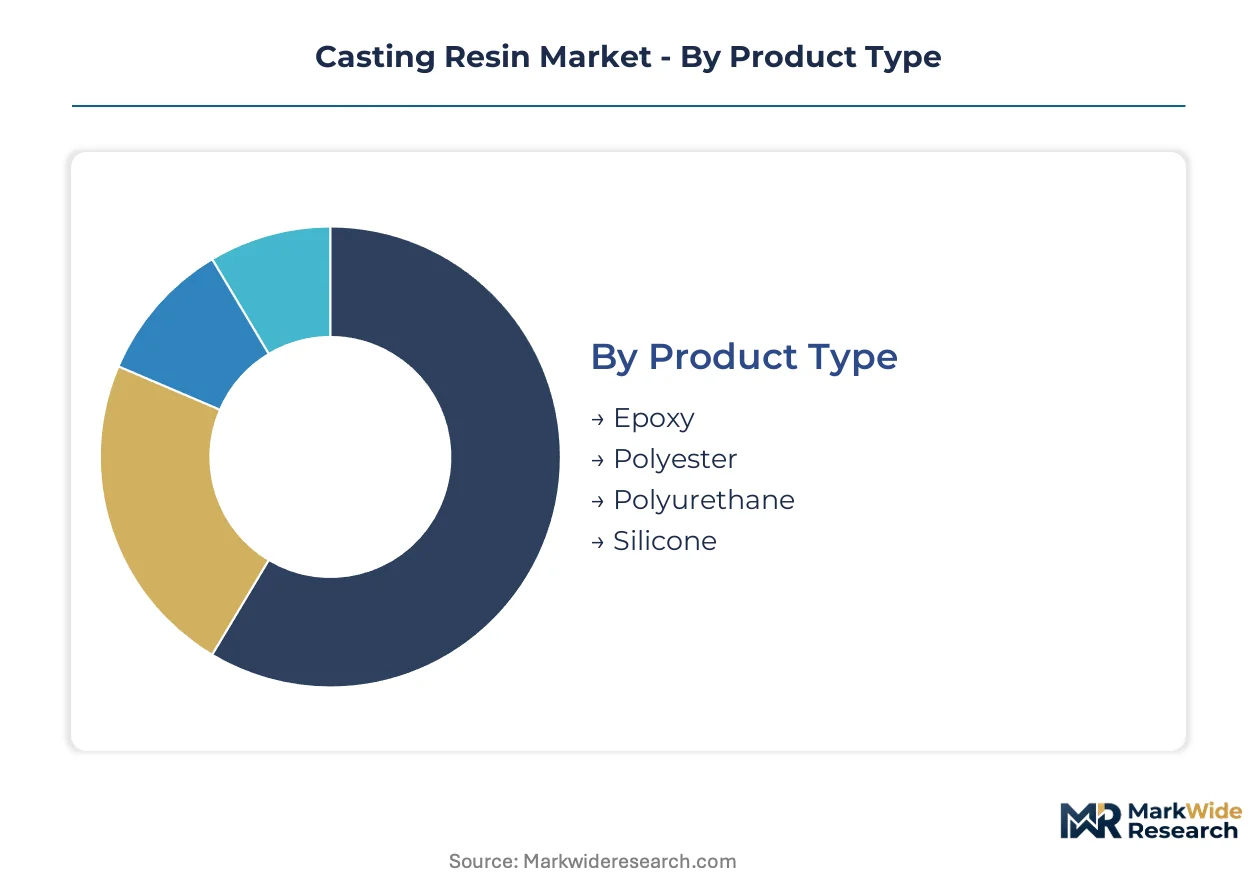
Casting resin procurement splits sharply between standalone material purchases and embedded system integration. Buyers in wind energy and electrical encapsulation specify resin chemistry at the component design stage, while art and craft segments treat resin as a finished goods input.
Product Type:
Epoxy and polyester formulations operate as standalone materials requiring separate hardener systems, whereas polyurethane and silicone often arrive as pre-mixed kits for embedded applications.
- Epoxy:Thermosetting polymer built from bisphenol-A and epichlorohydrin precursors achieving Shore D hardness above 80. Wind turbine blade manufacturers in China are locking multi-year supply agreements as blade lengths exceed 100 meters and fatigue specifications tighten.
- Polyester:Unsaturated resin systems cross-linked with styrene monomer, dominant in open-mold fabrication. REACH volatile organic compound limits and OSHA styrene exposure mandates are compressing processing margins and redirecting capital toward alternative chemistries.
- Polyurethane:Isocyanate-reactive systems valued for flexibility and impact absorption. Automotive lightweighting programs favor these formulations where rigid encapsulation is secondary to energy management.
- Silicone:Addition-cure and condensation-cure elastomers with thermal stability beyond 200°C. Museum-grade replication and jewelry casting tolerate 3-4x material cost premiums for dimensional precision under thermal cycling.
Epoxy leads volumes today; polyurethane is gaining share fastest.
Application:
Application segments stratify by performance certification burden, with electrical and automotive carrying multi-standard validation timelines versus art and craft's aesthetic-driven procurement.
- Art & Craft:Decorative casting, jewelry making, and hobbyist replication where visual clarity and pigment compatibility outweigh mechanical testing. Silicone dominates premium thermal stability applications.
- Industrial:Corrosion-resistant infrastructure including wastewater treatment and chemical processing facilities. Vinyl ester formulations displace steel in sulfuric acid exposure environments exceeding 90°C.
- Automotive:Lightweight structural components and impact-absorbing assemblies. Polyurethane systems capture growth as OEMs prioritize crash energy management over rigid encapsulation.
- Electrical:High-voltage transformer encapsulation and printed circuit board potting. NMPA certification requirements in China are expanding qualified supplier lists for converter applications.
Industrial applications anchor current demand; electrical encapsulation is climbing the fastest.
End User:
End user categories diverge by technical specification authority, with engineering firms and manufacturers writing resin chemistry into design documents while artisans and consumers accept off-the-shelf formulations.
- Manufacturers:Industrial fabricators and OEMs integrating resin into production workflows. Wind turbine blade producers specify aerospace-grade fatigue performance in direct contracting arrangements.
- Artisans:Small-batch creators and studio operations purchasing through distributor channels. Silicone-art crossover applications command premium positioning for thermal stability above 200°C.
- Engineering Firms:Design consultants specifying resin systems for infrastructure and electrical projects. EU Green Deal bio-content mandates are weighting lifecycle assessment scores above unit price in public procurement.
- Consumers:Hobbyist and DIY purchasers through retail and e-commerce channels. Pre-made formulations reduce handling complexity for non-technical users.
Manufacturers dominate volume procurement; engineering firms are expanding specification influence fastest.
Form:
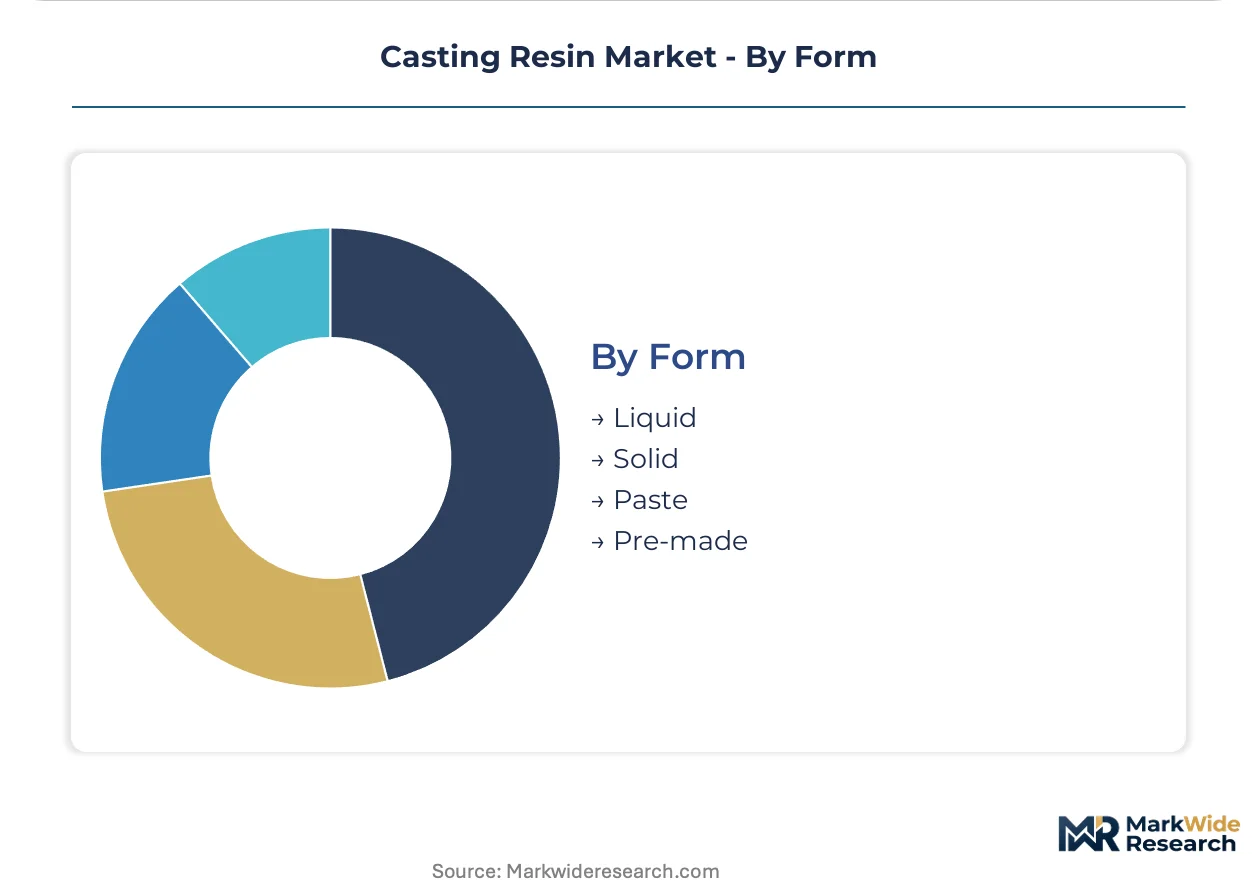
Form factors map to customer technical capability, with liquid systems requiring formulation expertise and pre-made options eliminating mixing variables.
- Liquid:Two-component systems requiring precise resin-to-hardener ratio control. Professional molders favor these for property optimization across cure kinetics and thermal performance.
- Solid:Pre-cured blocks and machinable blanks for post-processing operations. Limited adoption outside specialized tooling and fixture applications.
- Paste:Thixotropic formulations for vertical surface application and gap filling. Repair and maintenance operations value sag resistance.
- Pre-made:Single-component or pre-mixed kits eliminating handling errors. Consumer and artisan segments prefer these for reduced technical barriers.
Liquid formulations command the largest volume position; pre-made kits are expanding most quickly among non-technical users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting casting resin production toward jurisdictions with manageable compliance costs. Chinese formulators capture offshore wind blade contracts as European REACH restrictions elevate domestic production expenses. Indian domestic content requirements are attracting joint ventures that bypass import tariff exposure.
China
Offshore wind installation rates outpace all national markets, concentrating epoxy resin demand among specialized formulators. NMPA certification requirements for high-voltage electrical encapsulation expand qualified supplier lists for converter applications. Yangtze River Delta blade manufacturing clusters host embedded technical service teams from resin suppliers.
Germany
Bio-based epoxy precursor pilot plants scale for commercial qualification under ECHA bisphenol-A derivative restrictions. REACH volatile organic compound limits tighten polyester processing margins while redirecting capital toward polyurethane alternatives. North Rhine-Westphalia chemical producers anchor one tier of European specialty amine hardener supply.
United States
EPA 40 CFR Part 63 Subpart WWWW enforcement tightens volatile organic compound capture at polyester fabrication facilities. OSHA styrene exposure mandates force ventilation infrastructure upgrades at boatbuilding and sanitary ware operations. Texas and Louisiana petrochemical corridors provide integrated propylene oxide supply chain advantages.
India
PLI scheme domestic content requirements for renewable energy manufacturing attract epoxy resin joint ventures. Suzlon and Inox Wind qualify local formulators for blade shell infusion processes. Gujarat and Maharashtra industrial corridors concentrate new production capacity for wind and solar component supply.
Denmark
Vestas negotiates multi-year offtake agreements with volume commitments and technical collaboration clauses. Direct contracting between turbine OEMs and resin formulators displaces distributor intermediaries in blade supply chains. Copenhagen hosts advanced procurement restructuring with embedded technical service partnerships.
Casting Resin Market Vendor Landscape
Chinese producers anchor one tier of wind blade epoxy supply; German and US specialists hold positions in high-voltage electrical encapsulation and corrosion-resistant infrastructure. The vendor base splits between integrated petrochemical conglomerates and focused formulation houses. Three archetypes dominate: backward-integrated resin manufacturers, specialty hardener developers, and application-specific system integrators. Competitive moves center on multi-year offtake contracting and bio-based feedstock certification.
Within the integrated chemical tier, Dow Chemical and BASF SE exemplify scale-driven positioning through captive supply chain control. Ashland Global occupies a specialist position in vinyl ester formulations for industrial corrosion resistance. Master Bond, Inc. and Epoxy Technology, Inc. represent the focused formulation archetype serving electrical encapsulation niches with extended qualification timelines.
| Leading Market Players |
|---|
| Ellsworth Adhesives |
| Dow Chemical |
| Master Bond, Inc. |
| Ashland Global |
| BASF SE |
| Epoxy Technology, Inc. |
| Aremco Products, Inc. |
| Interplastic Corporation |
| Nylatech, Inc. |
| Others |
Supply Flow & Price Mechanics
Formulation chemist scarcity in North Rhine-Westphalia and the Yangtze River Delta drives labor-cost differentials that widen pricing-tier spreads between aerospace-grade epoxy systems and commodity polyester formulations. REACH compliance investments and OSHA ventilation mandates add fixed-cost layers that concentrate premium pricing power among qualified suppliers.
Pricing Analysis
Distributor margins of 15-25 percent in blade supply chains are compressing under direct-to-OEM contracting as Vestas and Siemens Gamesa negotiate volume-commitment discounts. Three-tier pricing structure across aerospace-grade, industrial-standard, and economy polyester levels reflects certification burden and bio-content credentials. Cost compression in open-mold polyester runs through EPA abatement technology requirements. Artisans and hobbyist consumers show highest price sensitivity; wind turbine OEMs prioritize fatigue-performance guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for MDI and TDI in polyurethane systems force automotive encapsulation programs to qualify both BASF and Covestro despite geographic concentration. Feedstock supply anchors in China, Germany, and the US Gulf Coast draws from propylene oxide, bisphenol-A, and lignin-derived precursor streams. Single-source vulnerability in Chinese chemical exports disrupts just-in-time availability for European automotive programs. Distribution runs through embedded technical service teams at blade manufacturing campuses rather than traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through bio-based precursor substitution that commands Green Deal procurement premiums while reducing petrochemical exposure.
For Market Incumbents: To counter ECHA bisphenol-A derivative restrictions, accelerate pilot-plant scale-up for lignin and vegetable-oil epoxy precursors in North Rhine-Westphalia. Anchor position through multi-year offtake agreements with volume commitments and technical collaboration clauses that displace distributor intermediaries. For New Entrants and Emerging Players: Launch via silicone-art crossover distribution partnerships targeting museum-grade replication and jewelry casting segments where thermal stability above 200°C tolerates 3-4x material cost premiums. Penetrate India's PLI scheme domestic content requirements through joint ventures with Suzlon and Inox Wind for blade shell infusion qualification. For Investors and Strategic Acquirers: Chemical conglomerates seeking electrical encapsulation capabilities are the most active acquirer in this space, targeting specialty amine hardener developers with IEC 61086 and UL 94 certification portfolios. Five-to-ten year viability hinges on bio-content certification scalability. Monitor NMPA qualification expansion in China as inflection signal for high-voltage converter supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Dow Chemical's captive supply chain insulates margins from feedstock volatility. |
| Bio-Based Precursor Pilot Scale-Up | German chemical producers validate lignin-derived epoxy under ECHA restrictions. |
| Long-Term Supply Agreement | Vestas negotiates multi-year offtake with volume commitments and embedded technical service. |
| Joint Venture for Domestic Content | India PLI scheme attracts epoxy resin partnerships for wind blade qualification. |
| Green Certification Program | EU Green Deal bio-content mandates weight lifecycle assessment scores above unit price. |
Methodological Framework
Coverage spans China, Germany, the United States, India, and Denmark, with primary inputs from each market combining interviews with formulation chemists, wind turbine OEM procurement leads, electrical encapsulation engineers, and specialty chemical distributors. Secondary validation draws from EPA 40 CFR Part 63 Subpart WWWW enforcement records, ECHA SVHC listings, NMPA certification databases, and SEC 10-K filings from integrated chemical producers. Bottom-up resin volume estimates triangulate against top-down wind blade installation forecasts.
Rate-of-change decomposition separates volume growth from value growth across the analysis window through segmentation by product type, application, end user, and form factor. CAGRs derive from regression analysis of historical procurement patterns and forward projection of regulatory-driven chemistry shifts. Industry-specific inputs include blade length scaling curves for epoxy demand and REACH compliance cost trajectories for polyester margin compression.
Forecast precision tightens around the base case; tail outcomes carry wider variance under isocyanate supply disruption or accelerated bio-based mandate adoption. Deviation in ECHA bisphenol-A derivative restriction timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Polymer Binders Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
PEKK Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Hair Styling Biopolymers Market