
 Poly (1-Decene) Market | 2026-2036
Poly (1-Decene) Market Size, Share, and Industry Trends Forecast 2026-2036
Poly (1-Decene) Market Analytics
Specialized polymerization chemists and alpha-olefin process engineers is reorganizing capacity planning across the poly (1-decene) value chain as plant complexity rises. ExxonMobil Corporation leverages its integrated alpha-olefin pipeline from Baytown to sustain captive feedstock supply for 1-decene-derived polyalphaolefin production. Chevron Phillips Chemical Company LLC anchors its position through Cedar Bayou manufacturing scale and proprietary metallocene catalyst systems. INEOS competes via its European olefins network and specialized polymer grades targeting high-performance lubricant blenders.
Poly (1-decene) constitutes a linear alpha-olefin monomer polymerized primarily via Ziegler-Natta or metallocene catalysis to yield polyalphaolefin synthetic base stocks with viscosity indices exceeding 140 and pour points below negative forty degrees Celsius, serving chiefly as high-performance lubricant base oils in automotive and industrial applications. Polymer Grades dominate current output volumes as lubricant blenders prioritize ISO VG 32-68 viscosity classes for electric vehicle thermal management fluids. Surfactants represent the fastest-expanding product category as formulators develop emulsion polymerization aids for water-based coatings. Processing Aids command concentrated margin pools in specialty adhesive applications requiring precise molecular weight distribution control.
The EPA governs lubricant environmental persistence through Vessel General Permit biodegradability thresholds, while REACH mandates monomer registration and downstream polyalphaolefin substance characterization across European manufacturing and import channels. Japan's METI enforces Chemical Substances Control Law reporting for imported 1-decene derivatives used in domestic lubricant compounding. Stakeholders must track evolving OEM factory-fill specifications for electric drivetrain fluids and assess backward integration into linear alpha-olefin feedstock as cracker product slate flexibility tightens.
Market Dynamics
OEM factory-fill specifications for electric drivetrain fluids are compressing formulation cycles and forcing poly (1-decene) suppliers to synchronize polymer grade development with automotive platform launches. This demand-side coordination requirement is restructuring supplier-automaker technical partnerships.
Growth Catalysts
- REACH substance characterization mandates:European lubricant blenders now require certified high-purity polyalphaolefin base stocks, pulling premium polymer grades through the value chain as registration deadlines approach.
- Electric vehicle thermal management fluids:Automotive OEMs in Germany, Japan, and the United States are specifying low-viscosity synthetic base oils for battery cooling systems, creating dedicated demand pools for specialized 1-decene derivatives.
- Metallocene catalyst diffusion:Proprietary single-site polymerization systems are enabling narrower molecular weight distributions, allowing formulators to meet tightening pour point specifications without additive packages.
Market Restraints
- Linear alpha-olefin feedstock concentration:Cracker product slate flexibility limits 1-decene availability, with supply clustering around Gulf Coast ethylene complexes and Northwestern European steam cracker corridors.
- Group III base oil substitution:Severely hydrocracked mineral oils from Middle Eastern and Asian refineries are capturing mid-tier synthetic lubricant applications at lower price points.
- EPA Vessel General Permit biodegradability thresholds:Environmental persistence testing adds formulation validation costs and extends qualification timelines for marine lubricant applications.
Strategic Opportunities
- Surfactant emulsion polymerization aids:Water-based coating formulators in Japan are adopting poly (1-decene) derivatives as stabilizers, opening non-lubricant demand channels with higher margin profiles.
- India specialty adhesive processing:Precise molecular weight distribution control enables penetration of industrial bonding applications requiring narrow polydispersity indices.
- EU Green Deal sustainable chemistry incentives:Bio-attributed 1-decene feedstock pathways qualify for green procurement preferences in public sector lubricant purchasing frameworks.
Industry Challenges
- Polymerization chemist scarcity:Specialized expertise in Ziegler-Natta and metallocene catalyst optimization is concentrating at integrated oil majors, constraining independent producer technical capabilities.
- Multi-jurisdiction substance registration synchronization:Coordinating REACH dossiers, EPA PMN filings, and METI Chemical Substances Control Law reports stretches regulatory affairs bandwidth across divergent timeline requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly (1-Decene) Market |
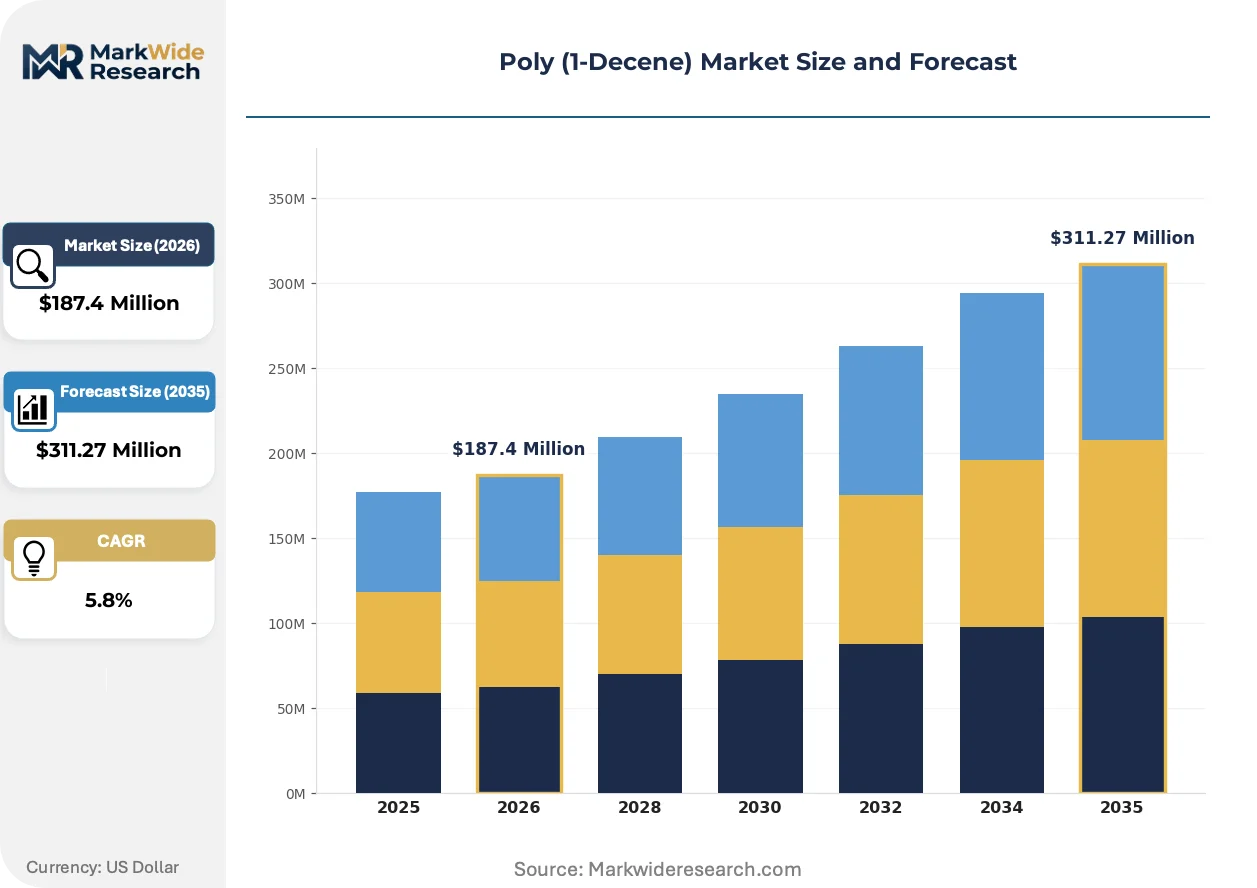
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Grades, Additive Formulations, Surfactants, Processing Aids Application: Coatings, Adhesives, Sealants, Lubricants End User: Automotive Parts, Consumer Goods, Construction Materials, Industrial Equipment Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | ExxonMobil Corporation, SABIC, Chevron Phillips Chemical Company LLC, Shell Chemicals, INEOS, Qatar Chemical Company Ltd, Sasol Limited, Idemitsu Kosan Co., Ltd., PJSC Nizhnekamskneftekhim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly (1-Decene) Market Evolving Landscape
Process intensification and catalyst precision are compressing the gap between monomer production and finished lubricant performance validation. These technical advances are redefining competitive differentiation beyond traditional viscosity grade supply.
Metallocene-based polymerization systems is miniaturizing the molecular weight distribution of high-viscosity polyalphaolefins, enabling formulators to achieve ISO VG 68 specifications with reduced pour point depressant loading. Specialty lubricant blenders in Germany and the United States are adopting these narrow-distribution grades for electric vehicle gearbox applications. The technology is compressing additive package complexity and reducing total formulation cost structures for OEM factory-fill contracts.
REACH monomer registration and downstream polyalphaolefin substance characterization requirements are forcing European suppliers to maintain dedicated analytical capabilities for impurity profiling and ecotoxicological data generation. Lubricant compounders now demand batch-level certification documentation to satisfy downstream user obligations. High-performance automotive segments are responding by consolidating supplier bases around registrants with complete Article 33 compliance portfolios.
Direct technical partnerships between poly (1-decene) producers and automotive OEM fluid engineers are displacing traditional distributor-mediated specification development. Formulators in Japan and Germany are embedding supplier personnel within platform development teams to accelerate viscosity-temperature property matching. This collaboration model is most visible in electric drivetrain thermal management fluid programs where development cycles have compressed below eighteen months.
Poly (1-Decene) Market Segmentation
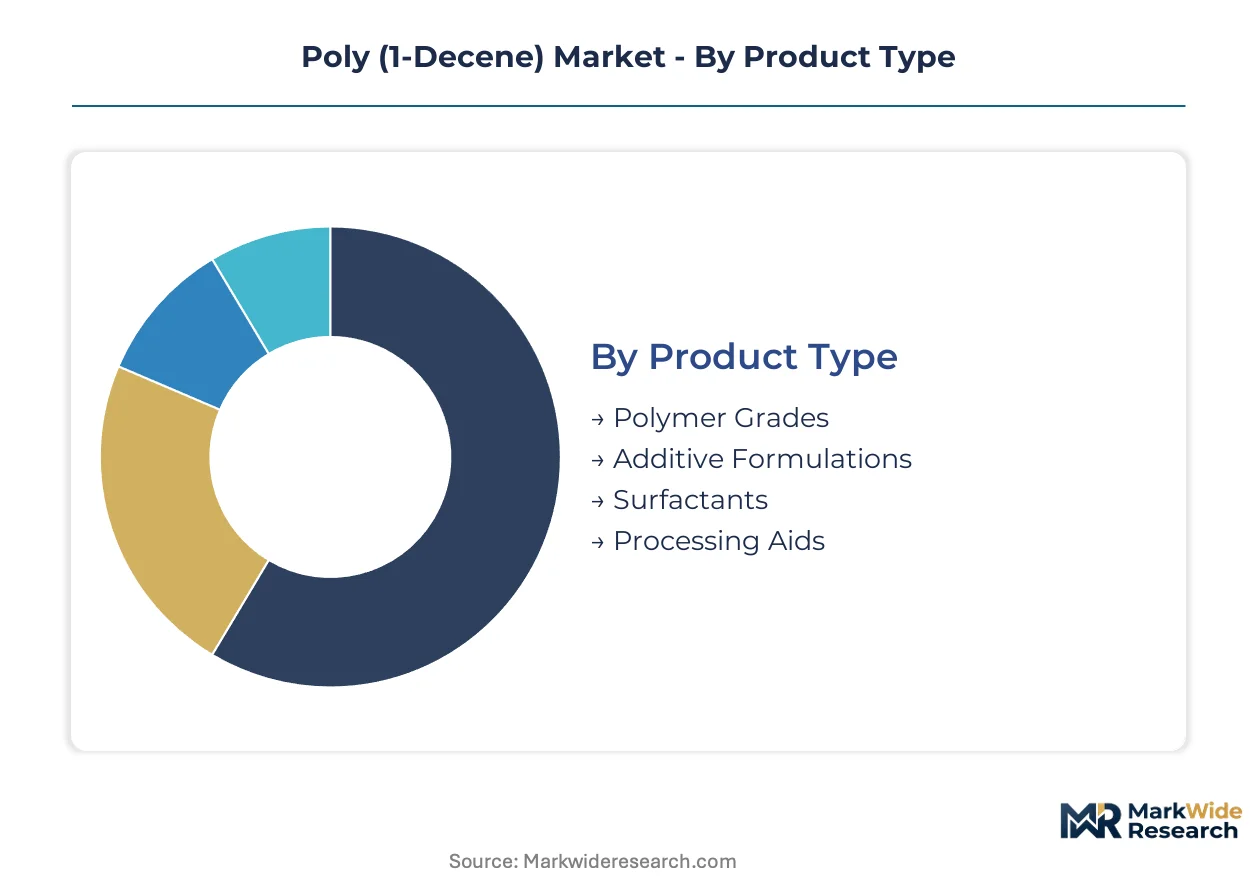
Poly (1-decene) derivatives serve distinct technical specifications across lubricant, coating, and adhesive applications. Regulatory frameworks in Germany, the United States, and Japan create divergent purity requirements that reshape how suppliers configure product portfolios and qualify customers.
Product Type:
REACH substance characterization mandates in Europe and EPA lubricant standards in North America are splitting the market between certified high-purity grades and general-purpose formulations.
- Polymer Grades:Linear polyalphaolefin base stocks with viscosity indices exceeding 140 serve automotive OEM factory-fill specifications for electric drivetrain thermal management. German and Japanese lubricant blenders prioritize ISO VG 32-68 classes for battery cooling systems.
- Surfactants:Poly (1-decene) derivatives function as emulsion polymerization stabilizers for water-based coatings. Japanese formulators are expanding adoption fastest as solvent-based systems face METI reporting obligations under the Chemical Substances Control Law.
- Additive Formulations:Pour point depressant and viscosity modifier packages combine poly (1-decene) oligomers with performance chemicals for industrial lubricant compounding.
- Processing Aids:Narrow molecular weight distribution grades enable precise flow control in specialty adhesive manufacturing requiring tight polydispersity indices.
Polymer Grades handle the majority of throughput; Surfactants are expanding most quickly on share as coating formulators switch to water-based systems.
Application:
Cost tier differentiation separates premium synthetic lubricant specifications from commodity coating and adhesive uses.
- Lubricants:High-viscosity polyalphaolefin base stocks dominate automotive and industrial lubricant demand. OEM factory-fill contracts in Germany, the United States, and Japan specify Group IV synthetic base oils with pour points below negative forty degrees Celsius.
- Adhesives:Industrial bonding applications in India require precise molecular weight distribution control for specialty adhesive processing. Narrow polydispersity indices command concentrated margin pools.
- Coatings:Water-based coating systems incorporate poly (1-decene) surfactants as emulsion stabilizers, particularly in Japanese architectural and automotive refinish markets.
- Sealants:Construction and automotive sealing applications utilize low-viscosity poly (1-decene) oligomers for flexibility and weathering resistance.
Lubricants absorb the largest volume commitments; Adhesives are climbing the fastest on margin contribution.
End User:
Customer type concentration around integrated automotive OEMs and specialized industrial compounders determines technical service intensity and contract structure.
- Automotive Parts:Electric vehicle manufacturers in Germany, Japan, and the United States specify low-viscosity synthetic base oils for battery thermal management and gearbox applications. Direct technical partnerships between poly (1-decene) producers and OEM fluid engineers are displacing traditional distributor relationships.
- Industrial Equipment:Heavy machinery and power generation lubricant requirements favor high-viscosity polyalphaolefin grades with extended drain intervals.
- Construction Materials:Sealant and adhesive applications for building envelope systems utilize mid-viscosity poly (1-decene) derivatives.
- Consumer Goods:Personal care and household product formulations represent niche demand for ultra-low viscosity oligomers.
Automotive Parts commands the deepest technical engagement; Industrial Equipment offers the broadest contract base.
Distribution Channel:
Supply concentration around Gulf Coast ethylene complexes and Northwestern European steam cracker corridors shapes logistics economics and channel selection.
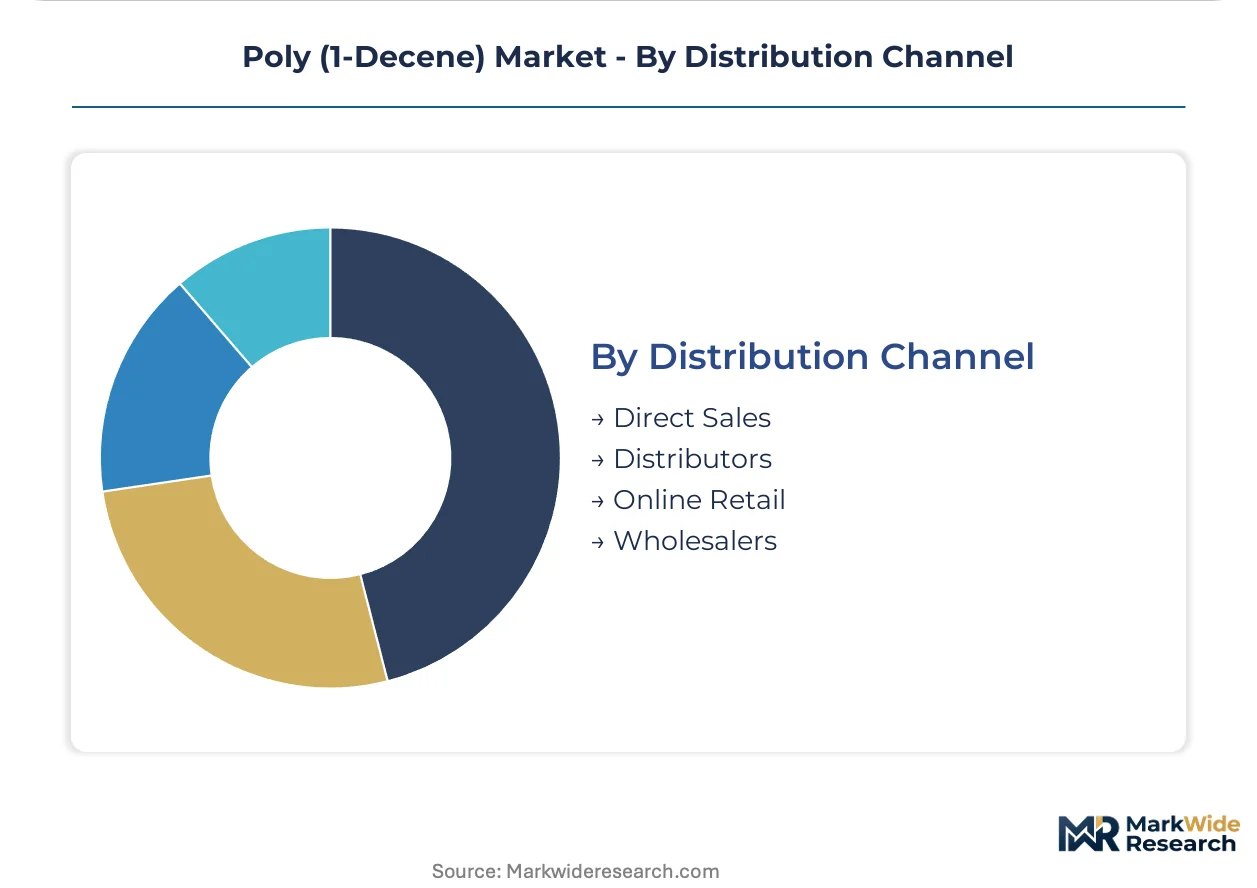
- Direct Sales:Captive supply agreements link integrated alpha-olefin producers with major lubricant compounders. ExxonMobil's Baytown-to-blender pipeline exemplifies this channel for high-volume automotive OEM contracts.
- Distributors:Specialized chemical distributors serve mid-tier lubricant blenders and coating formulators requiring smaller batch sizes and technical support.
- Wholesalers:Bulk material handlers move standard polymer grades to industrial compounders with established formulation capabilities.
- Online Retail:Digital platforms facilitate spot purchases of specialty grades for research and development or small-scale adhesive manufacturing.
Direct Sales carries the highest volume throughput; Distributors are gaining share fastest among specialty grade customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. Germany and Japan prioritize high-purity polymer grades for automotive OEM specifications, while India and China absorb broader grades for industrial compounding. The United States splits demand between premium synthetic lubricant base stocks and specialized surfactant derivatives.
Germany
Automotive OEM factory-fill contracts for electric drivetrain fluids drive demand for ISO VG 32-68 polymer grades. REACH substance characterization mandates force lubricant blenders to source certified high-purity polyalphaolefin base stocks. The Ruhr industrial corridor and Bavarian chemical clusters concentrate formulation expertise among specialty lubricant compounders.
United States
EPA Vessel General Permit biodegradability thresholds reshape marine lubricant formulation requirements, pulling premium grades through coastal blending operations. The Gulf Coast ethylene complex around Baytown anchors captive feedstock integration for integrated producers. Chevron Phillips Chemical's Cedar Bayou facility exemplifies manufacturing scale tied to regional cracker output.
Japan
METI Chemical Substances Control Law reporting obligations accelerate solvent-to-water coating transitions, expanding surfactant demand for emulsion polymerization stabilizers. Electric vehicle thermal management fluid specifications from domestic OEMs concentrate technical partnerships in the Kanto and Kansai regions. Idemitsu Kosan anchors domestic base stock supply for battery cooling system formulations.
India
Specialty adhesive processing requirements in industrial bonding applications create concentrated margin pools for narrow polydispersity grades. The PLI scheme for chemicals and petrochemicals incentivizes domestic alpha-olefin derivative manufacturing. Gujarat and Maharashtra host emerging formulation capabilities serving construction sealant and automotive component sectors.
China
Dual carbon goals and GB standards for lubricant biodegradability tighten environmental specifications for imported polyalphaolefin base stocks. The Yangtze River Delta and Pearl River Delta concentrate demand from electric vehicle battery thermal management system manufacturers. SABIC and regional traders supply polymer grades amid growing domestic alpha-olefin capacity investments.
Poly (1-Decene) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the poly (1-decene) value chain. Integrated oil majors control captive linear alpha-olefin feedstock and proprietary metallocene catalyst systems. National oil company affiliates and regional chemical conglomerates occupy mid-tier positions. Competitive dynamics center on backward integration into cracker product slates and direct technical partnerships with automotive OEM fluid engineers.
Among integrated leaders, ExxonMobil Corporation anchors its position through Baytown-based alpha-olefin pipeline integration. Chevron Phillips Chemical Company LLC exemplifies Gulf Coast manufacturing scale tied to Cedar Bayou operations. INEOS occupies a position within the European tier, leveraging Northwestern European olefins network access. These three represent distinct archetypes: captive feedstock integration, manufacturing scale concentration, and regional network optimization.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| SABIC |
| Chevron Phillips Chemical Company LLC |
| Shell Chemicals |
| INEOS |
| Qatar Chemical Company Ltd |
| Sasol Limited |
| Idemitsu Kosan Co., Ltd. |
| PJSC Nizhnekamskneftekhim |
| Others |
Value Network & Pricing Analysis
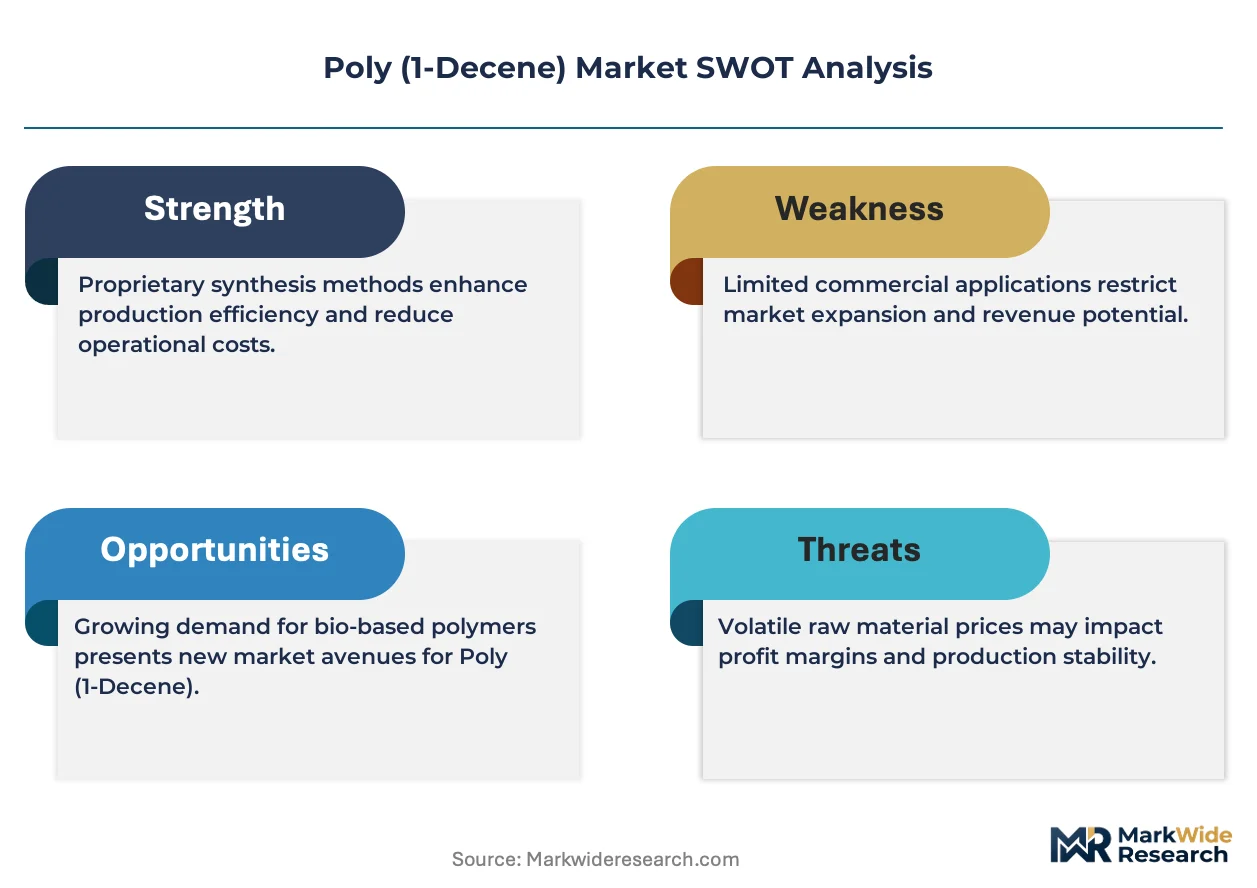
Group III base oil substitution is compressing mid-tier synthetic lubricant pricing while simultaneously redrawing supply geography toward Middle Eastern and Asian refineries with hydrocracking capacity. This displacement dynamic tightens margin pools for general-purpose polyalphaolefin grades and concentrates premium pricing power among REACH-certified registrants with captive 1-decene feedstock.
Pricing Analysis
Long-term offtake contracts dominate high-volume automotive OEM supply, with spot transactions limited to specialty surfactant grades and small-batch adhesive applications. Price differentiation hinges on REACH Article 33 compliance certification and volume scale, with certified polymer grades commanding substantial premiums over uncertified alternatives. Cost compression in standard viscosity classes intensifies as Group III mineral oils capture mid-tier synthetic applications. Tier 1 lubricant compounders exhibit lowest price sensitivity due to factory-fill specification lock-ins, while coating formulators and industrial adhesive manufacturers demonstrate highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Strategic stockpiling of linear alpha-olefin feedstock characterizes integrated producer behavior, whereas independent blenders maintain just-in-time inventory positions exposed to cracker output volatility. Supply concentrates in the United States, Germany, and Japan, with 1-decene availability tethered to Gulf Coast and Northwestern European ethylene complex product slates. Raw material dependencies encompass naphtha feedstock, metallocene catalyst systems, and specialized hydrogenation reagents. Single-source vulnerability from concentrated cracker corridors poses structural supply risk. Distribution runs through captive pipeline networks for integrated majors and specialized chemical distributors for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poly (1-decene) markets are approaching a platform-economics inflection as direct technical partnerships between producers and automotive OEM fluid engineers displace traditional distributor-mediated specification development, creating interoperability dependencies around viscosity-temperature property databases and accelerated formulation cycles.
For Market Incumbents: Compound technical partnership density with automotive OEM fluid engineering teams to embed proprietary polymer grades within electric drivetrain platform specifications before competitor qualification windows close. Prioritize backward integration into linear alpha-olefin feedstock as cracker product slate flexibility tightens, securing captive supply against Group III substitution pressure in mid-tier lubricant segments. For New Entrants and Emerging Players: Specialty adhesive processing technical service gaps in India offer penetrable white-space where incumbent majors under-invest in narrow polydispersity application support. Target surfactant emulsion stabilizer demand from Japanese water-based coating formulators facing METI Chemical Substances Control Law compliance deadlines. Pursue toll-manufacturing partnerships with European registrants lacking REACH-compliant production assets as primary go-to-market pathway. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional chemical distributors possessing REACH registration dossiers but lacking captive alpha-olefin feedstock integration. Five-to-ten year viability hinges on successful backward integration execution or strategic acquisition by integrated majors seeking European regulatory compliance portfolios. Monitor electric vehicle thermal management fluid specification finalization timelines as inflection indicator for premium polymer grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linear Alpha-Olefin Feedstock | Captive 1-decene supply from Baytown and Cedar Bayou crackers insulates margin pools from cracker output volatility. |
| REACH Article 33 Compliance Certification | Complete dossier portfolios enable premium pricing from German and Japanese lubricant blenders facing registration deadlines. |
| Direct OEM Technical Partnership Formation | Embedded personnel with automotive fluid engineers compress formulation cycles below eighteen months for electric drivetrain programs. |
| Metallocene Catalyst System Proliferation | Proprietary single-site polymerization enables narrower molecular weight distributions without pour point depressant additives. |
| Surfactant Grade Capacity Expansion | Japanese water-based coating transitions under METI reporting obligations create dedicated demand pools with higher margin profiles. |
Research Methodology
Initial hypotheses were tested against primary input from polymerization chemists, specialty lubricant formulators, alpha-olefin procurement leads, and automotive OEM fluid engineers, then refined through secondary validation. Primary fieldwork encompassed technical directors at integrated oil majors, regulatory affairs specialists navigating REACH dossier preparation, and distribution channel partners serving mid-tier coating formulators. Secondary sources included customs and trade flow databases, SEC 10-K filings from disclosed alpha-olefin producers, American Chemistry Council sector reports, and ECHA registration dossier disclosures. Bottom-up volume modeling triangulated against top-down value estimates derived from disclosed capacity and pricing intelligence.
Variance decomposition across the projection horizon isolates demand drivers by segmentation dimension: polymer grade viscosity class, surfactant versus lubricant application, automotive OEM versus industrial end-use, and regional regulatory cluster. CAGRs were computed from modeled annual volume trajectories incorporating electric vehicle penetration assumptions and thermal management fluid specification adoption curves. Industry-specific forecast inputs encompassed cracker product slate flexibility constraints, metallocene catalyst diffusion rates, and REACH registration timeline enforcement patterns.
Underlying assumptions cover electric vehicle thermal management fluid specification adoption, cracker output slate stability, and REACH enforcement continuity, with deviation risk concentrated in Group III base oil substitution acceleration and alpha-olefin feedstock supply disruptions. Forecasts reflect these documented assumptions without scenario probability weighting. Revision becomes warranted when electric drivetrain fluid specification finalization crosses commercialization thresholds or when cracker product slate reconfigurations materially alter 1-decene availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
GCC Vinyl Flooring Market