
 N-Vinylformamide Market | 2026-2036
N-Vinylformamide Market Size, Share, and Industry Trends Forecast 2026-2036
N-Vinylformamide Market Outlook
ISO 9001 certification is unwinding as the baseline qualification for N-vinylformamide suppliers seeking entry into pharmaceutical and electronics-grade supply chains. BASF SE leverages its Ludwigshafen integrated site to sustain backward integration into acetylene feedstocks, insulating margin exposure. Eastman Chemical Company anchors North American supply through Kingsport production, while Mitsubishi Chemical Corporation dominates Asian technical-grade distribution.
N-vinylformamide is a water-soluble N-vinyl monomer with a molecular formula C₃H₅NO, manufactured via transamidation of formamide with vinyl acetate or direct vinylation pathways, serving primarily as a reactive precursor for polyvinylamine and polyvinylpyrrolidone copolymers used in water treatment, papermaking, and biomedical coatings. Copolymer formulations command premium positioning in adhesives and coatings where amine functionality drives substrate bonding performance, while homopolymer grades occupy mature volume pools in textile sizing applications. Liquid form concentrates procurement attention from large-scale polymerization facilities seeking direct feedstock integration, whereas powder and granule formats compete in regional distribution markets with shorter supply chains.
REACH registration requirements in Europe gate market access through substance evaluation and authorization protocols, while EPA TSCA Section 5 premanufacture notifications govern new chemical introductions in the United States. Japan's METI chemical substance classification under CSCL mandates annual reporting for imported monomer volumes above specified thresholds. Stakeholders must monitor evolving polymerization catalyst technologies and regional feedstock cost spreads to optimize capacity placement decisions.
Market Dynamics
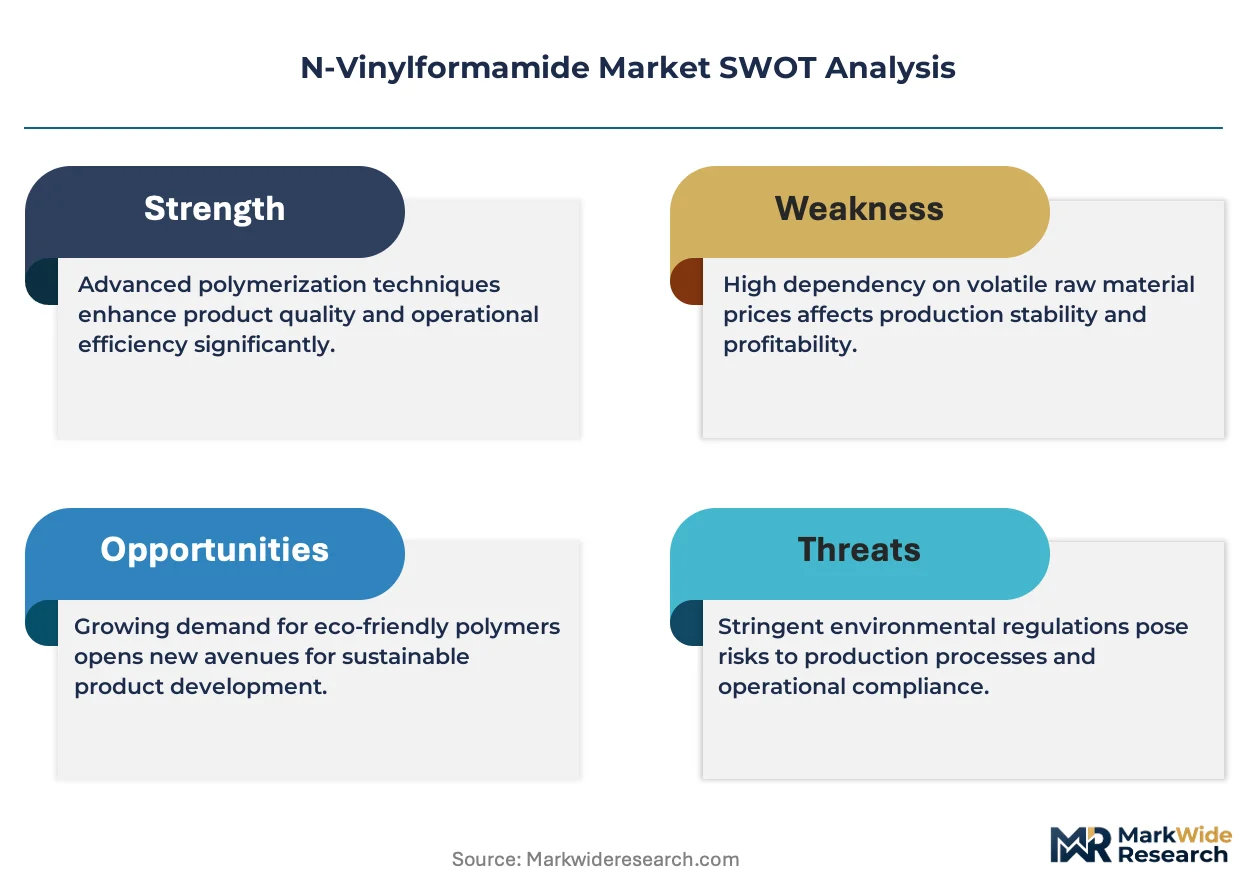
Acetylene feedstock volatility and REACH authorization tightening are compressing margin structures for non-integrated N-vinylformamide producers while favoring backward-integrated chemical majors with captive carbide supply.
Growth Catalysts
- Municipal water infrastructure:Upgrades to tertiary treatment systems in Germany and Japan are accelerating polyvinylamine consumption for coagulant applications.
- REACH polymer exemption pathways:Reduced registration burdens for polymer intermediates are streamlining market entry for specialty copolymer grades in European electronics coatings.
- Transamidation catalyst advances:Heterogeneous catalysis improvements are raising vinyl acetate conversion efficiency and lowering formamide recycle ratios.
Market Restraints
- Acetylene cost volatility:Calcium carbide production energy intensity exposes margin pressure when natural gas prices spike in key manufacturing clusters.
- Supply concentration risk:Ludwigshafen and Kingsport production sites account for disproportionate Western hemisphere technical-grade capacity.
- Substitution by dimethylaminoethyl methacrylate:Cationic acrylate alternatives are capturing share in lower-specification papermaking retention aid applications.
Strategic Opportunities
- Underpenetrated biomedical coatings:Hemocompatible surface modification protocols for cardiovascular devices represent nascent polyvinylamine demand in Swiss and German medical device manufacturing.
- Japan CSCL reporting thresholds:Relaxed import volume triggers for pre-registered substances are lowering compliance friction for regional distributors serving Osaka polymerization facilities.
- Photoinitiated polymerization convergence:UV-curable amine-functional systems are opening formulation space in radiation-cured adhesives and optical fiber coatings.
Industry Challenges
- ISO 9001-to-pharma-grade certification gap:ICH Q7 compliance timelines for active pharmaceutical ingredient excipient qualification extend 18-24 months beyond baseline quality management certification.
- Legacy batch reactor integration:Continuous flow vinylation technology retrofits face mechanical compatibility constraints with existing stainless-steel vessel infrastructure at mid-scale polymerization facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Vinylformamide Market |
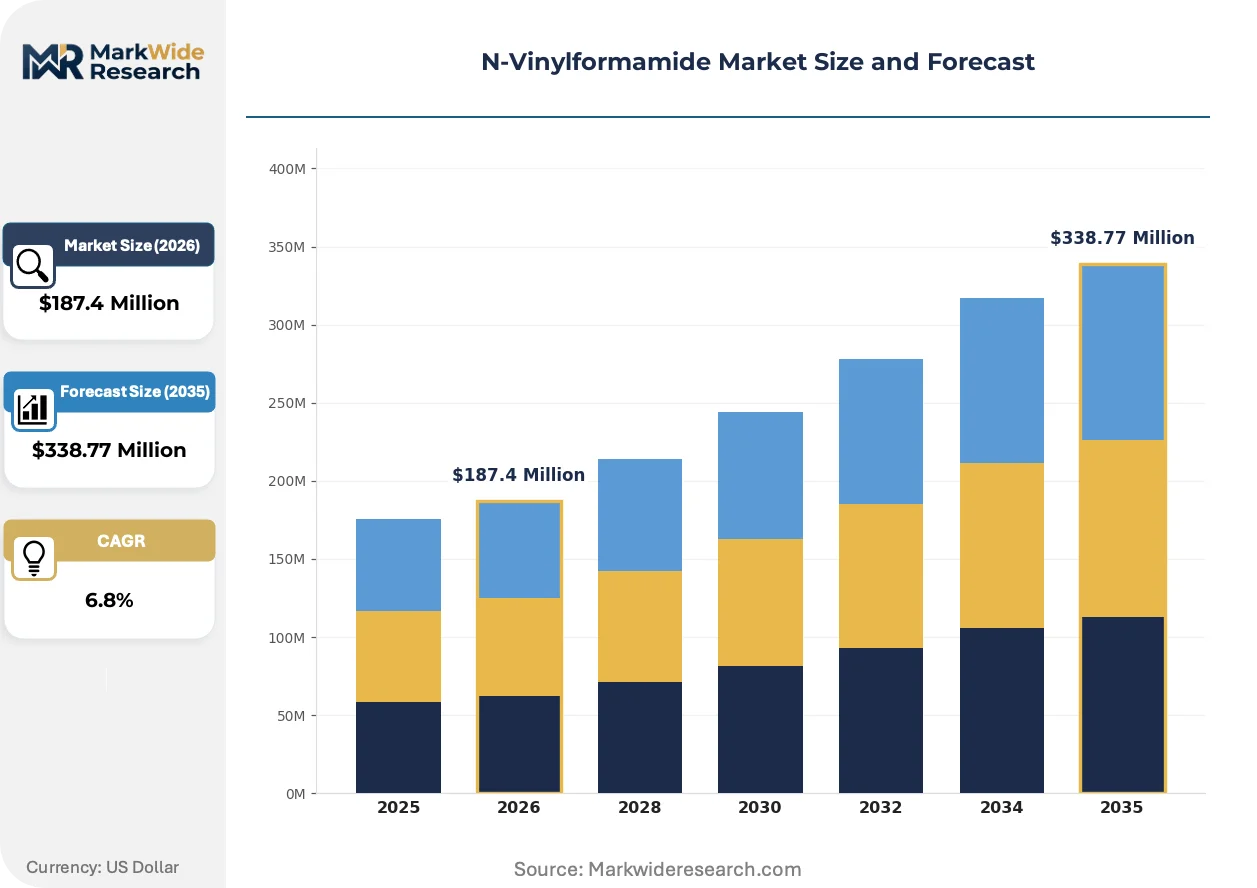
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Blends, Additives Application: Textiles, Adhesives, Coatings, Films End User: Manufacturing, Construction, Automotive, Healthcare Form: Liquid, Powder, Granules, Emulsion |
| Companies Covered | BASF SE, Eastman Chemical Company, Dia-Nitrix Co. Ltd, Ashland Global Holdings Inc., Merck KGaA, Avantor, Inc., Solenis LLC, Mitsubishi Chemical Corporation, Angene International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Vinylformamide Market Strategic Shifts
Process intensification and regulatory data requirements are restructuring how N-vinylformamide manufacturers validate purity grades and secure downstream qualification in pharmaceutical and electronics supply chains.
Membrane-based formamide recovery systems are decomposing traditional energy-intensive distillation sequences in transamidation units. Japanese specialty chemical producers are piloting these installations at 10,000-tonne annual capacities. This technology is decomposing the historical feedstock cost advantage held by carbide-integrated acetylene producers.
ECHA's revised REACH evaluation criteria for vinyl monomers are extending dossier update cycles and demanding additional reproductive toxicity data. Specialty polymer houses serving medical device coatings face 12-18 month authorization delays. German and Swiss electronics-grade buyers are consolidating supplier lists to pre-authorized substance pools.
Specification-driven procurement contracts are replacing spot-market purchasing for pharmaceutical-grade monomer. Large polymerization facilities in Ludwigshafen and Osaka are locking 24-36 month supply agreements with embedded purity certification clauses. This pattern is most visible in hemocompatible coating precursor procurement for cardiovascular device original equipment manufacturers.
N-Vinylformamide Market Segmentation
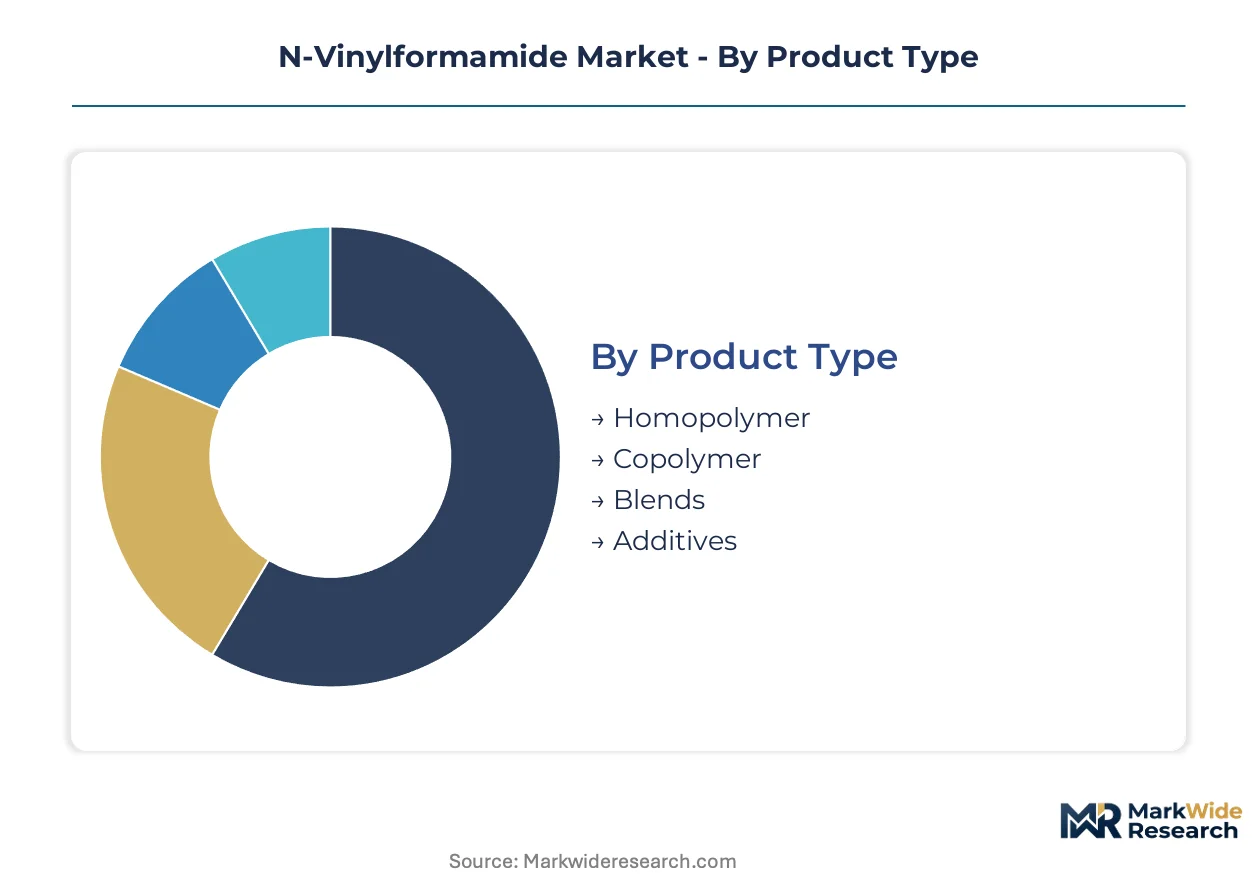
N-Vinylformamide procurement patterns diverge sharply across product grades and application specifications. Manufacturers align production configurations to distinct purity tiers and regional regulatory thresholds rather than pursuing universal formats.
Product Type:
Domestic consumption dominates homopolymer and copolymer grades in Germany and Japan, while specialty blends and additives flow disproportionately through export channels serving medical device manufacturers in Switzerland and electronics coating houses in South Korea.
- Homopolymer:Linear polyvinylamine chains derived from single-monomer polymerization serve textile sizing and paper retention aid applications. Demand clusters in Osaka and Ludwigshafen polymerization facilities where direct feedstock integration lowers unit costs.
- Copolymer:Amine-functional vinylamine-vinylpyrrolidone architectures deliver substrate adhesion for cardiovascular device coatings. Swiss and German medical device original equipment manufacturers lock multi-year supply agreements with embedded ICH Q7 purity clauses.
- Blends:Pre-formulated resin systems combine N-vinylformamide derivatives with crosslinking agents for radiation-cured adhesive lines.
- Additives:Reactive diluents and chain-transfer agents modify viscosity profiles in UV-curable optical fiber coatings.
Homopolymer commands the established base. The steepest expansion runs through copolymer grades serving hemocompatible surface modification protocols.
Application:
Cost stratification separates commodity papermaking retention aids from premium biomedical coatings, with adhesives and films occupying intermediate value tiers tied to performance specifications.
- Textiles:Warp sizing formulations exploit polyvinylamine film-forming characteristics to reduce yarn breakage during high-speed weaving. Japanese synthetic fiber producers in Osaka prefecture maintain captive consumption of technical-grade liquid monomer.
- Adhesives:UV-curable amine-functional systems penetrate radiation-cured packaging and electronics assembly lines. German automotive suppliers specify low-yellowing grades for interior laminate bonding.
- Coatings:Hemocompatible surface modifications for stents and catheters require sub-100 ppm impurity profiles validated under ISO 10993 biocompatibility protocols.
- Films:Water-soluble packaging layers for agrochemical unit-dose applications leverage rapid dissolution kinetics of high-molecular-weight polyvinylamine.
Textiles anchor volume consumption. Coatings deliver the highest value-per-kilogram realization across the application matrix.
End User:
Customer scale determines procurement modality, with large polymerization facilities favoring direct liquid tanker delivery while fragmented construction and healthcare buyers absorb distribution markups on packaged grades.
- Manufacturing:Specialty chemical and polymer producers in Germany, Japan, and the United States integrate N-vinylformamide into captive polyvinylamine production for downstream formulation.
- Construction:Cement admixture and waterproofing membrane manufacturers specify standard-grade powder formats for regional distribution through shorter supply chains.
- Automotive:Interior laminate and structural adhesive specifications drive demand for low-VOC, heat-resistant copolymer grades validated under OEM material approval processes.
- Healthcare:Cardiovascular and orthopedic device manufacturers impose pharmaceutical-grade purity certification extending 18-24 months beyond baseline ISO 9001 qualification timelines.
Manufacturing absorbs the dominant share of technical-grade volume. Healthcare requirements are expanding most quickly as hemocompatible coating protocols proliferate across German and Swiss device production.
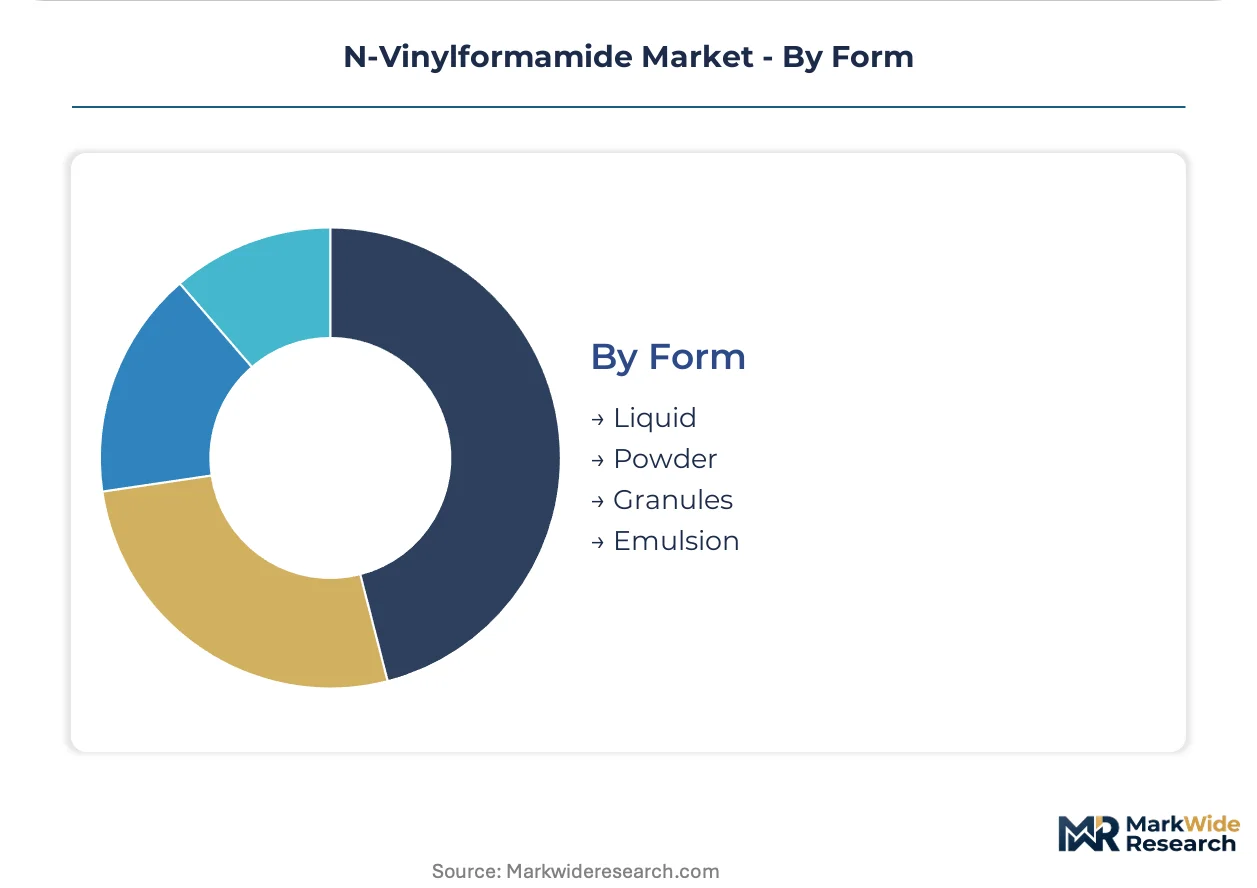
Form:
Volume concentration favors liquid formats for integrated polymerization facilities, while powder and granule packaging enables regional distribution to fragmented end-users lacking bulk handling infrastructure.
- Liquid:Direct tanker delivery to large-scale polymerization plants eliminates packaging and handling costs. BASF SE's Ludwigshafen complex and Mitsubishi Chemical Corporation's Osaka facilities consume liquid monomer in continuous transamidation trains.
- Powder:Spray-dried grades serve construction and textile compounders requiring precise dry-blending with additive packages.
- Granules:Low-dust handling characteristics suit automated dosing systems in European papermaking chemical kitchens.
- Emulsion:Pre-dispersed aqueous systems reduce formulation complexity for water-based adhesive and coating lines.
Liquid form captures the production-weighted majority. Emulsion formats are gaining share fastest among mid-scale compounders seeking simplified handling protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large polymerization facilities in Germany, Japan, and the United States absorb the majority of technical-grade N-vinylformamide volume, with specialty chemical clusters driving differentiated demand for pharmaceutical and electronics-grade specifications.
Germany
Municipal water infrastructure upgrades in the Rhine-Ruhr corridor accelerate polyvinylamine consumption for tertiary treatment coagulants. ECHA's revised REACH evaluation criteria for vinyl monomers extend dossier update cycles and demand additional reproductive toxicity data. The Ludwigshafen chemical complex sustains backward-integrated acetylene feedstock production, insulating margin exposure from calcium carbide price volatility.
Japan
Synthetic fiber producers in Osaka prefecture maintain captive consumption of technical-grade liquid monomer for warp sizing formulations. METI's Chemical Substances Control Law mandates annual reporting for imported monomer volumes above specified thresholds, though relaxed pre-registration triggers lower compliance friction for regional distributors. Mitsubishi Chemical Corporation's Osaka facilities anchor Asian technical-grade distribution through continuous transamidation trains.
United States
Cardiovascular and orthopedic device manufacturers impose pharmaceutical-grade purity certification extending 18-24 months beyond baseline ISO 9001 qualification timelines. EPA TSCA Section 5 premanufacture notifications govern new chemical introductions, creating procedural gates for specialty copolymer grades. The Kingsport production site in Tennessee anchors North American supply for large-scale polymerization facilities.
Switzerland
Swiss medical device original equipment manufacturers lock multi-year supply agreements with embedded ICH Q7 purity clauses for hemocompatible coating precursors. Swissmedic maintains stringent biocompatibility validation protocols under ISO 10993 for sub-100 ppm impurity profiles. Basel and Zurich clusters concentrate cardiovascular device manufacturing where polyvinylamine surface modification protocols proliferate.
South Korea
Electronics coating houses in the Seoul Capital Area drive demand for low-yellowing copolymer grades in optical fiber and display applications. The Ministry of Environment enforces K-REACH registration requirements paralleling European substance evaluation protocols. Gyeonggi-do province hosts specialty polymer facilities serving radiation-cured adhesive lines for automotive electronics assembly.
N-Vinylformamide Market Competitive Environment
Player mix skews toward integrated chemical majors with captive acetylene supply and mid-scale specialty distributors serving regional polymerization clusters. The vendor base concentrates around three strategic tiers: backward-integrated producers controlling carbide-to-monomer value chains, specialty chemical houses with pharmaceutical-grade certification capabilities, and regional distributors managing shorter supply chains for packaged powder and granule formats. Dominant competitive moves include capacity consolidation at Ludwigshafen-scale integrated sites and technology licensing partnerships for heterogeneous transamidation catalyst advances.
Among German-based integrated producers, BASF SE exemplifies the captive-feedstock archetype through its Ludwigshafen complex operations. Eastman Chemical Company and Mitsubishi Chemical Corporation represent the regional-anchor tier, with the former occupying North American supply positioning and the latter anchoring Asian technical-grade distribution. These three entities collectively illustrate how geographic concentration of polymerization infrastructure shapes supplier competitive positioning without requiring speculative claims about specific strategic actions or financial performance.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Dia-Nitrix Co. Ltd |
| Ashland Global Holdings Inc. |
| Merck KGaA |
| Avantor, Inc. |
| Solenis LLC |
| Mitsubishi Chemical Corporation |
| Angene International Limited |
| Others |
Value Chain & Pricing Dynamics
Heterogeneous catalysis adoption in transamidation units is displacing legacy carbide-integrated acetylene routes, redrawing the cost map from Ludwigshafen-scale sites toward Japanese specialty producers while compressing contract pricing power for non-integrated suppliers.
Pricing Analysis
Cost-plus contracts indexed to calcium carbide and natural gas benchmarks dominate technical-grade procurement between integrated producers and large polymerization facilities. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and technical-grade levels reflects purity certification burden and ICH Q7 compliance timelines. Pricing pressure stems from dimethylaminoethyl methacrylate substitution in papermaking retention aids. Construction sector buyers exhibit highest price sensitivity; cardiovascular device manufacturers accept premium positioning for sub-100 ppm impurity profiles.
Supply Chain Analysis
Antwerp-Rotterdam port congestion and Rhine water level volatility expose just-in-time feedstock deliveries to German polymerization complexes. Supply concentrates in Germany, Japan, and the United States where captive carbide-to-monomer integration anchors capacity. Raw material dependencies center on calcium carbide, vinyl acetate, and formamide feedstocks. Single-source vulnerability runs through Ludwigshafen and Kingsport technical-grade production sites. Distribution runs through direct tanker delivery for integrated facilities and regional packaged-goods distributors for fragmented construction and textile compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dimethylaminoethyl methacrylate incursion into lower-specification papermaking applications forces incumbents to defend premium positioning through certification moats and captive supply economics.
For Market Incumbents: Consolidate backward integration into acetylene feedstocks to insulate margin exposure from calcium carbide price spikes. Lock 24-36 month supply agreements with embedded purity certification clauses for pharmaceutical-grade buyers. Defend against dimethylaminoethyl methacrylate substitution by accelerating ICH Q7 qualification timelines for cardiovascular device coating precursors. For New Entrants and Emerging Players: Differentiate on hemocompatible biomedical coating grades where Swiss and German medical device manufacturers impose 18-24 month certification barriers that deter commodity competition. Target underpenetrated radiation-cured adhesive formulations in South Korean electronics coating houses. Enter through technology licensing partnerships for membrane-based formamide recovery systems rather than greenfield carbide integration. For Investors and Strategic Acquirers: ECHA's revised REACH evaluation criteria for vinyl monomers reshapes the acquisition landscape toward pre-authorized substance pools with completed reproductive toxicity dossiers. Long-term viability hinges on positioning for polymer exemption pathway benefits and continuous flow vinylation technology readiness. Watch for heterogeneous catalysis patent filings as the inflection signal for cost-competitive transamidation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetylene Feedstocks | BASF SE's Ludwigshafen complex demonstrates margin insulation from carbide price volatility through captive supply. |
| ICH Q7 Certification Investment | Swiss cardiovascular device OEMs lock multi-year agreements only with suppliers completing 18-24 month pharmaceutical-grade qualification. |
| Membrane-Based Formamide Recovery Deployment | Japanese producers piloting 10,000-tonne installations decompose traditional distillation energy cost structures. |
| Long-Term Supply Agreement Structuring | Osaka and Ludwigshafen polymerization facilities embed purity certification clauses in 24-36 month contracts. |
| Joint Venture for Regional Distribution | Mid-scale compounders in European papermaking chemical kitchens seek automated dosing-compatible granule supply partnerships. |
Study Parameters
A spread of perspectives from plant managers at integrated chemical complexes, procurement leads at downstream polymerization facilities, distribution channel partners serving regional textile compounders, and technical R&D directors developing heterogeneous catalysis systems converged on the working assumptions. Primary interview insights combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and ECHA REACH registration databases. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include grade tier (pharmaceutical, electronics, technical), end-use industry (water treatment, papermaking, biomedical coatings, textiles), packaging format (liquid tanker, powder, granule, emulsion), and regional production hub configuration. CAGRs derived from weighted average of historical trend extrapolation and driver-based elasticity modeling. Forecast inputs incorporated municipal water infrastructure investment pipelines, METI CSCL reporting threshold adjustments, and photoinitiated polymerization technology adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained calcium carbide price stability, REACH authorization timeline assumptions, or dimethylaminoethyl methacrylate substitution rates would require recalibration. Practitioners should keep alternative scenarios live as ECHA evaluation criteria and Japanese import volume triggers evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
North America Polymer Emulsion Market