
 Bio-Based Thermoplastic Elastomer Market | 2026-2036
Bio-Based Thermoplastic Elastomer Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Thermoplastic Elastomer Market Outlook
Thailand is tilting toward bio-based polymer compounding capacity with new reactor lines serving ASEAN automotive supply chains. BASF SE leverages its polyurethane precursor network to anchor TPE-U supply into European medical tubing channels. Arkema sustains differentiation through its Pebax Rnew platform, which dominates high-performance footwear midsole formulations. Dow competes on manufacturing scale with integrated bio-ethylene feedstock access across North American Gulf Coast operations.
Bio-based thermoplastic elastomers are block copolymers or polyolefin alloys derived from renewable feedstocks such as castor oil, sugarcane ethanol, or microbial fermentation products, exhibiting Shore A hardness ranging from 20 to 95 and melt processing temperatures between 160°C and 220°C; they serve as drop-in replacements for conventional TPEs in applications requiring elasticity, recyclability, and reduced cradle-to-gate carbon intensity. TPE-S formulations lead volume due to established styrenic block copolymer infrastructure and cost-competitive scaling, while TPE-U captures margin pools in medical device and aerospace cable jacketing where hydrolysis resistance and biocompatibility certifications command premium positioning. TPE-V occupies a mature niche in automotive underhood seals where heat aging requirements exceed the performance envelope of softer bio-based alternatives.
REACH registration requirements and the EU Green Deal's polymer sustainability criteria shape product standards by mandating renewable content thresholds and restricting substances of very high concern in elastomer formulations. FDA biocompatibility testing protocols under ISO 10993 govern market access for medical-grade TPE compounds destined for implantable and fluid-contact devices. Stakeholders must monitor evolving bio-content certification schemes and feedstock traceability mandates to secure offtake agreements with automotive and healthcare OEMs implementing scope 3 emissions reduction targets.
Market Dynamics
REACH restrictions on petrochemical-derived plasticizers are redirecting formulation roadmaps toward plant-based feedstocks across European automotive and medical supply chains, compressing development timelines for drop-in bio-based alternatives.
Growth Catalysts
- EU Green Deal polymer sustainability criteria:Mandatory renewable content thresholds in elastomer formulations are pulling automotive OEM procurement toward certified bio-based TPE compounds for interior trim applications.
- Castor oil-derived polyol infrastructure:Expanding cultivation and refining capacity in Brazil and India is reducing feedstock cost volatility for TPE-U producers serving medical tubing channels.
- East Asian manufacturing clusters:South Korean automotive supplier parks and Chinese medical device export zones are concentrating demand for high-volume bio-based TPE-S compounds with established styrenic block copolymer processing lines.
Market Restraints
- Feedstock cost volatility:Agricultural commodity price swings for sugarcane ethanol and castor oil create margin pressure that petrochemical-derived TPEs do not face.
- Performance envelope limitations:Bio-based alternatives currently fail to match TPE-V heat aging specifications required for automotive underhood seals above 150°C continuous operation.
- Certification timeline friction:ISO 10993 biocompatibility testing protocols for medical-grade compounds extend qualification cycles by 18-24 months versus conventional materials.
Strategic Opportunities
- Thailand polymer compounding expansion:New reactor lines serving ASEAN automotive supply chains offer first-mover positioning for bio-based TPE producers targeting Japanese OEM supplier networks.
- Microbial fermentation feedstocks:Convergence of synthetic biology with traditional polymer chemistry is opening pathways to bio-identical performance properties without agricultural land-use constraints.
- Scope 3 emissions accounting mandates:Automotive and healthcare OEMs implementing supply chain carbon reduction targets are creating preferential offtake terms for feedstock-traceable bio-based elastomers.
Industry Challenges
- Polymer processing engineer scarcity:Limited talent pools familiar with both bio-based feedstock handling and TPE melt processing parameters constrain plant commissioning timelines.
- Multi-standard compliance complexity:Simultaneous navigation of REACH substance restrictions, FDA biocompatibility protocols, and emerging bio-content certification schemes fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Thermoplastic Elastomer Market |
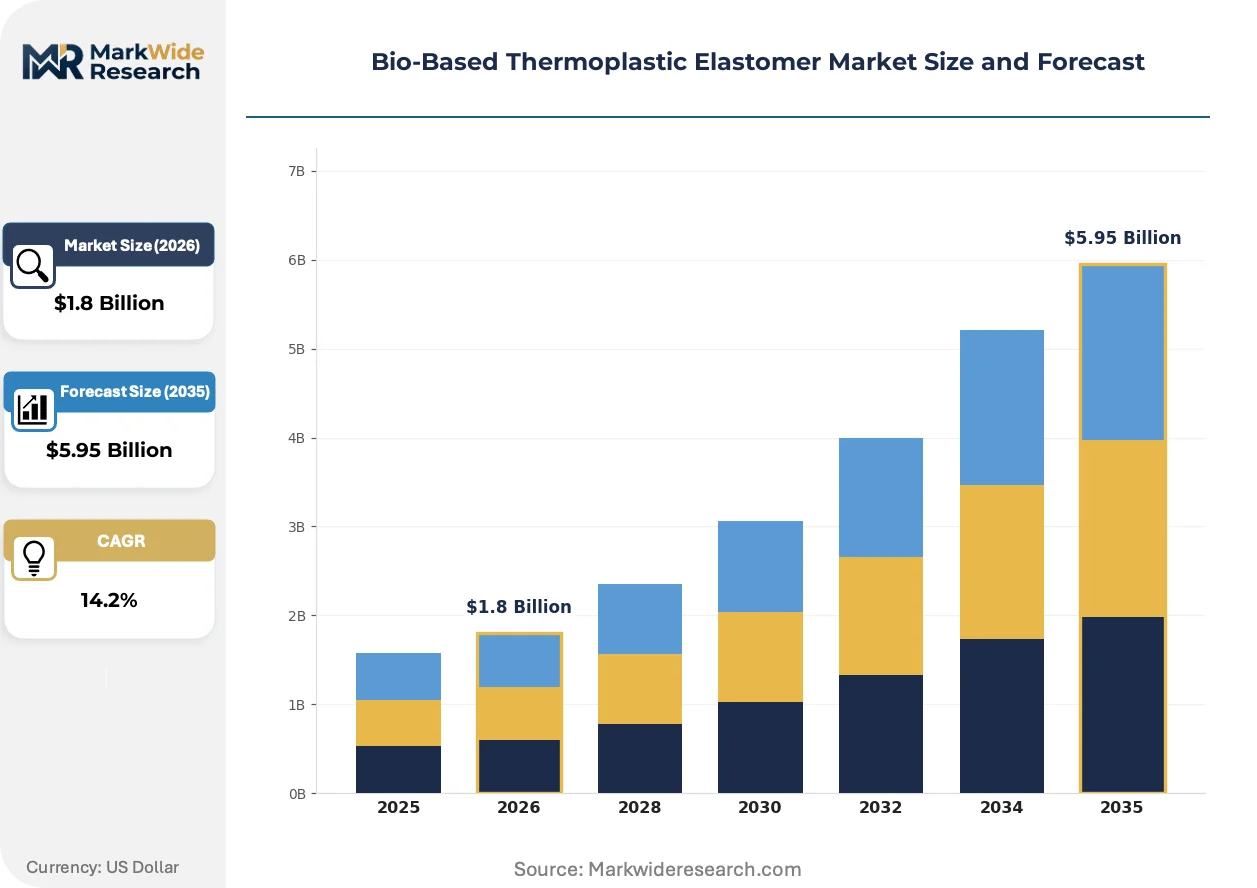
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TPE-S, TPE-O, TPE-U, TPE-V Application: Automotive Interiors, Medical Devices, Consumer Goods, Footwear End User: Aerospace, Automotive, Healthcare, Sports Equipment Form: Sheet, Film, Pellet, Rod |
| Companies Covered | BASF SE, Arkema, Asahi Kasei Corporation, Lubrizol Corporation, Huntsman International LLC, Dow, Evonik Industries AG, Covestro AG, Avient Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Thermoplastic Elastomer Market Strategic Shifts
Digital traceability infrastructure and advanced characterization methods are compressing the gap between laboratory formulation and production-scale qualification, reshaping how bio-based TPE developers validate performance equivalence with petrochemical incumbents.
Blockchain-enabled supply chain verification is digitizing feedstock provenance documentation for castor oil and sugarcane ethanol inputs. Automotive OEM sustainability auditors in Germany and Japan are mandating real-time traceability data for scope 3 emissions calculations. This transparency infrastructure is compressing supplier qualification timelines and displacing paper-based certification systems that previously created 6-12 month procurement delays.
REACH authorization requirements for phthalate plasticizers are tightening formulation constraints across European medical device and consumer goods applications. Compounders are accelerating substitution roadmaps toward bio-based plasticizer systems derived from epoxidized vegetable oils. Medical tubing extruders serving fluid-contact device markets are most affected, with several German and Swiss manufacturers now specifying minimum bio-content thresholds in raw material purchase agreements.
Automotive OEMs are consolidating approved supplier lists for interior trim compounds around vertically integrated compounders with captive bio-ethylene access. Tier-1 seating and dashboard manufacturers in South Korea and Michigan are shifting from spot procurement to multi-year offtake contracts with volume commitments and indexed pricing. This consolidation pattern is most visible in seating foam applications where TPE overmolding requirements now specify cradle-to-gate carbon intensity metrics alongside Shore hardness and compression set performance.
Bio-Based Thermoplastic Elastomer Market Segmentation
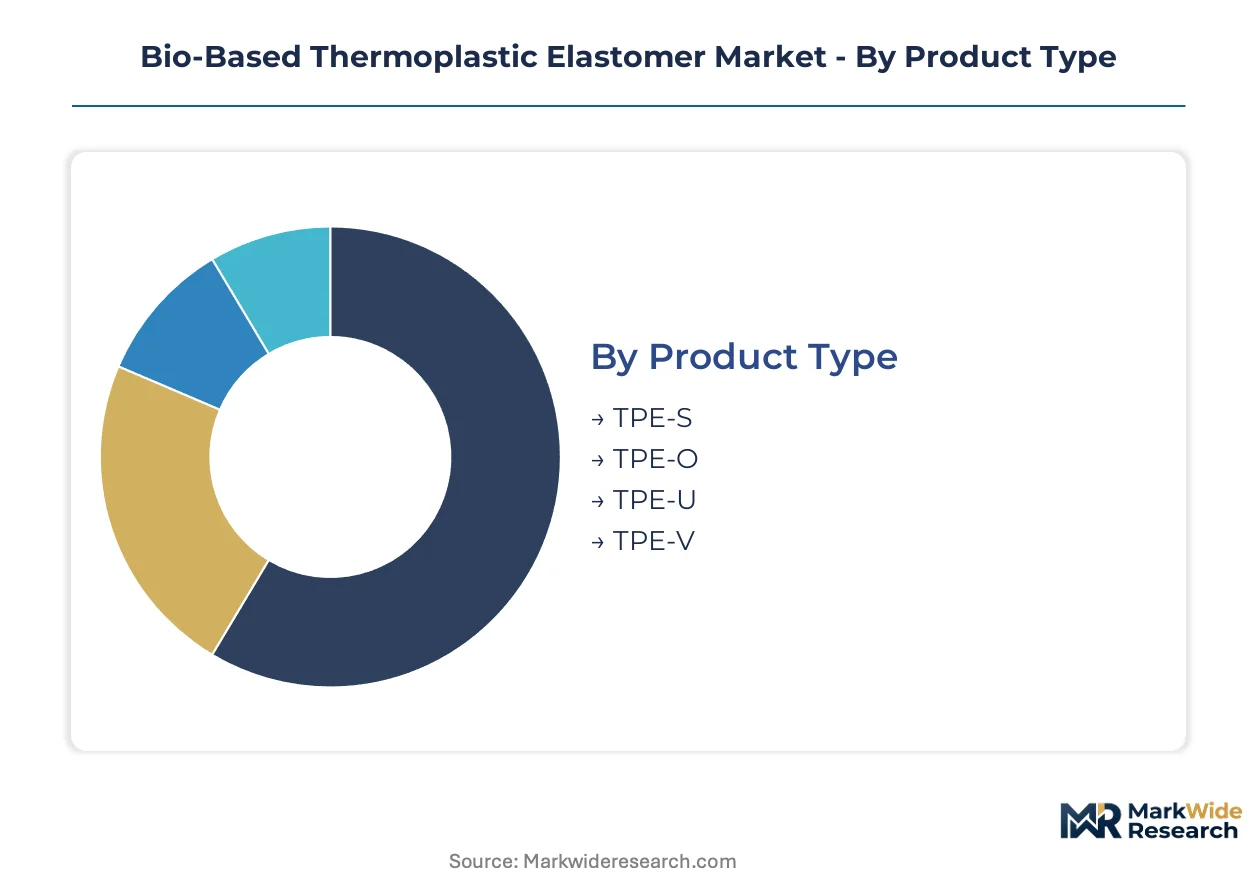
Bio-based thermoplastic elastomers serve divergent performance requirements across automotive, medical, and consumer applications. Segmentation reveals how formulation chemistry, processing form, and end-use certification demands create distinct commercial pockets with varying margin structures and qualification timelines.
Product Type:
Mature styrenic infrastructure dominates volume throughput, while newer polyurethane and olefinic platforms are expanding fastest on renewable content positioning.
- TPE-S:Styrenic block copolymers leverage established hydrogenation and compounding infrastructure, with Shore A hardness tunable from 20 to 95. German and Japanese automotive OEMs specify TPE-S for dashboard skins and door seals where compression set and UV stability requirements align with existing validation data. TPE-S handles the majority of throughput; TPE-U is climbing the fastest on medical tubing demand.
- TPE-U:Polyurethane elastomers derived from castor oil polyols deliver hydrolysis resistance and biocompatibility certifications required for fluid-contact medical devices. Swiss and German medical tubing extruders specify TPE-U for peristaltic pump tubing and IV connectors where ISO 10993 compliance is mandatory.
- TPE-O:Polyolefin alloys process on standard polyethylene extrusion lines with minimal equipment modification, serving cost-sensitive consumer goods applications.
- TPE-V:Vulcanizate alloys occupy a narrow niche in automotive underhood seals where continuous heat exposure exceeds 150°C.
TPE-S commands the installed base; TPE-U is expanding most quickly on healthcare premiumization.
Application:
Cost tier stratification separates specification-heavy automotive and medical channels from price-elastic consumer segments.
- Automotive Interiors:Seating, dashboard skins, and door panel overmolding require low-VOC emissions and cradle-to-gate carbon documentation. South Korean supplier parks specify bio-based TPE compounds with real-time feedstock traceability for scope 3 accounting.
- Medical Devices:Tubing, seals, and fluid-contact components demand ISO 10993 biocompatibility testing and REACH substance compliance. German and Swiss device manufacturers now mandate minimum renewable content thresholds in raw material agreements.
- Consumer Goods:Handles, grips, and soft-touch housings prioritize cost position over certification burden.
- Footwear:Midsole and outsole applications favor Pebax Rnew and similar high-rebound formulations for athletic performance segments.
Automotive Interiors absorbs the largest compound volume; Medical Devices is gaining share fastest on regulatory pull-through.
End User:
Customer type determines whether procurement prioritizes emissions accounting, biocompatibility certification, or mechanical performance specifications.
- Automotive:OEM sustainability mandates and scope 3 reduction targets drive multi-year offtake contracts with indexed pricing and renewable content guarantees.
- Healthcare:Device manufacturers navigate FDA and EMA pathways alongside REACH substance restrictions, extending qualification cycles.
- Aerospace:Cable jacketing and interior seal applications require flame retardancy and low smoke toxicity beyond standard bio-based formulations.
- Sports Equipment:Footwear and protective gear manufacturers specify high-rebound TPE-U for energy return metrics.
Automotive end users generate the bulk of purchase orders; Healthcare is the steepest expansion trajectory on tubing demand.
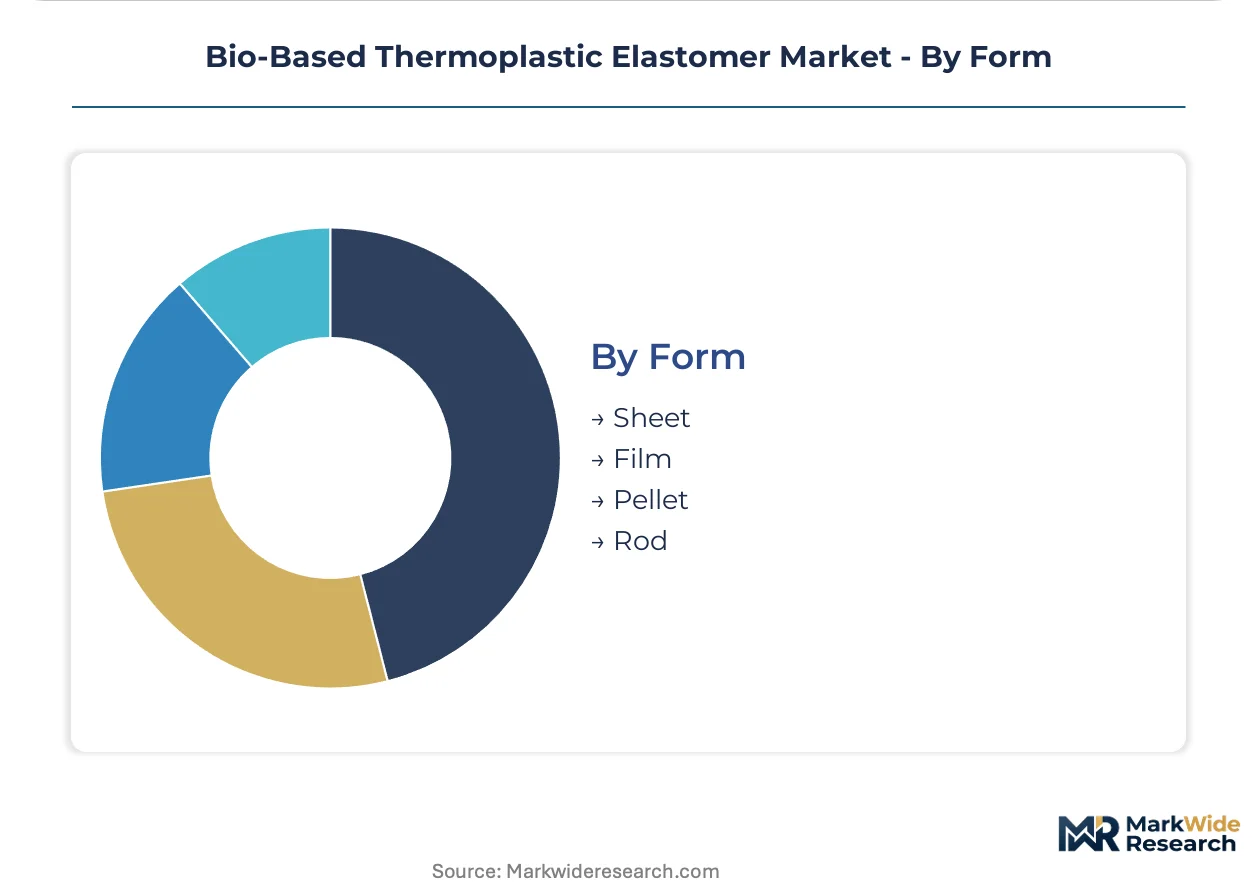
Form:
Supply concentration in pellet and sheet formats reflects downstream processing infrastructure rather than formulation differentiation.
- Pellet:Standard extrusion and injection molding feedstock serving high-volume automotive and consumer goods compounders.
- Sheet:Thermoforming feedstock for medical tray and automotive interior applications requiring consistent gauge control.
- Film:Thin-gauge extrusion for medical packaging and consumer goods lamination with barrier layer requirements.
- Rod:Profile extrusion stock for machining seals and custom gaskets in aerospace maintenance channels.
Pellet moves the highest tonnage; Film is expanding fastest on medical packaging conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Castor oil refining infrastructure in Brazil and India anchors upstream feedstock supply for polyurethane elastomer producers, while automotive compounding demand concentrates in German supplier parks and South Korean manufacturing clusters.
Germany
Automotive OEM sustainability mandates from BMW and Mercedes-Benz pull procurement toward bio-based TPE compounds for dashboard skins and door seals. ECHA REACH restrictions on phthalate plasticizers compress formulation timelines for interior trim suppliers. The Stuttgart and Munich supplier corridors host vertically integrated compounders with captive bio-ethylene access and real-time feedstock traceability systems.
United States
Medical device manufacturers in Minnesota and Massachusetts specify bio-based TPE-U for tubing applications requiring FDA biocompatibility clearance. EPA reporting requirements for scope 3 emissions drive automotive tier-1 suppliers toward certified renewable content agreements. The Michigan automotive corridor and Gulf Coast petrochemical complex intersect where Dow operates integrated bio-ethylene feedstock infrastructure.
China
Medical device export zones in Jiangsu and Zhejiang provinces concentrate demand for ISO 10993-compliant TPE compounds destined for European and North American markets. NMPA regulatory alignment with international standards accelerates qualification pathways for domestic compounders. The Yangtze River Delta manufacturing belt hosts the fastest-expanding extrusion capacity for bio-based medical tubing.
Japan
Automotive interior trim specifications from Toyota and Honda incorporate cradle-to-gate carbon intensity metrics alongside mechanical performance requirements. METI circular economy guidelines incentivize renewable content thresholds in elastomer procurement. The Nagoya supplier cluster and Kanto manufacturing region anchor compounding operations serving domestic OEM just-in-time supply networks.
Thailand
ASEAN automotive supply chain integration attracts Japanese OEM supplier networks establishing regional compounding operations. Board of Investment incentives for green chemistry manufacturing reduce capital deployment barriers for bio-based polymer reactor lines. The Eastern Economic Corridor industrial zone hosts new TPE compounding capacity serving Thai, Indonesian, and Vietnamese automotive assembly plants.
Bio-Based Thermoplastic Elastomer Market Competitive Environment
Integrated petrochemical majors and specialty chemical innovators split the market into scale-driven and performance-premium segments. The competitive structure tilts toward consolidated upstream control, with backward integration into bio-ethylene or castor oil polyol supply distinguishing viable participants from formulation-dependent compounders. Three archetypes dominate: diversified chemical conglomerates with captive renewable feedstock access, polyurethane specialists leveraging polyol expertise, and regional compounders serving automotive supplier park clusters. Capacity expansion in Thailand and Brazil, alongside multi-year offtake contracting with automotive OEMs, represents the dominant competitive moves.
Among European-based chemical conglomerates, BASF SE and Covestro AG occupy positions anchored by polyurethane precursor networks and integrated feedstock infrastructure. Arkema exemplifies the specialty innovator archetype through its Pebax platform positioning in high-performance footwear applications. These three companies represent distinct strategic postures: scale-driven manufacturing integration, performance-materials specialization, and regional automotive supply chain penetration.
| Leading Market Players |
|---|
| BASF SE |
| Arkema |
| Asahi Kasei Corporation |
| Lubrizol Corporation |
| Huntsman International LLC |
| Dow |
| Evonik Industries AG |
| Covestro AG |
| Avient Corporation |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp barge freight corridors for castor oil polyols transmit agricultural commodity volatility directly into TPE-U compound pricing, while concentration of bio-ethylene production on the US Gulf Coast creates divergent cost structures between European medical tubing buyers and North American automotive interior suppliers.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European bio-based TPE procurement. Three-tier pricing separates ISO 10993-certified medical grades from automotive interior compounds with cradle-to-gate carbon documentation, then from uncertified consumer goods formulations. Price differentiation rests on biocompatibility certification level and renewable content traceability. Cost compression in standard-grade TPE-S is intensifying because Brazilian castor oil harvest variability feeds directly into polyol input costs. Consumer goods compounders exhibit highest price sensitivity, while German medical device manufacturers accept premium positioning for batch-level feedstock documentation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for bio-based TPE compounders serving medical device export markets. Upstream concentration centers on Brazil and India for castor oil refining, Germany and Thailand for polymer compounding, and China for styrenic block copolymer hydrogenation capacity. Raw material dependencies include sugarcane ethanol for bio-ethylene, castor oil-derived polyols for TPE-U, and hydrogenated styrenic intermediates. Single-source vulnerability in castor oil cultivar supply creates crop failure exposure no petrochemical equivalent faces. Distribution runs through regional automotive supplier parks and medical device extrusion clusters rather than commodity chemical terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as automotive OEM scope 3 mandates splinter demand across feedstock-traceable specialty grades, creating defendable niches for compounders with documented renewable content rather than commodity scale players.
For Market Incumbents: Harden feedstock traceability infrastructure against emerging microbial fermentation competitors by securing multi-year castor oil offtake agreements with Brazilian cooperatives. Expand compounding capacity in Thailand's Eastern Economic Corridor to anchor Japanese OEM supplier networks before regional challengers commission reactor lines. Certification investment in blockchain-enabled provenance documentation is the defensive priority lever against formulation-dependent compounders lacking upstream integration. For New Entrants and Emerging Players: Southeast Asian medical device tubing extrusion presents the most penetrable white-space target, as Jiangsu and Zhejiang province manufacturers seek second-source TPE-U supply for European export compliance. Brazilian castor oil refining integration offers backward integration pathways unavailable to established petrochemical majors. Target specialty footwear midsole formulations as the entry segment, where Pebax Rnew premium positioning leaves price-accessible performance tiers underserved. Go-to-market execution should emphasize rapid ISO 10993 pathway navigation against incumbent qualification timelines. For Investors and Strategic Acquirers: Polyurethane specialists with captive polyol expertise and established medical channel relationships represent the acquisition target archetype with durable margin protection. Long-term viability over the next decade hinges on feedstock diversification beyond agricultural land-use constraints as synthetic biology pathways mature. The signal to watch is automotive OEM consolidation of approved supplier lists around vertically integrated compounders with real-time scope 3 emissions data, which would accelerate exit pressure on formulation-only participants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil Refining | Captive polyol supply insulates BASF and Covestro from Brazilian harvest volatility affecting medical tubing margins. |
| Thailand Compounding Capacity Expansion | New reactor lines in the Eastern Economic Corridor anchor supply to Toyota and Honda ASEAN supplier networks. |
| Blockchain Feedstock Traceability Deployment | Real-time provenance documentation satisfies BMW and Mercedes-Benz scope 3 auditors compressing qualification cycles. |
| ISO 10993 Biocompatibility Fast-Track Investment | Accelerated testing protocols differentiate TPE-U suppliers serving German and Swiss peristaltic pump tubing markets. |
| Microbial Fermentation Feedstock Partnership | Synthetic biology alliances reduce agricultural land-use exposure for Arkema's Pebax platform in footwear applications. |
Study Parameters
A standing panel of polymer processing engineers, automotive Tier 1 procurement managers, medical device regulatory affairs leads, and castor oil cooperative agronomists provided ongoing calibration across the study duration. Primary interviews with these stakeholders combined with secondary validation against ECHA REACH substance databases, FDA 510(k) filings for TPE medical devices, and Brazilian agricultural export statistics. Customs data from Indian castor oil derivatives trade, SEC filings from listed chemical conglomerates, and automotive OEM sustainability reports furnished quantitative anchors. Bottom-up segment sizing triangulated against top-down elastomer market allocations.
Scenario-bracketing framed the analytical approach across the projection horizon, with optimistic and conservative cases bound by castor oil price volatility assumptions and REACH authorization timeline acceleration. Segmentation dimensions modeled include product chemistry class, end-use certification tier, regional manufacturing cluster, and feedstock origin type. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-checks against automotive production forecasts and medical device tubing demand indices. Industry-specific inputs incorporated hydrogenation capacity utilization rates and bio-ethylene production cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by specialty polyurethane producers or breakthrough microbial fermentation scale-up would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Polymer Seals Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market