
 Global Styrene Acrylic Emulsion Polymer Market | 2026-2036
Global Styrene Acrylic Emulsion Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Styrene Acrylic Emulsion Polymer Market Intelligence
REACH is pivoting the European cost-of-entry calculus for styrene acrylic emulsion polymer suppliers by mandating stricter chemical safety dossiers and restricted substance thresholds. BASF SE leverages its integrated monomer-to-emulsion footprint to absorb compliance costs without outsourcing critical intermediates. Dow anchors its position through waterborne technology leadership and deep R&D spend on low-VOC architectural platforms. Celanese Corporation competes on specialty modified grades that command premium positioning in adhesive and textile niches.
Styrene acrylic emulsion polymer denotes a copolymer dispersion synthesized via free-radical emulsion polymerization of styrene and acrylic monomers, typically exhibiting 40-55% solids content, particle sizes of 100-300 nanometers, and glass transition temperatures tunable between -20°C and +60°C depending on monomer ratio. This material functions primarily as a film-forming binder in water-based coatings, adhesives, and surface treatments where it delivers adhesion, durability, and block resistance without volatile organic solvent carriers. Low VOC formulations now lead volume growth as regulatory ceilings harden across multiple geographies, while modified grades capture disproportionate margin pools in textile finishing and leather applications where performance specifications are most demanding. Standard grades remain the volume backbone for bulk architectural coatings but face commoditization pressure as Asian producers expand water-based capacity.
The US EPA enforces VOC content limits under architectural coatings rules that directly determine product eligibility for state and federal procurement. ECHA administers REACH registration and SVHC candidate listing that forces reformulation when styrene or acrylic monomer derivatives face scrutiny. China's MEE implements GB standards for indoor air quality and industrial emissions that push domestic manufacturers toward cleaner emulsion technologies. Stakeholders must monitor pending chemical hazard reclassifications that could trigger substitution cycles faster than existing product development timelines can accommodate.
Market Dynamics
Water-based formulation mandates across construction and coatings sectors are compressing solvent-borne capacity while concentrating procurement among emulsion specialists with verified low-VOC platforms. This regulatory compression is restructuring supplier tiers faster than incumbent capacity can pivot.
Growth Catalysts
- REACH SVHC scrutiny:ECHA's expanding candidate list for styrene derivatives is accelerating substitution toward compliant emulsion grades in European architectural coatings.
- China's GB standards tightening:MEE enforcement of indoor air quality limits is redirecting domestic paint production toward waterborne binder systems.
- Adhesive sector diversification:Pressure-sensitive tape and label manufacturers are expanding emulsion consumption for bond-line durability without solvent carriers.
Market Restraints
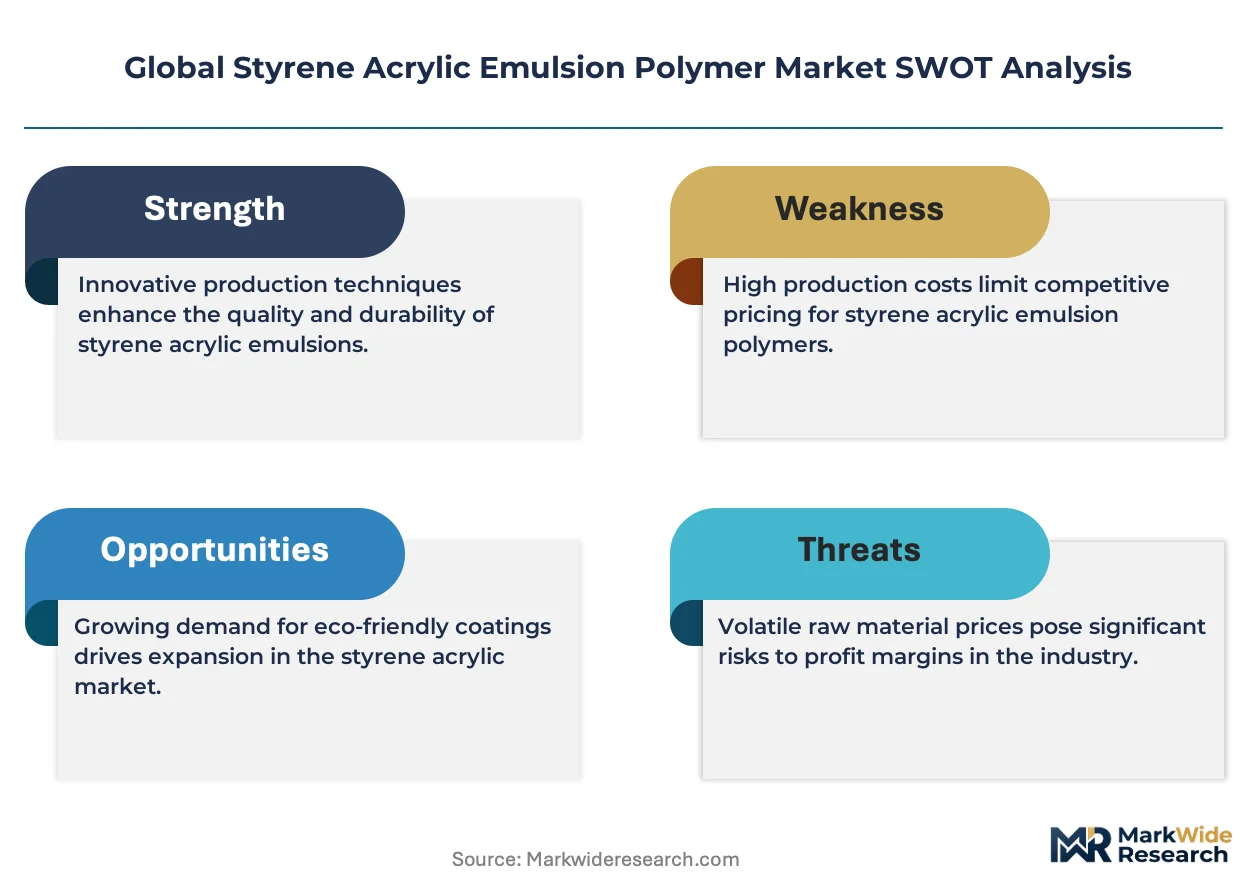
- Butadiene-styrene feedstock volatility:Crude-linked monomer pricing swings compress margin predictability for non-integrated emulsion producers.
- East Asian supply concentration:Bulk architectural grade capacity clusters in China's Shandong and Jiangsu provinces, creating single-source exposure for regional buyers.
- Performance ceiling in extreme climates:Standard emulsion films exhibit hydrolytic instability above 60°C surface temperatures, limiting exterior tropical applications.
Strategic Opportunities
- India's PLI-linked construction chemicals:Domestic manufacturing incentives for specialty coatings are opening localized emulsion supply gaps.
- Textile finishing convergence:Digital printing paste binders represent an emerging outlet for carboxylated styrene acrylic grades with pigment anchoring performance.
- EU Green Deal procurement mandates:Public infrastructure tenders now require Environmental Product Declaration compliance, favoring verified low-carbon emulsion suppliers.
Industry Challenges
- Emulsion polymerization process control expertise:Batch consistency at 200+ nanometer particle sizes requires scarce skilled technicians for seed-stage kinetics management.
- Multi-jurisdiction registration synchronization:Divergent chemical safety dossier timelines between ECHA, EPA, and China's MEE delay product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Styrene Acrylic Emulsion Polymer Market |
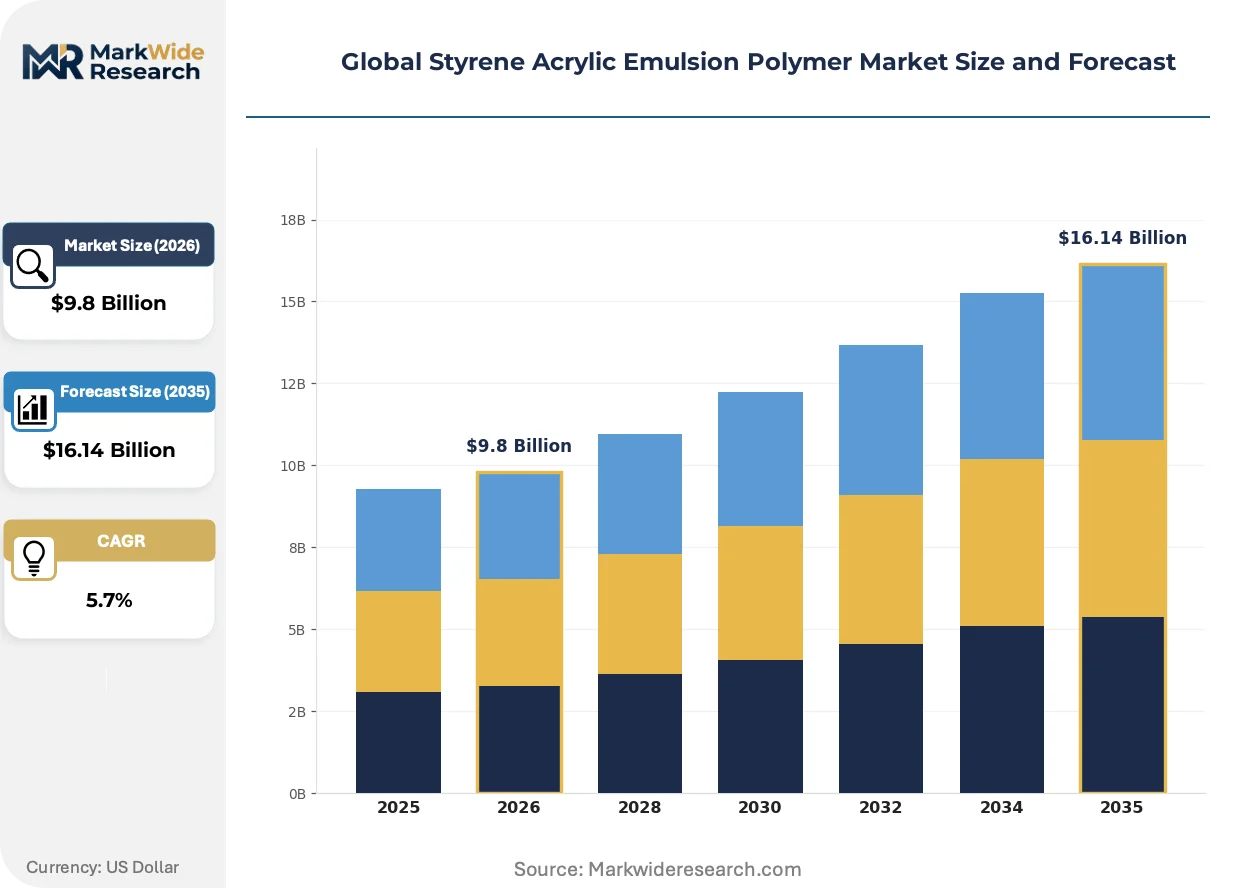
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
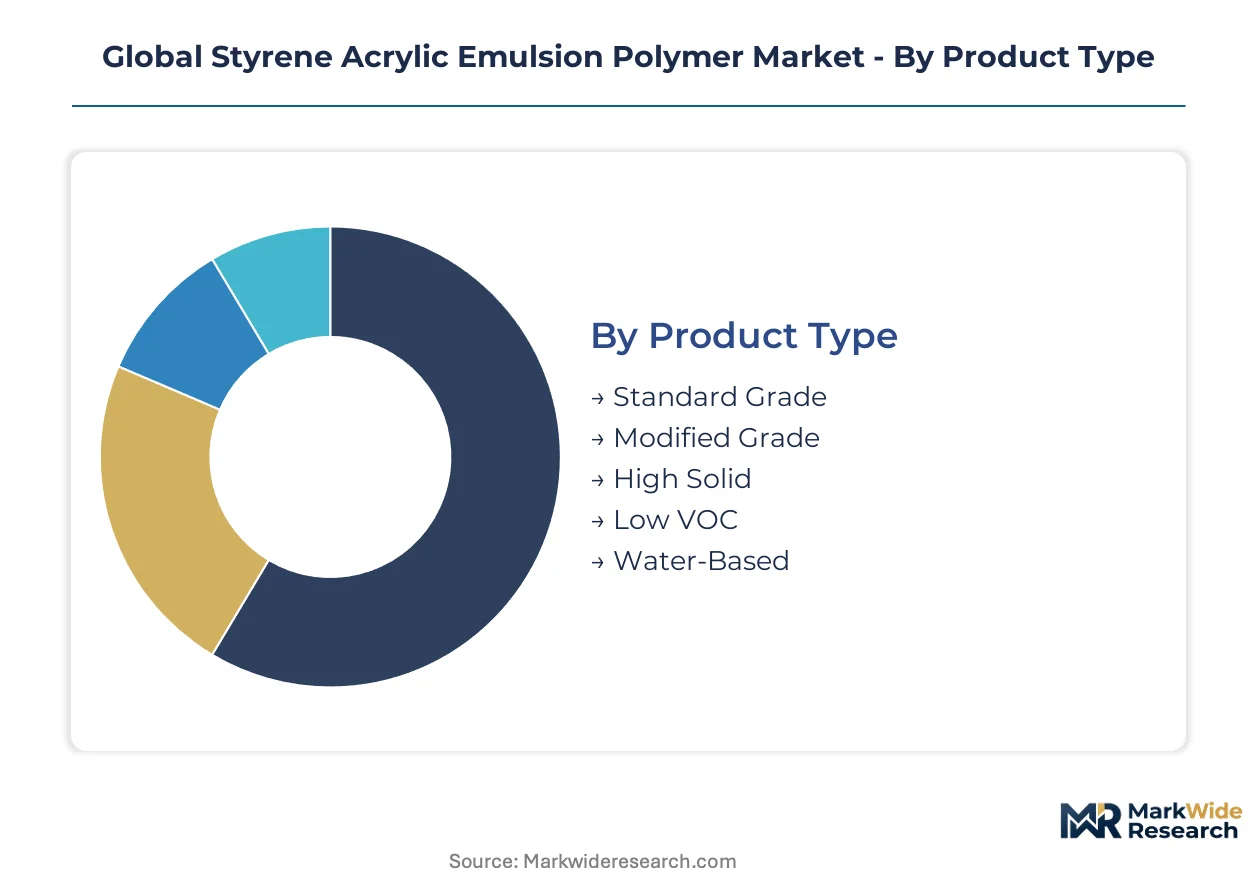
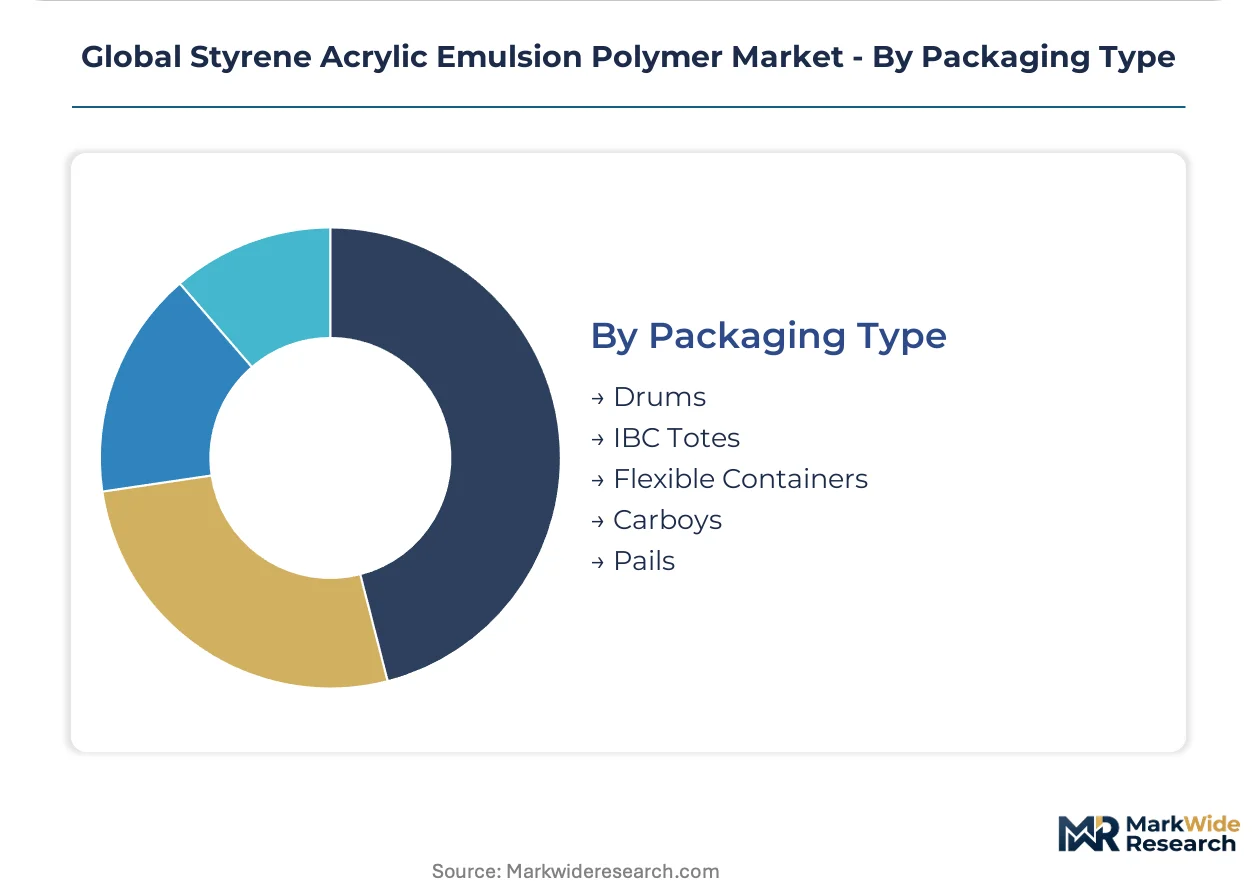
| Segmentation | Product Type: Standard Grade, Modified Grade, High Solid, Low VOC, Water-Based Application: Architectural Coatings, Adhesives, Textile Finishing, Paper Coating, Leather Finishing End User Industry: Construction Sector, Packaging Manufacturers, Textile Mills, Printing Companies, Footwear Producers Packaging Type: Drums, IBC Totes, Flexible Containers, Carboys, Pails |
| Companies Covered | BASF SE, Celanese Corporation, Dow, H.B. Fuller Company, Lubrizol Corporation, DIC Corporation, Mallard Creek Polymers, Chemrez Technologies, Pexi Chem Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Styrene Acrylic Emulsion Polymer Market Strategic Shifts & Innovations
Reactive surfactant technologies and hybrid acrylic-styrene-urethane architectures are compressing the performance gap between waterborne and solvent-borne films. These advances are enabling specification capture in historically solvent-dependent end uses.
Self-crosslinking styrene acrylic emulsions incorporating ketone-hydrazide or carbodiimide chemistries are unifying ambient cure durability with low-VOC compliance. Automotive refinish shops and industrial maintenance contractors in Germany and Japan are adopting these systems for corrosion-resistant primers. The technology is unifying previously separate primer and topcoat application steps into single-build processes.
EPA architectural coatings rules are tightening VOC content ceilings for industrial maintenance and plastic substrate categories. Formulators serving US military and infrastructure procurement channels are reformulating toward exempt compound systems. Coatings contractors in California and Texas are experiencing compressed product qualification cycles as state implementation plans diverge from federal baselines.
Specification-driven procurement is consolidating buyer power among large construction chemical distributors. Regional paint manufacturers in Brazil and Indonesia are bypassing traditional importer networks to source directly from integrated Asian producers. This channel compression is most visible in Southeast Asia, where project-scale buyers now negotiate annual emulsion supply agreements indexed to monomer futures rather than spot resin pricing.
Global Styrene Acrylic Emulsion Polymer Market Segmentation
Styrene acrylic emulsion polymer demand fragments across performance tiers, application intensities, and supply chain configurations that determine margin capture. Understanding segment boundaries reveals where formulation premiums apply versus commodity volume plays.
Product Type:
Integration depth varies sharply: standard grades function as standalone binder inputs, while modified and high-solid variants embed deeper into customer formulation workflows.
- Standard Grade:These emulsions carry 40-50% solids with unmodified styrene-acrylic ratios optimized for cost-sensitive architectural coatings. Demand concentrates in China's Shandong province where bulk paint manufacturers source directly from integrated producers to bypass distributor markups. Feedstock volatility compresses margins for non-integrated suppliers.
- Modified Grade:Carboxylated or hydroxyl-functional variants enable crosslinking with isocyanate or melamine systems for industrial maintenance primers. Japanese automotive refinish shops specify these grades for corrosion resistance without solvent carriers. Premium positioning reflects scarce polymerization expertise for controlled particle morphology.
- High Solid:55-65% solids content reduces transport costs and drying energy in high-throughput coating lines.
- Low VOC:Formulations meeting EPA architectural coatings rules and EU Green Deal procurement thresholds.
- Water-Based:Base emulsion platform for regulatory-compliant coating systems across multiple geographies.
Standard grade leads volumes today; modified grade is gaining share fastest.
Application:
Cost tier stratification separates specification-driven niches from price-sensitive bulk procurement channels.
- Architectural Coatings:Interior and exterior house paints consume the largest emulsion volumes, with Chinese domestic brands scaling water-based production for regional construction booms. MEE enforcement of GB indoor air quality standards redirects solvent-borne capacity toward compliant emulsion systems.
- Adhesives:Pressure-sensitive tape and label manufacturers require block resistance and bond-line durability without volatile carriers. German packaging converters specify carboxylated grades for PET film anchoring performance.
- Textile Finishing:Digital printing paste binders represent an emerging outlet for pigment anchoring applications.
- Paper Coating:Gloss and printability enhancement for publication and packaging papers.
- Leather Finishing:Topcoat binders requiring flexibility and abrasion resistance.
Architectural coatings dominates volume; adhesives applications show the steepest expansion trajectory.
End User Industry:
Customer type determines procurement leverage, with project-scale buyers negotiating index-linked supply agreements versus formulation houses seeking technical partnership.
- Construction Sector:Large chemical distributors consolidate procurement power across regional paint manufacturers in Brazil and Indonesia. These buyers now source directly from Asian integrated producers, bypassing traditional importer networks.
- Packaging Manufacturers:Pressure-sensitive adhesive demand from Southeast Asian tape and label producers scales with e-commerce logistics growth.
- Textile Mills:Digital printing adoption in India and Bangladesh drives carboxylated grade consumption.
- Printing Companies:Publication and packaging paper coating requirements.
- Footwear Producers:Leather finishing applications for synthetic and natural upper materials.
Construction sector absorbs the largest share; packaging manufacturers are climbing the fastest.
Packaging Type:
Supply concentration and logistics cost structure shape container selection across regional distribution networks.
- Drums:Standard 200-liter steel and plastic drums serve mid-volume coating formulators with established warehouse infrastructure.
- IBC Totes:Intermediate bulk containers reduce handling costs for high-throughput adhesive and textile chemical plants.
- Flexible Containers:Bag-in-box systems minimize cleaning and return logistics for specialty modified grades.
- Carboys:Smaller-volume packaging for sampling and specialty formulation development.
- Pails:Retail and artisan-scale coating distribution channels.
Drums and IBC totes together dominate volume; flexible containers are expanding most quickly in premium grade distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymerization technicians cluster in Germany's Rhine-Ruhr corridor, China's Shandong province, and the US Gulf Coast, anchoring emulsion production expertise in these geographies.
United States
EPA architectural coatings rules tighten VOC ceilings for industrial maintenance applications, redirecting solvent-borne capacity toward compliant waterborne systems. California and Texas contractors face compressed product qualification cycles as state implementation plans diverge from federal baselines. Houston-Galveston petrochemical corridors supply integrated monomer-to-emulsion operations.
Germany
REACH SVHC scrutiny accelerates substitution toward compliant emulsion grades in automotive refinish and industrial maintenance coatings. EU Green Deal procurement mandates now require Environmental Product Declaration compliance for public infrastructure tenders. BASF SE leverages its Ludwigshafen integrated footprint to absorb regulatory compliance costs without outsourcing critical intermediates.
China
MEE enforcement of GB indoor air quality standards redirects domestic paint production toward waterborne binder systems. Shandong and Jiangsu provinces concentrate bulk architectural grade capacity, creating single-source exposure for regional buyers. Domestic brands scale water-based production for regional construction booms.
Japan
Automotive refinish shops specify carboxylated grades for corrosion-resistant primers without solvent carriers. METI industrial standards push low-VOC formulation adoption in packaging and textile applications. Kansai region chemical complexes maintain specialized emulsion polymerization expertise for controlled particle morphology.
India
PLI-linked construction chemical incentives open localized emulsion supply gaps for specialty coatings manufacturers. Digital printing adoption in Gujarat and Tamil Nadu drives carboxylated grade consumption for textile finishing. Domestic manufacturing scale-up reduces import dependence for water-based architectural binders.
Global Styrene Acrylic Emulsion Polymer Market Key Industry Players
The competitive structure tilts toward integrated petrochemical majors with captive monomer supply. Tiered specialization separates bulk architectural suppliers from modified-grade specialists serving adhesive and textile niches. Three archetypes dominate: integrated chemical conglomerates with backward monomer control, specialty polymer houses focusing on functionalized grades, and regional volume producers serving construction chemical distributors. Capacity expansion and portfolio diversification toward low-VOC platforms represent the dominant competitive moves.
Among European integrated producers, BASF SE and Celanese Corporation occupy positions reflecting divergent strategic emphases. BASF exemplifies the monomer-to-emulsion archetype through its Rhine-Ruhr manufacturing complex. Celanese represents specialty modified-grade positioning that commands premium placement in performance-intensive applications. Dow anchors North American waterborne technology leadership through sustained R&D allocation on architectural platforms.
| Leading Market Players |
|---|
| BASF SE |
| Celanese Corporation |
| Dow |
| H.B. Fuller Company |
| Lubrizol Corporation |
| DIC Corporation |
| Mallard Creek Polymers |
| Chemrez Technologies |
| Pexi Chem Private Limited |
| Others |
Cost & Logistics Intelligence
Styrene monomer costs cascade from Gulf Coast crackers through three distinct pricing tiers downstream, with integrated producers capturing margin at each conversion stage while non-integrated formulators absorb volatility. Bulk architectural grades trade on spot benzene-styrene spreads, whereas carboxylated modified grades carry formulation service premiums that insulate specialists from commodity swings.
Pricing Analysis
Bundled technical service contracts dominate modified grade procurement, while standard grades transact on unbundled spot resin pricing indexed to monomer futures. Three-tier pricing structure across premium, standard, and economy levels separates certified low-VOC formulations from commodity architectural binders. Price differentiation hinges on REACH compliance documentation and volume scale, with spot benzene volatility compressing margins for non-integrated suppliers. Regional paint manufacturers in Southeast Asia exhibit highest price sensitivity, while Japanese automotive refinish shops accept premiums for corrosion-resistant carboxylated grades.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke delivery networks for drum and IBC tote shipments. Production gravity centers on China, Germany, and the United States, with Shandong province hosting the densest cluster of bulk architectural grade capacity. Feedstock dependencies rest on styrene, acrylic acid, and butadiene monomers sourced from integrated petrochemical corridors. Single-source vulnerability concentrates in China's Jiangsu province, where a handful of producers supply regional coating manufacturers. Distribution runs through construction chemical distributors consolidating procurement for mid-volume formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Styrene Acrylic Emulsion Polymer Market functions as a stable compounder, with regulatory-driven solvent-borne substitution providing steady volume expansion regardless of construction cycle volatility.
For Market Incumbents: Deepen backward integration into captive styrene supply to absorb monomer price swings that erode non-integrated competitors. Expand low-VOC certification portfolios ahead of ECHA SVHC reclassifications that could disqualify legacy formulations from EU public procurement. Prioritize R&D allocation toward self-crosslinking chemistries that unify primer-topcoat application steps for automotive refinish customers. For New Entrants and Emerging Players: Launch via direct supply agreements with Indian specialty coating manufacturers benefiting from PLI-linked construction chemical incentives. Target textile finishing applications in Gujarat and Tamil Nadu, where digital printing paste binder demand outpaces domestic carboxylated grade supply. Penetrate through technical partnership models that embed polymerization expertise into customer formulation workflows rather than commodity resin sales. For Investors and Strategic Acquirers: Roll-up economics work for specialty modified-grade producers because formulation complexity and regulatory dossier requirements create natural barriers to rapid capacity replication. Mid-cap specialists with proven EPD compliance and automotive refinish certifications offer the most defensible positions across a 5-10 year holding period. Monitor ECHA SVHC candidate list additions for styrene derivatives as the critical inflection signal that could accelerate substitution cycles beyond incumbent product development timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Monomer | Captive feedstock supply absorbs benzene price volatility that compresses non-integrated margins. |
| Low-VOC Platform Certification | EU Green Deal procurement mandates now require EPD compliance for public infrastructure tenders. |
| Self-Crosslinking Emulsion Development | Ketone-hydrazide chemistries unify primer-topcoat steps for German automotive refinish shops. |
| Regional Distribution Hub Expansion | Singapore and Rotterdam centers reduce logistics costs for Southeast Asian and European coating formulators. |
| Technical Service Partnership Model | Embedded polymerization expertise locks in Indian textile mills adopting digital printing paste binders. |
Research Approach
Direct dialogue with plant managers at integrated emulsion facilities, procurement leads at downstream coating OEMs, distribution channel partners, and technical R&D directors grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and regulatory dossiers submitted to ECHA and EPA. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic drivers to ensure segmentation coherence.
Bottom-up modeling of grade-specific consumption across architectural coatings, adhesives, and textile finishing applications anchored volume estimates, while top-down macroeconomic filters tested plausibility against construction spending and industrial production indices. Segmentation dimensions included product grade tier, end-use industry intensity, packaging format logistics cost structure, and regional production hub concentration. CAGRs were derived from slope analysis of normalized consumption trends, with feedstock price elasticity and regulatory compliance cost curves serving as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA SVHC reclassifications or sudden benzene supply disruptions from Gulf Coast weather events. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
United States Polymer Emulsion Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
Glutathione Resin Market