
 Global Flexible Polyurethane Foam Market | 2026-2036
Global Flexible Polyurethane Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible Polyurethane Foam Market Foresight
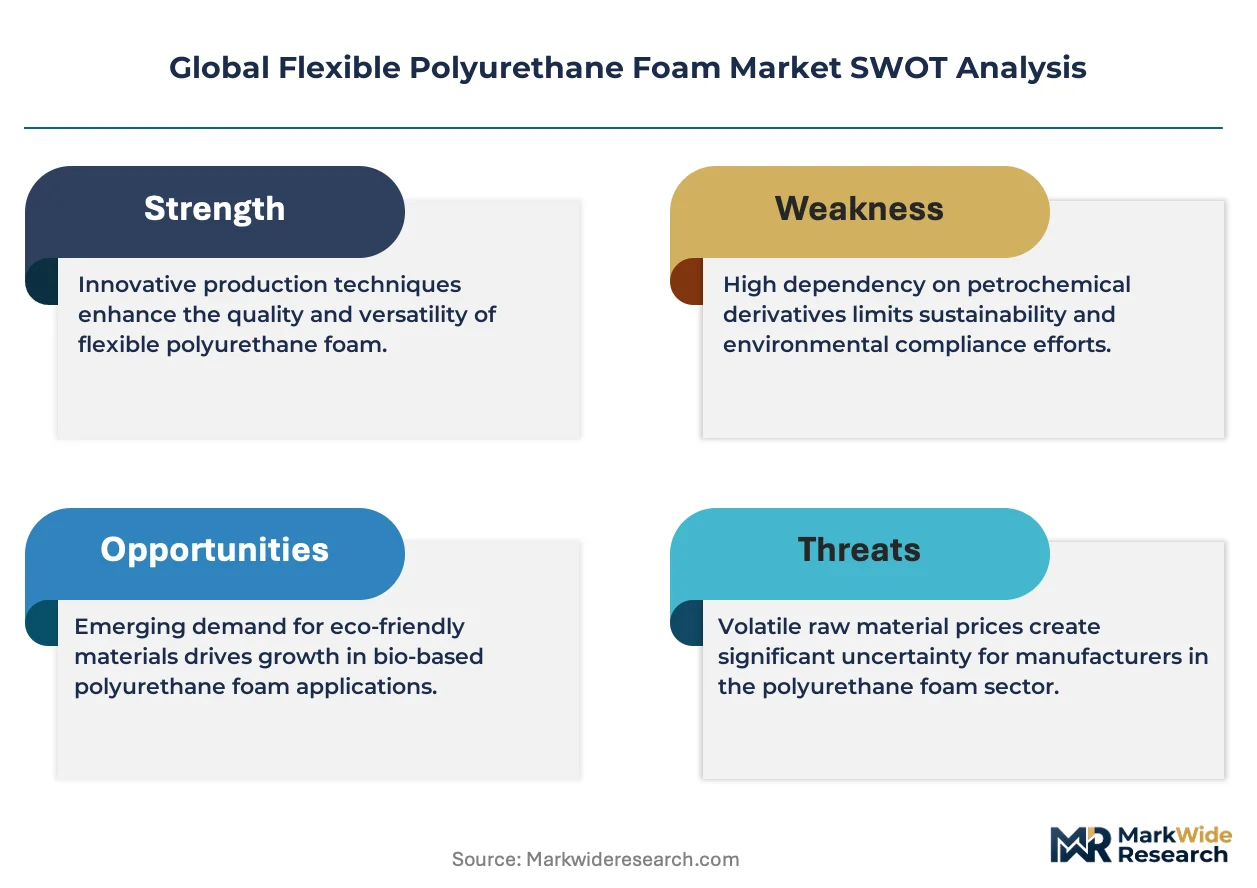
Asset-light leasing models for polyol storage and blending equipment is fragmenting the competitive landscape by lowering capital barriers for regional compounders. Huntsman Corporation leverages its integrated polyurethanes chain to sustain feedstock cost advantages across multiple continents. BASF SE anchors European supply through large-scale TDI and MDI production complexes near Ludwigshafen. Dow competes on formulation flexibility, offering customized high-resilience systems for automotive tier-one suppliers.
Flexible polyurethane foam consists of open-cell polymers produced through the reaction of polyols with diisocyanates, typically exhibiting densities from 15 to 80 kg per cubic meter and indentation force deflection values calibrated for load-bearing applications. The material functions primarily as a comfort and impact-absorption layer in seating, bedding, and packaging systems where controlled rebound and durability are specified. Polyether foam dominates volume consumption due to its cost-efficiency in furniture and bedding applications, while viscoelastic foam commands premium positioning in medical and luxury sleep products where pressure distribution is critical. Molded forms capture the highest value per kilogram in automotive seating programs, whereas slabstock production serves the commoditized mattress and cushion markets with thinner margin pools.
The EPA regulates VOC emissions from foam manufacturing under Clean Air Act provisions, while REACH restricts certain flame-retardant additives and isocyanate handling protocols across EU member states. China's MEE enforces wastewater and air-quality standards that affect polyol and isocyanate producers operating in the Yangtze River Delta cluster. Stakeholders must monitor how forthcoming restrictions on organohalogen flame retardants in California and the EU will redirect R&D spending toward phosphorus-based and bio-based alternatives before compliance deadlines tighten.
Market Dynamics
Automotive seating manufacturers in Germany, Japan, and the United States are consolidating procurement around viscoelastic and high-resilience foam grades, compressing specification cycles and forcing compounders to accelerate formulation turnaround times. This demand concentration is restructuring supplier relationships across the value chain.
Growth Catalysts
- REACH chemical disclosure mandates:European regulators are tightening volatile organic compound tracking requirements, compelling foam producers to invest in cleaner formulation capabilities that command premium positioning in export markets.
- China-India-Mexico manufacturing expansion:Domestic furniture and automotive production capacity growth in these three countries is absorbing increasing volumes of slabstock and molded foam grades.
- Viscoelastic pressure-distribution technology:Medical and luxury sleep product manufacturers are specifying memory foam layers for pressure ulcer prevention and ergonomic support applications.
Market Restraints
- TDI/MDI feedstock volatility:Polyisocyanate price swings tied to crude oil and benzene derivatives compress margin predictability for regional foam compounders lacking captive aromatics supply.
- Yangtze River Delta environmental enforcement:China's MEE wastewater and air-quality inspections have idled smaller polyol production units, concentrating intermediate supply among state-backed integrated producers.
- Natural latex substitution in premium bedding:Plantation rubber foam captures share in eco-positioned mattress segments where bio-based origin stories outweigh polyurethane performance advantages.
Strategic Opportunities
- India domestic automotive seating programs:OEM localization requirements under the country's PLI scheme create demand for molded high-resilience foam systems currently imported from East Asian suppliers.
- Phosphorus-based flame retardant convergence:California and EU restrictions on organohalogen additives are redirecting R&D budgets toward reactive phosphorus chemistry that integrates into polyol backbones.
- Asset-light polyol blending equipment leasing:Regional compounders in Mexico and Southeast Asia are accessing storage and mixing infrastructure without capital-heavy balance sheet commitments.
Industry Challenges
- Isocyanate handling certification timelines:REACH and OSHA protocols for diisocyanate worker exposure are extending facility qualification periods for new production lines.
- Legacy slabstock retooling for low-VOC blowing agents:Transitioning from HFC to hydrocarbon or water-blown systems requires reactor modifications that strain mid-tier producer capex budgets.
- Cross-border formulation IP fragmentation:Divergent patent landscapes between the United States, Germany, and Japan complicate technology licensing for viscoelastic cell-structure control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible Polyurethane Foam Market |
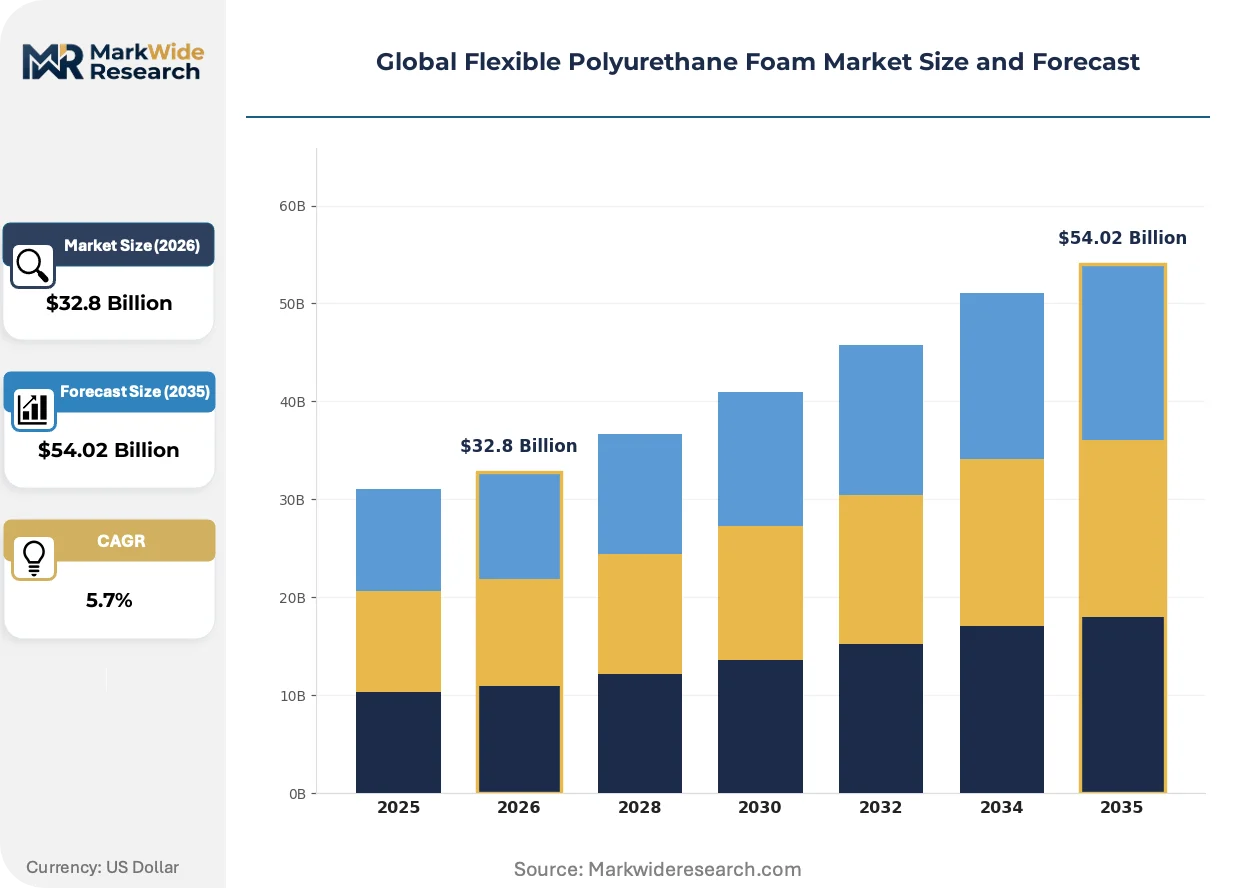
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $54.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Resilience Foam, Viscoelastic Foam, Polyether Foam, Polyester Foam, Melamine Foam Application: Furniture, Bedding, Automotive Seating, Packaging, Acoustic Insulation, Sports Equipment End User Industry: Consumer Goods Manufacturers, Transportation Suppliers, Construction Firms, Electronics Producers Form: Blocks, Molded, Slabs, Sheets, Rolls |
| Companies Covered | Covestro, Woodbridge Group, BASF SE, Sekisui Chemical Co., Ltd., Rogers Corporation, Huntsman Corporation, Recticel, INOAC Corporation, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible Polyurethane Foam Market Shifts & Advancements
Formulation chemistry and manufacturing process control are converging to enable mass customization of foam properties at production scale, collapsing the traditional trade-off between unit cost and performance specificity.
Bio-based polyol feedstocks derived from soybean oil and castor oil are rendering obsolete petroleum-dependent comfort layers in furniture and bedding applications. European mattress brands and US automotive tier-one suppliers are qualifying these materials for 15-30% renewable content targets. The shift is compressing price premiums for conventional polyether systems and forcing integrated producers to secure agricultural supply partnerships.
REACH restrictions on organohalogen flame retardants are redirecting compounder R&D spending toward phosphorus-based and nitrogen-based alternatives before 2026 compliance deadlines. The regulation is accelerating substitution in upholstered furniture and transportation seating segments where fire safety standards remain stringent. German and French foam producers are front-loading capital for reactive phosphorus polyol integration to maintain export access.
Fleet buyers in the US commercial furniture sector are consolidating vendor relationships around suppliers offering take-back programs for end-of-life foam recovery. Contract hospitality and healthcare facility managers are prioritizing circularity credentials in specification documents. The behavior is most visible in California and New York state procurement where extended producer responsibility frameworks are advancing through state legislatures.
Global Flexible Polyurethane Foam Market Segmentation
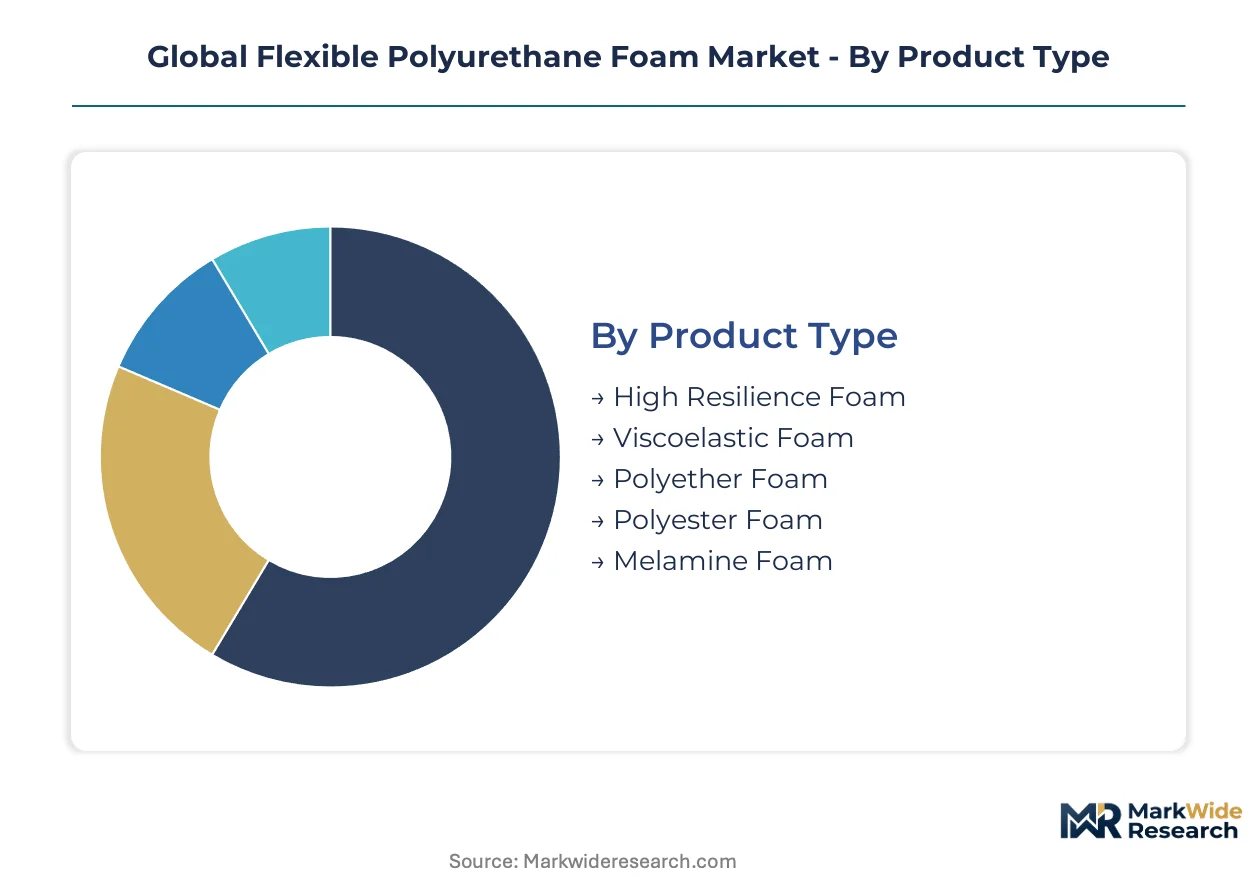
Segmentation in flexible polyurethane foam reveals how formulation chemistry and manufacturing form factor dictate margin structure, specification cycles, and supplier relationships across end-use markets. Understanding these divisions exposes where compounders capture premium positioning versus where volume commoditization compresses returns.
Product Type:
Cycle times vary dramatically across foam chemistries, with commodity polyether turning inventory weekly while viscoelastic grades tie up working capital through extended qualification periods.
- High Resilience Foam:Open-cell structures with rapid recovery characteristics serve automotive seating programs requiring durability under cyclic loading. Procurement from German and Japanese tier-one suppliers concentrates around molded seating modules where OEMs specify indentation force deflection tolerances within narrow bands.
- Viscoelastic Foam:Temperature-sensitive cell structures conform to body contours through controlled viscous flow, creating pressure-distribution layers for medical mattresses and luxury sleep products. Demand clusters in North American and European bedding markets where consumers pay premiums for ergonomic positioning and motion isolation.
- Polyether Foam:Cost-optimized comfort layers dominate furniture cushioning through bulk slabstock production.
- Polyester Foam:Higher tensile strength supports packaging and filtration applications requiring dimensional stability.
- Melamine Foam:Thermoset structures with exceptional sound absorption serve acoustic insulation in transportation and building applications.
Polyether foam anchors the volume base while viscoelastic foam gains share at the steepest rate.
Application:
Margin pools stratify sharply across end-uses, with automotive seating commanding formulation premiums and bedding absorbing the thinnest spreads per kilogram.
- Furniture:Cushion cores and upholstery padding consume bulk polyether slabstock through high-volume cutting operations. Chinese and Mexican manufacturers drive procurement concentration as domestic production capacity expands for export and local consumption.
- Bedding:Mattress comfort layers and toppers represent the largest single application by tonnage, though price competition from natural latex and imported finished mattresses constrains domestic compounder profitability.
- Automotive Seating:Molded high-resilience systems carry the highest value per kilogram, with German and Japanese OEMs specifying custom formulations for seat cushion and backrest modules.
- Packaging:Protective inserts and dunnage utilize lower-density polyester and polyether grades.
- Acoustic Insulation:Melamine and specialized open-cell foams address NVH requirements in transportation and building construction.
- Sports Equipment:Protective padding and equipment liners demand specific rebound characteristics.
Furniture absorbs the greatest tonnage while automotive seating delivers the highest returns on formulation investment.
End User Industry:
Procurement sophistication divides end-user categories, with transportation suppliers maintaining the most stringent qualification protocols and construction firms operating on spot-market purchasing patterns.
- Consumer Goods Manufacturers:Furniture and bedding brands source slabstock through annual contracts with volume-tiered pricing, consolidating supplier relationships around regional compounders offering consistent density specifications and reliable delivery windows.
- Transportation Suppliers:Tier-one seating manufacturers in Germany, Japan, and the United States enforce rigid quality systems, requiring compounders to maintain IATF certification and demonstrate batch-to-batch consistency across multi-year platform lifecycles.
- Construction Firms:Acoustic and insulation applications purchase on project-specific schedules with limited formulation customization.
- Electronics Producers:Protective packaging and component cushioning demand anti-static and precision-cut foam solutions.
Transportation suppliers maintain the most demanding specification regimes while consumer goods manufacturers drive the greatest aggregate volume.
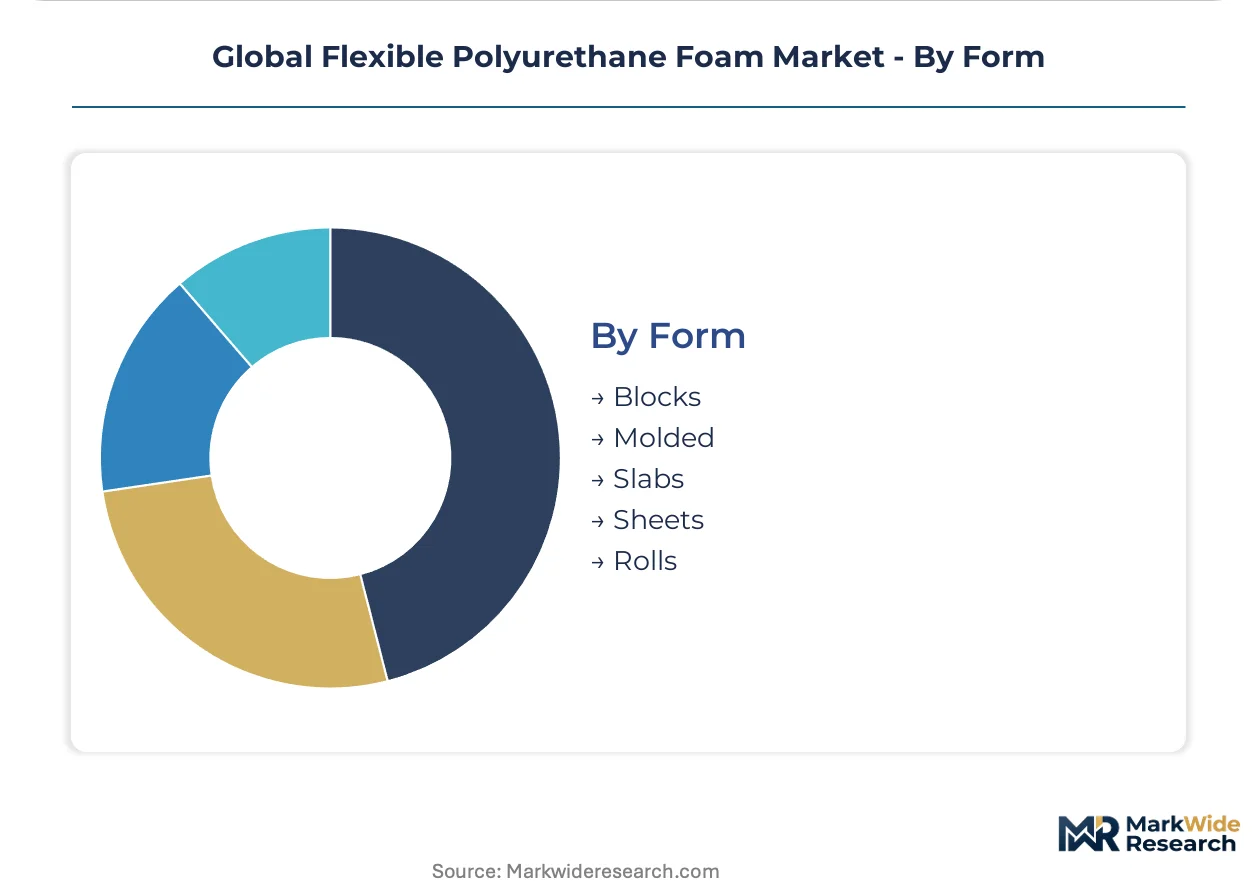
Form:
Capital intensity and technical capability requirements escalate from simple blocks to precision-molded components, filtering competitive participation across form categories.
- Molded:Custom-shaped components produced through reaction injection molding capture premium positioning in automotive seating, medical devices, and ergonomic furniture where complex geometries and consistent skin formation are specified. The form requires the highest capital investment in tooling and process control systems.
- Slabs:Continuous pour operations produce large buns for fabrication into cushions and mattresses, representing the most efficient scale economics but the thinnest margin pools due to commoditized competition.
- Blocks:Discrete bun production serves smaller fabricators and specialty applications.
- Sheets:Skived or cast thin sections address laminating and surface applications.
- Rolls:Continuous thin foam serves packaging and industrial bonding operations.
Slabs generate the highest throughput volumes while molded forms expand most quickly in value contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production incentives and localization mandates are redirecting capital flows toward manufacturing hubs with expanding domestic demand. Governments in China, India, and Mexico are deploying industrial policy tools to capture foam value chain segments previously concentrated in mature economies. Regulatory divergence on chemical disclosure and emissions standards is fragmenting compliance architectures across jurisdictions.
China
Domestic automotive seating programs and furniture manufacturing expansion are absorbing record volumes of slabstock and molded grades. The MEE enforces wastewater and air-quality standards that have idled smaller polyol units in the Yangtze River Delta, concentrating supply among state-backed integrated producers. Shanghai and surrounding Jiangsu province host the densest cluster of foam compounders serving both export markets and local OEMs.
Germany
Automotive tier-one seating manufacturers specify high-resilience molded systems with narrow indentation force deflection tolerances. REACH chemical disclosure mandates and evolving VOC tracking requirements compound formulation investment costs for exporters. The Ludwigshafen chemical complex anchors European isocyanate supply, with BASF SE maintaining integrated TDI and MDI production serving compounders across the continent.
United States
Commercial furniture fleet buyers consolidate vendor relationships around suppliers offering take-back programs for end-of-life foam recovery. EPA Clean Air Act provisions regulate VOC emissions from manufacturing operations, with California advancing extended producer responsibility frameworks through state legislation. The Southeast automotive corridor and Texas chemical manufacturing belt concentrate molding operations and polyol production capacity.
India
OEM localization requirements under the PLI scheme create demand for molded high-resilience foam systems currently imported from East Asian suppliers. BIS standards and evolving chemical handling protocols extend facility qualification timelines for new production lines. The Chennai-Bengaluru automotive belt and Gujarat chemical manufacturing zones are attracting compounder investment to serve domestic seating programs.
Mexico
Asset-light leasing models for polyol storage and blending equipment are lowering capital barriers for regional compounders serving US automotive and furniture supply chains. The country's proximity to US manufacturing customers supports just-in-time delivery requirements for molded seating components. Nuevo León and the Bajío Region concentrate foam fabrication operations integrated with tier-one automotive supplier parks.
Global Flexible Polyurethane Foam Market Competitive Landscape
On the supply side, the industry is consolidating around integrated chemical producers with captive aromatics supply and specialized compounders with formulation flexibility. Three archetypes dominate: integrated polyurethanes chains with feedstock cost advantages, regional compounders leveraging asset-light equipment leasing, and automotive-focused molders with IATF-certified quality systems. Competitive moves center on backward integration into polyol production and geographic expansion into high-growth manufacturing hubs.
Within the integrated chemical producer tier, BASF SE anchors European supply through large-scale production complexes, while Dow competes on formulation flexibility for automotive applications. Huntsman Corporation exemplifies the multi-continental integrated model. Among specialized compounders, Recticel and INOAC Corporation occupy positions in molded foam systems for transportation seating, with the latter representing Japanese precision manufacturing archetypes. Covestro and Sekisui Chemical Co., Ltd. sit within the materials science tier, supplying intermediates and differentiated foam grades to downstream fabricators.
| Leading Market Players |
|---|
| Covestro |
| Woodbridge Group |
| BASF SE |
| Sekisui Chemical Co., Ltd. |
| Rogers Corporation |
| Huntsman Corporation |
| Recticel |
| INOAC Corporation |
| Dow |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese slabstock production is compressing regional compounder margins while simultaneously accelerating price competition in export markets, forcing integrated producers to prioritize formulation differentiation over volume capture.
Pricing Analysis
Certification level creates the primary spread between automotive-grade molded systems and commodity furniture slabstock, with IATF-certified producers commanding substantial premiums over uncertified regional compounders. Three-tier pricing structure separates premium viscoelastic medical grades from standard high-resilience automotive formulations and economy polyether cushion cores. Cost compression in Chinese slabstock exports is intensifying because Yangtze River Delta environmental enforcement has idled smaller producers, concentrating supply among state-backed integrated players. Furniture manufacturers in Mexico and Southeast Asia exhibit the highest price sensitivity, while German and Japanese automotive tier-one suppliers prioritize batch consistency over unit cost.
Supply Chain Analysis
Export-control scrutiny on advanced polyol catalyst technologies limits technology transfer to certain manufacturing jurisdictions, constraining formulation capability diffusion. Feedstock supply concentrates in Germany, China, and the United States, with Ludwigshafen, Shanghai, and the Texas chemical belt anchoring global TDI and MDI production. Raw material flows draw from benzene derivatives, propylene oxide, and specialty amine catalysts. Single-source vulnerability runs through integrated aromatics complexes, where outages cascade immediately to downstream foam compounders lacking captive supply. Distribution runs through regional blending hubs serving just-in-time automotive seating programs and bulk slabstock shipments to furniture fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical disclosure mandates and California extended producer responsibility frameworks are disrupting established competitive positions, rewarding early movers in cleaner formulation capabilities and circular recovery systems.
For Market Incumbents: Insulate automotive seating margins through captive polyol production and accelerated phosphorus-based flame retardant qualification ahead of compliance deadlines. Natural latex substitution in premium bedding segments threatens polyurethane share, requiring bio-based polyol partnerships to defend positioning. Backward integration into agricultural feedstock supply secures renewable content credentials for European and North American mattress brands. For New Entrants and Emerging Players: Mid-market molded foam systems for India's domestic automotive seating programs represent the most penetrable entry point, given PLI localization requirements and current import dependence from East Asian suppliers. Asset-light polyol blending equipment leasing in Mexico's Bajío Region enables rapid market entry without capital-heavy balance sheet commitments. Partner with established tier-one supplier parks to bypass lengthy OEM qualification cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across regional compounder tiers as equipment leasing models proliferate, compressing returns for asset-heavy producers while elevating formulation-specialist valuations. Acquisition targets should display reactive phosphorus chemistry capabilities and established automotive certification pipelines. Monitor California and EU organohalogen flame retardant restriction implementation timelines as inflection indicators for R&D spending redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polyol Production | Soybean and castor oil supply partnerships secure renewable content credentials for furniture and automotive customers. |
| Phosphorus-based Flame Retardant R&D Acceleration | Reactive polyol integration maintains export access ahead of REACH and California compliance deadlines. |
| Asset-light Regional Blending Hub Expansion | Leased storage and mixing infrastructure lowers entry barriers in Mexico and Southeast Asia growth markets. |
| End-of-life Foam Recovery Program Development | Take-back systems align with California and New York extended producer responsibility procurement preferences. |
| IATF Certification Investment for Automotive Tier-one Access | Quality system credentials unlock multi-year platform contracts with German and Japanese OEMs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with foam compounder technical directors, automotive tier-one procurement managers, and furniture brand supply chain leads; and secondary validation through customs trade data, ACC and Cefic industry reports, and SEC filings from integrated chemical producers. Bottom-up volume estimates from regional production capacity and top-down demand segmentation from end-use consumption patterns were triangulated to reconcile figures.
Forecast inputs span grade tier differentiation, end-use industry application, manufacturing form factor, and regional production hub clustering across the projection horizon. CAGRs were derived from elasticity-adjusted demand modeling incorporating automotive seating content per vehicle, furniture production growth, and bedding replacement cycle dynamics. Feedstock cost volatility scenarios and regulatory compliance cost trajectories inform scenario-weighted outputs.
Practitioners should monitor REACH implementation timelines, California extended producer responsibility legislative progression, and Yangtze River Delta environmental enforcement intensity for early signals of forecast revision. Material shifts in organohalogen flame retardant restriction scope or bio-based feedstock cost competitiveness would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Calendering Resins Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Polysiloxane Market