
 Thermoplastic Polyolefin Market | 2026-2036
Thermoplastic Polyolefin Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Polyolefin Market Outlook
The EU Green Deal is repositioning European automotive OEM procurement criteria toward lower-carbon thermoplastic compounds. ExxonMobil Corporation leverages integrated polyolefin production to supply certified low-emission grades directly to major assemblers. SABIC anchors its competitive stance through specialized polypropylene compounds engineered for exterior cladding durability. Dow Inc. differentiates via advanced catalyst technologies that narrow molecular weight distribution in TPO blends.
Thermoplastic polyolefin denotes a polymer alloy combining polypropylene with ethylene-propylene rubber, typically containing 20-40% elastomer content by weight, produced through reactive extrusion or dynamic vulcanization to achieve rubber-like flexibility with thermoplastic processability. The material serves primarily as a lightweight substitute for conventional rubbers and engineering plastics in impact-resistant applications. Polypropylene leads product type demand due to its cost-efficiency and recyclability profile, while thermoplastic elastomers capture the fastest expansion as automakers pursue softer-touch interior surfaces. Automotive exteriors concentrate margin pools where paintability and UV resistance command specification premiums.
The EPA enforces VOC emission thresholds that restrict solvent-based adhesive formulations, indirectly steering specification toward hot-melt TPO bonding systems. REACH and RoHS compliance requirements in Europe compel reformulation of flame-retardant additives within roofing membrane grades. Japan's METI maintains JIS standards for automotive interior air quality that filter non-compliant compound suppliers from Japanese OEM supply chains. Stakeholders must monitor evolving Extended Producer Responsibility frameworks that will penalize non-recyclable multi-layer structures.
Market Dynamics
Automotive OEMs are compressing vehicle weight targets to meet fleet emission mandates, redirecting specification volumes toward reinforced thermoplastic compounds that substitute metal body panels without sacrificing impact resistance.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are eliminating incumbent foam insulation materials, opening specification pathways for TPO-based thermal barriers in commercial building envelopes.
- Automotive lightweighting mandates:CAFE standards and parallel EU CO2 fleet targets are compelling exterior panel redesigns that favor paintable TPO grades over sheet metal in bumper fascias and fender liners.
- Ethylene-propylene rubber supply expansion:Gulf Coast petrochemical complexes are adding metallocene EPR capacity, improving feedstock availability for compounders serving North American automotive clusters.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and PDH unit operating rates create input cost instability that compresses compounder margins during crude price swings.
- Specialized catalyst concentration:Single-digit producers control advanced Ziegler-Natta and metallocene systems for narrow MWD TPO grades, creating supply security exposure for tier-two compounders.
- Paint adhesion limitations:Low surface energy of polypropylene-rich substrates requires flame or plasma pretreatment, adding process cost that favors incumbent painted metal in premium vehicle segments.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for electric vehicle manufacturing are attracting TPO compounders to establish compounding operations near Chennai and Pune assembly plants.
- RoHS-driven flame retardant reformulation:European roofing membrane specifications are transitioning from halogenated to phosphorus-nitrogen systems, rewarding compounders with certified low-smoke TPO grades.
- Reactive extrusion-molding convergence:Integration of twin-screw compounding with direct injection molding is eliminating pelletization steps, enabling on-site material production at high-volume automotive stamping facilities.
Industry Challenges
- Color-matching competency scarcity:OEM exterior specification requires masterbatch formulation expertise that concentrates among a limited pool of technical service engineers, constraining compounder expansion timelines.
- Multi-material recycling complexity:Extended Producer Responsibility frameworks in Germany and France are penalizing non-separable TPO-PP-EPR structures, forcing redesign of interior soft-touch components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Polyolefin Market |
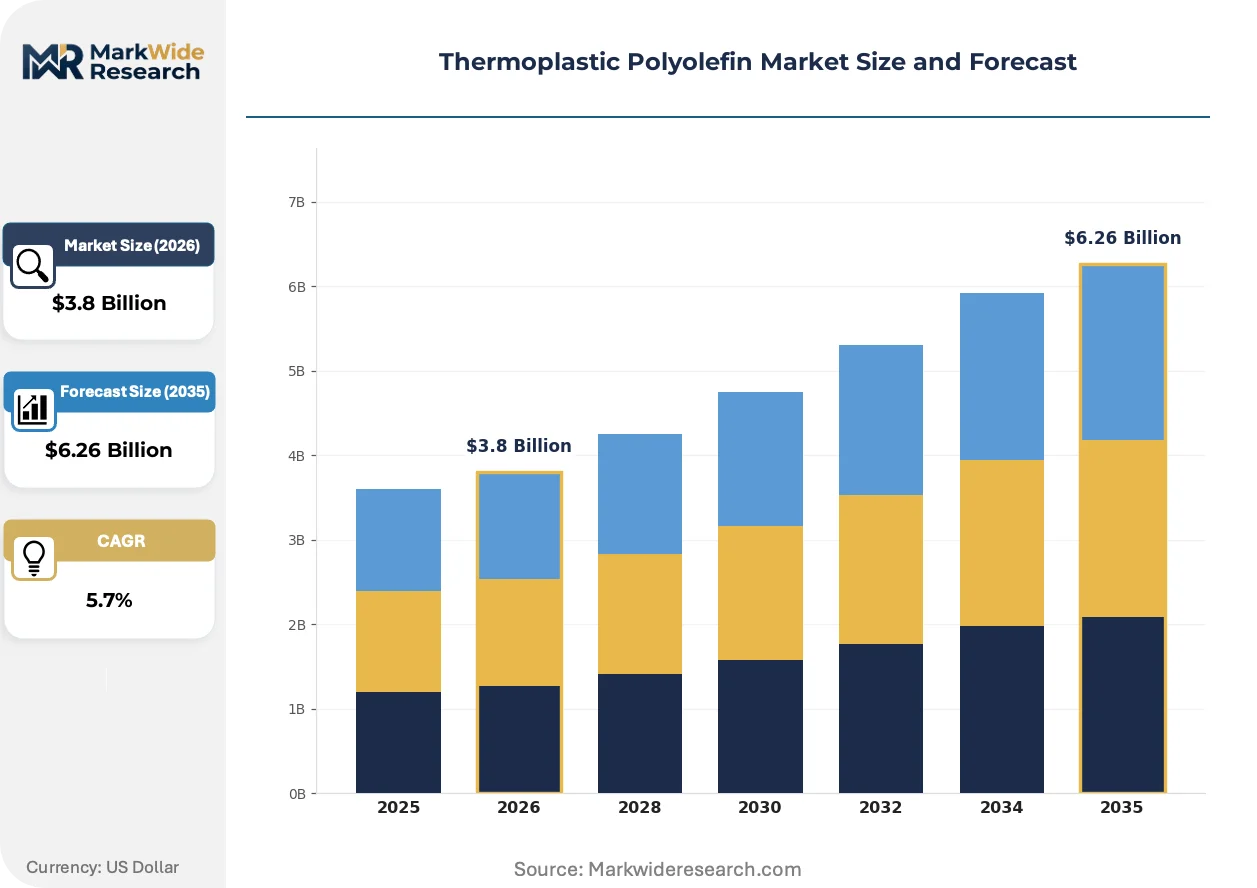
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Elastomers, Polyethylene, Polypropylene, Polyolefin Blends Application: Automotive Interiors, Roofing Membranes, Adhesives, Automotive Exteriors End User: Manufacturing, Automotive OEMs, Construction, Packaging Industry Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | ExxonMobil Corporation, SABIC, LyondellBasell Industries, Dow Inc., INEOS Olefins & Polymers, Borealis AG, Mitsui Chemicals, Inc., Sumitomo Chemical Co., Ltd., Arkema SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Polyolefin Market Strategic Shifts
Reactive processing technologies are collapsing traditional boundaries between compounding and conversion, enabling material formulation at the point of manufacturing rather than through centralized pellet supply chains.
Dynamic vulcanization using continuous mixing reactors is decentralizing TPO production geography. Tier-one automotive suppliers in Michigan and Bavaria are installing in-house compounding lines that bypass merchant compounder networks. This distributed manufacturing model compresses logistics costs and accelerates formulation iteration cycles for model-year changeovers.
REACH authorization requirements for persistent organic pollutants are restructuring additive supply chains. ECHA scrutiny of halogenated flame retardants is compelling roofing membrane producers to validate phosphorus-based alternatives through multi-year weathering protocols. German construction certification bodies are prioritizing TPO grades with third-party verified emission profiles for public infrastructure tenders.
Specification authority is migrating from OEM engineering centers to sustainability procurement offices. Volkswagen and Stellantis are embedding recycled content thresholds into TPO supplier scorecards that override traditional performance-price metrics. This behavioral shift is most visible in French and Italian automotive clusters where regulatory pressure for circular economy compliance exceeds technical specification rigor.
Thermoplastic Polyolefin Market Segmentation
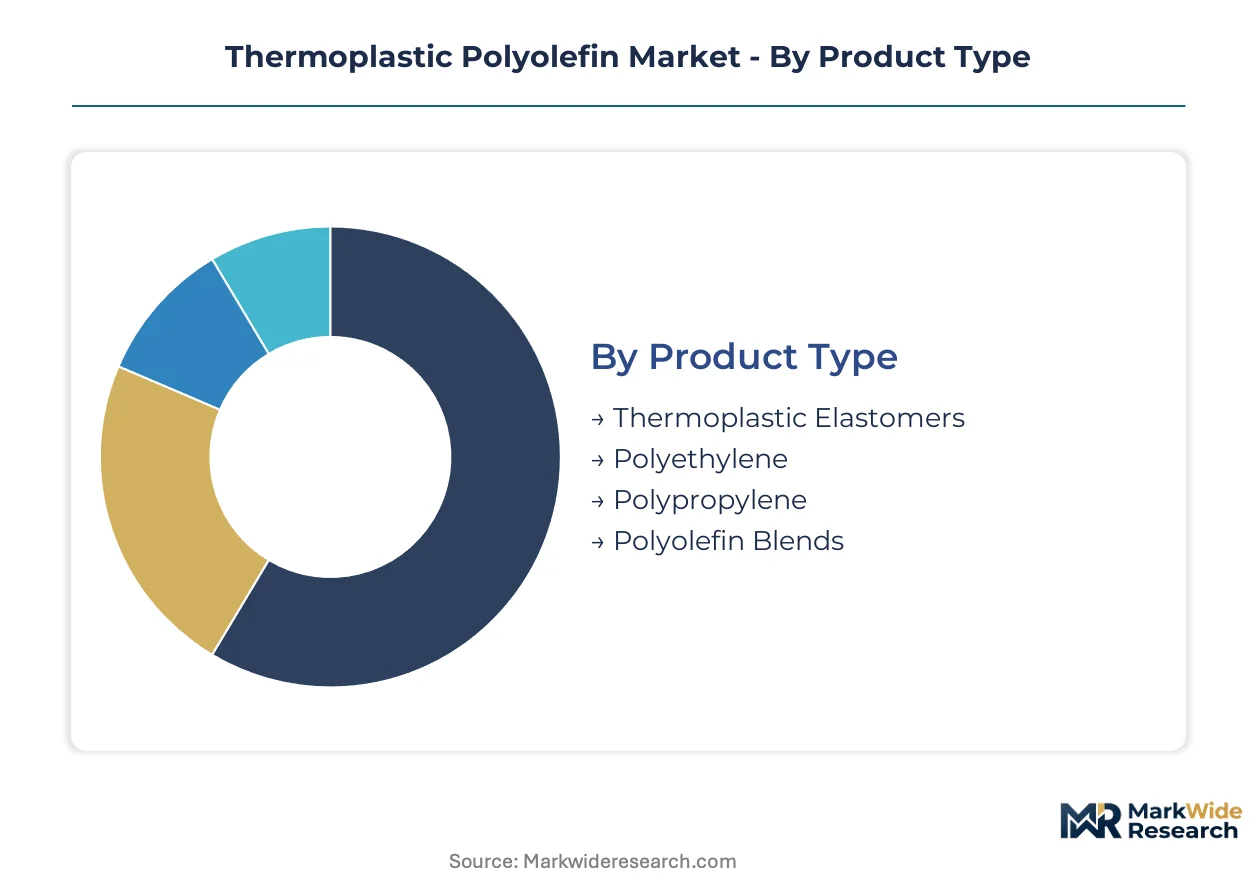
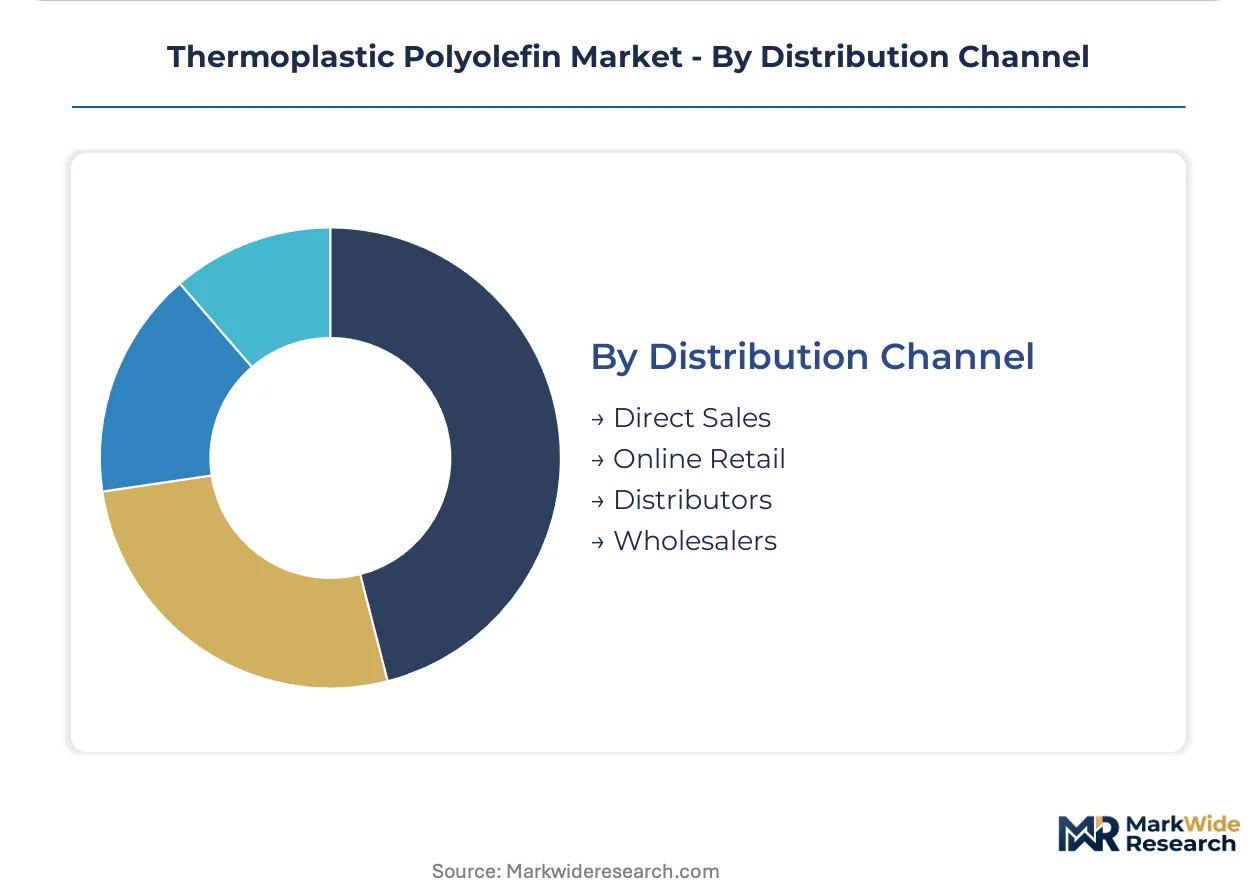
TPO segmentation reveals how material specifications diverge across automotive, construction, and industrial applications. Each dimension—product chemistry, application performance, end-user procurement, and channel structure—shapes margin capture and supply chain configuration differently.
Product Type:
Specialized catalyst systems and reactor technology concentrate among integrated polyolefin producers, creating tiered supply security for compounders.
- Polypropylene:Base resin comprising 60-80% of typical TPO formulations by weight, offering cost-efficiency and established recycling infrastructure. Demand clusters in German and Czech automotive manufacturing corridors where OEMs specify high-flow grades for thin-wall exterior panels under EU CO2 fleet mandates.
- Thermoplastic Elastomers:Ethylene-propylene rubber domains dispersed in polypropylene matrix deliver rubber-like flexibility with thermoplastic processability. Japanese OEM procurement through METI-certified supply chains prioritizes low-VOC TPE grades for soft-touch instrument panels.
- Polyethylene:Lower-density modifier improving impact resistance at sub-zero temperatures for roofing membrane applications.
- Polyolefin Blends:Custom reactor-grade alloys engineered for paint adhesion without flame pretreatment in premium automotive segments.
Polypropylene absorbs the bulk of installed capacity; thermoplastic elastomers are expanding most quickly.
Application:
Performance specifications vary sharply between visible exterior surfaces and concealed structural components.
- Automotive Exteriors:Paintable TPO grades replacing metal in bumper fascias and fender liners demand UV stability and coefficient of linear thermal expansion matching steel substrates. Stellantis and Volkswagen engineering centers in Turin and Wolfsburg specify these grades for lightweighting compliance.
- Automotive Interiors:Soft-touch surfaces for instrument panels and door trims require low-gloss aesthetics and fogging resistance. METI JIS standards filter supplier qualification for Japanese OEM supply chains.
- Roofing Membranes:Single-ply TPO sheets gaining share from EPDM in commercial building envelopes under EU F-Gas Regulation phase-down schedules.
- Adhesives:Hot-melt formulations displacing solvent-based systems as EPA VOC thresholds tighten in US manufacturing.
Automotive exteriors command specification premiums; roofing membranes are climbing the fastest as building codes shift.
End User:
Procurement authority concentrates with OEM sustainability offices rather than traditional engineering functions.
- Automotive OEMs:Direct material specification with embedded recycled content thresholds overriding price-performance metrics. French and Italian clusters lead circular economy compliance rigor.
- Construction:German certification bodies prioritize third-party verified emission profiles for public infrastructure tenders.
- Manufacturing:Industrial equipment producers sourcing impact-resistant housings.
- Packaging Industry:Niche flexible packaging applications requiring thermoplastic processability.
Automotive OEMs dominate volume absorption; construction end-use is gaining share fastest on regulatory tailwinds.
Distribution Channel:
Channel structure reflects the tension between centralized compounding economies and distributed manufacturing imperatives.
- Direct Sales:Integrated producers like ExxonMobil supply certified low-emission grades directly to major assemblers, bypassing merchant compounder networks.
- Distributors:Technical service engineers at regional distributors provide color-matching competency scarce among tier-two compounders.
- Wholesalers:Bulk volume handlers for standardized roofing membrane grades.
- Online Retail:Emerging channel for specialty adhesive formulations in small-lot industrial procurement.
Direct sales capture the majority of automotive volume; distributor relationships are deepening fastest where technical service creates switching costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wolfsburg anchors European TPO specification authority through Volkswagen's engineering center, where CO2 fleet compliance drives exterior panel lightweighting mandates across multiple continents.
United States
Detroit's automotive corridor concentrates North American TPO demand as Ford and General Motors redesign pickup truck bumpers for CAFE standard compliance. EPA VOC thresholds steer adhesive specifications toward hot-melt TPO bonding systems. Gulf Coast petrochemical complexes near Houston expand metallocene EPR capacity, improving feedstock security for regional compounders.
Germany
Stuttgart and Munich manufacturing clusters drive specialized compound consumption for premium exterior applications. EU F-Gas Regulation phase-down schedules eliminate incumbent foam insulation materials, opening specification pathways for TPO-based thermal barriers. German certification bodies prioritize third-party verified emission profiles for public infrastructure tenders.
China
Yangtze River Delta automotive plants specify paintable TPO grades for electric vehicle platforms under MIIT dual carbon goals. Shanghai-based OEM procurement offices embed recycled content thresholds into supplier scorecards. Local compounders establish operations near Ningbo and Suzhou assembly facilities to compress logistics costs.
Japan
Nagoya's Toyota engineering centers filter TPO suppliers through METI JIS standards for automotive interior air quality. Osaka-based chemical producers develop low-VOC thermoplastic elastomer grades for soft-touch instrument panels. Japanese OEM supply chains exclude non-compliant compounders through rigorous certification protocols.
India
Chennai and Pune assembly plants attract TPO compounders establishing localized operations under PLI scheme electric vehicle incentives. BIS standards for automotive materials compel reformulation of flame-retardant additives. Domestic producers leverage proximity to Maruti Suzuki and Hyundai Motor India manufacturing clusters.
Thermoplastic Polyolefin Market Competitive Environment
Premium-margin players sit above commodity-margin players across catalyst technology and certified low-emission grade supply. The vendor base separates into three tiers: integrated polyolefin producers controlling reactor technology, specialized compounders with color-matching competency, and regional distributors providing technical service. Consolidation pressure intensifies as automotive OEMs reduce approved supplier lists. Two dominant competitive moves define current positioning: direct sales relationships bypassing merchant compounder networks, and in-house compounding line installations at tier-one automotive suppliers.
Among integrated producers, ExxonMobil Corporation and SABIC exemplify the premium-tier archetype through certified low-emission grade supply and specialized polypropylene compound engineering respectively. Dow Inc. occupies a position within the advanced catalyst technology segment. These three entities anchor the competitive structure through differentiated reactor capabilities and direct OEM relationships that create switching costs for downstream customers.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| SABIC |
| LyondellBasell Industries |
| Dow Inc. |
| INEOS Olefins & Polymers |
| Borealis AG |
| Mitsui Chemicals, Inc. |
| Sumitomo Chemical Co., Ltd. |
| Arkema SA |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM sustainability procurement offices concentrate specification authority for certified low-emission TPO grades, compressing compounder margins through recycled-content thresholds that override traditional price-performance negotiations. This buyer concentration forces three-tier pricing stratification across premium certified grades, standard automotive specifications, and economy roofing membrane tiers.
Pricing Analysis
Paint adhesion performance without flame pretreatment anchors value-based pricing premiums in premium automotive exterior segments. Price differentiation separates OEM-certified low-emission grades from merchant-compounded standard grades and bulk roofing membrane tiers. Cost compression in standard automotive grades is intensifying because Gulf Coast EPR feedstock volatility transmits directly to compounder margins. Tier-one automotive suppliers exhibit lowest price sensitivity due to embedded sustainability scorecard requirements, while construction wholesalers face highest sensitivity on standardized membrane specifications.
Supply Chain Analysis
Single-source vulnerability sits with advanced Ziegler-Natta and metallocene catalyst systems controlled by single-digit integrated producers in the United States, Saudi Arabia, and Germany. Feedstock supply draws from naphtha-cracking complexes and PDH units concentrated on the US Gulf Coast and in Northwest Europe. Tariff exposure on EPR imports from Asia creates supply security risk for North American compounders lacking backward integration. Distribution runs through direct sales relationships for automotive OEMs and regional distributors providing scarce color-matching technical service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as automotive OEMs slash approved supplier lists, forcing tier-two compounders without certified low-emission grades or color-matching competency into exit or acquisition.
For Market Incumbents: Anchor competitive position through captive catalyst technology supply and direct OEM relationships that create switching costs. Integrated producers should deepen backward integration into metallocene EPR production to secure feedstock margins against PDH unit volatility. Defensive moves must prioritize sustainability certification investment as Volkswagen and Stellantis embed recycled-content thresholds into supplier scorecards. For New Entrants and Emerging Players: E-commerce platforms for specialty adhesive formulations offer the lowest barrier route into TPO downstream markets. White-space targets cluster in India's PLI scheme electric vehicle corridors near Chennai and Pune, where localized compounding operations bypass established merchant networks. Technical service partnerships with regional distributors overcome color-matching competency scarcity that constrains direct OEM qualification timelines. For Investors and Strategic Acquirers: The window for entry favors specialized compounders with certified low-emission grades and established Japanese OEM supply chain access. Acquisition targets should demonstrate proven formulation iteration capabilities for model-year changeover cycles. Watch for REACH authorization decisions on halogenated flame retardants as inflection indicators for roofing membrane grade restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallocene EPR | Gulf Coast producers secure feedstock margins against PDH unit volatility swings. |
| Reactive Extrusion-Molding Convergence | Tier-one suppliers in Michigan and Bavaria eliminate pelletization logistics costs entirely. |
| RoHS-Driven Flame Retardant Reformulation | European roofing membrane producers validate phosphorus-nitrogen systems through ECHA protocols. |
| Direct OEM Sustainability Partnerships | ExxonMobil bypasses merchant compounder networks with certified low-emission grade supply. |
| India PLI Scheme Localization | Compounders establish operations near Maruti Suzuki and Hyundai Motor India assembly clusters. |
Study Parameters
SEC 10-K filings, customs and trade data from ACC and Cefic, and vehicle production databases formed the secondary backbone for this analysis. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, technical R&D directors at integrated polyolefin producers, and roofing membrane specification consultants combined with secondary validation. Bottom-up segmentation modeling and top-down macroeconomic trend analysis enabled triangulation across data sources.
Historical trendline analysis established baseline growth patterns across the projection horizon. The analytical framework modeled segmentation dimensions including product chemistry grade, end-use application performance tier, automotive OEM procurement cluster, and regional production hub. CAGRs were derived through regression analysis of volume trajectories incorporating feedstock cost pass-through elasticity and regulatory compliance timeline acceleration.
The model holds under stable naphtha-cracking economics and continued EU F-Gas Regulation phase-down schedules; deviation in propylene feedstock volatility or REACH authorization timelines would shift compounder margin projections. Forecasts reflect assumptions about automotive lightweighting mandate stringency and recycling infrastructure development. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
India Engineering Plastics Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Bio-Based Construction Polymers Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Cellulosic Polymers Market