
 Automotive Thermoplastic Polymer Composites Market | 2026-2036
Automotive Thermoplastic Polymer Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Thermoplastic Polymer Composites Market Outlook
Tier-1 supplier consolidation around large-platform EV programs is realigning procurement volumes toward fewer, higher-volume contracts. BASF SE leverages its integrated polyamide supply chain to capture specification-influence at the resin stage. Toray Industries, Inc. anchors its position through carbon fiber-reinforced thermoplastic prepreg capacity serving structural applications. SABIC competes on polycarbonate blends optimized for electrical housing thermal management in next-generation vehicle architectures.
Automotive thermoplastic polymer composites are fiber-reinforced thermoplastic matrices—typically polyamide, polypropylene, or polycarbonate base resins with glass or carbon fiber loadings of 20-60% by weight—processed via injection molding or compression molding to achieve strength-to-weight ratios exceeding conventional metals while enabling end-of-life recyclability. Their primary purpose is mass reduction in vehicle structures and components without sacrificing crash performance or design flexibility. Polyamide dominates current volumes due to its heat resistance and compatibility with under-hood applications, while polycarbonate blends command margin pools in electrical housing where flame retardancy and dimensional stability carry premium pricing. Injection molding sustains its manufacturing share for high-volume interior and exterior components, though compression molding gains traction for larger structural parts where fiber orientation control proves critical.
Europe's REACH regulation and ELV directive mandate recyclability rates and restricted substance limits that directly shape material selection and composite formulation strategies for suppliers serving EU markets. The EPA in the United States enforces fuel economy standards that indirectly accelerate lightweight material substitution across vehicle platforms. China's MIIT implements new energy vehicle mandates with domestic content requirements that influence thermoplastic composite sourcing decisions for manufacturers operating in that market. Stakeholders must monitor evolving battery enclosure standards and cross-border carbon border adjustment mechanisms that will determine which material systems and manufacturing locations retain cost-competitive access to major automotive markets.
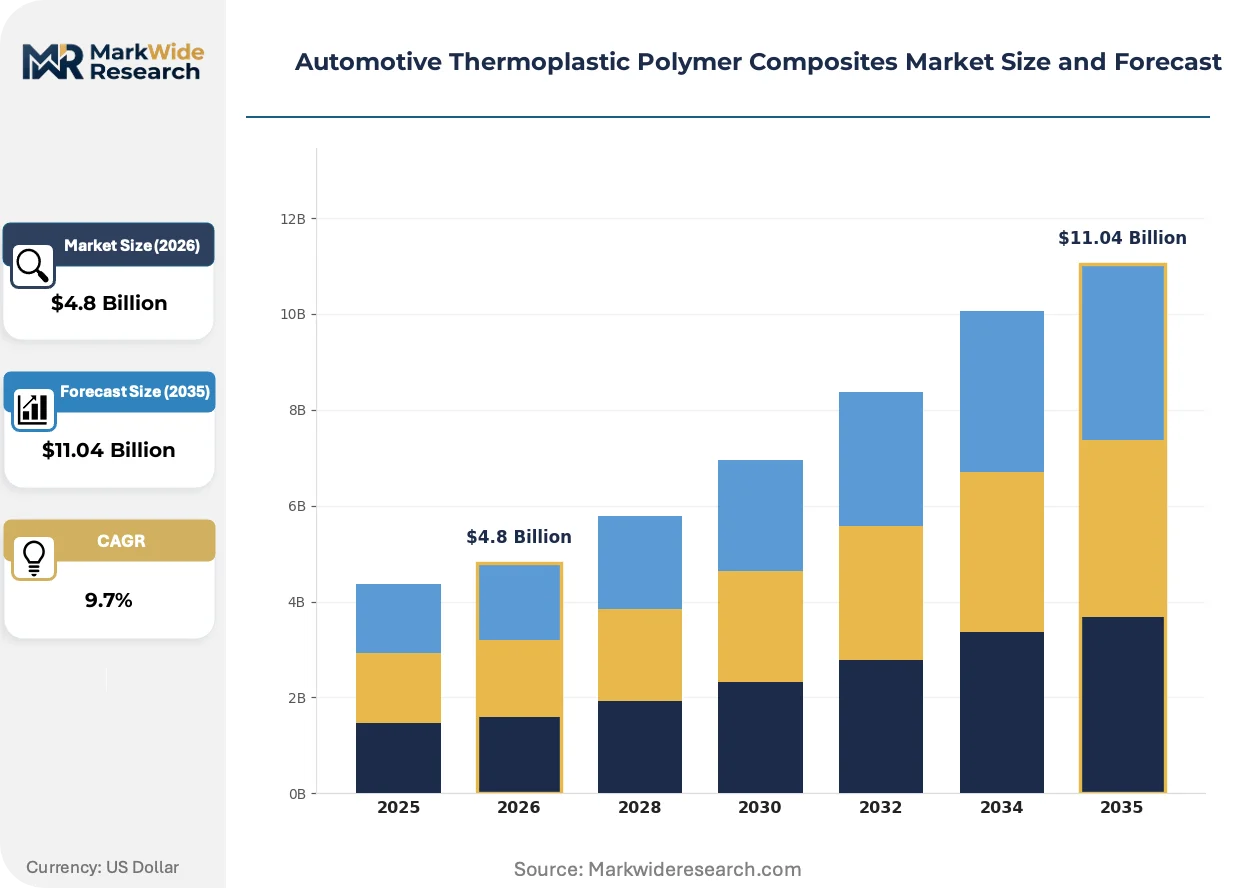
Market Dynamics
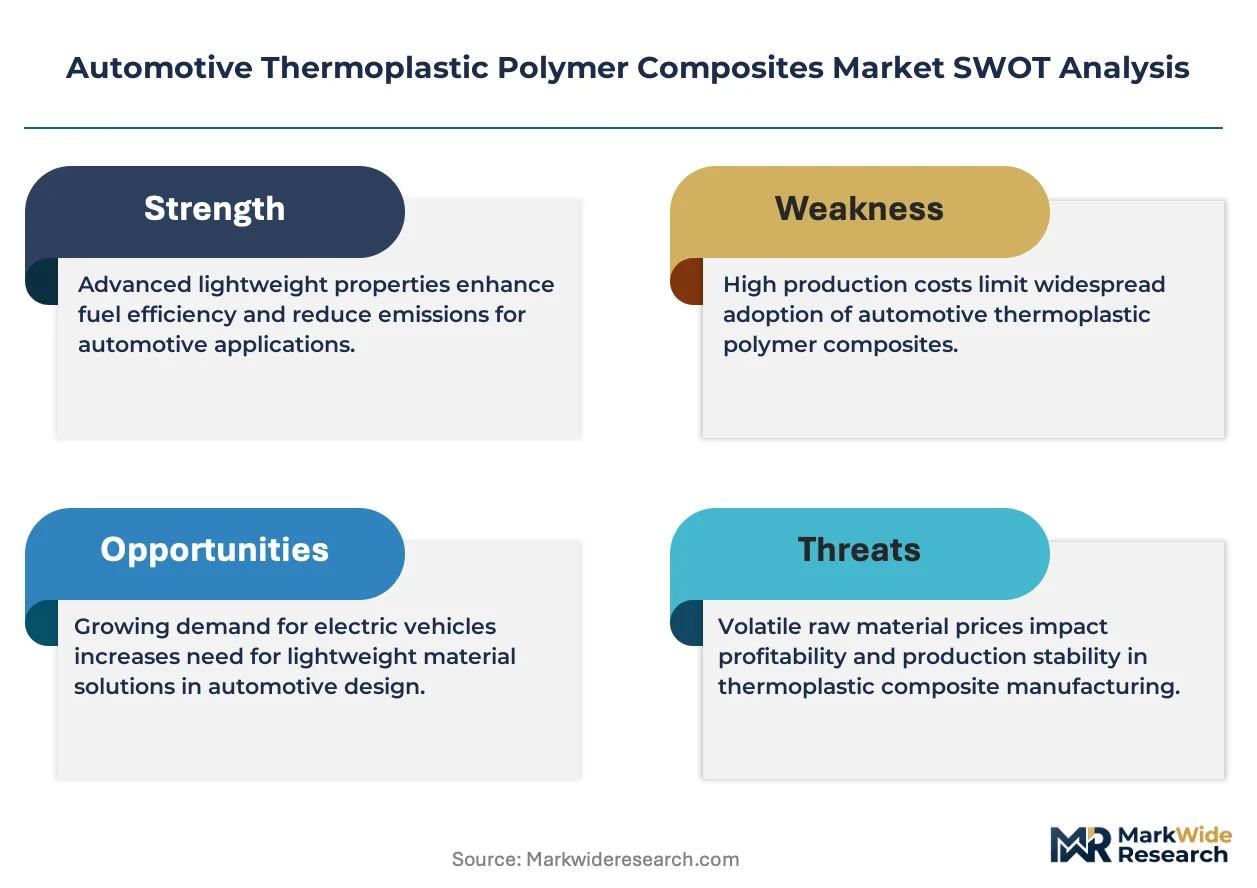
Electric vehicle platform architecture is compressing design cycles and forcing material specification decisions earlier in development, locking thermoplastic composites into long-term supply agreements before traditional metal alternatives complete validation.
Growth Catalysts
- EU ELV Directive recyclability mandates:End-of-life vehicle regulations in Europe require 85% material recovery rates, positioning thermoplastic composites as the only fiber-reinforced option meeting circular economy requirements without pyrolysis or chemical decomposition.
- Battery enclosure thermal management:Electric vehicle battery packs demand flame-retardant housings with dimensional stability across temperature swings, pulling polycarbonate and polyamide blends into structural electrical components previously served by metals.
- Germany's automotive manufacturing corridor:OEM headquarters and Tier-1 supplier clusters in Stuttgart, Munich, and Wolfsburg create concentrated specification influence where resin selection at the design stage cascades through global vehicle programs.
Market Restraints
- Carbon fiber feedstock concentration:Precursor supply and carbon fiber production capacity concentrate in Japan, the United States, and China, exposing European compounders to currency volatility and cross-border carbon adjustment mechanisms.
- REACH substance authorization timelines:ECHA's candidate list expansion and sunset date scheduling for critical additives and flame retardants create formulation uncertainty that extends qualification periods by 18-24 months.
- High-performance thermoplastic cost premiums:Polyamide 6.6 and PEEK base resins trade at 3-4x polypropylene pricing, constraining adoption in A-segment vehicles and emerging market platforms where bill-of-materials pressure intensifies.
Strategic Opportunities
- India PLI scheme for advanced materials:Production-linked incentive programs for automotive component manufacturing create localized compounding capacity opportunities serving domestic OEMs and export-oriented supplier parks.
- Structural battery enclosures:Cell-to-pack architectures eliminate modular housings and create demand for load-bearing composite panels that integrate crash management with electrical isolation functions.
- Recycled carbon fiber reclamation:Pyrolysis and solvolysis technologies converging with automotive shredder residue sorting systems enable cost-competitive recycled fiber feedstocks for non-structural interior applications.
Industry Challenges
- Simulation and predictive modeling talent scarcity:Fiber orientation prediction in injection molding and compression molding requires specialized CAE expertise that outpaces university polymer engineering program output.
- Multi-material joining certification:Adhesive bonding and mechanical fastening between thermoplastic composites and aluminum or steel substructures demand crash-test validation protocols that lack harmonization across NHTSA, KBA, and MIIT requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Thermoplastic Polymer Composites Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyamide, Polypropylene, Polyester, Polycarbonate Application: Interior Components, Exterior Components, Structural Parts, Electrical Housing Manufacturing Stage: Injection Molding, Compression Molding, Extrusion, 3D Printing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Automotive Design Firms |
| Companies Covered | Toray Industries, Inc., Teijin Limited, BASF SE, Hexcel Corporation, Mitsubishi Chemical Corporation, DuPont de Nemours Inc, Solvay SA, SABIC, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Thermoplastic Polymer Composites Market Strategic Shifts
Continuous fiber-reinforced thermoplastic tapes are migrating from aerospace qualification pathways into automotive series production, enabled by automated fiber placement and in-situ consolidation equipment scaled for 60-second cycle times.
Hybrid unidirectional tape-sandwich structures are integrating glass and carbon fiber-reinforced polyamide laminates into floor pans and seat structures. BMW and Porsche engineering teams specify these materials for secondary structural members where stiffness-to-weight ratios must exceed 6061 aluminum. The technology is integrating crash energy management with thermal joining compatibility for mixed-material vehicle architectures.
REACH authorization requirements for halogenated flame retardants are accelerating phosphorus-based and mineral filler alternatives in polycarbonate blends serving battery enclosures. ECHA's 2023-2025 sunset date clustering forces reformulation of electrical housing compounds ahead of new energy vehicle platform launches. German Tier-1 suppliers maintain dual-qualified material lines to ensure continuity across regulatory transition windows.
Fleet procurement contracts for electric vehicle platforms are consolidating specification authority at the platform-architecture level rather than component-sourcing level. Automotive OEMs in China's Yangtze River Delta region now mandate resin-grade pre-approval before supplier bid submission, compressing compounder influence windows and favoring integrated resin-to-composite suppliers with captive polymerization capacity.
Automotive Thermoplastic Polymer Composites Market Segmentation
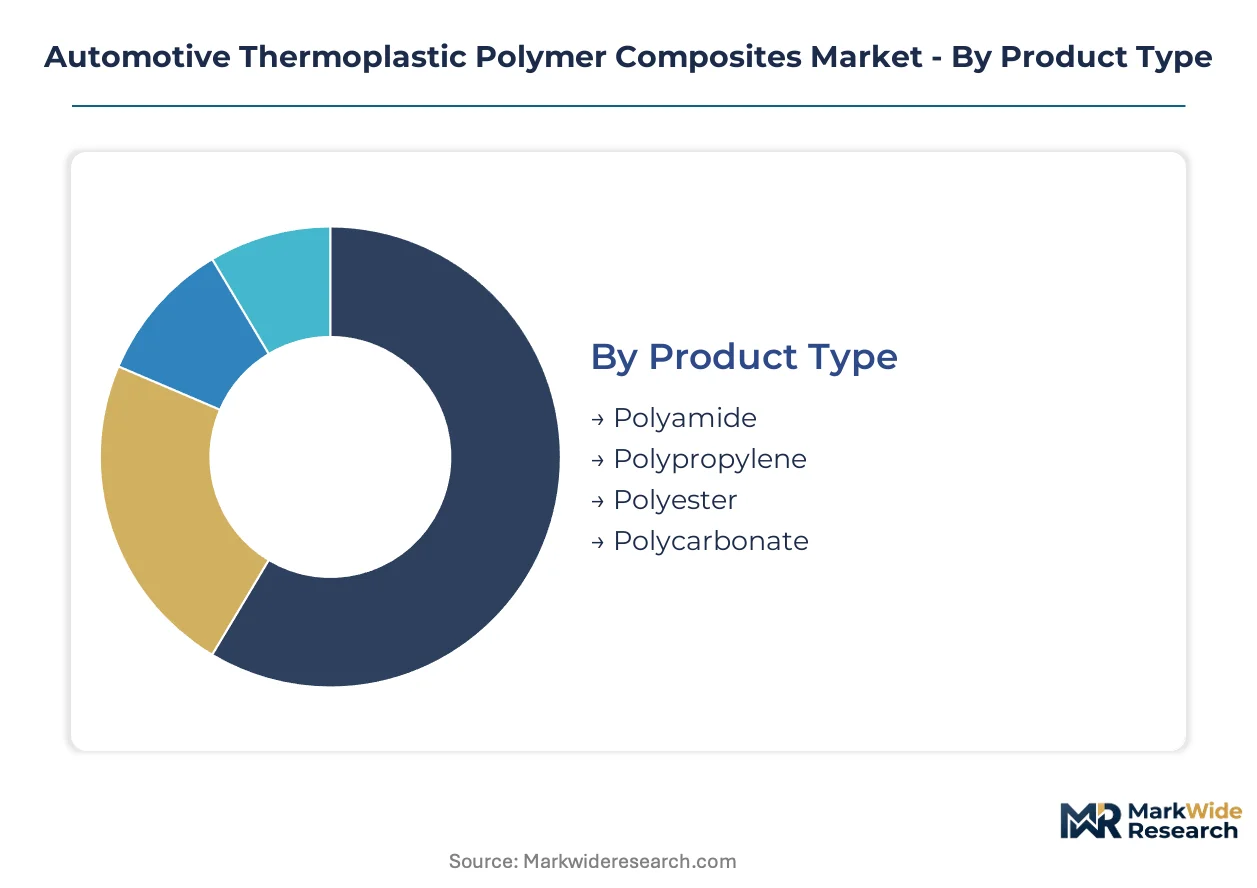
Thermoplastic polymer composite specifications cascade through automotive supply chains from resin selection through finished component qualification. Segmentation reveals where formulation decisions concentrate procurement power and where manufacturing technology choices lock in long-term cost structures.
Product Type:
Resin supply concentration in integrated petrochemical complexes determines regional formulation access and compounder margin capture.
- Polyamide:Glass and carbon fiber-reinforced polyamide 6 and 6.6 matrices dominate under-hood applications with continuous-use temperatures exceeding 150°C. German OEM specification committees in Stuttgart and Wolfsburg mandate polyamide grades for engine bay thermal management components, locking compounders into multi-year supply agreements.
- Polycarbonate:Flame-retardant blends with 20-30% glass fiber loading serve battery enclosure housings where electrical isolation and dimensional stability across thermal cycling prove critical. REACH authorization pressures on halogenated additives are forcing phosphorus-based formulation shifts that extend qualification timelines.
- Polypropylene:Cost-optimized compounds with 20-40% glass fiber reinforcement capture interior trim and non-structural exterior applications where heat resistance requirements moderate.
- Polyester:Saturated polyester thermoplastics occupy niche applications in lighting housings and select exterior components where UV resistance and surface finish quality justify material cost premiums.
Today's leader: Polyamide. Tomorrow's challenger: Polycarbonate.
Application:
Component location within vehicle architecture dictates performance specifications and manufacturing process selection.
- Interior Components:Door panels, instrument carriers, and seat structures utilize glass fiber-reinforced polypropylene and polyamide compounds processed via injection molding for 60-90 second cycle times. Tier-1 suppliers in Germany's automotive corridor concentrate procurement volumes for EV platform interiors.
- Structural Parts:Continuous fiber-reinforced thermoplastic tapes and compression-molded organosheets serve floor pans, cross-members, and crash structures where specific stiffness targets must exceed aluminum benchmarks. BMW and Porsche engineering specifications for secondary structural members are pulling carbon fiber-reinforced polyamide into series production.
- Exterior Components:Fenders, hoods, and liftgates employ long-fiber thermoplastic compounds where Class A surface requirements meet pedestrian impact regulations.
- Electrical Housing:Battery pack enclosures, junction boxes, and power electronics housings demand flame-retardant polycarbonate and polyamide blends with CTI tracking resistance for high-voltage isolation.
Structural applications are climbing the fastest as cell-to-pack architectures eliminate modular housings and create demand for load-bearing composite integration.
Manufacturing Stage:
Process technology selection hinges on fiber length retention, part geometry complexity, and production volume economics.
- Injection Molding:High-volume production of complex geometries with 20-40% short glass fiber compounds sustains manufacturing share for interior and exterior components. Tooling investments and cycle time optimization favor this process for A-segment through D-segment vehicle platforms.
- Compression Molding:Organosheet and glass mat thermoplastic processing for larger structural parts enables fiber orientation control critical to crash performance. Equipment scale-up for 60-second automotive cycle times is migrating aerospace-qualified tape laying technology into series production.
- Extrusion:Profile and sheet production for subsequent thermoforming serves bumper beams, underbody shields, and trim applications where linear stock geometry simplifies material handling.
- 3D Printing:Fused filament fabrication and selective laser sintering with chopped fiber-reinforced thermoplastics enable prototyping and low-volume tooling for motorsport and limited-production vehicle programs.
Injection molding retains volume dominance. Compression molding is gaining specification share for structural battery enclosure integration.
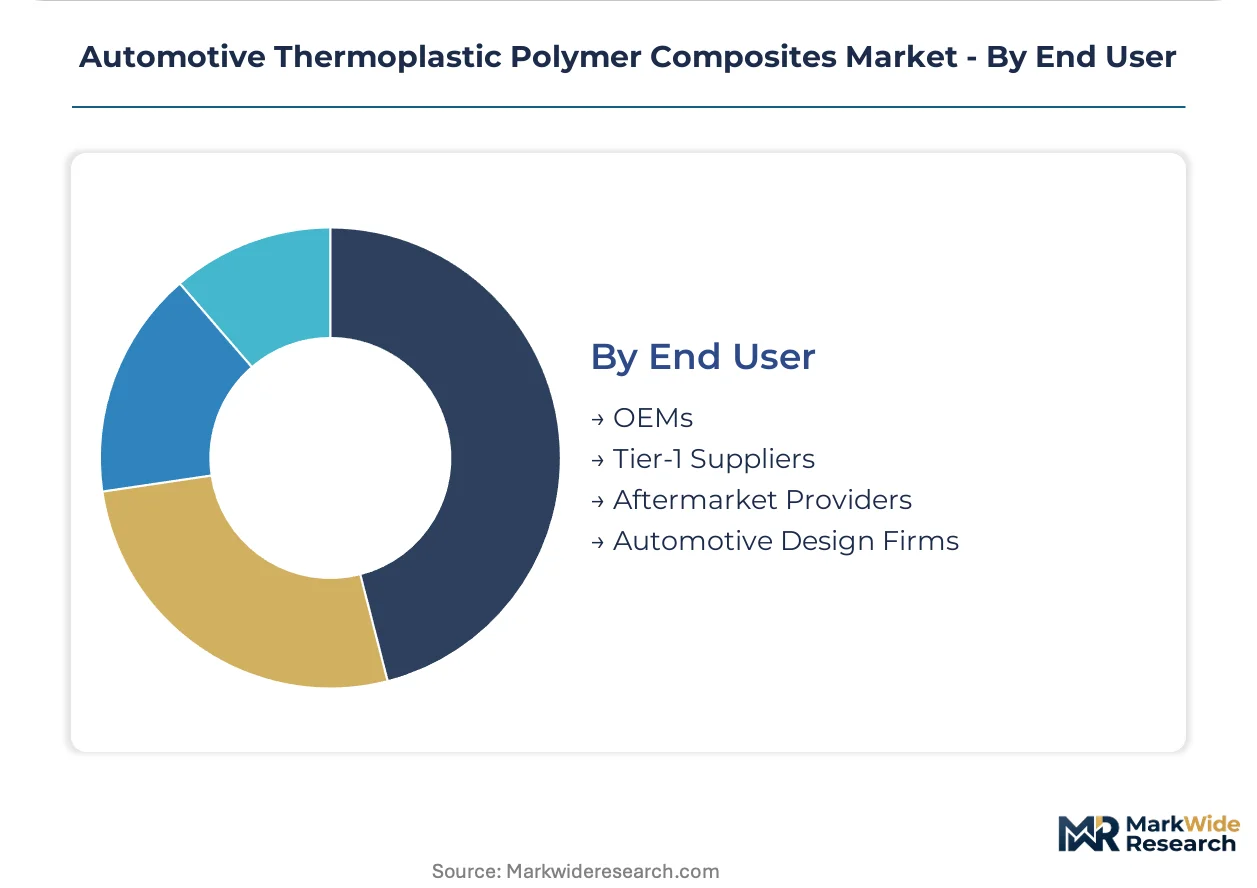
End User:
Specification authority concentration at the platform-architecture level is compressing compounder influence windows and favoring integrated suppliers.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz maintain resin-grade pre-approval mandates before supplier bid submission, capturing specification influence at the polymerization stage. Platform-level material decisions cascade through global vehicle programs.
- Tier-1 Suppliers:Continental, Bosch, and Magna consolidate procurement volumes around large-platform EV programs, realigning compounding contracts toward fewer, higher-volume agreements with qualification timelines extending 18-24 months.
- Aftermarket Providers:Collision repair and performance upgrade segments demand color-matched and specialty-grade compounds with lower minimum order quantities than OEM series production.
- Automotive Design Firms:Engineering consultancies and styling studios specify material systems during concept development, though manufacturing handoff to Tier-1 suppliers often drives formulation changes for process compatibility.
Tier-1 suppliers currently concentrate procurement volume. OEM direct material specification is expanding fastest as platform architectures consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor concentrates specification authority for thermoplastic composites, while China's Yangtze River Delta region drives volume expansion through domestic EV platform mandates.
Germany
Volkswagen Group, BMW, and Mercedes-Benz headquarters in Stuttgart, Munich, and Wolfsburg lock resin-grade specifications into multi-year supply agreements. KBA enforces type-approval protocols that extend qualification timelines for new composite formulations. The Baden-Württemberg and Bavaria industrial clusters host Tier-1 supplier engineering centers where material selection decisions cascade through global vehicle programs.
China
MIIT's new energy vehicle mandates with domestic content requirements accelerate thermoplastic composite integration into battery enclosures and structural components. The Yangtze River Delta region concentrates OEM platform engineering teams that mandate resin pre-approval before supplier bid submission. Shanghai and Suzhou supplier parks are scaling compression molding capacity for cell-to-pack architectures.
United States
EPA fuel economy standards indirectly accelerate lightweight material substitution across Detroit Three vehicle platforms. Michigan and Ohio manufacturing corridors concentrate injection molding capacity for interior and exterior components. NHTSA crash-test validation protocols for multi-material joining create compliance complexity that favors established compounders with in-house testing facilities.
Japan
METI's carbon fiber industrial policy supports precursor supply chain concentration that feeds automotive thermoplastic prepreg production. Nagoya and Tokyo industrial clusters anchor Toray Industries and Teijin Limited manufacturing positions. JIS standards for fiber-reinforced plastics create technical barriers that favor domestic compounders in keiretsu supply relationships.
India
PLI scheme production-linked incentives for advanced automotive materials attract compounding capacity investments serving domestic OEMs and export-oriented supplier parks. Maharashtra and Tamil Nadu automotive corridors concentrate demand from Maruti Suzuki and Hyundai Motor India platforms. BIS certification requirements for automotive plastics extend qualification periods for imported resin formulations.
Automotive Thermoplastic Polymer Composites Market Competitive Environment
German and Japanese producers anchor one tier; Chinese and Middle Eastern petrochemical specialists hold feedstock-integrated positions at scale. The vendor base concentrates around integrated resin-to-composite suppliers with captive polymerization capacity. Three archetypes dominate: integrated petrochemical conglomerates controlling upstream resin supply, carbon fiber specialists with aerospace-qualified tape technology, and regional compounders serving single OEM platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Among integrated chemical conglomerates, BASF SE and SABIC exemplify the resin-backward archetype that captures specification influence at the polymerization stage. Toray Industries, Inc. occupies a position within the carbon fiber-reinforced prepreg tier where aerospace technology migration enables automotive structural applications. These three anchors represent distinct competitive vectors: petrochemical integration, fiber technology leadership, and regional platform capture.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Teijin Limited |
| BASF SE |
| Hexcel Corporation |
| Mitsubishi Chemical Corporation |
| DuPont de Nemours Inc |
| Solvay SA |
| SABIC |
| Covestro AG |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber precursor indices and polyamide 6.6 feedstock benchmarks cascade through automotive thermoplastic composite supply chains into three distinct pricing tiers. German OEM specification committees capture premium-grade polyamide compounds through multi-year offtake agreements, while volume buyers in China's Yangtze River Delta region negotiate standard-grade polypropylene compounds on quarterly contract resets.
Pricing Analysis
Capacity additions in China's petrochemical corridor are reshaping price floors for polypropylene-based compounds serving interior applications. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber-reinforced polyamide for structural battery enclosures from glass fiber-reinforced polypropylene for non-structural trim. Pricing pressure stems from REACH authorization timelines extending qualification periods for flame-retardant polycarbonate blends. A-segment vehicle platforms exhibit highest price sensitivity, while German luxury OEMs demonstrate lowest sensitivity due to performance-specification lock-ins.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit anchor hub-and-spoke patterns for just-in-time compound delivery to Tier-1 supplier plants. Geographic supply concentration centers on Germany for polyamide compounding, Japan for carbon fiber precursor, and Saudi Arabia for base resin feedstock. Raw material dependencies draw from acrylonitrile for carbon fiber, caprolactam for polyamide 6, and bisphenol A for polycarbonate. Single-source vulnerability in Japanese carbon fiber precursor supply creates structural risk exposure for European compounders. Distribution runs through integrated resin-to-composite suppliers with captive polymerization capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where cell-to-pack battery architectures are forcing specification upgrades toward continuous fiber-reinforced thermoplastic tapes with crash-certified performance.
For Market Incumbents: Deploy backward integration into polyamide polymerization to defend specification influence as OEMs mandate resin-grade pre-approval before supplier bid submission. BASF SE's integrated supply chain model demonstrates how captive caprolactam production locks compounders into multi-year platform agreements. Counter emerging Chinese petrochemical entrants by accelerating REACH-compliant flame-retardant formulation qualification ahead of ECHA sunset dates. For New Entrants and Emerging Players: Direct-to-OEM digital specification platforms offer white-space entry around recycled carbon fiber reclamation for non-structural interior applications. India's PLI scheme for advanced materials presents the most penetrable geography for localized compounding capacity serving Maruti Suzuki and Hyundai Motor India platforms. Target aftermarket collision repair segments with color-matched specialty compounds requiring lower minimum order quantities than OEM series production. For Investors and Strategic Acquirers: Asymmetric upside sits with carbon fiber prepreg specialists possessing aerospace-qualified tape technology migrating into automotive cycle times. Long-term viability over the next decade hinges on qualification timelines compressing from 24 months toward 12 months for cell-to-pack structural applications. Acquisition target archetype: regional compounders with existing OEM platform approvals in Germany or China's Yangtze River Delta. Watch NHTSA harmonization with KBA crash-test protocols for multi-material joining as the inflection signal for cross-border specification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide Polymerization | BASF SE's captive caprolactam supply locks resin-grade specification influence at the design stage. |
| Continuous Fiber-Reinforced Tape Capacity Expansion | Toray Industries' aerospace-qualified prepreg technology enables 60-second automotive cycle time migration. |
| REACH-Compliant Flame-Retardant Formulation Investment | Phosphorus-based polycarbonate alternatives capture battery enclosure demand as ECHA halogenated sunset dates approach. |
| Regional Compounding Joint Venture in India | PLI scheme incentives attract capacity investments serving domestic OEMs and export-oriented supplier parks. |
| Recycled Carbon Fiber Reclamation Partnership | Pyrolysis technology convergence with automotive shredder residue sorting enables cost-competitive non-structural feedstocks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and specification-influence dynamics. Primary interviews engaged Tier-1 supplier procurement directors, OEM platform engineers, resin compounder technical directors, and aftermarket distribution managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from integrated chemical conglomerates. Bottom-up segmentation modeling and top-down macroeconomic anchoring were cross-checked for consistency.
Comparable-period anchoring linked projection assumptions to historical qualification timeline patterns and platform launch cycles across the analysis window. Segmentation dimensions modeled included resin chemistry tier, fiber reinforcement type, manufacturing process technology, vehicle propulsion architecture, and regional production cluster. CAGRs were derived from slope consistency checks against electric vehicle platform penetration curves and lightweighting content-per-vehicle trajectories. Forecast inputs incorporated REACH authorization sunset scheduling and MIIT domestic content requirement phase-ins.
Carbon border adjustment mechanism implementation, battery enclosure standard harmonization delays, and carbon fiber precursor supply disruptions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions around qualification timeline compression and platform-architecture consolidation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Water-Borne Epoxy Resins Market
Polymers & Resins
Australia Engineering Plastics Market
Polymers & Resins
Global Polymeric Adsorbents Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market