
 Global Wheel Tractor Scraper Market | 2026-2036
Global Wheel Tractor Scraper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wheel Tractor Scraper Market Foresight
A capital-intensity divergence between integrated manufacturers and component assemblers is rotating competitive advantage toward firms with in-house engine and hydraulics production. Caterpillar Inc. leverages its captive powertrain manufacturing to control cost structures across the 401-500 HP and Above 500 HP ranges. Komatsu Ltd. anchors its position through integrated telematics and autonomous haulage compatibility. K-Tec Earthmovers Inc. specializes in pull-type scraper attachments, competing on flexibility for contractors who retain existing tractor fleets.
A wheel tractor scraper is a self-propelled or towed earthmoving machine combining a tractor unit with an open bowl, apron, and ejector mechanism to cut, load, transport, and spread soil or overburden across distances exceeding 500 meters. Bowl capacities typically range from 15 to 44 cubic yards, with cutting depths adjustable via hydraulic apron control to match material density and site conditions. Articulated and elevating configurations dominate mining and quarrying applications where cycle efficiency determines project economics, while tandem and pull-type variants retain share among contractors serving fragmented land development and road building projects. Power ratings above 500 HP command premium positioning in Australian and Chilean mining corridors, whereas the 200-300 HP segment serves agricultural enterprises converting pasture to irrigated cropland.
EPA Tier 4 Final standards in the United States, EU Stage V regulations through the European Commission, and China's GB 20891 emissions framework collectively restrict diesel particulate emissions and drive after-treatment complexity. Equipment buyers in California face additional CARB compliance layers that accelerate interest in alternative-fuel prototypes. Stakeholders must monitor how emissions enforcement timelines interact with electrification cost curves and residual-value risk in secondary markets.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions standards are compressing diesel powertrain viability and accelerating manufacturer investment in electrified architectures, fundamentally restructuring competitive advantage toward firms with captive electric drivetrain development.
Growth Catalysts
- Lithium extraction expansion:Mining operators in Australia and Chile are scaling fleet procurement to serve battery supply chain demand, directly pulling high-horsepower articulated scraper orders.
- EU Green Deal infrastructure allocation:Renewable energy corridor construction across member states is generating sustained earthmoving equipment tenders with multi-year visibility.
- Telematics integration:Fleet management platforms that synchronize scraper positioning with autonomous haulage systems are reducing cycle times in open-pit operations.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems required by EPA Tier 4 Final have added substantial capital cost to conventional powertrains.
- Battery supply concentration:Lithium-ion cell production for electric prototypes remains concentrated in Chinese manufacturing corridors, exposing non-integrated OEMs to input bottlenecks.
- Residual value uncertainty:Secondary market buyers face opacity around Tier 4 Final equipment depreciation curves as electrified alternatives enter commercial testing.
Strategic Opportunities
- Indian mining formalization:The country's central mining regulator is consolidating small-scale operations, creating consolidated fleet procurement opportunities for standardized equipment.
- California CARB zero-emission pathways:The state's air resources board is piloting off-road equipment electrification incentives that could validate battery-electric scraper economics.
- Rental channel expansion:Equipment-as-a-service platforms are penetrating North American contractor segments that previously relied on owned fleets.
Industry Challenges
- Electrification engineering scarcity:OEMs face acute competition for power electronics and thermal management specialists capable of adapting heavy-duty earthmoving duty cycles.
- Certification timeline compression:Parallel EPA, EU Stage V, and China's GB 20891 compliance pathways are straining homologation resources across product development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wheel Tractor Scraper Market |
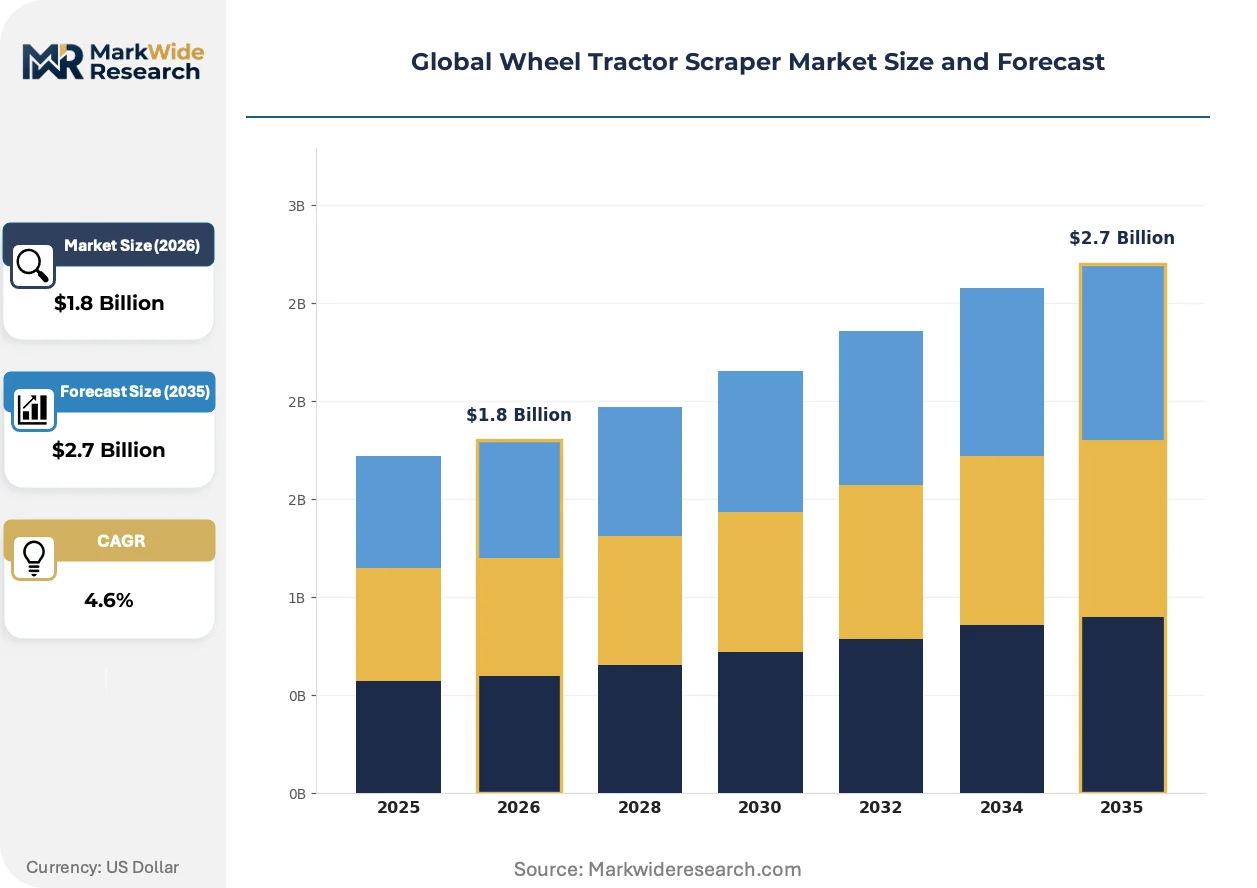
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated, Tandem, Pull-Type, Elevating, Wheeled Scraper Power Rating: 200-300 HP, 301-400 HP, 401-500 HP, Above 500 HP Application: Mining, Construction, Quarrying, Road Building, Land Development End User: Contractors, Infrastructure Developers, Mining Companies, Agricultural Enterprises |
| Companies Covered | Volvo Construction Equipment, CNH Industrial N.V., Caterpillar Inc., SANY Group, XCMG Group, Deere & Company, K-Tec Earthmovers Inc., Zoomlion Heavy Industry Science & Technology Co., Ltd., Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wheel Tractor Scraper Market Shifts & Advancements
Electrification architectures and autonomous compatibility layers are converging to redefine scraper value propositions, shifting buyer evaluation criteria from horsepower-per-dollar to total cost of ownership across energy and labor inputs.
Battery-electric powertrains with regenerative braking during bowl loading and descent cycles are supplanting mechanical transmission designs in pilot mining deployments. Australian iron ore operators are testing 300-ton-class electric prototypes for 24-hour continuous duty. This transition is compressing the competitive window for manufacturers lacking in-house battery thermal management or motor control expertise.
REACH chemical restrictions through the European Chemicals Agency are limiting hydraulic fluid formulations and lubricant additives permitted in EU-sold equipment. Manufacturers must reformulate component specifications or segment product lines by regulatory jurisdiction. The 200-400 HP construction-oriented segment faces the steepest compliance cost escalation as volumes do not amortize dedicated engineering.
Consolidated mining houses are unbundling maintenance contracts from equipment procurement, forcing OEMs to compete on parts availability and technician response time rather than upfront pricing. Rio Tinto and BHP have structured separate service agreements with third-party logistics providers. Western Australian Pilbara operations exhibit the most advanced disaggregation of capital and operating expenditure decisions.
Global Wheel Tractor Scraper Market Segmentation
Wheel tractor scraper segmentation reveals distinct procurement channels for each configuration. Mining houses favor high-horsepower articulated units through direct OEM negotiation, while contractors source pull-type attachments via rental networks. Understanding these flow patterns clarifies where pricing power concentrates and where margin erosion threatens.
Product Type:
Channel strategy diverges sharply across configurations, with integrated mining operators procuring directly while fragmented contractors rely on dealer and rental intermediaries.
- Articulated:Self-propelled units with hinged frames enable tight turning radius in confined cut zones. Australian iron ore corridors and Chilean copper pits generate concentrated demand as 24-hour continuous duty cycles justify premium capital deployment.
- Elevating:Conveyor-equipped bowls load material without auxiliary push tractors, reducing fleet complexity. Quarrying operations in the western United States specify these for limestone overburden removal where haul distances exceed one kilometer.
- Tandem:Dual-axle tractor units pull conventional bowls for agricultural conversion projects. Midwestern US pasture-to-cropland developments sustain residual demand despite limited mining penetration.
- Pull-Type:Detached bowls hitch to existing agricultural or construction tractors. North American rental channels stock these for contractors seeking fleet flexibility without dedicated scraper capital commitment.
- Wheeled Scraper:Compact single-axle variants serve road maintenance authorities. State departments of transportation in Texas and California maintain standing orders for shoulder rehabilitation contracts.
By volume, Tandem and Pull-Type units lead through agricultural and rental channel penetration. By growth pace, Articulated configurations are climbing the fastest on mining fleet replacement cycles.
Power Rating:
Cost tier stratification separates premium mining specifications from standard construction offerings, with emissions compliance burdens falling disproportionately on mid-range segments lacking volume scale.
- Above 500 HP:Mining-optimized powertrains deliver sustained output in high-altitude Chilean operations. BHP and Rio Tinto procurement specifications mandate this tier for Pilbara iron ore overburden stripping.
- 401-500 HP:Caterpillar's captive engine manufacturing controls cost structures here. Australian lithium extraction projects specify this range for balance between payload capacity and fuel efficiency.
- 301-400 HP:Construction contractors face steepest EPA Tier 4 Final compliance costs per unit. The segment lacks mining volume to amortize dedicated after-treatment engineering.
- 200-300 HP:Agricultural enterprises converting irrigation districts in California's Central Valley drive residual demand. CARB zero-emission pilot programs are testing electric alternatives in this bracket.
By volume, the 401-500 HP bracket dominates through mining procurement scale. By growth pace, Above 500 HP is gaining share fastest on battery-electric prototype validation.
Application:
Customer maturity varies by use case, with mining presenting consolidated procurement decisions while land development remains structurally fragmented across small contractors.
- Mining:Open-pit operations require 24-hour equipment availability and autonomous haulage integration. Western Australian Pilbara corridors represent the most advanced deployment of telematics-synchronized scraper fleets.
- Construction:General earthmoving contractors balance owned fleet utilization against rental flexibility. Equipment-as-a-service platforms are penetrating this segment in North America.
- Quarrying:Dimension stone and aggregate producers specify elevating scrapers for consistent material sizing. EU Green Deal infrastructure allocation is sustaining tender activity across member states.
- Road Building:Highway authorities and private contractors require rapid cycle completion to minimize traffic disruption. California Department of Transportation maintains specifications compatible with future zero-emission mandates.
- Land Development:Residential and commercial site preparation involves fragmented project scopes. Small contractors in Texas and Florida favor rental channels for intermittent demand.
By volume, Construction applications lead through broad contractor base. By growth pace, Mining is expanding most quickly on battery supply chain investment.
End User:
Procurement authority concentration determines contract structure, with mining companies unbundling maintenance from capital expenditure while agricultural enterprises prioritize upfront pricing.
- Mining Companies:Consolidated operators like BHP and Rio Tinto negotiate separate service agreements with third-party logistics providers. Western Australian operations exhibit the most advanced disaggregation of capex and opex decisions.
- Contractors:Small and mid-sized construction firms rely on dealer financing and rental platforms. K-Tec Earthmovers targets this segment with pull-type flexibility for retained tractor fleets.
- Infrastructure Developers:Renewable energy corridor projects across EU member states generate multi-year earthmoving tenders. EU Green Deal allocation provides visibility for fleet planning.
- Agricultural Enterprises:Irrigation district conversions in the western United States sustain demand for lower-horsepower units. California's CARB compliance layers accelerate interest in alternative-fuel prototypes.
By volume, Contractors represent the largest addressable base. By growth pace, Mining Companies are pulling ahead on lithium and copper extraction expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor segments in North America exhibit acute price sensitivity to after-treatment costs, whereas Australian mining houses prioritize payload capacity and 24-hour availability over capital expenditure. This elasticity divergence shapes regional procurement patterns and manufacturer channel strategies.
United States
Infrastructure corridors across Texas and California sustain demand for high-volume earthmoving capacity. EPA Tier 4 Final compliance burdens fall heaviest on the 200-400 HP construction segment lacking mining-scale volume amortization. The Central Valley agricultural belt generates pull-type scraper rental demand for irrigation district conversions.
Australia
Pilbara iron ore operators mandate above-500 HP specifications for continuous overburden stripping cycles. The Western Australian mining regulator enforces autonomous haulage compatibility standards that synchronize scraper telematics with fleet management platforms. Perth-based procurement offices coordinate consolidated fleet replacement schedules across BHP and Rio Tinto operations.
Chile
Atacama Desert lithium extraction projects specify 401-500 HP articulated units for high-altitude performance. The Ministry of Mining's formalization programs consolidate small-scale copper operations into standardized fleet procurement. Antofagasta and Calama industrial clusters concentrate maintenance infrastructure for 24-hour equipment availability.
Germany
EU Green Deal infrastructure allocation channels earthmoving tenders toward renewable energy corridor construction. REACH chemical restrictions through ECHA limit hydraulic fluid formulations permitted in domestically sold equipment. Bavarian quarrying operations specify elevating scrapers for limestone overburden removal exceeding one-kilometer haul distances.
China
GB 20891 emissions frameworks restrict diesel particulate output from construction equipment nationwide. The dual carbon policy accelerates battery-electric prototype development for domestic mining applications. Sichuan-Chongqing industrial clusters test regenerative braking architectures in 300-ton-class pilot deployments.
Global Wheel Tractor Scraper Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive powertrain manufacturing separating premium positioning from assembly-dependent competitors. The upper tier commands pricing authority through in-house engine and hydraulics production, while mid-scale fabricators compete on configuration flexibility and rental channel penetration. Two strategic archetypes dominate: diversified industrial conglomerates with construction equipment divisions, and pure-play earthmoving specialists. Competitive moves concentrate on backward integration into electric drivetrain components and telematics platform licensing.
Within the integrated industrial tier, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by captive manufacturing depth and autonomous system compatibility. K-Tec Earthmovers Inc. exemplifies the specialist archetype, competing through pull-type flexibility rather than vertical integration. Among Chinese fabricators, SANY Group and XCMG Group represent scale-driven challengers with domestic market anchoring and emerging export positioning. These three named entities span the structural spectrum from diversified conglomerate to configuration specialist to volume-scale regional leader.
| Leading Market Players |
|---|
| Volvo Construction Equipment |
| CNH Industrial N.V. |
| Caterpillar Inc. |
| SANY Group |
| XCMG Group |
| Deere & Company |
| K-Tec Earthmovers Inc. |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| Komatsu Ltd. |
| Others |
Supply & Pricing Matrix
Eighteen-month engine procurement lead times for Tier 4 Final after-treatment systems concentrate pricing power with Caterpillar and Komatsu, whose captive manufacturing insulates them from supplier bottlenecks that compress margins for assembly-dependent competitors.
Pricing Analysis
Parts and service revenue streams now drive lifetime value, with mining houses unbundling maintenance contracts from equipment procurement. Three-tier pricing structure across premium, standard, and economy levels separates integrated OEMs from pull-type specialists and rental-channel assemblers. Cost compression in the 301-400 HP construction segment intensifies because after-treatment engineering lacks mining-scale volume amortization. Contractors exhibit acute price sensitivity, whereas Australian mining operators prioritize payload capacity and 24-hour availability over capital expenditure.
Supply Chain Analysis
Strait of Malacca transit vulnerability exposes lithium-ion cell shipments from Chinese manufacturing corridors to Australian and Chilean assembly plants. Component sourcing draws from China for battery cells, Germany for precision hydraulics, and Japan for power electronics. Single-source vulnerability concentrates in Chinese cathode material production. Distribution runs through OEM-direct channels for mining houses and dealer-rental networks for fragmented contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wheel tractor scraper demand sits in early-cycle expansion as battery supply chain investment pulls fleet replacement schedules forward across Australian and Chilean mining corridors.
For Market Incumbents: Compound defensive positioning through backward integration into electric drivetrain components and telematics platform licensing. Battery supply concentration threatens non-integrated OEMs with input bottlenecks. Captive thermal management expertise anchors premium pricing in above-500 HP mining specifications. For New Entrants and Emerging Players: Lead with rental-channel penetration in North American contractor segments and CARB-compliant electric prototypes for California agricultural conversions. Pull-type flexibility for retained tractor fleets presents the most penetrable white space. Equipment-as-a-service platforms offer direct go-to-market access without dealer infrastructure investment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mining procurement centralization favors scaled service networks over fragmented assembly operations. Acquisition targets with in-house powertrain manufacturing and autonomous haulage compatibility command structural premiums. Watch battery-electric prototype validation in Western Australian Pilbara operations as the inflection signal for electrification economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Thermal Management | Caterpillar's captive engineering insulates margin structures from Chinese cell supply bottlenecks. |
| Telematics Platform Licensing | Komatsu's autonomous haulage compatibility synchronizes scraper positioning with fleet management systems. |
| Rental Channel Expansion | K-Tec's pull-type flexibility penetrates contractor segments without dedicated scraper capital commitment. |
| CARB Zero-Emission Prototype Development | California's air resources board incentives validate battery-electric economics in 200-300 HP agricultural applications. |
| Indian Mining Formalization Partnership | The country's central mining regulator consolidation creates standardized fleet procurement opportunities for OEMs. |
Research Methodology
Desk research of equipment registration databases, mining company procurement disclosures, and emissions compliance filings preceded structured interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary fieldwork with BHP and Rio Tinto fleet managers in Perth was cross-referenced against SEC 10-K filings and Australian Bureau of Statistics trade data. Bottom-up unit shipment estimates and top-down value aggregation were triangulated for convergence.
Variance decomposition across power rating, configuration type, and application segments structured the analytical framework over the projection horizon. Modeled dimensions included articulated versus pull-type deployment, mining versus construction end-use, and autonomous compatibility tiers. CAGRs were derived from segment-level growth rate synthesis. Forecast inputs incorporated lithium extraction project timelines and EU Green Deal infrastructure allocation schedules.
The analysis sits within stated boundaries; outcomes outside sustained battery supply chain investment or accelerated emissions enforcement timelines would require recalibration. Forecasts reflect documented assumptions around electrification cost curves and mining fleet replacement cycles. Practitioners should keep alternative scenarios live as CARB zero-emission pilot results and Indian mining formalization progress evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Tow Tractor Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Engine Components Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Garbage Collection Vehicle Market
Vehicle Components
Motor Monitoring Market
Vehicle Components
Idler Arm Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Rail Components Market