
 Off-Highway Diesel Engine Market | 2026-2036
Off-Highway Diesel Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Diesel Engine Market Insights
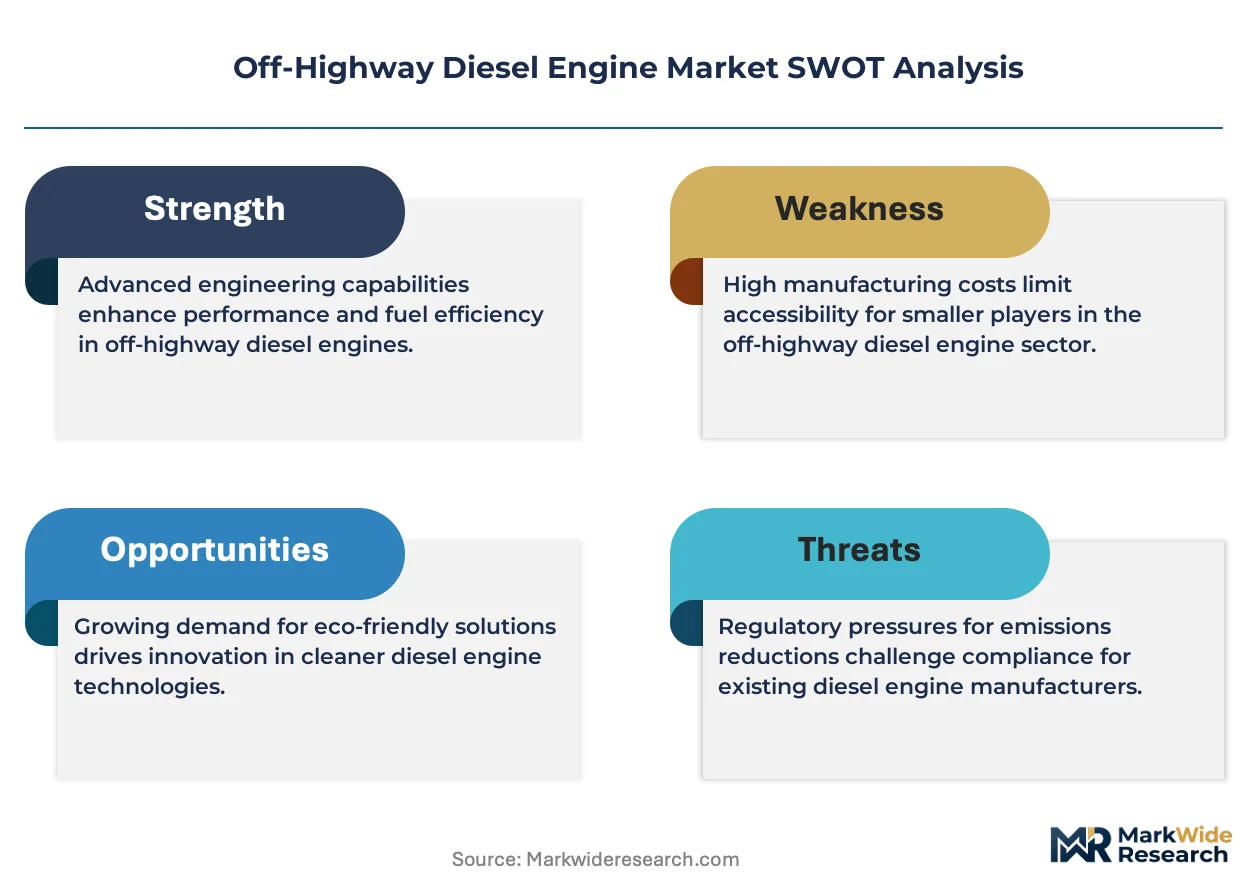
EPA Tier 4 Final and EU Stage V certification is redrawing competitive boundaries for off-highway diesel engine suppliers. Cummins Inc. leverages its vertical integration into aftertreatment systems to sustain pricing power in North American construction channels. Deere & Company anchors its position through captive engine production for agricultural machinery, while Kubota Corporation specializes in compact displacement architectures for Asian equipment OEMs.
An off-highway diesel engine is a compression-ignition powerplant purpose-built for mobile equipment operating outside public roadways, typically delivering 10 to 750 horsepower through cast-iron cylinder blocks with wet or dry liner construction and governed fuel injection systems. These engines convert diesel fuel to mechanical work for earthmoving, cultivation, and material extraction where continuous torque output and field serviceability outweigh highway emissions compliance priorities. Construction equipment applications command the largest revenue pool among product type segments, though mining equipment generates the highest per-unit margins due to severe-duty cooling and filtration specifications. Common rail technology leads technology segmentation for engines above 75 horsepower, while naturally aspirated configurations persist in cost-sensitive agricultural machinery below 50 horsepower where simplicity supports owner-operator maintenance.
EPA Tier 4 Final, EU Stage V, and China's Stage IV standards collectively force engine makers to integrate diesel particulate filters, selective catalytic reduction, and exhaust gas recirculation across most power classes. The US Environmental Protection Agency and European Environment Agency coordinate enforcement timelines that compress R&D amortization periods for mid-tier suppliers. China's Ministry of Ecology and Environment accelerates domestic technology substitution through emission testing protocols that favor locally produced aftertreatment catalysts. Stakeholders must monitor regulatory divergence between California Air Resources Board pathways and federal EPA frameworks, as this fragmentation determines whether platform engineering investments transfer across jurisdictions or strand capital in single-market configurations.
Market Dynamics
Stage IV and Stage V emission mandates are compressing engine architecture lifecycles, forcing simultaneous investment in aftertreatment integration and base engine redesign across all power classes above 25 horsepower.
Growth Catalysts
- China's Stage IV rollout:The Ministry of Ecology and Environment accelerates turbocharger penetration in construction equipment through mandatory emission testing protocols that disqualify naturally aspirated engines from urban job sites.
- Common rail technology:Fuel injection precision improvements enable agricultural machinery OEMs to meet power density requirements without displacement increases, preserving compact chassis designs.
- Brazilian agricultural mechanization:Soybean and sugarcane expansion drives replacement demand for irrigation pumps and harvesters, concentrating orders for 75-150 horsepower engines in Mato Grosso and São Paulo states.
Market Restraints
- Platinum group metal costs:Diesel oxidation catalyst and selective catalytic reduction substrates depend on palladium and rhodium pricing, creating margin volatility for aftertreatment suppliers.
- European supplier concentration:High-pressure common rail injection systems source primarily from German and Italian component houses, exposing non-European engine assemblers to currency and logistics risk.
- Electrification substitution:Battery-electric compact loaders and 20-ton excavators capture municipal and indoor construction applications where diesel particulate filter regeneration cycles create operational friction.
Strategic Opportunities
- India's agricultural upgrade cycle:The government's tractor replacement subsidy program targets 2 million pre-2000 engines for retirement, creating volume for Tier 4 interim-equivalent powerplants.
- Hydrogen combustion convergence:Dual-fuel retrofit kits combining compression ignition with hydrogen port injection open pathways for mining truck fleets seeking carbon intensity reductions without infrastructure overhaul.
- Telematics-enabled service contracts:Engine-hour monitoring and predictive maintenance bundling penetrate rental equipment channels, shifting revenue from hardware margin to recurring service streams.
Industry Challenges
- Aftertreatment calibration expertise:Diesel particulate filter regeneration mapping and urea dosing optimization require software competencies scarce among traditional mechanical engineering workforces.
- Platform certification timelines:EPA Tier 4 Final and EU Stage V validation cycles extend 18-24 months, freezing engineering resources on compliance rather than performance differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Diesel Engine Market |
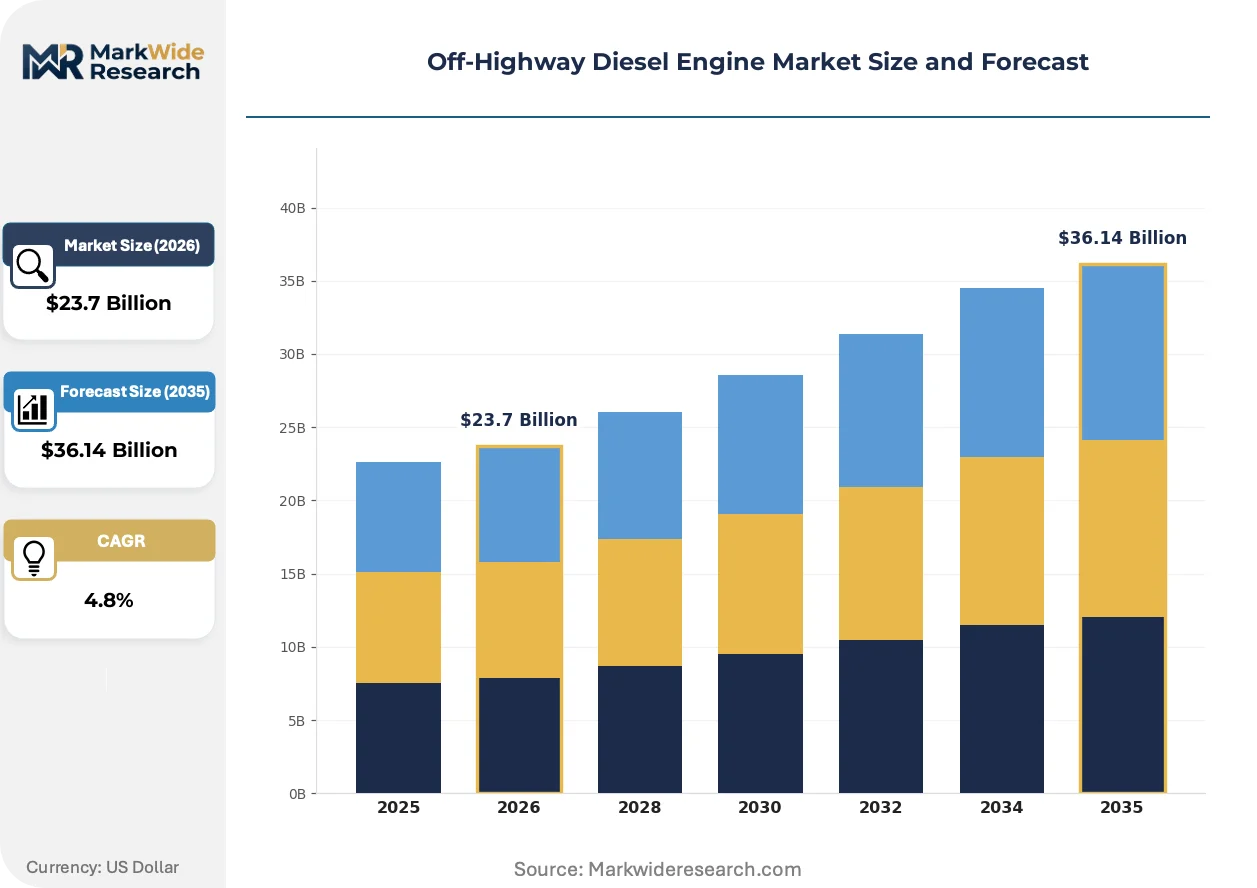
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Construction Equipment, Agricultural Machinery, Mining Equipment, Forestry Equipment Application: Excavation, Material Handling, Tilling, Drilling End User: Contractors, Farmers, Mining Companies, Logistics Providers Technology: Turbocharged, Naturally Aspirated, Common Rail, Direct Injection |
| Companies Covered | Volvo Group, AGCO Power, Cummins Inc., Weichai Power Co., Ltd., Kubota Corporation, Caterpillar Inc., Deere & Company, Komatsu Ltd., Deutz AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Diesel Engine Market Trends and Innovations
Electrification pressure and connected equipment architectures are bifurcating the market between severe-duty combustion platforms and electrified alternatives, with digital service layers emerging as the primary differentiation vector.
Variable geometry turbochargers are displacing fixed-geometry designs in 50-200 horsepower construction engines. Equipment OEMs in South Korea and Japan specify these units for excavators and wheel loaders where altitude compensation and transient response determine productivity. The technology is displacing wastegate-based boost control, compressing supplier margins on legacy turbine housings.
EU Stage V particulate number limits and California Air Resources Board off-road diesel regulations are forcing closed crankcase ventilation and diesel particulate filter integration on engines below 19 kilowatts for the first time. Industrial consequence includes chassis redesign for compact equipment where space constraints previously exempted smaller powerplants. European rental fleets are responding by accelerating replacement cycles to avoid maintenance complexity on non-compliant legacy units.
Equipment-as-a-service contracting is reshaping procurement in North American construction and mining. Fleet managers unbundle engine maintenance from machine purchase, favoring suppliers offering guaranteed uptime with telematics verification. This shift concentrates purchasing authority with national rental houses and away from owner-operators, compressing distributor networks and favoring direct OEM-service relationships in Texas oil patch and Alberta oil sands applications.
Off-Highway Diesel Engine Market Segmentation
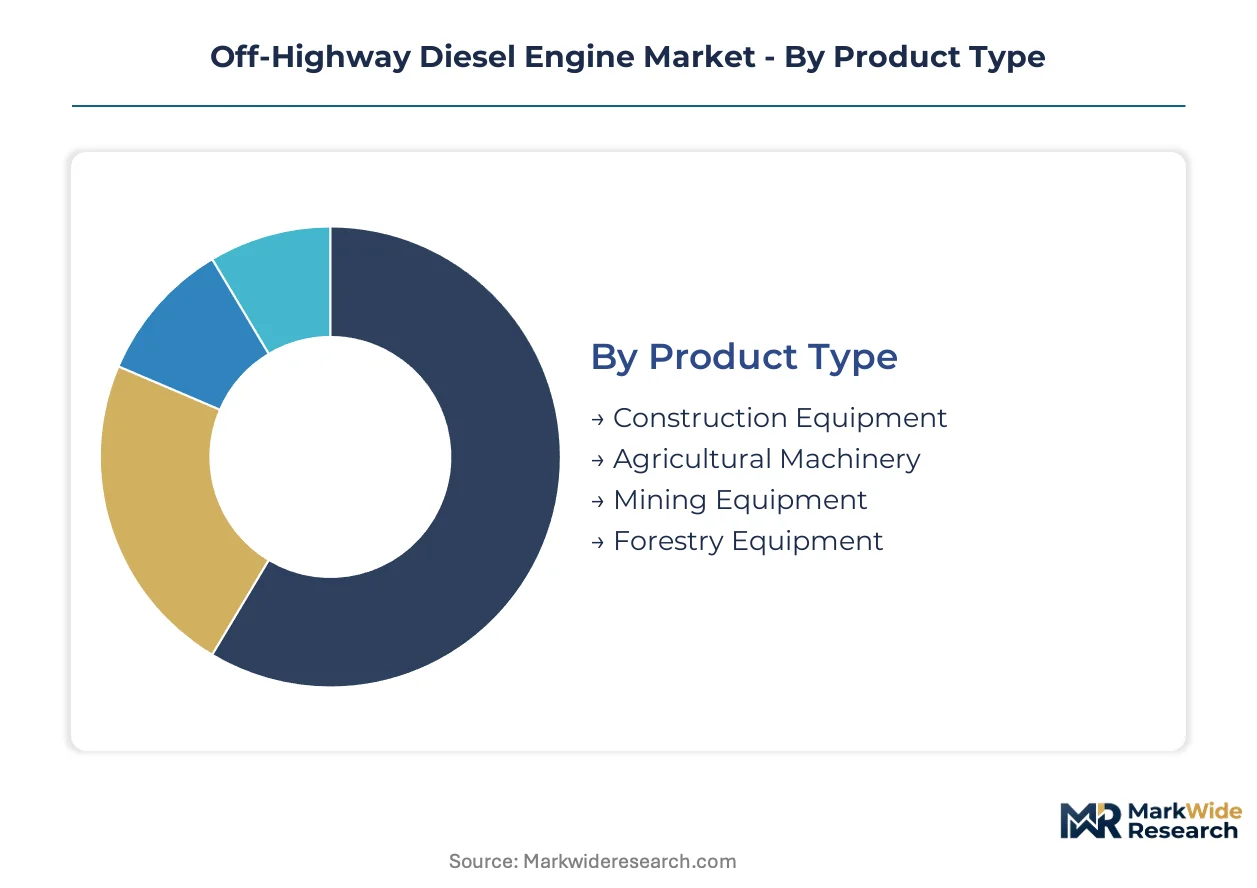
Off-highway diesel engine procurement patterns diverge sharply across equipment categories, with emission compliance tiers and duty-cycle severity determining technology specification. Equipment OEMs configure engine architectures differently for intermittent municipal work versus continuous mining operations, fragmenting supplier strategies across segments.
Product Type:
EPA Tier 4 Final and EU Stage V thresholds apply unevenly across equipment categories, with urban construction facing the strictest certification timelines while remote mining operations secure compliance extensions.
- Construction Equipment:Excavators and wheel loaders dominate procurement volume, with China's Ministry of Ecology and Environment mandating turbocharged architectures for urban job sites under Stage IV protocols. Municipal contractors in Beijing and Shanghai face compressed replacement cycles.
- Agricultural Machinery:Tractors and harvesters sustain demand for sub-75 horsepower configurations where naturally aspirated engines persist in cost-sensitive owner-operator segments. India's tractor replacement subsidy program concentrates orders for interim Tier 4-equivalent powerplants in Punjab and Haryana.
- Mining Equipment:Severe-duty cooling and filtration specifications command premium engineering.
- Forestry Equipment:Remote operation patterns limit aftertreatment service infrastructure.
Established volume favors Construction Equipment; emerging adoption favors Agricultural Machinery as mechanization accelerates in India and Brazil.
Application:
Work-cycle intensity determines engine sizing and durability specifications, with continuous-load applications requiring distinct thermal management architectures from intermittent-cycle equipment.
- Excavation:Hydraulic system integration demands precise torque curves for boom and bucket operations. South Korean OEMs specify variable geometry turbochargers for altitude-compensated performance in Andean mining districts.
- Material Handling:Forklifts and telehandlers face electrification pressure in European indoor warehousing, compressing diesel demand to outdoor yards and heavy-lift configurations.
- Tilling:Seasonal duty cycles favor mechanical simplicity and field serviceability.
- Drilling:Underground operations prioritize compact aftertreatment packaging for chassis integration.
Excavation anchors current revenue; Material Handling faces the steepest substitution risk from battery-electric alternatives.
End User:
Procurement authority is consolidating toward fleet-based decision-makers as equipment-as-a-service contracts displace owner-operator purchases.
- Contractors:Municipal and highway construction firms bundle engine maintenance into machine rental agreements, favoring suppliers with telematics-enabled uptime guarantees. National rental houses in Texas and Alberta concentrate purchasing authority.
- Farmers:Owner-operators in Brazil's Mato Grosso state prioritize first-cost minimization and mechanical serviceability over emission-compliant premium configurations.
- Mining Companies:Carbon intensity targets drive dual-fuel retrofit trials combining diesel with hydrogen port injection.
- Logistics Providers:Warehouse operators accelerate electrification for indoor material handling fleets.
Contractor consolidation favors integrated service offerings; Farmer fragmentation sustains price-competitive simplified architectures.
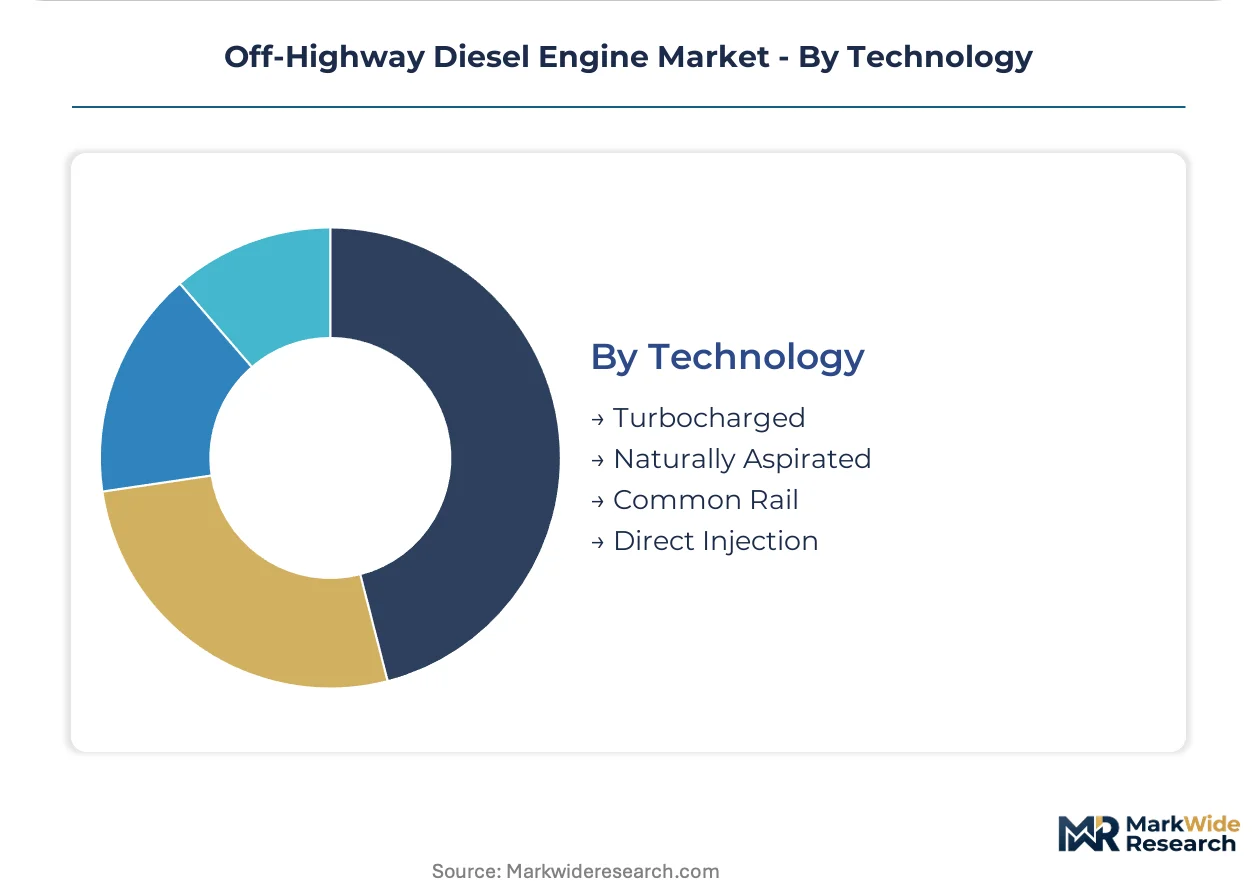
Technology:
Fuel injection and aspiration architectures segment along horsepower thresholds, with common rail and turbocharger penetration rising as emission standards tighten above 50 horsepower.
- Turbocharged:Variable geometry designs displace fixed-geometry units in 50-200 horsepower construction engines, with South Korean and Japanese OEMs specifying altitude-compensated boost control for excavator productivity. Wastegate-based legacy configurations face margin compression.
- Common Rail:High-pressure injection precision enables power density improvements without displacement increases, preserving compact chassis designs in European agricultural machinery. German and Italian component houses dominate supply.
- Naturally Aspirated:Mechanical simplicity persists in sub-50 horsepower agricultural applications.
- Direct Injection:Legacy architectures retreat to cost-minimized markets with deferred compliance timelines.
Common Rail claims the steepest expansion trajectory above 75 horsepower; Naturally Aspirated retains residual share in emerging market small-tractor segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors and agricultural cooperatives concentrate procurement authority across divergent regulatory timelines, with fleet managers in industrialized markets bundling maintenance into service contracts while emerging market owner-operators prioritize mechanical simplicity and first-cost minimization.
China
Urban construction equipment procurement is accelerating turbocharger penetration as the Ministry of Ecology and Environment enforces Stage IV emission testing protocols that disqualify naturally aspirated engines from Beijing and Shanghai job sites. Municipal contractors face compressed replacement cycles for excavators and wheel loaders.
United States
EPA Tier 4 Final compliance costs are consolidating purchasing authority toward national rental houses in Texas and Alberta, where telematics-enabled uptime guarantees reshape contractor procurement. The Environmental Protection Agency coordinates enforcement timelines with California Air Resources Board pathways that fragment platform engineering investments.
Germany
EU Stage V particulate number limits force closed crankcase ventilation and diesel particulate filter integration on compact equipment engines below 19 kilowatts. Industrial clusters in Baden-Württemberg and Bavaria host high-pressure common rail injection system suppliers that expose non-European assemblers to currency risk.
India
The government's tractor replacement subsidy program targets two million pre-2000 engines for retirement, concentrating orders for Tier 4 interim-equivalent powerplants in Punjab and Haryana agricultural belts. Farmers replace aging naturally aspirated units with common rail technology for irrigation pumps and harvesters.
Brazil
Soybean and sugarcane expansion drives replacement demand for 75-150 horsepower engines in Mato Grosso and São Paulo states, where owner-operators prioritize mechanical serviceability over emission-compliant premium configurations. ANVISA and environmental regulators coordinate deferred compliance timelines for cost-sensitive agricultural machinery.
Off-Highway Diesel Engine Market Competitive Landscape
Player mix skews toward vertically integrated engine-assemblers with captive aftertreatment production and diversified industrial conglomerates with construction equipment manufacturing arms. Three archetypes dominate: full-system integrators controlling injection, turbocharging, and exhaust aftertreatment; equipment OEMs with captive engine production for agricultural and mining machinery; and component specialists supplying high-pressure fuel systems to third-party assemblers. Competitive moves concentrate on strategic partnerships for hydrogen dual-fuel retrofit development and geographic expansion through localized emission certification expertise.
Among North American full-system integrators, Cummins Inc. and Caterpillar Inc. exemplify the vertically integrated archetype with upstream control over aftertreatment catalyst production. Deere & Company anchors the captive-production tier through in-house engine manufacturing for agricultural machinery. Kubota Corporation occupies a specialist position serving Asian equipment OEMs with compact displacement architectures. Komatsu Ltd. and Volvo Group represent the construction-equipment-anchored segment where engine development aligns with severe-duty mining and earthmoving applications.
| Leading Market Players |
|---|
| Volvo Group |
| AGCO Power |
| Cummins Inc. |
| Weichai Power Co., Ltd. |
| Kubota Corporation |
| Caterpillar Inc. |
| Deere & Company |
| Komatsu Ltd. |
| Deutz AG |
| Others |
Pricing and Supply Chain Analysis
Ninety-day catalyst inventory cycles at aftertreatment suppliers concentrate pricing leverage among German and Italian component houses, compressing margins for non-European engine assemblers while amplifying cost pass-through power for high-pressure common rail system providers. This inventory compression reinforces tiered pricing stratification across premium EPA Tier 4 Final-certified configurations, standard EU Stage V-compliant architectures, and economy naturally aspirated units serving deferred-compliance agricultural markets.
Pricing Analysis
Cost-plus contracts with palladium and rhodium indexation dominate aftertreatment procurement, with diesel oxidation catalyst substrates priced against London Metal Exchange spot movements. Price differentiation separates emission-certified premium tiers from mechanical-injection economy configurations, with Brazilian owner-operators exhibiting highest sensitivity to first-cost premiums. Pricing pressure stems from platinum group metal volatility, squeezing Tier 4 Final supplier margins while preserving premium capture for captive-production agricultural OEMs.
Supply Chain Analysis
Strategic stockpiling of turbocharger castings and common rail injection components characterizes procurement behavior, displacing just-in-time preferences given eighteen-month EPA certification timelines. Manufacturing concentrates in Germany, Japan, and China, with high-pressure fuel systems drawing from Baden-Württemberg industrial clusters. Single-source vulnerability pervades selective catalytic reduction substrate supply, while distribution runs through national rental houses consolidating contractor procurement authority in Texas and Alberta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftertreatment calibration expertise scarcity constrains mid-tier supplier expansion, with software competencies for diesel particulate filter regeneration mapping concentrated among incumbent engineering workforces and scarce in traditional mechanical talent pools.
For Market Incumbents: Compound backward integration into urea dosing system production to capture service contract revenue streams, while anchoring platform engineering resources on California Air Resources Board pathway alignment to prevent jurisdictional fragmentation from stranding R&D investments. Battery-electric compact loader substitution in municipal construction channels threatens core excavator engine volumes, demanding accelerated telematics-enabled uptime guarantee deployment. For New Entrants and Emerging Players: Differentiate on hydrogen dual-fuel retrofit kits for mining truck fleets, targeting carbon intensity reduction mandates without infrastructure overhaul requirements. India's tractor replacement subsidy program presents the most penetrable volume opportunity, with Tier 4 interim-equivalent powerplant demand concentrating in Punjab and Haryana agricultural belts. Pursue equipment-as-a-service contracting partnerships with national rental houses to bypass fragmented owner-operator distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from construction equipment OEMs seeking to divest captive engine production amid electrification capital reallocation. Long-term viability hinges on severe-duty mining platform specialization and aftermarket service contract recurring revenue conversion. Watch hydrogen combustion convergence trial outcomes as inflection indicator for dual-fuel retrofit market formation.| Strategic Initiative | Industry Significance |
|---|---|
| Aftertreatment System Backward Integration | Cummins and Caterpillar capture pricing power through captive catalyst production for North American construction channels. |
| Hydrogen Dual-Fuel Retrofit Development | Komatsu and Volvo Group trial mining truck kits combining compression ignition with hydrogen port injection for carbon intensity targets. |
| Telematics-Enabled Service Contract Bundling | Equipment-as-a-service models shift revenue from hardware margin to recurring uptime guarantees in Texas oil patch applications. |
| Common Rail Technology Localization | Weichai Power and domestic Chinese suppliers reduce dependency on German and Italian injection system imports under Stage IV protocols. |
| Variable Geometry Turbocharger Platform Expansion | South Korean and Japanese OEMs specify altitude-compensated boost control for Andean mining district excavator productivity. |
Research Methodology
A standing panel of engine platform engineers, aftertreatment calibration specialists, OEM procurement directors, and national rental fleet managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA certification filings, EU Stage V type-approval databases, China MEE emission test protocols, and equipment OEM SEC disclosures. Bottom-up unit shipment estimates triangulated against top-down horsepower-class demand models.
Consistency checks validated volume and value outputs against customs trade data for turbocharger and common rail injection component flows, with segmentation modeling spanning power class tiers, equipment category applications, technology architectures, and regional regulatory clusters. CAGRs derived from fitted growth curves incorporating replacement cycle compression effects and electrification substitution elasticity parameters across the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained platinum group metal price bands or accelerated battery-electric compact equipment penetration would require recalibration. Forecasts reflect documented assumptions regarding Stage IV and Stage V enforcement timelines and hydrogen infrastructure deployment trajectories. Revision becomes warranted when electrification substitution rates in municipal construction applications cross threshold levels triggering diesel platform retirement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
EV Connectors Market
Vehicle Components
Portable Wheel Jack Market
Vehicle Components
Sideloaders Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Navigation Light Market
Vehicle Components
Global Navigation Lighting Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Truck Axle Market
Vehicle Components
HCV Suspension System Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Bicycle Bottom Bracket Market
Vehicle Components
Front Forks Market
Vehicle Components
Trailer Terminal Tractor Market