
 EGR Valve Market | 2026-2036
EGR Valve Market Size, Share, and Industry Trends Forecast 2026-2036
EGR Valve Market Foresight
Commercial vehicle demand is rebalancing toward heavy-duty diesel applications as fleet operators retrofit existing engines rather than replace entire powertrains. Mahle leverages its thermal management portfolio to integrate EGR valves with charge air cooling systems. BorgWarner sustains technology leadership through electromechanical actuator designs that replace pneumatic controls. Rheinmetall Automotive anchors European supply through captive foundry capacity for high-temperature valve housings.
An exhaust gas recirculation valve meters cooled combustion gases back into engine intake streams, typically operating at temperatures exceeding 650°C with stainless steel or Inconel valve stems to resist thermal fatigue and corrosive exhaust constituents. Electronic EGR valves lead product type revenue due to precise duty-cycle control demanded by modern engine management systems, while pneumatic variants retain share in cost-sensitive commercial vehicle retrofits. Diesel fuel type installations dominate current volume, though gasoline direct-injection applications are expanding fastest as automakers adopt cooled EGR for fuel efficiency gains.
EPA Phase 2 standards, EU F-Gas Regulation, and China's MEE emission enforcement collectively mandate tighter NOx control, directly expanding EGR valve specification requirements across OEM sourcing agreements. California Air Resources Board testing protocols now require validated EGR flow accuracy across full engine duty cycles, raising certification barriers for aftermarket entrants. Stakeholders must monitor powertrain electrification timelines to calibrate EGR valve portfolio exposure against declining internal combustion engine investment cycles.
Market Dynamics
Commercial vehicle fleet operators are compressing EGR valve replacement cycles as EPA Phase 2 greenhouse gas standards tighten compliance windows, forcing Tier 1 suppliers to recalibrate just-in-time delivery cadences to powertrain assembly plants.
Growth Catalysts
- EPA Phase 2 Standards:Tighter NOx emission limits in the US mandate validated EGR flow accuracy across full engine duty cycles, expanding OEM specification requirements for electronic valve assemblies.
- Heavy-Duty Diesel Retrofits:Fleet operators in Germany's automotive supplier corridor are retrofitting existing engines rather than replacing entire powertrains, sustaining aftermarket demand for high-temperature valve housings.
- Gasoline Direct-Injection Expansion:Cooled EGR adoption for fuel efficiency gains in passenger vehicles is accelerating specification requirements across Asian and European OEM sourcing agreements.
Market Restraints
- Inconel Input Volatility:Stainless steel and Inconel valve stem materials face price pressure from nickel supply concentration, compressing margin structures for high-temperature component manufacturers.
- Powertrain Electrification Timeline:Battery electric vehicle deployment trajectories in China and the EU threaten long-term internal combustion engine investment cycles, creating demand uncertainty beyond the forecast window.
- Certification Barrier Elevation:California Air Resources Board testing protocols now require validated flow accuracy documentation, raising aftermarket entry costs for non-captive suppliers.
Strategic Opportunities
- India Commercial Vehicle Fleet Modernization:The country's national emission enforcement framework is tightening MEE-equivalent standards, opening specification windows for electronic EGR valve assemblies in heavy-duty applications.
- Charge Air Cooling Convergence:Integration of EGR valves with thermal management systems creates bundled specification opportunities for suppliers with captive foundry and cooling portfolio capabilities.
- EU F-Gas Regulation Tailwind:Refrigerant phase-down mandates are accelerating engine efficiency investments, positioning cooled EGR as a compliance pathway for commercial vehicle OEMs.
Industry Challenges
- Electromechanical Actuator Talent Scarcity:Pneumatic-to-electronic control migration requires embedded software and precision motor control expertise that concentrates in Germany's automotive engineering clusters.
- Dual Certification Timeline Compression:Simultaneous EPA and EU type-approval processes for new valve designs extend product launch cycles, straining R&D resource allocation.
- Legacy System Integration Friction:Electronic EGR valve retrofits into existing engine management architectures demand protocol adaptation, complicating aftermarket deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EGR Valve Market |
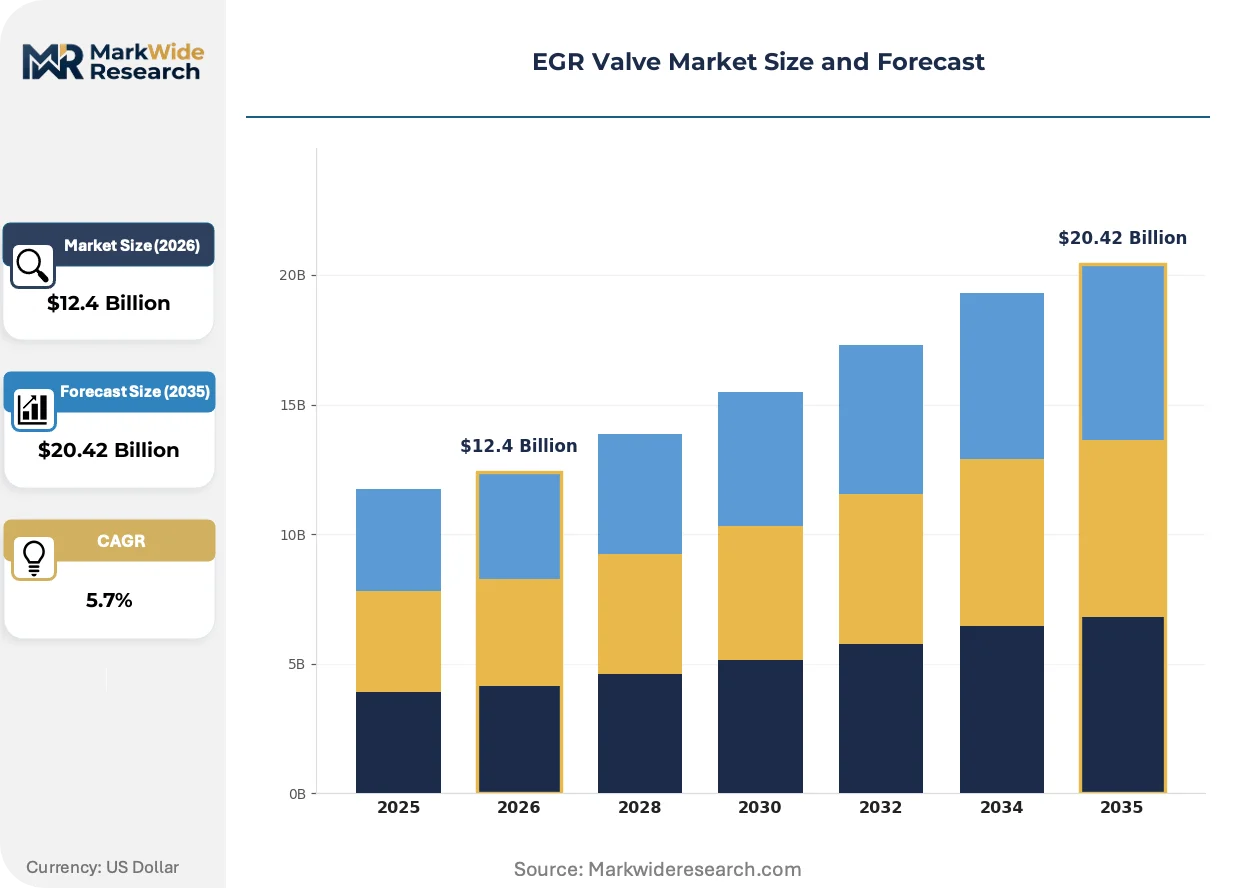
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic EGR Valves, Pneumatic EGR Valves, Vacuum EGR Valves, Throttle-Body EGR Valves End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Fuel Type: Gasoline, Diesel, Biofuel, Propane Installation Type: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Marine Applications |
| Companies Covered | Mahle, Rheinmetall Automotive, BorgWarner, Keihin, Delphi Technologies, Denso, Valeo, Eberspacher, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EGR Valve Market Shifts & Advancements
Electromechanical actuator architectures are displacing pneumatic controls across commercial and passenger vehicle applications, compressing supplier differentiation around precision duty-cycle performance rather than mechanical durability alone.
Electromechanical EGR valve designs are consolidating market preference as electronic engine management systems demand sub-degree positioning accuracy for emission compliance. Heavy-duty diesel OEMs in the US and EU are specifying these actuators for new powertrain platforms. This consolidation is compressing pneumatic valve share to cost-sensitive retrofit segments and emerging market commercial fleets.
EU F-Gas Regulation phase-down schedules are tightening refrigerant-based emission controls, redirecting commercial vehicle efficiency investment toward engine-based solutions including cooled EGR. German and French OEMs are expanding gasoline direct-injection EGR specifications to meet 2025 fleet averages. Passenger vehicle powertrain divisions now dominate cooled EGR valve demand growth, displacing historical diesel concentration.
Fleet procurement departments are unbundling EGR valve replacement from full powertrain service contracts, creating direct supplier relationships for high-rotation components. Independent service networks in the US Midwest and Germany's Ruhr industrial corridor are capturing this disintermediated volume. Commercial vehicle operators with captive maintenance facilities are consolidating supplier panels to three electronic valve specialists, compressing aftermarket fragmentation.
EGR Valve Market Segmentation
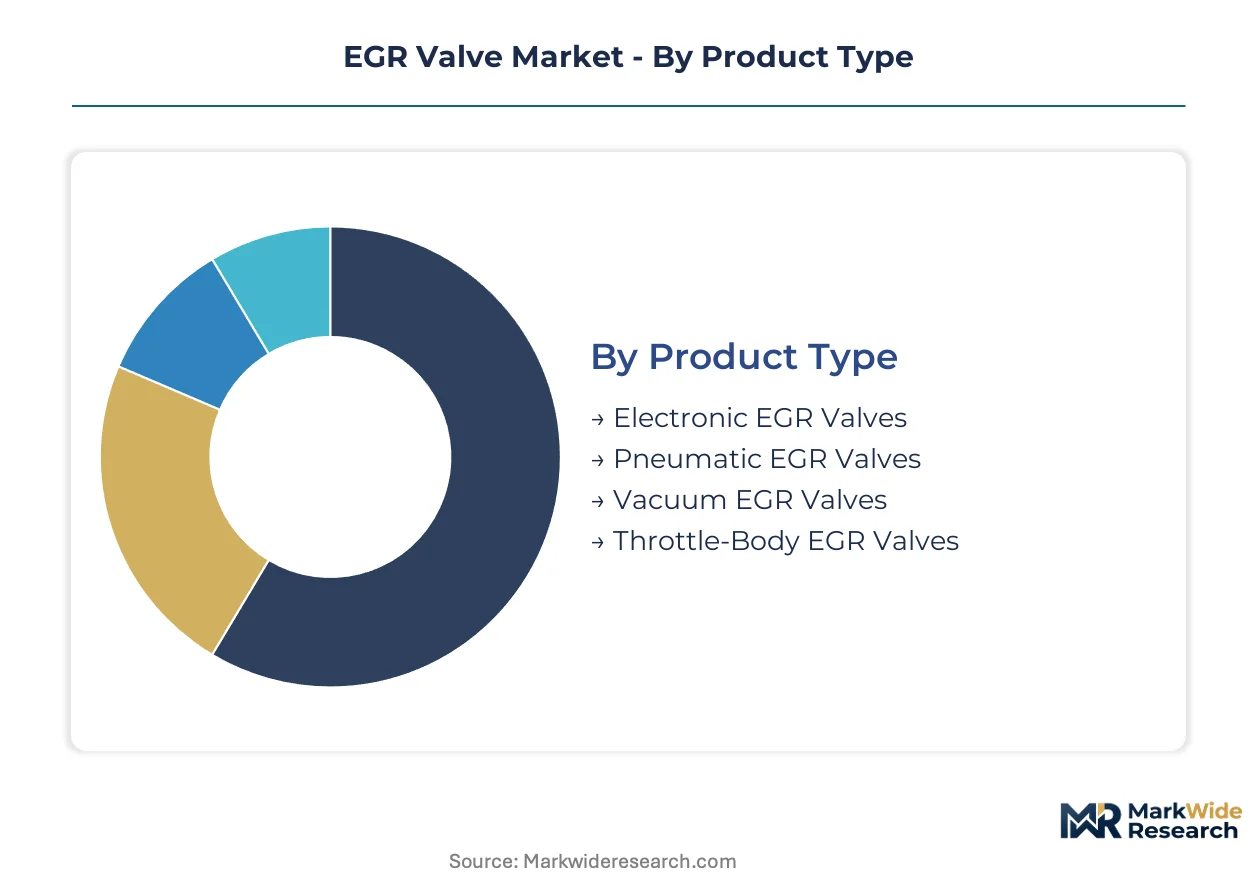
EGR valve procurement patterns diverge sharply across product architectures and customer types. Electronic actuation commands premium positioning in OEM contracts, while pneumatic variants sustain aftermarket retrofit economics. Fuel type and installation context further fragment specification requirements across powertrain engineering teams.
Product Type:
Cost tier separates electronic precision from pneumatic durability in buyer decision frameworks.
- Electronic EGR Valves:Stepper motor or DC motor actuators deliver sub-degree positioning accuracy for closed-loop emission control. EPA Phase 2 validation requirements in the US and EU F-Gas Regulation compliance windows concentrate demand among Tier 1 suppliers serving German powertrain assembly plants.
- Pneumatic EGR Valves:Diaphragm-actuated designs rely on intake manifold vacuum for valve positioning, trading precision for mechanical simplicity and field serviceability. Fleet operators in cost-sensitive commercial vehicle retrofits specify these units for existing engine management architectures that lack electronic control protocols.
- Vacuum EGR Valves:Legacy architecture dependent on ported vacuum signals from carburetor or throttle body sources.
- Throttle-Body EGR Valves:Integrated designs mounting directly to intake manifold throttle bodies for compact packaging.
Electronic EGR valves lead volumes today; gasoline direct-injection applications are gaining share fastest.
End User:
Volume scale and certification burden distinguish captive OEM sourcing from fragmented aftermarket procurement.
- OEMs:Original equipment manufacturers specify electronic valve assemblies through multi-year platform contracts requiring simultaneous EPA and EU type-approval documentation. Powertrain engineering divisions at German and US commercial vehicle producers consolidate supplier panels to three electronic specialists, compressing qualification timelines for new electromechanical designs.
- Aftermarket Providers:Independent distributors and private-label suppliers source pneumatic and vacuum variants for legacy fleet retrofits where electronic control retrofitting proves cost-prohibitive. California Air Resources Board flow accuracy certification requirements now elevate entry barriers, favoring established suppliers with validated test cell capacity.
- Vehicle Assemblers:Contract manufacturers and kit builders integrating engines into final vehicle configurations.
- Repair Shops:Direct procurement from fleet maintenance facilities seeking high-rotation component availability.
OEMs dominate contract value; aftermarket providers are expanding most quickly through fleet disintermediation.
Fuel Type:
Application maturity and emission control intensity shape specification divergence across combustion chemistries.
- Diesel:High exhaust gas temperatures and stringent NOx limits mandate Inconel valve stems and water-cooled housing designs. Heavy-duty commercial vehicle platforms in Germany's automotive supplier corridor anchor current procurement volumes for electronic actuator assemblies.
- Gasoline:Cooled EGR adoption for fuel efficiency gains in direct-injection passenger vehicles accelerates specification requirements. Asian OEMs and European fleet average compliance programs are expanding cooled EGR valve sourcing faster than diesel applications.
- Biofuel:Corrosive exhaust constituents from ethanol and biodiesel blends demand modified sealing materials.
- Propane:Lower combustion temperatures reduce thermal stress on valve components.
Diesel leads installed base; gasoline is climbing the fastest on efficiency regulation tailwinds.
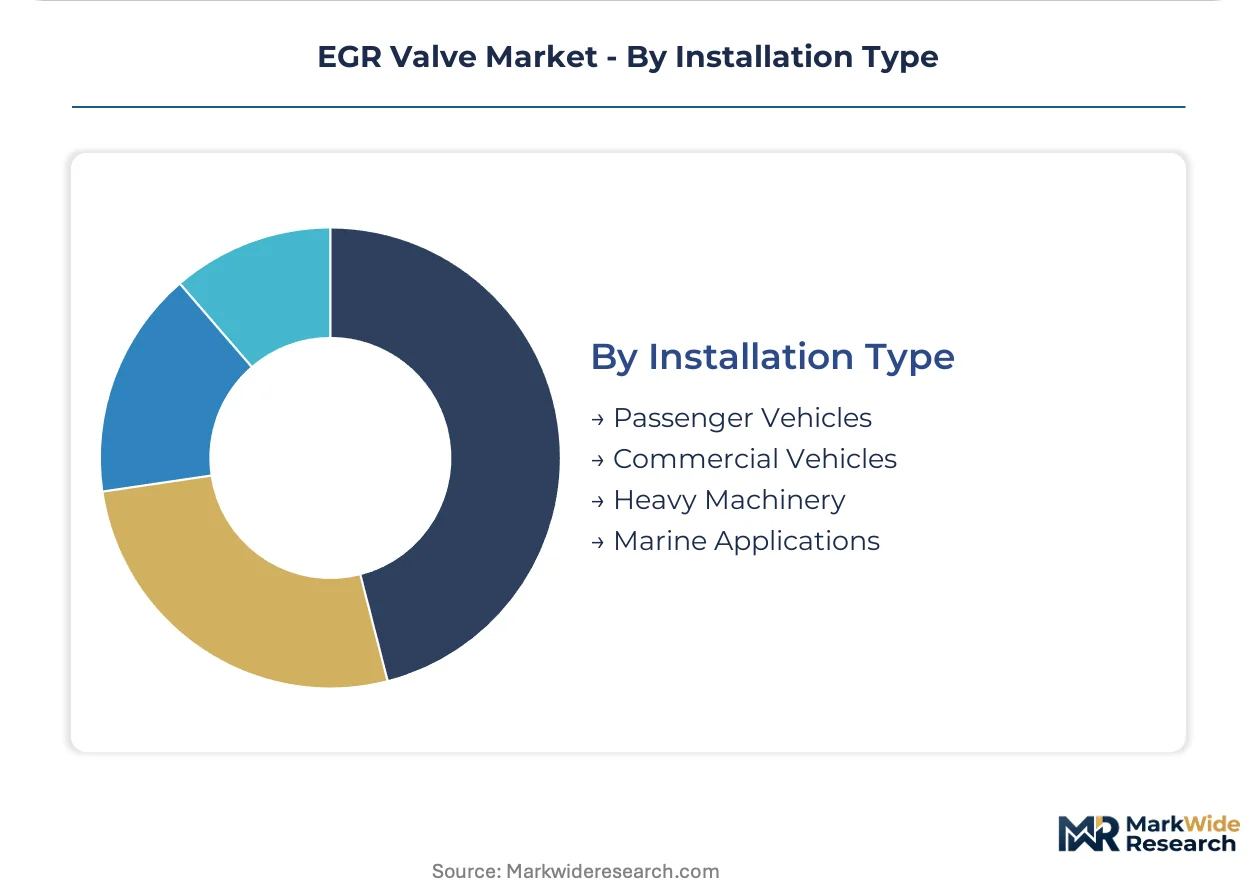
Installation Type:
Operating duty cycle severity and thermal environment define material and actuator selection.
- Commercial Vehicles:Heavy-duty diesel powertrains in US and EU fleets operate EGR valves at sustained temperatures exceeding 650°C, requiring stainless steel or Inconel valve stems with electromechanical actuators for precise duty-cycle control. EPA Phase 2 greenhouse gas standards compress replacement cycles, sustaining aftermarket demand for high-temperature housings.
- Passenger Vehicles:Gasoline direct-injection applications prioritize compact packaging and cooled EGR integration with charge air systems. German and French OEMs are expanding specifications to meet fleet average targets, displacing historical diesel concentration in EGR valve demand growth.
- Heavy Machinery:Off-highway equipment faces intermittent high-load thermal cycling.
- Marine Applications:Salt corrosion resistance and vibration tolerance dominate material selection.
Commercial vehicles anchor revenue; passenger vehicles show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping EGR valve sourcing patterns as suppliers relocate production to jurisdictions with streamlined EPA and EU type-approval reciprocity. Cost-of-compliance gaps between certification regimes now determine where captive foundry capacity anchors.
United States
Heavy-duty diesel fleet operators compress replacement cycles under EPA Phase 2 greenhouse gas standards. The California Air Resources Board mandates validated EGR flow accuracy documentation, elevating aftermarket entry barriers. Detroit's automotive engineering corridor concentrates Tier 1 supplier coordination with powertrain assembly plants.
Germany
EU F-Gas Regulation phase-down schedules redirect commercial vehicle efficiency investment toward cooled EGR pathways. The KBA enforces simultaneous type-approval processes that extend product launch cycles for new valve designs. Stuttgart's automotive supplier corridor anchors just-in-time delivery cadences to OEM powertrain divisions.
China
MEE emission enforcement tightens NOx control requirements for domestic commercial vehicle fleets. National dual carbon goals accelerate engine efficiency investments across state-owned OEM sourcing agreements. Yangtze River Delta manufacturing clusters concentrate high-temperature valve housing production for regional supply.
Japan
METI efficiency standards expand gasoline direct-injection EGR specifications for passenger vehicle fleet averages. JIS certification protocols demand precision duty-cycle performance from electromechanical actuator designs. Nagoya's Chubu industrial region hosts thermal management system integration facilities.
India
National emission enforcement frameworks tighten MEE-equivalent standards for commercial vehicle fleet modernization. The PLI scheme incentivizes domestic manufacturing of electronic EGR valve assemblies. Tamil Nadu's automotive component belt attracts Tier 1 supplier capacity expansion for heavy-duty applications.
EGR Valve Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers bundle EGR valve specifications with thermal management portfolios. The vendor base concentrates around three structural tiers: integrated powertrain specialists with captive foundry capacity, electromechanical actuator designers with embedded software expertise, and regional component fabricators serving cost-sensitive retrofit segments. Dominant competitive moves include backward integration into high-temperature material supply and technology licensing agreements that compress R&D timelines for electronic control migration.
Within the integrated powertrain tier, Mahle and BorgWarner exemplify suppliers leveraging thermal management convergence for bundled OEM contracts. Rheinmetall Automotive anchors the European supply position through foundry-backed production. These three entities represent the archetype of suppliers capturing specification requirements from EPA Phase 2 and EU F-Gas Regulation compliance windows.
| Leading Market Players |
|---|
| Mahle |
| Rheinmetall Automotive |
| BorgWarner |
| Keihin |
| Delphi Technologies |
| Denso |
| Valeo |
| Eberspacher |
| Continental |
| Others |
Supply & Pricing Matrix
Tier 1 commercial vehicle OEM procurement panels in Germany and the US concentrate contract value among three electronic valve specialists, anchoring a contract-based long-term offtake pricing model with volume-tier discounts. This buyer concentration compresses margin structures for captive foundry operators while elevating certification-grade premiums for EPA-validated assemblies.
Pricing Analysis
Distributor margins for aftermarket pneumatic variants run 18-25 points above direct-to-OEM electronic valve contracts. Three-tier pricing structure across premium, standard, and economy levels separates EPA-validated electronic actuators from CARB-certified mid-tier units and uncertified economy retrofits. Price erosion runs through the pneumatic segment as fleet operators disintermediate service networks. Cost-sensitive independent distributors in India's commercial vehicle belt exhibit highest price sensitivity; German powertrain engineering divisions show lowest sensitivity due to bundled thermal management specifications.
Supply Chain Analysis
Precision motor control engineering talent concentrates in Stuttgart's automotive corridor and Detroit's powertrain engineering clusters, constraining electromechanical actuator production scaling. High-temperature valve housing supply draws from Germany's captive foundry capacity, China's Yangtze River Delta manufacturing clusters, and India's Tamil Nadu automotive component belt. Raw material dependencies center on nickel-alloy feedstocks for Inconel valve stems, rare-earth magnets for stepper motor actuators, and specialized stainless steel forgings. Single-source vulnerability concentrates in German foundry capacity for EPA Phase 2 validated housings. Distribution runs through just-in-time delivery cadences to OEM powertrain assembly plants, with aftermarket inventory held at regional distributor hubs in the US Midwest and Germany's Ruhr industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU F-Gas Regulation compliance investments and India's PLI-scheme manufacturing incentives, with cost differentials of 15-20 points on electronic valve assembly production.
For Market Incumbents: Cement technology leadership through backward integration into rare-earth magnet supply chains for stepper motor actuators, insulating against Chinese export restriction risk. Expand captive foundry capacity in India's Tamil Nadu belt to capture PLI scheme benefits while maintaining KBA-validated production lines in Germany for EU OEM contracts. Powertrain electrification timelines threaten long-term internal combustion engine investment cycles; prioritize R&D in thermal management system integration to bundle EGR valves with charge air cooling specifications. For New Entrants and Emerging Players: Electromechanical actuator software expertise offers the most penetrable wedge into a market where pneumatic-to-electronic migration outpaces embedded systems talent supply. Target India's commercial vehicle fleet modernization as the least penetrated geography, where MEE-equivalent enforcement tightens without established supplier relationships. Pursue white-label manufacturing partnerships with Tier 1 thermal management specialists rather than direct OEM qualification to compress entry timelines. For Investors and Strategic Acquirers: Thermal management conglomerates are the most active acquirer in this space, seeking EGR valve capabilities to bundle with charge air cooling portfolios. Long-term viability hinges on calibrating exposure against powertrain electrification trajectories while capturing remaining internal combustion engine efficiency investment cycles. Acquisition target archetype: mid-cap electromechanical actuator designers with embedded software expertise and existing EPA validation documentation. Monitor battery electric vehicle deployment announcements from Chinese state-owned OEMs as the critical inflection signal for demand compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Secures stepper motor actuator production against Chinese export controls. |
| India Manufacturing Footprint Expansion | Captures PLI scheme incentives for domestic electronic EGR valve assembly. |
| Thermal Management System Bundling | Positions suppliers for EU F-Gas Regulation engine efficiency investment flows. |
| EPA Validation Documentation Investment | Elevates aftermarket entry barriers against uncertified competitors. |
| Embedded Software Talent Acquisition | Addresses electromechanical actuator expertise scarcity in German engineering clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and thermal management system integrators. Secondary validation drew from EPA certification databases, EU type-approval registries, KBA documentation filings, and vehicle production databases. Bottom-up segment sizing triangulated against top-down regulatory mandate impact modeling.
Historical reference periods anchored the projection horizon to pre-pandemic baseline volumes and post-EPA Phase 2 implementation trajectories. The analytical framework modeled demand across product architecture, fuel type, installation context, and regional regulatory cluster dimensions. CAGRs derived from segment-level driver elasticity analysis against emission enforcement timelines. Forecast inputs included powertrain electrification adoption curves and commercial vehicle fleet replacement cycle compression rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery electric vehicle deployment acceleration and nickel-alloy commodity price volatility. Forecasts reflect documented assumptions about regulatory enforcement continuity and OEM sourcing panel stability. Material deviation in Chinese dual carbon goal implementation timelines or EU F-Gas Regulation phase-down schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
EV Connectors Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Grille Guard Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Ceramic Ball Bearings Market
Vehicle Components
Car Modification Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
US Group 2 Powered Mobility Devices Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Electric Wheelbarrow Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Wheel Speed Sensor Market