
 Electric Handpiece Market | 2026-2036
Electric Handpiece Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Handpiece Market Foresight
Modular handpiece systems with detachable motors and autoclavable couplings is expanding buyer flexibility across dental practices. W&H Dentalwerk Bürmoos GmbH leverages its Austrian manufacturing base to sustain premium positioning in high-speed segments. J. Morita Corporation anchors its competitive stance through specialized micromotor technology for endodontic applications. Dentsply Sirona Inc. dominates the North American channel with extensive distribution networks and integrated digital dentistry workflows.
An electric handpiece is a motorized rotary instrument used in dental and surgical procedures, typically operating at speeds from 5,000 to 200,000 RPM with torque outputs exceeding 3 Ncm for cutting, polishing, or drilling hard and soft tissues. Brushless motor configurations now lead technology adoption due to reduced heat generation, extended sterilization cycles, and minimal maintenance requirements compared with brushed alternatives. High-speed handpieces command the largest product-type revenue pool, while cordless variants represent the fastest-growing technology segment as mobility demands intensify in multi-chair clinic layouts. Surgical handpieces targeted at oral surgeons generate premium margins driven by precision requirements and lower price sensitivity in hospital settings.
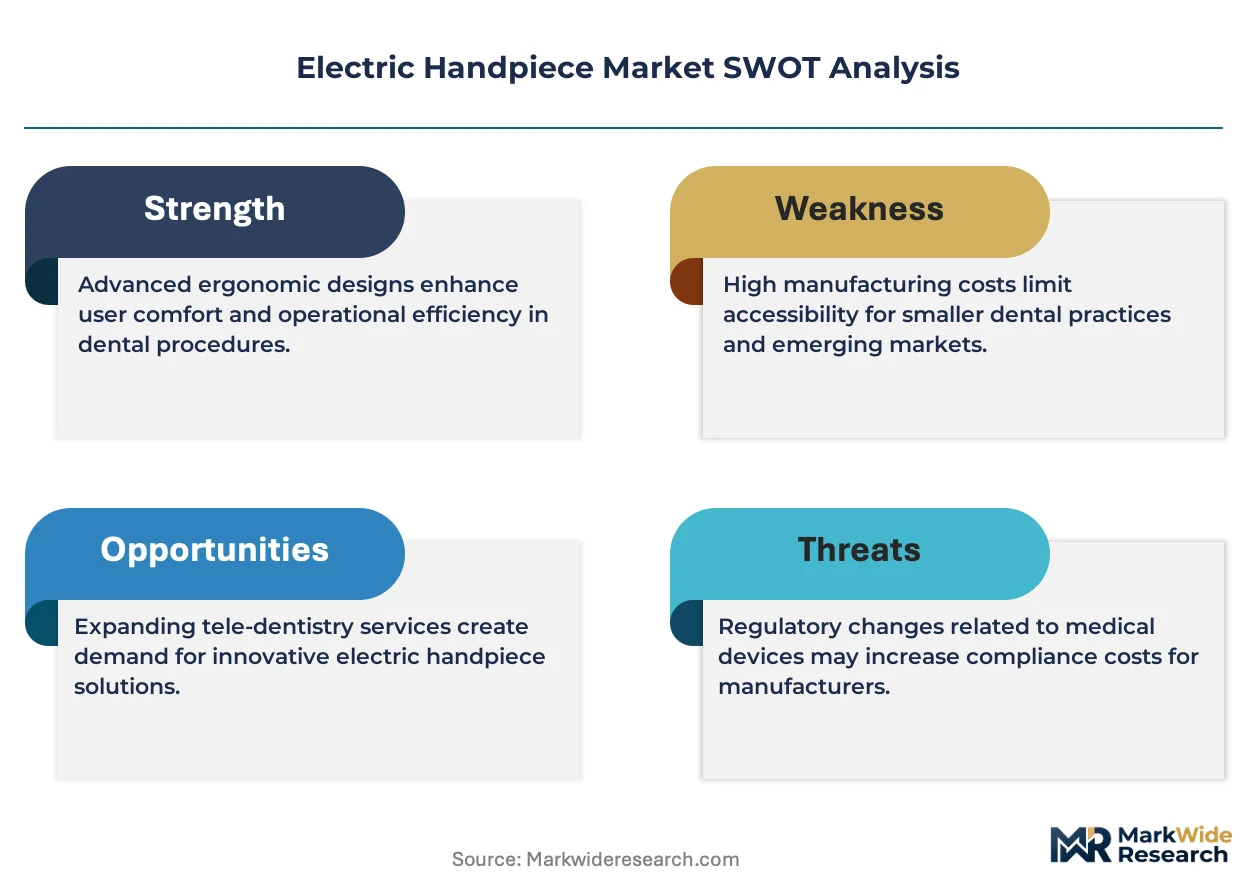
The FDA's 510(k) clearance framework and the EU MDR's updated clinical-evaluation requirements for active implantable surgical instruments are elevating compliance costs for new market entrants. ISO 14457 specifications for dental handpieces establish dimensional and performance benchmarks that manufacturers must satisfy for international market access. BIS certification in India and NMPA registration in China add further layers of regional conformity assessment. Stakeholders must weigh sterilization-validation investments against the margin compression from cordless commoditization in emerging dental economies.
Market Dynamics
The transition from air-turbine to brushless electric motor architectures is compressing replacement cycles while elevating sterilization durability requirements across dental procurement departments.
Growth Catalysts
- EU Medical Device Regulation:MDR's stricter clinical-evaluation mandates for active surgical instruments are filtering out low-quality imports and consolidating demand around certified manufacturers with validated sterilization protocols.
- Baden-Württemberg manufacturing cluster:Precision component suppliers in this German region anchor global OEM supply chains, ensuring consistent availability of high-torque micromotors and ceramic bearings.
- Autoclavable coupling systems:Modular handpiece designs with detachable motors enable single-instrument sterilization workflows that reduce cross-contamination risk in high-volume dental practices.
Market Restraints
- Neodymium magnet supply concentration:Rare-earth dependencies for brushless motor rotors create input cost volatility and geopolitical exposure concentrated in Chinese processing facilities.
- FDA 510(k) pathway complexity:Substantial equivalence demonstrations for powered surgical instruments extend regulatory timelines and elevate compliance expenditure for new market entrants.
- Air-turbine residual installed base:Legacy pneumatic infrastructure in established dental clinics creates switching friction and delays capital conversion to electric platforms.
Strategic Opportunities
- Cordless battery integration:Lithium-polymer power systems converging with induction charging protocols are eliminating hose tethering constraints in multi-chair clinic layouts.
- India BIS certification gap:Underpenetrated dental equipment formalization creates first-mover advantage for manufacturers achieving Bureau of Indian Standards compliance ahead of domestic competitors.
- Endodontic micromotor specialization:Torque-calibrated low-speed applications for root canal procedures command premium positioning distinct from commoditized high-speed cutting segments.
Industry Challenges
- ISO 14457 sterilization validation:Thermal cycling durability testing for handpiece bearings and seals extends product development timelines and requires specialized metrology investment.
- Multi-regional registration burden:Simultaneous FDA, EU MDR, NMPA, and BIS conformity assessments strain regulatory affairs capacity and compress margin contribution from emerging market volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Handpiece Market |
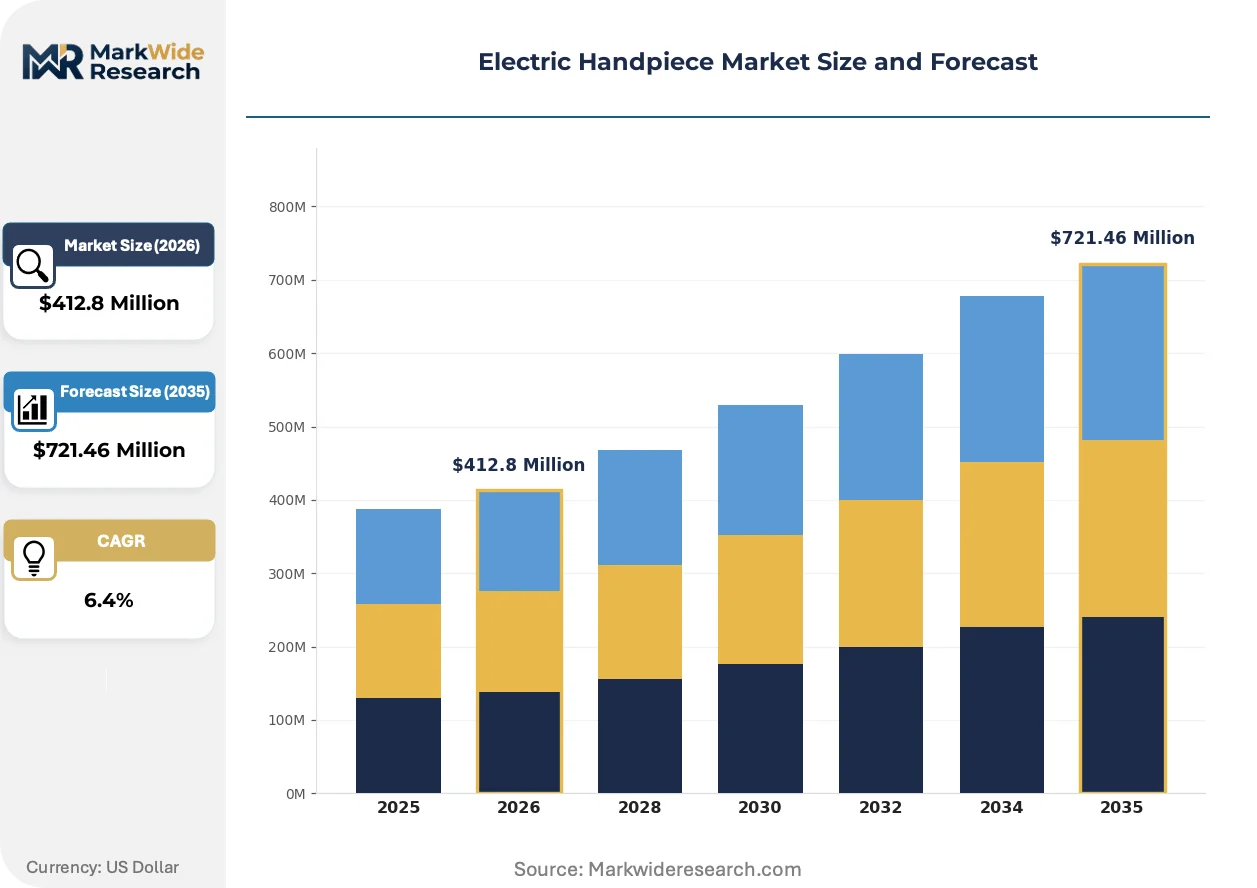
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $721.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Handpieces, Low-Speed Handpieces, Surgical Handpieces, Electric Micromotors End User: Dental Clinics, Hospitals, Oral Surgeons, Research Institutes Technology: Brushless, Brush Type, Cordless, Wired Application: Restorative Dentistry, Oral Surgery, Preventive Care, Cosmetic Dentistry |
| Companies Covered | W&H Dentalwerk Bürmoos GmbH, J. Morita Corporation, Dentsply Sirona Inc., Sable Industries Inc., COXO Medical Instrument Co., Ltd., KaVo Dental GmbH, Bien-Air Holding SA, Danaher Corporation, NSK Nakanishi Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Handpiece Market Shifts & Advancements
Digital dentistry workflows are integrating handpiece telemetry with practice management systems, creating new value layers beyond the physical instrument itself.
Brushless DC motor technology is overtaking traditional brushed architectures in high-speed handpiece segments. Dental OEMs in Germany and Japan are accelerating platform conversions to capture extended sterilization cycle ratings and reduced maintenance intervals. This transition is compressing aftermarket service revenue pools while elevating upfront equipment pricing power for manufacturers with validated thermal endurance credentials.
China's NMPA tightened registration requirements for active implantable surgical instruments in alignment with international harmonization initiatives. Domestic manufacturers must now submit clinical-evaluation reports comparable to EU MDR technical documentation, elevating barrier heights for low-cost competitors. Multinational suppliers with established Shanghai regulatory affairs infrastructure are capturing accelerated approval timelines relative to new entrants.
Multi-chair clinic operators are consolidating vendor relationships around single-source digital dentistry ecosystems. Independent dental supply distributors are losing shelf space to integrated equipment-and-software procurement contracts championed by major manufacturers. This concentration is most visible in North American group practice chains where standardization protocols override individual clinician brand preferences.
Electric Handpiece Market Segmentation
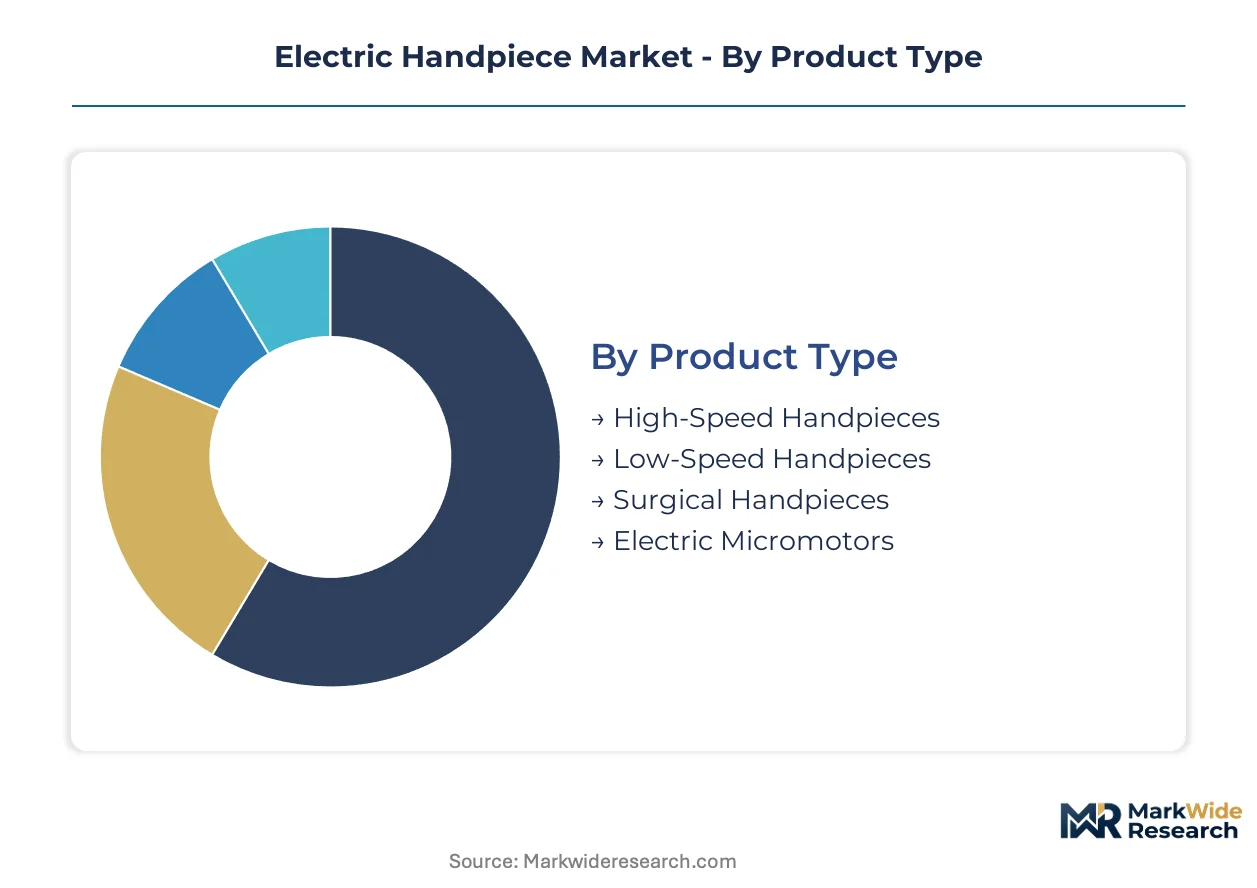
Segmentation in the electric handpiece market reveals how procurement priorities diverge across clinical settings and regulatory environments. Understanding these divides helps manufacturers align certification investments with revenue concentration.
Product Type:
FDA 510(k) clearance requirements vary sharply by product type, with surgical handpieces facing the most stringent active-implantable instrument pathways while high-speed variants navigate streamlined pneumatic-equivalence routes.
- High-Speed Handpieces:These instruments operate at 150,000 to 200,000 RPM with ceramic bearing assemblies that withstand repeated autoclave cycles. Demand clusters in German precision manufacturing clusters supplying Baden-Württemberg OEMs, driven by replacement of legacy air-turbine fleets in North American group practices.
- Surgical Handpieces:Torque-calibrated units for bone cutting and implantology command premium positioning through validated sterilization protocols under EU MDR Class IIa requirements. Oral surgeons in hospital settings generate the steepest margin contribution due to precision demands and lower price sensitivity.
- Low-Speed Handpieces:Prophylaxis and polishing applications at 5,000 to 40,000 RPM serve high-volume preventive workflows in multi-chair clinics.
- Electric Micromotors:Detachable motor units with autoclavable couplings enable modular system architectures that reduce cross-contamination risk.
High-speed handpieces sit at the top of the volume ranking, with electric micromotors climbing the fastest as modular procurement gains traction.
End User:
Customer type determines purchasing authority structure, with hospital procurement departments enforcing centralized vendor consolidation while independent dental clinics retain individual clinician discretion.
- Dental Clinics:Private practices and group chains drive standardization protocols that override brand preferences, particularly in North American DSO networks. These facilities prioritize cordless battery systems and integrated digital dentistry workflows to maximize chair utilization.
- Hospitals:Centralized supply chains and infection-control committees mandate FDA-cleared sterilization validation and extended thermal cycling documentation. Academic medical centers in the US and EU anchor demand for surgical-grade precision instruments.
- Oral Surgeons:Hospital-based and ambulatory surgical centers require torque-calibrated micromotors for implantology with validated clinical-evaluation reports.
- Research Institutes:University dental schools and biomaterials laboratories procure specialized instrumentation for experimental protocols and training curricula.
Dental clinics capture the largest addressable base, though hospitals are expanding most quickly as surgical dentistry migrates into integrated health systems.
Technology:
Technology choice dictates supply chain exposure, with brushless configurations dependent on Chinese-processed neodymium magnets while cordless variants require lithium-polymer cell sourcing strategies.
- Brushless:DC motor architectures with electronic commutation eliminate carbon brush wear, extending sterilization cycle ratings beyond 1,000 autoclave exposures. German and Japanese OEMs dominate this segment through validated thermal endurance credentials.
- Brush Type:Traditional brushed motors persist in price-sensitive emerging markets where maintenance intervals and heat generation trade-offs are acceptable.
- Cordless:Lithium-polymer battery packs with induction charging protocols eliminate hose tethering constraints in multi-chair layouts. This segment is gaining share fastest as mobility demands intensify.
- Wired:Tethered configurations retain installed-base presence in legacy clinic infrastructure with established pneumatic-to-electric conversion timelines.
Brushless technology holds the dominant revenue position, with cordless systems showing the steepest expansion trajectory as battery density improves.
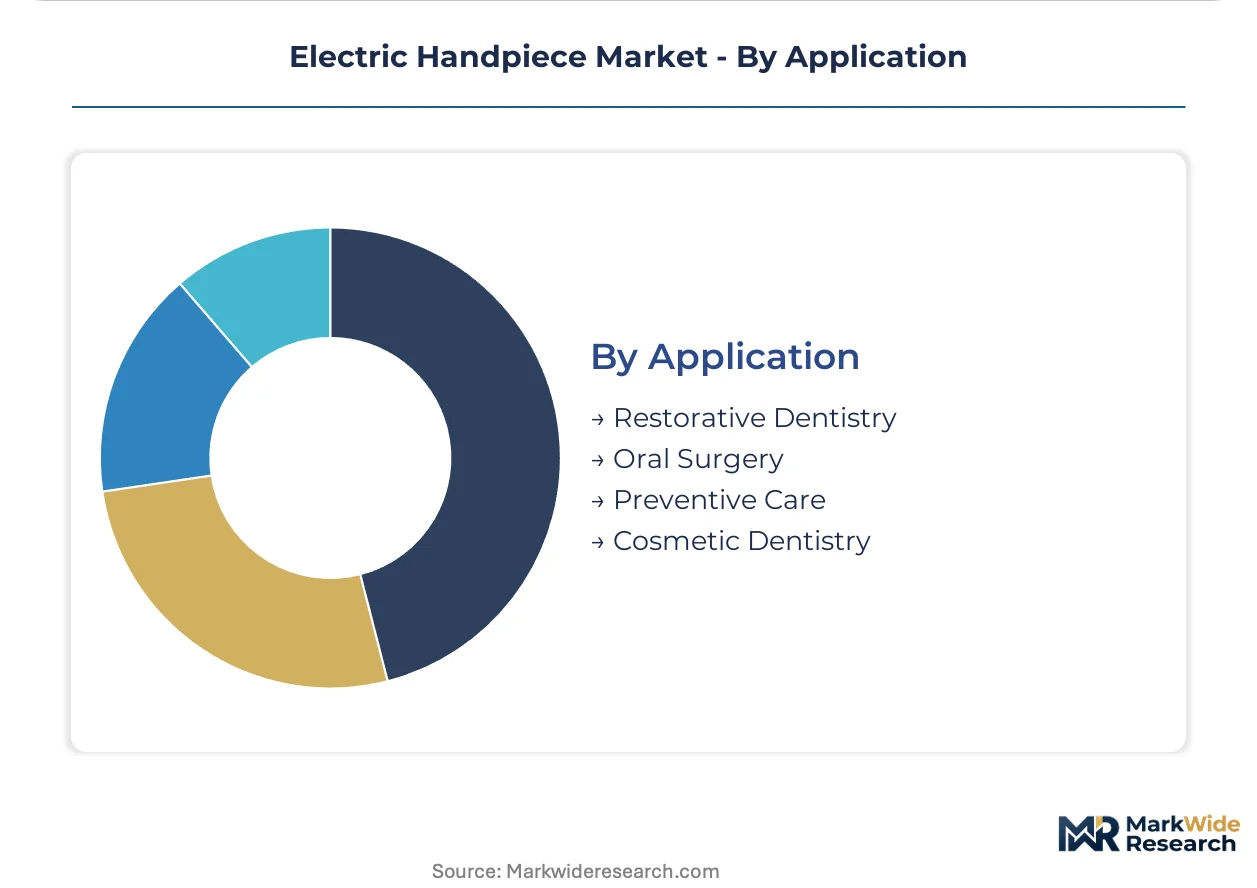
Application:
Application focus determines reimbursement alignment and procedure volume exposure, with restorative and preventive categories tied to dental insurance coverage while cosmetic segments track discretionary spending cycles.
- Restorative Dentistry:Crown preparation, cavity excavation, and amalgam removal constitute the highest procedure frequency in general dental practice. This application anchors demand for high-speed cutting efficiency and dust evacuation integration.
- Oral Surgery:Bone osteotomy, third-molar extraction, and implant site preparation require surgical handpieces with torque feedback and irrigation channel sterilization validation.
- Preventive Care:Prophylaxis polishing and sealant placement drive low-speed handpiece utilization in hygiene-operated workflows.
- Cosmetic Dentistry:Veneer preparation and enameloplasty procedures prioritize precision control and minimal invasiveness for aesthetic outcomes.
Restorative dentistry commands the deepest volume base, with cosmetic applications expanding most quickly as patient-funded elective procedures rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electric handpiece industry traces its modern origins to precision engineering clusters in Central Europe and Japan, where dental instrument manufacturing scaled through post-war industrial policy and university-industry collaboration in the mid-twentieth century.
Germany
Baden-Württemberg's precision manufacturing corridor supplies ceramic bearings and high-torque micromotors to global dental OEMs, with Stuttgart-based component fabricators serving as the primary sourcing node for premium handpiece assemblies. The EU MDR's Class IIa classification for active surgical instruments is elevating compliance documentation requirements for manufacturers exporting from German ports. Freiburg and Tübingen university hospitals anchor clinical validation partnerships that accelerate regulatory approval timelines for new sterilization protocols.
United States
Group dental service organizations across Texas and Florida are consolidating procurement around standardized electric handpiece fleets, replacing legacy air-turbine infrastructure in multi-chair clinic rollouts. The FDA's 510(k) clearance pathway for powered surgical instruments is extending premarket notification timelines as substantial equivalence demonstrations grow more complex. Minneapolis and Boston medical device clusters house regulatory affairs specialists managing simultaneous FDA and international conformity submissions for brushless motor platforms.
Japan
Osaka and Nagoya precision tool manufacturers are advancing micromotor miniaturization for endodontic torque calibration, with specialized low-speed applications commanding premium positioning distinct from commoditized cutting segments. The PMDA's alignment with IMDRF harmonization initiatives is streamlining clinical evaluation report formats for manufacturers seeking parallel US-Japan approvals. Chiba Prefecture's industrial zone concentrates final assembly operations for export-oriented dental equipment divisions.
China
Shanghai and Suzhou dental equipment manufacturers are navigating NMPA's tightened registration requirements for active implantable surgical instruments, which now demand technical documentation comparable to EU MDR standards. The Yangtze River Delta's medical device industrial parks are attracting multinational suppliers establishing captive regulatory affairs infrastructure to accelerate approval timelines. Shenzhen battery technology suppliers are converging with dental OEMs to develop lithium-polymer power systems for cordless handpiece integration.
India
Maharashtra and Gujarat dental equipment distributors are formalizing procurement relationships as BIS certification requirements expand for imported powered surgical instruments, creating first-mover positioning for compliant manufacturers. The CDSCO's medical device rules are elevating barrier heights for low-cost competitors previously operating under informal import channels. Mumbai's specialty dental clinic chains are piloting cordless handpiece deployments in high-volume preventive care workflows.
Electric Handpiece Market Competitive Landscape
The competitive structure tilts toward integrated dental equipment conglomerates with captive distribution networks and validated sterilization credentials. Tiered positioning separates premium manufacturers with extended autoclave cycle ratings from economy suppliers serving price-sensitive replacement markets. Three archetypes dominate: precision engineering specialists with university hospital validation partnerships, full-service dental equipment platforms bundling handpieces with imaging and software systems, and component-focused suppliers selling motors and bearings to third-party assemblers. Capacity expansion in cordless battery integration and strategic partnerships for induction charging protocols represent the dominant competitive vectors.
Among Austrian and German precision engineering specialists, W&H Dentalwerk Bürmoos GmbH and KaVo Dental GmbH occupy positions exemplifying premium-tier manufacturing anchored in Central European industrial clusters. Japanese manufacturers J. Morita Corporation and NSK Nakanishi Inc. represent the micromotor specialization archetype, with their geographic origin signaling torque-calibration expertise for endodontic applications. These named entities serve as anchors for understanding how regional engineering traditions translate into distinct competitive positioning across brushless motor and cordless technology vectors.
| Leading Market Players |
|---|
| W&H Dentalwerk Bürmoos GmbH |
| J. Morita Corporation |
| Dentsply Sirona Inc. |
| Sable Industries Inc. |
| COXO Medical Instrument Co., Ltd. |
| KaVo Dental GmbH |
| Bien-Air Holding SA |
| Danaher Corporation |
| NSK Nakanishi Inc. |
| Others |
Supply & Pricing Matrix
Group dental service organizations across Texas and Florida are mandating standardized electric handpiece fleets with validated sterilization credentials, forcing component suppliers in Baden-Württemberg and Osaka to qualify dual-source manufacturing partnerships that elevate upfront tooling investments and compress margin contribution from mid-tier configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with ISO 14457 certification grade and autoclave cycle endurance serving as the primary price differentiation drivers. Cost compression in the economy tier is intensifying because Shenzhen battery suppliers are commoditizing cordless lithium-polymer configurations. Hospital procurement departments exhibit the lowest price sensitivity due to infection-control liability exposure, while independent single-chair clinics in emerging markets remain the most price-sensitive buyer segment.
Supply Chain Analysis
Dual-sourcing requirements from North American group practices are mandating multi-supplier qualification for ceramic bearings and neodymium magnet rotors, drawing manufacturing capacity from Germany, Japan, and China. Raw material dependencies center on rare-earth magnet processing, precision-machined ceramic bearings, and medical-grade lithium-polymer cells. Single-source vulnerability concentrates in Chinese neodymium separation facilities. Distribution runs through integrated dental equipment conglomerates with captive GPO contracts and direct hospital system partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric handpiece market functions as a regulatory compounder where EU MDR Class IIa clinical-evaluation mandates are accelerating replacement demand for certified sterilization protocols.
For Market Incumbents: Anchor premium positioning through backward integration into ceramic bearing manufacturing in Baden-Württemberg, eliminating dependency on Stuttgart component fabricators. Capture channel control by bundling handpiece telemetry with practice management software subscriptions, defending against cordless commoditization from Shenzhen battery suppliers. For New Entrants and Emerging Players: Cordless induction-charging protocols for multi-chair clinic layouts offer a technology-first wedge into underpenetrated Indian dental equipment formalization. Target Maharashtra specialty clinic chains with BIS-compliant sterilization validation ahead of domestic competitors. Pursue white-label manufacturing partnerships with Yangtze River Delta medical device parks to bypass NMPA registration timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with precision micromotor specialists holding university hospital validation partnerships in Freiburg and Tübingen. Long-term viability over a multi-year horizon favors manufacturers with captive regulatory affairs infrastructure across FDA, EU MDR, and NMPA jurisdictions. Watch NMPA approval velocity for Shanghai-based multinational suppliers as the inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Clinical-evaluation documentation under EU MDR filters low-quality imports and consolidates demand around validated manufacturers. |
| Backward Integration into Ceramic Bearings | Captive supply of precision-machined bearings from Baden-Württemberg fabricators reduces input cost volatility and accelerates sterilization cycle validation. |
| Cordless Battery System Development | Lithium-polymer power systems with induction charging from Shenzhen suppliers eliminate hose tethering constraints in multi-chair layouts. |
| Hospital System Partnership | Direct procurement contracts with academic medical centers in Minneapolis and Boston anchor demand for surgical-grade precision instruments. |
| Digital Dentistry Workflow Integration | Telemetry-enabled handpieces feeding practice management systems create recurring revenue layers beyond equipment sales. |
Research Methodology
Multiple input streams — primary interviews with dental equipment procurement managers, biomedical engineers at university hospitals, and GPO contracts specialists; secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and NMPA registration records; alongside customs data from German and Japanese port authorities — were reconciled through bottom-up and top-down triangulation.
Historical shipment data from precision manufacturing clusters in Baden-Württemberg and Osaka were cross-referenced against panel input from dental supply distributors across North America and Europe. The analytical framework modeled volume and value across product type, technology architecture, end-user setting, and regional regulatory cluster throughout the forecast period. CAGRs were derived from sterilization cycle replacement rates and cordless adoption curves in multi-chair clinic deployments.
The model holds under stable regulatory harmonization trajectories; deviation in NMPA enforcement intensity or neodymium export restrictions from Chinese processing facilities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Spinal Surgery Devices Market
Medical Devices
Medical Pendant Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
United Kingdom Respiratory Devices Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Global Medical Devices Market
Medical Devices
PET Injectors Market
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market
Medical Devices
Specimen Retrieval Market
Medical Devices
North America Invisible Orthodontics Market