
 Intravenous Line Connectors Market | 2026-2036
Intravenous Line Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Intravenous Line Connectors Market Foresight
The EU Medical Device Regulation is consolidating purchasing criteria around sterility assurance and single-use compliance across European hospital systems. Becton, Dickinson and Company leverages its integrated manufacturing footprint to sustain catheter-to-connector bundling contracts with large health networks. ICU Medical, Inc. anchors its position through proprietary needleless connector designs that dominate oncology and critical care protocols. B. Braun Melsungen AG competes on closed-system transfer device integration, extending its reach into hazardous drug handling workflows.
Intravenous line connectors are luer-activated or needleless mechanical interfaces engineered from medical-grade polymers to establish sealed fluid pathways between infusion sets, catheters, and medication sources. These devices incorporate silicone valve membranes or split-septum architectures to maintain pressure tolerance while preventing microbial ingress and backflow contamination. Safety connectors lead the product type landscape due to needlestick prevention mandates, while multi-access connectors represent the fastest-expanding category as complex chemotherapy and biologic infusion protocols proliferate in oncology units. Polyurethane material segments command premium positioning where extended indwelling periods and lipid compatibility are required.
The FDA enforces 510(k) clearance pathways for needleless connectors with explicit fluid displacement and priming volume performance thresholds, while the EU MDR mandates updated clinical evidence and post-market surveillance for all Class IIa infusion accessories. ISO 80369-7 governs luer connector dimensions and interchangeability, directly shaping R&D allocation toward standardized yet differentiated locking mechanisms. Stakeholders must monitor evolving EPA and state-level single-use plastic restrictions that could force material transitions from PVC toward bio-based polypropylene alternatives.
Market Dynamics
The EU MDR sterility mandates and FDA 510(k) fluid displacement thresholds are forcing manufacturers to consolidate around validated closed-system architectures, compressing R&D cycles and elevating compliance costs across the connector supply base.
Growth Catalysts
- Oncology infusion protocols:Complex chemotherapy and biologic administration regimens in US and European cancer centers are driving multi-access connector adoption for simultaneous medication delivery.
- Needlestick prevention mandates:OSHA bloodborne pathogen standards and equivalent EU worker safety directives enforce safety-engineered device procurement in hospital systems.
- REACH substance restrictions:ECHA phased prohibitions on phthalate plasticizers in medical polymers are accelerating bio-based polyurethane and polypropylene material transitions.
Market Restraints
- Medical-grade polymer supply concentration:Specialty silicone and thermoplastic elastomer feedstock production clusters in Germany and Japan create vulnerability to regional logistics disruptions.
- ISO 80369-7 interchangeability compliance:Dimensional tolerances for luer connectors limit proprietary design differentiation and compress margin on standardized products.
- Closed-system transfer device substitution:Hazardous drug handling workflows in US oncology units increasingly favor integrated CSTD-connector combinations over standalone components.
Strategic Opportunities
- Home infusion therapy expansion:US Medicare reimbursement shifts toward outpatient parenteral antimicrobial and hydration therapy are creating demand for patient-operable needleless connectors.
- EPA single-use plastic restrictions:State-level prohibitions on PVC disposal are opening procurement pathways for bio-based polypropylene and polylactic acid connector alternatives.
- Digital health convergence:Integration of RFID-enabled connectors with smart infusion pumps enables dose-tracking and diversion monitoring in hospital pharmacy workflows.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and hemocompatibility validation for new polymer formulations extends product development cycles by 18-24 months.
- Legacy catheter interface compatibility:Hospital installed bases of varying luer-lock and non-standard port designs complicate universal connector deployment and increase SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravenous Line Connectors Market |
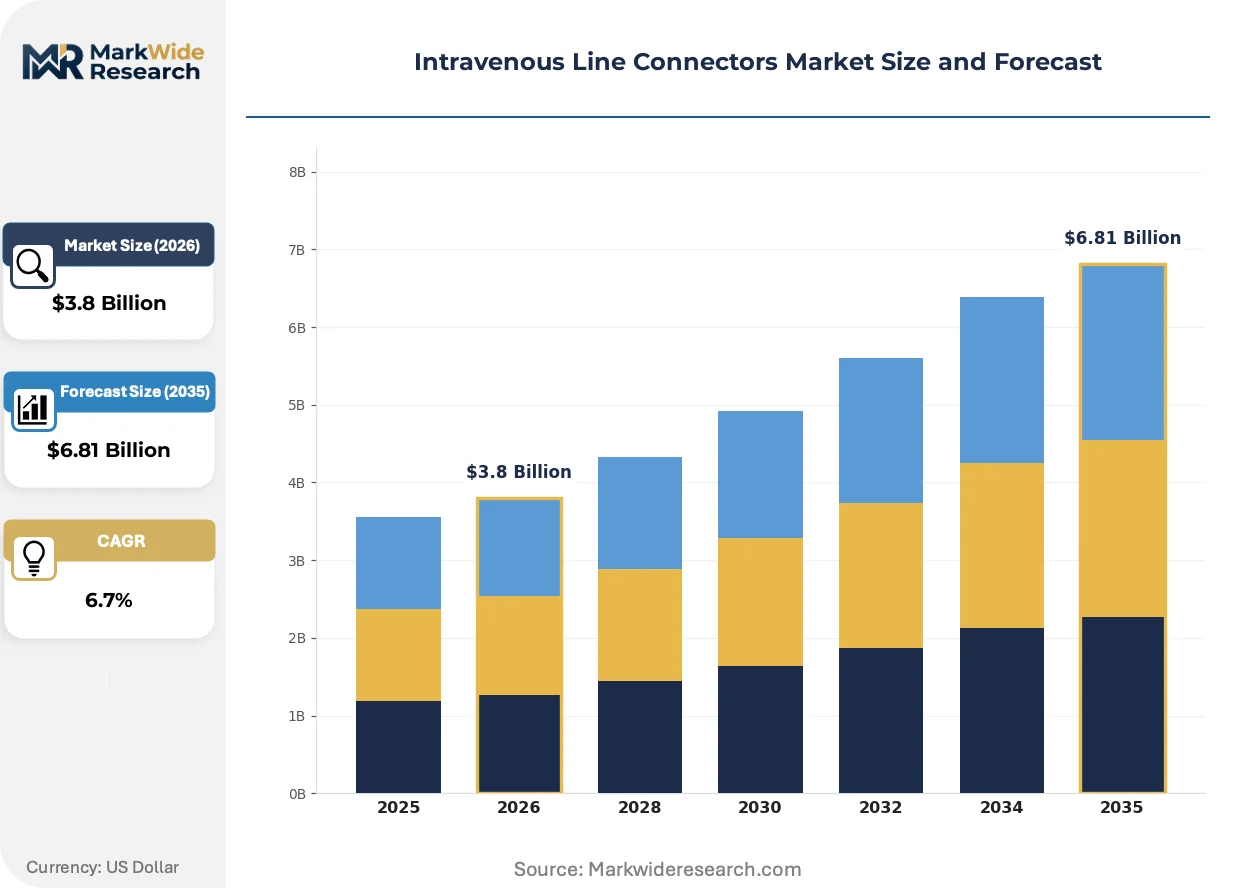
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spike Connector, Y-Site Connector, Safety Connector, Multi-Access Connector Material: Polypropylene, PVC, Silicone, Polyurethane End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Application: Medication Administration, Fluid Management, Blood Transfusion, Parenteral Nutrition |
| Companies Covered | Becton, Dickinson and Company, ICU Medical, Inc., B. Braun Melsungen AG, Baxter International Inc., CareFusion Corporation, Smiths Medical, Vygon SA, Merit Medical Systems, Inc., Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravenous Line Connectors Market Shifts & Advancements
Active valve membrane engineering and antimicrobial surface coatings are displacing passive split-septum designs in premium connector tiers, while regulatory pressure on material traceability is forcing supply chain digitization investments.
Antimicrobial-impregnated silicone valve technology is expanding into long-dwell central venous access applications where biofilm prevention justifies premium positioning. US academic medical centers with high bloodstream infection penalties are adopting these connectors for ICU and oncology populations. The technology is expanding into pediatric and immunocompromised patient segments previously considered cost-prohibitive.
The EU MDR post-market surveillance requirements and Unique Device Identification mandates are compelling manufacturers to deploy lot-level traceability systems across European distribution channels. German and French hospital procurement consortia now require electronic device history records as a contract precondition. Smaller connector specialists without integrated ERP-to-regulator data pipelines face exclusion from tier-one supply agreements.
Hospital pharmacy consolidation into centralized compounding operations is compressing the connector specification process from departmental autonomy to enterprise standardization. US health system formularies increasingly mandate single-manufacturer catheter-connector bundling to simplify inventory and training. This concentration is most visible in the southeastern and midwestern United States where regional hospital networks have absorbed independent community facilities.
Intravenous Line Connectors Market Segmentation
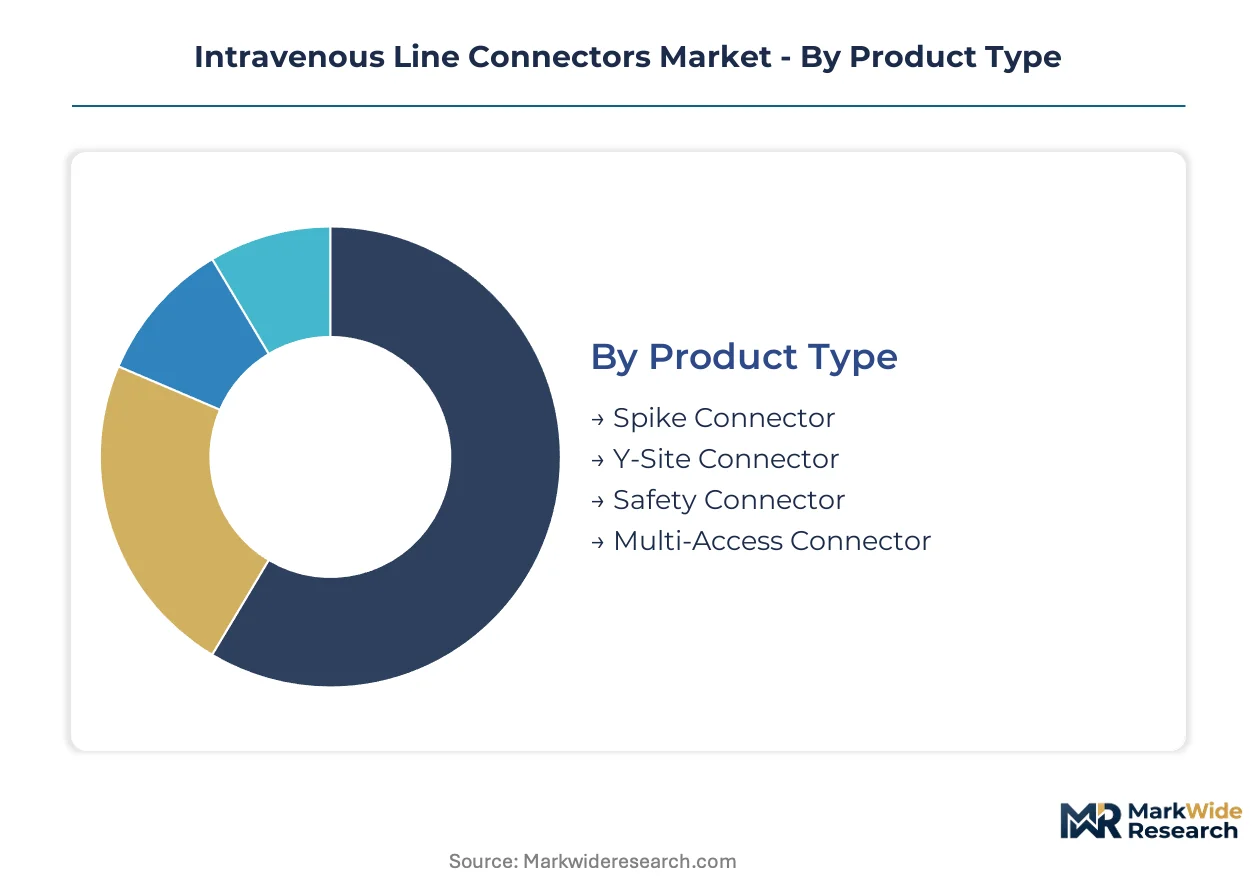
Connector specification in hospital procurement increasingly hinges on material traceability and closed-system validation rather than unit cost alone. Segmentation strategies must align with diverging regulatory timelines across FDA 510(k) pathways and EU MDR sterility mandates.
Product Type:
Supply concentration in safety-engineered designs has compressed development cycles for passive needlestick prevention architectures.
- Safety Connector:OSHA bloodborne pathogen standards mandate these needleless interfaces across US hospital systems. Demand concentrates in high-acuity units where clinician exposure risk justifies premium positioning against split-septum alternatives.
- Multi-Access Connector:Silicone valve membranes enable simultaneous medication delivery in oncology infusion protocols. US cancer centers and European academic hospitals are standardizing these for complex chemotherapy regimens requiring multiple concurrent lines.
- Spike Connector:Luer-activated designs for gravity-fed fluid bags remain prevalent in emerging market tertiary facilities with limited pump infrastructure.
- Y-Site Connector:Passive split-septum variants serve cost-sensitive clinical settings where single-access medication delivery suffices.
Safety connectors absorb the bulk of installed capacity; multi-access connectors are expanding most quickly.
Material:
REACH substance restrictions and EPA state-level disposal mandates are fragmenting polymer supply chains toward bio-based alternatives.
- Polyurethane:Lipid-compatible formulations with extended indwelling tolerance command premium positioning in US ICU and long-term parenteral nutrition applications. Academic medical centers with bloodstream infection penalties are absorbing these despite 40-60% cost premiums over standard polymers.
- Silicone:Platinum-cured elastomers dominate valve membrane production for needleless connectors requiring compression set resistance. German and Japanese feedstock clusters create vulnerability to regional logistics disruptions.
- Polypropylene:Bio-based variants are gaining procurement traction in Scandinavian hospital systems ahead of EU single-use plastic directives.
- PVC:Phthalate-plasticized grades face phased ECHA prohibitions, forcing reformulation or material substitution across European distribution channels.
Polyurethane captures the steepest pricing tier; polypropylene is climbing the fastest on sustainability procurement criteria.
End User:
Reimbursement shifts toward outpatient settings are redistributing connector demand from inpatient wards to patient-operable designs.
- Hospitals:Centralized pharmacy formularies in US health networks are consolidating catheter-connector specifications toward single-manufacturer bundling. Southeastern and midwestern regional systems have absorbed independent community facilities into standardized procurement protocols.
- Home Care:Medicare reimbursement for outpatient parenteral antimicrobial therapy is creating demand for intuitive needleless interfaces operable by non-clinical caregivers. Patient training burden and error tolerance are critical design constraints.
- Ambulatory Surgical Centers:High-throughput same-day procedures favor disposable connectors with minimal priming volume to accelerate turnover.
- Clinics:Federally qualified health centers and infusion suites prioritize cost-minimized standard luer-lock compatibility over advanced valve features.
Hospitals retain dominant volume share; home care is gaining share fastest on reimbursement migration.
Application:
Workflow integration with smart infusion pumps is elevating connector specification from passive tubing to active dose-verification nodes.
- Medication Administration:Oncology biologics and chemotherapy require pressure-tolerant needleless connectors with antimicrobial surface coatings. US academic medical centers with high CLABSI penalties are adopting premium tiers for ICU and immunocompromised populations.
- Fluid Management:Hydration therapy and electrolyte replacement utilize standardized luer-activated designs with minimal dead space. Demand concentrates in emergency departments and perioperative recovery units.
- Blood Transfusion:Specialized high-flow connectors with filter integration serve massive transfusion protocols in trauma centers.
- Parenteral Nutrition:Lipid emulsion compatibility requirements favor polyurethane construction for extended dwell central venous access in intestinal failure patients.
Medication administration commands the largest specification volume; parenteral nutrition is expanding most quickly on home infusion therapy growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's medical device corridor concentrates European connector manufacturing, while Minneapolis anchors North American production. Japanese silicone suppliers and Chinese polymer processors complete the supply triad.
United States
Aging demographics and chronic disease prevalence sustain high inpatient infusion therapy demand across southeastern and midwestern hospital networks. OSHA bloodborne pathogen standards enforce safety-engineered device procurement in all acute care settings. The Minneapolis-St. Paul medical device cluster hosts integrated catheter-connector manufacturing for large health system bundling contracts.
Germany
REACH substance restrictions on phthalate plasticizers accelerate bio-based polyurethane transitions across European distribution channels. The EU MDR mandates updated clinical evidence and post-market surveillance for Class IIa infusion accessories. The Frankfurt-Rhine-Main corridor concentrates specialty silicone and thermoplastic elastomer feedstock production for valve membrane manufacturing.
Japan
Platinum-cured silicone elastomer production clusters serve compression set-resistant valve membrane demand for needleless connectors. METI industrial standards govern medical-grade polymer purity specifications. The Nagoya-Chubu region houses precision polymer processing facilities supplying connector manufacturers across Asia-Pacific.
China
Domestic hospital infrastructure expansion drives standardized luer-activated connector procurement in tertiary facilities. NMPA medical device registration pathways align with ISO 80369-7 dimensional tolerance requirements. The Yangtze River Delta medical device manufacturing zone produces cost-optimized connectors for emerging market export.
India
Government hospital procurement programs expand access to disposable infusion components in tier-2 and tier-3 cities. CDSCO medical device rules implement risk-based classification for intravenous accessories. The Maharashtra pharmaceutical manufacturing corridor integrates connector supply into domestic oncology drug production workflows.
Intravenous Line Connectors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material traceability and closed-system validation capabilities. The vendor base stratifies into three tiers: integrated multinational manufacturers with catheter-to-connector bundling contracts, mid-scale specialists with proprietary valve architectures, and regional fabricators competing on standard luer-lock compatibility. Dominant competitive moves include strategic partnerships with smart infusion pump manufacturers and geographic expansion into Medicare-funded home infusion markets.
Within the integrated multinational tier, Becton, Dickinson and Company and ICU Medical, Inc. exemplify divergent strategic positions. Becton, Dickinson and Company occupies a position anchored in manufacturing footprint breadth, while ICU Medical, Inc. represents specialized focus on proprietary needleless designs. B. Braun Melsungen AG sits within the European-centered archetype with closed-system transfer device integration capabilities.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| ICU Medical, Inc. |
| B. Braun Melsungen AG |
| Baxter International Inc. |
| CareFusion Corporation |
| Smiths Medical |
| Vygon SA |
| Merit Medical Systems, Inc. |
| Nipro Corporation |
| Others |
Supply & Pricing Matrix
Specialized polymer compounding expertise in the Frankfurt-Rhine-Main corridor and Nagoya-Chubu region creates labor-cost differentials that stretch pricing-tier spreads between premium antimicrobial-coated connectors and commodity luer-lock alternatives.
Pricing Analysis
Value-based pricing anchors to bloodstream infection reduction outcomes in US academic medical centers with CLABSI penalties. Three-tier pricing structure across premium, standard, and economy levels separates antimicrobial-impregnated polyurethane from standard silicone and PVC alternatives. Cost compression in the economy tier intensifies as Chinese manufacturers expand standardized luer-activated production. Federally qualified health centers and emerging market tertiary facilities exhibit the highest price sensitivity, while US cancer centers with bundled oncology contracts show the least.
Supply Chain Analysis
Workforce availability for platinum-cured silicone processing concentrates in Germany, Japan, and select US medical device clusters. Raw material flows draw from German thermoplastic elastomer feedstock, Japanese silicone monomer production, and Chinese polymer compounding capacity. Single-source vulnerability runs through Japanese valve membrane specialists serving compression set-resistant applications. Distribution runs through health system GPO contracts in the US, hospital procurement consortia in Germany and France, and government tender programs in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: specialty silicone and bio-based polyurethane capacity expansion lags demand growth from oncology protocol proliferation, propping pricing in premium tiers.
For Market Incumbents: Cement catheter-to-connector bundling relationships with southeastern and midwestern US health networks before pharmacy consolidation completes. Deepen backward integration into platinum-cured silicone membrane production to offset Japanese feedstock concentration risk. Prioritize EU MDR post-market surveillance infrastructure to defend tier-one supply agreements against mid-scale specialists lacking ERP-to-regulator data pipelines. For New Entrants and Emerging Players: EPA single-use plastic restrictions in California and New York open a window for bio-based polypropylene and polylactic acid connector alternatives ahead of broader mandates. Home infusion therapy reimbursement expansion creates the most penetrable white space, with patient-operable needleless interfaces for Medicare-funded outpatient parenteral antimicrobial therapy. Pursue direct-to-patient training partnerships with home health agencies as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale connector specialists possessing proprietary valve architectures and EU MDR compliance infrastructure given hospital procurement consolidation favoring standardized suppliers. The five-to-ten-year viability window favors targets with integrated antimicrobial coating capabilities and RFID-enabled smart pump compatibility. Watch FDA 510(k) clearance backlogs for needleless connectors as an inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Surface Coating Development | US academic medical centers with CLABSI penalties absorb 40-60% cost premiums for biofilm prevention. |
| RFID-Enabled Connector Integration | Smart infusion pump interoperability enables dose-tracking and diversion monitoring in hospital pharmacy workflows. |
| Bio-Based Polypropylene Transition | Scandinavian hospital systems and EPA state-level mandates create procurement pathways ahead of EU directives. |
| Closed-System Transfer Device Integration | US oncology units increasingly favor CSTD-connector combinations over standalone components for hazardous drug handling. |
| Home Infusion Therapy Product Line | Medicare reimbursement shifts toward outpatient parenteral antimicrobial therapy demand patient-operable interfaces. |
Research Methodology
Document review covered FDA 510(k) clearances, EU MDR technical documentation, and hospital GPO contract databases, complemented by interviews with biomedical engineers, oncology pharmacy directors, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from ISO 80369-7 standards filings, REACH substance restriction updates, EPA state-level disposal mandate tracking, and CMS Medicare reimbursement policy releases. Bottom-up demand modeling across end-user segments triangulated against top-down manufacturer capacity assessments.
Segmentation outputs span product type, material composition, end-user setting, and application workflow across the projection horizon. Modeled dimensions include safety-engineered versus standard architectures, polyurethane-silicone-polypropylene-PVC material tiers, hospital-home care-ambulatory-clinic delivery settings, and medication administration-fluid management-blood transfusion-parenteral nutrition applications. CAGRs were derived from surgical volume projections, chronic disease prevalence trends, and reimbursement policy trajectory analysis. Infusion pump installed base growth and oncology protocol complexity indices served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for active valve membrane and antimicrobial surface coating penetration; alternative pathways for passive split-septum retention would alter the outlook. Forecasts reflect assumptions around EU MDR implementation timelines, EPA single-use plastic restriction geographic expansion, and Medicare home infusion reimbursement stability. Material deviation in specialty silicone feedstock availability, FDA 510(k) clearance velocity, or health system bundling contract concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wearable Medical Robots Market
Medical Devices
Pericardial Patches Market
Medical Devices
EMG Biosensors Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Submucosal Injections Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Contact Thermometer Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
United States Organ Preservation Market