
 Transcranial Magnetic Stimulator for Depression Requisition Market | 2026-2036
Transcranial Magnetic Stimulator for Depression Requisition Market Size, Share, and Industry Trends Forecast 2026-2036
Transcranial Magnetic Stimulator for Depression Requisition Market Insights
ISO 13485 certification is unwinding the competitive landscape for device manufacturers seeking hospital procurement contracts. Neuronetics leverages its established FDA-cleared platform to sustain institutional loyalty across academic medical centers. BrainsWay differentiates through deep TMS coil geometry that occupies a distinct niche in treatment-resistant depression protocols.
Transcranial magnetic stimulator for depression requisition encompasses the procurement, specification, and contractual acquisition of non-invasive neuromodulation systems delivering pulsed magnetic fields to dorsolateral prefrontal cortex at 1-10 Hz frequencies for major depressive disorder. The primary commercial purpose centers on enabling healthcare systems to source validated therapeutic hardware that meets clinical efficacy benchmarks and institutional workflow requirements. Magnetic coil configurations and repetitive TMS technology command the dominant share of requisition value, with theta burst protocols representing the fastest-growing segment as purchasers prioritize session efficiency and throughput optimization. Treatment delivery devices concentrate margin pools where software-integrated navigation and real-time dosing feedback differentiate premium tenders.
FDA 510(k) clearance and the EU Medical Device Regulation frame product eligibility for institutional buyers, while HIPAA and GDPR compliance requirements shape data-handling specifications in connected monitoring systems. The central bank of procurement decisions rests on how purchasers weight upfront capital expenditure against per-session operational economics as protocol diversity expands. Stakeholders must monitor whether emerging home-use regulatory pathways will fragment requisition authority from hospital supply chains toward direct prescriber-patient channels.
Market Dynamics
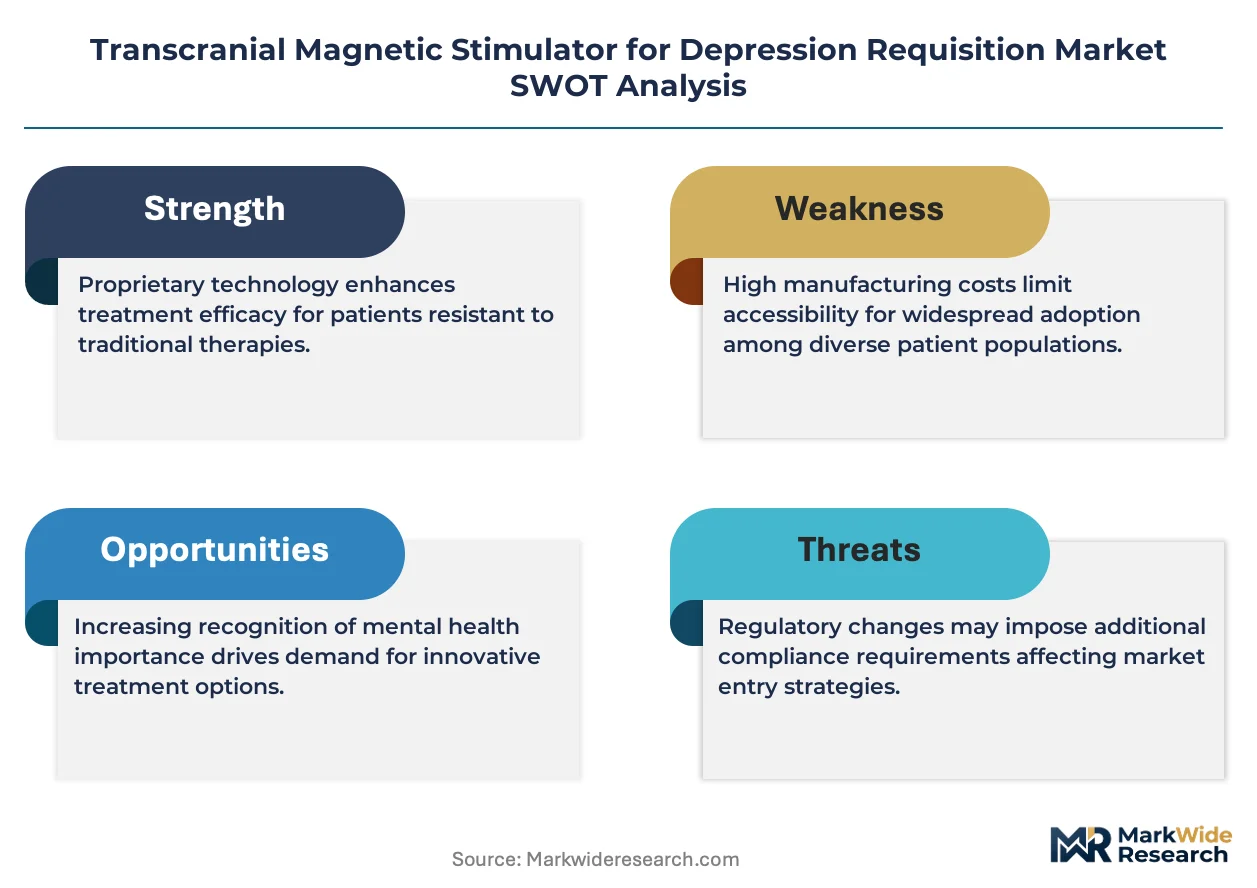
Reimbursement pathway fragmentation is forcing psychiatric clinics to renegotiate capital allocation frameworks for neuromodulation hardware. The divergence between established CMS coverage in the United States and emerging NICE guidance in the United Kingdom is creating procurement uncertainty across hospital networks.
Growth Catalysts
- Deep TMS coil geometry:Psychiatric clinics in Germany are prioritizing H-coil configurations for treatment-resistant depression protocols, expanding requisition volumes for specialized hardware.
- FDA 510(k) clearance streamlining:The de novo pathway for novel magnetic coil designs is compressing time-to-market for device manufacturers targeting academic medical centers.
- Japan's PMDA reimbursement expansion:METI-coordinated coverage decisions for repetitive TMS are unlocking hospital procurement budgets in Tokyo and Osaka metropolitan clusters.
Market Restraints
- Copper and rare-earth magnet cost volatility:Coil assembly inputs face price swings from concentrated Chinese mining operations, squeezing manufacturer margins.
- EU MDR technical documentation burden:The expanded clinical evidence requirements for Class IIa neuromodulation devices are extending certification timelines by 18-24 months.
- Ketamine infusion substitution:Intravenous esketamine clinics are capturing refractory depression patients who would otherwise qualify for TMS protocols.
Strategic Opportunities
- Home-use regulatory pathway emergence:FDA breakthrough device designation for portable TMS systems could fragment requisition authority toward direct prescriber-patient channels.
- Theta burst protocol standardization:The convergence of accelerated dosing algorithms with real-time neuroimaging feedback is opening premium tender opportunities.
- India's CDSCO fast-track mechanism:The country's national pharmaceutical regulator is prioritizing neuromodulation devices under its medical device rules amendment.
Industry Challenges
- ISO 13485 auditor capacity constraints:Certification body backlogs are delaying quality management system approvals for emerging manufacturers.
- Legacy EMR integration complexity:Hospital IT departments face workflow friction connecting TMS dosing software with existing electronic health record architectures.
- Skilled technician scarcity:Certified TMS operator training programs are failing to match installation growth in community mental health centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcranial Magnetic Stimulator for Depression Requisition Market |
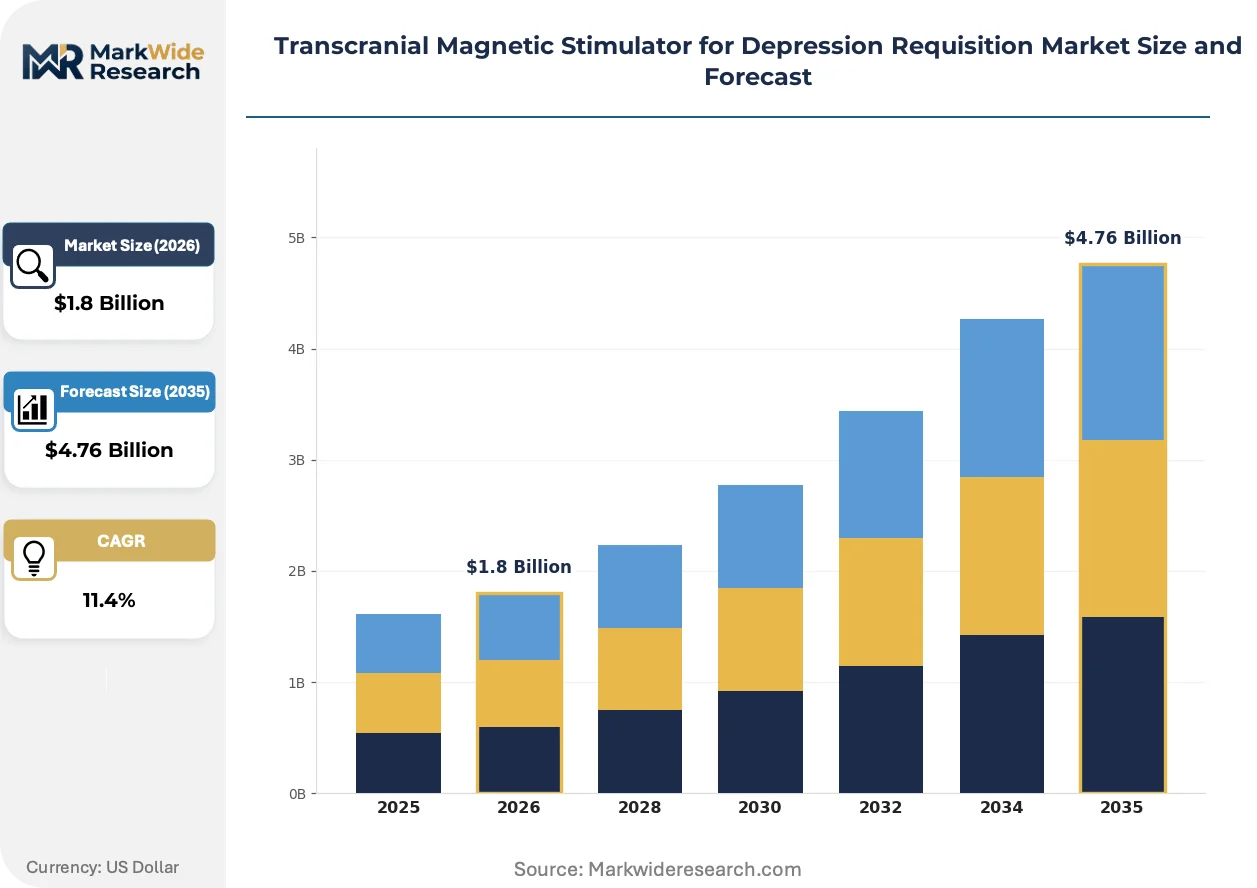
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Coil, System Controller, Treatment Delivery Device, Patient Monitor Technology: Single Pulse, Paired Pulse, Theta Burst, Repetitive TMS Application: Clinical Therapy, Research, Home Use, Hospital Treatment End User: Psychiatrists, Neurologists, Clinics, Research Institutions |
| Companies Covered | Neuronetics, BrainsWay, Magstim, Nexstim, MagVenture, Soterix Medical, neurocare group, Seber Medical, eNeura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcranial Magnetic Stimulator for Depression Requisition Market Trends and Innovations
Magnetic coil engineering and software-integrated navigation are converging to redefine procurement specifications. Hospital buyers are prioritizing session throughput metrics over standalone hardware durability.
Deep TMS H-coil technology is bifurcating the installed base between superficial and deep prefrontal targeting capabilities. Academic medical centers in Boston and Heidelberg are adopting these configurations for obsessive-compulsive disorder comorbidity protocols. The technology is bifurcating competitive positioning between premium navigation-enabled systems and legacy figure-eight coil platforms.
The EU Medical Device Regulation's post-market surveillance requirements are mandating real-world evidence collection from connected TMS devices. Manufacturers must now embed HIPAA-compliant and GDPR-aligned data transmission modules to maintain CE marking validity. German university hospitals are responding by centralizing procurement through consortium frameworks that standardize telemetry specifications.
Session-based leasing models are displacing outright capital purchase for mid-tier psychiatric clinics. Third-party equipment financiers in the United States are underwriting hardware deployments against guaranteed utilization minimums. This shift concentrates most visibly in California and Texas outpatient networks where patient volume forecasting remains volatile.
Transcranial Magnetic Stimulator for Depression Requisition Market Segmentation
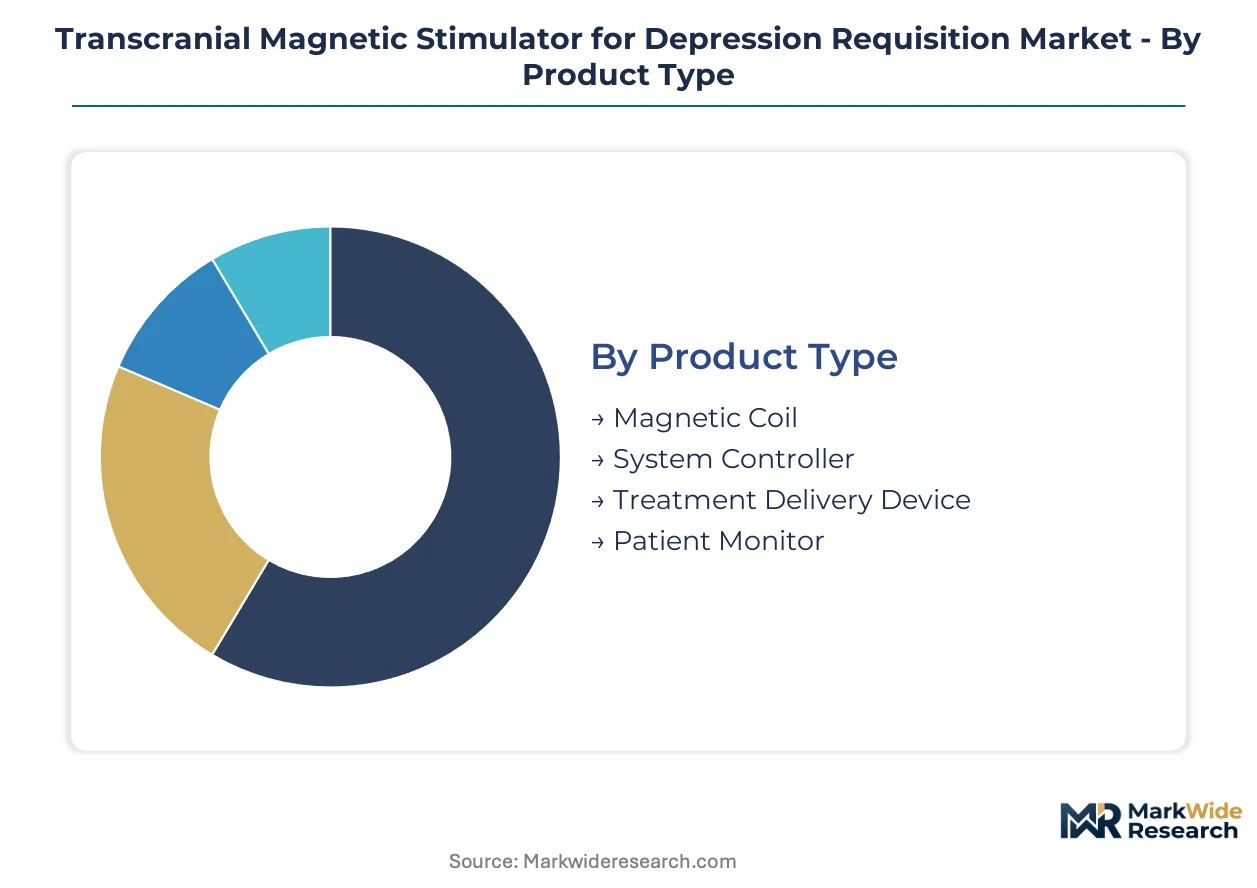
Requisition patterns for transcranial magnetic stimulators diverge sharply across hardware categories and treatment protocols. Procurement officers weight coil geometry against controller integration differently depending on whether installations serve high-volume outpatient networks or specialized academic research programs.
Product Type:
Magnetic coil assemblies dominate export-led procurement from German and Japanese manufacturers, while system controllers and patient monitors concentrate domestic assembly in the United States.
- Magnetic Coil:Copper-wound and rare-earth magnet assemblies determine field penetration depth and spatial resolution. Psychiatric clinics in Germany prioritize H-coil configurations for deep prefrontal targeting, with METI-coordinated procurement in Japan specifying figure-eight geometries for dorsolateral cortex protocols.
- Treatment Delivery Device:Integrated hardware-software platforms manage pulse sequencing, real-time dosing feedback, and navigation alignment. Academic medical centers in Boston and Heidelberg specify these systems for obsessive-compulsive disorder comorbidity programs, with session throughput metrics outweighing standalone durability in tender evaluations.
- System Controller:Pulse generation electronics and waveform modulation circuits form the computational core of TMS installations.
- Patient Monitor:Physiological tracking modules for motor threshold verification and adverse event detection during sessions.
Magnetic coil assemblies hold the largest share; momentum sits with treatment delivery devices as purchasers prioritize software-integrated navigation capabilities.
Technology:
Cost tier stratification separates established repetitive TMS protocols from emerging accelerated dosing methodologies, with theta burst commanding premium positioning.
- Repetitive TMS:Standard 1-10 Hz frequency protocols for major depressive disorder represent the installed base majority. FDA 510(k) clearance pathways and CMS reimbursement frameworks in the United States sustain hospital procurement volumes, though session duration limits throughput optimization.
- Theta Burst:Accelerated triplet-pattern stimulation reduces treatment sessions from 36 to 20 while maintaining efficacy benchmarks. University hospitals in California and Texas outpatient networks are specifying these protocols for capacity-constrained clinics, with third-party equipment financiers underwriting deployments against utilization minimums.
- Single Pulse:Isolated magnetic stimulation for motor threshold mapping and neurophysiological diagnostics.
- Paired Pulse:Dual-stimulation paradigms for cortical excitability assessment in research protocols.
Repetitive TMS retains the dominant installed base; theta burst protocols are climbing the fastest as purchasers prioritize session efficiency.
Application:
Customer type concentration shapes procurement authority, with hospital treatment networks consolidating requisition decisions differently from dispersed research grant funding.
- Hospital Treatment:Inpatient and outpatient neuromodulation services within integrated delivery networks. Academic medical centers in Boston and Heidelberg specify deep TMS configurations for treatment-resistant depression protocols, with EU MDR post-market surveillance requirements mandating connected device telemetry.
- Clinical Therapy:Dedicated psychiatric and neurology clinics operating outside hospital systems. Mid-tier outpatient networks in California and Texas are shifting from capital purchase toward session-based leasing models as patient volume forecasting remains volatile.
- Research:Investigator-initiated trials and pharmaceutical combination studies requiring protocol flexibility.
- Home Use:Portable systems for prescriber-supervised domestic administration, contingent on FDA breakthrough device designation pathways.
Hospital treatment commands the largest procurement volumes; home use represents the steepest expansion trajectory pending regulatory pathway clarification.
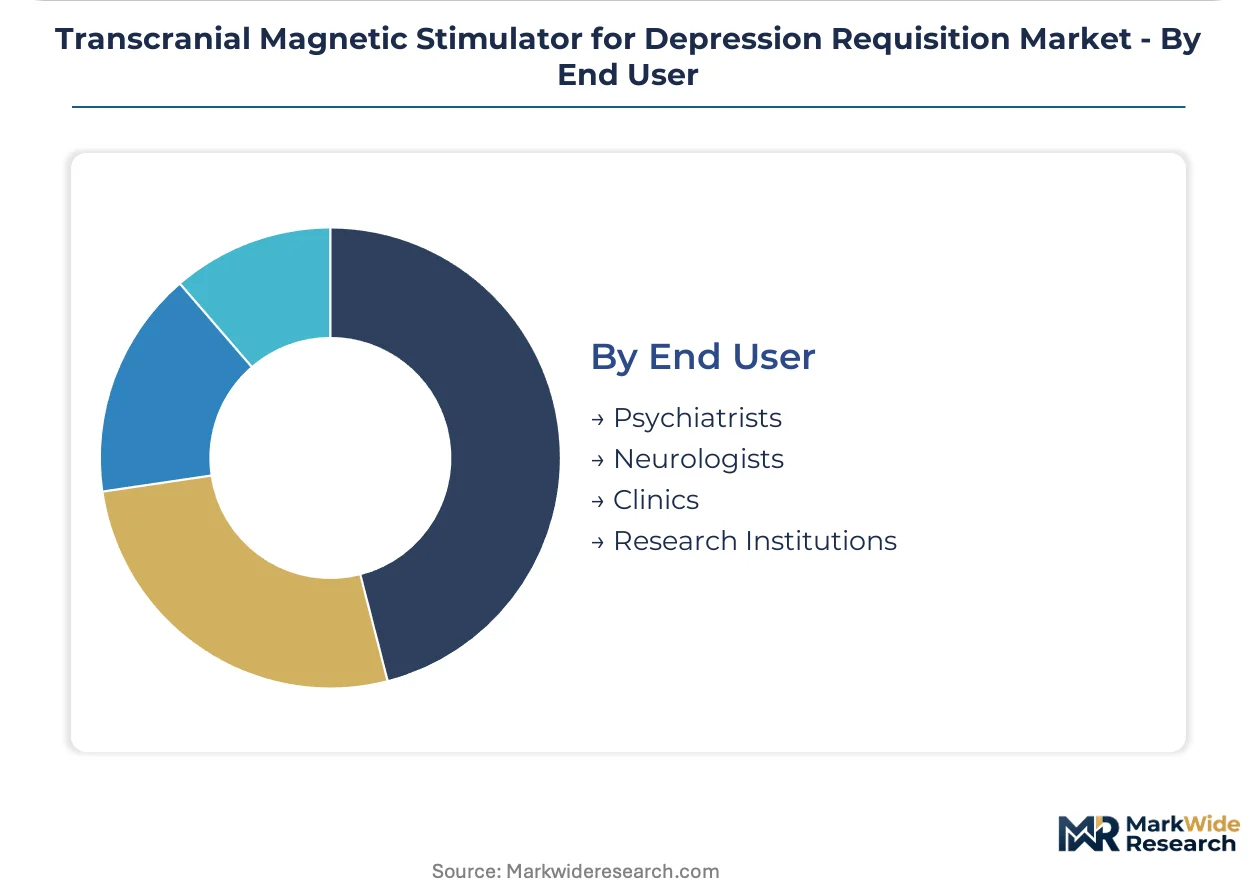
End User:
Margin concentration varies by prescriber specialty, with psychiatrists driving repetitive TMS adoption and neurologists prioritizing navigation-enabled precision.
- Psychiatrists:Primary prescribers for major depressive disorder protocols in community mental health centers. Skilled technician scarcity is constraining installation growth, with certified operator training programs failing to match hardware deployment rates in Texas and California networks.
- Clinics:Dedicated psychiatric and multidisciplinary neuromodulation facilities. German university hospitals are centralizing procurement through consortium frameworks that standardize telemetry specifications for EU MDR compliance.
- Neurologists:Movement disorder and epilepsy specialists employing TMS for diagnostic and therapeutic crossover applications.
- Research Institutions:Academic centers and contract research organizations requiring protocol customization and data export capabilities.
Psychiatrists anchor the largest prescriber segment; clinics are gaining share fastest as session-based leasing models fragment procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS coverage decisions and METI-coordinated reimbursement frameworks are unlocking hospital procurement budgets across mature psychiatric care markets. Device manufacturers prioritize FDA 510(k) clearance and PMDA registration to secure institutional contracts. Metropolitan clusters in Boston, Heidelberg, and Tokyo concentrate installation growth.
United States
Academic medical centers in Boston specify deep TMS configurations for treatment-resistant depression protocols. FDA 510(k) clearance pathways sustain competitive entry for novel coil designs. California and Texas outpatient networks are shifting toward session-based leasing models as third-party equipment financiers underwrite hardware deployments.
Germany
University hospitals in Heidelberg prioritize H-coil geometries for obsessive-compulsive disorder comorbidity programs. EU MDR post-market surveillance requirements mandate connected device telemetry for CE marking validity. German psychiatric clinics are centralizing procurement through consortium frameworks that standardize data transmission specifications.
Japan
METI-coordinated coverage decisions for repetitive TMS are unlocking hospital budgets in Tokyo and Osaka metropolitan clusters. PMDA reimbursement expansion targets dorsolateral prefrontal cortex protocols at 1-10 Hz frequencies. Japanese medical device distributors are prioritizing figure-eight coil geometries for institutional tenders.
United Kingdom
Emerging NICE guidance is creating procurement uncertainty across hospital networks as psychiatric clinics renegotiate capital allocation frameworks. The divergence from established CMS coverage patterns complicates volume forecasting for equipment financiers. London-based academic centers are piloting theta burst protocols to optimize session throughput.
India
The country's national pharmaceutical regulator is prioritizing neuromodulation devices under its medical device rules amendment for fast-track market entry. CDSCO regulatory clarity is attracting distributor investment in Mumbai and Bangalore psychiatric care networks. Indian hospital procurement officers are evaluating magnetic coil assemblies against domestic assembly cost benchmarks.
Transcranial Magnetic Stimulator for Depression Requisition Market Competitive Landscape
Player mix skews toward FDA-cleared platform specialists and deep TMS geometry innovators. The installed base concentrates around manufacturers with established institutional loyalty across academic medical centers. Two strategic archetypes dominate: navigation-enabled premium system providers and session-efficiency protocol specialists. Competitive moves center on ISO 13485 certification acceleration and theta burst algorithm standardization for throughput optimization.
Within the FDA-cleared platform tier, Neuronetics and BrainsWay exemplify divergent positioning strategies. Neuronetics anchors institutional loyalty through established academic medical center relationships. BrainsWay occupies a distinct niche through deep TMS coil geometry specialization. Magstim represents the European fabrication archetype with CE marking validity under EU MDR post-market surveillance frameworks. These three manufacturers collectively illustrate how regulatory pathway mastery and coil configuration differentiation determine procurement contract capture.
| Leading Market Players |
|---|
| Neuronetics |
| BrainsWay |
| Magstim |
| Nexstim |
| MagVenture |
| Soterix Medical |
| neurocare group |
| Seber Medical |
| eNeura |
| Others |
Pricing and Supply Chain Analysis
Session-based leasing contracts lock in supply access for psychiatric clinics while fixing per-treatment costs against volatile copper and rare-earth magnet pricing. These arrangements concentrate in California and Texas outpatient networks where third-party equipment financiers underwrite hardware deployments against utilization minimums, compressing price visibility for buyers and suppliers alike.
Pricing Analysis
Certification level creates the primary spread across requisition tiers, with FDA 510(k)-cleared and EU MDR-compliant systems commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium navigation-enabled, standard repetitive TMS, and economy figure-eight coil platforms reflects software integration depth and coil geometry sophistication. Cost compression in mid-tier installations is intensifying because copper and rare-earth magnet inputs face price swings from concentrated Chinese mining operations. Academic medical centers in Boston and Heidelberg show least price sensitivity, prioritizing deep TMS H-coil configurations for treatment-resistant depression protocols, while community mental health centers in Texas and California networks exhibit highest sensitivity and drive session-based leasing adoption.
Supply Chain Analysis
Inventory lead times for magnetic coil assemblies extend 18-24 months under EU MDR technical documentation burdens, forcing German and Japanese manufacturers to pre-position rare-earth magnet stockpiles. Manufacturing concentration centers on Germany for H-coil deep TMS geometries, Japan for figure-eight configurations, and the United States for integrated system controllers with software-embedded navigation. Copper-wound assemblies and neodymium magnet cores constitute critical input dependencies, with supply chain risk anchored in single-source vulnerability for rare-earth elements processed through Chinese mining operations. Distribution runs through hospital procurement consortiums in Germany, GPO contracts in the United States, and medical device distributors in Japan targeting Tokyo and Osaka metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent TMS manufacturers face substitution defense imperatives as intravenous esketamine clinics capture refractory depression patients who would otherwise qualify for magnetic stimulation protocols. Ketamine infusion substitution represents the most immediate threat to requisition volume growth.
For Market Incumbents: Compound institutional loyalty through theta burst protocol standardization and accelerated dosing algorithm integration, locking academic medical centers into premium navigation-enabled ecosystems. Deepen backward integration into copper coil fabrication to defend margin position against rare-earth magnet cost volatility from Chinese supply concentration. Prioritize ISO 13485 certification acceleration to maintain hospital procurement contract eligibility as auditor capacity constraints delay emerging competitor approvals.
For New Entrants and Emerging Players: India's CDSCO fast-track mechanism under medical device rules amendment offers the most penetrable regulatory pathway for neuromodulation market entry. Target Mumbai and Bangalore psychiatric care networks where distributor investment is accelerating and domestic assembly cost benchmarks favor competitive positioning. Pursue home-use regulatory pathway emergence through FDA breakthrough device designation for portable TMS systems, fragmenting requisition authority toward direct prescriber-patient channels.
For Investors and Strategic Acquirers: Navigation-enabled precision hardware specialists with established academic medical center relationships represent the highest-value acquisition archetype for portfolio consolidation. Long-term viability over the next decade hinges on whether emerging home-use regulatory pathways fragment procurement authority or reinforce hospital system consolidation. Monitor FDA breakthrough device designation decisions for portable TMS systems as the critical inflection indicator for channel structure transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Theta Burst Protocol Standardization | Accelerated dosing algorithms reduce session counts from 36 to 20 while maintaining CMS reimbursement eligibility. |
| Deep TMS H-Coil CE Marking Pathway | EU MDR post-market surveillance requirements mandate connected device telemetry for Heidelberg and Boston academic centers. |
| Hospital System Partnership | Consortium frameworks in Germany standardize data transmission specifications for psychiatric clinic network procurement. |
| Software Companion Development | Real-time neuroimaging feedback integration differentiates premium tenders from legacy figure-eight coil platforms. |
| Reimbursement Strategy | METI-coordinated PMDA coverage decisions unlock Tokyo and Osaka metropolitan cluster procurement budgets. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract records preceded structured interviews with psychiatric clinic directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary fieldwork with device manufacturers and third-party equipment financiers in California, Texas, and Germany was cross-validated against secondary sources including CMS Medicare reimbursement data, PMDA registration filings, and METI coverage decision records. Bottom-up installation volume estimates across coil geometry categories were triangulated with top-down market value reconstruction from manufacturer revenue disclosures.
Variance decomposition across technology segments, application settings, and end-user specialties informed the analytical framework over the projection horizon. Segmentation dimensions modeled include magnetic coil configuration, treatment protocol methodology, delivery setting, and prescriber specialty, with regional regulatory clusters capturing FDA, EU MDR, PMDA, and CDSCO pathway differences. CAGRs were derived from installation growth trajectories weighted by average system pricing and session throughput assumptions, with theta burst protocol adoption curves and home-use regulatory pathway emergence serving as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside FDA breakthrough device designation for portable systems or sustained CMS coverage stability would require recalibration. Forecasts reflect documented assumptions regarding reimbursement pathway fragmentation, rare-earth magnet supply concentration, and skilled technician training program expansion. Specific risk factors that could revise projections include ketamine infusion substitution acceleration, EU MDR auditor capacity constraints extending certification timelines, and copper price volatility from Chinese mining operations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Neuro Medical Devices Market
Medical Devices
Medical Electrodes Market
Medical Devices
Vibrating Mesh Nebulizer Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market