
 Flow Diverters Market | 2026-2036
Flow Diverters Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Diverters Market Intelligence
European nitinol weaving capacity is broadening as regional producers scale precision braiding operations for neurovascular stent manufacturing. Johnson & Johnson leverages its Cerenovus franchise to sustain leadership in cerebral aneurysm intervention across North American and European hospital networks. Medtronic anchors its position through integrated delivery systems that combine flow diverter deployment with proprietary microcatheter technology. Phenox GmbH competes from its German manufacturing base, specializing in custom device geometries for complex vascular anatomies.
Flow diverters are self-expanding, braided nitinol mesh implants designed to redirect blood flow away from aneurysm sacs while promoting endothelialization across the device surface, typically achieving pore densities below 30 microns to effect hemodynamic isolation. The primary commercial purpose centers on treating large or giant wide-neck cerebral aneurysms that prove unsuitable for traditional coiling techniques. Self-expanding configurations dominate procedural volumes due to their conformability to tortuous intracranial vessels, while robotic-assisted delivery modes represent the fastest-growing insertion category as hospitals invest in precision navigation platforms. Endovascular deployment through femoral access remains the mature standard, though catheter-based systems continue capturing margin pools through disposable kit bundling.
FDA premarket approval requirements and EU MDR technical documentation obligations shape product development timelines and clinical evidence thresholds for manufacturers seeking market access. Japan's PMDA enforces stringent biocompatibility testing protocols that extend registration cycles for foreign device makers. China's NMPA implements national volume-based procurement schemes that compress pricing for approved flow diverter brands. Stakeholders must monitor evolving reimbursement coding for robotic-assisted neurointervention procedures across Medicare, NHS England, and Germany's G-DRG system to anticipate capital allocation shifts.
Market Dynamics
Flow diversion technology is consolidating around braided nitinol mesh architectures as neurovascular centers prioritize hemodynamic isolation over traditional coiling for complex cerebral aneurysms, reshaping capital allocation and procedural training pathways across hospital networks.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways compress time-to-market for novel flow diverter geometries, accelerating commercial availability in US neurovascular centers.
- Complex Aneurysm Prevalence:Large and giant wide-neck cerebral aneurysms unsuitable for coiling drive procedural volume toward endovascular flow diversion as first-line therapy.
- German Neuroradiology Clusters:Specialized centers in Berlin and Munich generate concentrated demand for custom device configurations tailored to tortuous intracranial anatomies.
Market Restraints
- Nitinol Supply Concentration:Precision braiding capacity for neurovascular-grade nitinol mesh concentrates among European producers, creating input bottlenecks during demand surges.
- EU MDR Technical Documentation:Expanded clinical evidence requirements for CE marking extend product development timelines and elevate regulatory compliance costs.
- Antiplatelet Dependency:Mandatory dual antiplatelet therapy following flow diverter implantation limits patient eligibility and complicates emergency intervention protocols.
Strategic Opportunities
- Robotic-Assisted Delivery Platforms:Precision navigation systems for flow diverter deployment represent the fastest-growing insertion category as hospitals invest in capital equipment upgrades.
- Japan PMDA Registration:Stringent biocompatibility testing protocols create first-mover advantages for manufacturers that complete extended registration cycles ahead of competitors.
- China NMPA Volume Procurement:National tender schemes compress pricing but open volume commitments for approved brands willing to absorb margin compression.
Industry Challenges
- Microcatheter Integration Complexity:Flow diverter deployment requires proprietary delivery system compatibility, forcing hospitals to standardize across vendor ecosystems or maintain redundant inventory.
- Endothelialization Timeline Variability:Incomplete aneurysm occlusion during the healing window necessitates extended imaging follow-up and exposes providers to retreatment liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Diverters Market |
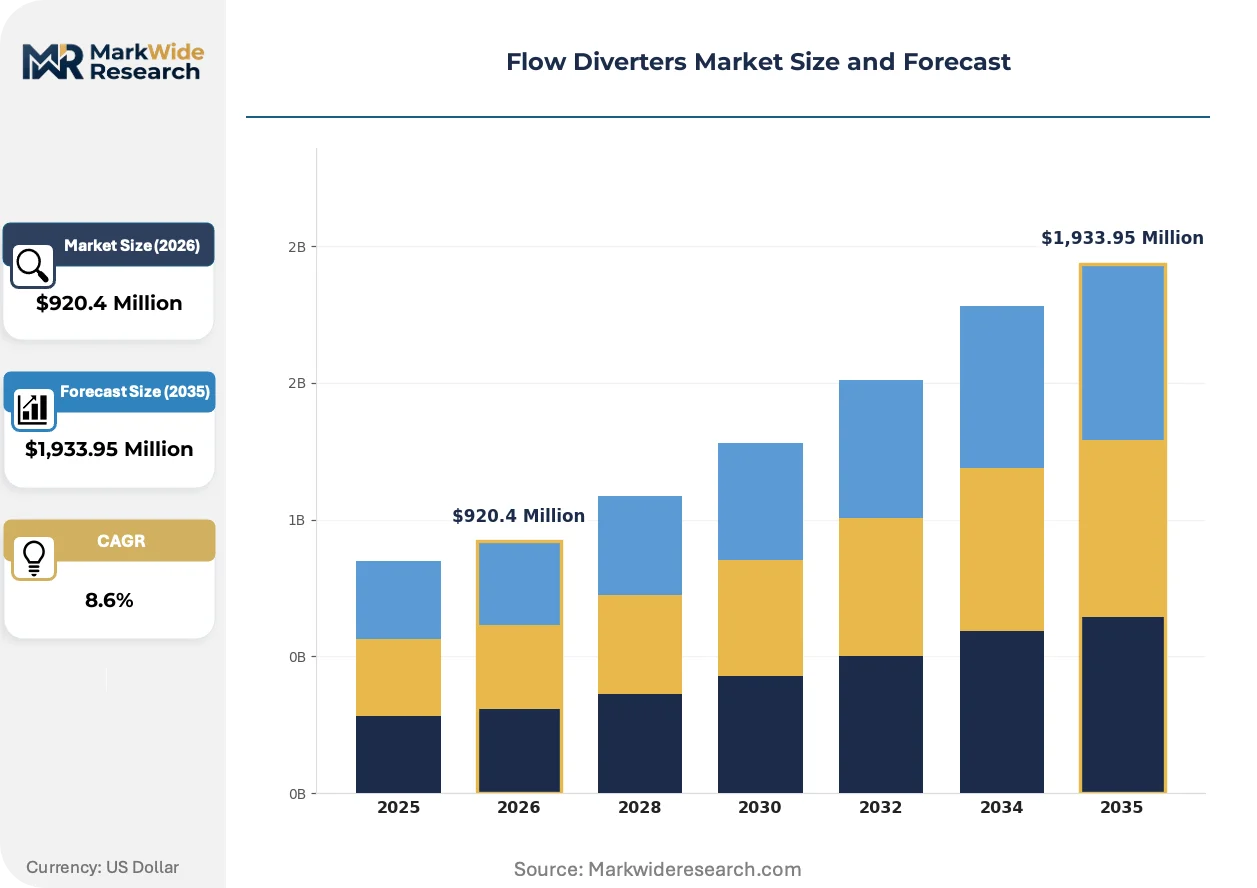
| Market Size in 2026 | $920.4 Million |
| Market Size in 2035 | $1,933.95 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-expanding, Balloon-expandable, Stent-like, Composite Delivery Mode: Intravenous, Endovascular, Catheter-based, Robotic-assisted End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Academic Medical Centers Application: Cerebral Aneurysm, Arteriovenous Malformations, Peripheral Vascular Disease, Others |
| Companies Covered | Johnson & Johnson, Abbott Laboratories, Medtronic, MicroPort Scientific Corporation, Penumbra, Stryker Corporation, Boston Scientific, Phenox GmbH, MicroVention (Terumo Corporation), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Diverters Market Strategic Shifts & Innovations
Braided mesh architectures are displacing laser-cut stent platforms as the dominant hemodynamic isolation technology, while regulatory pathways and procurement models undergo parallel transformation across major neurovascular markets.
Surface-modified nitinol braiding is consolidating competitive positioning around endothelialization kinetics. Manufacturers apply proprietary coating chemistries to accelerate neointimal coverage and reduce thromboembolic complications during the healing phase. Academic medical centers in the United States and Germany are prioritizing these enhanced-surface devices in protocol-driven evaluations, compressing demand for first-generation uncoated platforms.
EU MDR implementation is reshaping technical documentation obligations for flow diverter manufacturers. The regulation mandates expanded clinical follow-up data and post-market surveillance systems that elevate evidence thresholds beyond prior CE marking requirements. German and French notified bodies are applying these standards most stringently, forcing sponsors to extend trial enrollment periods or redirect initial launches toward US FDA pathways.
Hospital procurement committees are unbundling flow diverter kits from bundled payment structures. Neurovascular centers increasingly negotiate device costs separately from microcatheter and access sheath components, reversing prior disposable kit arrangements. This pattern is most visible in NHS England contracting and German G-DRG reimbursement frameworks, where separate coding for robotic-assisted delivery creates distinct budget line items.
Flow Diverters Market Segmentation
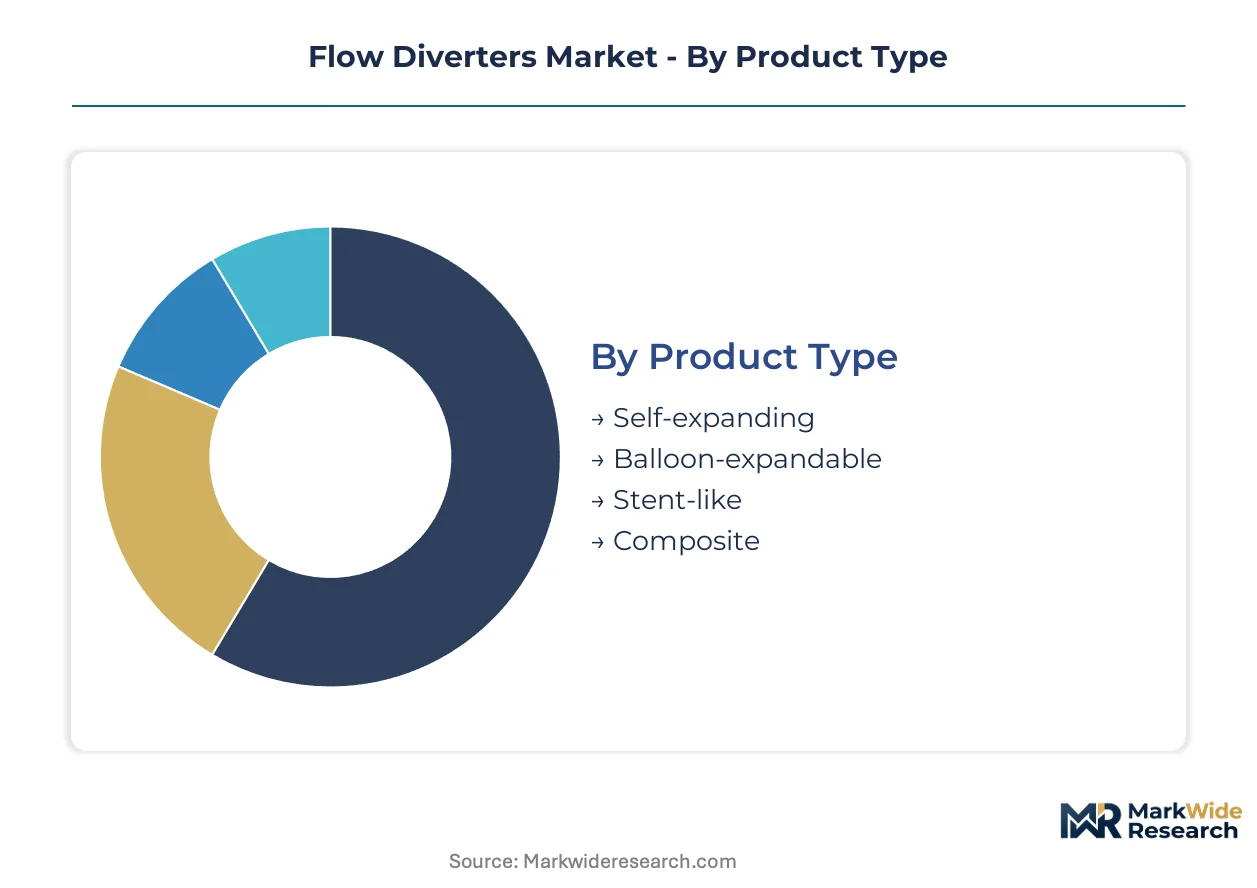
Flow diverter segmentation reveals how procedural complexity and reimbursement pathways shape purchasing decisions across hospital networks. Device configurations and delivery modalities determine capital allocation, training requirements, and inventory management strategies for neurovascular programs.
Product Type:
Replacement cycles for earlier-generation devices are accelerating as surface-modified platforms demonstrate superior endothelialization kinetics in clinical evaluations.
- Self-expanding:Braided nitinol mesh architectures achieve conformability to tortuous intracranial vessels through radial force distribution. Demand clusters in German neuroradiology centers in Berlin and Munich where specialized operators prioritize conformability for complex anatomies. Dual antiplatelet therapy requirements constrain patient eligibility but procedural volume continues climbing.
- Balloon-expandable:These platforms deliver precise diameter control through inflation-mediated deployment. Adoption concentrates in academic medical centers pursuing protocol-driven comparisons against braided alternatives. The mechanical expansion mechanism suits focal vessel segments with less tortuosity.
- Stent-like:Laser-cut tubular designs offer alternative hemodynamic isolation through strut-based flow disruption rather than dense mesh porosity.
- Composite:Hybrid constructions combine braided and laser-cut elements for customized mechanical properties.
Volume placements concentrate in Self-expanding configurations; the faster expansion belongs to Composite designs as manufacturers tailor hybrid geometries.
Delivery Mode:
Capital equipment refresh cycles at major neurovascular centers are rebalancing procurement toward integrated navigation platforms.
- Endovascular:Femoral access deployment remains the procedural standard across United States hospital networks. This mature technique leverages established microcatheter infrastructure and standardized operator training pathways. Reimbursement stability through Medicare DRG coding sustains volume.
- Robotic-assisted:Precision navigation systems enable submillimeter positioning control during deployment. Investment is accelerating at academic medical centers in Germany and the United States seeking differentiation in complex case referrals. FDA breakthrough device designations for integrated platforms compress regulatory timelines.
- Intravenous:Systemic delivery approaches remain experimental for flow diversion applications.
- Catheter-based:Conventional over-the-wire systems maintain installed base across community hospital settings.
Procedure economics favor Endovascular deployment at scale; steepest expansion trajectory is climbing the fastest in Robotic-assisted systems as capital budgets reallocate.
End User:
Reimbursement tier differentiation is concentrating purchasing authority among high-volume procedural centers.
- Hospitals:Tertiary care facilities generate dominant procedural volume through comprehensive neurovascular service lines. These institutions negotiate directly with manufacturers for device kit bundling and maintain redundant inventory across vendor ecosystems. Germany's G-DRG framework and NHS England contracting patterns shape procurement negotiations.
- Academic Medical Centers:Research-intensive institutions drive protocol-driven adoption of surface-modified and robotic-assisted platforms. NIH-funded investigators in the United States and German university hospitals prioritize devices with extended clinical evidence packages. EU MDR technical documentation requirements elevate evidence thresholds for initial launches.
- Ambulatory Surgical Centers:Outpatient settings capture select cases with straightforward anatomical presentations.
- Specialty Clinics:Focused neuroradiology practices concentrate elective procedures outside hospital cost structures.
Device placements concentrate in Hospital systems; Academic Medical Centers are gaining share fastest through research-driven procurement influence.
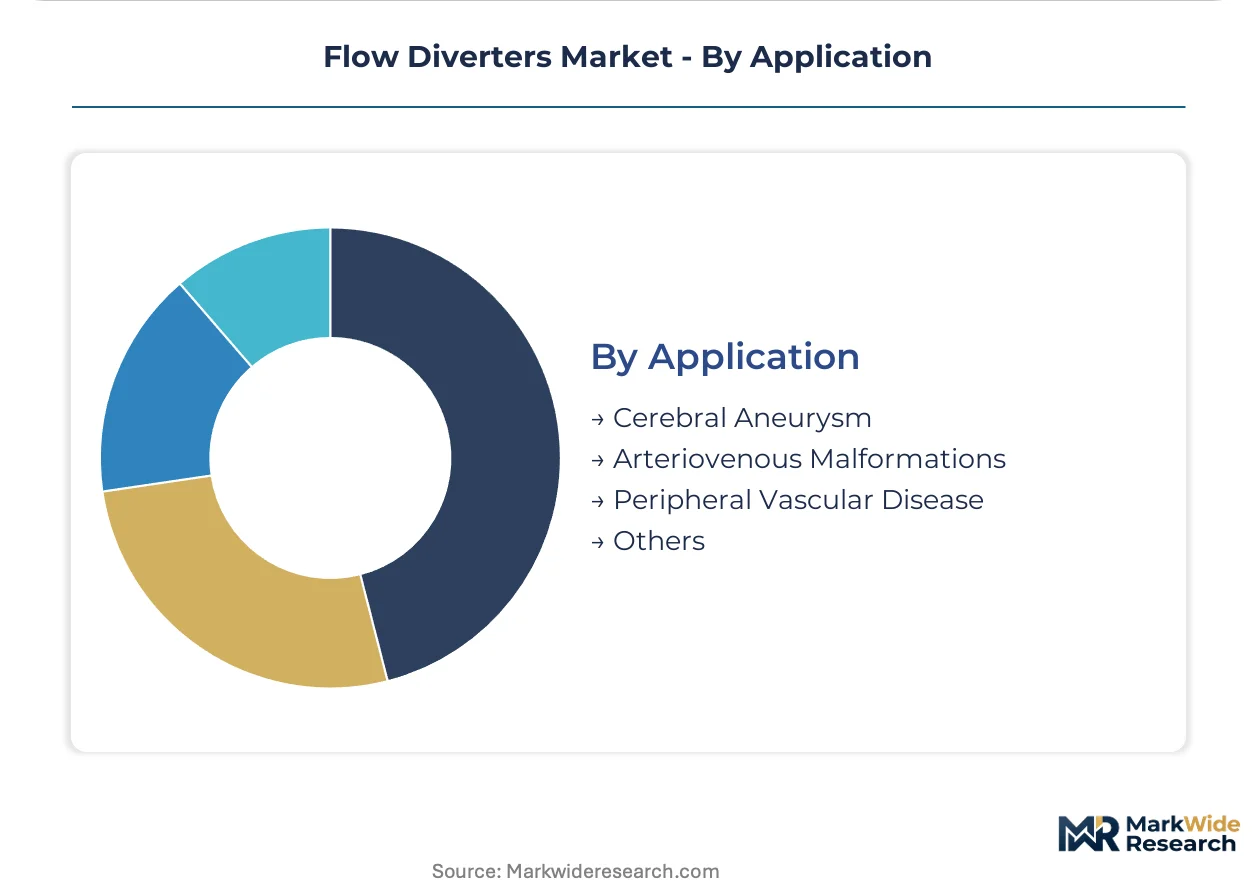
Application:
Clinical evidence accumulation is reshaping first-line therapy designations across aneurysm morphologies.
- Cerebral Aneurysm:Large and giant wide-neck aneurysms unsuitable for traditional coiling represent the core commercial indication. Flow diversion achieves hemodynamic isolation through pore densities below 30 microns while promoting endothelialization. United States neurovascular centers and German clusters generate concentrated procedural demand.
- Arteriovenous Malformations:Off-label utilization is expanding as operators adapt flow diversion principles to high-flow nidus anatomy. Academic investigators in Germany and the United States are generating case series for regulatory submission. Japan's PMDA maintains stringent oversight of expanded indications.
- Peripheral Vascular Disease:Cross-application of cerebral device platforms to peripheral anatomy remains limited.
- Others:Investigational applications include traumatic vascular injury and iatrogenic pseudoaneurysm.
Procedural volume concentrates in Cerebral Aneurysm treatment; Arteriovenous Malformations are expanding most quickly through off-label protocol development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nitinol wire drawing and precision braiding operations concentrate in European manufacturing corridors, with specialized neuroradiology clusters in Germany and the United States anchoring procedural demand for complex cerebral aneurysm interventions.
United States
FDA breakthrough device designations accelerate commercial timelines for novel flow diverter geometries. Medicare DRG coding sustains reimbursement stability for endovascular neurointervention procedures. Academic medical centers in Boston and Baltimore drive protocol-driven adoption of surface-modified platforms.
Germany
Specialized neuroradiology clusters in Berlin and Munich generate concentrated demand for custom device configurations tailored to tortuous intracranial anatomies. EU MDR technical documentation requirements elevate clinical evidence thresholds beyond prior CE marking standards. Notified bodies in Munich and Stuttgart apply these standards most stringently.
China
NMPA national volume-based procurement schemes compress pricing for approved flow diverter brands while opening volume commitments. Domestic nitinol processing capacity is scaling in Jiangsu and Zhejiang provinces. Shanghai-based neurovascular centers are expanding procedural volumes for complex aneurysm cases.
Japan
PMDA enforces stringent biocompatibility testing protocols that extend registration cycles for foreign device makers. First-mover advantages accrue to manufacturers completing extended approval timelines. Tokyo and Osaka academic hospitals prioritize devices with comprehensive clinical evidence packages.
United Kingdom
NHS England contracting patterns unbundle flow diverter kits from bundled payment structures, reversing prior disposable kit arrangements. Separate coding for robotic-assisted delivery creates distinct budget line items. London neurovascular centers negotiate device costs independently from microcatheter components.
Flow Diverters Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue robotic-assisted delivery integration and surface modification technologies. The vendor base stratifies across diversified medtech conglomerates with neurovascular franchises, specialized European manufacturers with custom geometry capabilities, and Asia-Pacific fabricators scaling nitinol processing capacity. Three archetypes dominate: integrated delivery system specialists, precision braiding contract manufacturers, and academic spin-outs commercializing protocol-driven innovations. Competitive moves center on M&A to secure microcatheter compatibility and capacity expansion in European nitinol weaving corridors.
Within the diversified medtech tier, Johnson & Johnson and Medtronic exemplify integrated delivery system strategies, while Phenox GmbH represents the specialized European manufacturer archetype with German-based operations. These three anchors illustrate how competitive positioning flows through proprietary microcatheter ecosystems, regional manufacturing concentration, and custom geometry capabilities for complex vascular anatomies.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Abbott Laboratories |
| Medtronic |
| MicroPort Scientific Corporation |
| Penumbra |
| Stryker Corporation |
| Boston Scientific |
| Phenox GmbH |
| MicroVention (Terumo Corporation) |
| Others |
Cost & Logistics Intelligence
Surface-modified nitinol braiding is compressing cost economics for first-generation uncoated platforms while simultaneously concentrating supply leverage among European precision weaving specialists with proprietary coating chemistries. This technological transition rewards manufacturers with captive nitinol processing capabilities and exposes dependent buyers to input bottlenecks during demand surges.
Pricing Analysis
Warranty and post-market surveillance bundling is separating premium-tier flow diverters from standard configurations as EU MDR technical documentation obligations elevate compliance costs. Three-tier pricing structure across surface-modified premium, standard braided, and economy laser-cut platforms reflects endothelialization performance differentiation. Cost compression in standard braided tiers is intensifying because China's NMPA volume-based procurement schemes force margin absorption for volume commitments. Academic medical centers exhibit lowest price sensitivity due to research funding insulation, while community hospitals face acute budget constraints under DRG reimbursement ceilings.
Supply Chain Analysis
Dual-sourcing mandates from FDA and EU notified bodies require manufacturers to qualify multiple nitinol wire suppliers and braiding subcontractors, extending qualification timelines. Geographic supply concentration centers on Germany, Switzerland, and the United States for neurovascular-grade nitinol wire drawing and precision braiding operations. Raw material dependencies encompass nickel-titanium alloy feedstock, platinum-iridium radiopaque markers, and proprietary polymer coating precursors. Single-source vulnerability concentrates in European precision braiding capacity for sub-30-micron pore density mesh. Distribution runs through direct manufacturer contracts with hospital purchasing committees and GPO-negotiated frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated delivery system specialists as EU MDR compliance costs and robotic-assisted platform R&D investments force subscale manufacturers toward exit or acquisition.
For Market Incumbents: Cement proprietary microcatheter ecosystem control through backward integration into nitinol braiding capacity or exclusive supply agreements with German and Swiss weaving specialists. Acquire robotic-assisted navigation platform capabilities to defend against precision deployment specialists entering from adjacent interventional cardiology markets. Prioritize FDA breakthrough device designation pathways for surface-modified geometries to compress regulatory timelines relative to CE marking under EU MDR. For New Entrants and Emerging Players: Enter via Japan PMDA registration completion to capture first-mover advantages before competitors navigate extended biocompatibility testing cycles. Target China's NMPA volume procurement tenders for approved brands willing to absorb initial margin compression for committed hospital volumes. Pursue academic medical center protocol-driven evaluations in Germany and the United States to generate clinical evidence packages that satisfy EU MDR technical documentation requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medtech conglomerates seeking neurovascular franchise expansion or robotic-assisted platform integration. Long-term viability favors manufacturers with captive nitinol processing, proprietary coating chemistries, and established FDA/CE dual-market presence. Monitor EU MDR notified body backlog resolution as inflection indicator for CE marking timeline normalization and competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation completion unlocks German and French hospital procurement access. |
| Hospital System Partnership | Berlin and Munich neuroradiology clusters generate protocol-driven adoption and training influence. |
| Backward Integration | Captive nitinol braiding capacity insulates against European supply concentration and input cost volatility. |
| Software Companion Development | Robotic-assisted delivery platform integration enables submillimeter deployment precision and capital equipment bundling. |
| Reimbursement Strategy | Medicare DRG coding optimization and NHS England unbundling negotiations secure procedure economics stability. |
Research Approach
Independent corroboration across neuroradiology department heads, hospital purchasing committee directors, and regulatory affairs specialists at flow diverter manufacturers underwrites the qualitative findings. Primary interviews with GPO contracts managers and biomedical engineers at academic medical centers in the United States and Germany combined with secondary validation from FDA 510(k) and PMA filings, EUDAMED CE marking databases, and hospital procurement contract disclosures. Bottom-up procedural volume estimates triangulate against top-down manufacturer revenue segmentation across self-expanding, balloon-expandable, and robotic-assisted delivery modalities.
Rate-of-change decomposition across the projection horizon segments expansion by product type, delivery mode, end user tier, and geographic regulatory cluster. CAGRs derive from modeled adoption curves for surface-modified platforms, robotic-assisted deployment penetration, and NMPA procurement volume commitments. Industry-specific forecast inputs incorporate EU MDR notified body capacity constraints, PMDA biocompatibility testing cycle durations, and German G-DRG reimbursement coding evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged EU MDR approval delays or sudden nitinol supply disruptions. Deviation in China NMPA procurement tender participation rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Syringeless Injector Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Middle Ear Implants Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
France Respiratory Devices Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market