
 Aesthetic Medicine Market | 2026-2036
Aesthetic Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Aesthetic Medicine Market Analysis
The aesthetic medicine sector is consolidating around a sharp split between premium physician-directed injectables and commoditized over-the-counter topicals. AbbVie leverages its Allergan heritage to dominate high-margin neurotoxin and filler portfolios through direct clinic relationships. Galderma anchors its position with biostimulatory fillers and integrated skincare systems that sustain recurring revenue per patient.
Aesthetic medicine encompasses minimally invasive and non-invasive procedures using pharmacologic agents, energy-based devices, and topical formulations to alter cosmetic appearance, typically involving hyaluronic acid concentrations of 20-24 mg/mL in cross-linked dermal fillers or fractional laser wavelengths of 1550 nm for collagen remodeling. Injectables command the deepest margin pools due to repeat treatment cycles and practitioner certification barriers, while laser devices compete on capital equipment financing and service contract attach rates. Medical spas and specialized clinics represent the fastest-growing end-user channel as they combine convenience with supervised care.
FDA device clearances under 510(k) and de novo pathways shape product launch timelines and clinical trial investment for US market entrants, while the EU MDR and CE marking requirements impose post-market surveillance obligations that filter smaller device manufacturers. South Korea's MFDS maintains accelerated approval tracks for novel energy devices that often predate Western regulatory decisions. Stakeholders must weigh regulatory jurisdiction sequencing against reimbursement and liability exposure when prioritizing geographic expansion.
Market Dynamics
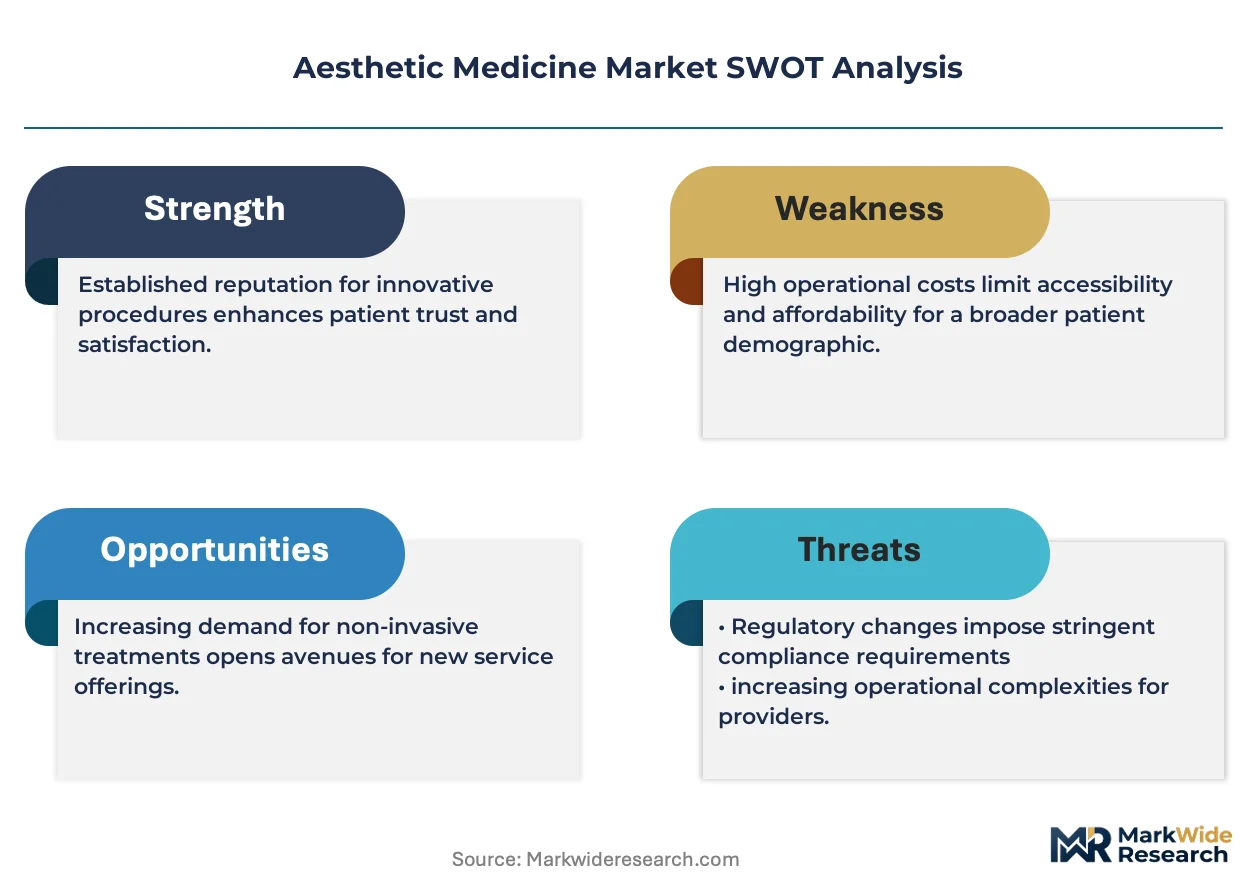
Injectable neurotoxins and hyaluronic acid fillers are consolidating purchasing power around physician-directed clinic networks, compressing margins for standalone device manufacturers while elevating recurring revenue models for integrated portfolios.
Growth Catalysts
- MFDS Accelerated Approval Tracks:South Korea's streamlined pathways for novel energy-based devices compress time-to-market for fractional laser and radiofrequency technologies, drawing pre-market validation investment ahead of Western jurisdictions.
- Medical Spa Channel Expansion:Supervised clinic settings in the United States are broadening service menus to include combination therapies, lifting per-patient spend through bundled injectable and device protocols.
- Biostimulatory Filler Demand:Poly-L-lactic acid and calcium hydroxylapatite formulations are extending treatment intervals, creating loyalty lock-in through collagen induction protocols that require practitioner certification.
Market Restraints
- FDA Clinical Evidence Escalation:510(k) and de novo pathways for energy-based devices now demand larger patient cohorts and longer follow-up periods, stretching R&D timelines and capital requirements for market entrants.
- Cross-Linked HA Feedstock Concentration:Pharmaceutical-grade hyaluronic acid production clusters in Chinese and Japanese fermentation facilities, exposing formulators to input cost volatility and supply security risks.
- Non-Invasive Topical Substitution:High-concentration retinoid and peptide formulations from dermatology skincare lines are capturing preventive maintenance occasions that previously flowed to clinic-based procedures.
Strategic Opportunities
- Middle East Clinic Infrastructure:Dubai and Riyadh are licensing medical spa operations under MOHAP and SFDA frameworks, creating first-mover positioning for training academy and device leasing models.
- EU MDR Post-Market Surveillance Gaps:Smaller device manufacturers are exiting CE-marked portfolios under tightened vigilance obligations, opening acquisition targets for compliant mid-scale players with notified body relationships.
- AI-Assisted Treatment Planning:Machine learning algorithms for facial mapping and injection depth prediction are converging with ultrasound guidance systems, enabling technician-delegated procedures under remote physician supervision.
Industry Challenges
- Injector Certification Bottlenecks:Physician, nurse, and physician assistant training programs for neurotoxin administration carry 6-12 month completion timelines, constraining clinic capacity expansion in high-demand metropolitan markets.
- Capital Equipment Financing Strain:Fractional laser and intense pulsed light platforms require 36-48 month lease structures with service contract attach rates above 15% annually, compressing cash flow for independent practice operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aesthetic Medicine Market |
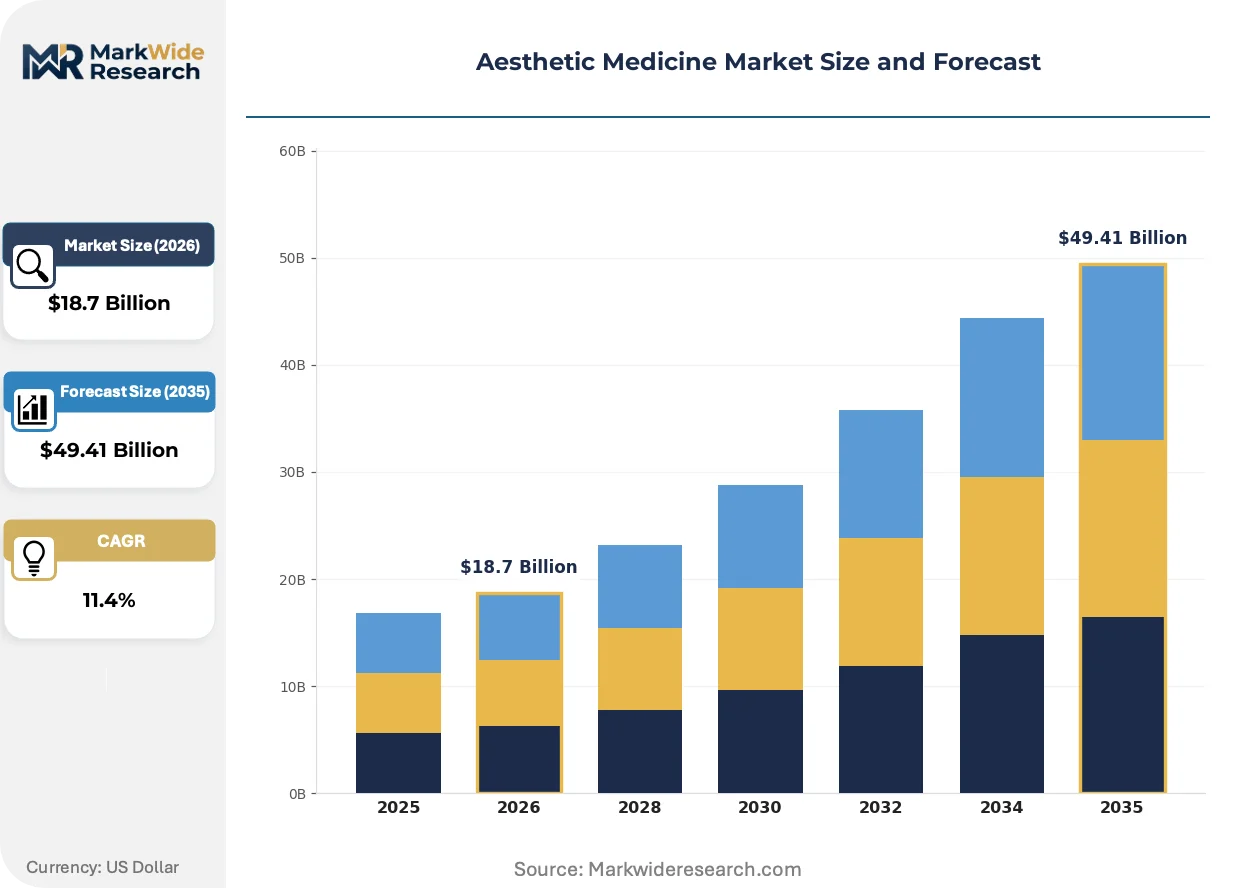
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Devices, Dermal Fillers, Skin Care Products End User: Clinics, Hospitals, Beauty Salons, Medical Spas Procedure Type: Wrinkle Reduction, Hair Restoration, Body Contouring, Skin Resurfacing Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Third-Party Retailers |
| Companies Covered | AbbVie, Galderma, Johnson & Johnson, Merz Pharma, Bausch Health, Cutera, Cynosure, Alma Lasers, Revance Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aesthetic Medicine Market Emerging Trajectories
Energy-device manufacturers are pivoting toward combination platforms that integrate multiple wavelengths and delivery modalities, reducing clinic capital footprints while enabling protocol customization.
Microfocused ultrasound with visualization is absorbing market share from traditional radiofrequency tightening procedures by delivering precise thermal coagulation points at specified depths. High-volume medical spa chains in South Korea and the United States are adopting these systems at replacement cycle intervals of 24-30 months. The technology is absorbing margin pressure from standalone device categories by bundling consumable cartridges with platform leases.
The EU MDR's post-market clinical follow-up requirements are forcing device manufacturers to maintain active implant registries and periodic safety update reports across their CE-marked portfolios. This regulatory burden is filtering smaller competitors from the European market while concentrating notified body relationships among established multinationals. Fractional laser and body contouring device categories are responding with extended warranty offerings and clinical training commitments to secure distributor loyalty.
Subscription-based membership programs are displacing per-procedure pricing in United States medical spa channels, locking patients into quarterly treatment cycles with prepaid credits. Younger demographic cohorts in urban California and Texas markets are gravitating toward these models for neurotoxin and filler maintenance. The shift is compressing seasonal demand fluctuations while elevating patient lifetime value calculations in clinic valuation metrics.
Aesthetic Medicine Market Segmentation
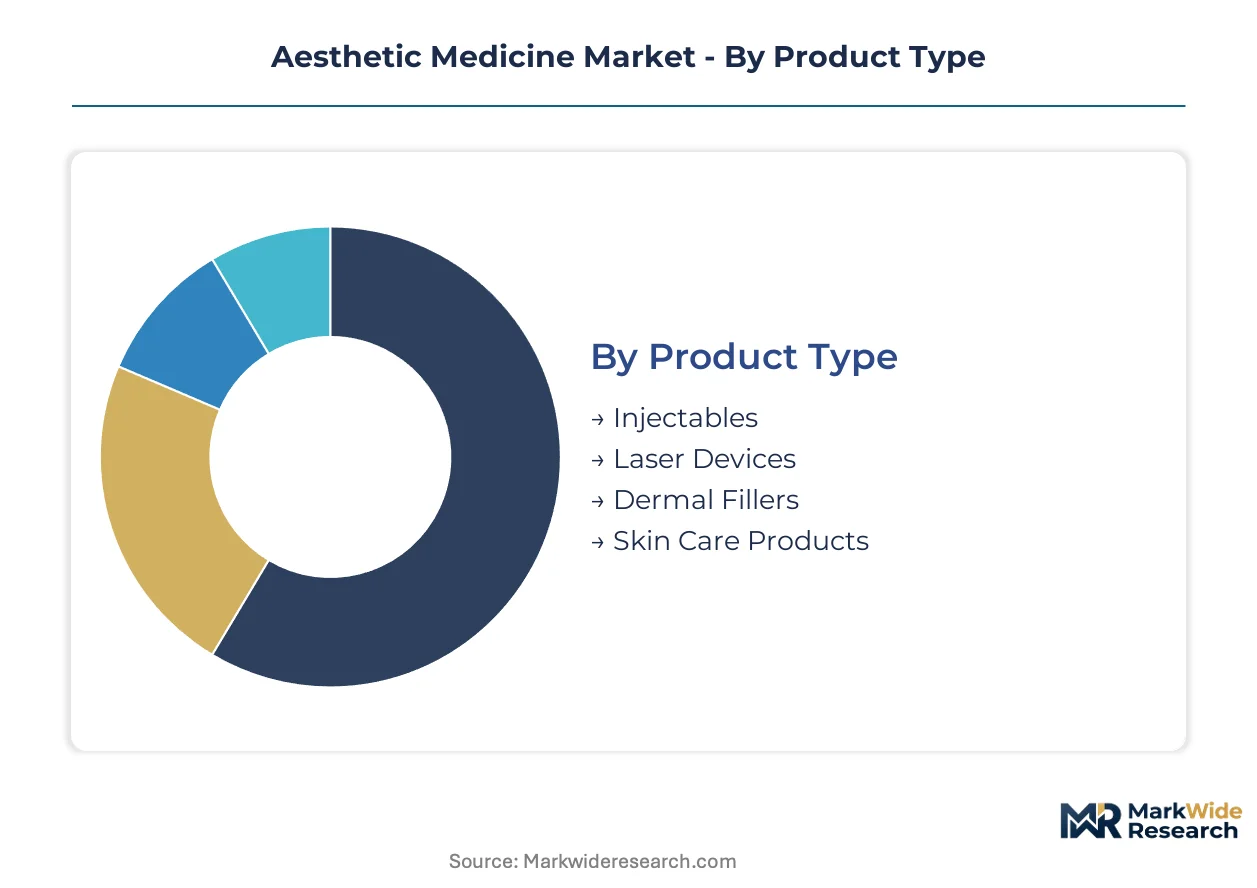
Segmentation in aesthetic medicine reveals distinct margin architectures and procurement behaviors. Product categories separate high-repeat injectables from capital-intensive devices, while end-user channels stratify around supervision requirements and per-patient spend thresholds.
Product Type:
Practitioner certification requirements and repeat purchase frequency drive buyer selection across product categories.
- Injectables:Neurotoxins and biostimulatory formulations require cold-chain logistics and prescriber licensing. Demand concentrates in United States metropolitan medical spas where quarterly treatment cycles generate predictable revenue streams.
- Laser Devices:Fractional and intense pulsed light platforms deliver energy at specified wavelengths for collagen remodeling. South Korean clinic chains drive replacement demand through accelerated 24-30 month technology refresh cycles.
- Dermal Fillers:Cross-linked hyaluronic acid formulations at 20-24 mg/mL concentrations address volume loss and contour definition.
- Skin Care Products:Medical-grade topicals with retinoid and peptide actives support procedure maintenance and preventive regimens.
Volume sits with injectables; growth tilts toward skin care products.
End User:
Supervision intensity and capital availability determine channel positioning for aesthetic service delivery.
- Medical Spas:Supervised clinic settings combine convenience with physician oversight for combination therapy protocols. United States urban markets in California and Texas are expanding membership-based pricing models that lock patients into prepaid quarterly cycles.
- Clinics:Specialized dermatology and plastic surgery practices maintain the deepest injector certification pipelines and highest per-procedure margins.
- Hospitals:Academic medical centers and outpatient surgery departments handle complex reconstructive and complication revision cases.
- Beauty Salons:Non-medical establishments face regulatory constraints on device energy settings and injectable administration scope.
Revenue concentrates with medical spas; certification depth favors clinics.
Procedure Type:
Patient demographic expansion and treatment interval economics shape procedure demand patterns.
- Wrinkle Reduction:Neurotoxin administration for glabellar and periorbital lines commands the highest treatment frequency with 3-4 month intervals. Younger cohorts in United States coastal markets are initiating preventive protocols earlier in the aging trajectory.
- Skin Resurfacing:Fractional laser and chemical peel procedures address photodamage and texture irregularities through controlled wounding responses.
- Body Contouring:Cryolipolysis and radiofrequency platforms target adipose tissue reduction without surgical intervention.
- Hair Restoration:Platelet-rich plasma injections and low-level laser therapy address androgenetic alopecia patterns.
Frequency advantages wrinkle reduction; technology investment flows toward skin resurfacing.
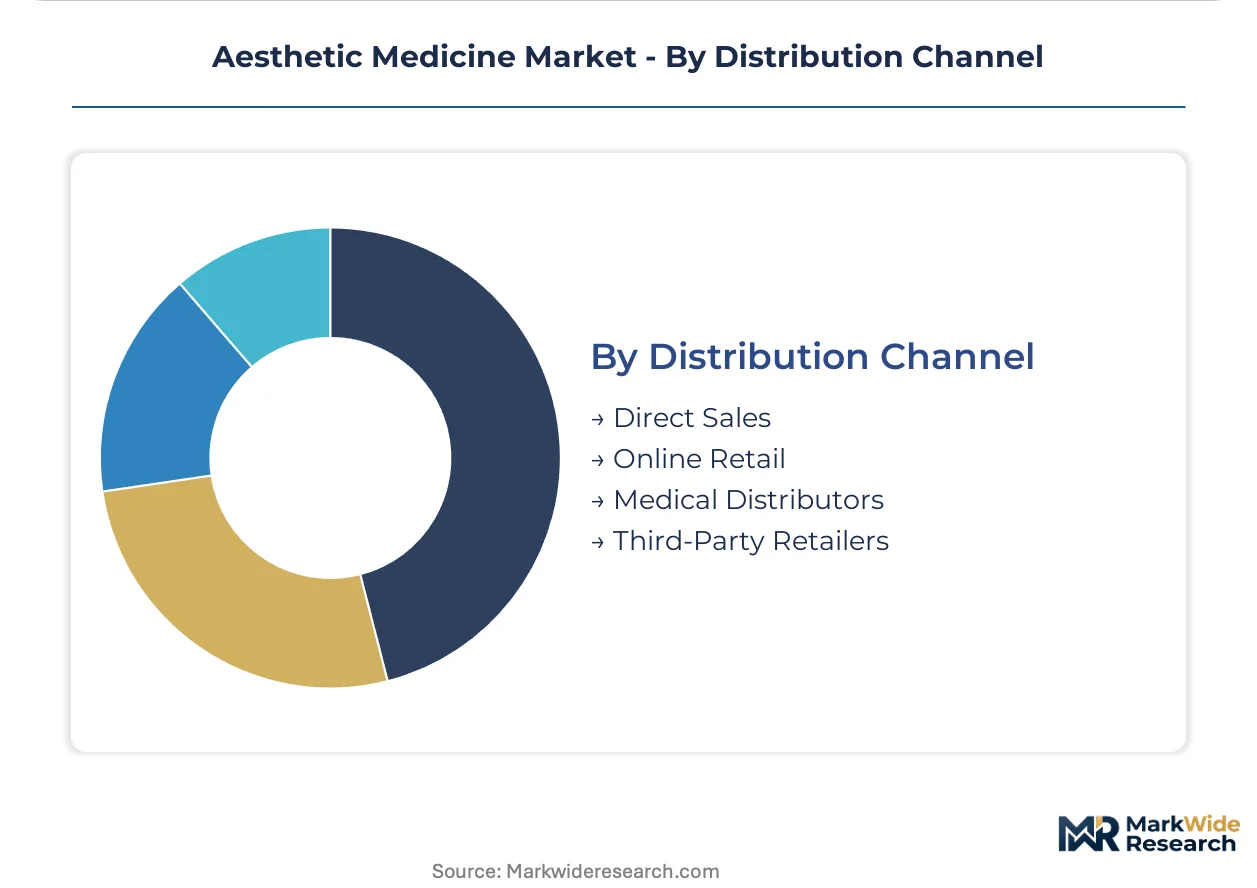
Distribution Channel:
Regulatory compliance burden and customer relationship depth determine channel viability for aesthetic product flows.
- Direct Sales:Manufacturer field forces maintain exclusive relationships with high-volume clinic accounts for injectable portfolios. AbbVie and Galderma deploy dedicated representatives to supervise inventory management and injection technique training.
- Medical Distributors:Specialty distributors handle device logistics, installation, and service contract administration for fractional laser and ultrasound platforms.
- Online Retail:E-commerce penetration concentrates in medical-grade skincare with lower regulatory barriers to direct consumer access.
- Third-Party Retailers:Pharmacy and beauty retail channels carry limited device consumables and post-procedure care formulations.
Margin capture favors direct sales; geographic reach expands through medical distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam district concentrates the world's densest cluster of aesthetic clinics, where per-capita procedure rates exceed any comparable metropolitan zone. National regulatory frameworks and cultural acceptance patterns diverge sharply across major markets.
United States
Medical spa chains in California and Texas are locking patients into prepaid quarterly membership cycles for neurotoxin maintenance. FDA 510(k) clearance timelines for energy-based devices now stretch to 18-24 months with expanded clinical cohort requirements. Los Angeles and Dallas-Fort Worth metro areas host the fastest-growing supervised clinic networks.
South Korea
MFDS accelerated approval tracks for fractional laser and radiofrequency devices compress pre-market validation to 8-12 months versus Western timelines. Seoul Capital Area clinics refresh energy-device platforms every 24-30 months through bundled consumable lease structures. Busan-Ulsan corridor manufacturers supply platform hardware to domestic chains before Western export.
Germany
EU MDR post-market surveillance obligations are filtering smaller device manufacturers from CE-marked portfolios. Notified body relationships concentrate among established multinationals with active implant registries. Baden-Württemberg precision engineering clusters supply optical components for fractional laser systems.
Brazil
ANVISA regulatory pathways for biostimulatory fillers require local clinical trial bridging studies that extend launch timelines. São Paulo and Rio de Janeiro metropolitan markets sustain physician-directed clinic networks with deep injector certification pipelines. Minas Gerais distributors handle device logistics for southeastern state expansions.
United Arab Emirates
MOHAP and SFDA frameworks in Dubai and Riyadh are licensing medical spa operations under supervised care protocols. Training academy and device leasing models capture first-mover positioning in Gulf Cooperation Council expansion. Abu Dhabi clinic infrastructure is absorbing spillover demand from Saudi patient flows.
Aesthetic Medicine Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and cold-chain logistics capabilities. Injectable portfolios command the deepest recurring revenue pools through quarterly treatment cycles and prescriber licensing barriers. Three archetypes dominate: integrated pharmaceutical-device houses, standalone energy-platform manufacturers, and biostimulatory formulation specialists. Competitive moves concentrate on direct clinic relationship capture and consumable cartridge bundling with platform leases.
Among integrated pharmaceutical houses, AbbVie and Galderma exemplify the premium-tier archetype through neurotoxin and biostimulatory filler portfolios. AbbVie leverages Allergan heritage to anchor direct clinic relationships in United States metropolitan markets. Galderma occupies a parallel position with biostimulatory formulations and integrated skincare systems that sustain recurring revenue per patient. Both represent the certification-barrier strategy that locks out commodity competitors.
| Leading Market Players |
|---|
| AbbVie |
| Galderma |
| Johnson & Johnson |
| Merz Pharma |
| Bausch Health |
| Cutera |
| Cynosure |
| Alma Lasers |
| Revance Therapeutics |
| Others |
Supply Flow & Price Mechanics
Physician-certification barriers split aesthetic medicine into premium injectable tiers and commoditized device segments, with pricing power accumulating at the certification-heavy neurotoxin end while supply chains fragment across cold-chain logistics for biologics and capital-equipment leasing for energy platforms. This bifurcation concentrates margin capture among AbbVie and Galderma's direct clinic relationships, while standalone laser manufacturers compete on financing terms and service attach rates.
Pricing Analysis
Outcome-based pricing anchors aesthetic medicine, with neurotoxin and filler treatments commanding per-procedure premiums tied to visible patient results and repeat visit loyalty. Three-tier pricing structure across premium, standard, and economy levels separates physician-supervised injectables from technician-delivered device protocols and over-the-counter maintenance topicals. Cost compression in the device tier is intensifying because bundled consumable leases and 24-month replacement cycles squeeze independent clinic operators. Price sensitivity concentrates among medical spa chains negotiating volume discounts, while specialized dermatology practices absorb premium markups for biostimulatory formulations with extended treatment intervals.
Supply Chain Analysis
Direct-to-clinic channels handle high-volume injectable demand, with manufacturer field forces maintaining exclusive inventory relationships and injection technique training programs. Pharmaceutical-grade hyaluronic acid production clusters in China and Japan, with cross-linked HA feedstock drawing from fermentation facilities in Shandong and Osaka prefectures. Cold-chain logistics for neurotoxins rests on temperature-controlled distribution networks with 2-8°C requirements, while fractional laser platforms source optical components from Baden-Württemberg precision engineering clusters. Single-source vulnerability concentrates in Chinese fermentation capacity for HA raw material, exposing formulators to input cost volatility. Distribution runs through specialty medical distributors for device installation and service contract administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aesthetic medicine has become a vertical-integration race, with incumbents pursuing backward integration into biostimulatory filler feedstock and downstream control over medical spa training academies to lock in procedure volume.
For Market Incumbents: Cement direct clinic relationships through exclusive injectable supply agreements and embedded inventory management systems that raise switching costs for high-volume accounts. Expand backward integration into cross-linked HA fermentation capacity to reduce exposure to Chinese and Japanese feedstock concentration. Certification bottlenecks for nurse injectors present a margin defense opportunity through proprietary training academy investments that constrain competitor clinic capacity expansion. For New Entrants and Emerging Players: Underserved mid-tier medical spa operators in Texas secondary metros present a white-space target for fractional laser leasing models with technician certification bundled into platform contracts. Dubai and Riyadh licensing frameworks under MOHAP and SFDA offer first-mover positioning for device-as-a-service entrants with training academy partnerships. Go-to-market traction flows through distributor relationships with established Gulf Cooperation Council medical equipment logistics networks rather than direct field force builds. For Investors and Strategic Acquirers: Re-rating potential sits with EU MDR-compliant device manufacturers given post-market surveillance obligations filtering smaller competitors from CE-marked portfolios. Long-term viability across the analysis window favors mid-scale players with notified body relationships and active implant registry capabilities. Acquisition targets cluster among distressed laser platform manufacturers exiting European markets under tightened vigilance requirements. The signal to watch is notified body capacity constraints extending CE marking timelines beyond 18 months.| Strategic Initiative | Industry Significance |
|---|---|
| Biostimulatory Filler Pipeline Expansion | Poly-L-lactic acid formulations extend treatment intervals and patient lifetime value for clinic accounts. |
| MFDS Pre-Market Validation Investment | South Korea's accelerated approval tracks compress time-to-market for novel radiofrequency technologies ahead of FDA pathways. |
| Medical Spa Training Academy Partnership | Certification pipelines for nurse injectors lock in procedure volume and raise competitor entry barriers. |
| EU MDR Notified Body Relationship | Active implant registries and periodic safety update reports secure CE-marked portfolio continuity. |
| Consumable Cartridge Bundling | Microfocused ultrasound platforms absorb margin pressure through lease-locked disposable revenue streams. |
Methodological Framework
Document review covered FDA 510(k) clearance databases, MFDS approval registries, EU MDR notified body guidance documents, and medical spa industry trade publications, complemented by interviews with clinic medical directors, device manufacturer product managers, specialty distributor operations leads, and pharmaceutical regulatory affairs specialists. Secondary validation drew from hospital procurement databases, GPO contract filings, and customs records for hyaluronic acid feedstock trade flows. Bottom-up clinic census data triangulated against top-down manufacturer revenue disclosures.
Segment-level outputs across product type, end user, procedure category, and regional regulatory cluster were generated through structured modeling of treatment frequency, per-procedure pricing, and platform replacement cycles. CAGRs were derived from log-linear trend fitting of historical volume trajectories adjusted for regulatory approval timeline impacts. Forecast inputs incorporated injector certification pipeline constraints, energy-device technology refresh intervals, and membership program adoption curves in United States metropolitan markets.
Revisions become necessary when FDA clinical evidence requirements escalate beyond current 510(k) cohort thresholds, when MFDS approval timelines extend due to backlog accumulation, or when EU MDR notified body capacity constraints disrupt CE marking continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Hirsutism Treatment Market
Aesthetic Medicine
Europe Dermal Fillers Market
Aesthetic Medicine
Facial Rejuvenation Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Global Dermal Filler Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Medical Aesthetic Dermal Filler Market
Aesthetic Medicine
Non-Surgical Fat Reduction Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Spain Facial Aesthetics Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Middle East and Africa Aesthetic Dermatology Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Global Aesthetic Fillers Market
Aesthetic Medicine
Skin Tightening Market