
 Italy Aesthetic Market | 2026-2036
Italy Aesthetic Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Aesthetic Market Insights
Trained aesthetic physicians is bifurcating the Italy aesthetic landscape into high-complexity intervention hubs and commoditized service tiers. Galderma leverages its dermal filler portfolio to anchor the injectables channel across northern Italian metropolitan clinics. L'Oréal Italia SpA sustains brand dominance in professional-grade skin care through dermatologist-exclusive distribution. Collistar SpA competes on accessible price positioning within spa and beauty center channels.
The Italy aesthetic sector encompasses medically supervised and cosmetically oriented procedures employing energy-based devices, pharmaceutical formulations, and topical agents to modify skin appearance, body contour, or facial structure. Injectable hyaluronic acid formulations and fractional laser systems operate at specified wavelengths and depths to stimulate collagen remodeling or adipose tissue disruption. Injectables command premium positioning due to physician-administered protocols and repeat-visit economics, while laser treatments capture expanding clinic investment as device efficacy improves across skin rejuvenation and fat reduction applications. Skin care products retain volume leadership through retail and professional dual-channel distribution, though margin pools concentrate in clinic-dispensed medical-grade lines.
Italy's Ministry of Health enforces EU MDR compliance for aesthetic devices, while the Italian Medicines Agency (AIFA) regulates pharmaceutical injectables under centralized authorization pathways. The National Institute of Health (ISS) issues clinical guidelines that shape physician training curricula and treatment protocol standardization. Stakeholders must monitor regional health authority licensing enforcement as clinic density rises in saturated urban markets.
Market Dynamics
Italy's transposition of EU MDR into national law is compressing the device vendor landscape while concentrating demand among certified clinic networks in Milan, Rome, and Bologna. This regulatory pressure is accelerating capital deployment toward compliance-ready infrastructure.
Growth Catalysts
- EU MDR National Transposition:Italy's Ministry of Health enforcement of elevated device certification standards is filtering out non-compliant suppliers and consolidating procurement toward established manufacturers with notified body relationships.
- Minimally Invasive Protocol Expansion:Dermatology clinics across Lombardy are broadening service menus to include combination therapies using hyaluronic acid injectables paired with fractional laser sequences.
- Milan Private Clinic Corridor Density:Concentrated high-net-worth patient pools in Milan's Porta Venezia and Brera districts sustain premium pricing for body contouring and skin rejuvenation procedures.
Market Restraints
- Notified Body Bottleneck:Limited EU MDR-designated notified body capacity is extending certification timelines for laser and radiofrequency devices, delaying product launches by 12-18 months.
- Hyaluronic Acid Raw Material Concentration:Pharmaceutical-grade sodium hyaluronate supply concentrates among a handful of European fermentation specialists, exposing formulation costs to input volatility.
- Reimbursement Exclusion:Italy's Servizio Sanitario Nazionale excludes aesthetic procedures from coverage, constraining addressable demand to discretionary private-pay segments.
Strategic Opportunities
- Southern Italy Clinic Underpenetration:Naples, Bari, and Catania exhibit clinic density ratios 40% below northern benchmarks, presenting first-mover expansion potential for compliant device vendors.
- Teleconsultation-Enabled Pre-Screening:Remote dermatological assessment platforms are reducing consultation friction and expanding patient acquisition beyond traditional metropolitan catchment areas.
- Combination Therapy Protocol Standardization:ISS clinical guideline development for sequential injectable-laser treatments is creating reimbursement-adjacent positioning for medically supervised aesthetic networks.
Industry Challenges
- Trained Aesthetic Physician Scarcity:Italy's specialist dermatology and plastic surgery residency pipelines produce insufficient operators to staff expanding clinic networks, inflating compensation for credentialed practitioners.
- Device-Platform Integration Complexity:Clinic management software incompatibility with new-generation laser systems is forcing costly middleware development or manual workflow workarounds.
- Patient Record Portability Gaps:Fragmented electronic health record standards across regional health authorities complicate treatment continuity for mobile patient populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Aesthetic Market |
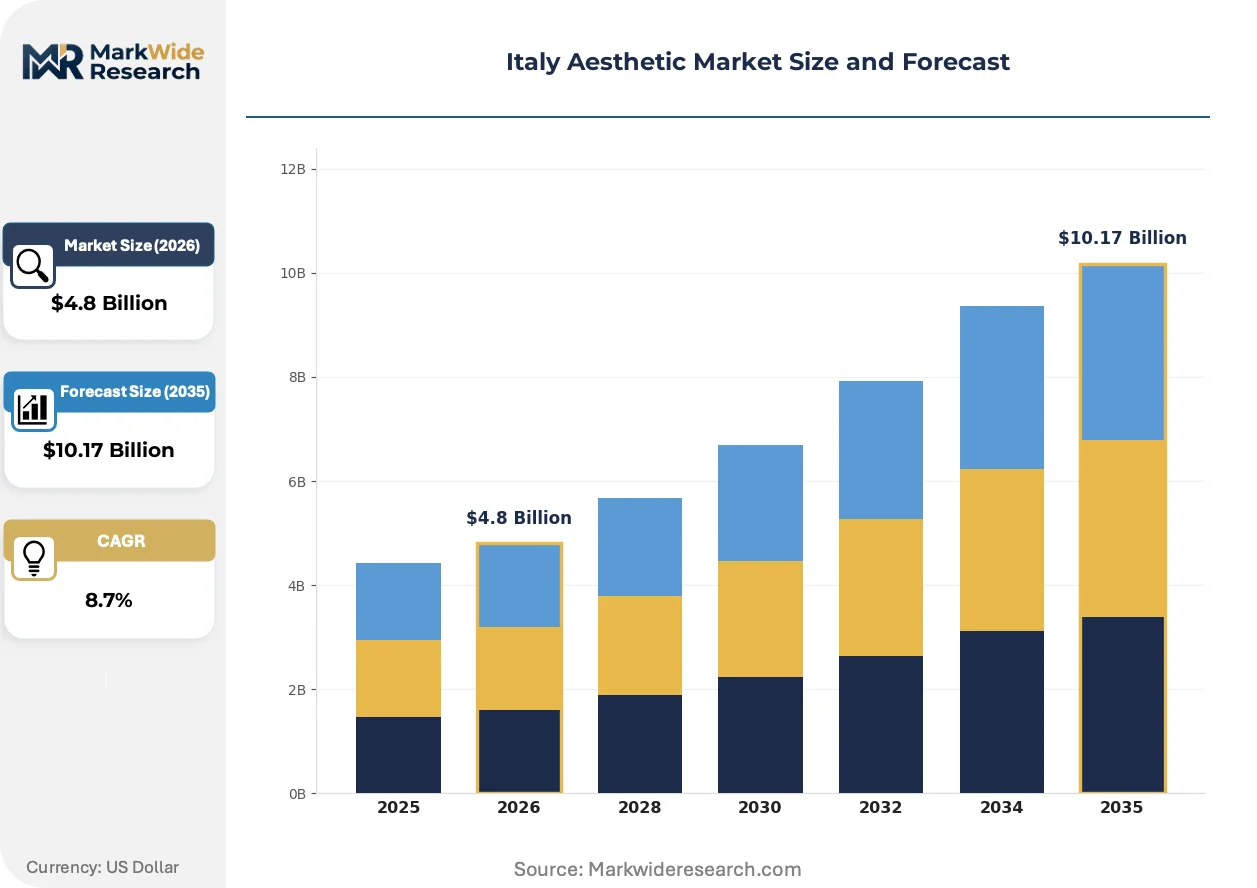
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Laser Treatments, Skin Care Products, Body Contouring End User: Clinics, Dermatologists, Spas, Medical Institutions Application: Anti-Aging, Skin Rejuvenation, Fat Reduction, Cosmetic Enhancements Technology: RF Technology, Ultrasound, Cryotherapy, Light Therapy |
| Companies Covered | Pierre Fabre Italia SpA, Galderma, L'Oréal Italia SpA, Clarins Italia SpA, Shiseido Group Italy SpA, Beiersdorf SpA, Allergan, Collistar SpA, Estée Lauder Srl, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Aesthetic Market Trends and Innovations
Device miniaturization and algorithm-driven treatment personalization are compressing the gap between professional clinic outcomes and medi-spa service tiers. These shifts are redistributing value capture across the Italian aesthetic supply chain.
Picosecond laser technology is fragmenting the traditional nanosecond device market by enabling faster pigment clearance with reduced thermal damage to surrounding tissue. Dermatology clinics in Milan and Turin are adopting these systems at replacement-cycle velocity. The technology is fragmenting competitive positioning by allowing mid-tier clinics to offer outcomes previously restricted to premium academic medical centers.
Italy's AIFA is tightening pharmacovigilance reporting requirements for hyaluronic acid injectables, mandating adverse event documentation that parallels prescription drug surveillance. This regulatory elevation is increasing compliance overhead for clinic operators and distributor networks. Injectable-focused practices in Emilia-Romagna are responding by consolidating purchasing through authorized importer channels with established pharmacovigilance infrastructure.
Subscription-based maintenance programs are displacing single-session booking patterns among millennial and Gen-Z patient cohorts. Milanese clinics are bundling quarterly injectable touch-ups with seasonal laser treatments under annual membership structures. This behavioral shift concentrates patient lifetime value while compressing acquisition cost economics for clinic operators with established loyalty infrastructure.
Italy Aesthetic Market Segmentation
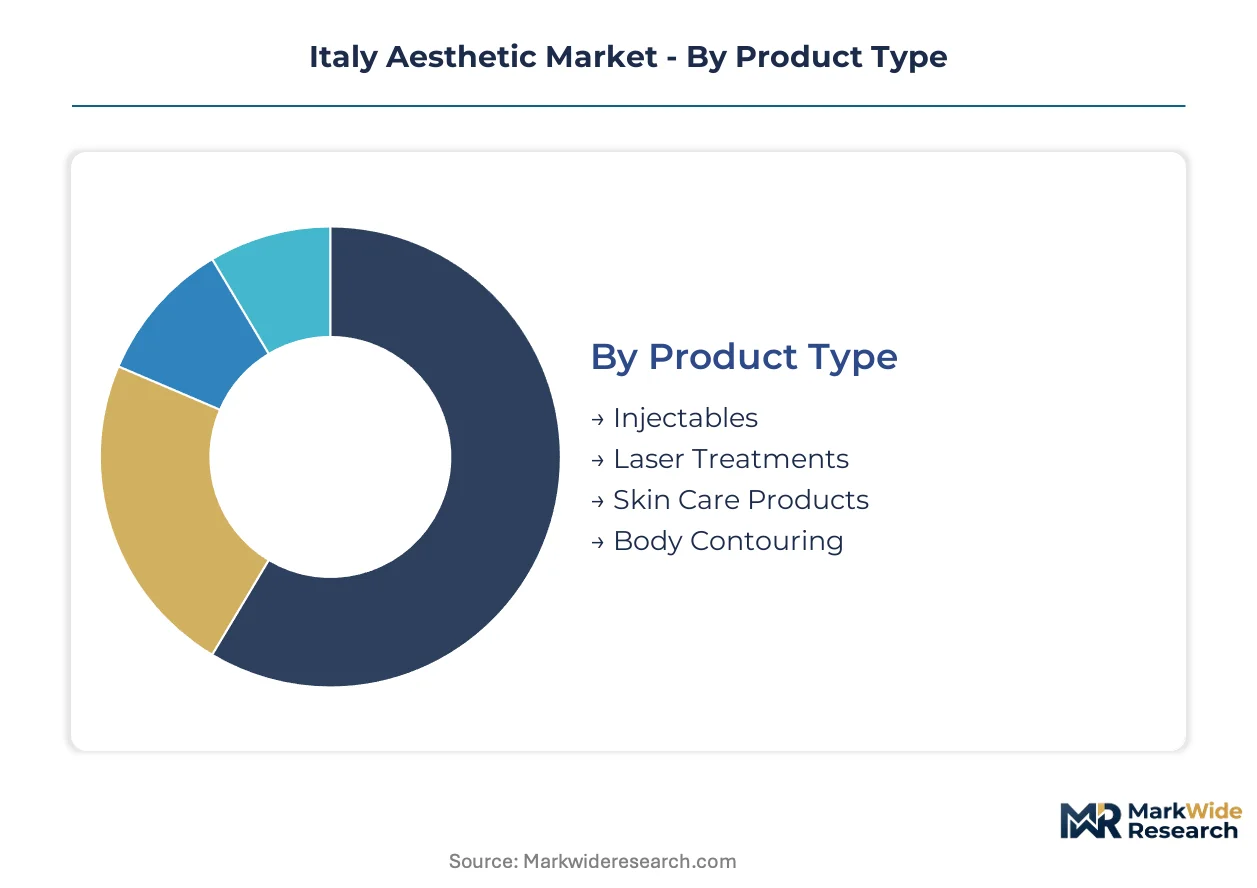
Channel economics in Italy's aesthetic sector diverge sharply across product categories. Injectables flow exclusively through physician-supervised channels, while skin care products penetrate retail, spa, and professional dispensing networks simultaneously. Understanding these pathway distinctions clarifies margin capture and regulatory exposure for each segment.
Product Type:
Channel concentration varies dramatically: injectables and laser treatments remain captive to clinic networks, whereas skin care and body contouring split across medical and non-medical distribution.
- Injectables:Hyaluronic acid and botulinum toxin formulations require physician administration under AIFA pharmaceutical oversight. Demand clusters in Milan's private clinic corridor, where repeat-visit economics sustain premium pricing and patient loyalty programs.
- Laser Treatments:Fractional, picosecond, and radiofrequency devices operate at specified wavelengths for collagen remodeling or adipose disruption. Northern Italian metropolitan clinics in Lombardy and Emilia-Romagna are expanding device fleets to capture combination therapy revenue.
- Skin Care Products:Medical-grade and cosmeceutical formulations distribute through dermatologist-exclusive, spa retail, and direct-to-consumer channels. L'Oréal Italia and Collistar SpA compete across tiered positioning.
- Body Contouring:Cryolipolysis and radiofrequency-based fat reduction systems serve clinic and medi-spa segments. Southern Italy's underpenetrated markets present first-mover expansion potential for compliant device vendors.
Injectables dominate installed base. Body contouring is where expansion concentrates.
End User:
Customer-type segmentation reveals a bifurcation between medically supervised and cosmetically oriented service tiers, with regulatory compliance thresholds determining channel access.
- Clinics:Private aesthetic medicine centers concentrate in Milan, Rome, and Bologna, deploying combination therapy protocols. EU MDR compliance requirements are filtering procurement toward established device manufacturers with notified body relationships.
- Dermatologists:Specialist physicians anchor high-complexity intervention hubs, particularly across Lombardy's dense metropolitan networks. Trained aesthetic physician scarcity inflates compensation for credentialed practitioners.
- Spas:Non-medical beauty centers access lower-risk device tiers and retail skin care distribution. Collistar SpA competes aggressively on accessible price positioning within this channel.
- Medical Institutions:Hospital-affiliated aesthetic units leverage ISS clinical guidelines for protocol standardization and training curriculum alignment.
Clinics capture premium procedure volume. Spas are climbing the fastest in absolute outlet expansion.
Application:
Procedure purpose segments align with patient demographic profiles and payment willingness, with anti-aging commanding sustained repeat engagement.
- Anti-Aging:Neuromodulator and filler protocols targeting facial lines require quarterly maintenance. Milanese clinics bundle these into subscription-based annual memberships for millennial and Gen-Z cohorts.
- Skin Rejuvenation:Laser resurfacing and topical retinoid protocols address photodamage and texture irregularities. Demand outpaces national averages in Milan's Porta Venezia and Brera districts.
- Fat Reduction:Cryolipolysis and ultrasound-based adipose disruption target localized deposits. Device miniaturization is compressing outcome gaps between professional clinics and medi-spa tiers.
- Cosmetic Enhancements:Structural facial augmentation and body sculpting procedures attract high-net-worth patient pools. AIFA pharmacovigilance tightening elevates compliance overhead for injectable-focused practices.
Anti-Aging dominates patient visit frequency. Fat reduction is gaining share fastest among younger demographic entrants.
Technology:
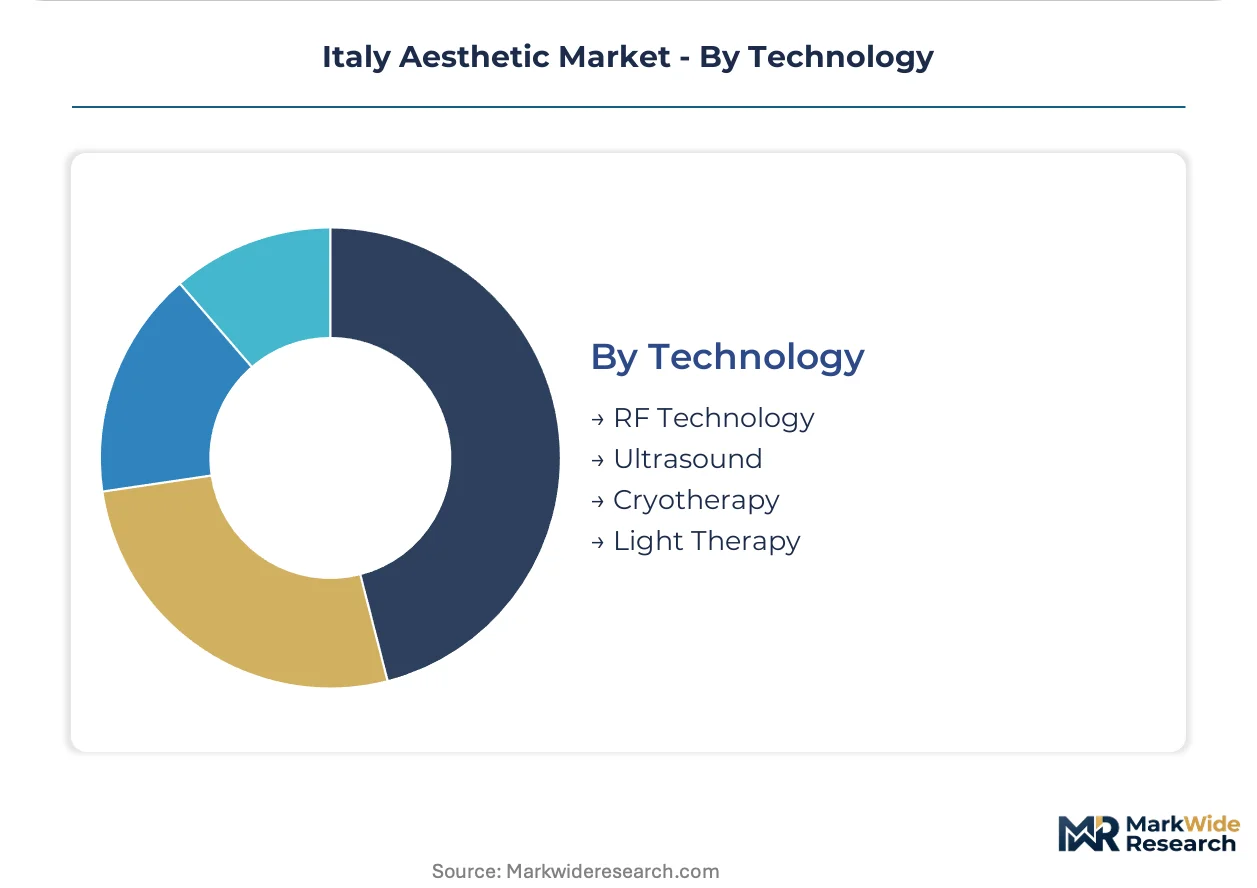
Energy-delivery modality selection determines capital intensity, treatment protocol complexity, and regulatory classification under EU MDR.
- RF Technology:Radiofrequency systems generate thermal energy for collagen contraction and fat cell disruption. Notified body bottlenecks are extending certification timelines by 12-18 months.
- Ultrasound:High-intensity focused ultrasound enables non-invasive adipose tissue targeting at specified depths. Mid-tier clinics are adopting these systems to offer outcomes previously restricted to premium academic centers.
- Cryotherapy:Controlled cooling protocols selectively eliminate fat cells without surrounding tissue damage. Device-platform integration complexity forces costly middleware development.
- Light Therapy:LED and laser-based photobiomodulation addresses inflammation and skin rejuvenation. Picosecond technology is fragmenting the traditional nanosecond device market.
RF Technology dominates installed clinic device base. Ultrasound is where manufacturer R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's Ministry of Health anchors aesthetic device oversight through EU MDR transposition, while regional health authorities enforce clinic licensing standards. The market concentrates across northern metropolitan corridors where patient density and disposable income sustain premium procedure pricing.
Lombardy
Milan's Porta Venezia and Brera districts generate premium body contouring and skin rejuvenation demand that outpaces national averages. The region's health authority mandates EU MDR compliance documentation for all energy-based devices deployed in private clinics. Dermatology networks across the metropolitan area are expanding combination therapy protocols pairing injectables with fractional laser sequences.
Emilia-Romagna
Bologna anchors a dense cluster of aesthetic medicine centers where trained physician scarcity inflates compensation for credentialed practitioners. AIFA pharmacovigilance requirements for hyaluronic acid injectables drive clinic consolidation toward authorized importer channels. The regional health system supports ISS-aligned training curricula that standardize treatment protocols across affiliated facilities.
Lazio
Rome's private clinic corridor captures substantial cosmetic enhancement volume from central Italian patient catchments. The Ministry of Health's national MDR enforcement filters device procurement toward established manufacturers with notified body relationships. Medical institutions in the capital leverage ISS guidelines for protocol development and resident physician training alignment.
Piedmont
Turin's dermatology clinics are adopting picosecond laser systems at replacement-cycle velocity to capture pigment clearance revenue. Regional licensing authorities monitor clinic density as saturation risks emerge in prime metropolitan zones. Device miniaturization trends enable mid-tier operators to offer outcomes previously restricted to premium academic centers.
Veneto
Padua and Verona exhibit growing demand for non-invasive fat reduction procedures among younger demographic entrants. The regional health authority coordinates with national regulators on adverse event reporting infrastructure for injectable products. Spa and beauty center channels in tourist-oriented municipalities access lower-risk device tiers through Collistar SpA's accessible price positioning.
Italy Aesthetic Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Italy's aesthetic market structure. Pharmaceutical multinationals with dermal filler portfolios anchor the injectables channel, while professional skin care houses dominate dual-channel distribution through dermatologist-exclusive and retail pathways. Three archetypes define competitive positioning: physician-administered pharmaceutical specialists, professional-grade skin care formulators, and accessible spa-channel marketers. Dominant competitive moves include portfolio diversification across procedure types and geographic expansion into southern Italy's underpenetrated markets.
Within the pharmaceutical specialist tier, Galderma and Allergan exemplify the injectables-focused archetype through their hyaluronic acid and neuromodulator positioning. L'Oréal Italia SpA anchors the professional skin care segment through dermatologist-exclusive distribution networks. Collistar SpA occupies the accessible spa-channel position, competing on price positioning within non-medical beauty center channels.
| Leading Market Players |
|---|
| Pierre Fabre Italia SpA |
| Galderma |
| L'Oréal Italia SpA |
| Clarins Italia SpA |
| Shiseido Group Italy SpA |
| Beiersdorf SpA |
| Allergan |
| Collistar SpA |
| Estée Lauder Srl |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-eighteen-month notified body certification timelines for EU MDR-compliant laser and radiofrequency devices compress inventory planning horizons for Italian clinic procurement teams, concentrating pricing power among established manufacturers with pre-existing notified body relationships while inflating capital deployment requirements for compliance-ready infrastructure.
Pricing Analysis
Milan's Porta Venezia and Brera districts command 15-25% procedure premiums over national benchmarks, reflecting concentrated high-net-worth patient pools. Three-tier pricing structure across premium physician-administered injectables, standard clinic-based laser treatments, and economy spa-channel skin care products dominates the landscape. Pricing pressure stems from raw material concentration among European pharmaceutical-grade sodium hyaluronate fermentation specialists. Price-sensitive millennial and Gen-Z cohorts drive subscription-based annual membership adoption, while high-net-worth patients exhibit minimal sensitivity to per-session pricing.
Supply Chain Analysis
Inventory buffers for AIFA-regulated hyaluronic acid injectables extend beyond typical pharmaceutical distribution cycles due to pharmacovigilance documentation requirements. Supply concentrates in Germany, Switzerland, and France for energy-based device manufacturing, with pharmaceutical-grade sodium hyaluronate sourcing anchored in European fermentation specialists. Single-source vulnerability characterizes raw material dependencies for sodium hyaluronate, botulinum toxin master cell banks, and picosecond laser crystal arrays. Distribution runs through authorized importer channels with established pharmacovigilance infrastructure for injectables, while skin care products penetrate dual-channel professional and retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's aesthetic sector sits as a high-growth disruption opportunity as EU MDR transposition filters non-compliant device vendors and picosecond laser technology fragments competitive positioning by enabling mid-tier clinics to match premium academic center outcomes.
For Market Incumbents: Secure notified body relationships ahead of competitor certification timelines to lock in procurement preference among Milan and Rome clinic networks facing EU MDR compliance deadlines. Consolidate purchasing through authorized importer channels to absorb AIFA pharmacovigilance overhead that threatens smaller distributor margins. Channel control represents the critical defensive lever against emerging teleconsultation-enabled patient acquisition platforms. For New Entrants and Emerging Players: Differentiate on algorithm-driven treatment personalization and device miniaturization to capture medi-spa tier expansion beyond saturated northern metropolitan corridors. Target Naples, Bari, and Catania where clinic density ratios trail northern benchmarks by 40%. Teleconsultation-enabled pre-screening platforms offer the most penetrable go-to-market angle for bypassing traditional metropolitan catchment limitations. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue healthcare services play because subscription-based maintenance programs displace single-session booking patterns and concentrate patient lifetime value. Acquisition focus should center on compliant device vendors with notified body relationships and established pharmacovigilance infrastructure. The signal to watch is ISS clinical guideline development for sequential injectable-laser treatments, which would create reimbursement-adjacent positioning for medically supervised networks.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Notified body relationships lock in procurement preference among Milan clinic networks facing compliance deadlines. |
| Teleconsultation Platform Deployment | Remote dermatological assessment reduces consultation friction and expands patient acquisition beyond metropolitan catchments. |
| Combination Therapy Protocol Standardization | ISS guideline alignment creates reimbursement-adjacent positioning for medically supervised aesthetic networks. |
| Southern Italy Clinic Network Expansion | First-mover presence in Naples, Bari, and Catania captures 40% underpenetration versus northern benchmarks. |
| Subscription-Based Membership Structuring | Annual bundling of quarterly injectable touch-ups with seasonal laser treatments concentrates patient lifetime value. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with aesthetic medicine clinic directors, dermatology network procurement leads, biomedical engineers at device manufacturers, and AIFA regulatory affairs specialists; and secondary validation through EU MDR notified body certification databases, AIFA pharmacovigilance reporting records, ISS clinical guideline publications, and regional health authority licensing registries. Bottom-up procedure volume estimates across Lombardy, Emilia-Romagna, Lazio, Piedmont, and Veneto triangulated against top-down market sizing from channel shipment data.
Across the analysis window, the forecast framework modeled demand trajectories by product type, end user channel, application purpose, and energy-delivery technology modality. CAGRs derived from procedure volume elasticity to disposable income trends, clinic network expansion rates, and replacement cycle velocity for picosecond laser systems. Key inputs included EU MDR certification timeline bottlenecks and AIFA pharmacovigilance compliance cost structures.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement intensity or stable pharmaceutical-grade sodium hyaluronate supply would require recalibration. Forecasts reflect assumptions regarding notified body capacity expansion and trained aesthetic physician pipeline growth. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
North America Aesthetic Dermatology Market
Aesthetic Medicine
Japan Facial Aesthetics Market
Aesthetic Medicine
Platysmaplasty Treatment Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market
Aesthetic Medicine
Global Cellulite Treatment Market
Aesthetic Medicine
Professional Beauty Services Market
Aesthetic Medicine
Aesthetic Medicine Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Global Aesthetic Threads Market
Aesthetic Medicine
Global Stretch Marks Treatment Market
Aesthetic Medicine
Chemical Peel Market