
 Wearable Insulin Pump Market | 2026-2036
Wearable Insulin Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Insulin Pump Market Insights
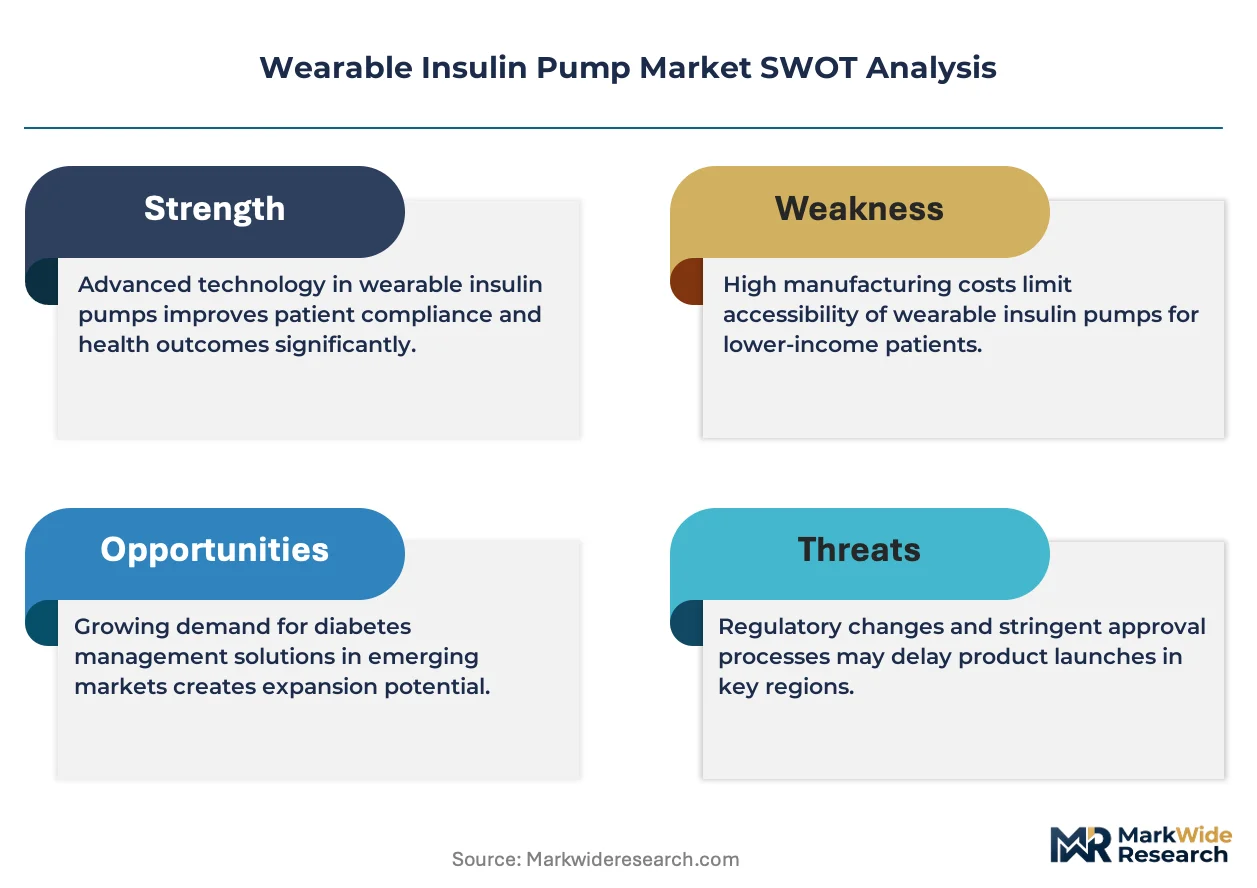
Subscription-based leasing for wearable insulin pumps is fragmenting competitive entry barriers, allowing patients and clinics to access devices without large capital outlays. Medtronic leverages its manufacturing scale to sustain broad distribution across hospital and retail channels. Insulet Corporation anchors its position through patch pump specialization that eliminates tubing. Tandem Diabetes Care differentiates via closed-loop algorithm integration with continuous glucose monitors.
A wearable insulin pump is a battery-powered, electromechanical drug delivery device worn on the body that administers rapid-acting insulin through a subcutaneous cannula at programmable basal rates and patient-triggered bolus doses, primarily serving diabetes patients requiring intensive insulin therapy outside clinical settings. Patch pump designs lead volume due to their disposable, tube-free form factor that improves adherence among active adults and pediatric users. Smart pump segments incorporating Bluetooth and closed-loop systems capture expanding margin pools as payers prioritize automated glycemic control outcomes. Traditional pump categories face slower growth amid patient migration toward integrated, smartphone-connected alternatives.
The FDA regulates wearable insulin pumps as Class II medical devices under 21 CFR 882.5550, requiring premarket notification and human factors validation that shapes product development timelines and design constraints. In Europe, the MDR and CE marking framework mandate clinical evidence and post-market surveillance, while the EU AI Act introduces additional scrutiny for closed-loop algorithms that autonomously adjust insulin delivery. Japan's PMDA enforces QMS requirements aligned with JIS standards that manufacturers must satisfy for market access. Stakeholders must monitor evolving software-as-medical-device classifications and reimbursement parity between automated and manual insulin delivery systems.
Market Dynamics
Closed-loop algorithm maturation is compressing competitive differentiation timelines as MEMS sensor miniaturization converges with automated glycemic control protocols, forcing manufacturers to integrate software capabilities ahead of hardware refresh cycles.
Growth Catalysts
- Reimbursement pathway expansion:Medicare coverage for closed-loop systems in the United States removes patient cost barriers for intensive insulin therapy outside hospital settings.
- MEMS sensor integration:Miniaturized electromechanical sensors enable tube-free patch pump designs that improve adherence among pediatric and active adult users.
- Home care demand concentration:Type 1 diabetes patients managing therapy outside clinical settings drive volume adoption as remote monitoring infrastructure matures.
Market Restraints
- Regulatory friction from EU AI Act:Autonomous insulin adjustment algorithms face additional clinical evidence requirements that extend European market entry timelines.
- Supply concentration in sensor substrates:MEMS fabrication capacity clusters in East Asian foundries, creating geographic vulnerability for pump manufacturers dependent on continuous glucose monitor integration.
- Lithium-ion cell cost volatility:Battery chemistry price swings directly impact wearable pump bill-of-materials and margin stability for disposable patch designs.
Strategic Opportunities
- Underpenetrated Japan market:Aging demographics and established diabetes infrastructure create white space for automated delivery systems as PMDA QMS pathways clarify.
- Subscription leasing channel innovation:Device-as-a-service models reduce capital barriers for clinics and patients while generating recurring revenue streams.
- Bluetooth-smartphone convergence:Wireless connectivity integration with iOS and Android ecosystems enables remote dosing alerts and caregiver monitoring features.
Industry Challenges
- Human factors engineering talent scarcity:FDA 21 CFR 882.5550 validation requirements demand specialized usability expertise that outpaces workforce supply.
- Software-as-medical-device classification uncertainty:Evolving FDA guidance on algorithm updates creates compliance timeline risk for closed-loop system manufacturers.
- Legacy pump integration complexity:Migration from traditional tubed devices to patch platforms requires patient retraining and clinical workflow redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Insulin Pump Market |
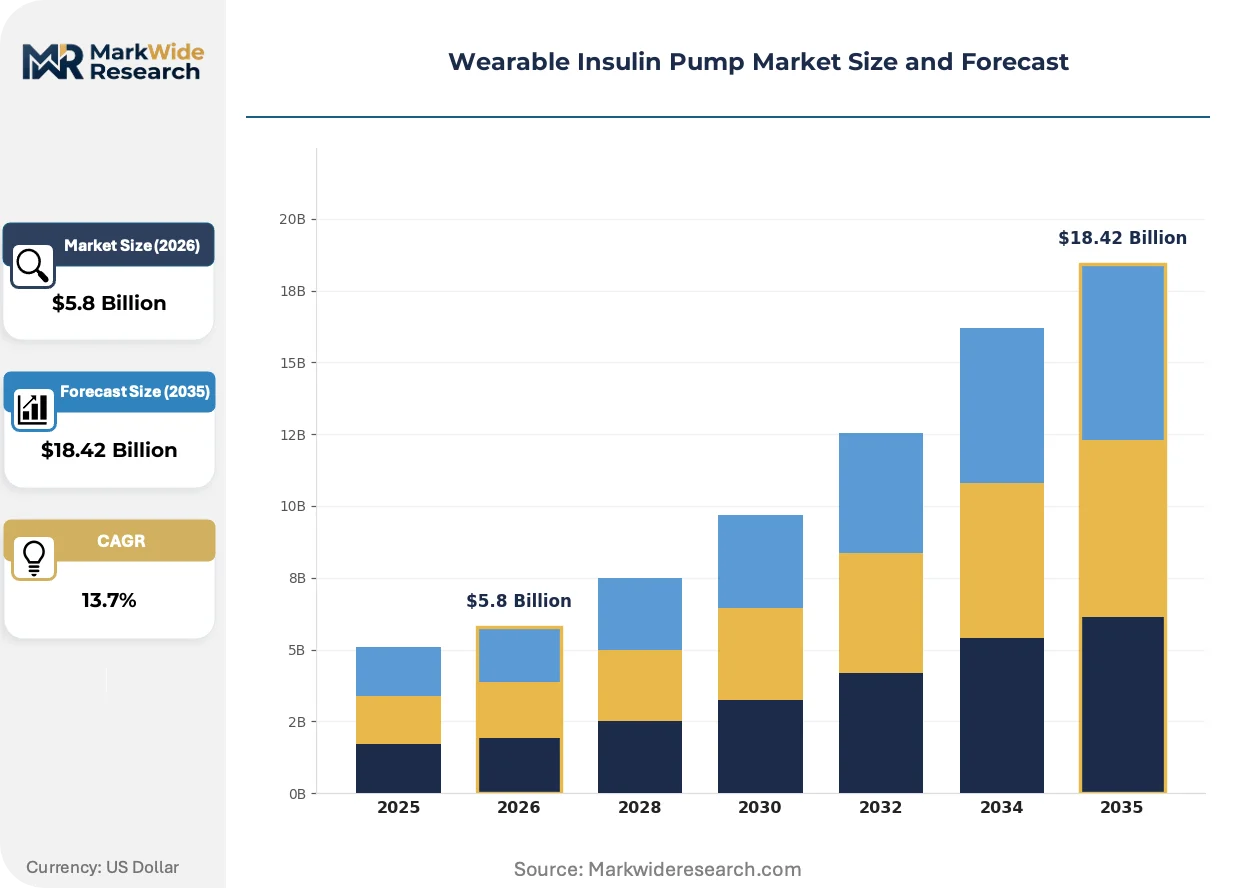
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $18.42 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Pump, Traditional Pump, Smart Pump, Disposable Pump Technology: Bluetooth, RFID, Wi-Fi, Closed-Loop System End User: Children, Adults, Seniors, Healthcare Providers Pricing Model: Subscription, One-Time Purchase, Lease, Reimbursement |
| Companies Covered | Medtronic, Insulet Corporation, Tandem Diabetes Care, SOOIL Development, Roche, Ypsomed, EOFlow, Beta Bionics, Bigfoot Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Insulin Pump Market Trends and Innovations
Algorithm-driven automation is redefining competitive boundaries as hardware commoditization accelerates and software differentiation becomes the primary margin driver across insulin delivery platforms.
Closed-loop control systems are hybridizing predictive glucose algorithms with real-time continuous monitor feeds to enable autonomous basal rate adjustments without patient intervention. Pediatric endocrinology practices and adult intensive insulin users are adopting these systems faster than traditional pump replacement cycles would predict. This convergence is compressing the viable market window for open-loop devices and forcing legacy manufacturers to accelerate software roadmap investments.
Europe's MDR and EU AI Act are imposing layered clinical evidence requirements on autonomous insulin delivery algorithms that adjust dosing without physician confirmation. The regulatory burden falls heaviest on closed-loop system developers, who must now maintain post-market surveillance infrastructure spanning hardware failure modes and algorithm performance drift. German notified bodies and French ANSM reviewers are setting precedent timelines that other European regulators reference.
Patient data ownership preferences are fragmenting traditional device-clinic relationships as smartphone-connected pumps enable direct-to-patient software updates and remote monitoring. Endocrinology practices are unbundling device provisioning from care management, with United States diabetes centers leading this separation. This behavioral shift concentrates purchasing influence among payers prioritizing automated glycemic outcome metrics over hardware brand loyalty.
Wearable Insulin Pump Market Segmentation
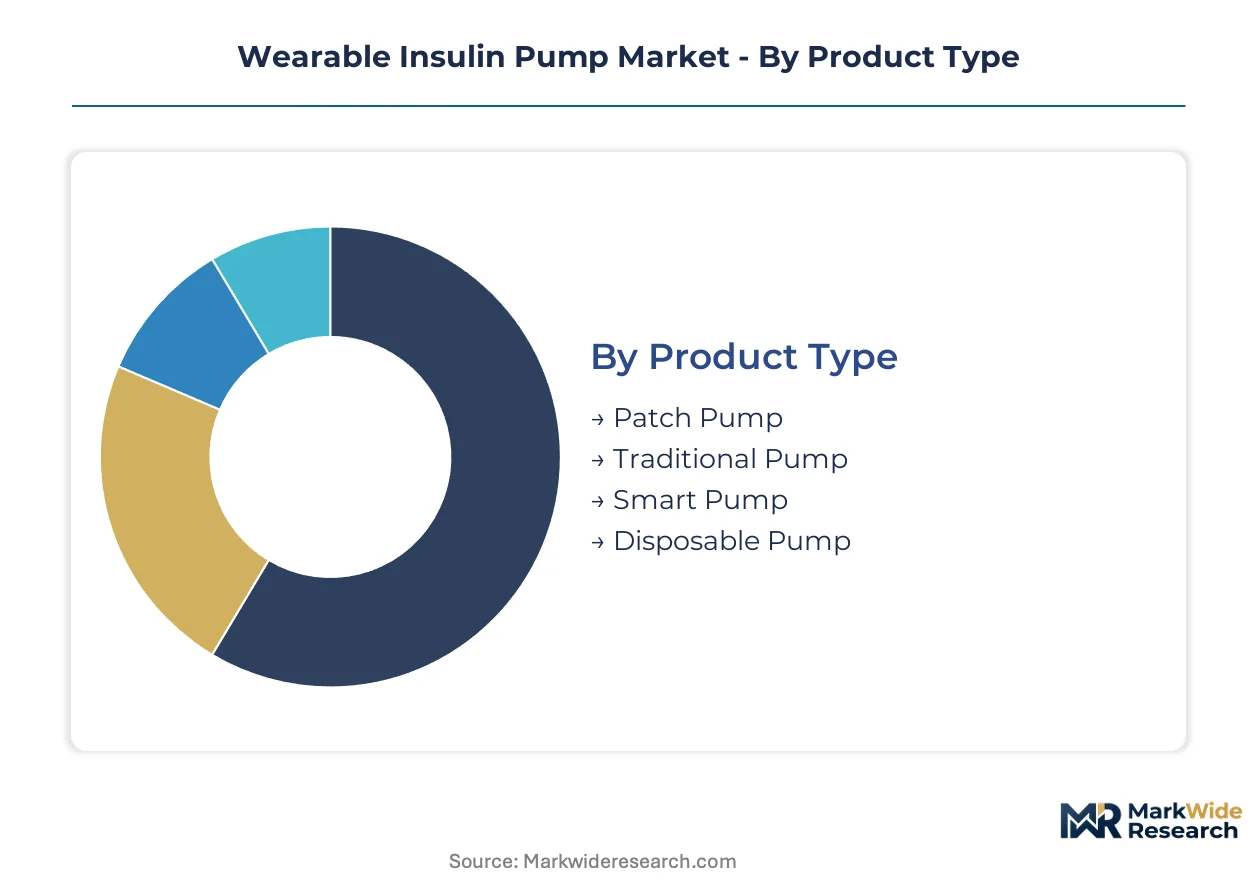
Wearable insulin pump segmentation reflects divergent patient needs across age demographics, reimbursement constraints, and automation readiness. Manufacturers align hardware configurations and software capabilities to specific glycemic management scenarios rather than pursuing universal device platforms.
Product Type:
Mature tubed designs coexist with emerging tube-free formats as patient preference fragments across convenience and familiarity spectra.
- Patch Pump:Disposable, tube-free electromechanical units adhere directly to skin with integrated insulin reservoirs and cannula insertion mechanisms. Pediatric endocrinology practices in the United States and Germany favor these devices for active children and adolescents where tubing snags compromise adherence.
- Smart Pump:Bluetooth-enabled devices with smartphone connectivity and predictive dosing algorithms capture expanding margin pools as payers prioritize automated glycemic outcomes. Adult Type 1 patients in Japan demonstrate strongest uptake where PMDA QMS pathways have clarified for software-integrated devices.
- Traditional Pump:Tethered devices with external tubing and separate infusion sets retain installed base among long-term users resistant to platform migration.
- Disposable Pump:Single-use, prefilled units eliminate maintenance requirements for short-term insulin therapy transitions and travel scenarios.
Patch pumps handle the majority of new patient throughput; smart pumps are gaining share fastest on reimbursement tailwinds for automated delivery.
Technology:
Cost tier stratification separates premium autonomous systems from connectivity-only and basic electronic alternatives.
- Closed-Loop System:Hybrid automated algorithms integrate continuous glucose monitor feeds with predictive insulin dosing, enabling autonomous basal adjustments without patient intervention. FDA 21 CFR 882.5550 human factors validation requirements concentrate development resources among manufacturers with established regulatory infrastructure.
- Bluetooth:Wireless protocol enables smartphone pairing for remote monitoring, dosing alerts, and caregiver notifications. Adult patients managing therapy independently drive volume as iOS and Android health ecosystem integration matures.
- Wi-Fi:Direct cloud connectivity supports clinical dashboard integration and automated data sharing with endocrinology practices for intensive insulin management.
- RFID:Near-field communication facilitates secure patient identification and automated reservoir tracking in hospital-to-home transition protocols.
Bluetooth-enabled devices dominate current shipment volumes; closed-loop systems are climbing the fastest on Medicare coverage expansion.
End User:
Application intensity varies sharply across age cohorts, with pediatric and senior segments presenting distinct adherence and usability challenges.
- Adults:Working-age Type 1 patients between 18 and 64 years constitute the core installed base, balancing glycemic control demands with occupational and lifestyle flexibility requirements. Patch pump adoption concentrates here among physically active users.
- Children:Pediatric patients under 18 require caregiver-mediated dosing oversight and school-based nursing coordination. Tube-free designs reduce stigma and physical interference with sports participation.
- Seniors:Patients over 65 with declining manual dexterity and cognitive load tolerance favor simplified interfaces and automated decision support. Medicare reimbursement parity for closed-loop systems removes cost barriers in this cohort.
- Healthcare Providers:Hospital discharge planning and diabetes education centers procure devices for patient trial periods and training protocols.
Adults account for the largest active user population; seniors are expanding most quickly on demographic aging and reimbursement alignment.
Pricing Model:
Customer type and procurement scale determine access pathway selection between capital purchase and recurring fee structures.
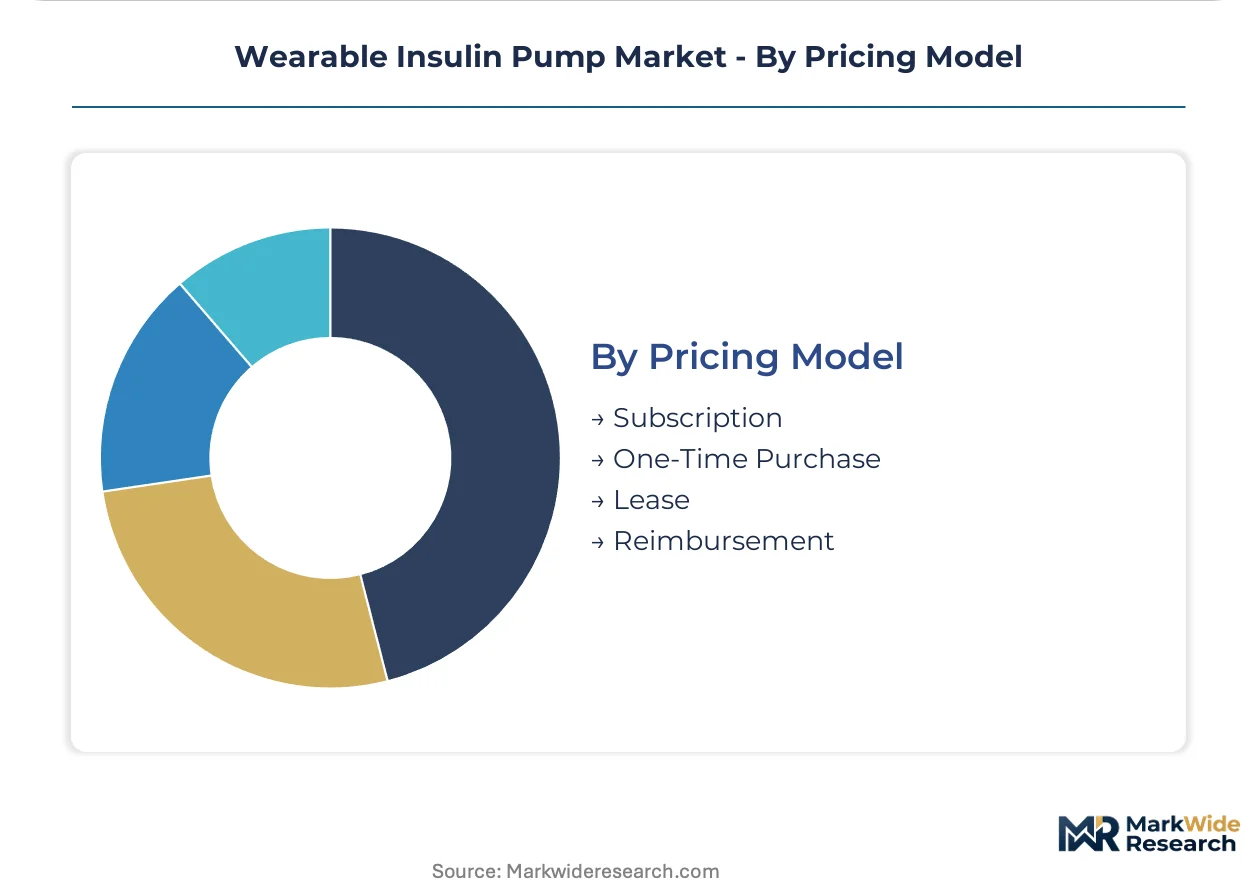
- Subscription:Monthly leasing arrangements reduce upfront patient burden while generating predictable manufacturer revenue streams. United States diabetes centers increasingly favor this model for cash-constrained uninsured populations.
- Reimbursement:Third-party payer coverage for device and supply costs dominates commercial and government insurance channels. Medicare's closed-loop system inclusion has reshaped United States access patterns.
- One-Time Purchase:Capital acquisition of durable pump hardware with separate ongoing supply costs retains preference among patients with high-deductible health plans.
- Lease:Fixed-term rental agreements with maintenance inclusion appeal to patients evaluating platform suitability before long-term commitment.
Reimbursement pathways handle the majority of transaction volume; subscription models are gaining traction fastest among direct-to-patient channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in wearable insulin delivery devices reflect concentrated manufacturing in East Asian MEMS foundries against dominant consumption in Western healthcare systems with mature reimbursement infrastructure. Import dependency for sensor substrates and battery cells creates geographic vulnerability for assembly operations in Germany, the United States, and Japan.
United States
Medicare coverage expansion for closed-loop systems has removed cost barriers for seniors managing Type 1 diabetes outside hospital settings. FDA 21 CFR 882.5550 human factors validation requirements shape product development timelines for manufacturers seeking premarket notification clearance. The Boston-Cambridge corridor hosts concentrated diabetes technology R&D operations alongside major endocrinology research centers.
Germany
Notified bodies under the MDR framework set precedent timelines for CE marking of automated insulin delivery systems that other European regulators reference. The EU AI Act imposes additional clinical evidence requirements on algorithms that autonomously adjust dosing without physician confirmation. Baden-Württemberg's medical technology cluster around Stuttgart maintains specialized MEMS fabrication capabilities for glucose sensor integration.
Japan
Aging demographics and established diabetes management infrastructure create white space for automated delivery systems as PMDA QMS pathways clarify for software-integrated devices. METI industrial policy supports domestic production of advanced medical devices to reduce import dependency for critical healthcare technologies. The Kansai region around Osaka hosts concentrated pharmaceutical and medical device manufacturing operations serving domestic and export markets.
United Kingdom
NHS England reimbursement frameworks increasingly prioritize automated glycemic outcome metrics over hardware specifications in procurement decisions. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating separate compliance obligations for manufacturers seeking market access. The Oxford-Cambridge-London golden triangle anchors diabetes research translation and health technology assessment capabilities.
South Korea
MFDS streamlined approval pathways for software-as-medical-device classifications accelerate market entry for Bluetooth-integrated pump systems. Government health technology procurement programs favor domestic manufacturers in hospital supply contracts, creating protected demand segments. The Seoul Capital Area concentrates electronics manufacturing capabilities that supply MEMS components to global pump assemblers.
Wearable Insulin Pump Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified medical technology conglomerates with manufacturing scale, specialized diabetes device pure-plays with algorithm expertise, and emerging challengers with disposable patch pump platforms. Dominant competitive moves include vertical integration into MEMS sensor supply chains and strategic partnerships with continuous glucose monitor developers to secure algorithm training data access.
Among the established diversified players, Medtronic anchors the tier with broad hospital and retail distribution infrastructure. Insulet Corporation exemplifies the patch pump specialization archetype through its tube-free disposable platform targeting pediatric and active adult adherence challenges. Tandem Diabetes Care occupies a position at the algorithm-intensive end, with closed-loop system integration representing the primary competitive differentiation vector in Medicare-covered segments.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Tandem Diabetes Care |
| SOOIL Development |
| Roche |
| Ypsomed |
| EOFlow |
| Beta Bionics |
| Bigfoot Biomedical |
| Others |
Pricing and Supply Chain Analysis
Single-source MEMS sensor substrate dependency determines both premium-tier margin spreads and supply chain geographic configuration for wearable insulin pump manufacturers. Lithium-ion cell cost volatility feeds directly into disposable patch pump bill-of-materials, compressing mid-tier pricing flexibility while forcing assembly operations toward East Asian battery sourcing corridors.
Pricing Analysis
Hospital procurement committees and diabetes center GPOs anchor subscription-based pricing structures across the United States and Germany. Three-tier pricing structure across premium closed-loop systems, Bluetooth-enabled smart pumps, and traditional tubed devices separates FDA-validated algorithm tiers from connectivity-only and basic electronic alternatives. Pricing pressure stems from Medicare reimbursement parity requirements that compress premium-tier margins. Uninsured cash-pay patients exhibit highest price sensitivity, while Medicare-covered seniors demonstrate lowest sensitivity due to cost-barrier removal.
Supply Chain Analysis
East Asian electronics manufacturing services—concentrated in South Korean MEMS foundries and Chinese battery cell assembly—hold dominant contract manufacturing capacity for pump sensor integration. Final device assembly clusters in Germany, the United States, and Japan, drawing from Taiwanese semiconductor substrates and Japanese precision electromechanical components. Single-source vulnerability in glucose sensor MEMS fabrication creates geographic concentration risk. Distribution runs through hospital supply chains, retail pharmacy networks, and direct-to-patient subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payer consolidation around automated glycemic outcome metrics has shifted purchasing influence from device brand loyalty toward reimbursement-aligned value demonstration. This buyer-power concentration rewards manufacturers with closed-loop algorithm capabilities and punishes hardware-only competitors.
For Market Incumbents: Pre-empt software-as-medical-device classification uncertainty by accelerating FDA 21 CFR 882.5550 premarket notification pathways for algorithm updates. Establish captive supply relationships with East Asian MEMS foundries to defend against sensor substrate allocation constraints. Secure continuous glucose monitor data partnerships to maintain algorithm training data access against emerging entrant disruption. For New Entrants and Emerging Players: Japan's aging demographic concentration and clarifying PMDA QMS pathways for software-integrated devices represent the most penetrable white-space entry point. Pediatric patch pump segments in German outpatient clinics offer secondary penetration opportunity due to tube-free adherence advantages. Pursue subscription leasing channel partnerships with United States diabetes centers to bypass capital-purchase barriers. For Investors and Strategic Acquirers: EU AI Act algorithm evidence requirements reshape the acquisition landscape toward targets with established European post-market surveillance infrastructure. Five-to-ten year viability favors closed-loop system developers with Medicare coverage tailwinds over traditional pump hardware manufacturers. Monitor FDA software-as-medical-device guidance publication cadence as inflection signal for compliance timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Algorithm Development | FDA 21 CFR 882.5550 validation secures Medicare reimbursement access for automated glycemic control systems. |
| MEMS Sensor Supply Agreement | East Asian foundry partnerships reduce single-source vulnerability for continuous glucose monitor integration. |
| Subscription Leasing Channel Launch | Device-as-a-service models bypass capital barriers for uninsured patients and cash-constrained clinics. |
| Bluetooth-Smartphone Platform Integration | iOS and Android ecosystem connectivity enables remote dosing alerts and caregiver monitoring differentiation. |
| Reimbursement Strategy Alignment | Medicare closed-loop system inclusion removes patient cost barriers and concentrates purchasing influence among payers. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR CE marking registries, and CMS Medicare coverage determinations preceded structured interviews with biomedical engineers, hospital GPO contract managers, pediatric endocrinologists, and diabetes center procurement leads. Secondary validation drew from PMDA QMS guidance documents, Japanese medical device trade statistics, and German notified body precedent timelines. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Fixed assumptions held reimbursement pathway expansion and MEMS sensor miniaturization trajectories constant across the projection horizon, while varying closed-loop algorithm adoption rates and EU AI Act implementation timelines. Segmentation dimensions modeled included product type, technology tier, end-user age cohort, and pricing model access pathway. CAGRs derived from patient population growth, replacement cycle compression, and premium-tier mix shift dynamics. Industry-specific inputs encompassed Medicare coverage expansion velocity and PMDA software-integrated device pathway clarification.
Practitioners should monitor FDA software-as-medical-device guidance evolution, EU AI Act delegated act publication, and East Asian MEMS foundry capacity utilization for early signals of forecast revision necessity. Quarterly review of Medicare closed-loop system claim volumes, German notified body CE marking queue lengths, and lithium-ion cell commodity price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
GCC Implantable Medical Devices Market
Medical Devices
Cytology Brush Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Capnography Devices Market
Medical Devices
Tourniquet Systems Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Venturi Mask Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Recanalization System Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Alpha Emitter Market
Medical Devices
Vaginal Specula Market