
 Isothermal Bags and Containers Market | 2026-2036
Isothermal Bags and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Isothermal Bags and Containers Market Intelligence
The shift from single-source procurement to multi-vendor strategies for specialized thermal packaging is decoupling buyer loyalty from any single supplier. Pelican BioThermal LLC specializes in high-performance, reusable containers for the demanding life sciences sector. Sonoco Products Company leverages its extensive material science and manufacturing scale to offer a broad portfolio. VA-Q-tec AG differentiates with its advanced vacuum insulation panel technology for long-duration shipments.
Isothermal bags and containers are engineered enclosures designed to maintain a stable internal temperature for a specified duration. They utilize insulating materials like polyurethane foam, expanded polystyrene, or vacuum insulation panels to minimize thermal transfer from the external environment. Pharmaceutical transport applications command the highest value due to stringent validation requirements. Within materials, polyurethane and vacuum panels define the premium segment, while PEVA and aluminum foil are common in lower-cost, single-use food delivery bags.
Compliance with standards from the US FDA and the EU's EMA, particularly Good Distribution Practice guidelines, is non-negotiable for pharmaceutical logistics. The WHO's Performance, Quality and Safety (PQS) program for vaccine cold chain equipment also sets global performance benchmarks. The critical decision for end-users now revolves around balancing the total cost of ownership for reusable containers against the logistical simplicity of single-use systems.
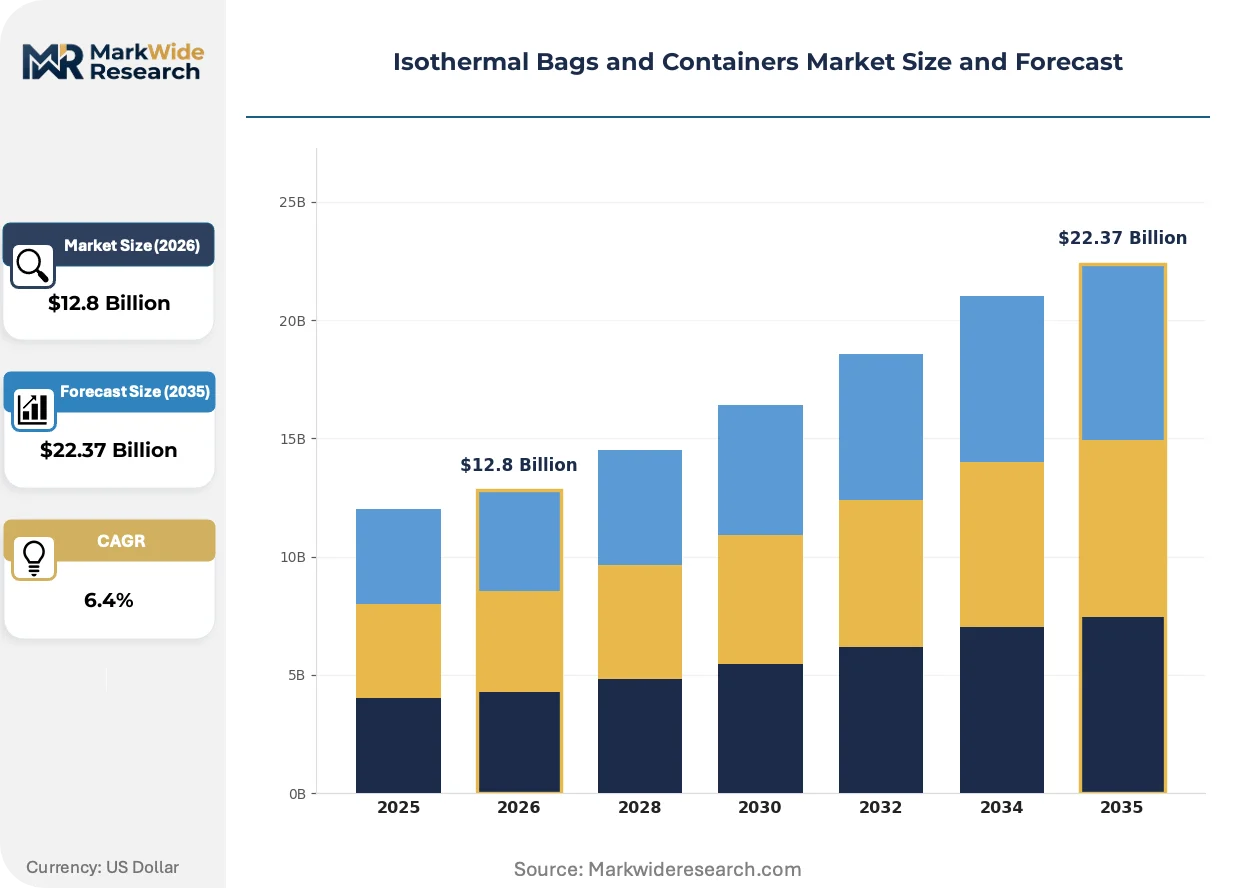
Market Dynamics
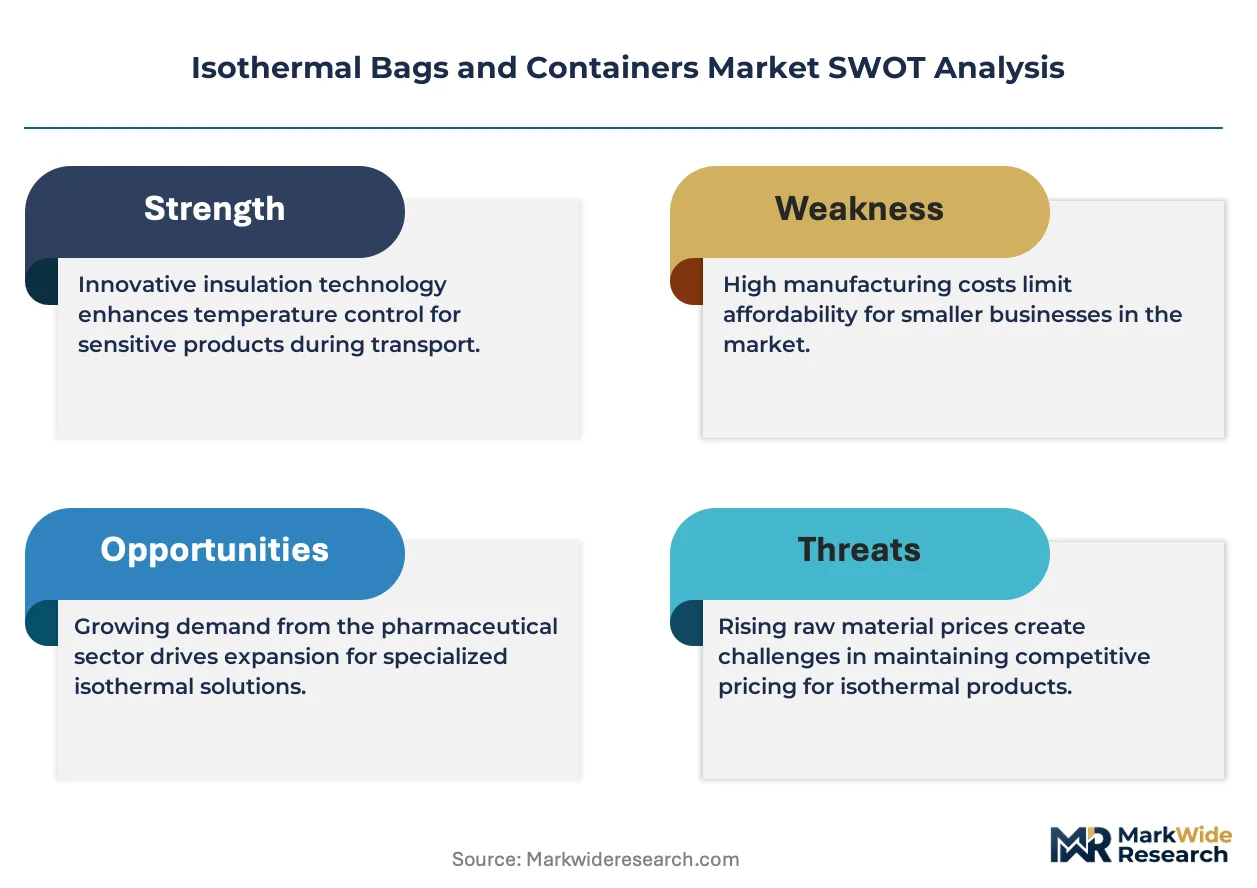
The central tension in the isothermal packaging market is the divergence between high-value pharmaceutical logistics and volume-driven food delivery. Stringent regulatory mandates from bodies like the EMA are forcing an upgrade cycle towards validated, reusable systems, creating a distinct premium tier.
Growth Catalysts
- Biologic Drug Expansion:The growing pipeline of temperature-sensitive biologics, including cell and gene therapies, necessitates advanced cold chain solutions that can guarantee product integrity throughout transit, directly driving demand for validated containers.
- Regulatory Harmonization:Efforts by organizations like the WHO through its PQS program to standardize vaccine cold chain equipment performance create a clear demand signal for compliant, high-performance isothermal packaging in global health initiatives.
- Food E-commerce Growth:The expansion of online grocery and meal-kit delivery services, particularly in urban centers across North America and Europe, fuels high-volume demand for lower-cost, often single-use, thermal bags and liners.
Market Restraints
- High Initial Investment:The significant capital cost of acquiring fleets of high-performance reusable containers, particularly those using vacuum insulation panels, acts as a barrier to entry for smaller logistics providers and pharmaceutical companies.
- Reverse Logistics Complexity:Managing the return, cleaning, inspection, and requalification of reusable thermal containers is operationally complex and costly, especially for international shipping lanes, limiting their economic viability for some routes.
- Material Cost Volatility:The pricing of key raw materials like polyurethane and polymers is subject to fluctuations in global petrochemical markets, creating margin pressure for manufacturers of both single-use and reusable containers.
Strategic Opportunities
- Direct-to-Patient Logistics:The rise of decentralized clinical trials and direct-to-patient delivery of specialty pharmaceuticals creates an opportunity for smaller, patient-centric validated packaging solutions that ensure temperature stability to the last mile.
- Smart Packaging Integration:Embedding IoT sensors for real-time temperature, humidity, and location tracking within containers offers a path to creating value-added data services, moving beyond simple hardware sales to subscription-based monitoring.
- Sustainable Materials Development:There is significant white space for developing and commercializing high-performance thermal insulation materials derived from sustainable sources, such as plant fibers or recycled polymers, to meet corporate ESG goals.
Industry Challenges
- Multi-Standard Compliance:Validating a single packaging solution to meet the distinct and sometimes conflicting performance and documentation requirements of the US FDA, EU's EMA, and Japan's PMDA is a time-consuming and expensive challenge for vendors.
- End-of-Life Management:Establishing scalable and economically viable recycling programs for single-use containers, especially those made of expanded polystyrene (EPS), remains a significant operational and public relations challenge for the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isothermal Bags and Containers Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Bags, Vacuum Containers, Thermal Boxes, Cooler Bags, Refrigerated Totes Application: Food Delivery, Pharmaceutical Transport, Outdoor Activities, Laboratory Samples, Cold Chain Logistics End User: Food Service Providers, Medical Facilities, Research Institutes, Logistics Companies, Retail Chains Material: PEVA, Aluminum Foil, Nylon, Polyester, Polyurethane, EVA Foam |
| Companies Covered | Sonoco Products Company, Cryopak Industries, Inc., Thermo Fisher Scientific Inc., VA-Q-tec AG, Cold Chain Technologies, Inc., Pelican BioThermal LLC, Sealed Air Corporation, Softbox Systems Ltd, Berry Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isothermal Bags and Containers Market Strategic Shifts & Innovations
The market is being redefined by the convergence of material science and data analytics. This is creating a clear split between intelligent, reusable systems for high-value payloads and optimized, sustainable solutions for single-use applications.
Advanced Insulation Systems
Advanced phase change materials (PCMs) and vacuum insulation panels (VIPs) provide highly stable thermal protection with minimal bulk. Pharmaceutical logistics providers are adopting these technologies to safeguard sensitive biologics and reduce payload weight. The ability to combine interchangeable PCM components with configurable container sizes is modularizing thermal performance, allowing shippers to tailor solutions to specific transit durations and temperature requirements.
Sustainability-Driven Regulation
Europe's proposed Packaging and Packaging Waste Regulation (PPWR) is creating significant pressure to improve the circularity of thermal packaging. The regulation's targets for recyclability and use of recycled content are forcing a design shift away from multi-material laminates and virgin plastics. The food delivery and consumer goods segments are most impacted, spurring innovation in mono-material insulation and certified compostable thermal liners.
Service Model Transformation
A shift from outright purchase to leasing and "cold chain-as-a-service" models is altering procurement dynamics. This approach replaces large capital expenditures for end-users with operational fees that bundle container provision, management, and performance qualification. This service-based model is most visible in the global clinical trials logistics sector, where operational flexibility and guaranteed compliance are critical success factors.
Isothermal Bags and Containers Market Segmentation
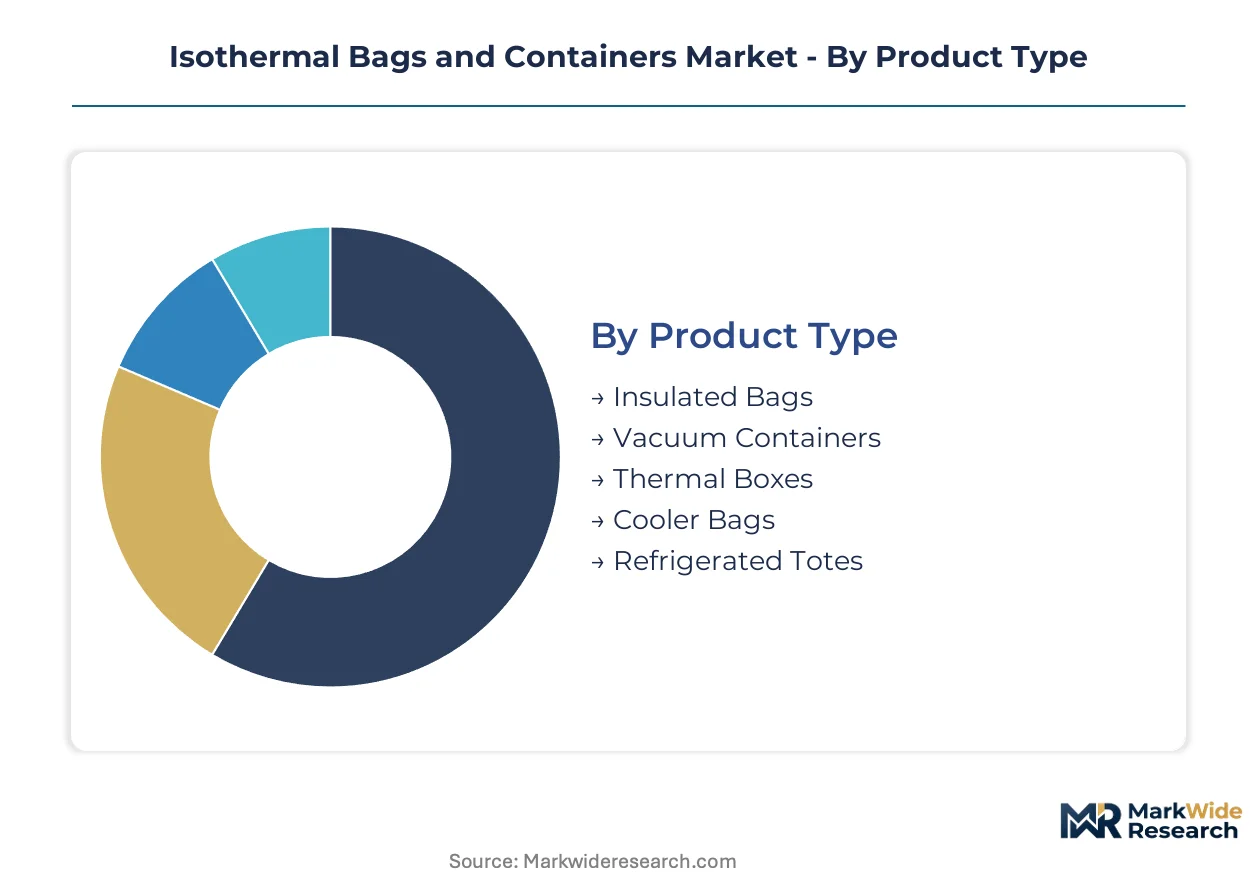
Understanding the market for isothermal bags and containers requires a granular breakdown of product types, applications, end-users, and materials. This segmentation reveals distinct value propositions and competitive landscapes across various industry needs, highlighting where specialized solutions are essential.
Product Type:
The capital intensity of manufacturing varies significantly across product types, with advanced vacuum insulation systems requiring substantial investment in specialized production lines.
- Vacuum Containers:These products feature double-walled construction with a vacuum space, providing superior thermal insulation for extended durations. Demand concentrates in pharmaceutical transport across Europe and North America, driven by the need to protect high-value biologics and cell therapies.
- Thermal Boxes:Engineered for robust protection, these rigid containers often integrate advanced insulation materials like polyurethane foam or VIPs. Logistics companies in Germany and South Korea extensively use thermal boxes for cold chain distribution of sensitive medical supplies.
- Insulated Bags:These flexible solutions typically use foam or fiber insulation layers, offering a balance of performance and portability. Food delivery services and direct-to-patient pharmaceutical shipments commonly utilize insulated bags.
- Cooler Bags:Designed for shorter durations and less stringent temperature control, cooler bags often feature soft-sided construction and gel pack inserts. Outdoor activities and consumer retail channels drive significant volume for these products.
- Refrigerated Totes:These larger, often wheeled, containers integrate active or passive cooling systems for precise temperature maintenance over longer periods. Specialized cold chain logistics for large-scale vaccine distribution rely on refrigerated totes.
Insulated Bags absorb the bulk of installed capacity; Vacuum Containers are expanding most quickly.
Application:
Applications for isothermal packaging span a wide spectrum, each presenting unique performance requirements and regulatory hurdles.
- Pharmaceutical Transport:This segment demands highly validated, precise temperature control for drugs, vaccines, and biologics, adhering to stringent guidelines from the US FDA and EU's EMA. Compliance with Good Distribution Practices is non-negotiable for pharmaceutical logistics.
- Food Delivery:This high-volume application requires cost-effective solutions to maintain food temperature for short durations, primarily for online grocery and meal-kit services. Consumer e-commerce platforms in North America and Europe drive this demand.
- Cold Chain Logistics:Encompassing a broad range of temperature-sensitive goods beyond pharmaceuticals, this application focuses on maintaining product integrity throughout the supply chain. Global trade of perishable goods and chemicals relies heavily on robust cold chain solutions.
- Laboratory Samples:Transporting biological samples, reagents, and diagnostic kits requires reliable temperature stability to preserve sample integrity. Research institutes and diagnostic laboratories utilize specialized containers for these critical shipments.
- Outdoor Activities:This consumer-focused segment requires durable, portable solutions for keeping food and beverages cool during recreational use. Retail sales of consumer goods drive this market.
Pharmaceutical Transport commands the highest average selling prices; Food Delivery represents the largest volume segment.
End User:
Different end-user groups prioritize distinct characteristics in isothermal packaging, from regulatory compliance to cost-efficiency and reusability.
- Medical Facilities:Hospitals, clinics, and pharmacies require validated containers for internal transport of medicines, blood products, and samples. Compliance with health authority guidelines is paramount for these users.
- Logistics Companies:Third-party logistics providers specialize in temperature-controlled shipping for various industries, demanding versatile and scalable isothermal solutions. Global freight forwarders and regional carriers are key customers.
- Food Service Providers:Restaurants, catering businesses, and food retailers utilize insulated bags and containers for maintaining food quality during delivery and storage. Urban centers in North America and Europe show high concentration of these users.
- Research Institutes:Universities, biotech firms, and government labs need specialized packaging for transporting sensitive biological and chemical samples. Precision temperature control is critical for research integrity.
- Retail Chains:Supermarkets and convenience stores use isothermal packaging for in-store cold chain management and home delivery services. E-commerce expansion drives demand for these solutions in the retail sector.
Logistics Companies are the largest purchasers by volume; Medical Facilities drive demand for premium, validated systems.
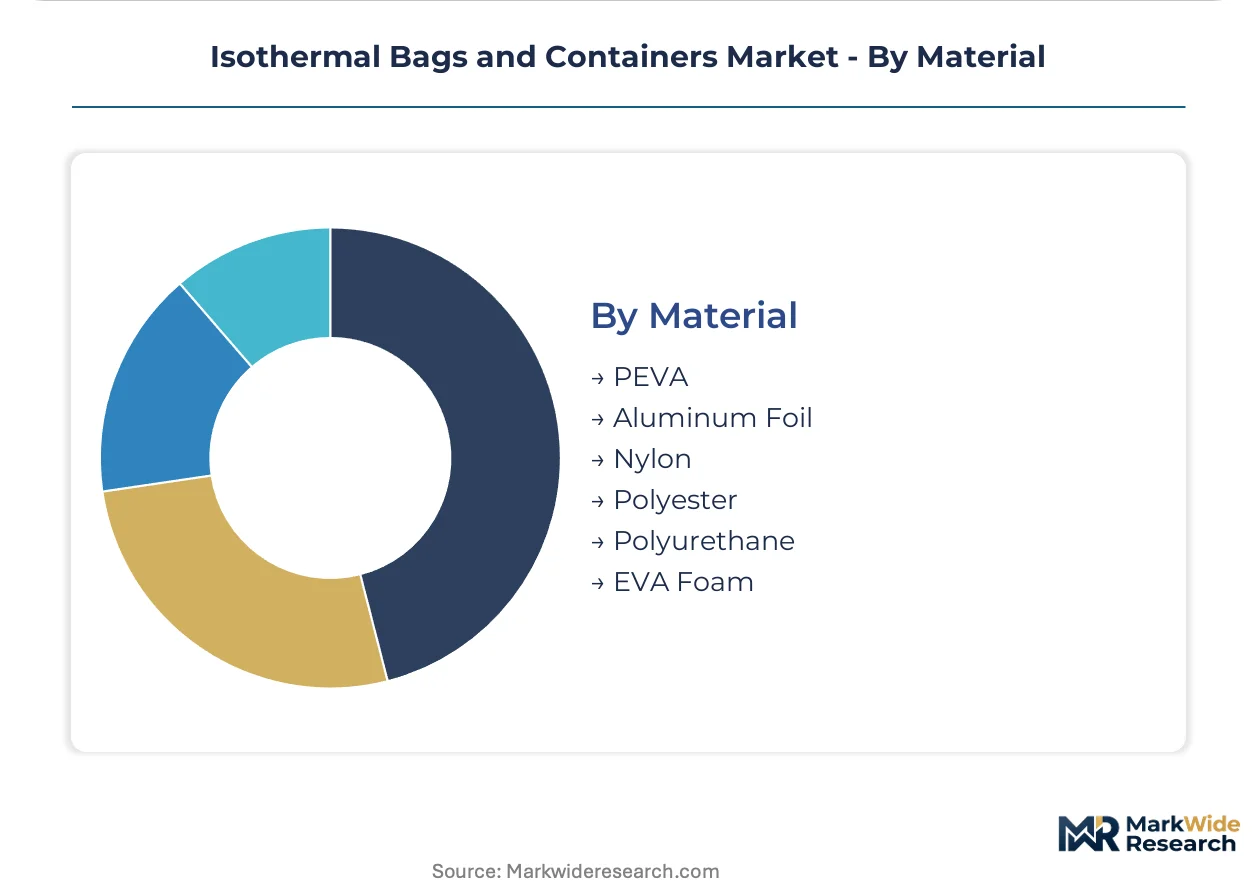
Material:
Material selection dictates the thermal performance, cost, and reusability of isothermal packaging, influencing its suitability for various applications.
- Polyurethane:This closed-cell foam offers excellent insulation properties, commonly used in high-performance thermal boxes and reusable containers. Its density and R-value make it a preferred choice for pharmaceutical cold chain applications requiring precise temperature control.
- EVA Foam:Ethylene-vinyl acetate foam provides good cushioning and insulation at a moderate cost, often found in cooler bags and insulated liners. Its flexibility and lightweight nature make it suitable for consumer goods and less stringent transport needs.
- PEVA:Polyethylene vinyl acetate is a non-chlorinated plastic often used as a liner in insulated bags due to its water resistance and flexibility. This material is common in lower-cost, single-use food delivery bags.
- Aluminum Foil:Frequently used as a reflective layer in multi-layer insulation systems, aluminum foil helps to reduce radiant heat transfer. It is a common component in disposable thermal liners and food delivery bags.
- Nylon:A durable and water-resistant fabric, nylon is often used for the outer shell of insulated bags and soft-sided coolers. Its strength contributes to the longevity of reusable packaging.
- Polyester:Similar to nylon, polyester is a common fabric for the exterior of thermal bags, offering good abrasion resistance and printability. It is widely adopted in both consumer and commercial insulated packaging.
Polyurethane is the material of choice for high-value applications; PEVA sees the most widespread use in volume-driven segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' extensive petrochemical infrastructure anchors the global supply of key polymers for isothermal packaging, influencing regional market dynamics. Demand for advanced solutions is concentrated in established pharmaceutical manufacturing hubs. Regulatory mandates and e-commerce growth shape regional adoption patterns.
United States
Pharmaceutical transport and direct-to-patient logistics drive significant demand for validated isothermal solutions. US FDA guidelines enforce strict temperature control requirements for medical products. Biotech clusters in Boston and California are expanding their use of advanced cold chain solutions for sensitive biologics.
Germany
Germany's established pharmaceutical manufacturing sector and biologics expansion necessitate high-performance thermal packaging. The EU's Good Distribution Practice (GDP) guidelines mandate stringent temperature control for drug distribution. Pharmaceutical hubs in Bavaria and North Rhine-Westphalia extensively use thermal boxes for cold chain integrity.
South Korea
South Korea's emerging biopharma clusters and growing medical device industry require robust cold chain logistics. The MFDS (Ministry of Food and Drug Safety) standards guide the transport of sensitive medical supplies. Biopharma R&D centers in Incheon and Seoul are expanding adoption of advanced containers for clinical trials.
Ireland
Ireland's significant pharmaceutical manufacturing base, particularly for biologics, fuels demand for specialized isothermal packaging for export. The EMA's Good Distribution Practice (GDP) regulations are critical for ensuring product integrity. Pharmaceutical manufacturing sites in Dublin and Cork require validated reusable systems for global distribution routes.
China
China's rapid e-commerce growth and expanding pharmaceutical market drive high-volume demand across both food delivery and medical applications. The NMPA (National Medical Products Administration) regulations govern pharmaceutical cold chain logistics. Major urban centers like Shanghai and Beijing increasingly utilize insulated bags for last-mile delivery services.
Isothermal Bags and Containers Market Key Industry Players
Global majors compete with regional champions across product portfolio breadth and technological specialization. The market structure is tiered, with high-performance specialists serving niche segments and diversified material science companies addressing broader needs. Strategic archetypes include innovation-driven technology providers, scale-focused manufacturing entities, and service-oriented logistics integrators. Competitive moves often involve portfolio diversification and strategic partnerships to expand geographic reach.
On the premium-tier vector, Pelican BioThermal LLC exemplifies specialization in high-performance, reusable containers for life sciences. VA-Q-tec AG, a German AG, differentiates through advanced vacuum insulation panel technology, enabling long-duration shipments. Sonoco Products Company, an Inc. entity, occupies a broad portfolio position, leveraging extensive material science and manufacturing scale across diverse segments.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Cryopak Industries, Inc. |
| Thermo Fisher Scientific Inc. |
| VA-Q-tec AG |
| Cold Chain Technologies, Inc. |
| Pelican BioThermal LLC |
| Sealed Air Corporation |
| Softbox Systems Ltd |
| Berry Global, Inc. |
Cost & Logistics Intelligence
Polyurethane and vacuum insulation panel costs influence the premium segment's pricing for high-performance containers, impacting pharmaceutical logistics. Lower-cost materials like PEVA drive volume-based pricing for food delivery bags.
Pricing Analysis
Warranty and service bundling often differentiate premium-tier offerings for validated reusable systems in pharmaceutical transport. The dominant pricing structure is contract-based long-term offtake for high-value applications, while per-unit transactional models prevail in food delivery. Price differentiation arises from certification level, particularly for US FDA and EU EMA compliance, and the level of after-sales support. Cost compression in the food delivery segment is intensifying due to high volume competition. Medical facilities exhibit the least price sensitivity, prioritizing validated performance, whereas food service providers are highly price-sensitive.
Supply Chain Analysis
Certification and qualification gating by regulatory bodies like the US FDA significantly shapes the supply chain for pharmaceutical-grade containers. Supply concentrates in established manufacturing hubs like Germany and the United States, which leverage extensive petrochemical infrastructure. The supply chain relies on polyurethane, polymers, and aluminum foil. Commodity price volatility for these raw materials presents a structural supply chain risk. Distribution runs through specialized logistics companies and direct sales from manufacturers to large end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The isothermal bags and containers market is becoming a vertical-integration race, as players pursue upstream material science innovation to control performance and cost. Downstream, service-based models extend control over the entire cold chain.
For Market Incumbents: Cement market leadership through strategic acquisitions of niche technology providers, particularly those specializing in advanced vacuum insulation panels. Diversify product portfolios to offer both high-performance reusable systems and optimized single-use solutions, mitigating the threat from sustainable material innovators. Invest in advanced analytics platforms for IoT-enabled smart packaging, leveraging data services as a key lever for customer retention against emerging competitors. Expand manufacturing capacity in emerging biopharma regions like South Korea.
For New Entrants and Emerging Players: Europe's proposed Packaging and Packaging Waste Regulation (PPWR) opens a window for new entrants focused on sustainable materials and circular economy models. Target the food delivery and direct-to-patient segments with certified compostable thermal liners and mono-material insulation solutions. The most penetrable segment is lower-cost, high-volume single-use applications. A service-based subscription model for smaller, patient-centric validated packaging offers a distinct go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized technology providers in Europe, particularly those with patented vacuum insulation panel technology. The long-term viability of advanced cold chain solutions remains strong over the next five to ten years due to biologics expansion. Target acquisition archetypes include companies with proprietary sustainable insulation materials or advanced IoT integration capabilities. The signal to watch is the adoption rate of "cold chain-as-a-service" models, indicating a shift in procurement dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Sustainable Material R&D | Develop high-performance thermal insulation from plant fibers, meeting corporate ESG goals and regulatory demands. |
| Expand Cold Chain-as-a-Service Offerings | Shift procurement from capital expenditure to operational fees, bundling container management and performance qualification. |
| Integrate IoT for Real-time Monitoring | Provide value-added data services for temperature and location tracking, enhancing product integrity for sensitive biologics. |
| Global Regulatory Compliance Certification | Validate packaging solutions for US FDA, EU EMA, and PMDA standards, unlocking access to multiple pharmaceutical markets. |
| Optimize Reverse Logistics Infrastructure | Improve efficiency and cost-effectiveness of reusable container return, cleaning, and requalification processes. |
Research Approach
Multi-period observation of market growth rates and regulatory changes anchored the trend analysis, supplemented by interviews with logistics managers, pharmaceutical procurement leads, and material science engineers. Secondary validation utilized US FDA guidelines, EU EMA documents, and WHO PQS program reports. Stakeholder insights from packaging manufacturers and food service providers informed market dynamics. A bottom-up data aggregation approach combined with top-down market sizing ensured robust validation.
An input-output matrix framework modeled market dynamics across the analysis window, considering product types, applications, end-users, and materials. Segmentation dimensions included insulation technology, temperature range requirements, and regional regulatory compliance. Compound annual growth rates were derived from historical data analysis and projected demand drivers. Biologic drug pipeline expansion and e-commerce growth served as key industry-specific forecast inputs throughout the modeling period.
The model assumes a particular technology adoption path; alternative pathways for sustainable insulation materials would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Geopolitical events impacting global supply chains represent a specific risk factor. A model refresh is warranted upon material change in global trade policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Foam Tube Mailer Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Global Polypropylene Woven Bags and Sacks Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Octabin Market