
 Inclusion Bags Market | 2026-2036
Inclusion Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Inclusion Bags Market Outlook
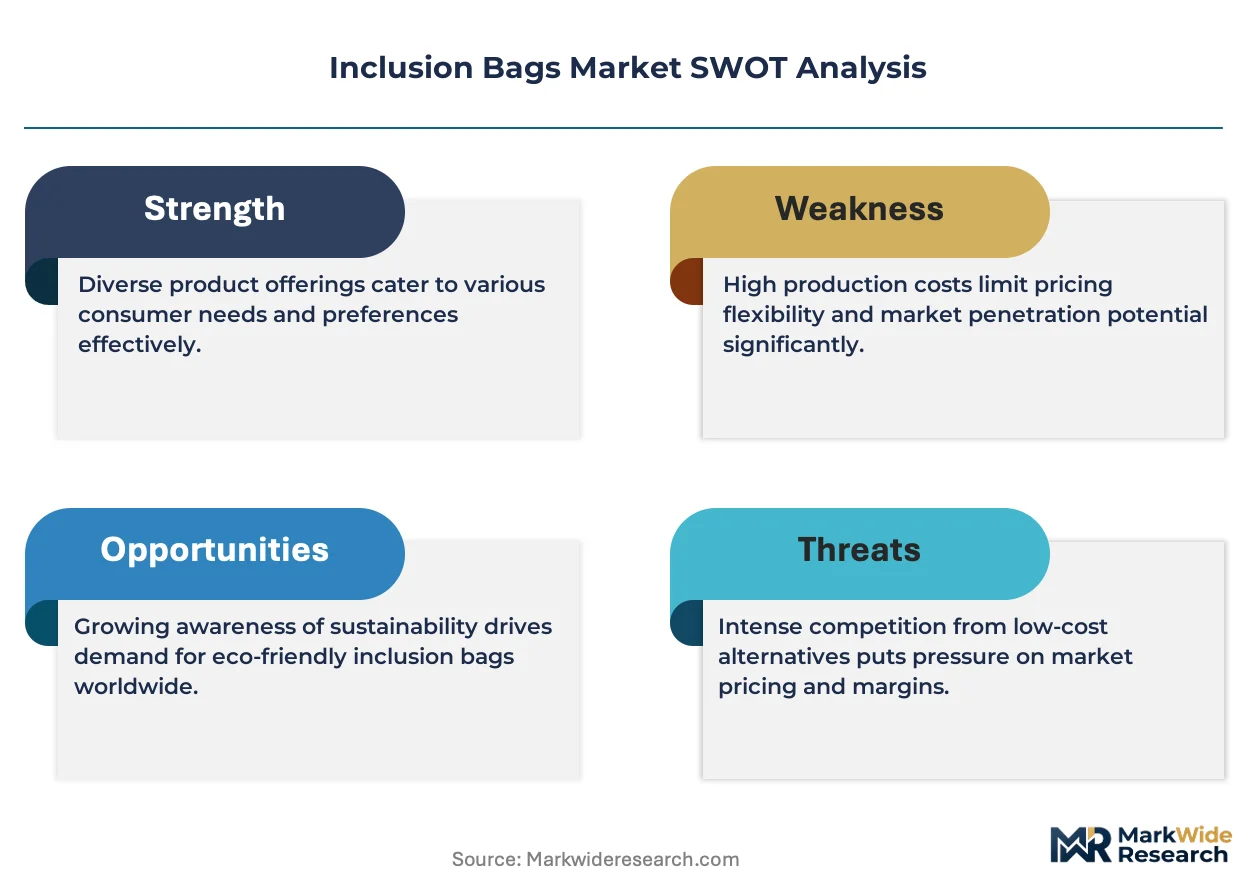
Shortages of polymer chemists and sustainable-material engineers is unwinding capacity expansion timelines across European and North American manufacturing bases. Amcor plc leverages its vertical integration into resin sourcing to sustain margin stability despite feedstock volatility. Mondi Group anchors its competitive stance through fiber-based innovation pipelines that reduce plastic dependency. Berry Global competes by dominating North American retail channel partnerships with scale manufacturing of certified compostable lines.
Inclusion bags are multi-layer or single-ply containers engineered from polypropylene, cotton, jute, or polyester substrates, typically rated between 30–150 microns thickness, designed to enclose promotional materials, product samples, or retail merchandise within primary packaging or direct-to-consumer shipments. Their commercial purpose centers on brand visibility, product protection, and compliance with retailer packaging mandates. Biodegradable bag formats are capturing the fastest expansion as grocery chains face Scope 3 emission targets, while heavy-duty polypropylene variants retain the largest margin pool due to industrial reuse cycles. Cotton and jute material segments are gaining traction among non-profits seeking natural-fiber credentials, though polypropylene still occupies the volume leadership position across retail outlet and wholesale distribution channels.
The EU Green Deal and REACH frameworks in Europe enforce recyclability thresholds and restricted substance lists that reshape material selection for inclusion bag producers seeking continental market access. FDA food-contact regulations in the United States govern barrier properties for bags holding consumable samples, while India's BIS certification requirements for plastic products create separate compliance pathways for exporters. Stakeholders must monitor evolving extended producer responsibility schemes and bio-based content verification standards to secure long-term supply contracts with tier-one retail buyers.
Market Dynamics
Retailer Scope 3 emission mandates are compressing material selection timelines and forcing rapid substrate transitions across the inclusion bags value chain. This structural pressure is accelerating certification requirements and reshaping supplier qualification protocols faster than production capacity can adapt.
Growth Catalysts
- EU Green Deal packaging mandates:Grocery chains across Germany, France, and Italy face binding recyclability thresholds that prioritize certified compostable inclusion bags in promotional material distribution.
- FDA food-contact barrier standards:CPG brands shipping consumable samples require compliant multi-layer structures, expanding addressable demand for specialized inclusion bag formats in North American direct-to-consumer channels.
- Polypropylene reuse cycles:Industrial logistics operators in the United States and Germany are extending bag lifespans through closed-loop collection systems, sustaining volume demand for heavy-duty woven variants.
Market Restraints
- Feedstock volatility in propylene monomer:European resin markets experience price swings that compress margin stability for extrusion-based inclusion bag manufacturers dependent on petrochemical inputs.
- REACH restricted substance compliance:ECHA substance-of-very-high-concern listings force reformulation of certain plasticizers and colorants, extending R&D timelines and qualification costs.
- Natural fiber substitution limitations:Cotton and jute alternatives face moisture barrier deficiencies that prevent full displacement of synthetic substrates in food-contact and high-humidity applications.
Strategic Opportunities
- India BIS certification pathway:Exporters establishing compliant manufacturing footprints can access rapidly modernizing retail infrastructure in Mumbai, Delhi, and Bangalore as organized grocery expands.
- QR-embedded smart packaging convergence:Integration of printed electronics with inclusion bags enables traceability and consumer engagement layers that command premium positioning in beauty and pharmaceutical sampling.
- Extended producer responsibility schemes:France and Italy's advancing EPR frameworks create first-mover advantages for producers offering take-back and recycling infrastructure bundled with bag supply contracts.
Industry Challenges
- Sustainable-material engineer scarcity:European and North American manufacturing bases face recruitment bottlenecks for polymer chemists capable of formulating bio-based barrier films at commercial scale.
- Multi-certification timeline compression:Simultaneous pursuit of OK Compost, FSC chain-of-custody, and retailer-specific audits strains quality assurance bandwidth and delays contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inclusion Bags Market |
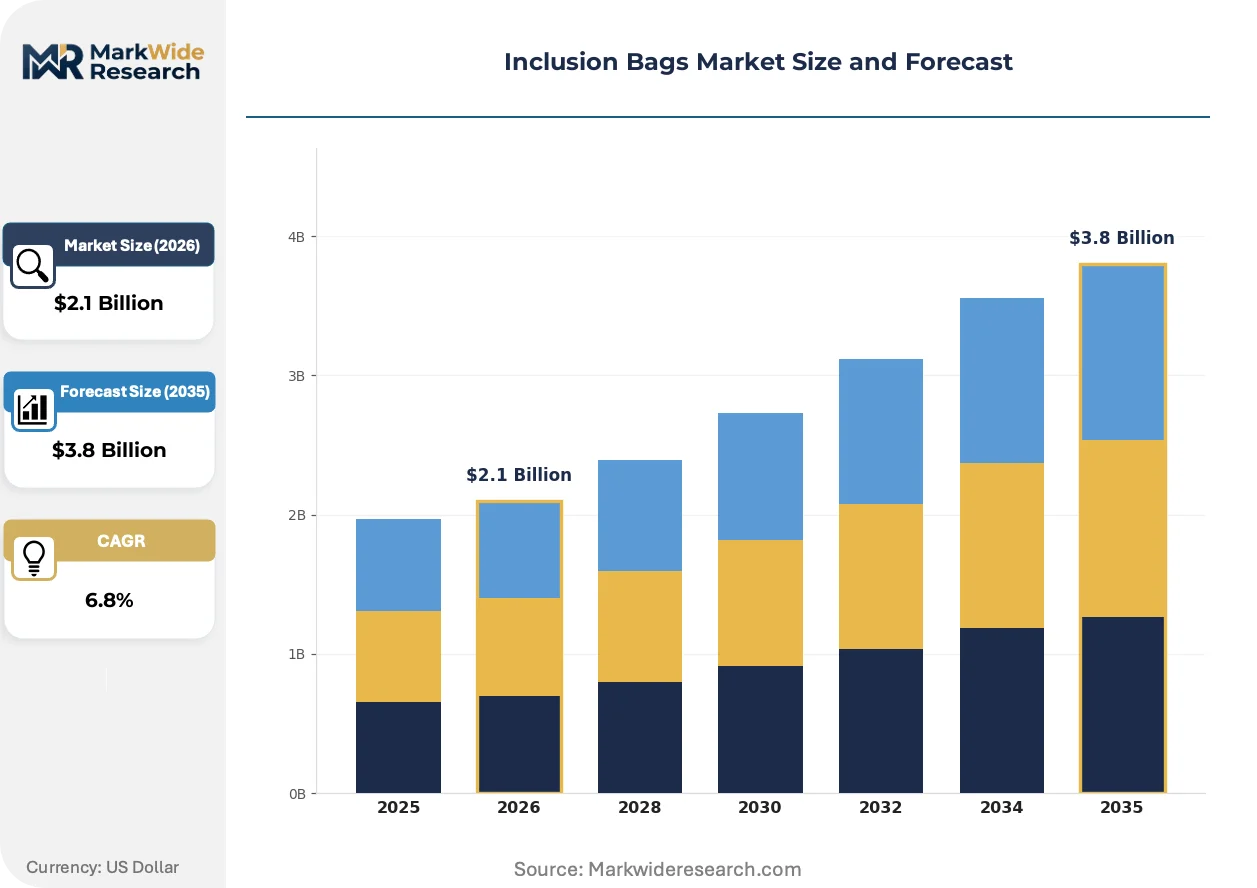
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Bags, Biodegradable Bags, Disposable Bags, Heavy-Duty Bags Material: Polypropylene, Cotton, Jute, Polyester End User: Retail Stores, Online Retailers, Grocery Chains, Non-Profits Distribution Channel: Online Sales, Retail Outlets, Wholesale, Direct Sales |
| Companies Covered | Amcor plc, Mondi Group, Berry Global, Inc., Sealed Air Corporation, Sonoco Products Company, Smurfit Kappa Group, J. Drasner & Co. Inc., Tex-Trude, Aalmir Plastic Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inclusion Bags Market Strategic Shifts
Material science advances and regulatory sequencing are compressing development cycles while fragmenting supplier tiers between specialized bio-based innovators and incumbent synthetic producers. This tension is reshaping competitive positioning across substrate categories.
Water-based barrier coatings are miniaturizing the functional thickness requirements for moisture and oxygen protection in inclusion bags. European pharmaceutical and nutraceutical samplers are adopting these coatings at accelerating pace to meet EU Green Deal recyclability targets. This technology is miniaturizing the multi-layer complexity historically required for shelf-stable sample protection, enabling mono-material structures that simplify end-of-life sorting.
REACH authorization requirements for persistent organic pollutants are tightening impurity thresholds in recycled polymer feedstocks. German and French inclusion bag producers face reformulation costs or sourcing switches to virgin-certified bio-based alternatives. Food-contact sampling applications in these markets are most affected, with brands accelerating supplier audits to preempt non-compliance exposure.
Direct-to-consumer brand sampling programs are consolidating procurement under sustainability scorecard systems that weight lifecycle emissions above unit cost. Beauty and wellness verticals in the United States and United Kingdom are replacing transactional spot-buying with multi-year framework agreements tied to verified carbon footprint reductions. This behavior concentrates volume among qualified suppliers capable of audited chain-of-custody documentation.
Inclusion Bags Market Segmentation
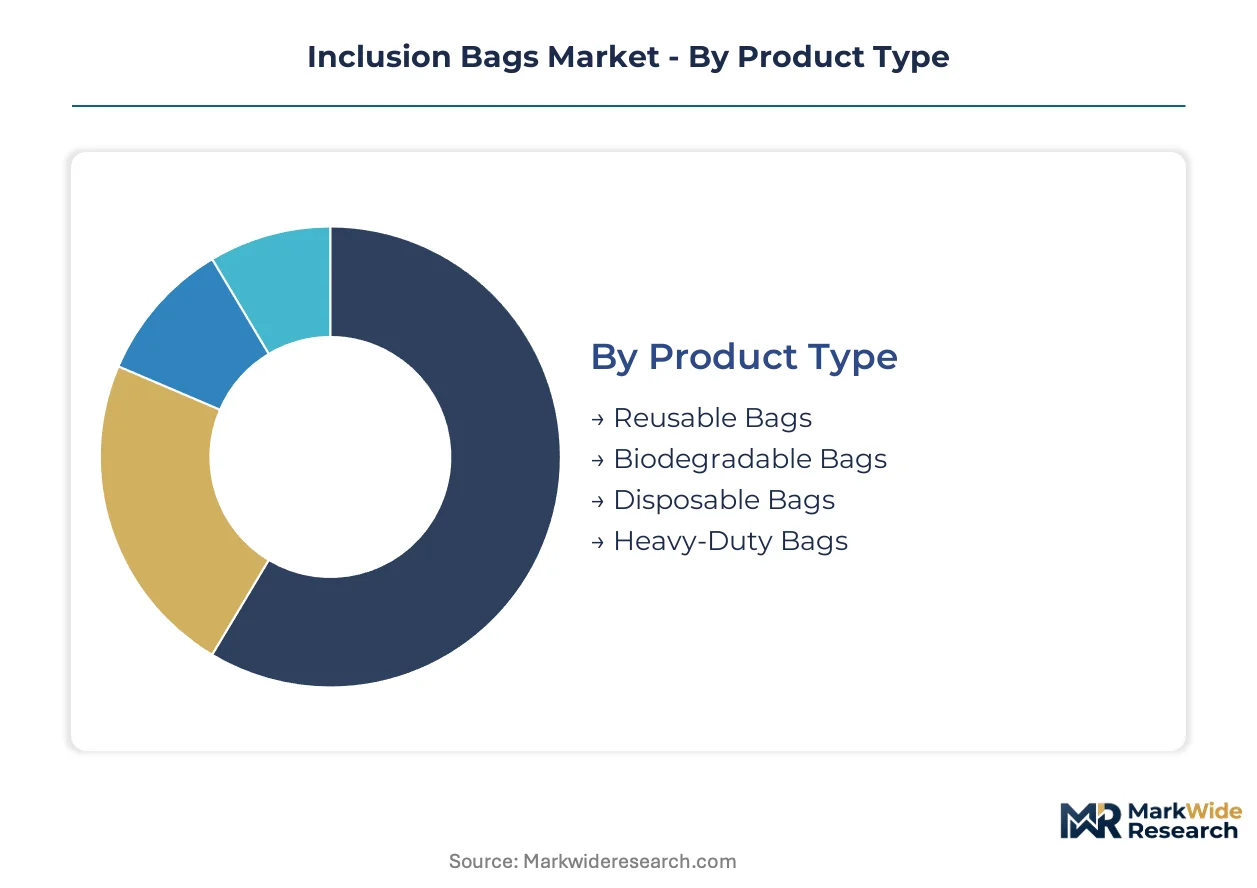
Segmentation in inclusion bags reveals how regulatory pressure fragments demand across substrate technologies and procurement channels. Buyers now sort suppliers by certification tier rather than unit cost alone, reshaping competitive dynamics within each category.
Product Type:
REACH authorization thresholds and EU Green Deal recyclability mandates create divergent compliance burdens across format categories, with certified compostable lines commanding procurement priority in German and French grocery channels.
- Reusable Bags:Woven polypropylene constructions rated for 50+ use cycles dominate industrial logistics applications in Germany and the United States. Closed-loop collection systems at Amazon fulfillment centers and Rewe distribution hubs sustain volume demand despite higher unit costs.
- Biodegradable Bags:PLA and PBAT blends certified to EN 13432 standards capture the steepest expansion trajectory as Carrefour and Tesco impose Scope 3 emission caps on promotional material suppliers. Moisture barrier limitations constrain food-contact deployment.
- Disposable Bags:Single-use polyethylene formats face procurement exclusion across EU retail frameworks.
- Heavy-Duty Bags:120-150 micron woven structures serve automotive parts logistics in Stuttgart and Wolfsburg manufacturing clusters.
Established volume favors heavy-duty variants; emerging adoption favors biodegradable formats.
Material:
Cost stratification separates commodity synthetics from premium natural fibers, with barrier performance requirements determining viable substitution thresholds.
- Polypropylene:Biaxially oriented films and woven tapes deliver moisture protection at 30-80 micron gauges. FDA food-contact compliance sustains dominance in North American CPG sampling programs despite petrochemical feedstock volatility.
- Cotton:GOTS-certified organic grades satisfy non-profit and luxury beauty sector demand for natural-fiber credentials in United Kingdom and Netherlands markets. Limited moisture resistance prevents pharmaceutical adoption.
- Jute:Hessian weaves serve agricultural seed and coffee bean inclusion applications in Indian and Bangladesh export channels.
- Polyester:PET non-wovens provide tear resistance for direct-mail promotional campaigns.
Polypropylene retains procurement volume leadership; cotton gains share fastest in sustainability-scored tenders.
End User:
Customer procurement maturity determines certification stringency, with organized retail imposing audited chain-of-custody requirements that disqualify spot-market suppliers.
- Retail Stores:Department store beauty counters and apparel fitting rooms deploy inclusion bags for gift-with-purchase programs. Nordstrom and Galeries Lafayette now require FSC or OK Compost certification for all promotional packaging.
- Grocery Chains:German discounters Aldi and Lidl mandate minimum recycled content thresholds in supplier qualification protocols. Product sample distribution drives multi-million unit annual procurement.
- Online Retailers:E-commerce unboxing experience investments elevate inclusion bag specifications at ASOS and Zalando.
- Non-Profits:Fundraising mailers and donor gift programs prioritize cotton and jute for environmental messaging alignment.
Grocery chains concentrate procurement scale; online retailers expand specification fastest.
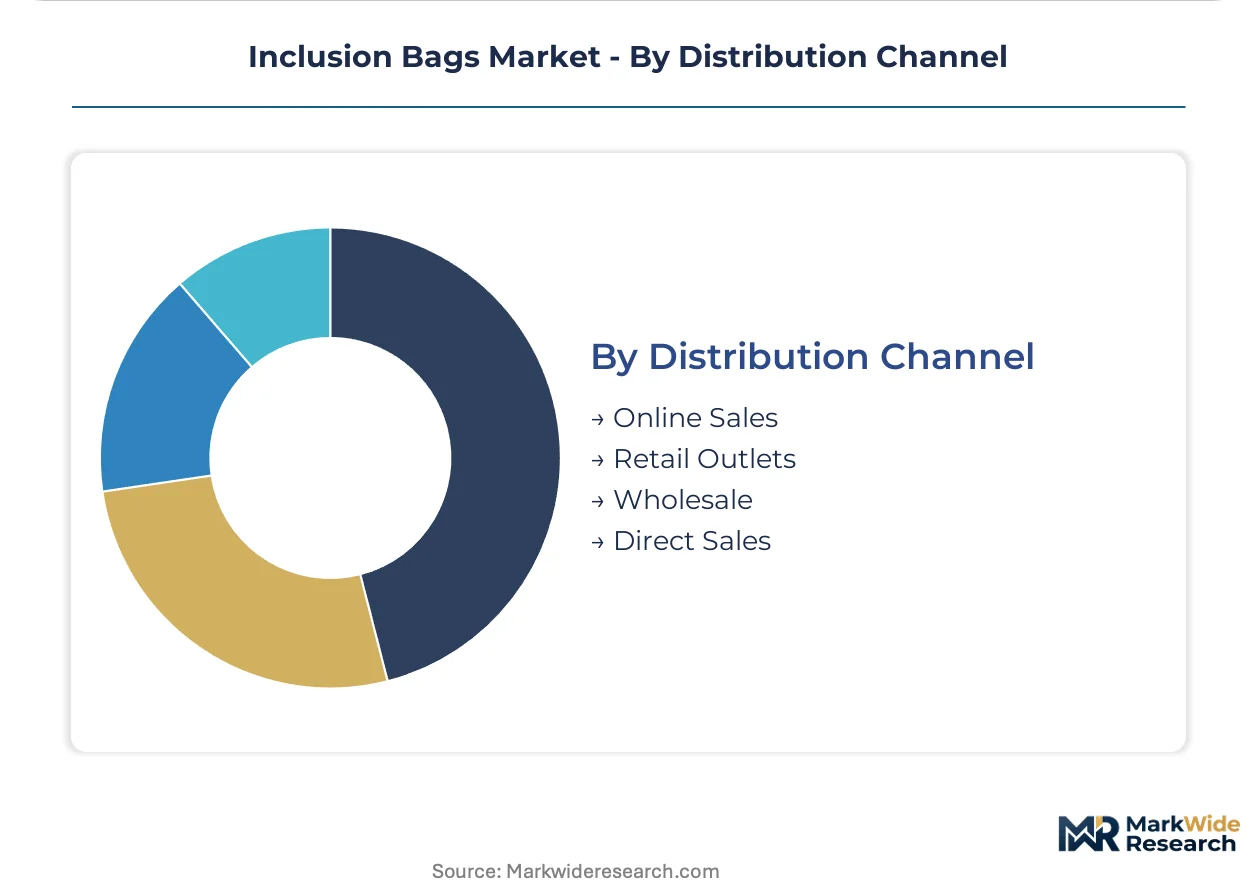
Distribution Channel:
Channel selection reflects buyer scale and customization requirements, with direct relationships enabling specification co-development.
- Online Sales:Alibaba and Amazon Business platforms aggregate small-batch orders from mid-tier CPG brands seeking rapid turnaround on seasonal promotional campaigns. Digital procurement reduces minimum order thresholds.
- Retail Outlets:Stationery and packaging specialty stores serve micro-business and artisan producer segments in Paris, Milan, and New York creative districts.
- Wholesale:Distributors like Bunzl and Rajapack consolidate volume for multi-site retail chains across European territories.
- Direct Sales:Manufacturer relationships with Unilever and L'Oréal enable collaborative development of branded inclusion formats.
Wholesale channels sustain volume concentration; online sales expand access fastest for emerging brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH enforcement through ECHA anchors European material compliance, while FDA food-contact standards govern North American sampling applications. Retailer sustainability mandates in Germany and the United States are compressing supplier qualification timelines faster than manufacturing capacity can adapt.
Germany
Aldi and Lidl procurement mandates drive heavy-duty woven polypropylene demand for closed-loop logistics systems. EU Green Deal recyclability thresholds force reformulation of promotional bag substrates. Stuttgart automotive clusters sustain 120-150 micron inclusion bag specifications for parts distribution.
United States
FDA barrier property requirements expand addressable demand for multi-layer food-contact sampling formats. Amazon fulfillment center closed-loop collection systems extend woven bag reuse cycles. California and Texas distribution hubs concentrate procurement scale for CPG promotional programs.
France
Carrefour Scope 3 emission caps accelerate certified compostable bag adoption in beauty sampling. Advancing EPR frameworks create infrastructure bundling opportunities for take-back service providers. Paris department store gift-with-purchase programs require FSC chain-of-custody documentation.
India
BIS certification requirements for plastic products create compliance pathways for exporters targeting organized grocery expansion. Mumbai, Delhi, and Bangalore retail infrastructure modernization drives specification upgrades. Jute hessian weaves serve agricultural seed inclusion applications for export channels.
United Kingdom
ASOS and Zalando e-commerce unboxing investments elevate inclusion bag specifications for direct-to-consumer channels. GOTS-certified organic cotton demand concentrates in non-profit and luxury beauty sectors. London creative districts sustain specialty stationery and packaging retail outlet demand.
Inclusion Bags Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with capacity concentration favoring backward-integrated resin producers over pure-play converters. Three archetypes dominate: vertically integrated packaging conglomerates controlling upstream polymer supply, fiber-based innovators reducing plastic dependency through substrate diversification, and regional specialists serving certified compostable niches. Competitive moves center on strategic partnerships with tier-one retail buyers and geographic expansion through BIS-compliant manufacturing footprints in India.
Among the integrated leaders, Amcor plc exemplifies upstream control over resin sourcing that stabilizes margin exposure to propylene monomer volatility. Mondi Group occupies a position within the fiber-based innovation tier, while Berry Global anchors the North American retail channel partnership archetype. These three represent distinct strategic postures: captive supply security, natural-fiber substitution pipelines, and scale manufacturing of certified compostable lines respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Berry Global, Inc. |
| Sealed Air Corporation |
| Sonoco Products Company |
| Smurfit Kappa Group |
| J. Drasner & Co. Inc. |
| Tex-Trude |
| Aalmir Plastic Industries |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal recyclability thresholds gate supplier qualification and price differentiation simultaneously, compressing margins for uncertified converters while enabling premium positioning for EN 13432-certified producers serving Aldi and Lidl procurement frameworks.
Pricing Analysis
German grocery chains command 15-20% price discounts on heavy-duty woven polypropylene against North American spot buyers due to closed-loop volume commitments. Three-tier pricing structure across premium certified-compostable, standard FDA-compliant, and economy non-certified levels tracks certification grade and volume scale. Cost compression in biodegradable PLA-PBAT blends is intensifying because European resin supply constraints outpace demand growth from Scope 3 mandates. Small-batch beauty samplers exhibit highest price sensitivity; industrial logistics operators show least.
Supply Chain Analysis
Just-in-time resin procurement dominates European extrusion operations, while strategic stockpiling of GOTS-certified organic cotton prevails among United Kingdom luxury beauty suppliers facing Bangladeshi harvest volatility. Manufacturing concentrates in Germany, China, and India, with resin compounding anchored in German chemical clusters and woven conversion scaling through Bangladeshi and Vietnamese textile mills. Feedstock exposure rests on propylene monomer, bio-based PLA granules, and organic cotton lint. Single-source vulnerability runs through European bio-resin suppliers lacking qualified alternatives. Distribution runs through wholesale distributors like Bunzl consolidating multi-site retail contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among German grocery discounters has shifted bargaining power decisively toward buyers, forcing supplier qualification investments ahead of contract awards.
For Market Incumbents: Secure captive bio-resin supply agreements to defend margin stability against propylene volatility threatening extrusion-based operations. Deepen FSC and OK Compost certification portfolios to preempt disqualification from Rewe and Carrefour sustainability scorecards. Capacity expansion in BIS-compliant Indian manufacturing hedges European regulatory tightening. For New Entrants and Emerging Players: Anchor in Mumbai and Bangalore retail infrastructure modernization as organized grocery expands specification requirements faster than incumbent supply response. Target biodegradable bag white-space in pharmaceutical sampling where moisture barrier coating miniaturization creates technical differentiation. Pursue direct sales relationships with direct-to-consumer beauty brands replacing spot-buying with framework agreements. For Investors and Strategic Acquirers: REACH authorization timelines for persistent organic pollutants reshape the acquisition landscape toward fiber-based innovators with natural-fiber substitution pipelines. Five-to-ten year viability favors producers with audited chain-of-custody documentation securing multi-year retail contracts. Acquisition candidates include regional specialists with BIS manufacturing footprints and compostable certification depth. Monitor ECHA substance-of-very-high-concern listing velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Resin Supply | Captive PLA-PBAT sourcing stabilizes margin exposure to European petrochemical volatility. |
| Multi-Certification Investment | Simultaneous FSC, OK Compost, and BIS qualification unlocks Aldi, Lidl, and organized Indian grocery access. |
| Water-Based Barrier Coating Adoption | Mono-material structures simplify EU Green Deal compliance for pharmaceutical sampling applications. |
| Closed-Loop Collection Infrastructure | Take-back service bundling aligns with France and Italy advancing EPR frameworks. |
| Smart Packaging Convergence | QR-embedded traceability commands premium positioning in beauty and pharmaceutical sampling. |
Study Parameters
Desk research of customs trade databases, EU regulatory filings, and retailer sustainability disclosure preceded structured interviews with polymer chemists, grocery procurement directors, packaging converters, and certification body auditors. Primary fieldwork validated secondary data from ECHA substance registrations, BIS plastic product standards, and FDA food-contact guidance documents. Bottom-up volume triangulation across substrate categories reconciled with top-down market sizing from trade flow analysis.
Variance decomposition across material, end-use, and distribution channel segments shaped the analytical framework over the projection horizon. Modeled dimensions included substrate technology, certification tier, procurement channel maturity, and regional regulatory cluster. CAGRs derived from segment-level growth rate reconciliation against macro demand drivers. Industry-specific inputs incorporated REACH authorization timelines and retailer Scope 3 emission target trajectories.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable propylene feedstock availability; material deviation would warrant model refresh. Revision becomes warranted when ECHA substance-of-very-high-concern listing velocity crosses thresholds triggering widespread reformulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Block Sack Market
Bags and Containers
Slider Bags Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Plastic Bags and Sacks Market