
 Global Thermal Transfer Ribbon Market | 2026-2036
Global Thermal Transfer Ribbon Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermal Transfer Ribbon Market Foresight
Aftermarket service revenue is fragmenting as printer OEMs compete with independent ribbon suppliers for recurring consumables spend. ITW Thermal Films leverages its North American manufacturing footprint to sustain consistent supply to automotive labeling programs. Zebra Technologies Corporation dominates the integrated printer-ribbon ecosystem, while Armor-IIMAK specializes in premium resin formulations for chemical-resistant applications.
Thermal transfer ribbon consists of a polyester film substrate coated with a thermal-sensitive ink layer that transfers to receiving media via precise heat application from a print head, typically operating between 90°C and 180°C depending on ribbon chemistry. The technology serves critical identification, tracking, and compliance labeling functions across industries requiring durable, scannable marks. Wax-resin hybrid formulations lead volume shipments due to their balance of print quality and substrate versatility, while pure resin ribbons command premium positioning in healthcare identification and chemical drum labeling where abrasion and solvent resistance prove essential. Flat head technology maintains installed base dominance, though near edge printing is gaining traction in high-speed logistics tracking applications.
REACH regulation in Europe restricts certain phthalate plasticizers and heavy metal pigments in ribbon coatings, compelling reformulation investments across suppliers. FDA's Unique Device Identification rules for healthcare identification labels mandate specific print durability standards that resin-grade ribbons satisfy. Stakeholders must monitor evolving pharmaceutical serialization requirements in China under NMPA guidance and assess whether wax-resin formulations can capture share from pure resin in secondary packaging applications without sacrificing scan reliability.
Market Dynamics
Pharmaceutical serialization mandates across China, Germany, and the United States are compressing ribbon specification cycles and forcing suppliers to certify resin-grade formulations for track-and-trace compliance at unprecedented speed.
Growth Catalysts
- REACH compliance deadlines:European ECHA enforcement against phthalate plasticizers in ribbon coatings is accelerating reformulation investments that favor compliant suppliers with certified resin stocks.
- Automated warehouse networks:Logistics tracking applications in high-velocity fulfillment centers are standardizing near-edge thermal transfer configurations for scan reliability at speed.
- China NMPA guidance:Evolving pharmaceutical serialization rules under China's national medical products administration are expanding demand for durable resin-grade healthcare identification labels.
Market Restraints
- Polyester film supply concentration:Substrate manufacturing clusters in East Asia create vulnerability to regional logistics disruptions and input cost volatility.
- Digital inkjet substitution:Variable-data printing technologies are capturing secondary packaging applications where barcode durability requirements permit lower-cost alternatives.
- Flat head installed base inertia:Legacy printer architectures in industrial labeling operations slow adoption of near-edge ribbon formulations despite throughput advantages.
Strategic Opportunities
- India pharmaceutical exports:CDSCO serialization alignment with international standards creates demand for compliant resin ribbon in contract manufacturing packaging lines.
- Wax-resin hybrid expansion:Secondary pharmaceutical packaging applications present white space for mid-tier formulations that balance cost against scan reliability thresholds.
- Direct thermal convergence:Integration of RFID inlay encoding with thermal transfer printheads enables single-pass smart label production for automotive part tracking.
Industry Challenges
- Printhead compatibility certification:OEM-specific ribbon approval timelines extend six to eighteen months, delaying formulation launches and locking out independent suppliers.
- Cross-regulatory harmonization:Divergent FDA durability standards, REACH substance restrictions, and NMPA serialization protocols force parallel certification tracks that fragment R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermal Transfer Ribbon Market |
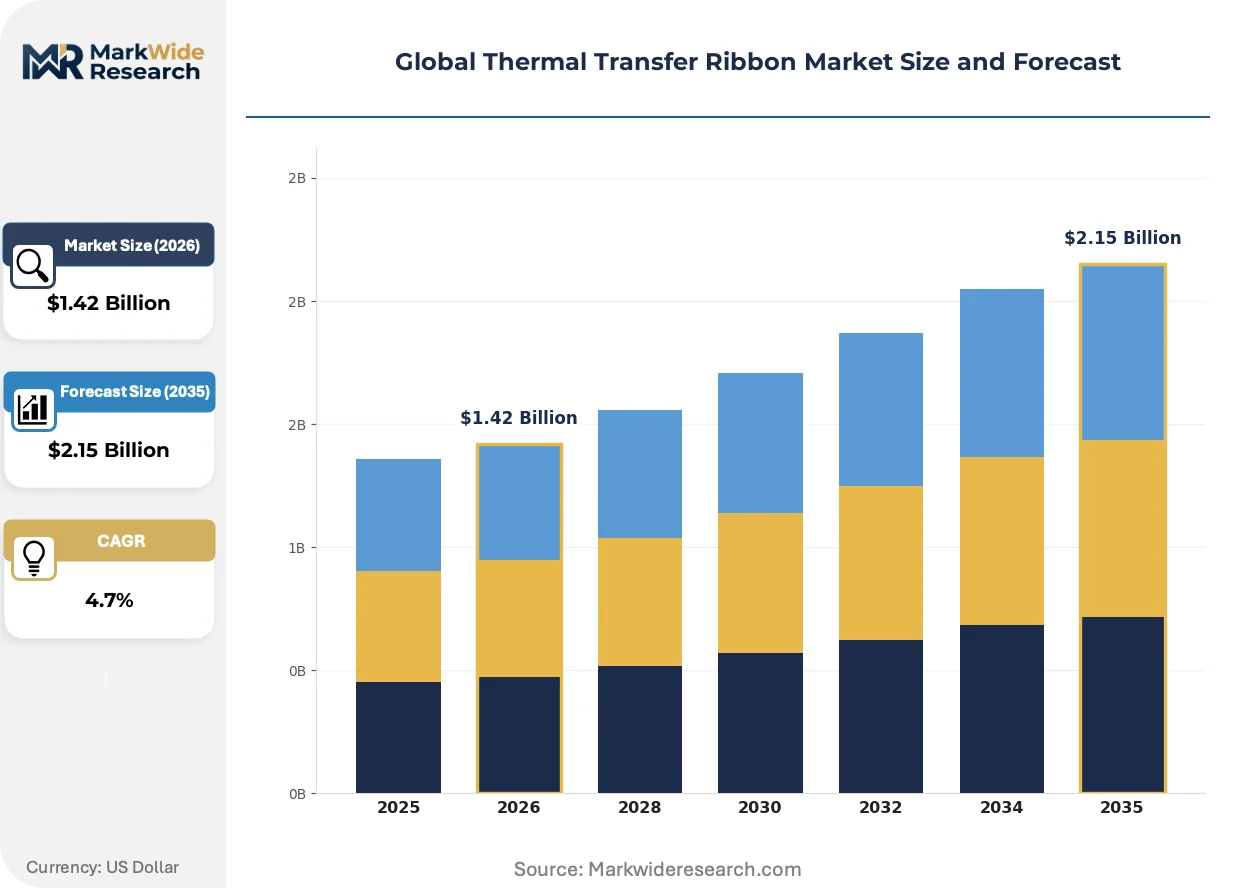
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.15 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wax, Resin, Wax-Resin, Specialty, Polymer Technology: Flat Head, Near Edge, Hybrid, Direct Thermal, Thermal Inkjet Application: Packaging Labels, Healthcare Identification, Retail Tagging, Logistics Tracking, Manufacturing Barcodes End User: Manufacturers, Distributors, Logistics Providers, Pharmacies, Retailers |
| Companies Covered | DNP Imagingcomm America Corporation, ITW Thermal Films, Zebra Technologies Corporation, Honeywell International Inc., SATO Holdings Corporation, Armor-IIMAK, Fujicopian Co., Ltd., Oji Imaging Media Co., Ltd., Ricoh Company, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermal Transfer Ribbon Market Shifts & Advancements
Near-edge printhead architectures and cloud-connected printer fleets are compressing the traditional ribbon-printer-specification cycle, forcing suppliers to integrate predictive analytics into consumables design.
Water-based resin coating technologies are virtualizing solvent-intensive manufacturing processes for chemical-resistant ribbon grades. Automotive battery manufacturers in Germany and South Korea are adopting these formulations for electrolyte drum labeling at commercial scale. The shift is virtualizing legacy petrochemical supply dependencies while compressing volatile organic compound compliance costs across European production facilities.
EU MDR (Medical Device Regulation) Article 27 implantable device traceability rules are mandating permanent-mark durability standards that exceed conventional wax-resin performance. Resin-grade ribbon suppliers must document twenty-year legibility under sterilization stress testing. German medical device exporters and their Irish contract labeling partners are consolidating procurement around certified suppliers with notified body documentation.
Aftermarket service unbundling is fragmenting the traditional OEM-captive consumables model. Third-party logistics operators in United States e-commerce fulfillment are disaggregating printer maintenance from ribbon supply contracts, enabling independent ribbon specialists to capture recurring revenue. This pattern concentrates in high-volume automated sortation hubs where print volume predictability supports alternative supplier qualification.
Global Thermal Transfer Ribbon Market Segmentation
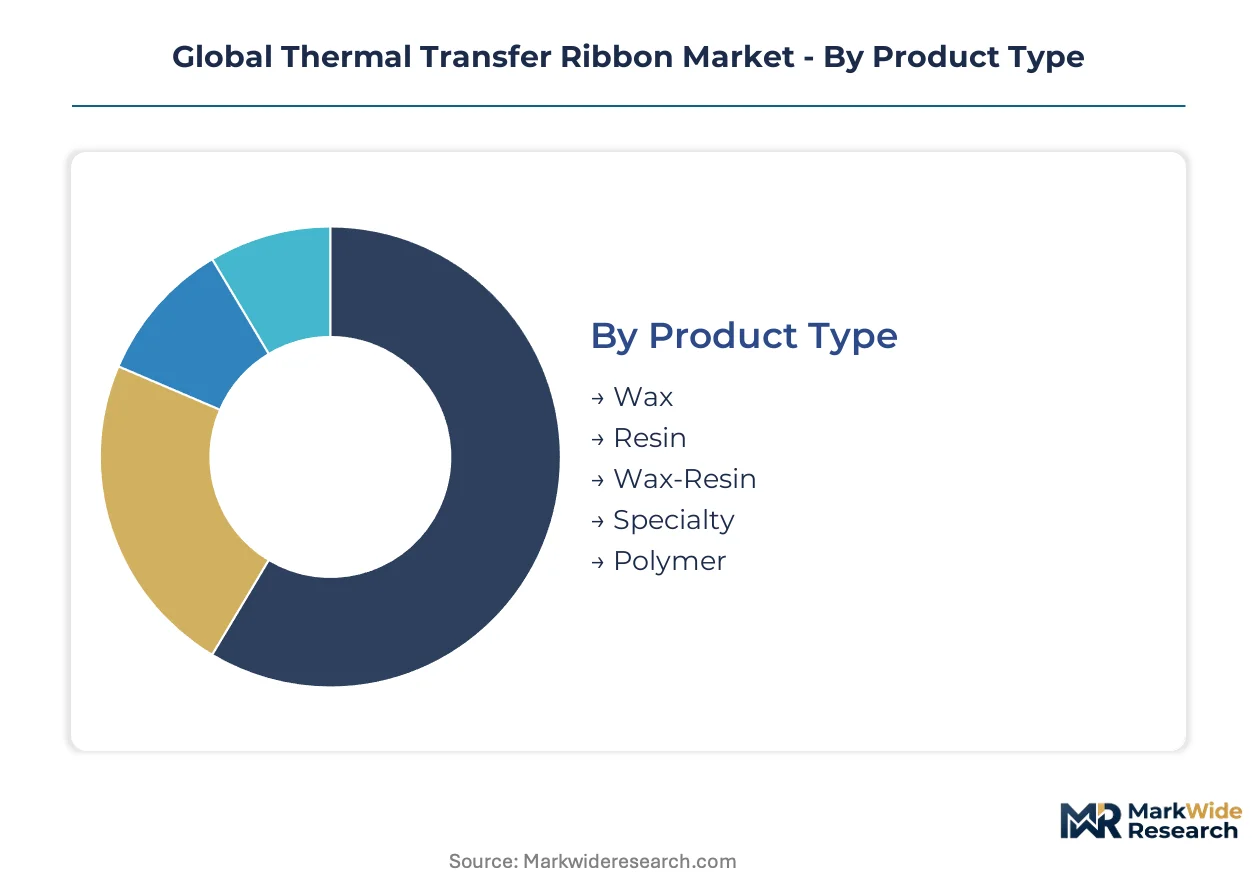
Ribbon chemistry and printhead architecture determine performance thresholds across compliance-heavy verticals. Segmentation reveals where wax-resin hybrids compete against pure resin grades, and why near-edge configurations are displacing legacy flat head installations in high-velocity fulfillment environments.
Product Type:
Mature formulations dominate volume, while emerging chemistries target regulatory-driven durability mandates.
- Wax:Lowest-cost formulation with high carbon black loading for paper-based substrates. Supermarket chains in Germany and discount retailers in the United States consume bulk volumes for short-life shipping labels where abrasion resistance remains secondary to unit economics.
- Resin:Premium-grade ribbon with thermoplastic binders engineered for synthetic substrates. Pharmaceutical manufacturers in China under NMPA serialization mandates and chemical drum labelers in Germany drive specification cycles for solvent-resistant, sterilization-proof marks.
- Wax-Resin:Hybrid chemistry balancing print quality against substrate versatility. Secondary packaging lines in contract manufacturing facilities favor this tier for cost-controlled compliance labeling.
- Specialty:Custom-formulated ribbons for extreme environments including cryogenic storage and high-temperature autoclave exposure. Biobank operators and aerospace component trackers specify these grades.
- Polymer:Advanced substrate-compatible ribbons with enhanced flexibility for curved surfaces. Medical device pouch labeling and flexible food packaging applications adopt these formulations.
Wax-resin handles the majority of throughput; resin is the fastest mover on share as serialization mandates tighten globally.
Technology:
Cost tier separation runs from legacy installed base to premium throughput architectures.
- Flat Head:Conventional printhead design with fixed thermal element alignment. Industrial manufacturing floors in the United States and Germany retain this technology due to capital replacement cycles and established maintenance protocols.
- Near Edge:Angled thermal element geometry enabling higher print speeds with reduced ribbon waste. Automated warehouse networks in China and e-commerce sortation hubs in Germany standardize this configuration for logistics tracking at velocity.
- Hybrid:Dual-mode printheads switching between flat and near-edge operation. Contract packaging operations serving multiple end-users adopt these for operational flexibility.
- Direct Thermal:Heat-sensitive media eliminating ribbon consumption entirely. Short-life retail tagging and temporary shipping applications use this technology where mark durability requirements permit.
- Thermal Inkjet:Non-contact printing with aqueous or solvent-based inks. Secondary packaging and promotional labeling applications employ this where variable data and color capability outweigh barcode durability needs.
Flat head retains the largest installed base; near edge is expanding most quickly in greenfield automated fulfillment deployments.
Application:
Customer type dictates specification intensity from commodity throughput to mission-critical traceability.
- Packaging Labels:High-volume primary and secondary packaging identification. Food and beverage manufacturers in Germany and consumer goods producers in China drive standardization around wax-resin performance thresholds.
- Healthcare Identification:Patient wristbands, specimen labels, and implantable device documentation. FDA UDI rules and EU MDR Article 27 mandates force resin-grade adoption with twenty-year legibility certification.
- Retail Tagging:Price marking and inventory control for apparel and electronics. Fast-fashion retailers in the United States and department stores in Germany consume ribbon in predictable seasonal patterns.
- Logistics Tracking:Parcel sortation, pallet identification, and cross-dock routing. Third-party logistics operators in China and express delivery networks in Germany prioritize scan reliability at conveyor speeds.
- Manufacturing Barcodes:Work-in-process tracking and finished goods serialization. Automotive suppliers in Germany and electronics contract manufacturers in China specify chemical-resistant formulations for harsh production environments.
Packaging labels generate the highest absolute volume; healthcare identification is climbing the fastest on regulatory compulsion.
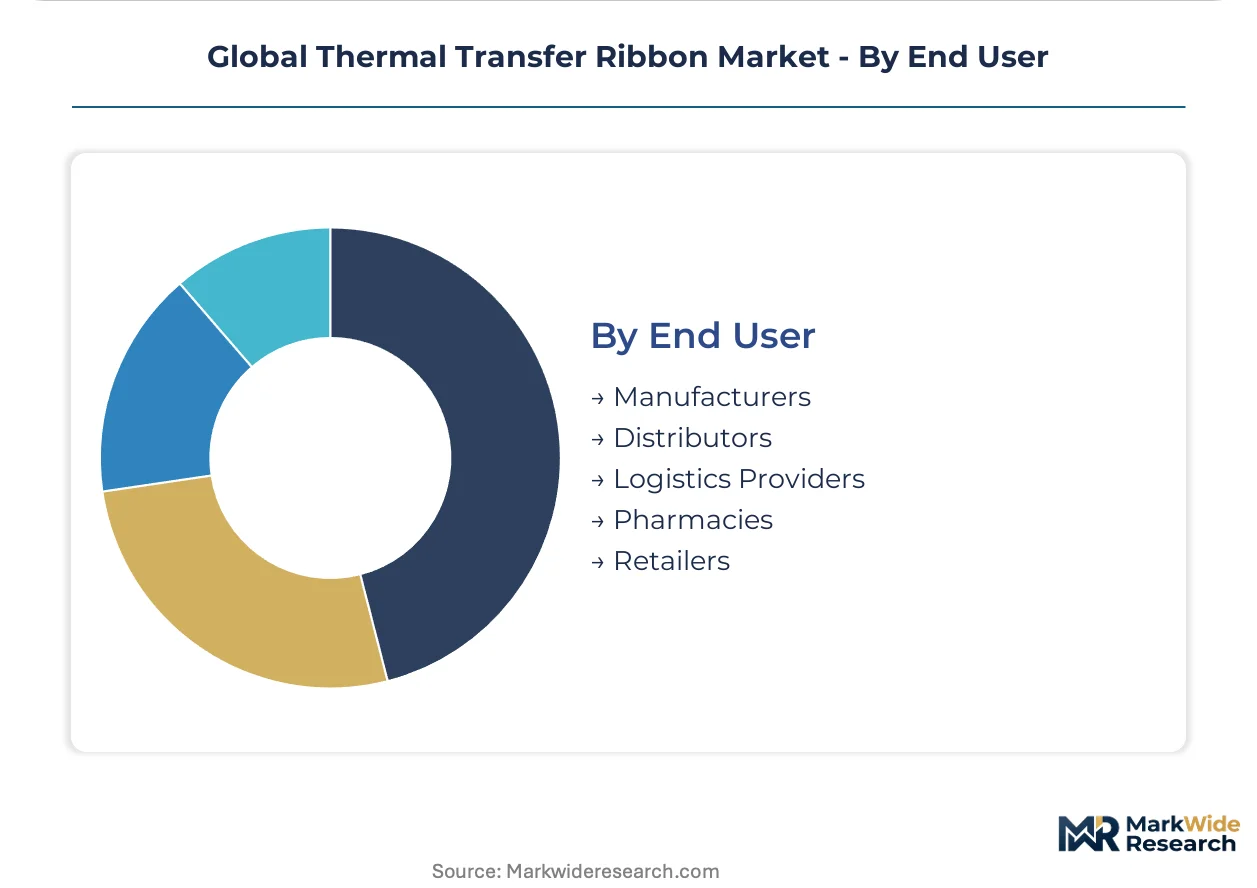
End User:
Supply concentration patterns separate captive procurement from open-market sourcing.
- Manufacturers:Integrated production facilities with dedicated labeling lines. Pharmaceutical and medical device producers in Germany and China maintain qualified supplier lists with multi-year resin certification requirements.
- Distributors:Third-party logistics and value-added resellers managing ribbon inventory for downstream customers. Independent ribbon specialists in the United States compete against OEM-captive channels here.
- Logistics Providers:Express carriers and warehouse operators with high-velocity print requirements. Automated sortation hub operators in China and Germany disaggregate printer maintenance from consumables procurement.
- Pharmacies:Retail and hospital pharmacy dispensing label operations. Chain pharmacies in the United States and Germany standardize around specific printer-ribbon combinations for prescription compliance.
- Retailers:In-store marking and omnichannel fulfillment label production. E-commerce fulfillment centers operated by major retailers in China and the United States drive near-edge adoption for same-day shipment processing.
Manufacturers command the most stringent specification authority; logistics providers are gaining procurement autonomy fastest through aftermarket unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States prioritize resin-grade certification over unit cost, while Chinese logistics operators and Indian contract manufacturers drive volume through wax-resin formulations that balance compliance against price elasticity.
United States
FDA's Unique Device Identification rules and e-commerce fulfillment automation propel resin-grade ribbon consumption. EPA volatile organic compound limits pressure coating reformulation investments. Pharmaceutical serialization clusters in New Jersey and North Carolina concentrate demand for twenty-year legibility certification.
Germany
EU MDR Article 27 implantable device traceability mandates exceed conventional wax-resin durability thresholds. ECHA REACH enforcement against phthalate plasticizers accelerates compliant resin stock qualification. Automotive battery manufacturers in Bavaria adopt water-based resin formulations for electrolyte drum labeling at commercial scale.
China
NMPA pharmaceutical serialization guidance expands demand for durable healthcare identification labels. MIIT smart logistics initiatives standardize near-edge thermal transfer in automated warehouse networks. Yangtze River Delta contract manufacturers qualify resin ribbons for export pharmaceutical packaging lines.
India
CDSCO serialization alignment with international standards creates demand for compliant resin ribbon in pharmaceutical export packaging. FSSAI food traceability expansion drives wax-resin adoption in secondary packaging. Maharashtra and Gujarat contract manufacturing clusters consolidate procurement around certified suppliers.
Japan
METI supply chain digitization programs accelerate automated logistics tracking adoption. PMDA medical device labeling durability standards mirror FDA UDI requirements. Kanto region electronics contract manufacturers specify chemical-resistant formulations for component traceability.
Global Thermal Transfer Ribbon Market Competitive Landscape
Capability concentration sits with resin formulation specialists; scale advantage sits with integrated printer-ribbon ecosystem providers. The market structures around three tiers: captive OEM consumables divisions, independent ribbon specialists with regional manufacturing footprints, and diversified imaging media conglomerates with coating technology cross-application. Dominant competitive moves include strategic partnerships between ribbon suppliers and printhead OEMs for compatibility certification, plus geographic capacity expansion to hedge East Asian substrate supply concentration.
Among North American-based suppliers, ITW Thermal Films exemplifies the regional manufacturing footprint archetype, while Zebra Technologies Corporation anchors the integrated printer-ribbon ecosystem position. Armor-IIMAK represents the premium resin formulation specialist tier. These three occupy distinct competitive spaces without direct overlap in capability claims.
| Leading Market Players |
|---|
| DNP Imagingcomm America Corporation |
| ITW Thermal Films |
| Zebra Technologies Corporation |
| Honeywell International Inc. |
| SATO Holdings Corporation |
| Armor-IIMAK |
| Fujicopian Co., Ltd. |
| Oji Imaging Media Co., Ltd. |
| Ricoh Company, Ltd. |
| Others |
Supply & Pricing Matrix
Yangtze River Delta port congestion cost dynamics cascade through polyester film substrate pricing and downstream ribbon tier differentiation. Freight rate volatility from East Asian manufacturing clusters compresses margins for independent suppliers while reinforcing integrated printer-ribbon ecosystem pricing power.
Pricing Analysis
Aftermarket consumables revenue sustains lifetime value capture across the installed base. Three-tier pricing structure across premium resin, standard wax-resin, and economy wax levels separates certification-grade pharmaceutical ribbons from logistics-optimized formulations. Cost compression in mid-tier wax-resin hybrids intensifies because digital inkjet substitution erodes barcode durability premiums. Contract packaging operations in India exhibit highest price sensitivity; German medical device exporters show least sensitivity due to EU MDR Article 27 compliance mandates.
Supply Chain Analysis
Extended payment terms from Chinese polyester film manufacturers anchor supplier-financing relationships across coating operations. Substrate manufacturing concentrates in China, Japan, and South Korea; thermal-sensitive ink layers draw from petrochemical and water-based resin feedstocks. Single-source vulnerability in East Asian film production creates exposure to regional logistics disruptions. Distribution runs through OEM-captive channels, independent ribbon specialists, and third-party logistics operators with disaggregated procurement autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-edge printhead standardization in automated fulfillment networks creates platform-economics inflection where ribbon-printer interoperability determines supplier lock-in. Cloud-connected fleet management compresses specification cycles and rewards predictive analytics integration.
For Market Incumbents: Pre-empt independent ribbon specialists by accelerating printhead compatibility certification timelines and securing exclusive resin formulation partnerships. Digital inkjet substitution in secondary packaging threatens wax-resin volume; backward integration into water-based coating technology hedges petrochemical cost volatility and EPA volatile organic compound compliance exposure. For New Entrants and Emerging Players: Indian pharmaceutical export packaging lines under CDSCO serialization alignment represent the most penetrable entry point for compliant resin ribbon qualification. Water-based resin formulations for automotive battery electrolyte drum labeling in Germany and South Korea offer specialty chemistry white space. Partner with regional printhead distributors for rapid compatibility testing bypassing OEM-captive channel blockades. For Investors and Strategic Acquirers: Regional coating facilities with notified body documentation for EU MDR and FDA UDI durability certification command scarcity premia in consolidation scenarios. Long-term viability hinges on reformulation agility across REACH-compliant resin stocks and predictive consumables analytics integration. Watch NMPA pharmaceutical serialization enforcement velocity as demand inflection signal for China-dedicated capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Formulation Certification Investment | EU MDR Article 27 twenty-year legibility mandates force notified body documentation consolidation. |
| Water-Based Coating Technology Transition | Automotive battery manufacturers in Bavaria adopt virtualized solvent processes for electrolyte labeling. |
| Near-Edge Printhead Partnership | Automated warehouse networks in China standardize high-speed logistics tracking configurations. |
| Predictive Analytics Integration | Cloud-connected printer fleets compress ribbon specification cycles through consumption forecasting. |
| Regional Manufacturing Footprint Expansion | East Asian substrate concentration risk drives coating capacity diversification to North America and Europe. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented compliance trajectories. Conversations with coating plant managers, pharmaceutical packaging engineers, printhead OEM procurement leads, and third-party logistics operators combine with FDA UDI guidance documents, ECHA REACH substance restrictions, NMPA serialization protocols, and customs trade data for bottom-up and top-down triangulation.
Calibration against historical resin-grade adoption curves and pharmaceutical serialization implementation timelines shapes the analytical framework. Segmentation dimensions span ribbon chemistry tier, printhead architecture, application durability requirement, end-user procurement autonomy, and regional regulatory cluster across the modeling period. CAGRs derive from elasticity-adjusted volume projections incorporating NMPA enforcement pace and e-commerce fulfillment automation penetration.
Practitioners should monitor REACH substance restriction expansion, FDA UDI durability standard updates, and NMPA serialization compliance deadlines for early signals of specification cycle compression. Forecasts reflect assumptions about regulatory harmonization velocity and substitution technology penetration; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Qatar Printing and Packaging Market
Packaging Printing
North America Print Label Market
Packaging Printing
Laser Coders Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
Rotogravure Printing Machine Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Stamping Foils Market
Packaging Printing
Global Printing for Packaging Market
Packaging Printing
Pre-Press for Packaging Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
LAMEA Label Printing Software Market
Packaging Printing
Czech Republic Printing Label Market
Packaging Printing
Rotogravure Printing Cylinder Market