
 Global Polypropylene Woven Bags and Sacks Market | 2026-2036
Global Polypropylene Woven Bags and Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polypropylene Woven Bags and Sacks Market Foresight
Market Context with Strategic Players
Agricultural producers is bifurcating from chemical manufacturers as the dominant buyer archetype in woven packaging procurement. Emmbi Industries Limited leverages vertical integration across tape extrusion and bag conversion to sustain cost leadership in Indian agricultural supply chains. Mondi plc anchors European demand through its specialty laminated sack portfolio designed for food-contact compliance. Berry Global Inc. competes on manufacturing scale, operating multi-continent production networks that serve construction materials distributors with UV-stabilized bulk containers.
Technical Definition and Structural Segments
Global Polypropylene Woven Bags and Sacks are fabricated from extruded polypropylene tapes woven into tubular or flat fabrics, typically rated for loads between 25 kg and 2,000 kg, with optional polyethylene lamination for moisture barrier performance. These containers serve as primary packaging for granular and powdered commodities across agriculture, chemicals, and construction verticals where mechanical strength and unit-cost efficiency outweigh rigid packaging alternatives. Laminated sacks command premium positioning within the product type dimension due to their moisture resistance and printability for branded consumer-facing applications. Food grade material specifications concentrate margin pools where FDA and EFSA compliance requirements create qualification barriers against commodity industrial-grade competitors. Recycled polypropylene grades represent the fastest-expanding material category as brand owners impose post-consumer content mandates on packaging procurement.
Regulatory Frame and Forward-Looking Close
REACH in Europe, FDA food-contact regulations in the United States, and BIS certification requirements in India collectively shape material composition standards, recyclability claims, and market access conditions for polypropylene woven packaging manufacturers. ECHA substance restrictions on specific additives and the EU Green Deal's packaging waste directives are forcing reformulation of UV stabilizers and colorant systems across export-oriented production facilities. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to absorb compliance costs or pass them through to price-sensitive agricultural and construction end users.
Market Dynamics
Agricultural modernization in India and China is concentrating polypropylene woven sack demand around laminated, food-grade specifications, forcing manufacturers to absorb compliance costs from REACH and FDA material-grade mandates while defending price positions in commodity grain storage.
Growth Catalysts
- REACH substance restrictions:European ECHA additive limitations are accelerating reformulation of UV stabilizers and colorants, creating qualification barriers that favor established compounders with in-house testing capabilities.
- Grain storage infrastructure:Indian agricultural cooperatives are expanding cold-chain-adjacent bulk handling, driving laminated sack procurement for moisture-sensitive oilseeds and pulses.
- Post-consumer content mandates:Brand-owner sustainability procurement rules are pulling recycled polypropylene grades into food-contact applications previously reserved for virgin resin.
Market Restraints
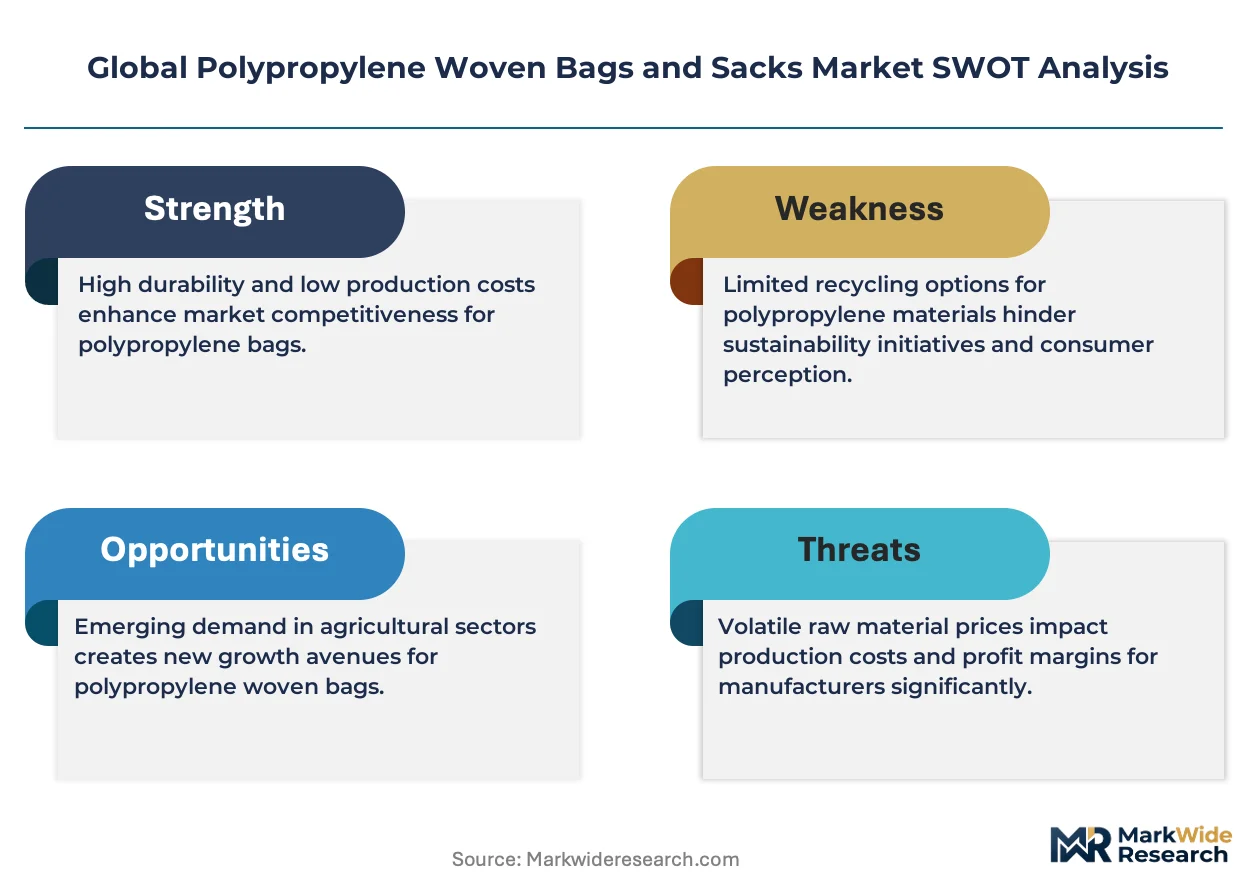
- Propylene feedstock volatility:Naphtha-cracker output fluctuations in Middle Eastern and Asian petrochemical complexes transmit directly to tape extrusion cost structures.
- Substitution by flexible intermediate bulk containers:Construction materials distributors above 500 kg unit loads are migrating to FIBC formats, compressing woven sack addressable volume in cement and aggregates.
- BIS certification timelines:Indian Bureau of Standards food-grade approval cycles extend 8-14 months, freezing new entrant market access while incumbents stockpile certified inventory.
Strategic Opportunities
- EU Green Deal packaging waste directives:Extended producer responsibility frameworks in Germany and France create first-mover advantages for closed-loop recycling partnerships with agricultural cooperatives.
- Digital printing convergence:Combination of high-resolution flexography and QR-code traceability is enabling branded consumer-facing sack applications in specialty coffee and organic grains.
- Rural China distribution:E-commerce penetration into county-level agricultural supply is opening direct-to-cooperative channels bypassing traditional wholesale sack distributors.
Industry Challenges
- Multi-jurisdiction compliance staffing:Simultaneous REACH, FDA, and BIS qualification requirements demand specialized regulatory affairs functions scarce in mid-scale tape extrusion operations.
- Lamination line capex intensity:Coextrusion equipment for PE barrier layers requires 2.5-4 million dollar outlays per production line, straining balance sheets during margin compression cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polypropylene Woven Bags and Sacks Market |
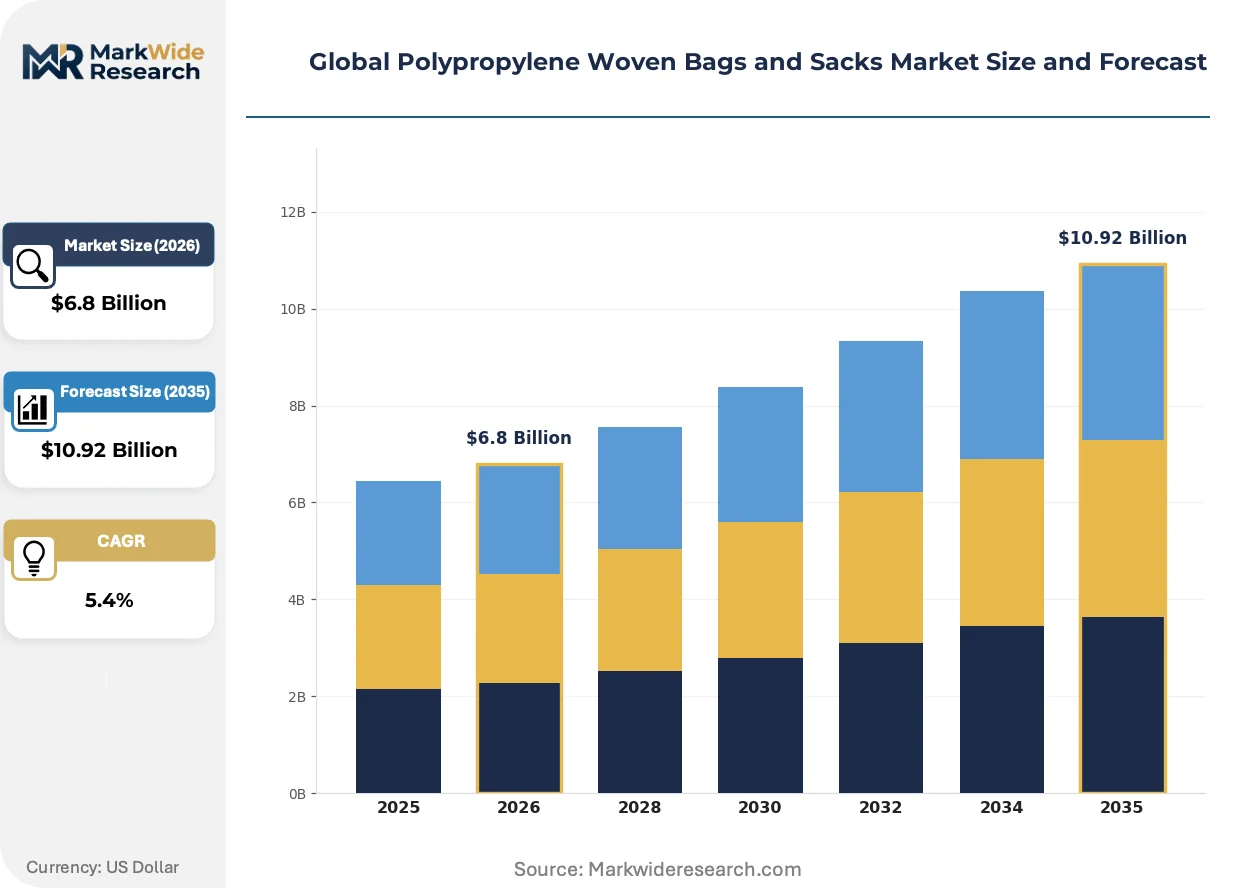
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Bags, Laminated Sacks, Coated Bags, Printed Sacks, Plain Bags Application: Agricultural Packaging, Chemicals Handling, Food Packaging, Construction Materials, Industrial Goods Material Grade: Food Grade, Industrial Grade, UV Stabilized, Recycled Polypropylene, Virgin Polypropylene End User: Food Processing Units, Chemical Manufacturers, Construction Contractors, Agricultural Producers, Textile Firms |
| Companies Covered | Emmbi Industries Limited, United Bags, Mondi plc, ProAmpac, Conitex Sonoco USA, Berry Global Inc., LC Packaging, Flexi-tuff, Uflex Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polypropylene Woven Bags and Sacks Market Shifts & Advancements
Material science advances and regulatory stringency are fragmenting the historically commoditized woven sack landscape into performance-differentiated tiers, with sustainability credentials and digital integration emerging as the primary axes of supplier competition.
Recycled polypropylene feedstock streams are decomposing the virgin resin cost advantage that historically dominated agricultural procurement. Large grain traders in Brazil and Argentina are now specifying 30% post-consumer content in annual sack tenders. This specification shift is compressing margins for single-source virgin resin compounders while rewarding integrated recyclers with captive flake supply.
EU Green Deal packaging waste directives are mandating recyclability-by-design standards that prohibit multi-material laminations incompatible with existing polypropylene mechanical recycling infrastructure. Sack converters serving European food-contact applications are responding with mono-material PE barrier coatings and water-based print systems that maintain moisture resistance while satisfying EFSA compliance.
Buyer concentration among multinational grain traders is compressing procurement cycles from annual to quarterly negotiations, with penalty clauses for delivery variance. This behavioral shift is most visible in Black Sea wheat corridors, where traders now demand real-time inventory visibility through RFID-tagged sacks and vendor-managed stock programs at port elevators.
Global Polypropylene Woven Bags and Sacks Market Segmentation
Segmentation in polypropylene woven packaging reveals how substitution pressures and compliance costs fragment a historically uniform commodity landscape. Buyers now sort procurement across performance tiers where lamination quality, food-contact certification, and recycled content determine supplier qualification and price realization.
Product Type:
Laminated and coated formats face the stiffest substitution threat from flexible intermediate bulk containers above 500 kg loads, forcing converters to defend position through moisture-barrier performance and printability.
- Laminated Sacks:PE-coextruded barrier layers deliver moisture resistance for oilseed and pulse storage in Indian agricultural cooperatives. Cold-chain-adjacent bulk handling expansion concentrates procurement of FDA- and EFSA-compliant specifications with premium print surfaces for branded grain applications.
- Woven Bags:Tubular or flat fabric construction without barrier coating serves cost-sensitive cement and aggregates distribution where UV stabilization outweighs moisture protection. Construction materials distributors in China and India specify these for 25-100 kg unit loads below FIBC migration thresholds.
- Coated Bags:Surface-treated polypropylene provides intermediate moisture resistance at lower cost than full lamination.
- Printed Sacks:Flexographic or digital print capability enables traceability coding and cooperative branding for specialty coffee and organic grain exports.
- Plain Bags:Unprinted, uncoated standard fabric serves commodity chemical and mineral bulk where identification requirements are minimal.
Woven bags anchor the volume base while laminated sacks gain share at the steepest rate.
Application:
Cost tier stratification separates agricultural procurement—where price sensitivity dominates—from food packaging where certification premiums justify material-grade upgrades.
- Agricultural Packaging:Grain storage and oilseed handling in India and China drives laminated sack specification for moisture-sensitive commodities. Indian agricultural cooperatives expanding cold-chain infrastructure are pulling food-grade compliance requirements into historically industrial-grade procurement.
- Food Packaging:Direct-contact applications for flour, rice, and specialty grains demand FDA, EFSA, and FSSAI material certification with full batch traceability. EU Green Deal recyclability mandates are forcing mono-material barrier reformulation away from multi-layer laminations incompatible with mechanical recycling.
- Chemicals Handling:Fertilizer and agrochemical distribution requires UN-certified construction for hazardous material containment.
- Construction Materials:Cement, sand, and aggregate packaging above 500 kg faces accelerating FIBC substitution.
- Industrial Goods:Mineral and resin bulk handling prioritizes unit-cost efficiency over barrier performance.
Agricultural packaging anchors the volume base while food packaging gains share at the steepest rate.
Material Grade:
Customer type bifurcation splits procurement between multinational grain traders demanding post-consumer content and agricultural cooperatives prioritizing virgin resin consistency.
- Recycled Polypropylene:Post-consumer flake feedstock now specified at 30% content in Brazilian and Argentine grain trader tenders. Large agricultural exporters are imposing sustainability mandates that compress margins for single-source virgin compounders while rewarding integrated recyclers with captive supply.
- Food Grade:Virgin resin with full additive disclosure meets FDA, EFSA, and BIS food-contact limits on heavy metals and migratory substances. ECHA substance restrictions on specific UV stabilizers and colorants are forcing reformulation cycles that favor established compounders with in-house testing capabilities.
- Industrial Grade:Standard virgin resin without food-contact certification serves chemical and construction applications.
- UV Stabilized:Additive packages for outdoor storage durability in tropical and high-altitude climates.
- Virgin Polypropylene:Unmodified resin for basic industrial applications with minimal performance requirements.
Food grade anchors the volume base while recycled polypropylene gains share at the steepest rate.
End User:
Margin concentration tracks regulatory exposure, with food processing units absorbing compliance costs that construction contractors reject.
- Agricultural Producers:Indian and Chinese farming cooperatives are consolidating procurement around laminated, food-grade specifications as agricultural modernization accelerates. These buyers face tension between REACH and FDA material-grade mandates and price defense requirements in commodity grain markets.
- Food Processing Units:Milling and packaging operations for rice, flour, and pulses require full certification chains from resin through conversion. Quarterly procurement cycles with penalty clauses for delivery variance are compressing supplier margins while demanding real-time inventory visibility.
- Chemical Manufacturers:Fertilizer and agrochemical producers specify UN-certified hazardous material construction.
- Construction Contractors:Cement and aggregates distributors above 500 kg loads are migrating to FIBC formats.
- Textile Firms:Fiber and yarn producers use woven sacks for internal material handling with minimal performance requirements.
Agricultural producers anchor the volume base while food processing units gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Mumbai anchors Indian woven sack export capacity for agricultural commodities bound for Southeast Asian and African markets. This maritime infrastructure underwrites India's position as the fastest-expanding procurement zone for laminated food-grade specifications.
India
Agricultural cooperatives in Punjab and Haryana are consolidating grain storage procurement around BIS-certified laminated sacks for oilseed exports. FSSAI food-contact mandates are tightening additive disclosure requirements for converters serving domestic milling operations. The Pithampur-Dhar-Mhow industrial belt near Indore concentrates tape extrusion capacity serving both local agricultural markets and export corridors to the Middle East.
China
Rural e-commerce penetration into county-level agricultural supply chains is bypassing traditional wholesale distributors for direct-to-cooperative sack procurement. SAMR enforcement of GB standards for food-contact plastics is accelerating reformulation of recycled polypropylene grades previously excluded from grain applications. The Yangtze River Delta cluster around Shanghai anchors high-volume production for construction materials distribution across Southeast Asia.
United States
Midwest grain elevators are specifying RFID-tagged sacks with real-time inventory visibility for quarterly procurement cycles with penalty clauses. FDA food-contact regulations on migratory substances from recycled content are creating qualification barriers against imported laminated specifications. The Gulf Coast petrochemical corridor from Houston to Baton Rouge supplies virgin polypropylene resin to tape extrusion operations serving Latin American agricultural export markets.
Germany
Extended producer responsibility frameworks in Bavaria and Baden-Württemberg are mandating closed-loop recycling partnerships between sack converters and agricultural cooperatives. ECHA substance restrictions on specific UV stabilizers are forcing reformulation cycles that favor established compounders with in-house testing laboratories. The Rhine-Ruhr industrial region concentrates coextrusion lamination capacity for EU food-contact applications requiring mono-material barrier compliance.
Brazil
Large grain traders in Mato Grosso and Goiás are imposing 30% post-consumer content mandates in annual sack tenders for soybean and corn exports. ANVISA food-contact regulations are converging with EU standards for agricultural packaging destined for European markets. The Port of Santos corridor concentrates conversion capacity serving Atlantic export routes to African and European destinations.
Global Polypropylene Woven Bags and Sacks Market Competitive Landscape
Concentration sits with vertically integrated tape extruders and multi-continent converters serving multinational grain traders. The vendor base fragments across regional specialists serving domestic agricultural cooperatives and construction materials distributors. Three archetypes dominate: integrated recyclers with captive flake supply, specialty laminated sack producers with food-contact certification depth, and scale-driven bulk converters with UV-stabilized construction portfolios. Competitive dynamics center on backward integration into resin compounding and geographic expansion through distributor partnerships in high-growth agricultural corridors.
Among India-based integrated producers, Emmbi Industries Limited and Uflex Limited exemplify the archetype of converters controlling tape extrusion through bag conversion for cost leadership in agricultural supply chains. Mondi plc occupies a position within the European specialty tier, anchoring demand through laminated sack portfolios designed for REACH and EFSA compliance. Berry Global Inc. represents the scale-driven North American archetype, with multi-continent production networks serving construction materials distributors.
| Leading Market Players |
|---|
| Emmbi Industries Limited |
| United Bags |
| Mondi plc |
| ProAmpac |
| Conitex Sonoco USA |
| Berry Global Inc. |
| LC Packaging |
| Flexi-tuff |
| Uflex Limited |
| Others |
Supply & Pricing Matrix
Eight-to-fourteen-month BIS certification cycles in India concentrate pricing power with incumbent compounders holding certified inventory, while quarterly procurement cycles with penalty clauses among multinational grain traders compress margins across the laminated sack tier. This lead-time asymmetry between regulatory qualification and buyer negotiation cadence forces converters to absorb compliance costs or sacrifice food-grade market access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA- and EFSA-compliant laminated sacks from industrial-grade woven bags and uncoated commodity formats. Price differentiation hinges on certification depth and volume scale, with agricultural cooperatives in India and China driving the most aggressive price compression in standard-tier procurement. Pricing pressure stems from recycled polypropylene feedstock mandates that erode virgin resin cost advantages. Construction materials distributors prove most price-sensitive, while food processing units absorb certification premiums for compliance security.
Supply Chain Analysis
Inventory cycles extending 8-14 months for BIS food-grade approval freeze new entrant access while incumbents stockpile certified resin. Tape extrusion capacity concentrates in India, China, and Germany, with naphtha-cracker output from Middle Eastern petrochemical complexes feeding raw material flows. Supply chain risk centers on propylene feedstock volatility transmitted directly from cracker operations. Distribution runs through agricultural cooperative networks in India and county-level e-commerce channels in rural China, bypassing traditional wholesale sack distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational grain traders consolidating procurement around quarterly cycles with penalty clauses, fragmenting supplier margins while demanding real-time inventory visibility and post-consumer content compliance.
For Market Incumbents: Secure captive flake supply through backward integration into post-consumer polypropylene recycling, insulating margin compression from virgin resin volatility. Invest in mono-material barrier lamination lines to preempt EU Green Deal recyclability mandates that disqualify multi-layer constructions. Defend against FIBC substitution in construction materials by locking long-term offtake agreements with cement distributors below 500 kg thresholds. For New Entrants and Emerging Players: Digital printing convergence with QR-code traceability represents a service-layer gap where established compounders under-serve specialty coffee and organic grain exporters seeking branded consumer-facing applications. Target county-level agricultural cooperatives in rural China through direct e-commerce channels bypassing wholesale distributor markups. Pursue laminated food-grade certification in India where BIS approval timelines freeze incumbent inventory advantages. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because regulatory fragmentation across REACH, FDA, and BIS jurisdictions favors compounders with in-house testing laboratories and multi-certification portfolios. Acquisition candidates include integrated recyclers with captive flake supply and specialty laminated sack producers with EFSA compliance depth. Watch for extended producer responsibility framework rollouts in Germany and France as inflection signals for closed-loop recycling partnership valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling | Captive post-consumer flake supply insulates margin compression from virgin resin volatility in agricultural procurement. |
| Mono-Material Barrier Reformulation | EU Green Deal recyclability mandates force PE coating substitution for multi-layer laminations incompatible with mechanical recycling infrastructure. |
| Digital Print Capability Investment | High-resolution flexography with QR-code traceability unlocks branded specialty grain applications in organic and coffee export segments. |
| Direct E-Commerce Channel Development | Rural China county-level penetration bypasses wholesale distributor layers for agricultural cooperative procurement. |
| Multi-Jurisdiction Certification Expansion | Simultaneous REACH, FDA, and BIS qualification creates qualification barriers against mid-scale tape extrusion competitors. |
Research Methodology
Initial hypotheses were tested against primary input from tape extrusion plant managers, agricultural cooperative procurement leads, chemical distributor channel partners, and food processing unit supply chain directors, then refined against customs trade data, BIS certification registries, SEC filings of listed packaging converters, EU ECHA substance restriction databases, and FSSAI food-contact compliance records. Bottom-up volume estimates from regional production clusters were triangulated with top-down demand aggregation across end-use verticals.
Variance decomposition across product type, application, material grade, and end-user dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic drivers. Modeled inputs included naphtha-cracker output correlations for resin pricing, BIS certification pipeline velocities for supply elasticity, and grain trader tender specifications for recycled content adoption curves.
Underlying assumptions cover propylene feedstock stability, regulatory timeline adherence, and agricultural modernization continuity in India and China, with deviation risk concentrated in ECHA substance restriction scope expansion and FIBC substitution acceleration above 500 kg loads. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag in Drum Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Pre-Made Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
FIBC Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Bag Clips Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Counter Bags Market
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Inclusion Bags Market